20 mins. ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio

1 hr. ago
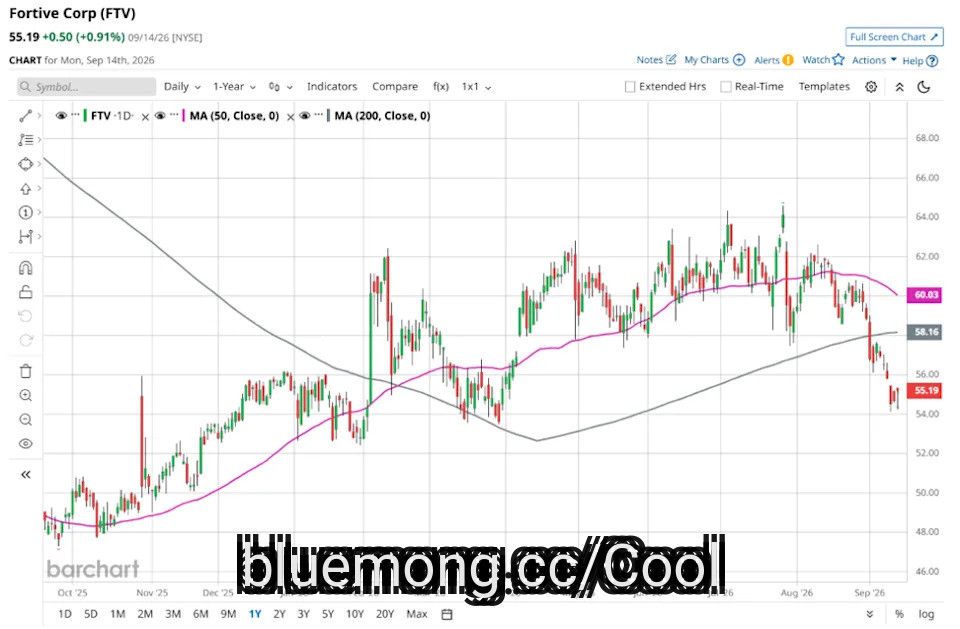
Everett, Washington-based Fortive Corporation (FTV) designs, develops, manufactures, and services professional and engineered products, software, and services. Valued at $16.7 billion by market cap, the company focuses on professional instrumentation, automation, sensing, and transportation technologies.
Companies worth $10 billion or more are generally described as "large-cap stocks," and FTV perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the scientific & technical instruments industry. FTV stands out for its strong brand recognition and leadership across its IOS, PT, and AHS segments. Its portfolio of established brands creates a durable moat that is hard to replicate, reflecting a sustained commitment to quality, innovation, and service, and supporting long-term growth and profitability.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#valued
Companies worth $10 billion or more are generally described as "large-cap stocks," and FTV perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the scientific & technical instruments industry. FTV stands out for its strong brand recognition and leadership across its IOS, PT, and AHS segments. Its portfolio of established brands creates a durable moat that is hard to replicate, reflecting a sustained commitment to quality, innovation, and service, and supporting long-term growth and profitability.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#valued



2 hours ago
Goleta, California-based Deckers Outdoor Corporation (DECK) is a global footwear and lifestyle company with products spanning performance running, outdoor activities, and premium casual fashion. Valued at a market cap of $11.1 billion, the company offers its products under the UGG, HOKA, Teva, Koolaburra, and AHNU brand names.
Companies with a market cap between $10 billion and $200 billion are typically called "large-cap stocks," and DECK fits that definition. Its portfolio of distinctive, high-growth footwear brands, particularly HOKA and UGG, drives its market dominance. HOKA stands out for its performance-driven, comfort-focused running shoes, while UGG combines its iconic heritage with evolving lifestyle products. This strong brand equity, differentiated product design, and loyal customer base give Deckers pricing power and help it compete beyond traditional footwear trends.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#billion
Companies with a market cap between $10 billion and $200 billion are typically called "large-cap stocks," and DECK fits that definition. Its portfolio of distinctive, high-growth footwear brands, particularly HOKA and UGG, drives its market dominance. HOKA stands out for its performance-driven, comfort-focused running shoes, while UGG combines its iconic heritage with evolving lifestyle products. This strong brand equity, differentiated product design, and loyal customer base give Deckers pricing power and help it compete beyond traditional footwear trends.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#billion



2 hours ago
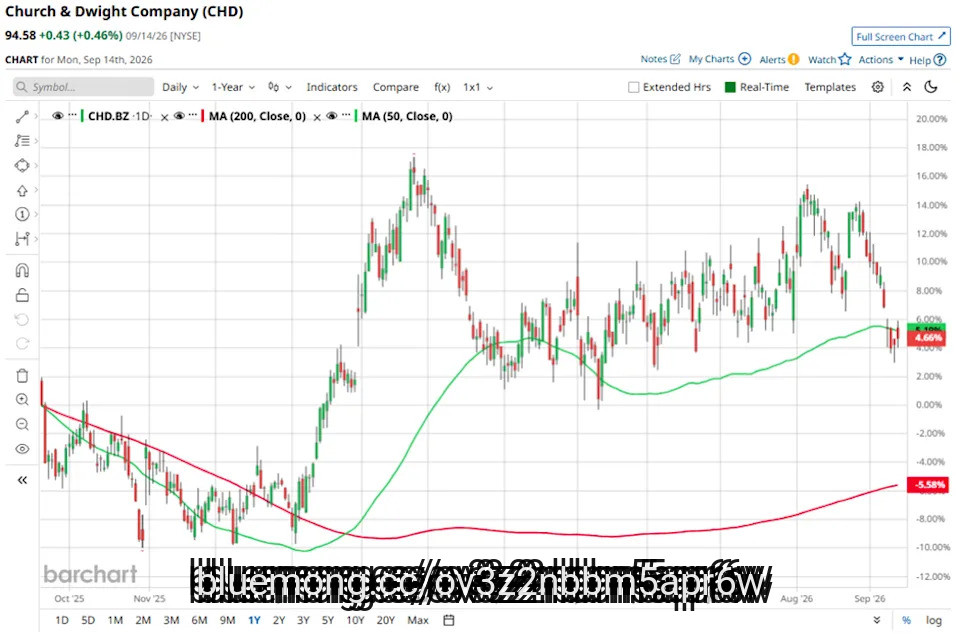
With a market cap of $22.4 billion, Church & Dwight Co., Inc. (CHD) is a leading developer, manufacturer, and marketer of household, personal care, and specialty products. Best known as the U.S. leader in sodium bicarbonate production, the company's portfolio includes iconic power brands such as ARM & HAMMER, Trojan, OxiClean, Waterpik, and Vitafusion.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean

3 hours ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current


3 hours ago
With a market cap of $22.4 billion, Dollar Tree, Inc. (DLTR) operates discount variety stores across the United States and Canada under the Dollar Tree and Dollar Tree Canada brands. The company offers a wide range of consumables, variety merchandise, and seasonal goods, catering to everyday needs as well as holidays and special occasions.
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Dollar Tree fits this criterion perfectly. Supported by a nationwide logistics network and its e-commerce platform, DollarTree.com, the retailer serves individuals, small businesses, and organizations with affordable products and bulk purchasing options.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#tree #canada #united #Companies
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Dollar Tree fits this criterion perfectly. Supported by a nationwide logistics network and its e-commerce platform, DollarTree.com, the retailer serves individuals, small businesses, and organizations with affordable products and bulk purchasing options.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#tree #canada #united #Companies



4 hours ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue


4 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
5 hours ago
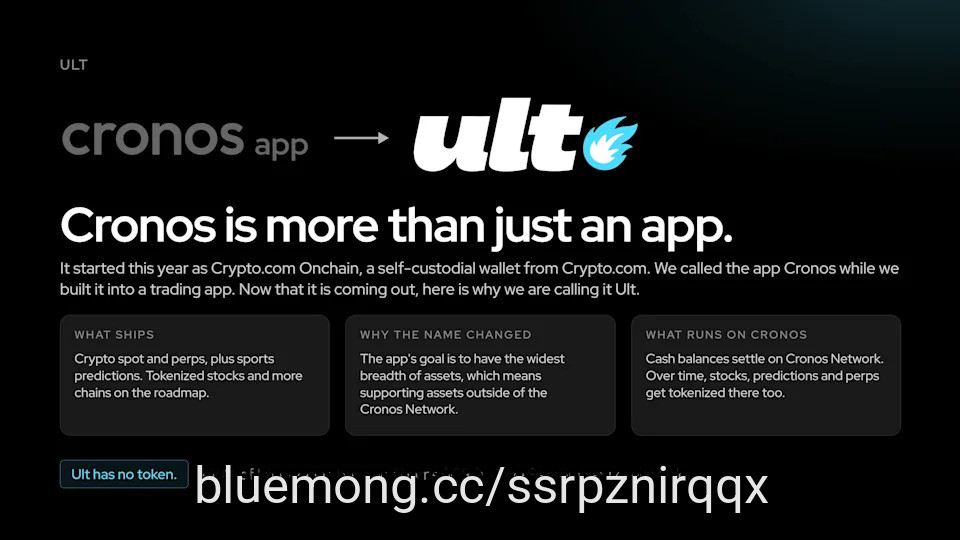
Cronos rebrands its trading app as Ult, expanding beyond crypto into prediction markets, perpetuals and tokenized **** ets.
Ult targets 100+ countries with 24/7/365 trading, 10 sports prediction categories and around 40 leveraged markets at launch.
Cronos Network could see more trading flow as Ult brings users, **** ets and liquidity into the ecosystem, with plans to move more markets onchain as volume grows.
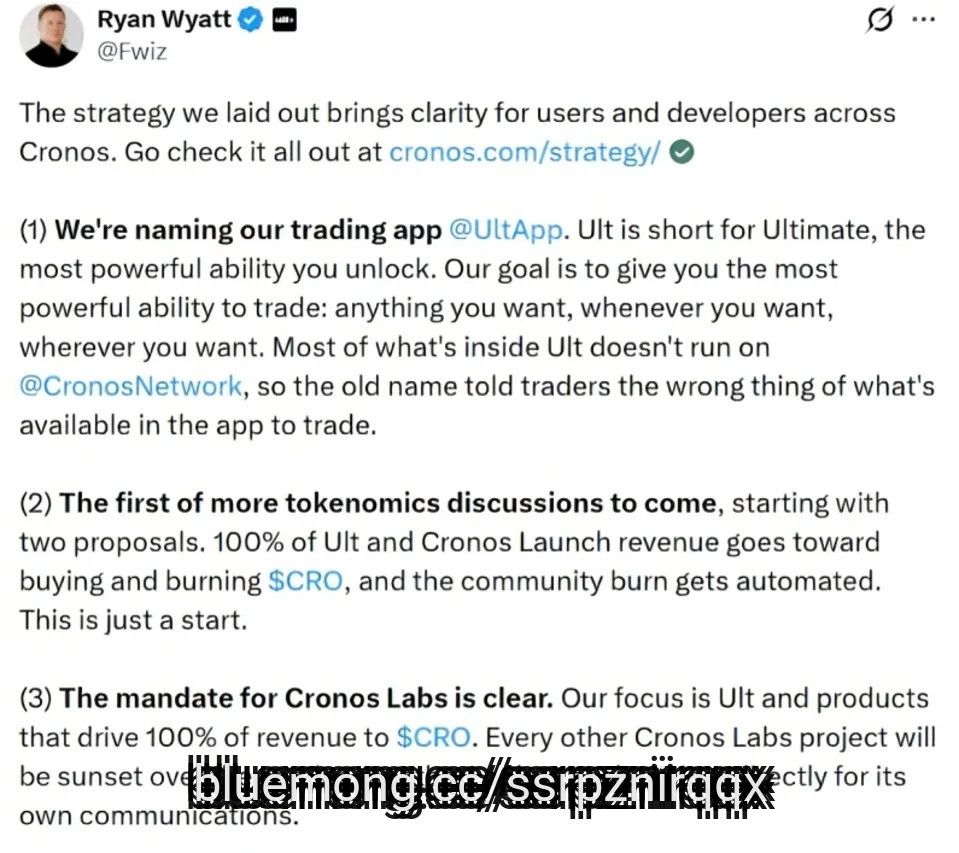
Cronos, the blockchain ecosystem **** ociated with Crypto.com, is reshaping its product strategy around a new trading application called Ult. It has introduced a revenue-linked mechanism designed to support its native CRO token.
Cronos CEO Ryan Wyatt announced the changes on X, saying the new strategy is intended to provide greater clarity for users and developers. It aims to put a stronger focus on products that generate value for CRO.
#markets
Ult targets 100+ countries with 24/7/365 trading, 10 sports prediction categories and around 40 leveraged markets at launch.
Cronos Network could see more trading flow as Ult brings users, **** ets and liquidity into the ecosystem, with plans to move more markets onchain as volume grows.
Cronos, the blockchain ecosystem **** ociated with Crypto.com, is reshaping its product strategy around a new trading application called Ult. It has introduced a revenue-linked mechanism designed to support its native CRO token.
Cronos CEO Ryan Wyatt announced the changes on X, saying the new strategy is intended to provide greater clarity for users and developers. It aims to put a stronger focus on products that generate value for CRO.
#markets


5 hours ago
Everett, Washington-based Fortive Corporation (FTV) designs, develops, manufactures, and services professional and engineered products, software, and services. Valued at $16.7 billion by market cap, the company focuses on professional instrumentation, automation, sensing, and transportation technologies.
Companies worth $10 billion or more are generally described as "large-cap stocks," and FTV perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the scientific & technical instruments industry. FTV stands out for its strong brand recognition and leadership across its IOS, PT, and AHS segments. Its portfolio of established brands creates a durable moat that is hard to replicate, reflecting a sustained commitment to quality, innovation, and service, and supporting long-term growth and profitability.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Stock #everett #corporation #valued
Companies worth $10 billion or more are generally described as "large-cap stocks," and FTV perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the scientific & technical instruments industry. FTV stands out for its strong brand recognition and leadership across its IOS, PT, and AHS segments. Its portfolio of established brands creates a durable moat that is hard to replicate, reflecting a sustained commitment to quality, innovation, and service, and supporting long-term growth and profitability.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Stock #everett #corporation #valued


10 hours ago
Kraft Heinz is a $25 billion global brand selling two million bottles of ketchup a day and it owns more than 200 other brands including Lunchables and Capri Sun. Reporting for TODAY, NBC's Vicky Nguyen sits down with new CEO, Steve Cahillane, to discuss where the company is headed as consumers move toward less-processed foods and more affordable store brands.
#heinz #reporting #today #vicky
#heinz #reporting #today #vicky


11 hours ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal


14 hours ago
New vehicle sales in Indonesia surged by a further 32% year-on-year to 81,756 units in August 2026, up from weak year-earlier sales of 61,771 units, according to wholesale data compiled by the local automotive industry ***** ociation, Gaikindo. The market last month was driven higher by strong demand for trucks and battery electric vehicles (BEVs).
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year

2 days ago
On September 1, Korn Ferry (NYSE:KFY) completed its £850 million acquisition of UK-based AMS, from OMERS Private Equity. The deal combines two well-reputed brands, resulting in a highly well-rounded solutions provider and a leading business within the global talent and organizational consulting **** e. It offers a broader market reach to Korn Ferry, along with more extensive coverage spanning several new industries.
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business


2 days ago
Steakhouse dining chains have faced a challenging year of rising beef prices, which increased by 9.4% year-over-year in July 2026, making it harder for many restaurants to maintain profitable businesses and keep their doors open.
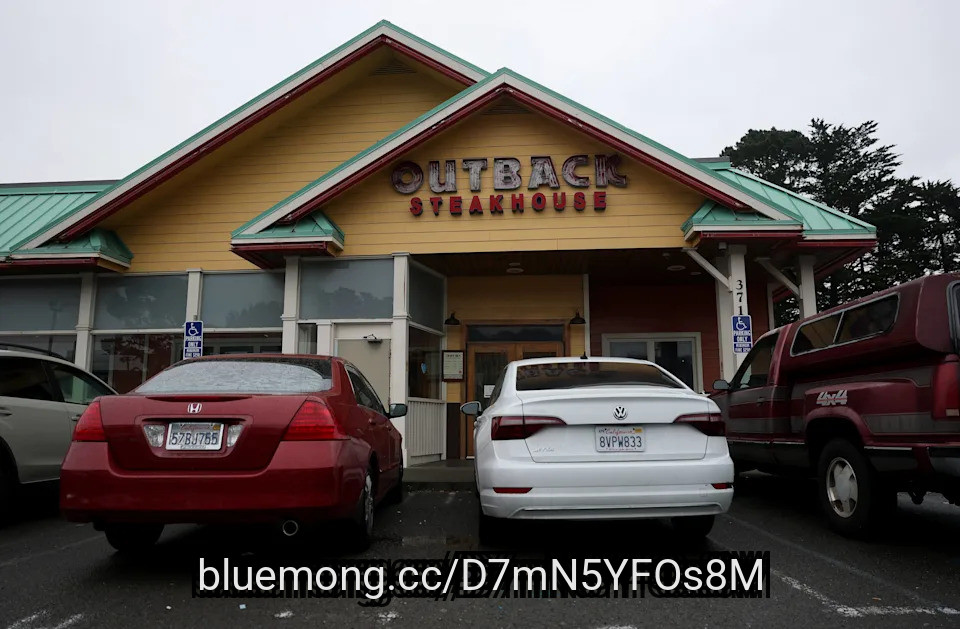
Among the restaurant chains implementing plans to improve their business performance is Bloomin' Brands' Outback Steakhouse, which has closed locations that no longer make economic sense to operate.
Outback Steakhouse is closing two more of its restaurants about 10 months after the chain's owner Bloomin' Brands launched a multi-year turnaround strategy that will eliminate locations that lack the potential for growth.
The 38-year-old steakhouse chain abruptly closed its Evansville, Wyo., location on Aug. 23, 2026, and posted a farewell note on its front door.
"G'Day Casper/Evansville: Outback Steakhouse is now closed. Thank you for all your support over the last 21 years. It has been a pleasure working with so many great, local Outbackers over the years. To all the fond memories!!! Cheers, The Outback Team," the note stated.
#closed
Among the restaurant chains implementing plans to improve their business performance is Bloomin' Brands' Outback Steakhouse, which has closed locations that no longer make economic sense to operate.
Outback Steakhouse is closing two more of its restaurants about 10 months after the chain's owner Bloomin' Brands launched a multi-year turnaround strategy that will eliminate locations that lack the potential for growth.
The 38-year-old steakhouse chain abruptly closed its Evansville, Wyo., location on Aug. 23, 2026, and posted a farewell note on its front door.
"G'Day Casper/Evansville: Outback Steakhouse is now closed. Thank you for all your support over the last 21 years. It has been a pleasure working with so many great, local Outbackers over the years. To all the fond memories!!! Cheers, The Outback Team," the note stated.
#closed

2 days ago
Walmart (WMT) recently took another step into restaurant delivery, announcing a national partnership with Inspire Brands that puts it more directly in competition with DoorDash (DASH) and Uber Technologies' (UBER) Uber Eats. But the expansion announced recently is still largely limited to restaurants operating as tenants inside Walmart stores, where the logistics are considerably easier to manage. The bigger question is what happens when the company moves beyond these in-store tenants and takes on the more difficult parts of the restaurant delivery market. Until then, the current expansion says more about Walmart's ambition than its ability to become a structural competitor to the established players.
Walmart is expanding its restaurant delivery strategy through a new collaboration with Inspire Brands, whose portfolio includes Arby's, Jimmy John's, Dunkin, Baskin-Robbins, and Sonic. The partnership will bring restaurant delivery into Walmart's app. Dunkin' will be the first brand to launch, starting with 150 in-store tenant locations. Walmart and Dunkin' then plan to expand the offering to most of Dunkin's roughly 10,000 U.S. restaurants, including locations outside Walmart's stores. The broader opportunity is built around Walmart's existing physical footprint. A customer could place a restaurant order alongside a Walmart purchase and receive both through the same delivery. The retail giant says its footprint is located within 10 miles of about 90% of the U.S. population.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#uber #Stock #inspire #launch
Walmart is expanding its restaurant delivery strategy through a new collaboration with Inspire Brands, whose portfolio includes Arby's, Jimmy John's, Dunkin, Baskin-Robbins, and Sonic. The partnership will bring restaurant delivery into Walmart's app. Dunkin' will be the first brand to launch, starting with 150 in-store tenant locations. Walmart and Dunkin' then plan to expand the offering to most of Dunkin's roughly 10,000 U.S. restaurants, including locations outside Walmart's stores. The broader opportunity is built around Walmart's existing physical footprint. A customer could place a restaurant order alongside a Walmart purchase and receive both through the same delivery. The retail giant says its footprint is located within 10 miles of about 90% of the U.S. population.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#uber #Stock #inspire #launch


2 days ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands

2 days ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal

2 days ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy

2 days ago
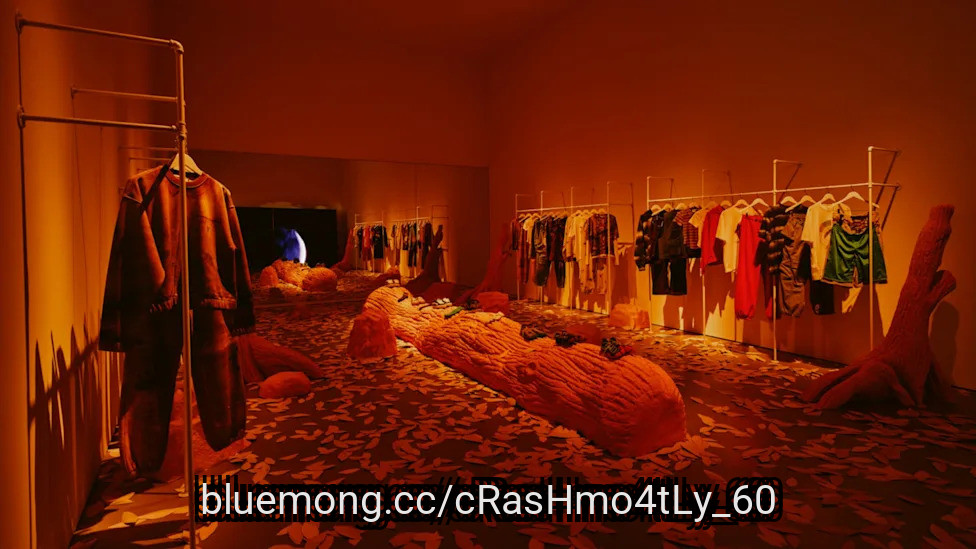
SZA and Vans are inviting the public to step into the world of the soon-to-launch, and aptly named, Vansza collection with an elaborate New York Fashion Week experience.
While the collection doesn't launch until Oct. 22, the Vansza activation will open its doors at 260 Bowery significantly sooner. Visitors will have the chance to take in the unique experience starting Sept. 10 at 2 p.m. local time. Following an 8 p.m. shutdown that night, the Vansza world will restart on Sept. 11 at 12 p.m. local time before wrapping for good at 4 p.m.
In a statement shared with Complex, SZA teased the forthcoming collection, which features footwear and apparel, as "a reflection" of how she lives and what inspires her on a daily basis.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
"I wanted to create pieces that feel comfortable, functional, and expressive, whether you're on a trail, in the city, or discovering something new about yourself," the seven-time Grammy winner said. "Working with Vans gave me the freedom to explore ideas rooted in creativity, curiosity, and play, and my hope is that people feel inspired to step outside their comfort zone, trust their instincts, and have fun making something uniquely their own."
#time
While the collection doesn't launch until Oct. 22, the Vansza activation will open its doors at 260 Bowery significantly sooner. Visitors will have the chance to take in the unique experience starting Sept. 10 at 2 p.m. local time. Following an 8 p.m. shutdown that night, the Vansza world will restart on Sept. 11 at 12 p.m. local time before wrapping for good at 4 p.m.
In a statement shared with Complex, SZA teased the forthcoming collection, which features footwear and apparel, as "a reflection" of how she lives and what inspires her on a daily basis.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
"I wanted to create pieces that feel comfortable, functional, and expressive, whether you're on a trail, in the city, or discovering something new about yourself," the seven-time Grammy winner said. "Working with Vans gave me the freedom to explore ideas rooted in creativity, curiosity, and play, and my hope is that people feel inspired to step outside their comfort zone, trust their instincts, and have fun making something uniquely their own."
#time

2 days ago
Elon Musk reportedly used his first dance with his then-wife to establish who was in charge.
"I am the alpha in this relationship," Musk allegedly told his first wife, Justine Wilson Musk, as the newlyweds danced at their 2000 wedding, according to her appearance in Alex Gibney's new documentary Musk, which was viewed by People.
More than two decades later, Justine says the comment wasn't an isolated moment. She describes a marriage in which Musk regularly criticized her, made her feel insignificant, and spoke to her as though she worked for him.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
"I learned the term 'gaslighting' through my relationship with Elon," Justine says in the film. "He was constantly remarking on the ways he found me lacking."
#justine #elon #alex #people
"I am the alpha in this relationship," Musk allegedly told his first wife, Justine Wilson Musk, as the newlyweds danced at their 2000 wedding, according to her appearance in Alex Gibney's new documentary Musk, which was viewed by People.
More than two decades later, Justine says the comment wasn't an isolated moment. She describes a marriage in which Musk regularly criticized her, made her feel insignificant, and spoke to her as though she worked for him.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
"I learned the term 'gaslighting' through my relationship with Elon," Justine says in the film. "He was constantly remarking on the ways he found me lacking."
#justine #elon #alex #people


2 days ago
A multimillion-dollar, oceanfront Malibu home said to be owned by Oscar-winning actor Nicolas Cage has been threatened by a sizable sinkhole, with officials now cautioning that conditions in the area are "likely to worsen" in the coming days.
As noted in an ***** ociated Press report on Tuesday (Sept. 8), the driveway of the mansion has collapsed, leading to a swiftly remedied gas leak. The damage has been linked to Hurricane Marie, despite it never having made landfall.
As for the Cage connection, the Los Angeles Times, citing real estate records, says the actor is listed as the property's owner. Other reports point to prior coverage of its sale to Cage back in 2024 for more than $10 million.
Tuesday, Malibu's Director of Emergency Services confirmed a local emergency declaration in response to "a large sinkhole." An evacuation order has also been put in motion "for all affected properties," officials said in a press release.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#malibu #oscar
As noted in an ***** ociated Press report on Tuesday (Sept. 8), the driveway of the mansion has collapsed, leading to a swiftly remedied gas leak. The damage has been linked to Hurricane Marie, despite it never having made landfall.
As for the Cage connection, the Los Angeles Times, citing real estate records, says the actor is listed as the property's owner. Other reports point to prior coverage of its sale to Cage back in 2024 for more than $10 million.
Tuesday, Malibu's Director of Emergency Services confirmed a local emergency declaration in response to "a large sinkhole." An evacuation order has also been put in motion "for all affected properties," officials said in a press release.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#malibu #oscar



2 days ago
Megan Thee Stallion is shedding light on her relationship with ex Klay Thompson.
In an interview with InStyle published Wednesday (Sept. 8), the rapper was asked about how she was feeling after her breakup with the NBA star.
"I'm trying my best," she told journalist Jason Sheeler. "I feel like I've been put through the washing machine and the dryer with tins, shovels, and a cactus."
After describing the situation as "very rough," Megan chose her words carefully.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#thee #klay #sept #jason
In an interview with InStyle published Wednesday (Sept. 8), the rapper was asked about how she was feeling after her breakup with the NBA star.
"I'm trying my best," she told journalist Jason Sheeler. "I feel like I've been put through the washing machine and the dryer with tins, shovels, and a cactus."
After describing the situation as "very rough," Megan chose her words carefully.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#thee #klay #sept #jason



2 days ago
Noel Clarke has been hit with six criminal charges involving five women, years after allegations of ****** ual misconduct derailed the Doctor Who actor's career.
According to People, London's Metropolitan Police announced on Wednesday, September 9, that Clarke faces two counts of ****** ual ****** ault, three counts of voyeurism, and one count of exposure. The alleged incidents took place between 2007 and 2016, overlapping with some of the most successful years of his television and film career.
"Doctor Who" star Noel Clarke has been charged with multiple ****** ual offenses including ****** ual ****** ault, voyeurism and exposure.
The charges come almost a year after Clark was arrested as his London home was searched by police.
In August 2025, Clarke lost a libel case against The… pic.twitter.com/AGyZZjGMQ3
— Variety (Variety) September 9, 2026
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#noel #variety
According to People, London's Metropolitan Police announced on Wednesday, September 9, that Clarke faces two counts of ****** ual ****** ault, three counts of voyeurism, and one count of exposure. The alleged incidents took place between 2007 and 2016, overlapping with some of the most successful years of his television and film career.
"Doctor Who" star Noel Clarke has been charged with multiple ****** ual offenses including ****** ual ****** ault, voyeurism and exposure.
The charges come almost a year after Clark was arrested as his London home was searched by police.
In August 2025, Clarke lost a libel case against The… pic.twitter.com/AGyZZjGMQ3
— Variety (Variety) September 9, 2026
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#noel #variety



2 days ago
A major consumer company is considering a move that could put several familiar household brands on the market.
The move comes as the company reassesses parts of its portfolio and seeks to strengthen performance in a key market. If completed, the sale could reshape a personal care business that includes well-known products used by consumers for decades.
The potential sale follows a trend of other large companies reshaping their portfolios amid shifting consumer spending, rising costs, and intensifying competition.
Founded in 1806 in New York City, Colgate-Palmolive is an American multinational consumer products company that owns multiple familiar brands in oral health, pet health, personal care, and home care.
Colgate-Palmolive (CL) is exploring the potential sale of certain mass-market personal care brands, including Softsoap, Irish Spring, and Speed Stick, according to sources familiar with the matter cited by Reuters.
#care #palmolive
The move comes as the company reassesses parts of its portfolio and seeks to strengthen performance in a key market. If completed, the sale could reshape a personal care business that includes well-known products used by consumers for decades.
The potential sale follows a trend of other large companies reshaping their portfolios amid shifting consumer spending, rising costs, and intensifying competition.
Founded in 1806 in New York City, Colgate-Palmolive is an American multinational consumer products company that owns multiple familiar brands in oral health, pet health, personal care, and home care.
Colgate-Palmolive (CL) is exploring the potential sale of certain mass-market personal care brands, including Softsoap, Irish Spring, and Speed Stick, according to sources familiar with the matter cited by Reuters.
#care #palmolive


2 days ago
Steven Kolb apologized for physically restraining PETA activists during the COS runway show at New York Fashion Week
The protesters disrupted the show to highlight animal cruelty in the wool industry, calling for brands to stop using wool
PETA criticized Kolb's actions, while an activist announced that the organization plans to file a police report
A fashion executive is apologizing for his reaction to protesters crashing a New York Fashion Week show.
While models were walking the runway for the COS fall-winter 2026 collection in the WSA building on Sunday, Sept. 13, a group of animal activists from People for the Ethical Treatment of Animals (PETA) emerged holding signs and shouting against supporting the brand owned by Swedish retailer H&M, CNN, The New York Times and The Business of Fashion reported.
#fashion #peta #activists #animal
The protesters disrupted the show to highlight animal cruelty in the wool industry, calling for brands to stop using wool
PETA criticized Kolb's actions, while an activist announced that the organization plans to file a police report
A fashion executive is apologizing for his reaction to protesters crashing a New York Fashion Week show.
While models were walking the runway for the COS fall-winter 2026 collection in the WSA building on Sunday, Sept. 13, a group of animal activists from People for the Ethical Treatment of Animals (PETA) emerged holding signs and shouting against supporting the brand owned by Swedish retailer H&M, CNN, The New York Times and The Business of Fashion reported.
#fashion #peta #activists #animal



2 days ago
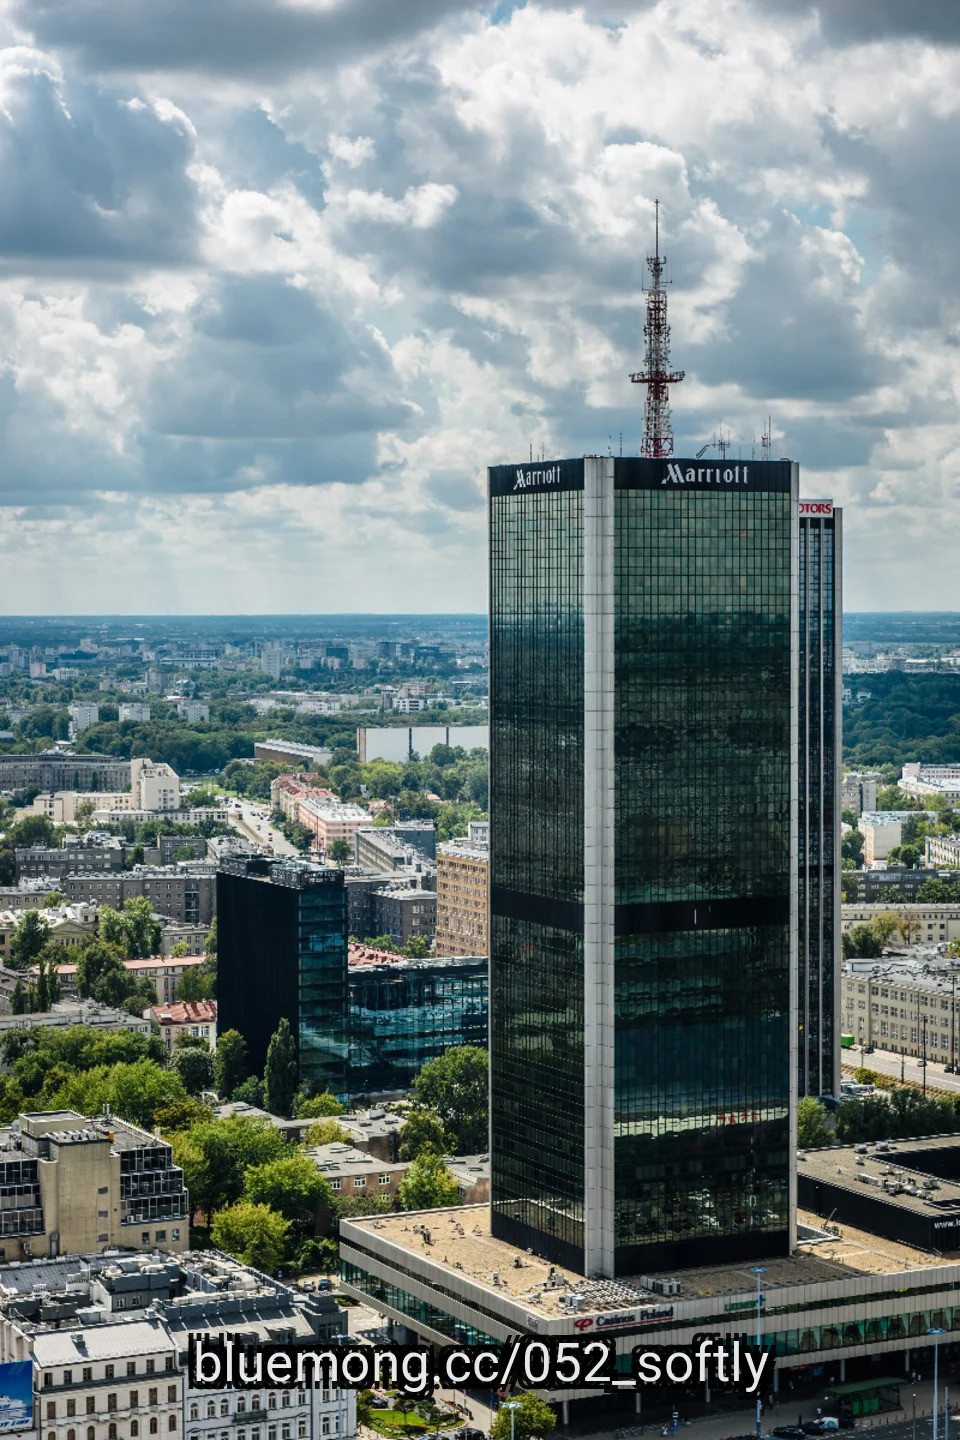
Marriott International, Inc. (NASDAQ:MAR)'s Middle East business showed a meaningful improvement in July, with revenue per available room (RevPAR) declining 12% year over year, a sharp improvement from the 43% decline in the second quarter. The improvement came despite continued regional conflict, suggesting that demand is proving more resilient than initially feared. More importantly, Marriott's global business remains strong: global room revenue increased 7% in July, with the U.S. and Canada up 8%.
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room

2 days ago
If you turn to Gordon Ramsay for cooking advice, the legendary chef is probably going to have some useful info, but if it's frozen food you're curious about, the man has sent some mixed signals over the years. As a famous TV yeller/chef, Ramsay is known for speaking his mind on foods he won't touch, and one thing he's been keen to attack in the past is frozen food meals. While many of us might turn to a frozen pizza or burrito for a cheap, quick meal when we don't have the energy to cook, Ramsay once told Bon Appétit it's the one type of food he refuses to eat.
As for why we won't touch frozen food, Ramsay's reasons are understandable, but they're also a little tone-deaf. "It's so easy to prepare a quick meal using fresh produce, such as a simple stir-fry, but people still resort to ready meals that all taste exactly the same," he told the outlet. It's certainly true that there are plenty of quick and easy recipes if you're in a rush and that plenty of frozen foods are of less-than-ideal quality.
But in the life of most non-celebrity chefs, there are times when you simply don't have the ingredients, time, or energy to cook. Additionally, it appears that Ramsay doesn't think every frozen meal tastes the same, or else he wouldn't have launched his own line of frozen meals called "By Chef Ramsay" in 2023. Maybe his frozen chicken pot pie really is that much better?
Read more: 18 Frozen Dinner Brands, Ranked From Worst To Best
Julia Duda/Tasting Table
#chef #foods
As for why we won't touch frozen food, Ramsay's reasons are understandable, but they're also a little tone-deaf. "It's so easy to prepare a quick meal using fresh produce, such as a simple stir-fry, but people still resort to ready meals that all taste exactly the same," he told the outlet. It's certainly true that there are plenty of quick and easy recipes if you're in a rush and that plenty of frozen foods are of less-than-ideal quality.
But in the life of most non-celebrity chefs, there are times when you simply don't have the ingredients, time, or energy to cook. Additionally, it appears that Ramsay doesn't think every frozen meal tastes the same, or else he wouldn't have launched his own line of frozen meals called "By Chef Ramsay" in 2023. Maybe his frozen chicken pot pie really is that much better?
Read more: 18 Frozen Dinner Brands, Ranked From Worst To Best
Julia Duda/Tasting Table
#chef #foods


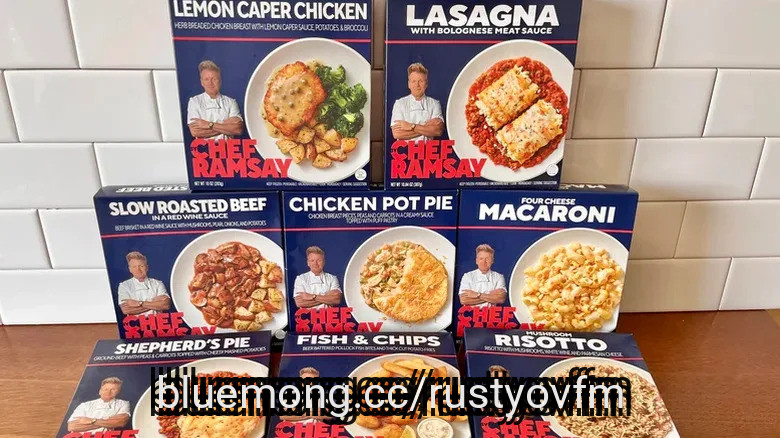
2 days ago
The family of Celeste Rivas Hernandez, who would have turned 16 this week, has named D4vd in a wrongful death lawsuit.
The Withered artist was ordered to stand trial in Celeste's murder back in July, with prosecutors accusing him of "brutally killing [the 14-year-old] because he feared their illicit ***** ual relationship would ruin his aspiring career." In addition to the murder, D4vd, born David Burke, is charged with continuous ***** ual abuse of a child and unlawful mutilation of human remains.
Separately, per this report from Los Angeles Times, Celeste's parents, Mercedes Martinez and Jesus Rivas, have now hit D4vd with a wrongful death lawsuit. The suit finds the family seeking damages from the singer, who has pleaded not guilty in the criminal case. Also named are managers, his mother, and others close to him.
Complex has reached out to a rep for Celeste's family for comment on the lawsuit. This story may be updated.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#d4vd #wrongful #death #murder
The Withered artist was ordered to stand trial in Celeste's murder back in July, with prosecutors accusing him of "brutally killing [the 14-year-old] because he feared their illicit ***** ual relationship would ruin his aspiring career." In addition to the murder, D4vd, born David Burke, is charged with continuous ***** ual abuse of a child and unlawful mutilation of human remains.
Separately, per this report from Los Angeles Times, Celeste's parents, Mercedes Martinez and Jesus Rivas, have now hit D4vd with a wrongful death lawsuit. The suit finds the family seeking damages from the singer, who has pleaded not guilty in the criminal case. Also named are managers, his mother, and others close to him.
Complex has reached out to a rep for Celeste's family for comment on the lawsuit. This story may be updated.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#d4vd #wrongful #death #murder

3 days ago
Long-running speculation over the future of Hain Celestial's business in Europe has finally come to a head with the disposal to a private-equity investor.
Nasdaq-listed Hain Celestial said in a statement today (14 September) it has agreed the sale of its "international" operations to Aurelius for $323m in cash.
The divestment follows a review of Hain Celestial's portfolio instigated by president and CEO Alison Lewis last year, which already resulted in the sale of its North American snacks business in 2026 to Canada's Snackruptors for $115m in cash.
That disposal included the brands Garden Veggie Snacks, Terra chips and Garden of Eatin'.
Ella's Kitchen baby and kids foods, the Joya and Natumi plant-based beverage lines and Hartley's jelly are joining Aurelius.
#hain #garden #sale #long
Nasdaq-listed Hain Celestial said in a statement today (14 September) it has agreed the sale of its "international" operations to Aurelius for $323m in cash.
The divestment follows a review of Hain Celestial's portfolio instigated by president and CEO Alison Lewis last year, which already resulted in the sale of its North American snacks business in 2026 to Canada's Snackruptors for $115m in cash.
That disposal included the brands Garden Veggie Snacks, Terra chips and Garden of Eatin'.
Ella's Kitchen baby and kids foods, the Joya and Natumi plant-based beverage lines and Hartley's jelly are joining Aurelius.
#hain #garden #sale #long