

9 hours ago
Sandisk (NASDAQ:SNDK) gave investors two pieces of news on Thursday, Oct. 29. The flash memory company's fiscal first-quarter revenue grew 23% over the previous quarter to $11.0 billion. And the board approved an eight-for-one stock split, with split-adjusted trading expected to start Friday, Nov. 20.
Does a split announcement tell investors anything about where a stock heads next? I checked what happened over the year after eight big-name split announcements, measured from every stock's close on announcement day.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Five of the eight were up one year later, and the median stock rose around 26%. Five also beat the S&P 500. But the results ran from a 43% drop to a 79% gain.
Image source: Getty Images.
#NVIDIA #eight

24 days ago
In January, then-CEO Tim Cook said that there were more than 2.5 billion active Apple (NASDAQ: AAPL) devices around the world. During the most recent fiscal quarter (the third quarter, ended June 27), the business exceeded 1.5 billion paid subscriptions to its family of services. These two data points demonstrate how dominant the consumer tech juggernaut has become.
If you'd invested $10,000 in this "Magnificent Seven" stock 10 years ago, here's how much you'd have today.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past decade, Apple shares have produced a total return of 1,190% (as of Oct. 5). This gain would've turned a starting $10,000 investment into more than $129,000 today.
In October 2016, Apple was the world's most valuable enterprise. While its market capitalization has ballooned to $4.9 trillion, it has given up the top spot to Nvidia.
#flashing #billion

24 days ago
Amcor plc (NYSE:AMCR) isn't a flashy business. Most people probably don't know much about the company, even though they come across its products every day. The company makes the packaging used for food, drinks, healthcare products, beauty products, and plenty of other everyday items.
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE

26 days ago
Before we get worried about recessions or market crashes, let's put a 10% drop in context. Going back to 1980, the S&P 500 has fallen 10% or more in roughly half of all calendar years, and a correction of that size has historically shown up about once every 12 to 18 months.
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month


26 days ago
Disney raised prices on many of its theme park offerings today, coinciding with the start of the company’s new fiscal year. But consumers aren’t pushing back the way they did a few years ago.
Disney’s price hikes are an annual October ritual for the company, and it’s always a tricky balancing act between increasing revenue and consumers’ willingness to pay.
Many ticket types, passes and add-ons at Disneyland are not increasing at all this time. But premium products are getting more expensive, like the highest-level, skip-the-line service at Walt Disney World, which could now run just shy of the $500 mark during peak demand.
It’s a reflection of the company’s strategy: Spread the price boosts across different audiences, while leaving bottom-tier prices - like the slowest season, one-day, one-park tickets - unchanged.
Its theme parks strategy, Disney said, has evolved over time. Higher-priced premium products and add-ons, alongside targeted discounts and a refresh of older attractions, allowed the company this summer to generate the strongest parks and cruises revenue in two years.
#disney #company #consumers



26 days ago
JNJ and PG both trade at 21x forward earnings, but J&J's 46% payout ratio versus P&G's 62% signals stronger long-term dividend coverage.
P&G carries a $1.4 billion after-tax earnings headwind into fiscal 2027, while J&J has already absorbed its Stelara biosimilar competition.
J&J's 10-year share price gain of 181% nearly doubled P&G's 117%, with management targeting double-digit earnings growth by decade's end.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Johnson & Johnson (NYSE:JNJ) orProcter & Gamble (NYSE:PG): If someone saving for retirement could hold only one Dividend King for the next 20 years, which one should it be? My pick is Johnson & Johnson, and the gap is wider than the yields suggest. Both stocks trade near 21 times forward earnings (P&G at 21), so valuation is effectively a tie. The decision comes down to three things that matter more to a retiree: dividend coverage, durability and structural risk.
#trade



26 days ago
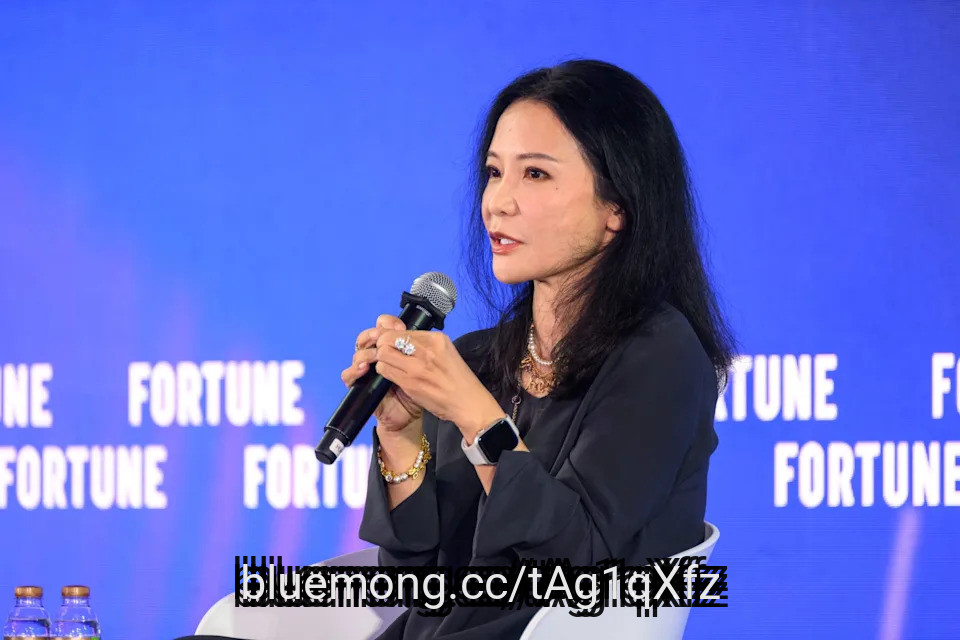
Christina Zhu, the head of Walmart's China business, remembers when Chinese shoppers did not have much choice.
As a child, she watched her parents wake up at 4:30 a.m. on Sundays to go to the wet market. "They had to haggle, and high-quality produce wasn't always guaranteed," Zhu, born in 1973, recalled at the Fortune Leaders Forum in Macau in September.
Today, Chinese shoppers are "probably the group with the most choices [in the world]," and they have become "the most demanding customers," she said.
Meeting those rising expectations has become the defining challenge for retailers in China, and Walmart has managed it better than most. It entered China in 1996 with a Supercenter and a Sam's Club in Shenzhen. Three decades later, the U.S. retailer is thriving in the world's second-largest economy even as other foreign brands struggle.
China represents 3% of Walmart's overall business, but it is growing, generating $24.6 billion in sales in its past fiscal year, a 19.3% jump. Sales grew 20.7% last quarter, faster than the 5.9% reported by the company as a whole.
#China
1 month ago
Shares of AutoZone (NYSE: AZO) rose on Tuesday after the automotive replacement parts and accessories distributor reported stronger-than-expected profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AutoZone's net sales grew 5.6% year over year to $6.6 billion in its fiscal 2026 fourth quarter, which ended on Aug. 29.
The auto-parts purveyor opened 175 stores during the quarter and a total of 374 over the trailing 12 months. AutoZone ended the period with 8,031 stores, including 6,863 stores in the U.S., 1,001 in Mexico, and 167 in Brazil.
Additionally, same-store sales, which measure revenue from locations open for at least a year, increased by 2.7%, or 1.5% when excluding foreign currency fluctuations.
#year #autozone #quarter #NYSE

1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


1 month ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

1 month ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ


1 month ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

1 month ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

1 month ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley

1 month ago
RF Industries, Ltd. (NASDAQ:RFIL) reported stronger fiscal third-quarter results on September 14. Revenue increased 21% to $23.96 million for the quarter ended July 31, 2026, while operating income reached approximately $1.8 million, compared with $720,000 a year earlier.
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier

1 month ago
Forgent Power Solutions, Inc. (NYSE:FPS) reported fiscal fourth-quarter revenue of approximately $462 million on September 15, up 94% year over year. Bookings reached $1.503 billion, increasing 375%, while backlog stood at $3.0 billion as of June 30, 2026.
The reported 3.3 times book-to-bill ratio compares quarterly bookings with quarterly revenue. Bookings and backlog are operating measures of order activity and outstanding contractual work, respectively. Neither represents cash collected, and backlog does not guarantee the timing of future revenue.
Forgent Power Solutions, Inc. (NYSE:FPS) expects fiscal 2027 revenue of $2.4 billion to $2.6 billion, implying 76% growth at the midpoint. The question is whether factories, employees, and working capital can support that expansion while preserving cash generation.
Forgent Power Solutions, Inc. (NYSE:FPS) already has evidence of stronger production economics. Fourth-quarter operating income reached $91.9 million, compared with $8.3 million a year earlier. Operating cash flow was $74 million, exceeding the quarter's $31 million of capital expenditures.
Those results suggest that rising output is beginning to cover the costs of expansion. Management attributed stronger profitability partly to revenue growing faster than operating costs as new campuses approached target production levels.
#operating #power #solutions #NYSE
1 month ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter

1 month ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
1 month ago
Apple's (NASDAQ: AAPL) new iPhones are here, and this could be just the ticket to get the consumer tech ******* an back on top of the market cap throne. It doesn't have far to go to get there.
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ
1 month ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


1 month ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

1 month ago
ResMed Inc. (NYSE:RMD) is well positioned to benefit from the long-term growth of the global obstructive sleep apnea (OSA) treatment market. Likewise, the company remains well positioned to benefit from growing awareness and penetration in the global market, backed by a robust product portfolio.
The company's OSA portfolio includes CPAP and APAP machines, led by the AirSense platform. The AirSense 10 series is one of the most widely used CPAP and APAP machine series. Beyond sleep therapy machines, it also offers nasal, nasal-pillow, and full-face masks, along with a wide range of accessories and related products.
The broad product portfolio offers multiple avenues for generating recurring revenue beyond the initial sale of a sleep therapy device.
Monkey Business Images/Shutterstock.com
In the fourth quarter of fiscal 2026, ResMed's revenue increased 9% year over year to $1.5 billion, supported by strong demand for sleep devices, masks, and accessories. Americas device revenue increased 6%, while total Americas Sleep and Breathing Health revenue rose 8%. Americas masks and other revenue increased 10%. The stronger performance is particularly important as it highlights the ability to monetize the installed patient base beyond the initial device purchase.
#sleep #increased

1 month ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company


1 month ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo

1 month ago
For custom chip designer Broadcom Inc. (NASDAQ:AVGO), the debate is all about whether the demand for AI products will sustain and grow. It is among the few firms capable of designing custom AI chips that big technology firms rely on to supplement NVIDIA's high-power and expensive AI chips. Anthropic CEO Dario Amodei's latest remarks about the need to slow down AI development due to safety concerns have generated quite a buzz, and Cramer discussed what Broadcom Inc. (NASDAQ:AVGO)'s CEO told him when asked about AI infrastructure development losing traction:
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong

1 month ago
Cybersecurity provider CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s shares are up by more than 100% year to date. With AI continuing to dominate the market narrative, the firm has found itself at the center of the industry's concerns about cybersecurity. While some, such as Anthropic's Dario Amodei, have claimed that their AI software is sufficient for cybersecurity purposes, others have argued that firms such as CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play a key role in the industry. Cramer is in the latter camp, and in his morning appearance on September 15th, the CNBC TV host discussed the recent discussions about AI being a threat:
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew




