10 mins. ago
Cardinal Health, Inc. (CAH), headquartered in Dublin, Ohio, operates as a healthcare services and products company. Valued at $54.6 billion by market cap, the company's services include pharmaceutical distribution, health-care product manufacturing, distribution and consulting services, drug delivery systems development, pharmaceutical packaging, automated dispensing systems manufacturing, and retail pharmacy franchising.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems



18 mins. ago
This story was originally published on Healthcare Dive. To receive daily news and insights, subscribe to our free daily Healthcare Dive newsletter.
Nearly three-quarters of Gen Z healthcare workers intend to find a new role in the next year, according to a new poll of more than 1,500 U.S. healthcare employees.
The survey, commissioned by the Harris Poll found that less than half of Gen Z healthcare workers feel very loyal to their current employer, in part because professional development and career advancement feel out of reach.
At the same time, three-quarters of employers said retaining and recruiting this age group is important as they anticipate older healthcare workers entering retirement soon.
The poll comes as the healthcare industry is facing workforce shortages, with a projected scarcity of around 500,000 healthcare workers predicted by 2038. Currently, healthcare professionals, especially physicians and nurses, are mostly over the age of 50, opening the door for younger workers to fill the gap.
#healthcare #feel
Nearly three-quarters of Gen Z healthcare workers intend to find a new role in the next year, according to a new poll of more than 1,500 U.S. healthcare employees.
The survey, commissioned by the Harris Poll found that less than half of Gen Z healthcare workers feel very loyal to their current employer, in part because professional development and career advancement feel out of reach.
At the same time, three-quarters of employers said retaining and recruiting this age group is important as they anticipate older healthcare workers entering retirement soon.
The poll comes as the healthcare industry is facing workforce shortages, with a projected scarcity of around 500,000 healthcare workers predicted by 2038. Currently, healthcare professionals, especially physicians and nurses, are mostly over the age of 50, opening the door for younger workers to fill the gap.
#healthcare #feel


21 mins. ago
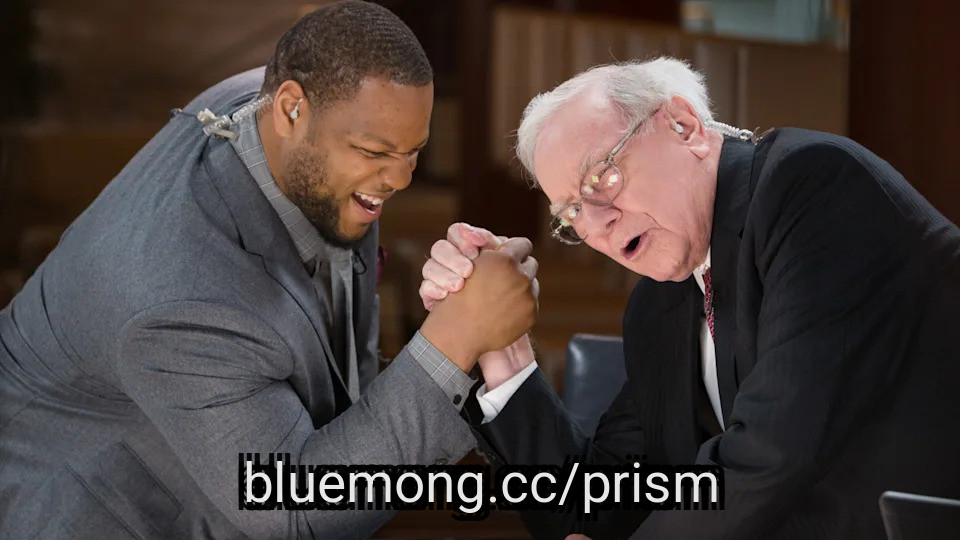
NFL fans know all about Ndamukong Suh's impressive career as a defensive lineman for teams like the Detroit Lions and the Tampa Bay Buccaneers. But what they may be surprised to learn is that this former football star has long been interested in investing.
Back in Suh's college days as a Nebraska Cornhusker, he was searching for someone to help guide him on creating a winning portfolio. Luckily for Suh, he was able to get in touch with one of Wall Street's most illustrious investors: Berkshire Hathaway's former CEO Warren Buffett.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#like #tampa #cornhusker
Back in Suh's college days as a Nebraska Cornhusker, he was searching for someone to help guide him on creating a winning portfolio. Luckily for Suh, he was able to get in touch with one of Wall Street's most illustrious investors: Berkshire Hathaway's former CEO Warren Buffett.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#like #tampa #cornhusker
29 mins. ago
This story was originally published on Restaurant Dive. To receive daily news and insights, subscribe to our free daily Restaurant Dive newsletter.
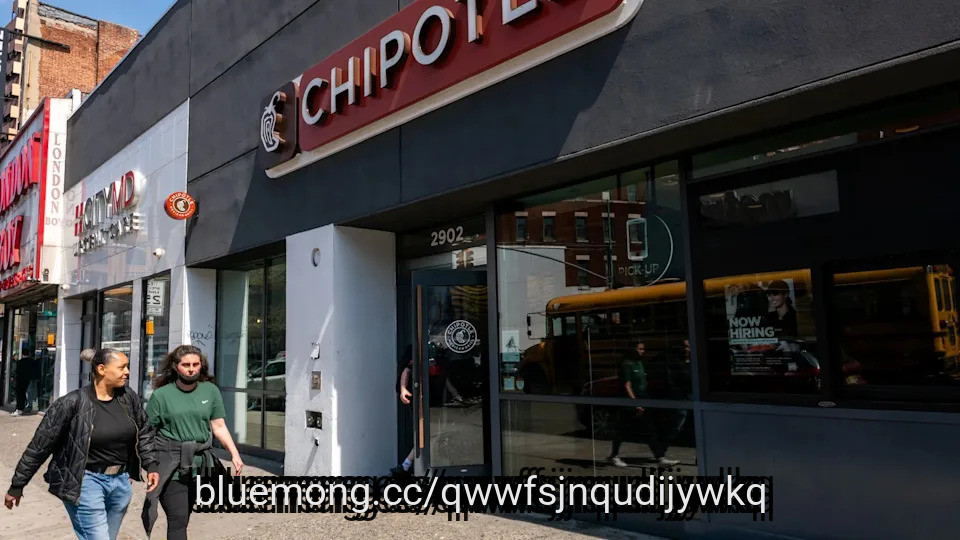
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees

42 mins. ago
International Flavors & Fragrances Inc. (IFF), headquartered in New York, produces and markets cosmetic active and natural health ingredients for use in various consumer products. Valued at $21.3 billion by market cap, the company flavors and fragrances are individual ingredients and compounds of a large number of ingredients that are blended, mixed, and reacted together to produce proprietary formulas.
Companies worth $10 billion or more are generally described as "large-cap stocks," and IFF perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty chemicals industry. IFF is a preeminent player in global flavors and fragrances, with 35,000+ products spanning food, beverage, personal care, and health & wellness. Its scale, innovation focus, and alignment with natural, sustainable, and customized ingredient trends support a competitive edge, while operations in 60+ countries provide access to emerging markets and evolving consumer preferences.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#ingredients #markets #Health #products
Companies worth $10 billion or more are generally described as "large-cap stocks," and IFF perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty chemicals industry. IFF is a preeminent player in global flavors and fragrances, with 35,000+ products spanning food, beverage, personal care, and health & wellness. Its scale, innovation focus, and alignment with natural, sustainable, and customized ingredient trends support a competitive edge, while operations in 60+ countries provide access to emerging markets and evolving consumer preferences.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#ingredients #markets #Health #products



12 hours ago
Jim Cramer sees Seneca Foods Corporation (NASDAQ:SENEA) as an attractive food stock after its sharp rally, but he wants investors to leave room for a further pullback. During the September 10 episode of Mad Money, he noted that the shares had recently fallen about 11% from their high the previous week. He added:
Looking at the chart, you'd think this was an AI data center company. The stock's up 256% over the past three years, nearly 70% year to date.
Cramer said its appeal starts with its exposure to both branded and private-label products:
They don't care whether you're buying the premium nationally branded stuff or the cheap private-label knockoffs because they package everything.
Seneca reported fiscal first-quarter 2027 revenue of $405.2 million, up 36.2% year over year, while diluted EPS increased to $2.85 from $2.14. Management attributed the revenue growth to the Green Giant U.S. frozen acquisition, private-label growth and the timing of contract-packaging sales. Cramer credited the Green Giant transaction with helping drive the improvement after Seneca acquired B&G Foods' U.S. frozen business in March.
#seneca #giant
Looking at the chart, you'd think this was an AI data center company. The stock's up 256% over the past three years, nearly 70% year to date.
Cramer said its appeal starts with its exposure to both branded and private-label products:
They don't care whether you're buying the premium nationally branded stuff or the cheap private-label knockoffs because they package everything.
Seneca reported fiscal first-quarter 2027 revenue of $405.2 million, up 36.2% year over year, while diluted EPS increased to $2.85 from $2.14. Management attributed the revenue growth to the Green Giant U.S. frozen acquisition, private-label growth and the timing of contract-packaging sales. Cramer credited the Green Giant transaction with helping drive the improvement after Seneca acquired B&G Foods' U.S. frozen business in March.
#seneca #giant


13 hours ago
HIVE Digital Technologies (Nasdaq: HIVE), a Canada-based Bitcoin miner and data center operator, has appointed Hubert Marleau as an independent director at BUZZ HPC.
The company, which trades on the Nasdaq and Toronto Stock Exchange, said Marleau will serve on the board of its wholly owned AI cloud and high-performance computing subsidiary.
Marleau brings more than 50 years of experience in Canadian capital markets. He co-founded Palos Capital Corp. and Palos Management Inc. and has served as governor of both the Montreal and Vancouver stock exchanges, chairman of the Toronto Stock Exchange Listing Committee, and a director of the Investment Dealers ******* ociation of Canada.
Related: Dogecoin co-founder mocks Trump's $5,000 dividend plan
During his five-decade-long career, he has sat on the boards of more than 50 publicly traded companies in Canada and the United States and advised on numerous mergers, acquisitions, and financings, according to the company.
#canada #marleau #palos
The company, which trades on the Nasdaq and Toronto Stock Exchange, said Marleau will serve on the board of its wholly owned AI cloud and high-performance computing subsidiary.
Marleau brings more than 50 years of experience in Canadian capital markets. He co-founded Palos Capital Corp. and Palos Management Inc. and has served as governor of both the Montreal and Vancouver stock exchanges, chairman of the Toronto Stock Exchange Listing Committee, and a director of the Investment Dealers ******* ociation of Canada.
Related: Dogecoin co-founder mocks Trump's $5,000 dividend plan
During his five-decade-long career, he has sat on the boards of more than 50 publicly traded companies in Canada and the United States and advised on numerous mergers, acquisitions, and financings, according to the company.
#canada #marleau #palos
13 hours ago
Sept 15, 2026, 2:38 pm EDT
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana


13 hours ago
Hive Digital Technologies Chief Financial Officer Darcy Daubaras joined Steve Darling from Proactive to discuss the appointment of renowned capital markets executive Hubert Marleau as an Independent Director of HIVE's wholly owned subsidiary, BUZZ High Performance Computing (BUZZ HPC), a move designed to strengthen governance and strategic oversight as the company expands its sovereign AI infrastructure platform across Canada.
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across

13 hours ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion


14 hours ago
Interested in Eli Lilly and Company? Here are five stocks we like better.
The healthcare sector offers options for investors of every age, combining high-growth drugmakers, defensive operators, and reliable dividend payers.
Eli Lilly suits younger investors with its obesity and diabetes drug pipeline driving growth, having gained nearly 34% since its April low.
UnitedHealth Group fits middle-aged investors with a turnaround story and rising dividend, while Johnson & Johnson's Dividend King status appeals to older, income-focused investors.
When it comes to investing, there is no one-size-fits-all approach. Strategies vary based on numerous factors, including but not limited to investors' risk tolerance, net worth, and age. When it comes to stock-picking, that last one is important.
#comes #here #april
The healthcare sector offers options for investors of every age, combining high-growth drugmakers, defensive operators, and reliable dividend payers.
Eli Lilly suits younger investors with its obesity and diabetes drug pipeline driving growth, having gained nearly 34% since its April low.
UnitedHealth Group fits middle-aged investors with a turnaround story and rising dividend, while Johnson & Johnson's Dividend King status appeals to older, income-focused investors.
When it comes to investing, there is no one-size-fits-all approach. Strategies vary based on numerous factors, including but not limited to investors' risk tolerance, net worth, and age. When it comes to stock-picking, that last one is important.
#comes #here #april

14 hours ago
Investors looking for cheap stocks to buy before the end of 2026 don't have to look too far to find some great investments. There are many top stocks that can make for solid long-term growth investments that are trading at absurdly cheap valuations right now.
Three stocks that are trading at low earnings multiples and that have lots of growth still ahead are Novo Nordisk (NYSE:NVO), Intuit (NASDAQ:INTU), and Reddit (NYSE:RDDT). Here's why these can make for great growth stocks to buy right now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
It's been a rough stretch for healthcare company Novo Nordisk, as it has declined about 23% in value over the past 12 months. Investors are questioning its ability to grow and compete alongside its rival, Eli Lilly. Novo was an early leader in the GLP-1 race with Ozempic and Wegovy, but now has lost more than a couple of steps.
#NVIDIA #investors #cheap
Three stocks that are trading at low earnings multiples and that have lots of growth still ahead are Novo Nordisk (NYSE:NVO), Intuit (NASDAQ:INTU), and Reddit (NYSE:RDDT). Here's why these can make for great growth stocks to buy right now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
It's been a rough stretch for healthcare company Novo Nordisk, as it has declined about 23% in value over the past 12 months. Investors are questioning its ability to grow and compete alongside its rival, Eli Lilly. Novo was an early leader in the GLP-1 race with Ozempic and Wegovy, but now has lost more than a couple of steps.
#NVIDIA #investors #cheap


15 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted H&R Block, Inc. (NYSE:HRB). H&R Block, Inc. (NYSE:HRB) provides ***** isted and do-it-yourself (DIY) tax preparation solutions. On September 14, 2026, H&R Block, Inc. (NYSE:HRB) closed at $45.74 per share. Over the past month, H&R Block, Inc. (NYSE:HRB) declined 10.21%, and its shares lost 8.87% over the past 52 weeks. H&R Block, Inc. (NYSE:HRB) has a market capitalization of $5.64 billion, and its stock has traded within a 52-week range of $28.16 and $58.67.
Conventum – Alluvium Global Fund stated the following regarding H&R Block, Inc. (NYSE:HRB) in its Q2 2026 investor letter:
"Last quarter we mentioned in regard to H&R Block, Inc. (NYSE:HRB), the tax agents, that a "SAASpocalypse" did not necessarily apply across the board, and that there was a mispricing opportunity so we bought more. Somewhat ironically, during its results call in early May, management stated that rather than AI replacing its products, it is using AI to build better products which are being well received. After returning 21.3% during the quarter, it now accounts for 4.6% of the Fund. Although it is now trading at a more respectable price, H&R Block achieves high returns on its capital, and trades at double digit cash flow and earnings yields. In no way do we see it as expensive."
H&R Block, Inc. (NYSE:HRB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 33 hedge fund portfolios held H&R Block, Inc. (NYSE:HRB) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of H&R Block, Inc. (NYSE:HRB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted H&R Block, Inc. (NYSE:HRB). H&R Block, Inc. (NYSE:HRB) provides ***** isted and do-it-yourself (DIY) tax preparation solutions. On September 14, 2026, H&R Block, Inc. (NYSE:HRB) closed at $45.74 per share. Over the past month, H&R Block, Inc. (NYSE:HRB) declined 10.21%, and its shares lost 8.87% over the past 52 weeks. H&R Block, Inc. (NYSE:HRB) has a market capitalization of $5.64 billion, and its stock has traded within a 52-week range of $28.16 and $58.67.
Conventum – Alluvium Global Fund stated the following regarding H&R Block, Inc. (NYSE:HRB) in its Q2 2026 investor letter:
"Last quarter we mentioned in regard to H&R Block, Inc. (NYSE:HRB), the tax agents, that a "SAASpocalypse" did not necessarily apply across the board, and that there was a mispricing opportunity so we bought more. Somewhat ironically, during its results call in early May, management stated that rather than AI replacing its products, it is using AI to build better products which are being well received. After returning 21.3% during the quarter, it now accounts for 4.6% of the Fund. Although it is now trading at a more respectable price, H&R Block achieves high returns on its capital, and trades at double digit cash flow and earnings yields. In no way do we see it as expensive."
H&R Block, Inc. (NYSE:HRB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 33 hedge fund portfolios held H&R Block, Inc. (NYSE:HRB) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of H&R Block, Inc. (NYSE:HRB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#conventum

16 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter

16 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos


16 hours ago
This story was originally published on CFO Dive. To receive daily news and insights, subscribe to our free daily CFO Dive newsletter.
Stewart Grierson took the fifth CFO seat of his career this summer, joining Austin, Texas-based AI development company Anaconda.
In addition to his two decades of experience in the data infrastructure sector, Grierson brings to his new post all the experience gained after helping to complete multiple initial public offerings: Like when serving as the CFO of the security management company ArcSight, which went public and then was acquired in 2010 by HP in a $1.5 billion transaction.
Yet Grierson in a recent interview said taking Anaconda or any company public has never been an end goal for him, **** erting that it is just one path that any company may take as it evolves and grows.
"We have shareholders who will want liquidity at some point and I think my background gives [Anaconda] the optionality" of either looking at public markets in the futuure or taking other routes, including private equity investments or acquisitions, Grierson told CFO Dive.
#taking
Stewart Grierson took the fifth CFO seat of his career this summer, joining Austin, Texas-based AI development company Anaconda.
In addition to his two decades of experience in the data infrastructure sector, Grierson brings to his new post all the experience gained after helping to complete multiple initial public offerings: Like when serving as the CFO of the security management company ArcSight, which went public and then was acquired in 2010 by HP in a $1.5 billion transaction.
Yet Grierson in a recent interview said taking Anaconda or any company public has never been an end goal for him, **** erting that it is just one path that any company may take as it evolves and grows.
"We have shareholders who will want liquidity at some point and I think my background gives [Anaconda] the optionality" of either looking at public markets in the futuure or taking other routes, including private equity investments or acquisitions, Grierson told CFO Dive.
#taking

17 hours ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival

18 hours ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c


18 hours ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly

18 hours ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda


18 hours ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year

18 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio

18 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted IQVIA Holdings Inc. (NYSE:IQV). IQVIA Holdings Inc. (NYSE:IQV) is a US-based provider of clinical research services, commercial insights, and healthcare intelligence to the life sciences and healthcare industries. On September 14, 2026, IQVIA Holdings Inc. (NYSE:IQV) closed at $265.67 per share. Over the past month, IQVIA Holdings Inc. (NYSE:IQV) returned 10.68%, and its shares are up 42.21% over the past year. IQVIA Holdings Inc. (NYSE:IQV) has a market capitalization of $43.73 billion, and its stock has traded within a 52-week range of $154.50 to $271.80.
Broyhill **** et Management stated the following regarding IQVIA Holdings Inc. (NYSE:IQV) in its Q2 2026 investor letter:
"IQVIA Holdings Inc. (NYSE:IQV) gained 14% after being our largest detractor in the first quarter. We set out our full case last quarter and will not repeat it here. The second quarter added evidence: results came in ahead, and request-for-proposal flow and award timing both improved. We trimmed the position in June and rolled the proceeds into Thermo Fisher, an exercise in portfolio management rather than a statement about our conviction."
IQVIA Holdings Inc. (NYSE:IQV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held IQVIA Holdings Inc. (NYSE:IQV) at the end of the second quarter, down from 64 in the previous quarter. While we acknowledge the potential of IQVIA Holdings Inc. (NYSE:IQV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#iqvia
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted IQVIA Holdings Inc. (NYSE:IQV). IQVIA Holdings Inc. (NYSE:IQV) is a US-based provider of clinical research services, commercial insights, and healthcare intelligence to the life sciences and healthcare industries. On September 14, 2026, IQVIA Holdings Inc. (NYSE:IQV) closed at $265.67 per share. Over the past month, IQVIA Holdings Inc. (NYSE:IQV) returned 10.68%, and its shares are up 42.21% over the past year. IQVIA Holdings Inc. (NYSE:IQV) has a market capitalization of $43.73 billion, and its stock has traded within a 52-week range of $154.50 to $271.80.
Broyhill **** et Management stated the following regarding IQVIA Holdings Inc. (NYSE:IQV) in its Q2 2026 investor letter:
"IQVIA Holdings Inc. (NYSE:IQV) gained 14% after being our largest detractor in the first quarter. We set out our full case last quarter and will not repeat it here. The second quarter added evidence: results came in ahead, and request-for-proposal flow and award timing both improved. We trimmed the position in June and rolled the proceeds into Thermo Fisher, an exercise in portfolio management rather than a statement about our conviction."
IQVIA Holdings Inc. (NYSE:IQV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held IQVIA Holdings Inc. (NYSE:IQV) at the end of the second quarter, down from 64 in the previous quarter. While we acknowledge the potential of IQVIA Holdings Inc. (NYSE:IQV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#iqvia

19 hours ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ******* et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#sotera #broyhill #second
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Sotera Health Company (NASDAQ:SHC). Sotera Health Company (NASDAQ:SHC), a US-based company that provides sterilization solutions, lab testing, and advisory services for the healthcare industry, contributed positively to the portfolio's performance this quarter. On September 14, 2026, Sotera Health Company (NASDAQ:SHC) closed at $18.52 per share, reflecting a market capitalization of $5.29 billion. Sotera Health Company (NASDAQ:SHC) posted a one-month return of 0.05%, while its shares gained 13.62% over the past 52 weeks.
Broyhill ******* et Management stated the following regarding Sotera Health Company (NASDAQ:SHC) in its Q2 2026 investor letter:
"Sotera Health Company (NASDAQ:SHC) was our largest contributor, with shares gaining 25%. We bought it in the first quarter, when the litigation docket was the only thing anyone wanted to discuss, and the price gave no weight to the fact that there are only two companies of scale doing this work. Results beat on revenue, adjusted EBITDA, and earnings per share; guidance was reaffirmed across every line, and management described March as its best volume month in three to four years. The EPA has proposed a full repeal of the 2024 ethylene oxide standard. At the time, the shares traded at roughly 14x forward earnings against 20x for the closest comparable."
Sotera Health Company (NASDAQ:SHC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 43 hedge fund portfolios held Sotera Health Company (NASDAQ:SHC) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Sotera Health Company (NASDAQ:SHC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#sotera #broyhill #second

19 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea

19 hours ago
With a market cap of $30.1 billion, Willis Towers Watson Public Limited Company (WTW) is a leading global advisory, broking, and solutions company, serving clients worldwide. Through its two segments: Health, Wealth & Career and Risk & Broking, the firm delivers services that help organizations manage risk, optimize benefits, and enhance performance.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Willis Towers Watson fits right into that category. Headquartered in London, the United Kingdom, the company combines deep expertise, data-driven insights, and innovative solutions to support businesses of all sizes.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#towers #public
Companies valued over $10 billion are generally described as "large-cap" stocks, and Willis Towers Watson fits right into that category. Headquartered in London, the United Kingdom, the company combines deep expertise, data-driven insights, and innovative solutions to support businesses of all sizes.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#towers #public


19 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na

19 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st


20 hours ago
With a market cap of $22.4 billion, Church & Dwight Co., Inc. (CHD) is a leading developer, manufacturer, and marketer of household, personal care, and specialty products. Best known as the U.S. leader in sodium bicarbonate production, the company's portfolio includes iconic power brands such as ARM & HAMMER, Trojan, OxiClean, Waterpik, and Vitafusion.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
20 hours ago
Wall Street is looking beyond this week's Federal Reserve interest-rate decision to a potentially bigger market-moving signal: the Fed's latest dot plot and what it says about the path for rates after an expected quarter-point hike.
Fed Chair Kevin Warsh faces a pivotal test of his inflation-fighting credibility as policymakers confront hotter prices, rising energy costs, and mounting bets on further rate increases.
A hike on Sept. 16 would be the Fed's first increase since July 2023, but investors may care even more what the dot plot signals for additional hikes and how aggressively Warsh intends to push rates to bring inflation back to the central bank's 2% goal.
Note that a rate hike is certain to draw highly vocal criticism from President Donald Trump and his allies, who have been campaigning for a drastic slash to 1% or less for years.
Remember, the Fed doesn't traditionally pull the "one and done" game when it comes to increasing the benchmark short-term interest rate. The Federal Open Market Committee reset of the Federal Funds Rate usually lands in a package of at least two, if not more.
#rate
Fed Chair Kevin Warsh faces a pivotal test of his inflation-fighting credibility as policymakers confront hotter prices, rising energy costs, and mounting bets on further rate increases.
A hike on Sept. 16 would be the Fed's first increase since July 2023, but investors may care even more what the dot plot signals for additional hikes and how aggressively Warsh intends to push rates to bring inflation back to the central bank's 2% goal.
Note that a rate hike is certain to draw highly vocal criticism from President Donald Trump and his allies, who have been campaigning for a drastic slash to 1% or less for years.
Remember, the Fed doesn't traditionally pull the "one and done" game when it comes to increasing the benchmark short-term interest rate. The Federal Open Market Committee reset of the Federal Funds Rate usually lands in a package of at least two, if not more.
#rate