

2 hours ago
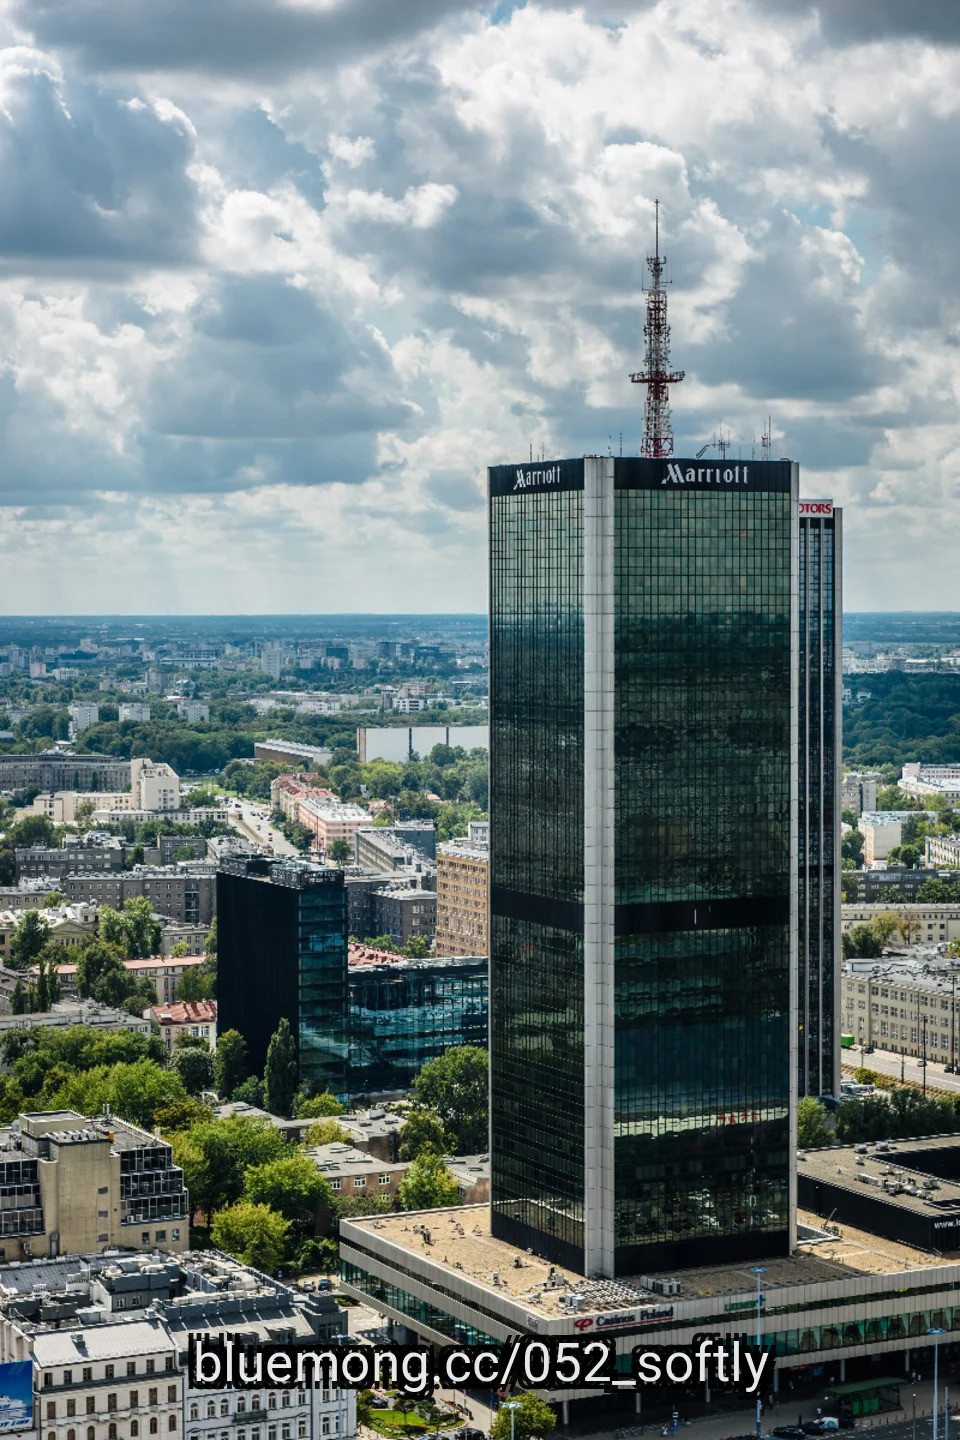
Marriott International, Inc. (NASDAQ:MAR)'s Middle East business showed a meaningful improvement in July, with revenue per available room (RevPAR) declining 12% year over year, a sharp improvement from the 43% decline in the second quarter. The improvement came despite continued regional conflict, suggesting that demand is proving more resilient than initially feared. More importantly, Marriott's global business remains strong: global room revenue increased 7% in July, with the U.S. and Canada up 8%.
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room

2 hours ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial



3 hours ago
Dow Inc. (NYSE:DOW) is reportedly considering selling its 35% stake in Sadara Chemical, its $20 billion chemicals joint venture with Saudi Aramco, as the company continues to reshape its portfolio amid a prolonged downturn in the global chemicals industry. No final decision has been made, and Aramco or another strategic or financial investor could potentially acquire Dow's stake.
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals

3 hours ago
When we moved to our former house in the Tradition neighborhood of Port St. Lucie, Fla., we had two Starbucks, two Dunkin's, and two local coffeehouses within a few miles of our house. A few years later, when we moved away, we still had two Starbucks, but the local, independent chains had both closed.
In their place, we added 7 Brew, Cali Coffee, Carmela (a regional chain), Vicky Bakery (a popular Cuban cafe chain), another Dunkin', and a new independent coffee place.
It's a staggering amount of competition in a fast-growing section of the city that's only a few square miles. All of those added competitors come at a time when the overall market has been growing, but seems to have hit a wall.
"The Coffee and Snack Shops industry has experienced a wave of growth, emerging as a standout performer in the food service sector. It boasts an annualized growth rate of 2.5%, shooting revenues up to $75.5 billion over the five years to 2026," according to IBISWorld's Coffee & Snack Shops in the US Industry Data and ***** ysis.
Nationally, Americans also have more places to get their daily cup.
#coffee #starbucks #snack #House
In their place, we added 7 Brew, Cali Coffee, Carmela (a regional chain), Vicky Bakery (a popular Cuban cafe chain), another Dunkin', and a new independent coffee place.
It's a staggering amount of competition in a fast-growing section of the city that's only a few square miles. All of those added competitors come at a time when the overall market has been growing, but seems to have hit a wall.
"The Coffee and Snack Shops industry has experienced a wave of growth, emerging as a standout performer in the food service sector. It boasts an annualized growth rate of 2.5%, shooting revenues up to $75.5 billion over the five years to 2026," according to IBISWorld's Coffee & Snack Shops in the US Industry Data and ***** ysis.
Nationally, Americans also have more places to get their daily cup.
#coffee #starbucks #snack #House


3 hours ago
Long-running speculation over the future of Hain Celestial's business in Europe has finally come to a head with the disposal to a private-equity investor.
Nasdaq-listed Hain Celestial said in a statement today (14 September) it has agreed the sale of its "international" operations to Aurelius for $323m in cash.
The divestment follows a review of Hain Celestial's portfolio instigated by president and CEO Alison Lewis last year, which already resulted in the sale of its North American snacks business in 2026 to Canada's Snackruptors for $115m in cash.
That disposal included the brands Garden Veggie Snacks, Terra chips and Garden of Eatin'.
Ella's Kitchen baby and kids foods, the Joya and Natumi plant-based beverage lines and Hartley's jelly are joining Aurelius.
#hain #garden #sale #long
Nasdaq-listed Hain Celestial said in a statement today (14 September) it has agreed the sale of its "international" operations to Aurelius for $323m in cash.
The divestment follows a review of Hain Celestial's portfolio instigated by president and CEO Alison Lewis last year, which already resulted in the sale of its North American snacks business in 2026 to Canada's Snackruptors for $115m in cash.
That disposal included the brands Garden Veggie Snacks, Terra chips and Garden of Eatin'.
Ella's Kitchen baby and kids foods, the Joya and Natumi plant-based beverage lines and Hartley's jelly are joining Aurelius.
#hain #garden #sale #long


4 hours ago
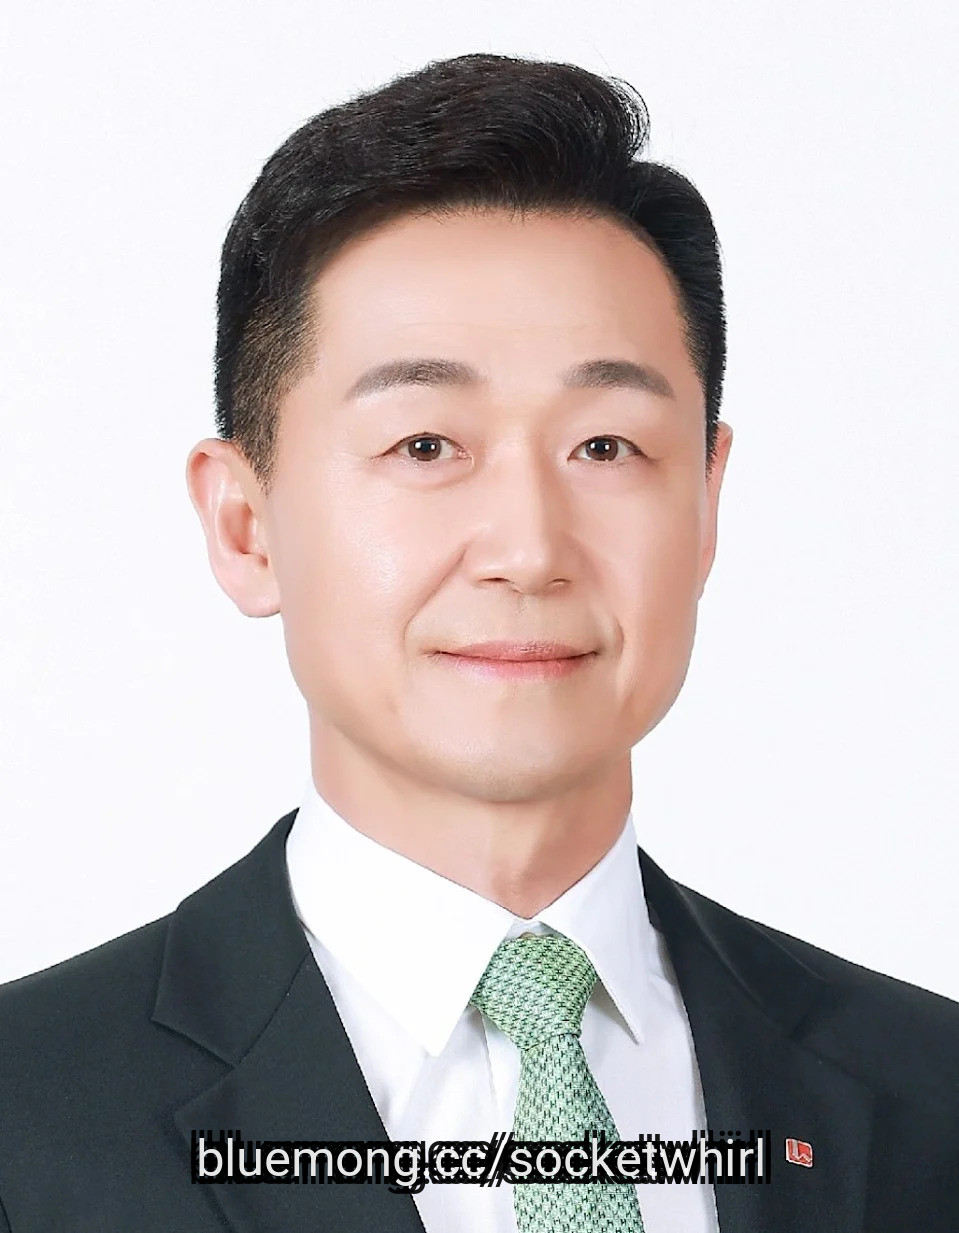
Founded in 1977 and headquartered in South Korea, LX Pantos has grown into a global logistics provider spanning freight forwarding, contract logistics, e-commerce fulfillment, last-mile delivery and installation, and supply chain management consulting. The company now operates more than 380 locations worldwide with a workforce of approximately 8,500 employees, moving more than 1.6 million TEUs of ocean freight and over 120,000 tons of air freight annually. In 2025, LX Pantos recorded revenue of approximately $5.85 billion.
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics



4 hours ago
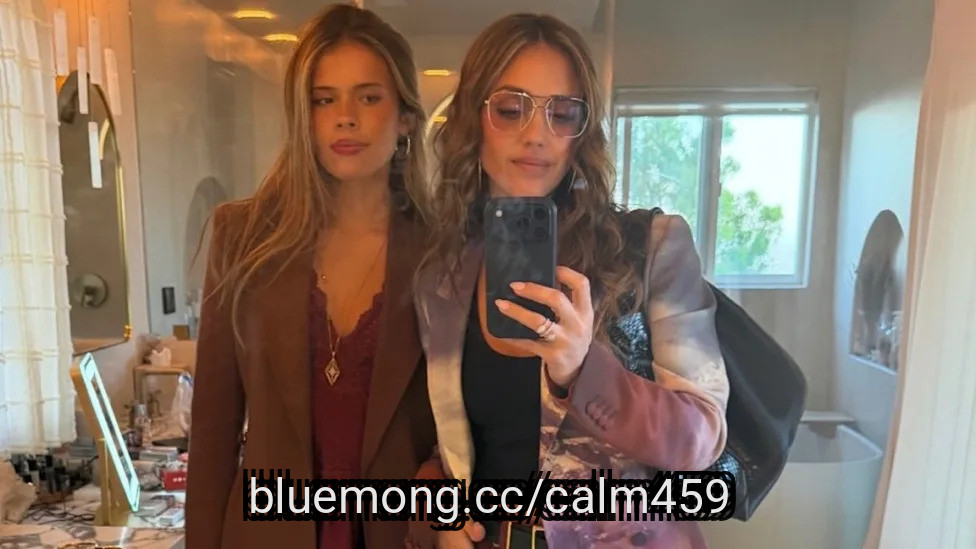
Jessica Alba and her daughter twinned for "day and night" looks during recent outings. The "Fantastic Four" star shared a collaborative Instagram post with her daughter featuring two photos of the duo. They appeared in matching ensembles in the women's final of the 2026 US Open on September 12.
At the women's final of the 2026 US Open, Jessica Alba and her daughter, Honor Warren. looked like twins in matching outfits. The 45-year-old wore an airy, off-white midi sundress with thin spaghetti straps. It had a fitted sweetheart bodice that transitioned into a pleated A-line skirt.
She knotted a slate-gray sweater around her waist, adding a casual, laid-back structure to the monochrome outfit. Rimless, tinted oval sunglasses, large hoop earrings, layered gold chain necklaces, a black shoulder bag, and pointed-toe white leather flats completed her look. She wore her hair down in loose waves.
Meanwhile, Warren wore a relaxed, blue-and-white micro-checkered gingham maxi dress featuring a smocked bust, a lace-up front detail, and a flowy tiered skirt. She layered a soft white sweater, casually draped and tied over her shoulders. She accessorised with narrow dark rectangular sunglasses, a pendant necklace, a black shoulder bag, and dark brown leather ballet flats.
For the evening look, Warren and Alba switched into lace-trimmed black dresses. The actress wore a sultry black satin slip dress trimmed with black lace along the diagonal neckline and sheer lace hem. She paired it with glossy black platform ankle-strap heels. Further, she carried a Fendi Multicolor Baguette, adding a pop of color to her look.
#warren #white #open
At the women's final of the 2026 US Open, Jessica Alba and her daughter, Honor Warren. looked like twins in matching outfits. The 45-year-old wore an airy, off-white midi sundress with thin spaghetti straps. It had a fitted sweetheart bodice that transitioned into a pleated A-line skirt.
She knotted a slate-gray sweater around her waist, adding a casual, laid-back structure to the monochrome outfit. Rimless, tinted oval sunglasses, large hoop earrings, layered gold chain necklaces, a black shoulder bag, and pointed-toe white leather flats completed her look. She wore her hair down in loose waves.
Meanwhile, Warren wore a relaxed, blue-and-white micro-checkered gingham maxi dress featuring a smocked bust, a lace-up front detail, and a flowy tiered skirt. She layered a soft white sweater, casually draped and tied over her shoulders. She accessorised with narrow dark rectangular sunglasses, a pendant necklace, a black shoulder bag, and dark brown leather ballet flats.
For the evening look, Warren and Alba switched into lace-trimmed black dresses. The actress wore a sultry black satin slip dress trimmed with black lace along the diagonal neckline and sheer lace hem. She paired it with glossy black platform ankle-strap heels. Further, she carried a Fendi Multicolor Baguette, adding a pop of color to her look.
#warren #white #open

4 hours ago
General Motors is developing a domestic battery supply chain it expects to complete within two to three years, even as the company currently relies on some Chinese-sourced materials for its existing battery production.
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're


2 days ago
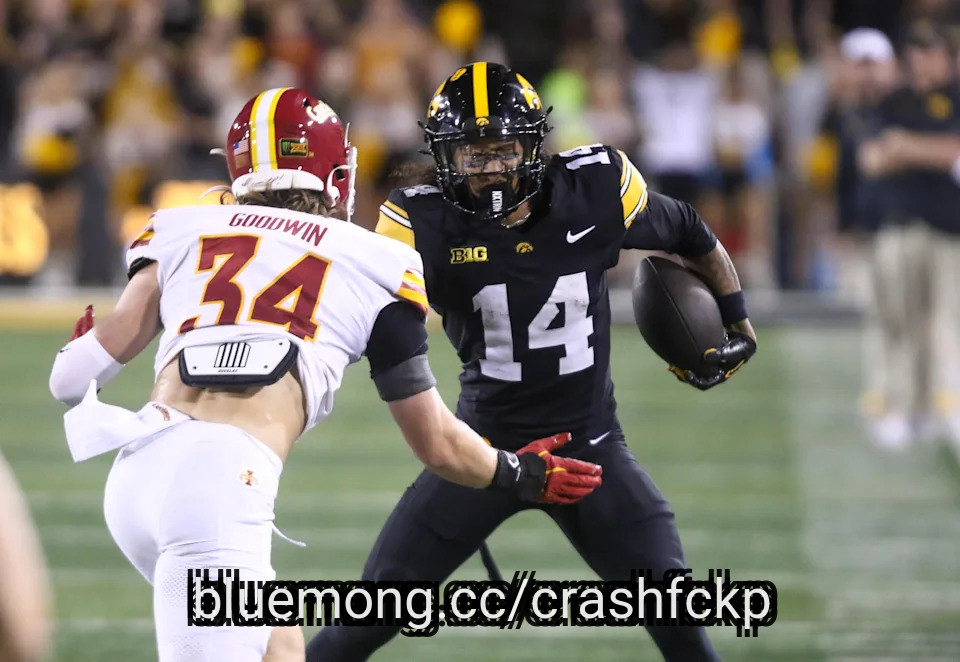
The Iowa Hawkeyes flipped the script on the Cyclones, winning this year's CyHawk game on a late field goal to pull out a 16-13 win. It was a scrappy, ugly, sometimes dirty game that was pretty much in line to how this series has gone these last ten years. But the Hawkeyes exorcised the demons of the last two years with a Caden Burr field goal from 42 yards out with :15 seconds left to bring the CyHawk trophy back home to Iowa City.
After last week's performance against NIU and with a brand new regime in Ames, many expected this to be a much more comfortable game for the Hawkeyes, especially under the lights in Kinnick Stadium with a raucous crowd. But Iowa State put Iowa into an early 10-0 hole midway through the second quarter that had the black and gold faithful starting to get that "here we go again" familiar feeling. But the offense managed to come to life, thanks to a massive 56-yard bomb to Tony Diaz that set up a Hank Brown touchdown run late the first half. A huge 45-yard Buhr field goal right before halftime reset the score and setting up a grinding second half of football.
Neither team had a great first quarter. Iowa started with the ball but procedural penalties doomed their drive. Meanwhile the Hawkeye defense held the Cyclones to only six plays in the quarter. Iowa State managed to move the chains in the second quarter with drives of nine and ten plays that ended on a Kyle Konrardy field goal and 7-yard Jalen Raynor touchdown pass, respectively. Raynor's stat line tonight won't impress anyone: 10/19 for 117 yards, and no touchdowns with some crucial misfires on potential big plays. But aside from those misses he made no back breaking mistakes that allowed the Iowa defense to capitalize.
Hank Brown REACHES OUT for Iowa's first score.
📺 Big Ten Football on NBC & Peacock pic.twitter.com/PJpKvvqkKt
Iowa State regained their momentum coming out of the break with an eight play drive that ended with another Konrardy field goal. Running back Aiden Flora had the play of the drive with a 34-yard scamper down to the Iowa 19, but holding and illegal substitution penalties stalled the drive leading to the Konrardy kick to put ISU up 13-10. Iowa's offense went in to hibernation as they could not get Kamari Moulton going on the ground, the Cyclones were clearly committed to stopping the run and it worked for much of the game. Iowa's first three drives of the second half went for only 21 yards (four plays), 8 yards (3 plays), and -5 yards (3 playes, not helped by a holding penalty on Dotzler). Woof.
#cyclones #game #state
After last week's performance against NIU and with a brand new regime in Ames, many expected this to be a much more comfortable game for the Hawkeyes, especially under the lights in Kinnick Stadium with a raucous crowd. But Iowa State put Iowa into an early 10-0 hole midway through the second quarter that had the black and gold faithful starting to get that "here we go again" familiar feeling. But the offense managed to come to life, thanks to a massive 56-yard bomb to Tony Diaz that set up a Hank Brown touchdown run late the first half. A huge 45-yard Buhr field goal right before halftime reset the score and setting up a grinding second half of football.
Neither team had a great first quarter. Iowa started with the ball but procedural penalties doomed their drive. Meanwhile the Hawkeye defense held the Cyclones to only six plays in the quarter. Iowa State managed to move the chains in the second quarter with drives of nine and ten plays that ended on a Kyle Konrardy field goal and 7-yard Jalen Raynor touchdown pass, respectively. Raynor's stat line tonight won't impress anyone: 10/19 for 117 yards, and no touchdowns with some crucial misfires on potential big plays. But aside from those misses he made no back breaking mistakes that allowed the Iowa defense to capitalize.
Hank Brown REACHES OUT for Iowa's first score.
📺 Big Ten Football on NBC & Peacock pic.twitter.com/PJpKvvqkKt
Iowa State regained their momentum coming out of the break with an eight play drive that ended with another Konrardy field goal. Running back Aiden Flora had the play of the drive with a 34-yard scamper down to the Iowa 19, but holding and illegal substitution penalties stalled the drive leading to the Konrardy kick to put ISU up 13-10. Iowa's offense went in to hibernation as they could not get Kamari Moulton going on the ground, the Cyclones were clearly committed to stopping the run and it worked for much of the game. Iowa's first three drives of the second half went for only 21 yards (four plays), 8 yards (3 plays), and -5 yards (3 playes, not helped by a holding penalty on Dotzler). Woof.
#cyclones #game #state


2 days ago
What's been exciting about Robinhood Chain (RHC) is seeing tokens attempt new mechanisms to answer questions like: why would someone hold this token? How can we make participating in this token attractive? And, more broadly, how can market activity around a token overall be designed to contribute to its success?
All new projects should ask this and the best ones do, but when you have a new chain, with a new market and new infrastructure, it can be sort of a "clean slate" or fresh design ***** e and breathe new life into the solutions to such questions.
The dominant answer right now seems to be distributions: hold this token and get stock, tokens, etc. Below are projects which execute this with a twist, expanding either the type of rewards or the source for rewards that end up in the hands of holders.
Others attempt to answer the second question, experimenting with new infrastructure that tries to make market activity, of whatever kind, directly contribute to the token's success.
These are all shared to give you a sense of what novelty can look like amidst this meta and act as a guiding force to understand what's been done, what's working, and overall where to direct your attention towards.
#make
All new projects should ask this and the best ones do, but when you have a new chain, with a new market and new infrastructure, it can be sort of a "clean slate" or fresh design ***** e and breathe new life into the solutions to such questions.
The dominant answer right now seems to be distributions: hold this token and get stock, tokens, etc. Below are projects which execute this with a twist, expanding either the type of rewards or the source for rewards that end up in the hands of holders.
Others attempt to answer the second question, experimenting with new infrastructure that tries to make market activity, of whatever kind, directly contribute to the token's success.
These are all shared to give you a sense of what novelty can look like amidst this meta and act as a guiding force to understand what's been done, what's working, and overall where to direct your attention towards.
#make


2 days ago
Coinbase (NASDAQ: COIN), one of the world's largest cryptocurrency exchanges, recently partnered with Moov, a payments infrastructure provider, to bring stablecoin payments and settlements to more than 1,000 U.S. community banks and credit unions. By integrating Coinbase's digital ******* et infrastructure into Moov's payments platform, the two companies will enable those financial institutions to accept stablecoins without building their own blockchains.
Let's see how this partnership could help Coinbase, why everyone is talking about stablecoins right now, and how the upcoming vote on the CLARITY Act could impact those plans.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Stablecoins are cryptocurrencies pegged to a stable fiat currency, such as the U.S. dollar or the euro, and can be held without a bank account. Their payments can be settled 24/7, enabling faster, cheaper money transfers than fiat currencies. They can be deposited in third-party lending platforms and liquidity pools to earn higher yields than traditional bank accounts.
Stablecoins can also allow people in countries with hyperinflation to preserve their savings without buying the underlying fiat currencies. They can also be used to accelerate cross-border transfers by acting as a "bridge currency" between the two fiat currencies.
#signal #Coinbase
Let's see how this partnership could help Coinbase, why everyone is talking about stablecoins right now, and how the upcoming vote on the CLARITY Act could impact those plans.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Stablecoins are cryptocurrencies pegged to a stable fiat currency, such as the U.S. dollar or the euro, and can be held without a bank account. Their payments can be settled 24/7, enabling faster, cheaper money transfers than fiat currencies. They can be deposited in third-party lending platforms and liquidity pools to earn higher yields than traditional bank accounts.
Stablecoins can also allow people in countries with hyperinflation to preserve their savings without buying the underlying fiat currencies. They can also be used to accelerate cross-border transfers by acting as a "bridge currency" between the two fiat currencies.
#signal #Coinbase


2 days ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management

2 days ago
Back in the late 70s and early 1980s, my small town had a mom-and-pop convenience store, Paul's Market, as well as one location of a regional chain, Richdale's. It later added a store from a larger chain, White Hen Pantry.
7-Eleven and other large chains existed, but local stores, even one-offs, were common. Now, just over the past few years, a number of bigger players have swallowed up some smaller chains.
The banner retirements are real and named, according to data from NACS Magazine.
GetGo was sold to Circle K, Redwood Markets went to Jacksons (24 stores, California), and Maverick bought the ****** & Go Brand, which included about 400 locations. In all three cases, the name changes were gradual as stores got remodeled, but in the end, the classic names disappeared.
Now, the same thing has happened again as Casey's has begun the process of removing the CEFCO name from the 198 stores it added when it bought the rival chain in 2024.
#store
7-Eleven and other large chains existed, but local stores, even one-offs, were common. Now, just over the past few years, a number of bigger players have swallowed up some smaller chains.
The banner retirements are real and named, according to data from NACS Magazine.
GetGo was sold to Circle K, Redwood Markets went to Jacksons (24 stores, California), and Maverick bought the ****** & Go Brand, which included about 400 locations. In all three cases, the name changes were gradual as stores got remodeled, but in the end, the classic names disappeared.
Now, the same thing has happened again as Casey's has begun the process of removing the CEFCO name from the 198 stores it added when it bought the rival chain in 2024.
#store


2 days ago
Interested in Lam Research Corporation? Here are five stocks we like better.
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced

2 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
An option contract's price rarely moves for just one reason. The stock shifts, time keeps passing, expectations for volatility rise and fall, and interest rates maintain their influence in the background. All of that gets folded into the cost of the contract, known as its premium. This makes it hard to tell which force actually moved the number on your screen.
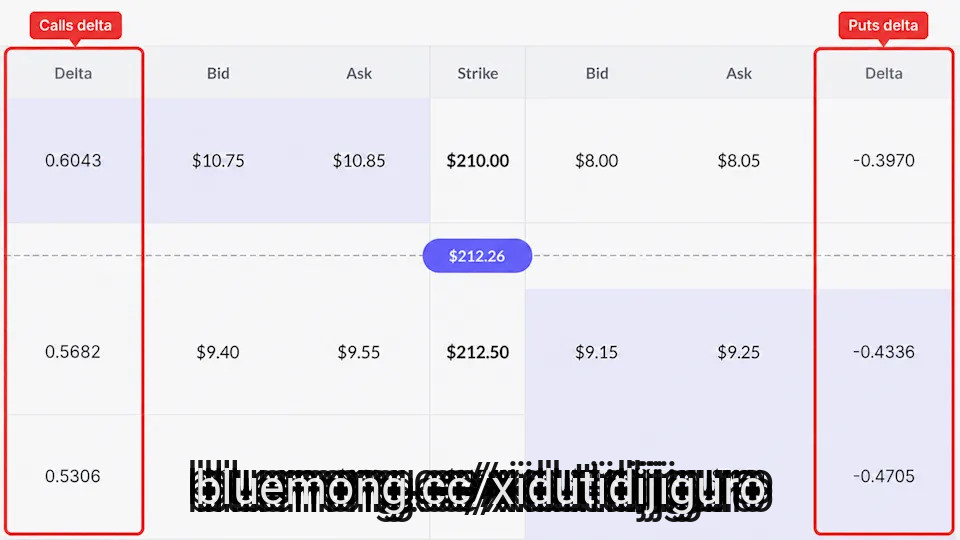
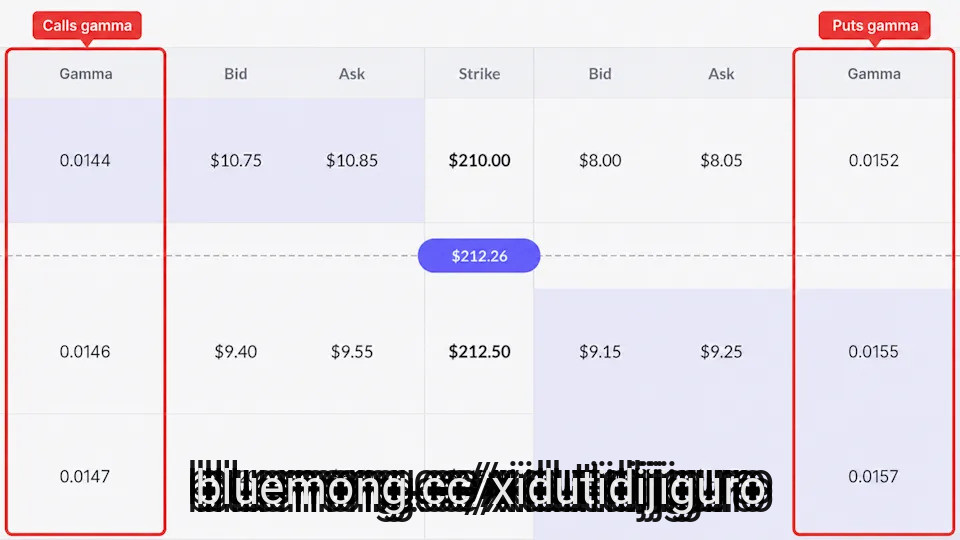
The options Greeks can help you solve that problem. Each one estimates how an option's value would respond to a change in one input, such as the stock price, time, or volatility, with the others held constant.
Let's follow a real contract to see how. Nvidia (NVDA) is one of the most actively traded stocks in the options market, which makes its chain a useful place to watch these numbers work. The stock was trading at $212.26 at the time, so we picked a $215 call expiring in 29 days.
Explore options contracts with AlphaSpace
#options #volatility #contract #disclosure
An option contract's price rarely moves for just one reason. The stock shifts, time keeps passing, expectations for volatility rise and fall, and interest rates maintain their influence in the background. All of that gets folded into the cost of the contract, known as its premium. This makes it hard to tell which force actually moved the number on your screen.
The options Greeks can help you solve that problem. Each one estimates how an option's value would respond to a change in one input, such as the stock price, time, or volatility, with the others held constant.
Let's follow a real contract to see how. Nvidia (NVDA) is one of the most actively traded stocks in the options market, which makes its chain a useful place to watch these numbers work. The stock was trading at $212.26 at the time, so we picked a $215 call expiring in 29 days.
Explore options contracts with AlphaSpace
#options #volatility #contract #disclosure
2 days ago
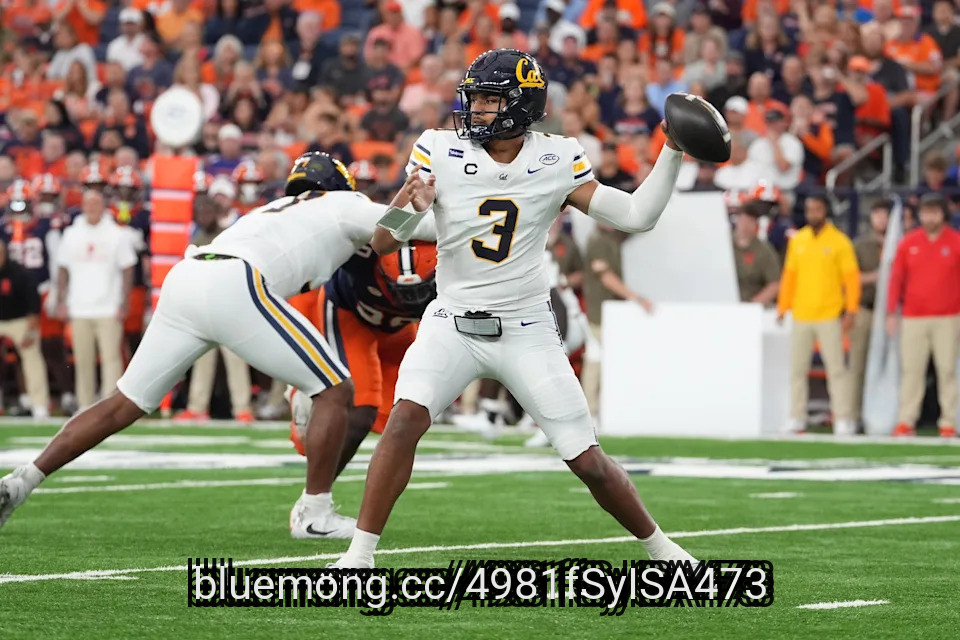
SYRACUSE, N.Y. — The Syracuse Orange missed several redzone opportunities, turned the ball over at costly times and committed numerous penalties to undo all of their hard work against the Golden Bears. A game in which the offensive numbers looked far better for Syracuse ended in a Cal 21-18 win when Golden Bears safety Kingston Lopa housed a pick six for the eventual winning score with 4:51 left in the 4th quarter.
Syracuse started the game with the ball, and fireworks showed immediately. Tylik Hill ripped a 55 yard rush on the second play of the game to immediately put the Orange in a goal-to-go situation. Syracuse couldn't convert and settled for a Tripp Woody field goal to open the scoring at 3-0.
Cal set its intentions early by playing in empty sets for much of its first drive. Although the Golden Bears got a first down, impressive pressure from Keyshawn Johnson and Dillan Fontus on 3rd down stalled the first Cal drive before midfield.
Syracuse's second drive saw the return of Justus Ross-Simmons, newly eligible after a long and nervous legal battle. He snagged the first Orange reception of the day, going 22 yards up the right sideline. Shavane Anderson Jr. also started to show that his first week performance wasn't a fluke with a pair of good eight-yard gains to move the chains. The Orange had to punt, however, to end their second drive of the day.
Cal showed more of its pass heavy offense, led by its star quarterback Jaron-Keawe Sagapolutele. After moving the chains with some good outside passes, JKS finally targeted his top receiver, Ian Strong on a third down play. Syracuse had ****** r Ward instead of Chris Peal covering Strong on this play, but Ward did a great job to force an incompletion and end Cal's second drive.
#orange #game #play #down
Syracuse started the game with the ball, and fireworks showed immediately. Tylik Hill ripped a 55 yard rush on the second play of the game to immediately put the Orange in a goal-to-go situation. Syracuse couldn't convert and settled for a Tripp Woody field goal to open the scoring at 3-0.
Cal set its intentions early by playing in empty sets for much of its first drive. Although the Golden Bears got a first down, impressive pressure from Keyshawn Johnson and Dillan Fontus on 3rd down stalled the first Cal drive before midfield.
Syracuse's second drive saw the return of Justus Ross-Simmons, newly eligible after a long and nervous legal battle. He snagged the first Orange reception of the day, going 22 yards up the right sideline. Shavane Anderson Jr. also started to show that his first week performance wasn't a fluke with a pair of good eight-yard gains to move the chains. The Orange had to punt, however, to end their second drive of the day.
Cal showed more of its pass heavy offense, led by its star quarterback Jaron-Keawe Sagapolutele. After moving the chains with some good outside passes, JKS finally targeted his top receiver, Ian Strong on a third down play. Syracuse had ****** r Ward instead of Chris Peal covering Strong on this play, but Ward did a great job to force an incompletion and end Cal's second drive.
#orange #game #play #down


2 days ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


2 days ago
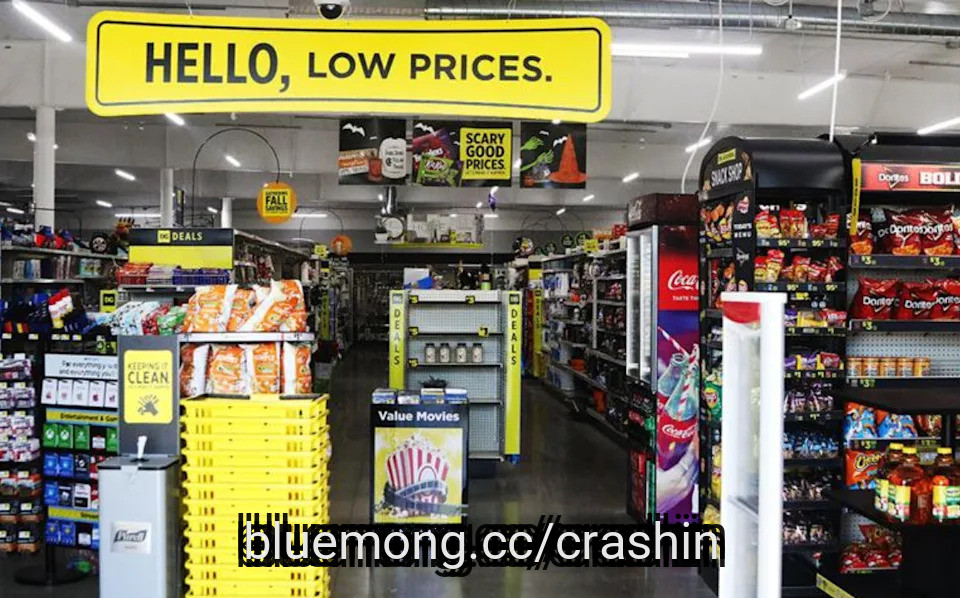
As continuous inflation squeezes household budgets, the discount retail sector should potentially benefit across the board, with middle- and lower-income consumers looking for value driving foot traffic into value chains. That's roughly what happened in the second-quarter reports from Dollar General Corporation (NYSE:DG) and Dollar Tree, Inc. (NASDAQ:DLTR), both of which were released in late August. Both retailers outperformed expectations, though only one company's stock was rewarded for this.
Dollar General Corporation (NYSE:DG) reported second-quarter results on August 27 that exceeded expectations, and shares rose more than 6.5% in premarket trading. Net sales increased 5.2% to $11.29 billion, surpassing the $11.2 billion market forecast, while diluted EPS came in at $2.48, up 33.3% year-over-year and well above the $2.01 ******* ysts projected. Same-store sales increased 3.5%, driven by a 2.0% increase in customer traffic and a 1.5% increase in average transaction amount, marking the fifth consecutive quarter of traffic growth and the sixth consecutive quarter of positive comps across all four merchandise categories.
Management improved their full-year estimate across the board: same-store sales growth is now expected to be 2.5% to 2.9%, up from 2.2% to 2.7% before, while full-year EPS guidance increased to $7.80-$8.00 from $7.20-$7.45. Tariff refunds, a lower LIFO provision, and improved shrink and damages helped increase the gross margin by 127 basis points to 32.6%. CEO Todd Vasos also pointed to continued market share gains from higher-income households switching away from traditional grocers, a trend the company has cited for several quarters, with management announcing plans to resume up to $700 million in share buybacks in the latter half of the year, backed by remodels under its Project Renovate and Project Elevate initiatives.
Dollar Tree's results, released on August 27, indicate a more complicated situation. Diluted EPS came in at $2.70, including a $1.31-per-share net benefit related to tariff refunds, while revenue increased 7% year-over-year to $4.89 billion. Comparable store sales up 3.7%, driven by a 3.3% gain in average ticket and a 0.4% increase in traffic, a return to positive traffic that occurred a full quarter ahead of management's internal plan.
However, the headline figure includes an important caveat: $1.31 of the $2.70 in EPS came from the net impact of $383 million in IEEPA tariff refunds after related reinvestment spending, duties, and taxes. Strip that out, and underlying EPS was $1.39, above the $1.00-$1.15 range management had guided to in May and about 23% above the $1.13 consensus estimate.
#TRAFFIC
Dollar General Corporation (NYSE:DG) reported second-quarter results on August 27 that exceeded expectations, and shares rose more than 6.5% in premarket trading. Net sales increased 5.2% to $11.29 billion, surpassing the $11.2 billion market forecast, while diluted EPS came in at $2.48, up 33.3% year-over-year and well above the $2.01 ******* ysts projected. Same-store sales increased 3.5%, driven by a 2.0% increase in customer traffic and a 1.5% increase in average transaction amount, marking the fifth consecutive quarter of traffic growth and the sixth consecutive quarter of positive comps across all four merchandise categories.
Management improved their full-year estimate across the board: same-store sales growth is now expected to be 2.5% to 2.9%, up from 2.2% to 2.7% before, while full-year EPS guidance increased to $7.80-$8.00 from $7.20-$7.45. Tariff refunds, a lower LIFO provision, and improved shrink and damages helped increase the gross margin by 127 basis points to 32.6%. CEO Todd Vasos also pointed to continued market share gains from higher-income households switching away from traditional grocers, a trend the company has cited for several quarters, with management announcing plans to resume up to $700 million in share buybacks in the latter half of the year, backed by remodels under its Project Renovate and Project Elevate initiatives.
Dollar Tree's results, released on August 27, indicate a more complicated situation. Diluted EPS came in at $2.70, including a $1.31-per-share net benefit related to tariff refunds, while revenue increased 7% year-over-year to $4.89 billion. Comparable store sales up 3.7%, driven by a 3.3% gain in average ticket and a 0.4% increase in traffic, a return to positive traffic that occurred a full quarter ahead of management's internal plan.
However, the headline figure includes an important caveat: $1.31 of the $2.70 in EPS came from the net impact of $383 million in IEEPA tariff refunds after related reinvestment spending, duties, and taxes. Strip that out, and underlying EPS was $1.39, above the $1.00-$1.15 range management had guided to in May and about 23% above the $1.13 consensus estimate.
#TRAFFIC

2 days ago
On September 3, Genesco (NYSE:GCO) reported a second quarter that should not have worked on paper. Revenue fell 3% to $530 million, yet the company nearly halved its adjusted operating loss and raised full-year earnings guidance to the top end of its range. That combination, shrinking sales alongside expanding profit, is the footwear-first strategy showing up in real numbers. Every one of the company's three brands beat internal expectations, and management says the toughest sales pressure ahead is coming from a deliberate choice rather than a weakening business.
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure

3 days ago
Kroger (KR) stock has inched lower ahead of the department store chain's fiscal Q2 results, which are set to be published before the market opens on Sept. 11. Consensus is for the retailer to post $1.05 a share of earnings (EPS) for the quarter, which would represent a 0.96% increase versus last year.
The earnings event comes as Kroger shares have fallen out of favor with investors, currently down nearly 25% versus their year-to-date high.
Why It's Time to Load Up on Intel Stock
Nvidia CEO Jensen Huang Just Called CrowdStrike Its Top Security Partner. How to Play CRWD Stock Here.
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
#year #sept #consensus #Intel
The earnings event comes as Kroger shares have fallen out of favor with investors, currently down nearly 25% versus their year-to-date high.
Why It's Time to Load Up on Intel Stock
Nvidia CEO Jensen Huang Just Called CrowdStrike Its Top Security Partner. How to Play CRWD Stock Here.
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
#year #sept #consensus #Intel


3 days ago
Conagra Brands, Inc. (NYSE:CAG) faces a governance test alongside its turnaround. Reuters reported on September 7 that Institutional Shareholder Services, or ISS, recommended opposing executive compensation, citing weak financial performance and inadequately explained incentive targets.
The September 23 non-binding advisory vote covers fiscal 2026 named-executive compensation. It does not separately approve new CEO John Brase's package. Brase succeeded Sean Connolly on June 1, after fiscal 2026 ended, separating his compensation arrangements from the prior year's pay decisions.
The proxy lists Brase's annual base salary at $1.15 million, his annual incentive target at 150% of eligible salary, and annual long-term incentives of $7.3 million, split 60% into performance shares and 40% into restricted stock units. Incentive opportunities are not guaranteed realized pay.
Conagra Brands, Inc. (NYSE:CAG) needs executives willing to work through changes whose benefits may take several years to appear. Brase's priorities include restoring margins, investing in brands and the supply chain, simplifying operations, and rebalancing capital allocation.
A mix of performance awards and service-based equity can support that effort. Performance shares link rewards to results, while restricted units help retain leaders through disruption. Retention has value if it allows management to complete difficult changes instead of optimizing the next quarterly result.
#performance
The September 23 non-binding advisory vote covers fiscal 2026 named-executive compensation. It does not separately approve new CEO John Brase's package. Brase succeeded Sean Connolly on June 1, after fiscal 2026 ended, separating his compensation arrangements from the prior year's pay decisions.
The proxy lists Brase's annual base salary at $1.15 million, his annual incentive target at 150% of eligible salary, and annual long-term incentives of $7.3 million, split 60% into performance shares and 40% into restricted stock units. Incentive opportunities are not guaranteed realized pay.
Conagra Brands, Inc. (NYSE:CAG) needs executives willing to work through changes whose benefits may take several years to appear. Brase's priorities include restoring margins, investing in brands and the supply chain, simplifying operations, and rebalancing capital allocation.
A mix of performance awards and service-based equity can support that effort. Performance shares link rewards to results, while restricted units help retain leaders through disruption. Retention has value if it allows management to complete difficult changes instead of optimizing the next quarterly result.
#performance
3 days ago
Horizon Technology Finance Corp., an affiliate of Monroe Capital, on September 10 said that the RoHo Capital Opportunity Fund LLC, a joint venture formed by Horizon and CR Financial Holdings, Inc., the holding company for Roth Capital Partners, LLC, has provided a $20-million senior credit facility to NeoVolta, Inc., with the ability to increase the facility to $30 million upon mutual agreement. An initial $20 million was funded at closing to support NeoVolta's continued growth.NeoVolta is an energy technology company focused on developing and manufacturing domestic battery energy storage systems (BESS). Together with its joint venture partner LONGi, NeoVolta is developing a 210,600-square-foot manufacturing facility in Pendergrass, Georgia, to produce BESS systems designed to meet U.S. domestic content and supply-chain requirements. The facility is expected to have an initial annual production capacity of up to 2 GWh, with the potential to scale to 8 GWh over time."Providing growth capital to innovative companies operating in attractive, high-growth markets is a core focus of RoHo's investment strategy," said Paul Seitz, chief investment officer of Horizon. "Formed by Horizon and Roth Capital, RoHo pairs Horizon's venture lending and structuring expertise with Roth's deep public markets relationships to deliver flexible growth capital to small- and micro-cap public companies. We are pleased to support NeoVolta's growth plans with a tailored financing solution and look forward to continuing to deploy capital through RoHo in support of innovative public companies pursuing significant market opportunities.""Horizon and Roth Capital bring valuable experience and a collaborative approach as we advance NeoVolta's domestic battery energy storage systems manufacturing platform," said Ardes Johnson, CEO of NeoVolta. "As we ramp our Georgia facility and pursue larger commercial and utility-scale opportunities, this relationship supports our ability to execute on our long-term growth strategy."Horizon Technology Finance Corp. is a specialty finance company that provides capital in the form of secured loans to venture capital and private equity-backed companies and publicly traded companies in the technology, life science, healthcare information and services, and sustainability industries. The investment objective of Horizon is to maximize its investment portfolio's return by generating current income from the debt investments it makes and capital appreciation from the warrants it receives when making such debt investments. Horizon is headquartered in Farmington, Connecticut, with a regional office in Pleasanton, California, and investment professionals located throughout the U.S.Monroe Capital is a premier ****** et management firm specializing in private credit markets across various strategies, including direct lending, technology finance, venture debt, opportunistic, structured credit, real estate and equity.CR Financial Holdings, Inc., is a private hol


3 days ago
Sky Protocol, earlier known as MakerDAO, is a decentralized finance (DeFi) project built on Ethereum.
The crypto project is best known for its USDS stablecoin. Pegged 1:1 to the U.S. dollar, USDS attempts to keep its value the same as that of the dollar.
As per the onchain ****** ytics platform DeFiLlama, USDS has a market cap of more than $6 billion and accounts for over 2% of the total stablecoin market.
Sky Protocol's governance token, SKY, gives holders the right to vote on the protocol's future. With a market cap of $1.38 billion, SKY is the 62nd largest cryptocurrency.
Related: Explained: What is a stablecoin?
#stablecoin #project #dollar #billion
The crypto project is best known for its USDS stablecoin. Pegged 1:1 to the U.S. dollar, USDS attempts to keep its value the same as that of the dollar.
As per the onchain ****** ytics platform DeFiLlama, USDS has a market cap of more than $6 billion and accounts for over 2% of the total stablecoin market.
Sky Protocol's governance token, SKY, gives holders the right to vote on the protocol's future. With a market cap of $1.38 billion, SKY is the 62nd largest cryptocurrency.
Related: Explained: What is a stablecoin?
#stablecoin #project #dollar #billion


3 days ago
USA Rare Earth, Inc. (NASDAQ:USAR) announced on September 4 that it completed the Serra Verde acquisition one day earlier, paying $300 million in cash and issuing approximately 126.8 million common shares. The transaction adds Brazil's Pela Ema mine to Less Common Metals in the United Kingdom, the Stillwater, Oklahoma, magnet facility, and the Round Top project in Texas.
Serra Verde began production in January 2024 but is still completing optimization and commissioning. Stage 1 is expected to reach an annual run rate of approximately 4,000 metric tons of total rare-earth oxide, or TREO, by year-end 2026. Stage 2 construction targets average annual production of 6,400 metric tons, with commissioning expected to begin within 12 months.
Serra Verde had $425 million of principal outstanding under its U.S. International Development Finance Corporation loan at June 30. At closing, a $100 million tranche was extinguished after related warrants were exercised, leaving approximately $325 million of principal. The unaudited pro forma combined balance sheet reported a $304.1 million debt carrying value after discounts and issuance costs.
Serra Verde gives USA Rare Earth, Inc. (NASDAQ:USAR) a producing source of dysprosium, terbium, and other rare earths used in permanent magnets. Combining mining, metals, alloys, and magnet manufacturing could capture more of the value chain outside Asia.
The Phase 1 offtake agreement supports revenue visibility. It covers 100% of Pela Ema's Phase 1 products, subject to limited carve-outs, and includes escalating price floors annually. The counterparty is a special-purpose vehicle capitalized by the U.S. government and private investors. The arrangement provides contractual price protection, subject to the counterparty's performance.
#earth #approximately #NASDAQ #usar
Serra Verde began production in January 2024 but is still completing optimization and commissioning. Stage 1 is expected to reach an annual run rate of approximately 4,000 metric tons of total rare-earth oxide, or TREO, by year-end 2026. Stage 2 construction targets average annual production of 6,400 metric tons, with commissioning expected to begin within 12 months.
Serra Verde had $425 million of principal outstanding under its U.S. International Development Finance Corporation loan at June 30. At closing, a $100 million tranche was extinguished after related warrants were exercised, leaving approximately $325 million of principal. The unaudited pro forma combined balance sheet reported a $304.1 million debt carrying value after discounts and issuance costs.
Serra Verde gives USA Rare Earth, Inc. (NASDAQ:USAR) a producing source of dysprosium, terbium, and other rare earths used in permanent magnets. Combining mining, metals, alloys, and magnet manufacturing could capture more of the value chain outside Asia.
The Phase 1 offtake agreement supports revenue visibility. It covers 100% of Pela Ema's Phase 1 products, subject to limited carve-outs, and includes escalating price floors annually. The counterparty is a special-purpose vehicle capitalized by the U.S. government and private investors. The arrangement provides contractual price protection, subject to the counterparty's performance.
#earth #approximately #NASDAQ #usar


3 days ago
Solana (SOL) has been trading relatively range-bound lately, but bulls have managed to defend the $100 psychological threshold ahead of the Federal Reserve's interest rate decision.
The macroeconomic backdrop continues to be challenging for cryptocurrencies, as inflation in the United States is nearly 200 basis points higher than the central bank's target.
Odds of a rate hike in September have now jumped to 62%, up from a recent low of 50%. Meanwhile, the Treasury Department's decision to triple its bond buybacks did little to change the market's cautious attitude.
As a result, the latest crypto rally has stalled, with SOL experiencing a mild 0.7% advance in the past 7 days.
However, an on-chain metric seems to be indicating that a massive price move is about to take place based on historical patterns.
#rate #meanwhile
The macroeconomic backdrop continues to be challenging for cryptocurrencies, as inflation in the United States is nearly 200 basis points higher than the central bank's target.
Odds of a rate hike in September have now jumped to 62%, up from a recent low of 50%. Meanwhile, the Treasury Department's decision to triple its bond buybacks did little to change the market's cautious attitude.
As a result, the latest crypto rally has stalled, with SOL experiencing a mild 0.7% advance in the past 7 days.
However, an on-chain metric seems to be indicating that a massive price move is about to take place based on historical patterns.
#rate #meanwhile



3 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted The Elmet Group Co. (NASDAQ:ELMT). The Elmet Group Co. (NASDAQ:ELMT) manufactures and sells precision-engineered components and high-energy systems for the aerospace, defense and government, industrial, medical, semiconductor and electronics, and energy industries. On September 09, 2026, The Elmet Group Co. (NASDAQ:ELMT) closed at $16.46 per share. Over the past month The Elmet Group Co. (NASDAQ:ELMT) declined 4.02% and its shares lost 15.29% over the past 3 months. The Elmet Group Co. (NASDAQ:ELMT) has a market capitalization of $511.11 million and its stock has traded within a 52-week range of $12.49 to $22.51.
Prosper Stars & Stripes stated the following regarding The Elmet Group Co. (NASDAQ:ELMT) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense (AADX) and The Elmet Group Co. (NASDAQ:ELMT). Elmet's critical materials division supplies inputs for the U.S. military supply chain that are essential to production and increasingly must be sourced domestically, steering business towards the company. We believe the building of domestic supply chains can benefit Elmet and drive better-than-forecast earnings growth as they grow organically and deploy their underutilized balance sheet to broaden their businesses."
The Elmet Group Co. (NASDAQ:ELMT) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 19 hedge fund portfolios held The Elmet Group Co. (NASDAQ:ELMT) at the end of the second quarter which was 0 in the previous quarter. While we acknowledge the potential of The Elmet Group Co. (NASDAQ:ELMT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted The Elmet Group Co. (NASDAQ:ELMT). The Elmet Group Co. (NASDAQ:ELMT) manufactures and sells precision-engineered components and high-energy systems for the aerospace, defense and government, industrial, medical, semiconductor and electronics, and energy industries. On September 09, 2026, The Elmet Group Co. (NASDAQ:ELMT) closed at $16.46 per share. Over the past month The Elmet Group Co. (NASDAQ:ELMT) declined 4.02% and its shares lost 15.29% over the past 3 months. The Elmet Group Co. (NASDAQ:ELMT) has a market capitalization of $511.11 million and its stock has traded within a 52-week range of $12.49 to $22.51.
Prosper Stars & Stripes stated the following regarding The Elmet Group Co. (NASDAQ:ELMT) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense (AADX) and The Elmet Group Co. (NASDAQ:ELMT). Elmet's critical materials division supplies inputs for the U.S. military supply chain that are essential to production and increasingly must be sourced domestically, steering business towards the company. We believe the building of domestic supply chains can benefit Elmet and drive better-than-forecast earnings growth as they grow organically and deploy their underutilized balance sheet to broaden their businesses."
The Elmet Group Co. (NASDAQ:ELMT) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 19 hedge fund portfolios held The Elmet Group Co. (NASDAQ:ELMT) at the end of the second quarter which was 0 in the previous quarter. While we acknowledge the potential of The Elmet Group Co. (NASDAQ:ELMT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr


3 days ago
Mike Evans had to travel outside the United States to score his first touchdown in a San Francisco 49ers uniform. The former Texas A&M star caught six passes for 49 yards and a touchdown during San Francisco's 27-7 victory over the Los Angeles Rams in Melbourne, Australia.
After spending 12 seasons in Tampa Bay, where he owns virtually every major Buccaneers receiving record, the future Hall of Famer proved he still has plenty to offer. Evans tied Deebo Samuel for the team lead with six receptions and averaged 8.2 yards per catch. More importantly, three of his catches moved the chains on third down, and his touchdown also came on third down.
It was only one game, and Evans may no longer have the youthful legs he once did, but he still knows how to get open and make contested catches. His 109th career touchdown reception was a perfect example.
After Samuel opened the second half with a 45-yard kickoff return, the 49ers quickly moved into the red zone. That is where Evans came through. It was nothing complicated. Evans used an outside release, and Brock Purdy gave him an opportunity to make a play. Evans went over the defensive back and pulled down the two-yard touchdown to give San Francisco a 17-7 lead.
You can watch the catch below.
#touchdown #francisco #samuel
After spending 12 seasons in Tampa Bay, where he owns virtually every major Buccaneers receiving record, the future Hall of Famer proved he still has plenty to offer. Evans tied Deebo Samuel for the team lead with six receptions and averaged 8.2 yards per catch. More importantly, three of his catches moved the chains on third down, and his touchdown also came on third down.
It was only one game, and Evans may no longer have the youthful legs he once did, but he still knows how to get open and make contested catches. His 109th career touchdown reception was a perfect example.
After Samuel opened the second half with a 45-yard kickoff return, the 49ers quickly moved into the red zone. That is where Evans came through. It was nothing complicated. Evans used an outside release, and Brock Purdy gave him an opportunity to make a play. Evans went over the defensive back and pulled down the two-yard touchdown to give San Francisco a 17-7 lead.
You can watch the catch below.
#touchdown #francisco #samuel


3 days ago
Daktronics Inc. (NASDAQ:DAKT) reported its Q1 FY27 results, showing continued momentum across core segments and its strategic push. The company reported topline figures of $234.6 million, which grew 7.1% compared to the same period last year. This growth was primarily driven by impressive numbers across the Live Events, Transportation, and International units. The diluted EPS of $0.40 was the highest quarterly figure in the last twelve quarters, exhibiting a substantial growth of more than 21%. The business generated $31.4 million in cash from operations, which pushed the cash balance to $154.6 million by the quarter end, after accounting for $4.4 million expenditure on share repurchases.
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results


3 days ago
On September 8, 2026, GE Aerospace (NYSE:GE) agreed to buy Consolidated Precision Products (CPP) for $11.75 billion. The acquisition marks the company's largest bet yet on precision engine castings, a constraint that has been capping GE's growth. Trading already at roughly 40x earnings, the company has now attacked one of its genuine bottlenecks through the deal. But has it paid too much to do it?
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including


3 days ago
Casey's General Stores Inc. (NASDAQ:CASY), the third-largest convenience chain and fifth-biggest pizza brand within the U.S., released its first quarter results, showing early traction from the company's recently announced three-year strategic plan. For the recent quarter, inside same-store sales jumped 3.2% year-over-year, and 7.7% on a two-year stacked basis, leading to inside margins of 42.2%. Total inside gross profit stood at $749.8 million, rising 6.3% compared to the same period last year. The company posted net income of $273.7 million, exhibiting a 27.1% increase relative to Q1 last year. This translated into a 27.7% jump in diluted EPS which rose to $7.37.
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest



