1 min. ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
For millions of Americans, handing a driver's license to a rental-car agent, hotel clerk or security guard is a routine transaction that barely warrants a second thought.
But what happens when the system designed to verify your identity becomes a tool that can help criminals steal it?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A record 45% of central banks plan to grow gold reserves — and many investors are following suit. Get your free gold IRA guide from Priority Gold
#Gold #rental
For millions of Americans, handing a driver's license to a rental-car agent, hotel clerk or security guard is a routine transaction that barely warrants a second thought.
But what happens when the system designed to verify your identity becomes a tool that can help criminals steal it?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A record 45% of central banks plan to grow gold reserves — and many investors are following suit. Get your free gold IRA guide from Priority Gold
#Gold #rental

14 mins. ago
Dell Technologies (DELL) and Hewlett Packard Enterprise (HPE) found themselves at the top of the S&P 500 on the back of Oracle's (ORCL) forceful reminder of how much money is still flowing into AI infrastructure.
Dell's stock soared 12% on Sept. 11, while HPE was another of the index's best performers. Investors quickly saw the connection: Oracle needs plenty of servers, networking gear, and other data center hardware to keep up with surging AI demand.
Oracle's fiscal first-quarter results supported this trend. Total revenue rose 30% to $19.3 billion, while cloud infrastructure revenue surged 121% to $7.4 billion. Even more impressive, remaining performance obligations rose $209 billion to $664 billion.
That backlog presents a potential strong read-through for Dell and HPE.
But there is another side to this tale. The businesses fueling the AI boom are more and more fixated on the costs of borrowing and the next actions by the Federal Reserve as they pour unusual amounts of resources into building enough data centers to translate Oracle's contracts into income.
#infrastructure #revenue
Dell's stock soared 12% on Sept. 11, while HPE was another of the index's best performers. Investors quickly saw the connection: Oracle needs plenty of servers, networking gear, and other data center hardware to keep up with surging AI demand.
Oracle's fiscal first-quarter results supported this trend. Total revenue rose 30% to $19.3 billion, while cloud infrastructure revenue surged 121% to $7.4 billion. Even more impressive, remaining performance obligations rose $209 billion to $664 billion.
That backlog presents a potential strong read-through for Dell and HPE.
But there is another side to this tale. The businesses fueling the AI boom are more and more fixated on the costs of borrowing and the next actions by the Federal Reserve as they pour unusual amounts of resources into building enough data centers to translate Oracle's contracts into income.
#infrastructure #revenue


28 mins. ago
SWKS surged 27% in a month to $88.35, now trading above its $68.35 consensus ****** yst target with most ****** ysts rating it Hold or worse.
The Qorvo merger could unlock $500M+ in synergies, but a regulatory delay leaves Skyworks holding $2B in new debt against shrinking revenue.
At 46x trailing P/E with 14 downward EPS revisions and the CFO selling into the rally, momentum is doing all the heavy lifting.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
At $88.35, Skyworks Solutions (NASDAQ:SWKS) is a Hold. The stock has ripped past its consensus ****** yst price target of $68.35, and with a pending merger, a fresh capital allocation framework, and a mixed fundamental picture, the case for chasing here is as thin as the case for stepping in front of the momentum.
#skyworks #solutions #analyst #target
The Qorvo merger could unlock $500M+ in synergies, but a regulatory delay leaves Skyworks holding $2B in new debt against shrinking revenue.
At 46x trailing P/E with 14 downward EPS revisions and the CFO selling into the rally, momentum is doing all the heavy lifting.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Skyworks Solutions didn't make the cut. Enter your email to see the names that beat SWKS. The report is free. Enter your email and see if any of your stocks made the cut.
At $88.35, Skyworks Solutions (NASDAQ:SWKS) is a Hold. The stock has ripped past its consensus ****** yst price target of $68.35, and with a pending merger, a fresh capital allocation framework, and a mixed fundamental picture, the case for chasing here is as thin as the case for stepping in front of the momentum.
#skyworks #solutions #analyst #target

30 mins. ago
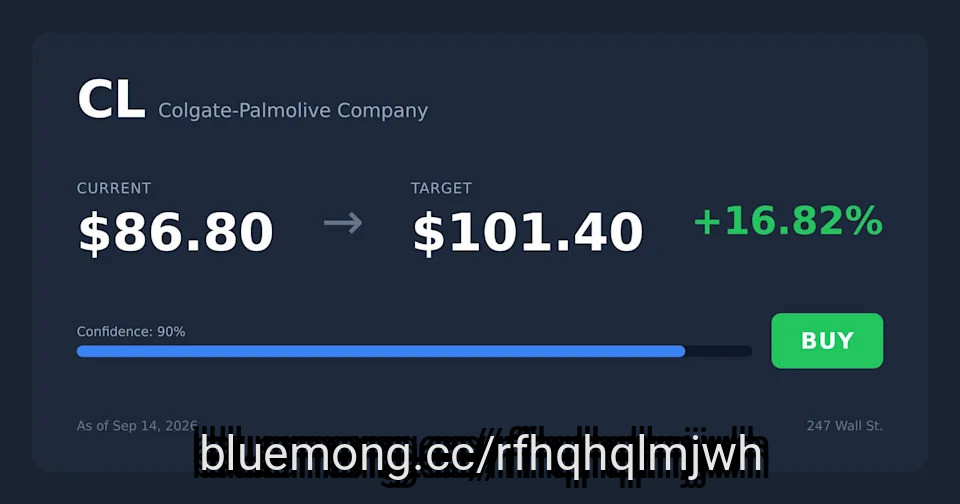
Colgate-Palmolive (CL) hired Goldman Sachs to explore selling Softsoap, Irish Spring, and Speed Stick as North America revenue fell 3% in Q2 2026.
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish

32 mins. ago
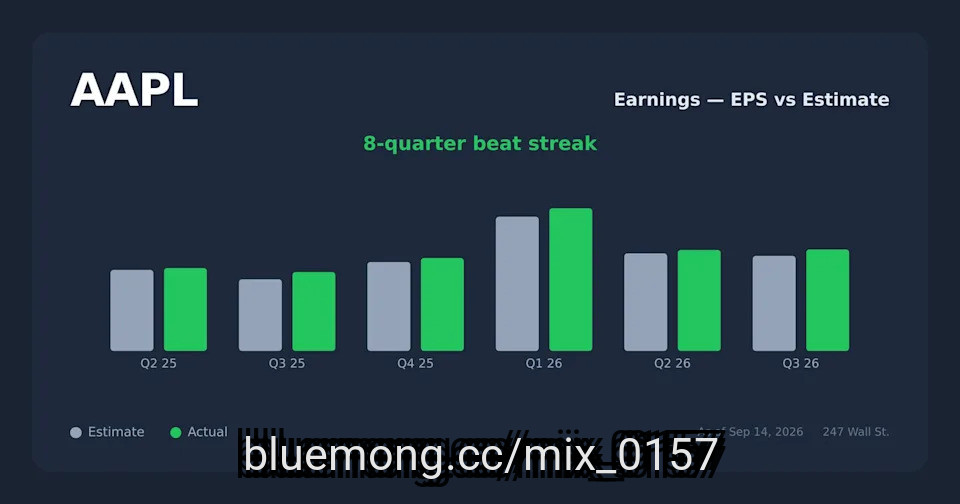
Apple trades at 37x earnings after a 45% one-year run; Microsoft sits at 27x and is up just 3% year to date, offering a cheaper AI entry point.
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks



39 mins. ago
"Hearst Magazines and Yahoo may earn commission or revenue on some items through these links."
It's been 84 years two months since Taylor Swift and Travis Kelce got married at Madison Square Garden in New York City, and the couple managed to keep the wedding completely private. There are no leaked photos to speak of, and we still haven't seen pics of Tay's wedding dress—a Dior haute couture gown designed by Jonathan Anderson.
So, why hasn't Tay shared photos of her and Travis's big day yet—and when can fans expect them to drop?
The New York Times previously noted that a Dior spokesman said photos would be shared "after Swift herself posts the first pictures on her Instagram." Which obviously hasn't happened just yet! And now a source tells the Daily Mail that Taylor is simply doing things on her own terms.
While Taylor has been "very secretive" about her exact plans, she's waiting for buzz about the wedding to calm down a bit before sharing photos. But "when she eventually does, it's not going to be transactional. She's not going to suddenly release her wedding photos to sell an album or coincide with some big announcement."
#taylor #wedding
It's been 84 years two months since Taylor Swift and Travis Kelce got married at Madison Square Garden in New York City, and the couple managed to keep the wedding completely private. There are no leaked photos to speak of, and we still haven't seen pics of Tay's wedding dress—a Dior haute couture gown designed by Jonathan Anderson.
So, why hasn't Tay shared photos of her and Travis's big day yet—and when can fans expect them to drop?
The New York Times previously noted that a Dior spokesman said photos would be shared "after Swift herself posts the first pictures on her Instagram." Which obviously hasn't happened just yet! And now a source tells the Daily Mail that Taylor is simply doing things on her own terms.
While Taylor has been "very secretive" about her exact plans, she's waiting for buzz about the wedding to calm down a bit before sharing photos. But "when she eventually does, it's not going to be transactional. She's not going to suddenly release her wedding photos to sell an album or coincide with some big announcement."
#taylor #wedding


1 day ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify


1 day ago
Private equity advisers are racing to leverage AI and automate the services they provide to fund managers and their investors. Law firms, such as Kirkland & Ellis, have been among the most active adopters.
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private

1 day ago
Dell Technologies (DELL) stock more than quadrupled over the past year, a 323% gain, against about 18% for the S&P 500, and even Hewlett Packard Enterprise (HPE), up 130.6%, finished far behind. Management had described most of the drivers before the run began: customers sitting on old servers, AI orders that had outrun shipments earlier in the year, and costs falling while sales rose. Those signs could not tell you how far the stock would go.
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
1 day ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ***** ysis, subscribe to Bisnow's free suite of newsletters.
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses


1 day ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Bank accounts are important financial tools that help protect your money and even allow you to earn interest. But depending on where you bank — and how you use your account — certain fees can chip away at your balance. From monthly maintenance charges to overdraft penalties, these costs can add up quickly if you're not paying attention.
Understanding the most common bank fees, why financial institutions charge them, and how to avoid them can help you keep more of your money.
Fees serve as added revenue for banks. If a bank charges a fee for account maintenance or an optional service, the institution can put those funds toward operational expenses and even generate additional income — at the customer's expense. After all, a bank is a business, and a business's goal is to earn money.
Recent data shows that banks have become increasingly dependent on fees over the years, especially those charged for overdrafts and non-sufficient funds (NSF). In fact, according to the Consumer Finance Protection Bureau (CFPB), NSF and overdraft fees account for about two-thirds of a typical bank's fee-based revenue.
#financial #Help
Bank accounts are important financial tools that help protect your money and even allow you to earn interest. But depending on where you bank — and how you use your account — certain fees can chip away at your balance. From monthly maintenance charges to overdraft penalties, these costs can add up quickly if you're not paying attention.
Understanding the most common bank fees, why financial institutions charge them, and how to avoid them can help you keep more of your money.
Fees serve as added revenue for banks. If a bank charges a fee for account maintenance or an optional service, the institution can put those funds toward operational expenses and even generate additional income — at the customer's expense. After all, a bank is a business, and a business's goal is to earn money.
Recent data shows that banks have become increasingly dependent on fees over the years, especially those charged for overdrafts and non-sufficient funds (NSF). In fact, according to the Consumer Finance Protection Bureau (CFPB), NSF and overdraft fees account for about two-thirds of a typical bank's fee-based revenue.
#financial #Help


1 day ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Angel investor and All-In Podcast host Jason Calacanis warned that allowing Chinese electric vehicles into the U.S. could devastate domestic automakers even as their low prices attract consumers, reacting to Sen. Elissa Slotkin's (D-Mich.) claim that President Donald Trump could loosen barriers as part of a China deal.
"This would be the end of the US automotive industry — but consumers will love to buy these cars," Calacanis wrote in an X post on Wednesday. He added, "Everywhere I go, from the Middle East to Europe to Mexico, the streets and Uber fleets are filled with dirt-cheap Chinese EVs," calling such U.S. access "a disaster."
This would be the end of the US automotive industry — but consumers will love to buy these cars
But…. You'll probably die in one since they're not very safe
Everywhere I go, from the Middle East to Europe to Mexico, the streets and uber fleets are filled with dirt cheap… https://t.co/LGUwforT6a
— jason (Jason) September 10, 2026
#calacanis #chinese #Europe #uber
Angel investor and All-In Podcast host Jason Calacanis warned that allowing Chinese electric vehicles into the U.S. could devastate domestic automakers even as their low prices attract consumers, reacting to Sen. Elissa Slotkin's (D-Mich.) claim that President Donald Trump could loosen barriers as part of a China deal.
"This would be the end of the US automotive industry — but consumers will love to buy these cars," Calacanis wrote in an X post on Wednesday. He added, "Everywhere I go, from the Middle East to Europe to Mexico, the streets and Uber fleets are filled with dirt-cheap Chinese EVs," calling such U.S. access "a disaster."
This would be the end of the US automotive industry — but consumers will love to buy these cars
But…. You'll probably die in one since they're not very safe
Everywhere I go, from the Middle East to Europe to Mexico, the streets and uber fleets are filled with dirt cheap… https://t.co/LGUwforT6a
— jason (Jason) September 10, 2026
#calacanis #chinese #Europe #uber
1 day ago
HIVE Digital Technologies (Nasdaq: HIVE), a Canada-based Bitcoin miner and data center operator that trades on the Nasdaq and Toronto Stock Exchange, said it has exceeded $1 million in daily revenue on Aug. 21.
The milestone combined income from Bitcoin mining and GPU cloud services for the first time at that level, according to preliminary, unaudited management estimates.
Since that date, the company has produced an average of approximately 12 Bitcoin per day, representing roughly 2% of global Bitcoin network production.
Its GPU cloud operations, run through wholly owned subsidiary BUZZ HPC, a sovereign AI cloud and high-performance computing provider, have generated approximately $100,000 in average daily revenue over the same period.
Related: Man declares bankruptcy with 34 cents while hiding millions
#Bitcoin #hive #daily #average
The milestone combined income from Bitcoin mining and GPU cloud services for the first time at that level, according to preliminary, unaudited management estimates.
Since that date, the company has produced an average of approximately 12 Bitcoin per day, representing roughly 2% of global Bitcoin network production.
Its GPU cloud operations, run through wholly owned subsidiary BUZZ HPC, a sovereign AI cloud and high-performance computing provider, have generated approximately $100,000 in average daily revenue over the same period.
Related: Man declares bankruptcy with 34 cents while hiding millions
#Bitcoin #hive #daily #average


1 day ago
During the September 8 episode of Mad Money, Jim Cramer turned his attention to Enbridge Inc. (NYSE:ENB), examining escalating geopolitical tensions. He commented:
As long as the war with Iran drags on, it's easy to recommend the refiners like a Valero or a Marathon. I don't see it ending any time soon, not with the US and Iran trading volleys this evening at islands and ships in the Strait. But how about a pipeline that moves about 30% of all crude produced in North America? Now, I'm talking about Enbridge which has a 5.5% yield. Also has a natural gas, you know, it transports 20% of the natural gas that's consumed in America. Okay, it's Canadian, but it's not caught up in the tariff fight because slapping tariffs on Canadian energy would be economic suicide for our country.
Cramer's focus on Enbridge Inc. (NYSE:ENB) highlights the structural dominance of its midstream network. The company operates as a significant transport network for North American energy, moving approximately 30% of all crude produced on the continent. Moreover, its vast utility and transmission network handles 20% of the natural gas consumed in the United States. The company's toll-road business model generates highly predictable cash flows, supporting an attractive dividend yield of roughly 5.6%. For income-focused investors, the combination of essential operational volume and reliable capital return creates a defensive cushion during volatile market cycles.
The company's defensive moat goes into cross-border trade and regional security. As Cramer pointed out, imposing punitive tariffs on Canadian energy imports would amount to severe economic self-harm for the United States, given the deep interdependence of North American energy grids.
Even with steady toll revenues, Enbridge Inc. (NYSE:ENB) carries a heavy debt load that comes with the territory of running massive pipeline networks, with long-term debt sitting at approximately C$104 billion. Because building and maintaining energy infrastructure requires heavy borrowing, higher interest rates hit financing costs, which can occasionally weigh on income-seeking investors.
#enbridge #natural #Iran #America
As long as the war with Iran drags on, it's easy to recommend the refiners like a Valero or a Marathon. I don't see it ending any time soon, not with the US and Iran trading volleys this evening at islands and ships in the Strait. But how about a pipeline that moves about 30% of all crude produced in North America? Now, I'm talking about Enbridge which has a 5.5% yield. Also has a natural gas, you know, it transports 20% of the natural gas that's consumed in America. Okay, it's Canadian, but it's not caught up in the tariff fight because slapping tariffs on Canadian energy would be economic suicide for our country.
Cramer's focus on Enbridge Inc. (NYSE:ENB) highlights the structural dominance of its midstream network. The company operates as a significant transport network for North American energy, moving approximately 30% of all crude produced on the continent. Moreover, its vast utility and transmission network handles 20% of the natural gas consumed in the United States. The company's toll-road business model generates highly predictable cash flows, supporting an attractive dividend yield of roughly 5.6%. For income-focused investors, the combination of essential operational volume and reliable capital return creates a defensive cushion during volatile market cycles.
The company's defensive moat goes into cross-border trade and regional security. As Cramer pointed out, imposing punitive tariffs on Canadian energy imports would amount to severe economic self-harm for the United States, given the deep interdependence of North American energy grids.
Even with steady toll revenues, Enbridge Inc. (NYSE:ENB) carries a heavy debt load that comes with the territory of running massive pipeline networks, with long-term debt sitting at approximately C$104 billion. Because building and maintaining energy infrastructure requires heavy borrowing, higher interest rates hit financing costs, which can occasionally weigh on income-seeking investors.
#enbridge #natural #Iran #America

1 day ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company

1 day ago
Interested in Intuitive Surgical, Inc.? Here are five stocks we like better.
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable
1 day ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management

1 day ago
Investors seeking exposure to artificial intelligence infrastructure must weigh the explosive growth of Astera Labs Inc (NASDAQ:ALAB) against the established scale and diverse portfolio of Marvell Technology Inc(NASDAQ:MRVL) to determine the better buy.
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million

2 days ago
AbbVie (ABBV) grew revenue 10.4% over the past twelve months and turned 33.9% of it into operating profit, second only to Eli Lilly among its peers on both counts. Its stock returned 24.9% over the same twelve months, fifth of the six. What the business delivered and what the market paid for it have come apart.
Johnson & Johnson makes the contrast sharpest. JNJ grew revenue 8.1% over the same twelve months on an operating margin of 26.8%—edging out Pfizer's 26.7%—while its stock returned 53.9%. It also trades at 30.5 times earnings, where AbbVie trades at 71.5.
ABBV
JNJ
PFE
#abbvie #grew #operating
Johnson & Johnson makes the contrast sharpest. JNJ grew revenue 8.1% over the same twelve months on an operating margin of 26.8%—edging out Pfizer's 26.7%—while its stock returned 53.9%. It also trades at 30.5 times earnings, where AbbVie trades at 71.5.
ABBV
JNJ
PFE
#abbvie #grew #operating

2 days ago
Salesforce (CRM) trades at 20.6 times earnings, below the S&P 500 median of 22.6, after losing 2.8% over the past twelve months while the index gained 17.9%. A profitable software company priced under the market is the setup value buyers wait for. The question is whether that is a good business on sale or a fair price for a legacy platform facing disintermediation from next-generation AI architectures.
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
2 days ago
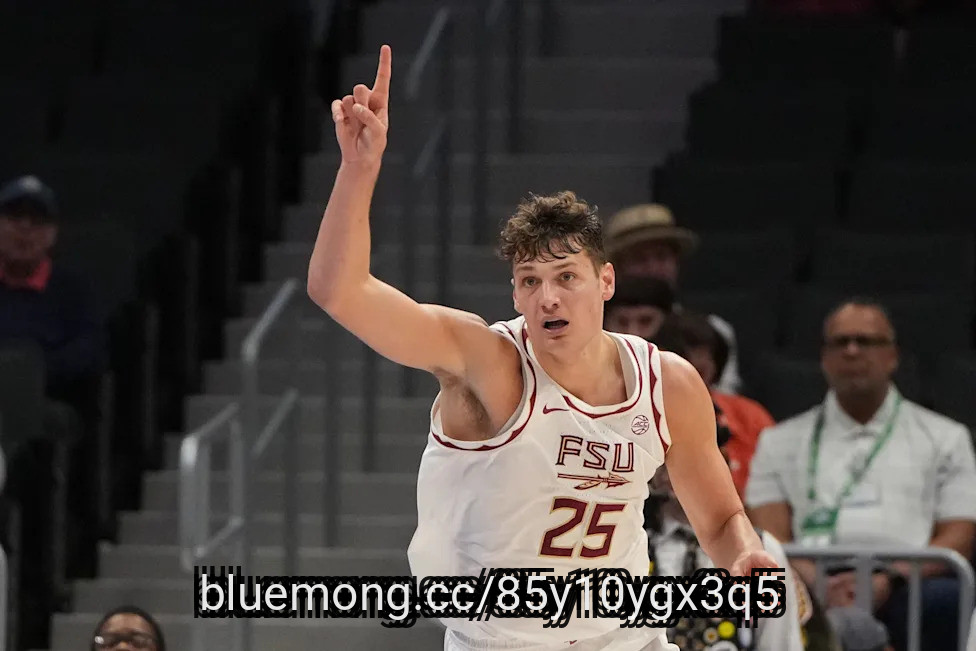
Former Florida State forward Alex Steen suffered a setback in his effort to secure another season of college basketball eligibility, according to Chris Nee of Noles247. Leon County Circuit Court Judge David M. Frank denied Steen's verified emergency motion for a temporary and preliminary injunction on Friday, Sept. 11. Steen is suing the NCAA in an effort to obtain a fifth season of eligibility for the 2026-27 season.
Steen and attorneys representing both sides appeared before Frank for a hearing on Sept. 2. The former Seminole is part of the 2022 high school class and played four consecutive college seasons without redshirting. His lawsuit challenges his exclusion from the NCAA's new eligibility framework that provides five seasons of competition to athletes from the 2023 class and beyond.
Under Florida law, Steen needed to satisfy four requirements to receive a temporary injunction: a substantial likelihood of success on the merits, no adequate remedy at law, irreparable harm without an injunction, and a showing that granting relief would serve the public interest. Frank determined Steen had not met the necessary standard.
The court found Steen's claimed losses involving practices, workouts, team activities, recruiting conversations, and professional evaluation were not supported by sufficient evidence and remained speculative. Frank also wrote that potential lost NIL income could be measured financially and therefore addressed through monetary damages.
Frank additionally determined a temporary injunction would not serve the public interest, reasoning that granting one player another season could affect roster spots, playing time, scholarships, and revenue-sharing allocations for other athletes.
#steen #frank #eligibility
Steen and attorneys representing both sides appeared before Frank for a hearing on Sept. 2. The former Seminole is part of the 2022 high school class and played four consecutive college seasons without redshirting. His lawsuit challenges his exclusion from the NCAA's new eligibility framework that provides five seasons of competition to athletes from the 2023 class and beyond.
Under Florida law, Steen needed to satisfy four requirements to receive a temporary injunction: a substantial likelihood of success on the merits, no adequate remedy at law, irreparable harm without an injunction, and a showing that granting relief would serve the public interest. Frank determined Steen had not met the necessary standard.
The court found Steen's claimed losses involving practices, workouts, team activities, recruiting conversations, and professional evaluation were not supported by sufficient evidence and remained speculative. Frank also wrote that potential lost NIL income could be measured financially and therefore addressed through monetary damages.
Frank additionally determined a temporary injunction would not serve the public interest, reasoning that granting one player another season could affect roster spots, playing time, scholarships, and revenue-sharing allocations for other athletes.
#steen #frank #eligibility
2 days ago
High-performance computing is currently undergoing a massive generational shift. Deciding between Astera Labs Inc (NASDAQ:ALAB) and Applied Materials Inc (NASDAQ:AMAT) means choosing between a fast-growing connectivity specialist and an established ******* an of manufacturing equipment.
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ

2 days ago
Navan Inc. (NASDAQ:NAVN), a global AI-enabled business travel and expense management solutions provider, announced its second quarter results on September 9. The company registered a 45% growth in its gross booking volume (GBV), which reached more than $3 billion. Such growth was fueled by cohort expansion, customer additions and increase in its existing install base. Total revenue for the quarter was $233 million, representing a 35% year-over-year jump. The company's adjusted operating income more than doubled compared to Q2 FY26, and the quarter also saw positive cash flow generation.
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume


2 days ago
CrowdStrike (CRWD) stock rose about 97% over the past year, against 18% for the S&P 500, as growth in the recurring revenue it adds each quarter sped up. Management was forecasting that speed-up by March 2025 and named one mechanism: Falcon Flex customers using up their contracts early and coming back for more. The direction was public. The size of the fiscal 2027 speed-up was not.
How Early Did CrowdStrike Forecast The Speed-Up?
The earliest sign came with the fiscal Q4 2025 report in March 2025. After its July 19 outage, CrowdStrike had given affected clients customer commitment packages, mostly extra product and Falcon Flex subscriptions. The CEO said that uptake underpinned an expected speed-up in net new annual recurring revenue (ARR) in the second half of fiscal 2026. He added that Flex demand plans were running ahead of schedule and expected contracts to be upsized and renewed. The CFO expected more acceleration in fiscal 2027.
The fiscal Q1 2026 report in early June 2025 put numbers on the mechanism: 39 Flex customers had deployed initial plans signed for 35 months on average and came back for more within five months, a step the company calls a reflex.
What Could You See Just Before The Run Began?
#speed #crowdstrike
How Early Did CrowdStrike Forecast The Speed-Up?
The earliest sign came with the fiscal Q4 2025 report in March 2025. After its July 19 outage, CrowdStrike had given affected clients customer commitment packages, mostly extra product and Falcon Flex subscriptions. The CEO said that uptake underpinned an expected speed-up in net new annual recurring revenue (ARR) in the second half of fiscal 2026. He added that Flex demand plans were running ahead of schedule and expected contracts to be upsized and renewed. The CFO expected more acceleration in fiscal 2027.
The fiscal Q1 2026 report in early June 2025 put numbers on the mechanism: 39 Flex customers had deployed initial plans signed for 35 months on average and came back for more within five months, a step the company calls a reflex.
What Could You See Just Before The Run Began?
#speed #crowdstrike

2 days ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity

2 days ago
As artificial intelligence matures, investors must decide between the high-growth niche players and the foundational giants. Choosing between Astera Labs Inc (NASDAQ:ALAB) and Taiwan Semiconductor Manufacturing Co (NYSE:TSM) involves weighing explosive potential against established dominance.
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
2 days ago
Apple (AAPL) is selling iPhones and Macs faster than it can build them, but the number a holder should fear most is the gross margin underneath those sales. Leaving out tariff refunds, that margin fell in the June quarter and is guided lower again for the September quarter. Management puts both steps down to rising memory prices, while the stock's price-to-earnings multiple sits near the top of its 10-year range.
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year


2 days ago
A $48 billion valuation and more than $2 billion in fresh venture capital would normally signal that investors have completely lost the plot.
Cognition AI, the startup behind the autonomous coding agent Devin, closed its Series E round on Sept. 8, 2026, to those exact headline figures.
The sheer size of the round drew immediate and predictable comparisons to the frothiest stretch of the 2026 AI investment cycle.
But the arithmetic behind the deal paints a different picture, one in which the ratio of investors' per-dollar revenue barely moved.
Between its May 2026 Series D and Series E close, Cognition's annualized run-rate revenue grew from $492 million to nearly $900 million, the company reported.
#round #devin
Cognition AI, the startup behind the autonomous coding agent Devin, closed its Series E round on Sept. 8, 2026, to those exact headline figures.
The sheer size of the round drew immediate and predictable comparisons to the frothiest stretch of the 2026 AI investment cycle.
But the arithmetic behind the deal paints a different picture, one in which the ratio of investors' per-dollar revenue barely moved.
Between its May 2026 Series D and Series E close, Cognition's annualized run-rate revenue grew from $492 million to nearly $900 million, the company reported.
#round #devin
2 days ago
Interested in Lam Research Corporation? Here are five stocks we like better.
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced
Lam Research raised its 2026 wafer-fabrication equipment spending outlook to the low-$150 billion range from $135 billion-$140 billion, driven by sustained AI demand and expectations for eight to 10 new leading-edge fabs through 2027.
AI hardware is increasing equipment intensity, while advanced chip designs and packaging are expanding Lam's addressable market. The company cited growing opportunities in gate-all-around transistors, backside power delivery, advanced packaging and dry-resist technology.
Lam is accelerating capacity expansion, including a second Malaysia facility, as clean-room availability and supply-chain capacity constrain the industry. The company also expects NAND upgrades to accelerate, while targeting mid-50% gross margins and reporting record customer-support revenue.
From High Dividend Growth to High Yield, These 3 Stocks Just Boosted Dividend Payouts
#billion #Research #equipment #advanced
2 days ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare