
3 days ago
A Florida woman who passed away kept receiving her Social Security retirement benefits for nearly six years — and her great-niece was cashing in.
Asha Anderson, 48, of Pompano Beach, Florida had been withdrawing her great-aunt's benefits from ATMs between April 2017 and December 2022 — to the tune of more than $152,000, according to prosecutors.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#great #asha #anderson #beach
21 days ago
Realty Income (O) sits near its 52-week low of $53, but UBS ***** yst Brent Dilts sees 39% upside to his $74 Buy target.
Net-lease peers NNN REIT and Agree Realty also fell double digits as the 10-year Treasury yield surged toward 5.3%, its one-year high.
A 6% forward yield and 674 consecutive monthly dividends offer income stability, but a recovery toward $74 depends entirely on rates turning.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Realty Income made the cut. Enter your email to see the other nine names and why O earned its spot. The report is free. Enter your email and see the full list.
Realty Income (NYSE:O) trades at $53.35. Wall Street's average price target is $66.39, which puts the stock about 24.4% below where ***** ysts think it belongs.
#income #yield #toward
23 days ago
Florida exempts a $600,000 IRA from Medicaid's $2,000 **** et limit once the account enters payout status through RMDs or regular distributions.
Every IRA distribution counts as income against Florida's $2,982 monthly cap, and nearly all of it goes directly to the nursing home.
A named IRA beneficiary keeps the remaining balance out of probate, blocking Florida's estate recovery claim under Fla. Stat. § 409.9101.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A Florida retiree entering long-term care with $600,000 in her IRA looks like an automatic Medicaid denial. A single applicant there can't hold more than $2,000 in countable **** ets. Thankfully, Florida's IRA Medicaid rules leave a narrow opening: once a retirement account is in payout status, the state can exclude the balance from the **** et count. This means withdrawals still count, each distribution is treated as income, and that income ends up paying most of her nursing home bill.
#Florida

1 month ago
Investors eager to buy into the futuristic vision of profitable driverless vehicles will get their chance soon. May Mobility is aiming to become the first U.S. publicly listed pure-play option for an autonomous ride-hailing technology company. It is poised to go public through a special purpose acquisition company (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the combined company at roughly $1.4 billion.
It's expected to operate as May Mobility. trading on the Nasdaq exchange under MAY. But before investors get too excited, let's pump the brakes and take a look at the details.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's easy for investors to get excited about the opportunity, but many might not be aware of the potential market size or growth prospects. The global robotaxi market is projected to reach about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. commercial autonomous vehicles (AVs) is projected to expand from only about 4,000 vehicles currently to around 35,000 by 2030 -- or about 8% of the ride-sharing market.
A year ago this month, Bank of America projected that the long-term U.S. total addressable market (TAM) for AV ride-hailing is a trillion-dollar opportunity as companies such as May Mobility aim to replace the drivers that take roughly 70% of every fare. It's also important for investors to realize how early in the game this is: Alphabet's Waymo, with an estimated $350 million in annualized revenue, would represent only about 0.5% of U.S. ride-hailing bookings.
#vehicles #company #roughly #billion
1 month ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ

1 month ago
On September 14, NextEra Energy, Inc. (NYSE:NEE) and Dominion Energy, Inc. (NYSE:D) announced a "transformational" Virginia benefits package to address concerns regarding their proposed $66.8 billion merger. The Virginia supplier program, worth up to $1 billion annually for five years, will direct spending toward contractors, suppliers, and service providers in the state.
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs

1 month ago
For custom chip designer Broadcom Inc. (NASDAQ:AVGO), the debate is all about whether the demand for AI products will sustain and grow. It is among the few firms capable of designing custom AI chips that big technology firms rely on to supplement NVIDIA's high-power and expensive AI chips. Anthropic CEO Dario Amodei's latest remarks about the need to slow down AI development due to safety concerns have generated quite a buzz, and Cramer discussed what Broadcom Inc. (NASDAQ:AVGO)'s CEO told him when asked about AI infrastructure development losing traction:
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong

1 month ago
Happy Friday, traders. Welcome to our weekly market wrap, where we take a look back at these last five trading days with a focus on the market news, economic data, and headlines that had the most impact on gold prices and other key correlated ****** ets—and may continue to in the future.
So, what kind of week has it been?
Gold took a more volatile path than expected but rebounded from a post-FOMC low near $4,260/oz to trade just above $4,350/oz shortly after the US market open on Friday, putting the yellow metal in position for a moderate weekly gain.
The Federal Reserve delivered the week's main event on Wednesday, unanimously raising policy rates by 25 basis points. Gold's sharp initial drop appeared tied less to the hike itself than to projections showing elevated inflation expectations and another 25-basis-point increase before the end of 2026.
Thursday brought the countermove as crude oil slid back toward and then below $100 per barrel, US Treasury yields eased, and gold recovered to around $4,360/oz. The Bank of ****** an's overnight rate hike to 1.25% added another tailwind into Friday.
#Friday #weekly #welcome
1 month ago
How long after someone's death will you be dealing with the financial aftermath?
Let's imagine Janice, whose husband, Bill, died five years ago. She thought she had finally finished dealing with all the expensive logistics.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#bezos #dave

1 month ago
In late 2022, OpenAI released ChatGPT, and within months the bottom rung of the tech-industry career ladder started to disappear. Graduates who majored in computer science and other AI-exposed fields are increasingly missing out on the jobs they trained for, and a chunk of them are landing behind restaurant counters and retail registers instead, according to two Census Bureau papers.
An April 2026 Census paper tracked matched employer-employee records and found that hiring of workers ages 22 to 24 fell sharply in the industries most exposed to AI, while hiring in less-exposed industries held steady. Employment for early-career workers in the most AI-exposed fifth of industries dropped 12% over the ten quarters after ChatGPT's release. Lee Tucker, one of the coauthors of the paper, said "the decline in hires is the primary cause" of that rate of unemployment, not people losing jobs they already had.
That mattered most for one type of graduate. The most AI-exposed industries, Tucker found, cluster heavily around software and information-technology work, which are the very fields computer science and other highly AI-exposed majors are built to feed into.
A second paper from last week, also coauthored by Tucker, follows the graduates of the most AI-exposed decile of college majors. Their odds of holding a job one quarter after graduation fell by five percentage points, and full-quarter initial earnings dropped 13% following ChatGPT's release. A 13% earnings decline is roughly the size economists would expect from graduating into a severe recession—except there wasn't one, since the rest of the labor market held up fine.
Young grads still need to work and still have jobs, even if they've received highly exposed degrees. So the decline in earnings is less about a lack of employment and more about pursuing lower-wage occupations to make ends meet.
#graduates

1 month ago
OpenAI holds $122B in cash and no IPO deadline, stripping Nvidia of the urgency and dependency that sustain premium chip pricing.
Broadcom dropped 7.95% and AMD held near flat as markets priced each company's exposure to OpenAI's supplier diversification.
Nvidia owns the training workload that ends once, while purpose-built inference chips capture every query that follows.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Sarah Friar, chief financial officer of OpenAI, sat with CNBC's Jim Cramer and described her chip procurement in the language a corporate treasurer would use. "We also have a strategy for diversifying our supply chain. And that is just good CFO risk mitigation. You never know when someone's supply chain is going to get gummed up. So you need to have multiple providers."
#chip #stocks #broadcom

1 month ago
Some refiners in ******* an this week rushed to buy Oman's crude for earlier loadings after Saudi Arabia shut down its key pipeline bypassing the Strait of Hormuz, traders with knowledge of the purchases told Bloomberg on Wednesday.
Late last week, Saudi Arabia was forced to temporarily shut down the East-West oil pipeline following drone attacks launched from the territory of Iraq close to the Iranian border on Thursday. The shutdown of the pipeline is a precautionary measure, after the attacks resulted in a number of injuries, the world's top crude oil exporter said.
The 750-mile-long East-West pipeline became Saudi Arabia's vital oil route to bypass the Strait of Hormuz after the Middle East conflict started and Hormuz was closed to shipping traffic. Thanks to the East-West pipeline, the Kingdom has managed to re-route most of its crude loadings from the western ports in the Persian Gulf to the Red Sea port of Yanbu.
Apart from announcing the shutdown of the pipeline and condemning the attacks, Saudi Arabia has not officially updated the market either on the extent of the damage or the timelines for repairs.
The repairs could take three to five weeks, two regional officials briefed on the matter told The ******* ociated Press.
#hormuz #strait

1 month ago
Piper Sandler believes Broadcom Inc. (NASDAQ:AVGO) is the leader in ASIC chips, holding 75% share of the ASIC market for AI inference. On September 9, firm ******* yst David O'Connor initiated coverage on the stock with an Overweight rating and a $460 price target.
O'Connor estimates demand running twice the available supply for Broadcom, which makes the ability to deliver chips central to his thesis. Even though the chipmaker boasts demand, component availability and deployment timing will determine its conversion into earnings.
The biggest advantage that Broadcom holds is that it doesn't need to win new customers, but to keep expanding what it ships to the ones it already has. The company is already ramping Meta's MTIA program and OpenAI's Jalapeno chips, along with two other customers.
Google's TPU program remains Broadcom's major volume ASIC program, while Anthropic is also scaling deployments using AVGO-enabled TPU compute. Broadcom also boasts a rising networking attach rate, which is currently around 30%. This would likely generate an estimated $20-30 billion of total content per gigawatt of deployed capacity.
The firm has a line of sight to 12 gigawatts of demand in fiscal 2027, rising toward an estimated 38 gigawatts by fiscal 2030. This underpins a roughly 51% EPS compound growth rate through the decade.
#asic

1 month ago
In the early 2000s, house-flipping was the get-rich-quick trend that seemingly everyone with enough liquidity wanted to try their hand at. It was popularized by TV shows like Flip This House that showcased fixer-upper success stories and took viewers along for the ride.
Though the heyday ended with the 2008 housing crash, the practice was revived in the COVID-era housing lull and remains popular even now, despite not being as profitable as it once was given rising real estate, material, and labour costs. One way around those realities is to take advantage of the speculative nature of certain properties so a flip doesn't have to involve much renovation work (or any at all, if you're lucky).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#like #covid #bezos
1 month ago
On September 1, Korn Ferry (NYSE:KFY) completed its £850 million acquisition of UK-based AMS, from OMERS Private Equity. The deal combines two well-reputed brands, resulting in a highly well-rounded solutions provider and a leading business within the global talent and organizational consulting **** e. It offers a broader market reach to Korn Ferry, along with more extensive coverage spanning several new industries.
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business

1 month ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal

1 month ago
What happened: The 10-year Treasury yield (^TNX) climbed to 4.97% on Monday, just 3 basis points away from the 5% threshold. Meanwhile, the 30-year Treasury (^TYX) yield hovered at 5.35%.
What's behind the move: Bond yields stayed elevated as Brent crude climbed to $107 a barrel, stoking inflation fears and leading investors to price in rate hikes ahead of the Federal Reserve's policy meeting this week.
Goldman Sachs revised its forecast for this week from no change to a rate hike following Friday's August inflation print.
"The report had little impact on our inflation view but pushed market pricing of a hike to nearly 90%, high enough that the FOMC will likely want to avoid the market reaction that would likely follow from remaining on hold," Goldman Sachs' chief economist David Mericle wrote on Sunday night.
Some strategists believe long-dated bond yields may ease if the Fed hikes rates at its Sept. 15-16 meeting.
#yield

2 months ago
Interested in American Tower Corporation? Here are five stocks we like better.
2026 is expected to be American Tower's organic growth trough, with tenant billings growth projected to accelerate in 2027 as Dish Network churn fades and carrier network investment improves.
Future demand could be supported by 5G capacity expansion, higher-band spectrum, AI-driven uplink traffic and eventual 6G deployments. CoreSite's data-center business is also benefiting from rising bandwidth and cloud-interconnection demand.
American Tower is targeting 200–300 basis points of tower-business margin expansion and mid- to upper-mid-single-digit long-term AFFO-per-share growth, while Dish litigation and a Mexico arbitration could provide additional upside if resolved favorably.
AST ****** eMobile Looks to Extend Its 30-Day FCC Satellite Testing Window
#Growth #expansion #interested
2 months ago
USA Rare Earth, Inc. (NASDAQ:USAR) announced on September 4 that it completed the Serra Verde acquisition one day earlier, paying $300 million in cash and issuing approximately 126.8 million common shares. The transaction adds Brazil's Pela Ema mine to Less Common Metals in the United Kingdom, the Stillwater, Oklahoma, magnet facility, and the Round Top project in Texas.
Serra Verde began production in January 2024 but is still completing optimization and commissioning. Stage 1 is expected to reach an annual run rate of approximately 4,000 metric tons of total rare-earth oxide, or TREO, by year-end 2026. Stage 2 construction targets average annual production of 6,400 metric tons, with commissioning expected to begin within 12 months.
Serra Verde had $425 million of principal outstanding under its U.S. International Development Finance Corporation loan at June 30. At closing, a $100 million tranche was extinguished after related warrants were exercised, leaving approximately $325 million of principal. The unaudited pro forma combined balance sheet reported a $304.1 million debt carrying value after discounts and issuance costs.
Serra Verde gives USA Rare Earth, Inc. (NASDAQ:USAR) a producing source of dysprosium, terbium, and other rare earths used in permanent magnets. Combining mining, metals, alloys, and magnet manufacturing could capture more of the value chain outside Asia.
The Phase 1 offtake agreement supports revenue visibility. It covers 100% of Pela Ema's Phase 1 products, subject to limited carve-outs, and includes escalating price floors annually. The counterparty is a special-purpose vehicle capitalized by the U.S. government and private investors. The arrangement provides contractual price protection, subject to the counterparty's performance.
#earth #approximately #NASDAQ #usar

2 months ago
By Aditya Kalra
NEW DELHI, Sept 9 (Reuters) - India's Serious Fraud Office has recommended Xiaomi be investigated for alleged irregularities in its business model and compliance with foreign investment law, potentially intensifying scrutiny of the smartphone maker, a government document shows.
China's Xiaomi was once India's top-selling smartphone brand but has seen its market share dwindle amid intense competition from Apple and Samsung. It is also battling several tax demands and royalty payment disputes.
The recommendation from India's Serious Fraud Investigation Office (SFIO) said the investigation should examine movement of funds and whether Xiaomi sought mandatory investment approvals as required after India tightened scrutiny of Chinese investments following deadly border clashes between the two nations in 2020.
A person familiar with the matter said the government is examining the memorandum, which was drafted in May and reviewed by Reuters.
#serious #fraud #investigation #investment

2 months ago
Signet Jewelers early Wednesday easily beat fiscal second-quarter earnings estimates and guided higher for the full year. Shares of the long-term laggard surged in morning trade.
For its second fiscal quarter, Signet Jewelers (SIG) reported adjusted earnings per share of $2.19, up 36% vs. a year earlier and handily beating **** ysts' expectations of $1.74, reflecting improved margins. Sales of $1.53 billion were in line with views and a fraction below the $1.54 a year earlier.
The owner of Kay Jewelers, Zales and Jared now eyes 2027 adjusted EPS of $10.45 to $12.15, up from its prior target range of $9.20 to $11. It still sees sales of $6.7 billion to $6.9 billion. **** ysts' expect $10.82 in adjusted EPS on revenue of $6.84 billion.
Signet also announced plans for a $125 million accelerated share repurchase deal "this month."
"We are raising our full year adjusted EPS guidance by over 10% to reflect year-to-date operating performance, additional share repurchases, refunds of tariffs previously paid, and the terms of the new consumer credit agreement," said COO and CFO Joan Hilson.
#year #second

2 months ago
MongoDB, Inc. (NASDAQ:MDB) reported fiscal second-quarter revenue of $771.8 million, up 30% year over year. Atlas revenue increased approximately 29% to $565.9 million, while Enterprise Advanced and other revenue rose approximately 36% to $181.2 million.
Remaining performance obligations, or RPO, increased 91% to $1.52 billion. RPO represents the aggregate transaction price in contracts allocated to performance obligations not delivered or partially undelivered. MongoDB, Inc. (NASDAQ:MDB) omits contracts lasting 12 months or less from the disclosure. Current RPO, the portion expected to be recognized within 12 months, increased 73% to $797.3 million.
GAAP operating income reached $28.4 million, compared with a $65.3 million loss a year earlier. MongoDB, Inc. (NASDAQ:MDB) also raised fiscal 2027 revenue guidance to $2.99 billion to $3.03 billion from $2.92 billion to $2.96 billion, with the second-half increase attributed mainly to Atlas.
Growth was broad. Atlas expanded 29%, while Enterprise Advanced and other revenue grew faster at 36%. Total customers increased to more than 70,600 from more than 59,900 a year earlier, and Atlas customers reached more than 69,300.
The margin profile also improved. GAAP gross margin expanded to 74% from 71%, while revenue growth outpaced operating-expense growth enough to produce positive GAAP operating income. This shows MongoDB, Inc. (NASDAQ:MDB) can scale infrastructure, research and sales costs more slowly than revenue.
#million #mongodb #NASDAQ #gaap
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Oracle (ORCL) has enough on its plate heading into earnings week. Now Brussels wants a word.
European antitrust regulators are quietly examining how Oracle licenses its software, and the timing could hardly be more inconvenient for shareholders.
The stock trades near $158.78, down about 19% so far in 2026 and roughly 54% below its 52-week high of $345.72.
Investors were already nervous about Oracle's debt-heavy artificial intelligence (AI) buildout. This regulatory question adds to the list of worries.
The European Commission is gathering information from Oracle's customers and rivals to decide whether its cloud software terms unfairly lock clients in, Reuters reported.
#european #enough

2 months ago
Synopsys (SNPS), a leading provider of software used to design, verify, and test semiconductor chips, remains one of the most dominant players in electronic design automation (EDA). Its EDA software and semiconductor intellectual property (IP) solutions play a critical role in the development of increasingly sophisticated chips.
Moreover, the company has expanded its capabilities with its approximately $35 billion acquisition of Ansys, bringing semiconductor design and engineering simulation under one roof. However, the integration has also brought restructuring and workforce reductions.
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
Apple Stock: September Surprise Could Be Bigger Than a New iPhone
#Stock #synopsys


2 months ago
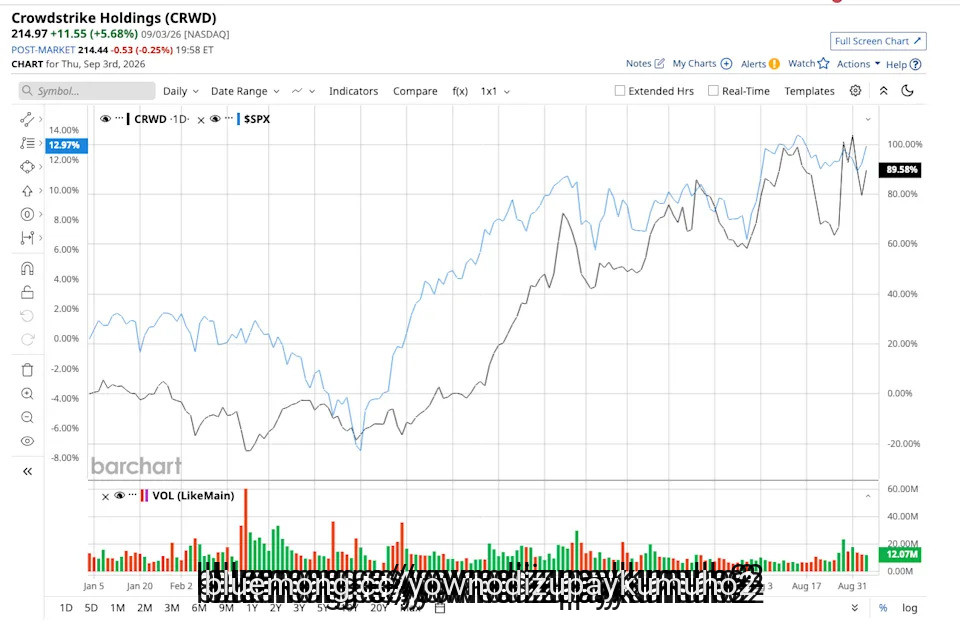
CrowdStrike (CRWD) looks like one of the strongest growth stories in cybersecurity right now. It had a lot to prove in the fiscal second-quarter earnings. The company delivered on all three numbers that I flagged ahead of the Q2 print, and in some cases it did much better than expected. And the stock's massive 90% gains so far this year reflect that outstanding performance.
With a market cap of $220 billion, CrowdStrike is a cloud-based cybersecurity company best known for its Falcon platform. The company helps businesses protect endpoints, cloud workloads, identities, and other parts of their technology infrastructure from cyber threats.
How to Play SNPS Stock as Layoffs Hit Synopsys
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
#Stock #company #Cybersecurity
2 months ago
Few retail chains that filled malls in the 1980s and 1990s still exist today.
Teenage me could have shopped at Chess King for shiny shirts, visited Gadzooks for baggy pants, or gone a little classier and purchased dressier clothes at Structure. All of those chains were fairly, if not very, popular for a minute, and none of them exist now.
Former Tory Burch Chief Client Officer Francesca Danzi told Forbes that it's a major challenge for a brand to remain relevant across decades.
"Enhancing retail experience is key and goes beyond adding omnichannel capabilities that boost convenience. We are witnessing the rise of experiential retail that is reshaping the store of the future," she said.
Danzi does not see the so-called retail apocalypse as a crisis where stores are closing, but as an opportunity to right-size store portfolios.
#danzi #chains #store
2 months ago
Pre-approval signals you likely qualify, but no underwriter has verified your income, debts, or employment, so it is far from a guaranteed loan.
Full underwriting approval verifies income, employment, credit, and ***** ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#income
2 months ago
On August 6, Installed Building Products (NYSE:IBP) reported second-quarter results that told two different stories at once. Net revenue hit a second-quarter record of $777.8 million, yet profit and margins moved the other way, and the board still found room to raise the dividend for the fifth straight year.
The headline number was $777.8 million in net revenue, up 2.3% from $760.3 million a year earlier. That growth came almost entirely from outside the core insulation installation business. Other revenue, which covers IBP's manufacturing and distribution operations, jumped 50.4% to $67.1 million, while commercial work inside the Installation segment posted same-branch sales growth of 10.4%. Acquisitions did heavy lifting too. The company closed Diamond Energy Systems in May, then Harkraft and Builders Hardware of South Carolina in July, adding roughly $30 million in combined annual revenue. Year to date, IBP has acquired about $59 million in revenue and still expects to reach at least $100 million for all of 2026.
The balance sheet backed that ambition, with $394.5 million in cash on hand at quarter-end. Management also kept returning cash to shareholders, repurchasing about 365,000 shares for $76.2 million in the quarter, with $398 million still available under the buyback authorization through March 2027. The board topped it off by declaring a third-quarter dividend of $0.39 per share, payable September 30 to holders of record on September 15, more than a 5% increase over last year's third-quarter payout.
The strength was uneven. Residential same-branch installation sales fell 6.1% for the quarter, and job volume excluding heavy commercial work dropped 5.2%, evidence that the housing slowdown is landing directly on IBP's biggest business line. That mix shift showed up in the bottom line. Net income fell to $64.9 million, or $2.43 per diluted share, from $69.0 million and $2.52 a year ago. Adjusted EBITDA slid 2.3% to $130.9 million, with the margin compressing to 16.9% from 17.6%.
Gross profit margin also narrowed to 33.3% from 34.2%, and the company pointed to a specific cause: the faster-growing Other segment carries a 24.7% gross margin, well below the 36.5% margin in core Installation work, so revenue mix worked against profitability even as total sales climbed. Higher fuel costs added further pressure on gross margin, while administrative expense crept up as a percentage of revenue, driven by higher medical insurance costs. CEO Jeff Edwards acknowledged the backdrop directly, saying the company expects affordability and consumer confidence to keep weighing on the residential market.
#million #installation #year #sales

2 months ago
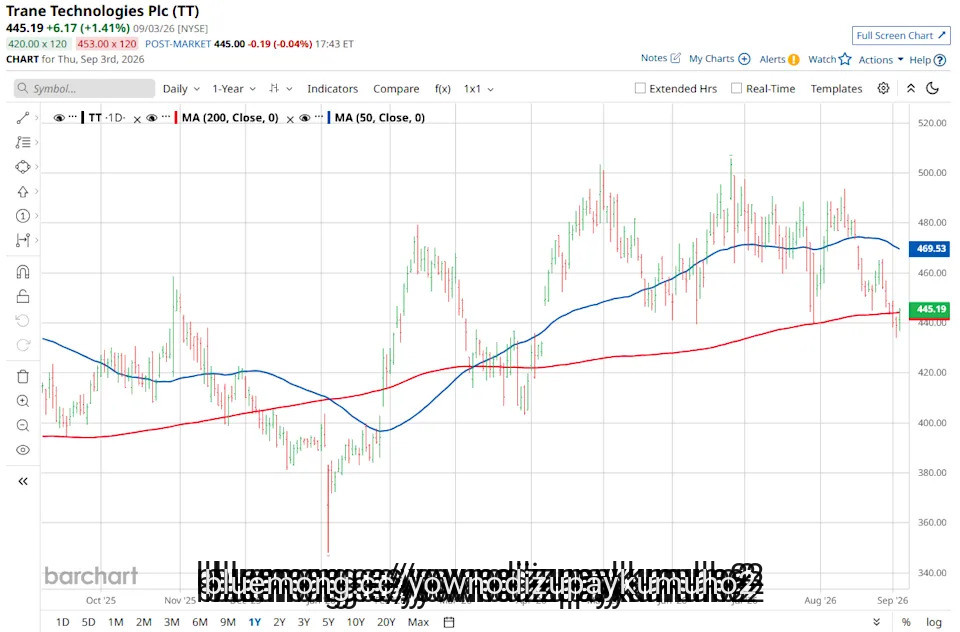
Swords, Ireland-based Trane Technologies plc (TT) designs, manufactures, sells, and services solutions for heating, ventilation, air conditioning, and custom and transport refrigeration. The company has a market cap of $96.6 billion and offers air conditioners, exchangers, and handlers; airside and terminal devices; air-sourced heat pumps; chillers; coils and condensers; auxiliary power, cold storage, and condensing units; and more.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." TT fits squarely into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the building products and equipment industry.
Why Palantir Stock Could Jump 50% From Here
Down 75%, This Tesla Rival Continues to Grow Vehicle Deliveries in 2026
Is AVGO Stock Poised for a Rebound After Broadcom's Strong Q3 Results?
#billion

2 months ago
On September 3, Ermenegildo Zegna Group (NYSE:ZGN) reported first-half revenues of €987.3 million, up 6.4% year over year and 9.3% on an organic basis. Direct-to-consumer sales did nearly all the work, climbing 15.8% organically and now making up 86% of branded revenue. But headline profit told a rougher story, sliding to €28.4 million from €47.9 million a year earlier. The gap between a business growing almost everywhere that matters and a bottom line moving the other direction is what investors now have to untangle.
The clearest strength in the first half of 2026 is how much of Zegna's growth is coming from channels it controls directly. Direct-to-consumer revenue grew 12.1% as reported and 15.8% organically, while the Group deliberately shrank its wholesale business by 14.6% as it keeps trimming third-party accounts. The Zegna segment, which houses the flagship ZEGNA brand along with Textile, generated €724.3 million in revenue, up 9.7% year over year, with the ZEGNA brand itself growing 13.9% organically to €634.6 million. That segment's Adjusted EBIT Margin rose 50 basis points to 14.8%, driven by higher sales per square meter and better sell-through in its own stores.
Group-wide Adjusted EBIT rose to €74.5 million from €68.7 million, pushing the margin to 7.5%. The balance sheet moved in the right direction too, with the net cash surplus climbing to €59.6 million at June 30 from €52.1 million at December 31, 2025. Free cash flow flipped to a positive €19.2 million, compared with a negative €23.1 million a year earlier, helped by stronger operating cash flow and tighter working capital management. Even Tom Ford Fashion, still unprofitable, cut its Adjusted EBIT loss to €12.1 million from €19.4 million, a sign the newer brand is moving toward breakeven rather than away from it.
The drop in profit isn't just optics. H1 2025's €47.9 million figure included a €27.8 million non-cash gain from remeasuring non-controlling interest put option liabilities, a boost that didn't repeat this year. On top of that, the effective tax rate jumped to 38.8% from 29.6%, and the combined swing in financial expenses and foreign exchange moved to a negative €22.7 million from a positive €6.0 million. Together, those items explain most of the gap between a profit margin of 2.9% this year and 5.2% last year, even as operating profit itself improved to €68.5 million from €61.3 million.
Thom Browne is the segment causing the most concern. Revenue there fell 4.9% year over year to €123.1 million, and Adjusted EBIT swung to a loss of €8.3 million from a profit of €4.5 million, which the company attributed to foreign exchange pressure and investment in shifting the brand toward a retail-first model. Capital expenditure also climbed to €64 million from €54 million, largely tied to a new shoe production plant in Parma, and corporate costs rose to €12 million from €10.7 million as the Group builds out its structure.
#million