1 day ago
India Love, a social media personality, had a rude awakening when she saw pictures of herself from ComplexCon and immediately decided to begin her fitness journey. Love noted that her weight has increased from 150 pounds to 173 pounds and doesn't plan on waiting until her subathon to do something about it.
On her recent Twitch stream, Love explained how the photos were an eye-opening experience for her.
"Y'all, I looked at pictures of me at Complex. Time I said, 'Whoa, baby, that'll do it. That'll do it,'" she stated. "I'm not gonna wait for my subathon to start my journey. The time is now."
Love didn't hold back on her reaction.
"I got rolls falling out the side of my s*** like this ain't it," she admitted. "Ain't done to it but to do it. Me versus me."
#ain 't

1 day ago
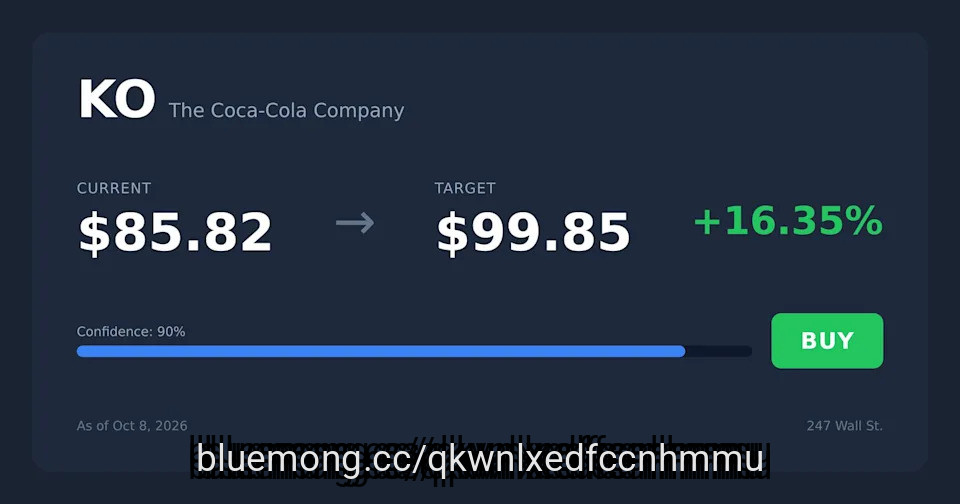
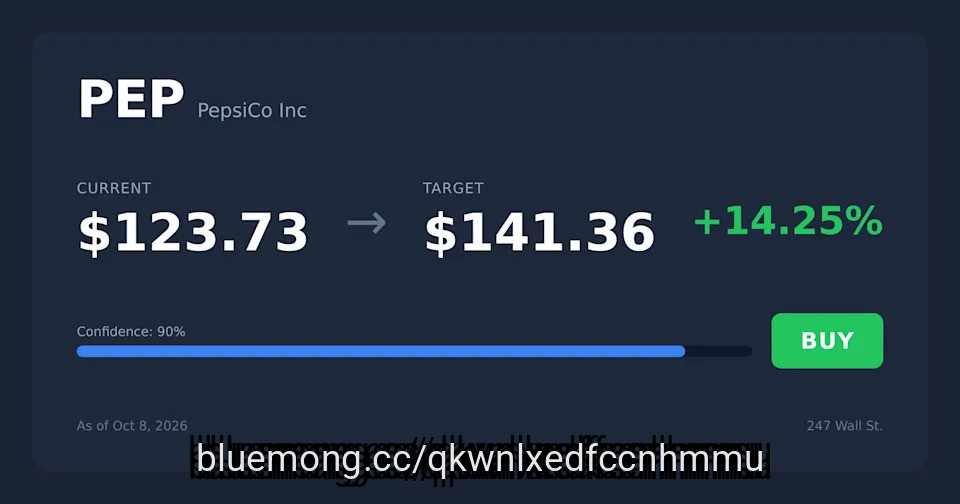
Coca-Cola ($KO) beats PepsiCo ($PEP) for generational portfolios with 63 consecutive dividend increases, wider margins, and 182% 10-year share gains versus 60%.
PepsiCo's free cash flow barely covers its 4.44% dividend yield, while Coca-Cola's expected $12.4B free cash flow dwarfs its $8.8B dividend payout.
A pending IRS appeals ruling and a premium P/E of 28 are the two risks that could crack Coca-Cola's otherwise dominant long-term case.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coca-Cola didn't make the cut. Enter your email to see the names that beat KO. The report is free. Enter your email and see if any of your stocks made the cut.
Coca-Cola (NYSE:KO) or PepsiCo (NASDAQ:PEP): Which one better suits someone investing for retirement right now, knowing the shares may pass to the next generation? Looked at over several decades, Coca-Cola wins. PepsiCo pays the bigger yield today. Coca-Cola has the safer dividend, the stronger brand economics and fewer structural cracks.
#stocks


2 days ago
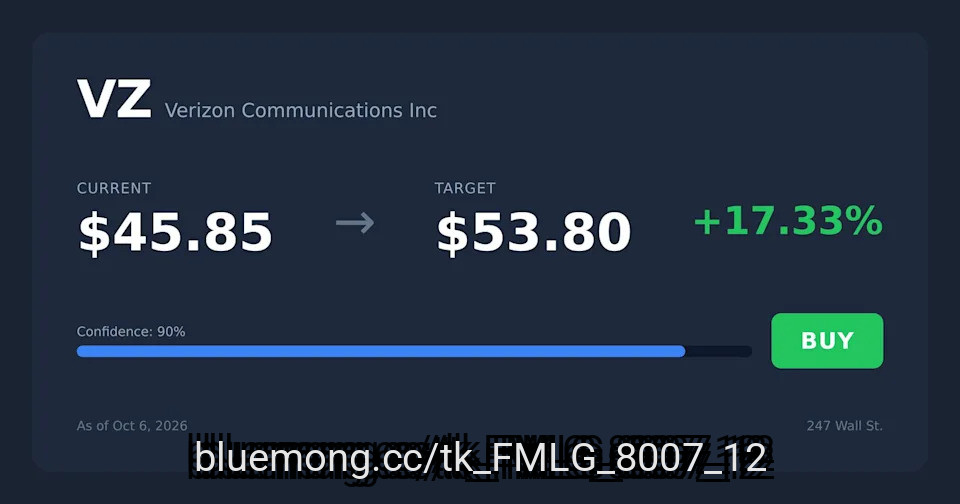
Verizon yields 6% versus AT&T's 5%, but AT&T slashed its dividend 47% in 2022 while Verizon has raised its payout for 20 consecutive years.
AT&T's EchoStar (SATS) spectrum purchase pushes its leverage from 2.68x toward 3.2x, delaying a return to its 2.5x target by roughly three years.
Verizon's 2026 free cash flow grows 9-10% to roughly $22B; AT&T's management says dividends and buybacks will consume essentially 100% of its FCF.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Verizon (NYSE:VZ) orAT&T (NYSE:T): Which yield can you trust to keep paying, and growing, for the next decade? I pick Verizon, and the gap between the two is wider than the reported yields suggest.
#verizon #years

3 days ago
A $300,000 investment in SCHD grew to $468,150 over five years versus $573,900 in VOO, leaving a $105,750 gap driven by missing big tech.
SCHD's dividend quality screen kept out the tech giants that led the market, yet that same tilt powered its 23.86% one-year return.
SCHD suits retirees drawing income today, but younger investors should know the yield cost a $300,000 account over $100,000 in five years.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Putting $300,000 into the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) on October 1, 2021 left a holder with $468,150 by October 5, 2026. The same money in the Vanguard S&P 500 ETF (NYSEARCA:VOO) grew to $573,900. That leaves a shortfall of $105,750.
#nysearca #Dividend #income #same
3 days ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly
3 days ago
Palantir surged 60% in Q3 after reporting 93% revenue growth, but trades at 100x forward earnings versus Microsoft's 25x.
Michael Burry holds puts through 2027 while UBS and DA Davidson set $250 targets, signaling a sharply divided Wall Street on Palantir.
Palantir's November earnings must hit $2.16 billion guidance, which is a bar the current share price already ****** umes it clears.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Palantir Technologies (NASDAQ:PLTR) rose 60.3% in the third quarter. That was its best three-month run since the second quarter of 2025. Even so, Palantir is up just 6.55% this year, because it lost most of that ground in the first half.
#burry #davidson


3 days ago
JNJ and PG both trade at 21x forward earnings, but J&J's 46% payout ratio versus P&G's 62% signals stronger long-term dividend coverage.
P&G carries a $1.4 billion after-tax earnings headwind into fiscal 2027, while J&J has already absorbed its Stelara biosimilar competition.
J&J's 10-year share price gain of 181% nearly doubled P&G's 117%, with management targeting double-digit earnings growth by decade's end.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Johnson & Johnson (NYSE:JNJ) orProcter & Gamble (NYSE:PG): If someone saving for retirement could hold only one Dividend King for the next 20 years, which one should it be? My pick is Johnson & Johnson, and the gap is wider than the yields suggest. Both stocks trade near 21 times forward earnings (P&G at 21), so valuation is effectively a tie. The decision comes down to three things that matter more to a retiree: dividend coverage, durability and structural risk.
#trade


7 days ago
US bond yields have surged upward over the past month, as yields on both the 10-year Treasury (^TNX) and 30-year Treasury (^TYX) have reached levels not seen since 2002, surpassing 2007 high-water marks in the lead-up to the financial crisis.
Investors have attributed the run-up in yields to a variety of concerns, from the artificial intelligence build-out and the competition for capital to changing foreign ownership of gold versus fixed income.
Read more: How soaring Treasury yields could hit your finances
One overlooked source of upward pressure, argued Macquarie's Thierry Wizman, is not just the impact of the Iran war on the energy market but uncertainty about when the war will end or what the conflict will look like going forward.
"The perception that global conflict is endemic may also be causing long-term inflation expectation[s] to stay elevated," Wizman wrote to clients.
#conflict
8 days ago
Bill Burr is pitching a different use for artificial intelligence: point it at the top of the org chart.
The comedian made the case during a sit-down with Rolling Stone, pointing out that it makes way more sense to create AI CEOs instead of AI workers, considering the fact that companies will save way more.
"All this AI is to replace working people. It's like, why don't you make an AI CEO that's empathetic, that cares about the middle class and the future of the planet?" the comedian asked.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
"They're making way more. You take that guy's salary versus all the work. You're going to save way more money replacing one guy," Burr continued. "Why don't you do that? Because it's not for us, it's for them."
#bill



19 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited

19 days ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo

19 days ago
GOOG trades at a P/E of 14 versus META's 24, with Cloud revenue surging 82% while META's operating margins collapsed from 43% to 31%.
META's Reality Labs bleeds roughly $4B per quarter, 2026 capex is projected between $130B and $145B, and active litigation makes it a volatile aggressive-growth bet rather than a retirement hold.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Google didn't make the cut. Enter your email to see the names that beat GOOG. The report is free. Enter your email and see if any of your stocks made the cut.
Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google's family-focused CC, a shared agent supporting up to six family members, and Meta's single-user Muse, aiming for higher autonomy across a user's digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user's behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user's digital life, including commerce. They compete in the emerging "AI agent that actually does things" category, but target different use cases and user models.
#stocks #family


19 days ago
On August 10, Simon Property Group (NYSE:SPG) reported results for the three months through June 30 and raised its full-year profit outlook once again. Real estate funds from operations (FFO), a cash-flow measure suited to landlords, hit $3.29 per share. Tenants are earning more from their stores, and management is confident enough to lift its guidance again. Yet the professionals who own the stock are heading the other way.
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate
20 days ago
HDV has outpaced VYM by nearly 9 points year-to-date in 2026 while paying a 3.34% yield versus VYM's 2.20%.
HDV's 75-stock tilt toward energy, healthcare, and staples drives its 2026 edge but can lag equally in growth-led markets.
Taxable investors switching from VYM should redirect new contributions into HDV rather than selling lots with large embedded capital gains.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
If you own the Vanguard High Dividend Yield ETF (NYSEARCA:VYM), you own it for a good reason. VYM tracks the FTSE High Dividend Yield Index, holds roughly 500 above-average payers, and delivers a broad, cheap slice of dividend-paying American stocks. It is one of the most widely held income ETFs on the market, and for buy-and-hold investors who want a diversified basket of yielders without thinking too hard about it, VYM has done its job. But in 2026, VYM is losing ground to a much smaller, more concentrated peer from BlackRock that pays a higher yield and follows a very different rulebook.
#same
20 days ago
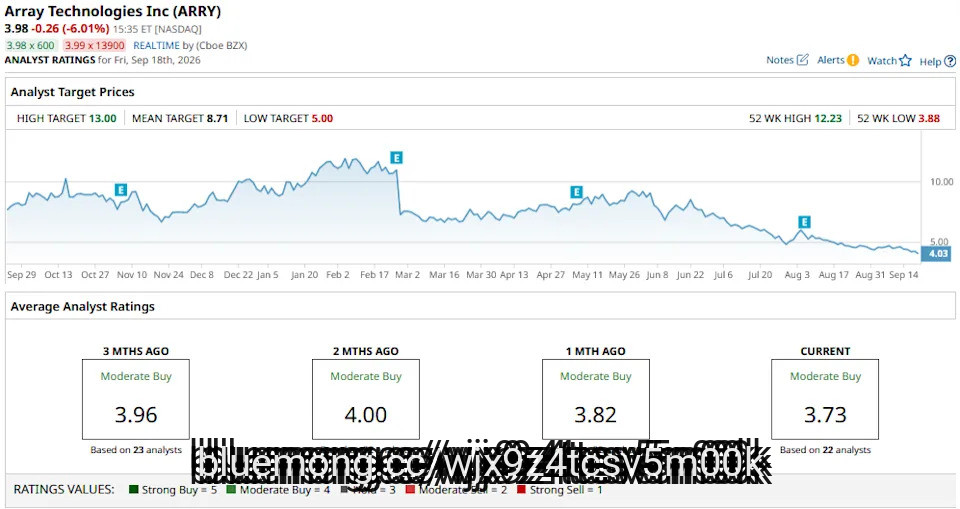
Array Technologies (ARRY) shares moved meaningfully lower on Sept. 18 after a senior UBS **** yst, Jon Windham, downgraded the solar tracking manufacturer to "Neutral." Windham also slashed his price target in half to $5, cautioning investors against expecting a swift recovery in ARRY in the near term.
His bearish call is meaningful, given that Array Technologies stock has already been a disappointment for investors in 2026, currently down more than 65% versus its year-to-date high.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#arry #Stock #musk


20 days ago
In June, ****** eX (NASDAQ: SPCX) successfully completed its blockbuster IPO, raising more than $85 billion. In the days that followed, ****** eX's market cap soared from an initial IPO valuation of $1.77 trillion to nearly $2.8 trillion. Shares corrected hard after the surge, however, and ****** eX's valuation now hovers just below $2 trillion -- a 36% decline versus the company's all-time high.
Morgan Stanley (NYSE: MS) ****** ysts remain unfazed regarding the ****** e stock's long-term growth potential. On Sept. 15, the bank reiterated its "buy" rating on shares, affirming its $300 price target. That price target implies more than 100% in near-term upside over the next 12 months.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Why does Morgan Stanley remain so bullish? The answer might surprise you.
Morgan Stanley appears all-in on the ****** e economy. The bank, in many ways, predicted ****** eX's meteoric rise years before much of the public caught on.
#trillion #valuation

20 days ago
Coinbase (COIN) shares moved meaningfully higher on Sept. 18 as Bitcoin (BTCUSD) recovered sharply, hitting an intraday high of more than $81,000. As COIN rallied on a sharp crypto market rebound, it soared past its 20-day moving average (MA) today, indicating that bullish momentum could sustain in the near term.
Versus the start of this year, Coinbase stock is still down about 15%.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#sept


20 days ago
SCHD delivers nearly double VIG's forward yield at roughly 3% compared to 1.7%, making it the stronger cash anchor for retirees funding withdrawals today.
Despite radically different portfolios, both funds produced nearly identical 10-year returns: VIG at 243% versus SCHD's 237%.
With the 10-year Treasury at 5%, rising rates are punishing VIG's growth tilt, and SCHD leads year-to-date by a wide margin of 25% to 8%.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Retirees weighing a dividend anchor keep landing on the same two funds: Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) and Vanguard Dividend Appreciation ETF (NYSEARCA:VIG). They look like siblings but diverge sharply under the hood. SCHD screens hard for cash-flow quality and pays a meaningfully higher current yield. VIG buys only companies with 10-plus consecutive years of dividend increases and explicitly kicks out the highest-yielding quartile. That single rule sends the two funds toward very different portfolios, and it is showing up in the returns.
#Dividend #same #nearly #cash

20 days ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson

20 days ago
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee's history and the state's first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn't carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice

20 days ago
Margin debt hit $1.45 trillion in August, up 140% since 2022 and outpacing the S&P 500's 98% gain, which leaves the market carrying far more forced-selling risk.
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors
20 days ago
Owning a $400,000 Villages home costs owners roughly 4.5% annually in forgone investment income alone, before taxes, insurance, or CDD bond payments.
Annual rentals run between $2,200 and $3,000 a month, but renting beats owning only for stays under eight years once all costs are counted.
A 75-year-old facing a forced sale in a narrow buyer pool at 3.98 million existing home sales risks losing the flexibility a lease ending provides.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
At the end of the day, renting versus buying in The Villages comes down to one thing: math. More owners are running the numbers and finding that renting wins on the spreadsheet, so here is what the comparison actually looks like when every line is filled in.
#income

20 days ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


20 days ago
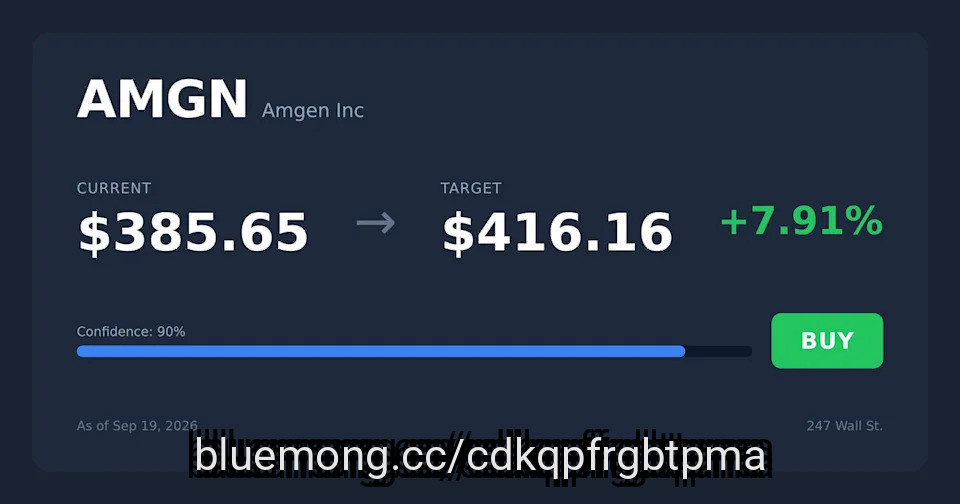
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen

20 days ago
This story was originally published on Supply Chain Dive. To receive daily news and insights, subscribe to our free daily Supply Chain Dive newsletter.
TJX Companies is confident in navigating weather-related events such as El Niño due to its warehouse distribution model, CEO Ernie Herrman said in a Q2 earnings call on Aug. 19.
Herrman said since the company keeps its liquidity and shipping out of its warehouses, it has better control than traditional retailers. Inventory doesn't need to go straight to the stores if the off-price retailer thinks there's going to be an unusual weather pattern in a certain region, he added.
"[T]his is a benefit of our model where we stage goods in our warehouses versus goods at most brick-and-mortar retailers come into the warehouse and have to go out," Herrman told **** ysts. He added that the company's "planning organization is really good at reacting to any wild swings in weather or natural disasters or any of those red flags."
Off-price retailers and classic retailers tend to have different supply chain models when it comes to how they manage their inventory, but it's not one-size fits all, Dheera Anand, a partner at Bain and Co., told Supply Chain Dive in an interview. The supply chain strategy Hermann described in TJX's earnings call is known as the hold and flow, or staged, model, Anand said.
#supply

21 days ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion


21 days ago
QQQI holders forfeited roughly $11 per share in total return versus QQQ over 31 months, equal to about $2,194 on a $10,000 stake.
Nearly 99% of QQQI's 2025 distributions were return of capital, meaning investors received their own money back, not income, with a shrinking cost basis.
QQQM and JEPQ serve as alternative ways to access the same underlying index.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Every month, a NEOS Nasdaq-100 High Income ETF (NASDAQ:QQQI) holder gets a distribution check. In August 2026, it was $0.6518 per share. The annualized forward rate sits at $7.8216. The check feels like income, but the total-return record tells a different story. Since QQQI's first ex-dividend date, holders have quietly foregone roughly $10.97 per share in total return compared to a matching Nasdaq-100 position that costs a fraction to own.
#high

21 days ago
Starting the lightning round on September 14, when a caller inquired about SentinelOne, Inc. (NYSE:S), Mad Money host Jim Cramer remarked:
No, look, I think you don't need, look, my Charitable Trust owns both Palo Alto and CrowdStrike. It's already too many. I think either one of those two is superior to letter S.
The latest results show a large difference in scale. SentinelOne's fiscal second-quarter 2027 revenue rose 21% year over year to $292 million, while annualized recurring revenue increased 22% to $1.218 billion. Palo Alto Networks, Inc.'s (NASDAQ:PANW) fiscal fourth-quarter 2026 revenue rose 34% to $3.41 billion, while Next-Generation Security ARR increased 63% to $9.10 billion. Additionally, we have discussed CRWD in our recent article, "Jim Cramer Highlights CrowdStrike (CRWD) as AI Security Concerns Lift Cybersecurity Stocks."
SentinelOne, Inc. (NYSE:S) non-GAAP operating margin reached 10% in fiscal Q2 2027, up from 2% a year earlier, while its GAAP operating margin improved to negative 31% from negative 33%. The company guided for fiscal third-quarter revenue of $309 million to $311 million and full-year revenue of $1.202 billion to $1.207 billion.
Palo Alto Networks, Inc. (NASDAQ:PANW) reported approximately $1 billion of non-GAAP operating income in its fiscal fourth quarter of 2026, compared with $768 million a year earlier. Adjusted free cash flow reached approximately $1.3 billion, while GAAP operating income was $172 million versus $497 million a year earlier. Palo Alto CEO Nikesh Arora said in the September 1 earnings release that the latest advances in AI are "elevating cybersecurity to the top of the CIO priority list."
#billion #year #gaap #operating

21 days ago
High Tide Inc. (NASDAQ:HITI) reported record fiscal third-quarter revenue of C$198.8 million on September 14, up 33% year over year. Operating income increased 133% to C$8.7 million for the quarter ended July 31, 2026, yet net cash provided by operating activities slipped to C$10.1 million from C$10.7 million.
High Tide Inc. (NASDAQ:HITI) generated C$11.9 million of operating cash flow before changes in non-cash working capital, up 44%. Working capital then absorbed C$1.8 million, compared with a C$2.4 million release a year earlier. That approximately C$4.2 million unfavorable swing outweighed the improvement before working-capital movements. The question is whether expansion will keep requiring a larger cash commitment.
High Tide Inc. (NASDAQ:HITI) is translating sales growth into stronger operating profitability. Operating income represented approximately 4.4% of revenue, compared with 2.5% a year earlier. That improvement gives the business more room to absorb the costs of expansion.
High Tide Inc. (NASDAQ:HITI) opened four Canadian stores and acquired four more during the quarter. Its German medical-cannabis subsidiary, Remexian, generated C$38.2 million in revenue, up from C$31.6 million sequentially. Remexian distributed 10.2 tonnes, a 35% sequential increase. Both markets offer opportunities to build sales across a larger operating base.
High Tide Inc. (NASDAQ:HITI) also improved operating cash flow to C$4.4 million in the second quarter. For the first nine months, operating cash flow reached C$20.4 million versus C$19.6 million a year earlier. Those comparisons show that the quarterly year-over-year decline sits alongside improving cash generation over other periods.
#high


21 days ago
McDonald's (MCD) stock fell 14.2% over the past 12 months, versus roughly 14.3% for the S&P 500, and now sits near its 52-week low. Over roughly the same stretch, management changed how it explains weak traffic. It used to point at customers outside its control. It now points at its own restaurants, and that makes the stock a different bet.
Who Did McDonald's Say Was Pulling Back?
About a year ago, on the second-quarter 2025 call, the lead worry sat outside the company. The CEO put it this way: "Visits across the industry by low-income consumers once again declined by double digits." The value message of that period leaned on core menu pricing, which management said shapes how customers judge value most.
So What Does McDonald's Say Went Wrong Instead?
In the latest call, for the second quarter of 2026, low-income consumers did not come up by name. The backdrop still comes up: industry traffic in several of its largest markets stayed flat to negative. The lead, though, is a miss of its own making. U.S. comparable sales grew 0.8%, and the CEO said the company did not execute at the level it needed.
#TRAFFIC