3 days ago
By Lisandra Paraguassu, Brendan O'Boyle and Luciana Magalhaes
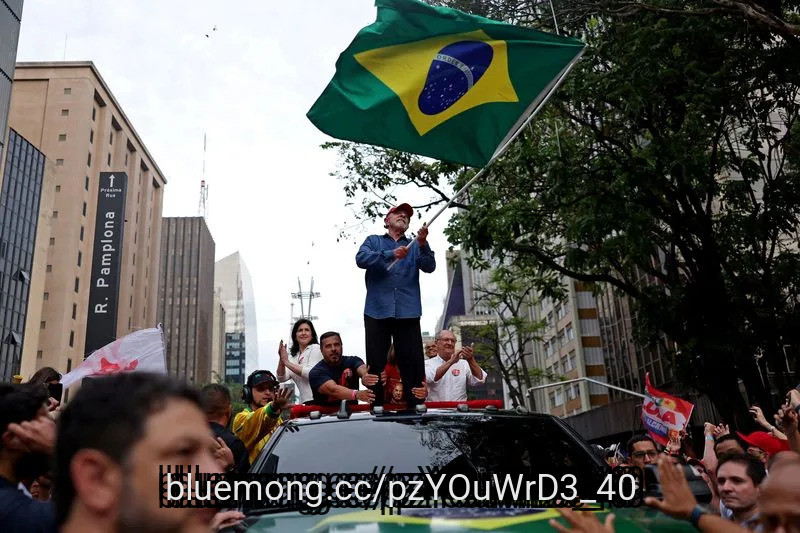
SAO PAULO, Oct 25 (Reuters) - Brazilian President Luiz Inacio Lula da Silva won a historic fourth term on Sunday, the country's electoral court said, in a shock result that defied polls, precedent and global anti-incumbent sentiment to put the brakes on a wave of right-wing election victories across Latin America.
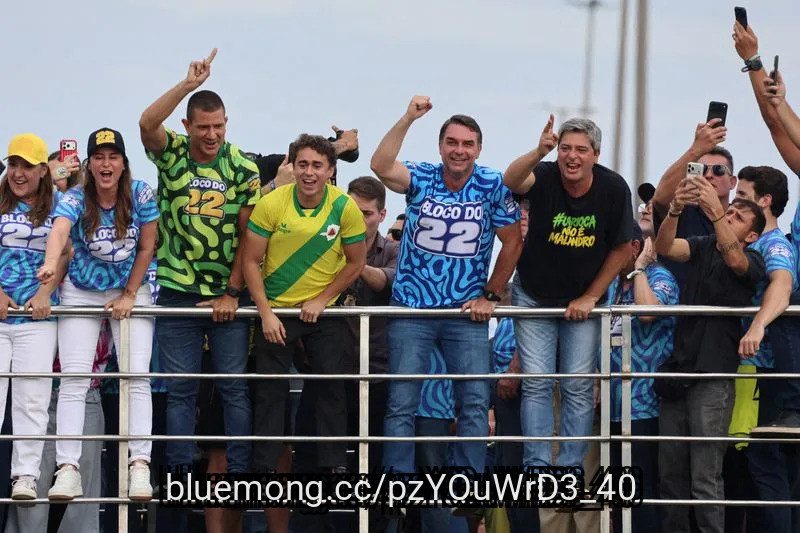
However, his opponent Senator Flavio Bolsonaro, the eldest son of former President Jair Bolsonaro, refused to accept defeat and said he would ask for the result to be annulled due to a Sunday ruling from a Supreme Court justice that extended voting for two hours.
Bolsonaro led the election's first round but lost in the runoff by over 4 million votes, rattling Brazilian financial markets which had bet on his victory. His refusal to concede defeat has echoes of his father's reaction after losing to Lula in 2022. Jair Bolsonaro never accepted his loss and was later sentenced by the Supreme Court to 27-years in prison for plotting a coup to remain in power.
The scale of Flavio Bolsonaro's loss to Lula — by more than twice his father's losing margin — and the fact his campaign also asked for an extension due to rains in the conservative-leaning south make any annulment unlikely, **** ysts said.
#bolsonaro #lula #supreme

10 days ago
FC Bayern welcome ****** nal to the Allianz Arena on Wednesday evening (21.00 CEST) for Matchday 3 of the Champions League. The Munich side faced the Gunners in the league phase last season too – and, after five consecutive matches against them without defeat (four wins), suffered a 3–1 defeat at the hands of Mikel Arteta's team in London. Now, FCB are out for revenge on their home turf, and as our ****** ysis of the facts shows, the prospects of that are pretty good.
Of the seven home games against the Gunners to date, the Munich men have lost just one and come away as winners on five occasions. The record champions have won all three of their most recent encounters in Munich – including two by a margin of at least four goals.
Overall, too, the head-to-head stats favour the Bavarians. In 15 Champions League meetings, FCB have won eight of them, three have ended in a draw and ****** nal have won four times. This means the London side have lost 53 per cent of their matches against FCB – of all the opponents the Gunners have faced five times or more in major European competition, they have a higher loss rate only against Barcelona (67 per cent – six defeats from nine matches).
The league phase of the Champions League and Munich's Allianz Arena – from FC Bayern's perspective, they're a perfect match: since a 3–2 defeat to Manchester City in December 2013, the German record champions have not lost a home fixture in the Champions League group stage/league phase. Of the 39 home games at that stage of the competition during this period, they've won 37 (with two draws) – most recently, they've even recorded nine consecutive home wins.
However, their opponents ****** nal have also been in outstanding form in the early stages of the competition recently and have won all of their last 14 Champions League group stage/league phase encounters. They last dropped points in November 2024, when they lost 1–0 away to Inter Milan.
#arsenal

10 days ago
Steelers fans overwhelmed Raymond James Stadium on Sunday, boosting the road team's effort to overcome a 13-0 halftime deficit and a 16-3 fourth-quarter deficit.
Tackle Tristan Wirfs isn't upset with Buccaneers fans for the lack of in-person support.
"Can you blame them?" Wirfs said, via JoeBucsFan.com. "You know, we're 1-4 and haven't really given them much to cheer about.
"So, yeah, it sucks. It sucks when you're going ****** near silent count at home. But you've got to give [fans] something to cheer for."
The Bucs are now 1-5. And the fans didn't have much to cheer for on Sunday, as the double-digit margin melted into a loss.
#deficit #steelers #james


21 days ago
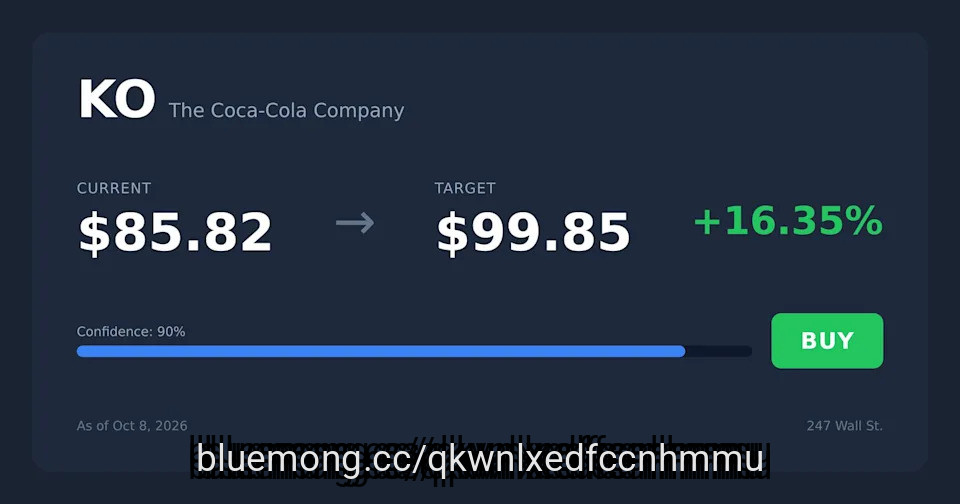
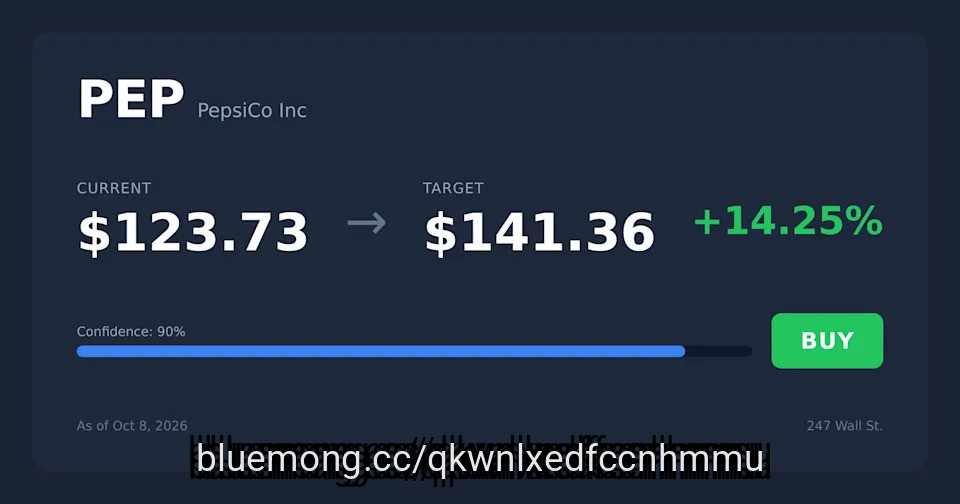
Coca-Cola ($KO) beats PepsiCo ($PEP) for generational portfolios with 63 consecutive dividend increases, wider margins, and 182% 10-year share gains versus 60%.
PepsiCo's free cash flow barely covers its 4.44% dividend yield, while Coca-Cola's expected $12.4B free cash flow dwarfs its $8.8B dividend payout.
A pending IRS appeals ruling and a premium P/E of 28 are the two risks that could crack Coca-Cola's otherwise dominant long-term case.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coca-Cola didn't make the cut. Enter your email to see the names that beat KO. The report is free. Enter your email and see if any of your stocks made the cut.
Coca-Cola (NYSE:KO) or PepsiCo (NASDAQ:PEP): Which one better suits someone investing for retirement right now, knowing the shares may pass to the next generation? Looked at over several decades, Coca-Cola wins. PepsiCo pays the bigger yield today. Coca-Cola has the safer dividend, the stronger brand economics and fewer structural cracks.
#stocks



22 days ago
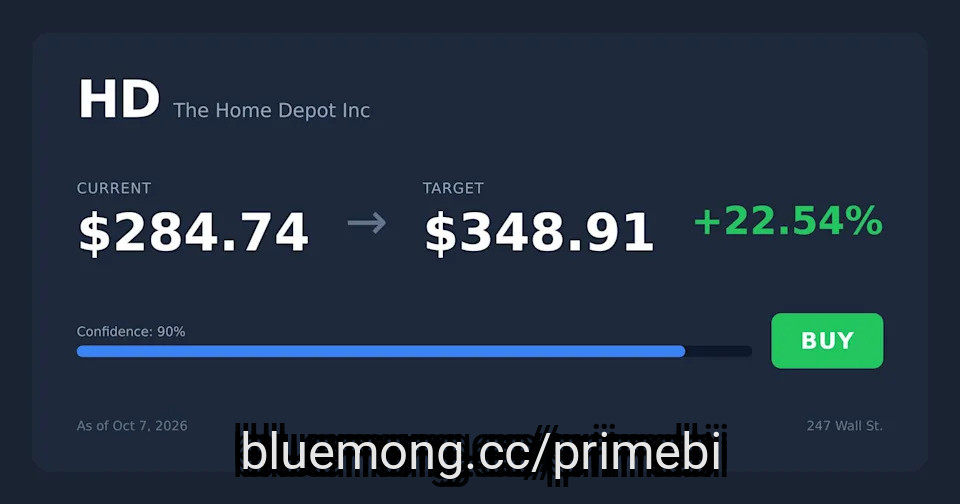
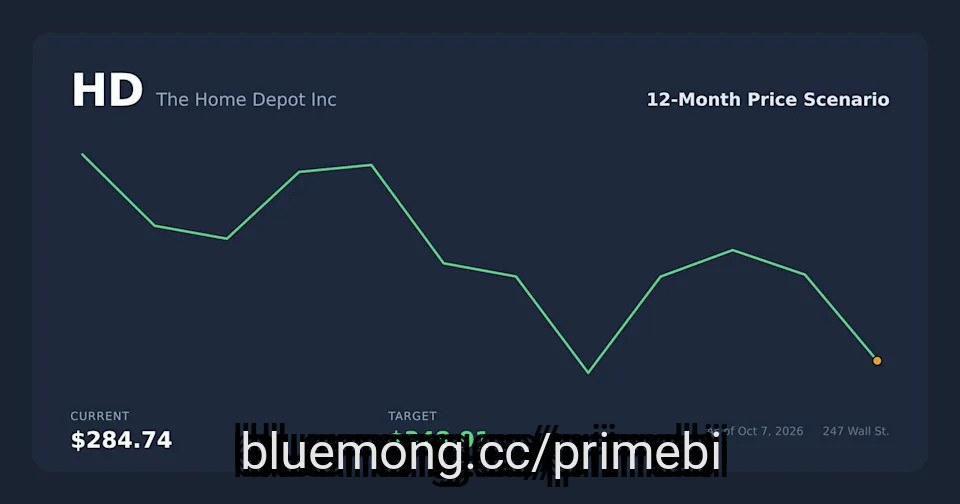
Home Depot (HD) has dropped 15% year to date, yet even the model's conservative one-year price target of $319 sits above today's $285.
A 3.75% dividend yield anchors the buy threshold at $243, requiring a further 15% decline from current levels before reassessment.
The 52-week low of $277 sits just 3% below today's price, making it too thin a margin to serve as a meaningful buy trigger.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Shares of Home Depot (NYSE:HD) traded at $285.10 as of 10:01 AM ET on October 7, 2026, down 0.55% in Wednesday's session. The stock has fallen 15.33% year to date and 24.68% over the past twelve months. Most of the damage is recent. Shares are down 11.2% over the past month.
#down

22 days ago
JPMorgan just raised its dividend 10% while still paying out only 28% of earnings, and Visa's even lower 23% payout fuels years of double-digit raises.
Cisco's AI infrastructure orders hit $9.3 billion, lifting earnings faster than its dividend, while T. Rowe Price yields 5% at just 10 times earnings.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The best dividend raises come from companies that pay out a small piece of what they earn. JPMorgan Chase (NYSE:JPM) just showed how that works: it lifted its quarterly dividend from $1.50 to $1.65, a 10% increase, and the new annual rate still matches only 28.3% of trailing earnings. The five companies below all fit that pattern. Each has strong earnings and a payout ratio low enough to fund many more raises. A long streak of past increases supports the case for some of them, but the reason they're here is how much room each has to keep advancing.
Visa (NYSE:V) yields only about 0.72% on its $2.68 annualized dividend at a share price of $370.97. That's a small yield, but the dividend has a lot of room to grow. The payout uses about 22.8% of trailing diluted EPS of $11.75, and Visa's trailing operating margin is 66.1%.
#payout #trailing
22 days ago
From a purely statistical standpoint, Wall Street has thrived under President Donald Trump. During his first, non-consecutive term, the timeless Dow Jones Industrial Average (DJINDICES:^DJI), benchmark S&P 500 (SNPINDEX:^GSPC), and tech-focused Nasdaq Composite (NASDAQINDEX:^IXIC) gained 57%, 70%, and 142%, respectively. We've witnessed something of an encore performance since the beginning of his second term in January 2025.
The Trump bull market is being fueled by the artificial intelligence (AI) infrastructure build-out, much better-than-expected corporate earnings, and record share buybacks. The president's first-term tax-and-spending law, the Tax Cuts and Jobs Act (signed into law December 2017), spurred the latter by reducing the peak marginal corporate income tax rate to 21%, the lowest level since 1939.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Official White House Photo by Daniel Torok.
But things may not be as perfect for the stock market as the Dow's, S&P 500's, and Nasdaq Composite's gains imply. An ominous $8.44 trillion figure with historical precedent at its back looms large, implying that the Trump bull market is operating on borrowed time.
#term


22 days ago
American Tower Corporation (NYSE:AMT) traded at around $165 on October 6, within five dollars of its 52-week low of $160.06.
The company keeps 45.41% of revenue as operating profit on a portfolio of communications towers leased to wireless carriers. A business that profitable sitting at a 52-week low is usually a disagreement about the future rather than the present.
READ ALSO: What is eBay's (EBAY) Economic Moat, and is it Widening or Narrowing?
A tower is difficult to replicate for reasons that have nothing to do with engineering. Local authorities restrict where new structures can go, so an existing site near a highway or a dense suburb cannot simply be copied next door.
The economics follow from that scarcity. The first tenant on a tower covers the construction and the ground lease, and each additional tenant is close to pure margin. Gross margin of 73.77% is what that layering produces, and the 45.41% operating margin is what survives after the overheads.
#NYSE


22 days ago
AbbVie Inc. (NYSE:ABBV) was trading at around $263 on October 5, up 14.18% over twelve months. Its payout ratio is 190.40%. The company distributes nearly twice what it reports as profit.
A dividend that large is either about to be cut or is being paid out of something the earnings line does not show.
READ ALSO: Here is Why Tripadvisor (TRIP) is a Bad Investment at Today's Price
AbbVie reported net income of $6.27 billion and generated $16.87 billion of free cash flow. Dividends are paid from the second number, so a ratio measured against the first is describing depressed earnings rather than a company living beyond its means.
The margins show what depresses them. Operating margin is 40.04%. Net margin is 9.80%. Thirty points vanish between those lines, and where they vanish matters. Costs that high sitting below the operating line are not the business failing to earn. They are the amortization of a drug portfolio AbbVie bought rather than discovered, plus interest on the debt that bought it.
#paid
22 days ago
The Boeing Company (NYSE:BA) was trading at around $193 on October 5, down 11.91% over twelve months. Boeing reported net income of $2.09 billion over the past twelve months. Its EBITDA over the same period was negative $2.9 billion.
Those two figures describe the same year and point in opposite directions. Only one of them tells you what the business did.
READ ALSO: GE Aerospace (GE) vs. RTX (RTX): Which Is the Better Stock to Buy?
Start with the figure that describes the aircraft business itself. Boeing's operating margin is 0.00%. On $93.99 billion of revenue, building and selling airplanes earned nothing.
That is not a rounding problem. Gross profit was $4.43 billion on that revenue, under five percent for a manufacturer, which means the cost of building the aircraft very nearly equals what customers pay for them.
#same

23 days ago
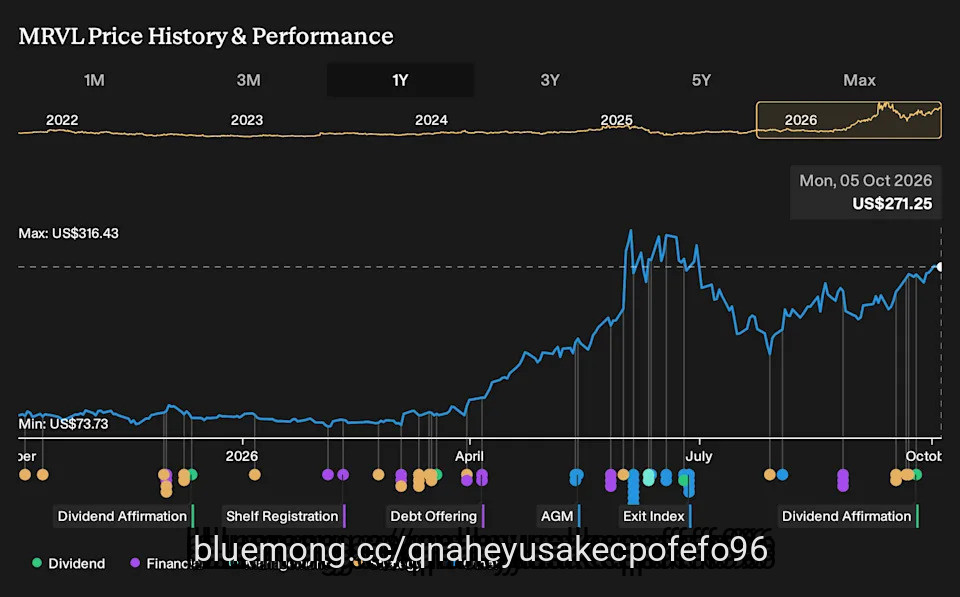
In late September 2026, AT&S Austria Technologie & Systemtechnik AG announced an expanded collaboration with Marvell Technology to increase advanced IC substrate capacity for next-generation AI and cloud infrastructure, while Marvell also affirmed a quarterly dividend of US$0.06 per share payable on October 29, 2026.
This deeper manufacturing partnership gives Marvell greater access to complex packaging technologies that are increasingly critical for high-performance AI chips and data center hardware.
Next, we'll examine how this expanded AT&S manufacturing capacity could influence Marvell's AI-focused growth story and longer-term investment narrative.
The future of work is here. Discover the 89 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
To own Marvell, you need to believe its AI and data center franchises can justify today's rich valuation and eventually translate into stronger, more consistent earnings power. The expanded AT&S IC substrate deal directly supports Marvell's near term AI optics and custom silicon ramp, while also amplifying the existing risk that long term supplier prepayments and capacity commitments could weigh on margins and free cash flow if AI demand or customer ramps slow.
#term #substrate #Manufacturing #data

23 days ago
In late September 2026, Huntington Ingalls Industries' Newport News Shipbuilding division secured a US$5.10 billion contract to conduct the refueling and complex overhaul of USS Harry S. Truman (CVN 75), while also advancing carrier programs and expanding unmanned production capacity across its U.S. facilities.
Together with the Navy order for 10 ROMULUS unmanned surface vessels and the Pocasset unmanned systems campus expansion, these developments highlight how HII is tying long-duration carrier work to growing autonomous maritime capabilities within its Mission Technologies division.
We'll now examine how the Truman overhaul award, alongside new ROMULUS unmanned vessel production, could influence Huntington Ingalls Industries' investment narrative.
Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 33 best rare earth metal stocks of the very few that mine this essential strategic resource.
To own Huntington Ingalls Industries, you need to believe that its multi decade carrier, submarine and unmanned systems backlog can be converted into steadier margins and free cash flow despite current back end loaded cash expectations. The Truman refueling and complex overhaul award reinforces that backlog, but does not remove the near term risk that 2026 free cash flow could miss if contract advances or tax benefits arrive later or smaller than management hopes.
#unmanned #truman #romulus


25 days ago
VANDALIA, Ohio — President Donald Trump rallied Saturday for Republicans in Ohio’s competitive races for Senate and governor, predicting that the party will defy expectations in a choppy midterm election climate.
“I think we’re going to have a big surprise, because they don’t know what’s happening,” Trump said while speaking onstage inside a high school gymnasium near Dayton.
“Just get out and vote,” Trump added. “If you do that, we’re going to win, and we’re going to win big. And we’re going to shove it up their ***** .”
The visit, part of what White House officials have told NBC News will be a push through at least 17 states between now and Nov. 3, was aimed at boosting Sen. Jon Husted and GOP gubernatorial nominee Vivek Ramaswamy.
Trump, who won Ohio three times by comfortable margins, opened his speech with praise for both before moving into broader remarks to promote himself and his administration. He also offered support for local Rep. Mike Turner and for several House candidates in attendance, including Derek Merrin, the Republican running against longtime Democratic Rep. Marcy Kaptur in northwest Ohio.
#Trump #saturday #republicans #senate



25 days ago
Chris Rock said that his problem with "quote, unquote, wokeness" is that it leads to a world that is, in his opinion, less forgiving than it needs to be.
The comedian and "Misty Green" filmmaker stopped by the New York Times' "The Interview" series this weekend and said that while advocating for marginalized communities is great, it needs to come with forgiveness, a huge theme in his new film starring Rosalind Eleazar.
When asked by host David Marchese about the throughline forgiveness has in the film, Rock said that "you don't really realize if you love somebody until you have to forgive them," adding that somebody letting you down or betraying you, but still choosing to be around them, is what true love is.
"I have a friend that's going to be nameless that might have gotten canceled," Rock said. "Another friend of mine was like, 'How can you be friends with that person?' I was like, 'If you're only friends with your friends when they're good, they're not your friends.' If you've got a bunch of people that are only going to be there when you're good, you have no friends. That doesn't mean condoning abusive behavior; you can reprimand your friends. That's also part of friendship."
When pressed by Marchese, who said that everyone has to have a line at some point, the comedian held his ground.
"I'm a Christian, and God forgives," he said. "The problem with quote, unquote, wokeness — and don't get me wrong, it is great that marginalized people have a voice; it is great to advocate for anybody that feels marginalized — but the problem is we're in the Old Testament right now, and the Old Testament has no forgiveness. The Old Testament didn't work, so they had to write a remix called the New Testament."
#rock #marginalized #forgiveness

25 days ago
Chris Rock dished the big "problem with wokeness" is it turned its true believers into coldhearted prudes who are unwilling to forgive people for supposed transgressions, no matter how big or small.
The comedy icon weighed in on the "Woke 1.o era" during a Saturday interview with The New York Times in which he compared it to the Old Testament… or what Jews simply refer to as the Bible.
Rock said it was "great" that society became more concerned with how "marginalized" people are treated in recent years, but he said the movement has gone way too far and become ruthless.
"The problem with wokeness is we're in the Old Testament right now, okay," Rock said. "The Old Testament has no forgiveness. The Old Testament didn't work, so they had to write a remix called the New Testament."
The Interview co-host David Marchese followed up by saying there has been a lot of talk about it lately, especially after Rep. Alexandria Ocasio-Cortez (D-NY) declared "Woke 1 was crazy!" back in August.
#people
1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

1 month ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

1 month ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


1 month ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
1 month ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

1 month ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

1 month ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley


1 month ago
RF Industries, Ltd. (NASDAQ:RFIL) reported stronger fiscal third-quarter results on September 14. Revenue increased 21% to $23.96 million for the quarter ended July 31, 2026, while operating income reached approximately $1.8 million, compared with $720,000 a year earlier.
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier

1 month ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth

1 month ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
1 month ago
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial