
6 days ago
With the federal budget deficit at $2 trillion and debt-interest costs topping $1 trillion a year, it may be tempting to look for extra cash under the sofa cushions.
Urgency has grown in recent months as Treasury yields have soared to the highest levels in more than 20 years, putting more pressure on interest expenses.
The Treasury Department has tried some unconventional measures recently to take the heat off yields, including buybacks of more long-dated debt and its intervention to prop up the yen that let ***** an avoid selling its Treasuries.
Given such surprises, speculation has grown around even more far-out tactics. One idea that comes up from time to time is for the Treasury Department to price its immense gold holdings at market rates.
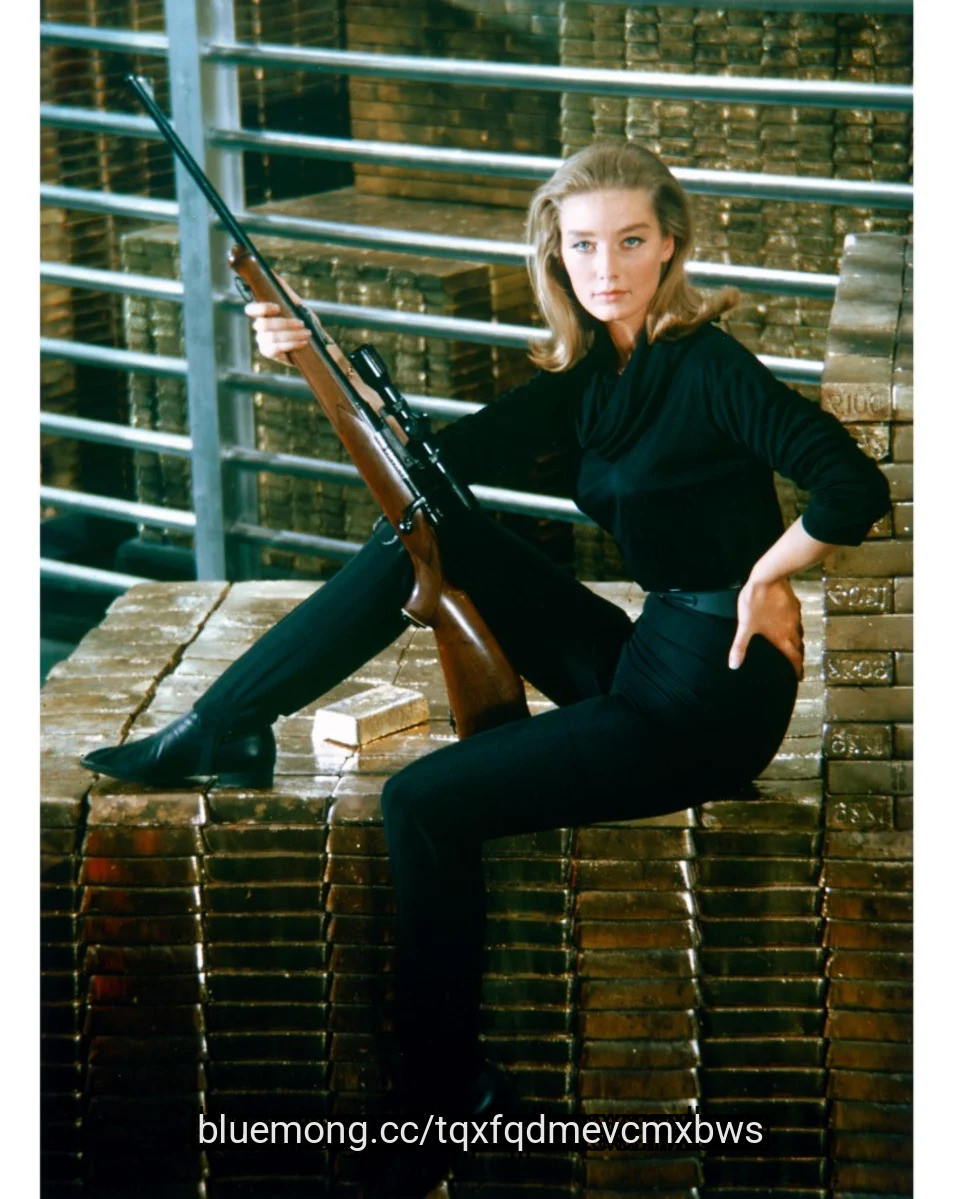
The U.S. has the world's largest gold reserves, which total about 261.5 million ounces, or more than double what No. 2 holder Germany has. But the U.S. ***** d's official price was set by Congress in 1973 at $42.22 per ounce, and it hasn't changed since.
#trillion #interest
25 days ago
(Bloomberg) -- Cryptocurrencies fell on Wednesday as a wave of forced selling swept across digital-asset venues, with broader market jitters further weighing on risk appetite.
Most Read from Bloomberg
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Deeply Distressed US Loans Rise to Highest Level Since Pandemic, JPMorgan Says
SpaceX in Talks to Borrow $40 Billion to Buy Nvidia Chips
#launch #developed #deeply
Most Read from Bloomberg
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Deeply Distressed US Loans Rise to Highest Level Since Pandemic, JPMorgan Says
SpaceX in Talks to Borrow $40 Billion to Buy Nvidia Chips
#launch #developed #deeply

1 month ago
GOOG trades at a P/E of 14 versus META's 24, with Cloud revenue surging 82% while META's operating margins collapsed from 43% to 31%.
META's Reality Labs bleeds roughly $4B per quarter, 2026 capex is projected between $130B and $145B, and active litigation makes it a volatile aggressive-growth bet rather than a retirement hold.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Google didn't make the cut. Enter your email to see the names that beat GOOG. The report is free. Enter your email and see if any of your stocks made the cut.
Alphabet (NASDAQ:GOOG) and Meta Platforms (NASDAQ:META) just unleashed rival consumer AI agents (Google's family-focused CC, a shared agent supporting up to six family members, and Meta's single-user Muse, aiming for higher autonomy across a user's digital life, including commerce), and the retirement-focused investor writing one check today needs a clear answer: which mega-cap deserves the slot?
Both stocks are pouring tens of billions into AI infrastructure. Both consumer AI agents (not just chatbots) are designed to take real actions on a user's behalf rather than only answering questions. However, CC is a family-oriented productivity and logistics agent tightly tied to the Google ecosystem. Muse is a more general-purpose personal agent aiming for higher autonomy across a user's digital life, including commerce. They compete in the emerging "AI agent that actually does things" category, but target different use cases and user models.
#stocks #family


1 month ago
The federal government is preparing to cash out a chunk of its stake in GlobalFoundries (GFS). A new filing shows Washington plans to sell as many as 9.9 million shares of the semiconductor firm, months after agreeing to take an equity position in the company.
For investors watching GFS stock, the move raises questions about what comes next, even as GlobalFoundries lands new government-backed deals in quantum computing and silicon photonics. Here is what the filing means, and why the government owned shares of GlobalFoundries stock in the first place.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#globalfoundries #months #filing


1 month ago
When Ray Dalio speaks, investors tend to listen, and likely for good reason. He ran Bridgewater **** ociates, the hedge fund he founded, for half a century, and over that time, he was one of the most successful investment managers in history.
In fact, he has long used history as a guide for deploying capital, and today, he believes history offers lessons for how investors should approach the AI boom. Specifically, he sees echoes of 1929 and 2000 in the current situation, and is urging investors to approach AI stocks with caution. Here is what he said and why investors may want to heed his advice.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
First of all, investors should remember that Dalio has stepped down from Bridgewater. Thus, the fund's investments in AI stocks like ServiceNow and Nutanix were likely made without his input.
Given what he has said recently, he may even disagree with those purchases. When Dalio appeared on the podcast The Diary of a CEO in August, he said that AI shows "classic signs" of a bubble.
#dalio #signal #flashing #likely


1 month ago
Intuitive Surgical (ISRG), maker of the da Vinci surgical robots, trades at about $382, some 36% below its 52-week high. Even so, you pay about 35.9 times trailing adjusted earnings. That is normalized net income with stock-based compensation added back, a basis meant to sit closer to the one ****** ysts forecast on, though the two are not defined identically. ****** ysts' forecasts run to 2027, the year Intuitive plans to start lowering what customers pay per use on some instruments.
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures

1 month ago
US stock futures moved higher on Wednesday as investors awaited the Federal Reserve's interest rate decision. Oil prices declined following an unexpected increase in US inventories, while developments involving Meta and OpenAI remained in focus.
At 07:12 GMT, Dow futures were up 129 points, or 0.3%. S&P 500 futures gained 21 points, or 0.3%, while Nasdaq 100 futures advanced 145 points, or 0.5%.
Wall Street's main indices had declined in the previous session as US government bond yields approached two-decade highs. Higher oil prices, linked to the widening conflict in the Middle East, contributed to concerns about inflation and further monetary policy tightening.
Analysts at Vital Knowledge described a feedback mechanism in which rising oil prices push bond yields higher, affect investor sentiment and increase pressure on central banks to raise interest rates.
Markets broadly anticipated a 25-basis-point interest rate increase at the conclusion of the Federal Open Market Committee's two-day meeting.
#higher #interest #prices #rate

2 months ago
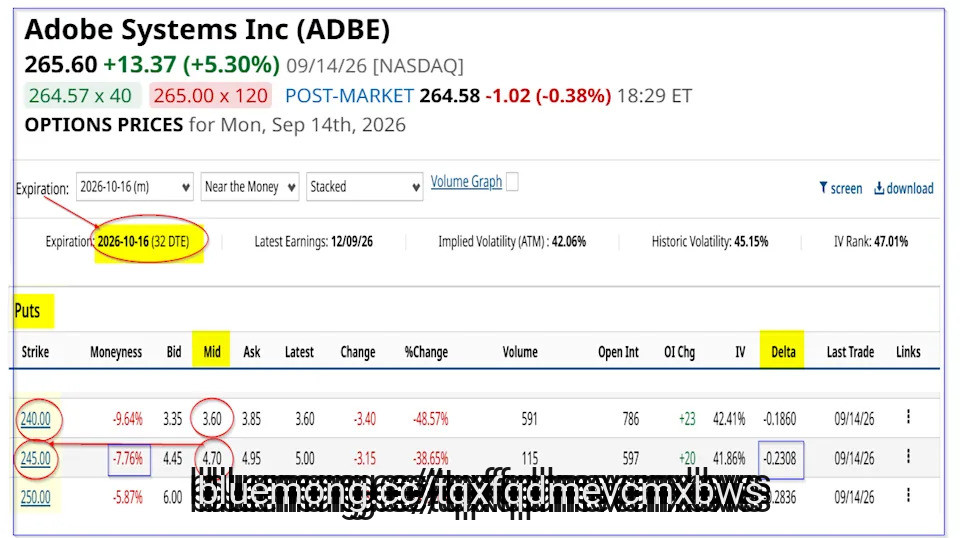
Adobe Systems (ADBE) reported strong revenue and free cash flow results for fiscal Q3 on Sept. 10. Free cash flow (FCF) margins were over 40% over the past year. ADBE stock is dirt cheap now at less than 10x earnings and 10x trailing 12-month (TTM) FCF. As a result, shorting ADBE puts and put credit spreads work well for value investors.
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#investors #cash #flow #past

2 months ago
Oracle Chief Financial Officer Hilary Maxson told employees on Tuesday that the company's latest round of layoffs should not be understood as a directive to do more with fewer resources, according to Business Insider, which reviewed a recording of the remarks.
"I don't mean doing more with less, which is a phrase that I really, really don't like," Maxson said. "It means simplifying processes that don't help customers and making clear choices on where we're going to use our resources where they have the greatest impact."
The comments came during Maxson's first companywide meeting since joining Oracle, held one day after the company began a new round of job cuts. According to Business Insider, the layoffs went unmentioned by Maxson and the other executives who spoke during the roughly hour-long town hall. Instead, executives focused on growth, customer demand, and artificial intelligence.
Co-CEO Mike Sicilia used the meeting to offer employees a mantra for the quarter. "I'd ask you to keep asking a very simple question: How does the work that I'm doing help deliver a better outcome for a customer?" Sicilia said. "There's a lot of change around this, a lot going on in the world, and in moments like this, how we work together and how we show up for our customers and for each other matters most."
The latest cuts follow a significant reduction in Oracle's workforce over the past year. According to a regulatory filing, Oracle shed approximately 21,000 positions — representing about 13% of its workforce — across the fiscal year that closed on May 31, 2026.
#business #round
2 months ago
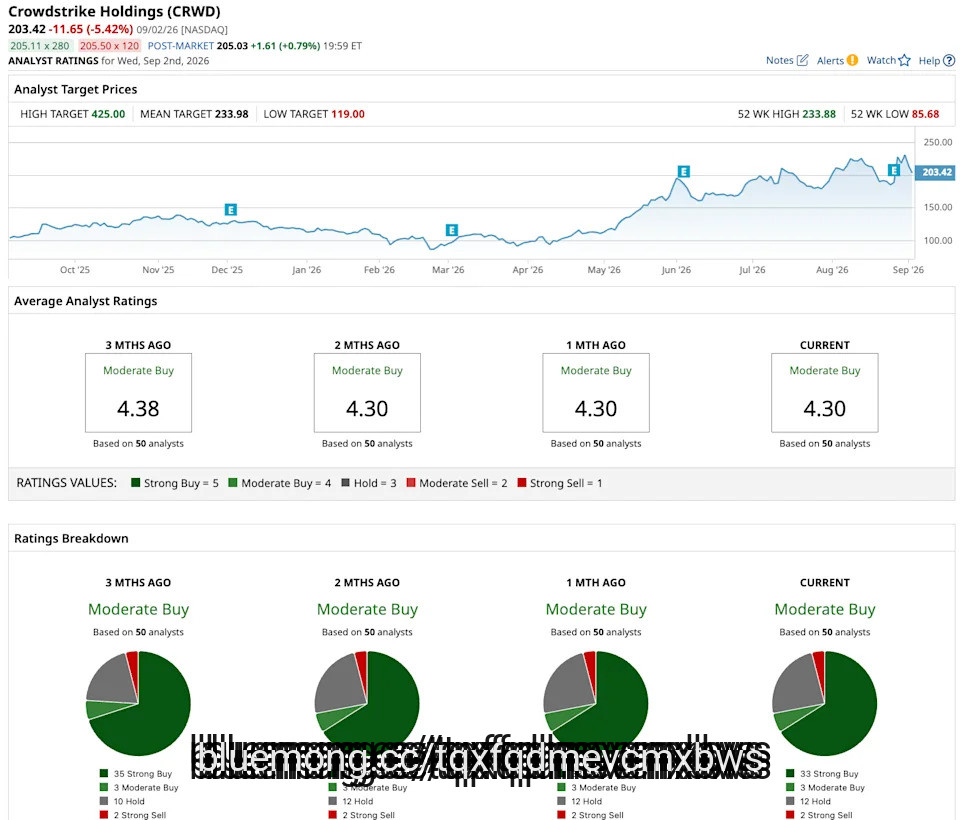
CrowdStrike (CRWD) is among the largest cybersecurity companies globally. Valued at a market capitalization of more than $218 billion, CrowdStrike stock has returned more than 500% since its initial public offering (IPO) in 2019.
At its Fal.Con conference this week, the cybersecurity giant rolled out two major artificial intelligence (AI) products built to protect the growing army of AI agents running inside businesses. These announcements have arrived as CRWD stock draws fresh attention from Wall Street. CrowdStrike is betting that securing AI will soon be the key driver of its future growth engine.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#Stock #fans

2 months ago
Affordability in a car market usually looks like a math problem. Every so often it turns out to be a permission problem.
Americans have spent four years watching window stickers climb and calling it inflation. The average new vehicle sold for $50,089 in August, the first month of 2026 that the industry average cleared $50,000, according to Kelley Blue Book.
Buyers feel it without reading the data.
"Many American households are under significant financial pressure," said Erin Keating, executive ***** yst at ***** Automotive, in comments published by Kelley Blue Book.
Electric cars sit higher up the ladder. The cheapest new EV on sale in the U.S. starts at $29,990 before destination, a price Nissan (NSANY) called "the lowest starting MSRP for any new EV currently on sale in the U.S.," according to Electrek.
#according
2 months ago
Oracle's remaining performance obligations surged 363% to $638 billion, but $56 billion in quarterly capex pushed free cash flow deeply negative.
Jensen Huang disclosed NVIDIA can only meet 70% of current demand, while CoreWeave burned $5.7 billion in Q2 free cash flow against $104 billion in backlog.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Oracle didn't make the cut. Enter your email to see the names that beat ORCL. The report is free. Enter your email and see if any of your stocks made the cut.
OpenAI now plans to spend roughly $750 billion on compute infrastructure through 2030, a figure that represents a 25% increase from earlier 2026 estimates. The company still calls itself "really short" on capacity. That gap, between three-quarters of a trillion dollars in planned spend and a stated capacity shortfall, is the number that reframes every AI infrastructure bet on the board, starting with Oracle (NYSE:ORCL).
Oracle is the clearest public-market conduit for that OpenAI dollar. In Q4 FY26, Oracle disclosed remaining performance obligations of $638 billion, up 363% year over year, of which $75 billion is tied to prepaid or customer-supplied GPU arrangements. Cloud Infrastructure revenue reached $5.79 billion, up 93% year over year, and Oracle Multicloud AI Database grew 404% in Q4. Global GPU utilization sits at 97.5%, and management said "there's still a massively higher demand than there is supply."
#free #orcl


2 months ago
If you hold Pfizer (PFE) or Zoetis (ZTS), you hold the same idea: a branded medicine becomes a standard of care and keeps earning for years, in people or in animals. That is where it stops. Pfizer is buying replacements for older drugs losing exclusivity. Zoetis is cutting its effective price to keep the franchises it has. Same bet, two opposite defenses.
Pfizer lifted the midpoint of its 2026 revenue guidance by $500 million while cutting its COVID-19 revenue expectation to about $4 billion from about $5 billion. The rest of the company covered that gap: excluding COVID products, the underlying business grew 5% operationally in the second quarter of 2026, with Eliquis and Padcev among the drivers management named.
Zoetis cut its 2026 outlook and now expects revenue to decline 1% to 3% on an organic operational basis. Management said sales trends through July had not yet indicated market stabilization. Pfizer's raise rests on business it can already see. Zoetis has yet to see visibility on market stabilization.
Pfizer is buying growth and cutting cost, and expects about $9.7 billion in total net savings through 2029. What that funds is an aim, not a guide: a risk-adjusted high single-digit revenue CAGR from year-end 2028 through year-end 2033.
The pipeline behind that aim is expensive to get wrong. A Phase III lung cancer trial that missed its primary endpoint and, to a lesser extent, the removal of revenue projections for Oxbryta led to $4.3 billion of noncash intangible **** et impairments recorded in the second quarter of 2026. While an unadjusted price-to-EBIT comparison puts Pfizer at 23.9 against Zoetis at 9.2, aligning the two on operating income brings them to 9.7x and 9.0x, largely erasing the paying-up premium.
#pfizer #covid

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Volkswagen just told investors it will cut 50,000 more jobs, and the market cheered.
Shares of Europe's largest automaker jumped after the announcement, a reaction that tells you a lot about what Wall Street wants from legacy car companies right now.
For investors, a rising stock and a shrinking workforce point in the same direction, and that is worth understanding.
Volkswagen's Frankfurt-listed shares rose more than 8% on Thursday, September 3, after its supervisory board approved the plan.
When a company cuts tens of thousands of jobs, its fixed costs fall fast, and investors read lower costs as higher future profit.
#shares #Jobs #volkswagen #frankfurt

2 months ago
On August 13, Legence Corp. (NASDAQ:LGN) reported second-quarter results that more than doubled the company's revenue from a year earlier, a jump big enough to make even seasoned investors do a double take. Strip out the contribution from the company's Bowers acquisition and the underlying business still grew 60%. But dig one line deeper into the same report and a less flattering picture shows up: profitability per dollar of revenue actually shrank, and the bottom line posted a wider loss than it did last year. That contrast, blistering growth paired with thinning margins, is the story investors now have to sort out.
The headline number was revenue of $1.26 billion for the quarter, up 110.7% from $598.9 million a year ago. Adjusted EBITDA climbed even faster in percentage terms, rising 114.1% to $154.6 million, which tells you the company managed to grow its cash-generating profit measure roughly in step with the top line even during a period of heavy acquisition-driven expansion. Backlog and awarded contracts, effectively the pipeline of future work already on the books, reached $5.67 billion, more than double the $2.77 billion Legence held a year earlier.
That backlog is not concentrated in one place either. While data centers and technology remained the biggest driver, management pointed to healthy activity across life sciences and healthcare, state and local government, and education as well, spreading the growth across several end markets rather than resting it on a single customer type. The Installation & Maintenance segment did the heavy lifting, with revenue up 162% to $1.06 billion, and even after removing the Bowers acquisition's impact, that segment still grew 86.6% on its own.
Management also used the quarter to raise its full-year guidance, now targeting $4.7 billion to $4.8 billion in revenue, up from a prior range of $4.1 billion to $4.3 billion, alongside adjusted EBITDA guidance lifted to $565 million to $585 million from $470 million to $490 million.
The same report shows profitability moving in the opposite direction of revenue. Gross margin fell to 17.4% from 21.5% a year ago, and the non-GAAP adjusted version slipped to 18.5% from 21.8%, a shift the company attributed to a revenue mix leaning more heavily toward lower-margin installation and maintenance work. The Engineering & Consulting segment felt this directly, with gross profit down 12.4% to $56.1 million even as its revenue grew, a sign that pricing and cost pressure in that business outpaced its sales growth. Net loss attributable to Legence widened to $27.8 million from $5.3 million a year earlier, and the company's total net loss grew to $34.6 million from $3.9 million.
#year #grew #adjusted

2 months ago
On August 25, Box Inc. (NYSE:BOX) reported second-quarter fiscal 2027 results that beat management's own guidance across the board, with revenue climbing 9% to $321.1 million as customers piled into the company's priciest tier, Enterprise Advanced. The bigger story sits underneath the headline number. Box is repositioning itself as the security layer that lets AI agents from Anthropic, Databricks, and Slack actually touch a company's files, and that shift is starting to show up in the billings line.
Billings jumped 17% to $309.5 million, a figure management tied directly to booking strength and record second-quarter wins, which suggests customers are signing bigger contracts rather than trickling in seat by seat. Net retention rose to 106%, ahead of the 105% the company had guided to, driven by both seat expansion and higher price per seat. That combination matters because it means existing customers are both growing their headcount on the platform and paying more per person, a dual engine that is harder to replicate than growth from new logos alone. Suites, Box's bundled higher-tier offering, now make up 69% of revenue, up from 63% a year earlier, and customers paying at least $100,000 annually grew 10% year over year.
A major federal agency illustrated the pattern in the flesh, upgrading to Enterprise Advanced with a fourfold seat expansion to replace several separate software vendors it had been using for contract management and research. Operating margin expanded to 29.4%, and free cash flow jumped 67% to $59.7 million, evidence that the growth is not being bought with discounts. Box also introduced new Model Context Protocol integrations with partners including Anthropic, Databricks, and Slack, letting AI agents execute multistep tasks directly inside a customer's Box environment rather than just answering questions about files stored there.
Not everything in the quarter was clean. CFO Dylan Smith flagged that gross margin faces a constraint tied to "limited access to certain components of the infrastructure," language that points to capacity limits at the cloud providers Box relies on to run its AI features, and management guided third-quarter gross margin down to roughly 80.5% from the 81.2% just posted. Operating margin guidance for the third quarter also steps down to about 28%, a full percentage point below the 29.4% Box just delivered, even as the top line keeps growing.
Currency is another drag that will not disappear on its own. The company absorbed a $0.04 per share hit from foreign exchange in the quarter and expects roughly $0.09 off full-year earnings per share, which is baked into the raised full-year EPS guidance of $1.54. And while 9% reported revenue growth beat expectations, it is still a business growing in the high single digits, a pace that leaves little room for stumbles if Enterprise Advanced adoption cools or larger AI platforms decide to build competing file-governance tools of their own rather than partner with B
2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage
2 months ago
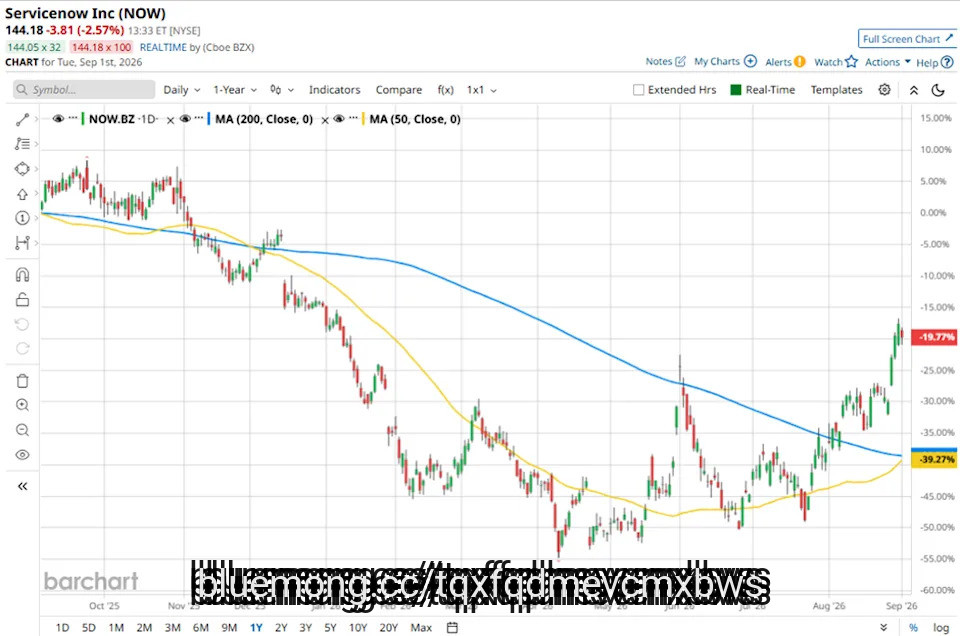
With a market cap of $153 billion, ServiceNow, Inc. (NOW) is a leading provider of cloud-based digital workflow solutions that help organizations automate and streamline business operations across industries worldwide. The company offers a comprehensive portfolio of products spanning IT services, customer service, security, risk management, human resources, and workflow automation, enabling enterprises to improve efficiency and enhance user experiences.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Salesforce fits this criterion perfectly. Headquartered in Santa Clara, California, ServiceNow serves customers globally and continues to expand its capabilities through innovation, strategic partnerships, and AI-driven solutions.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#billion
2 months ago
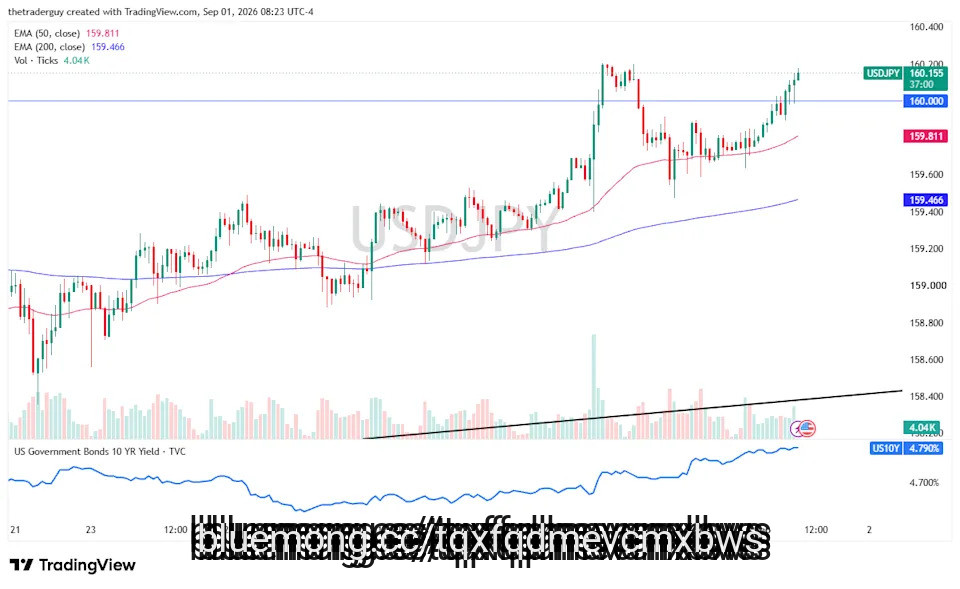
The US dollar against the ***** anese yen is a pair that I watch all the time. I actually have longer-term buy-and-hold positions in this, but I may be adding to this if we can break to a fresh new high somewhere around 160.33.
This is a market that I have no interest in shorting because of the interest rate differential, but there is a little bit of intervention risk here. For myself, I've been long of this pair for months, so this is an addition to what I already have been doing. For short-term trading, it is a viable potential breakout play. I would keep an eye on that 159.8 level, though. A breakdown below that level could signify some type of shift in momentum.
The Australian dollar is a pair that I'm watching closely. If we can break down below the 0.7130 level, I might start shorting for a small move, maybe down to about 0.71, with a stop loss above 0.7160. This is an interest rate play, and the US dollar, of course, is seeing higher rates, while Australia is as well, but it's a different ratio; it's a different amount. The situation still favors the US dollar as far as that is concerned.
The New Zealand dollar, same story. I either sell a break below the 0.5885 level, or I sell a rally that shows signs of exhaustion near the 0.5915 level. I'll be watching this closely. The interest rate differential still favors the US dollar, and I think the real support is probably closer to the 0.5870 level. So maybe a 20-pip move. If we get a little bit of a rally and signs of exhaustion, that might open up more of like a 40-pip move.
If you'd like to know more about how to trade forex, please visit our educational area.
#level #interest #pair

2 months ago
The robot revolution has a slightly awkward sales pitch: Cheaper labor for companies, cheaper products for consumers and, potentially, a pink slip for the person whose job just got cheaper than the machine doing it.
Microsoft (MSFT) co-founder and billionaire Bill Gates is warning that the transition could move faster than society is ready for.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
Dear Broadcom Stock Fans, Mark Your Calendars for August 31
#dear
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Bitcoin (BTC-USD) opened at $77,695.48 on Monday, August 31, 2026, 0.7% lower than Sunday's opening price. As of 9:06 a.m. ET this morning, the price of bitcoin moved up to $77,999.80.
Ethereum (ETH-USD) opened at $2,417.98 on Monday, August 31, 2026, down 1.6% from Sunday's opening price. The price of ethereum moved higher this morning to $2,453.78 as of 9:06 a.m. ET.
Last week we featured an article ******* led, "Bitcoin's Next Test Is $80,000 as Jackson Hole Meeting Looms."
So far, bitcoin isn't passing the test.
#ethereum


2 months ago
Two telecommunications giants recently showcased the contrasting sides of the 5G and connectivity ecosystem. On August 6, AT&T Inc. (NYSE:T) announced it selected Telefonaktiebolaget LM Ericsson (publ) (NASDAQ:ERIC) to supply 600 MHz dual-band radios to support the deployment of its newly acquired spectrum from EchoStar. The partnership reinforces AT&T's ongoing network modernization while keeping Ericsson deeply embedded in U.S. carrier infrastructure.
Shortly after, on August 10, AT&T demonstrated real-world execution by upgrading wireless connectivity at Mississippi State University's Davis Wade Stadium using a Distributed Antenna System powered by Airspan's MobileAccess 6000. While AT&T is actively converting network upgrades into sticky, high-margin subscriber growth, Ericsson faces the capital-intensive burden of hardware delivery.
Ken Wolter / Shutterstock.com
AT&T Inc. (NYSE:T) is showing a stronger financial trajectory and cash-generation profile than its equipment vendor partner, Ericsson. In Q2 2026, AT&T's consolidated revenue increased 2.3% year over year to $31.6 billion, supported by a 5.1% increase in Advanced Connectivity service revenue. Adjusted EPS surged 20.4% to $0.65, beating the $0.59 consensus estimate, while adjusted EBITDA rose 5.2% to $12.3 billion, producing a strong 39.1% margin. Free cash flow reached $4.7 billion, enabling management to raise its full-year share buyback target to $10 billion while maintaining its forecast for more than $18 billion in full-year free cash flow.
Telefonaktiebolaget LM Ericsson (publ) (NASDAQ:ERIC), meanwhile, faced weaker operating momentum in Q2 2026, with net sales declining 6% year over year to SEK 52.7 billion, or approximately $5.0 billion, due to lower IPR licensing revenue and uneven carrier capital spending. Net income fell 12% to SEK 4.1 billion, or approximately $390 million, although adjusted gross margin remained resilient at 48.4%. Free cash flow before M&A, however, plunged from SEK 2.6 billion to just SEK 385 million, or approximately $36.7 million.
#year
2 months ago
Canada Goose Holdings Inc. (NYSE:GOOS) shares closed at $8.28 on August 24, down 5.3%, after Wells Fargo downgraded the stock to Underweight. The call followed a new 50% U.S. duty on certain Canadian imports, including apparel. The duties were originally scheduled for August 19 but took effect on August 22 after a three-day suspension. The question for Canada Goose Holdings Inc. (NYSE:GOOS) is whether luxury pricing and direct distribution can absorb the added cost without weakening demand.
The duty applies to the customs value of covered products, making product-level exposure—not U.S. revenue alone—the key number. Canada Goose Holdings Inc. (NYSE:GOOS) generated C$385.1 million in the United States during fiscal 2026, equal to 25.2% of C$1.53 billion in total revenue.
Canada Goose Holdings Inc. (NYSE:GOOS) has not disclosed how much of its U.S. ****** ortment falls under the tariff or the customs-value base subject to the duty. However, the company reported that most of its goods were manufactured in Canada during fiscal 2026, including nearly all of its down-filled outerwear. More than 80% of those down-filled products were manufactured directly in company facilities.
Canada Goose Holdings Inc. (NYSE:GOOS) has more flexibility than a mass-market apparel supplier. Direct-to-consumer revenue reached C$1.16 billion in fiscal 2026, or 75.7% of total sales. That model gives the company greater control over retail pricing, promotions, product allocation and channel mix.
Canada Goose Holdings Inc. (NYSE:GOOS) also entered the tariff period with evidence that its brand can support higher-value purchases. In the first quarter of fiscal 2027, management reported improved conversion and average order value, while gross margin increased to 62.4% from 61.4% a year earlier. Fiscal 2026 gross margin was 69.7% despite higher freight and duty costs.
#holdings #duty #value

2 months ago
Aristotle Capital Management, LLC, an investment management company, released its "Value Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a 4.32% total return in Q2 2026, underperforming the 13.87% gain for the Russell 1000 Value Index and the 15.20% return for the S&P 500, while its 1.99% year-to-date return also lagged the Russell 1000 Value Index's 16.26% and the S&P 500's 10.21%. The Fund attributed the performance gap largely to limited exposure to the AI infrastructure spending boom, noting that the U.S. has about 4,000 existing data centers and nearly 3,000 more planned or under construction, while AI-related demand has created bottlenecks in processors and memory. The letter highlighted the scale of the cycle, with industry cash flows in key AI hardware areas rising sharply, while the Russell 1000 Value Index's top 10 contributors gained an average 182% year to date and accounted for 9.29 percentage points of the index's 16.23% return. Looking ahead, the fund expects investors to eventually reassess the sustainability of current AI infrastructure earnings and valuations. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like Corteva, Inc. (NYSE:CTVA). Corteva, Inc. (NYSE:CTVA) provides advanced seeds, crop protection products, and agricultural technologies designed to improve farm productivity and resilience. The one-month return of Corteva, Inc. (NYSE:CTVA) was 4.69% while its shares traded between $60.54 and $90.97 over the last 52 weeks. On August 27, 2026, Corteva, Inc. (NYSE:CTVA) stock closed at approximately $82.88 per share, with a market capitalization of about $54.98 billion.
Aristotle Value Equity Fund stated the following regarding Corteva, Inc. (NYSE:CTVA) in its Q2 2026 investor letter:
Corteva, Inc. (NYSE:CTVA), the seed and crop protection company, was one of the largest detractors during the period. While fundamentals remained healthy, with first-quarter FREE cash flow supported by strength in both Seed and Crop Protection, the stock lagged a sharply rising market as investors focused on Corteva's more tempered outlook for the balance of the year. The management team cited potential second-half headwinds from tariffs, higher oil-related input costs, farmer fuel expenses, and competitive crop protection pricing in Latin America and Asia. We believe the market also weighed the near-term complexity of Corteva's planned fourth-quarter separation into New Corteva and Vylor, including potential dis-synergies from operating two public companies. Nevertheless, our investment thesis remains intact. Farmers continue to adopt Corteva's latest hybrids, varieties, and premium crop protection technologies, supporting Corteva's margin expansion. Meanwhile, the company's R&D-led innovation, disciplined cost management, and path toward net royalty income sho

2 months ago
On August 20, ATRenew (NYSE:RERE) reported second-quarter results that beat the high end of its own guidance, with revenue climbing 32.4% year over year to RMB 6.6 billion. Net income jumped 78.6% to RMB 129.1 million, and the company kept buying back shares even as it pushed into new markets overseas. For a business built on other people's used phones, that pairing of faster growth and faster profit is the number worth sitting with.
The engine behind that growth is ATRenew's 1P model, where the company buys, refurbishes, and resells devices itself rather than just running a marketplace. Net product revenue rose 35.9% to RMB 6.2 billion, and the company moved 11.6 million consumer products during the quarter, up from 10.3 million a year earlier. Owning more of that chain is also making each device more profitable. Gross margin on the 1P business rose to 15.7% from 13.2% a year ago, and 1P-to-C retail revenue, the curated resale of phones and computers, grew 92.4% and now makes up 48.8% of product revenue, up from 34.4% last year. Revenue from refurbished products alone grew 87.8%.
All of that flowed to the bottom line: non-GAAP operating income rose 70.1% to RMB 206.3 million, with margin expanding 69 basis points to 3.1%. Newer categories are following the same pattern. Luxury recycling revenue grew 77.3% after the company upgraded select stores into specialized formats, and its B2B marketplace, PJT, grew its registered merchant base to 2.2 million while lifting inspection penetration to 84.4%, up 11.5 percentage points from a year ago. Overseas, the company crossed HKD 120 million in monthly export sales in June and is now building out its FoneSquare and ReRe brands toward hubs in Hong Kong, Dubai, and Miami.
Not every part of the business is pulling in the same direction. Net service revenue fell 4.2% to RMB 414.6 million, a decline the company tied to discretionary discounts handed to merchants during its extended June 18 promotional push. Gold recycling revenue fell even harder, down 35%, as gold prices swung lower and the company chose to pass higher payouts to users rather than protect its own take. Costs are climbing too. Fulfillment expenses rose 31.1% to RMB 540 million as the company staffed up its to-door recycling teams during peak demand.
Physical footprint is also shrinking at the edges, with the company trimming its AHS store count to 2,117 locations by closing underperforming sites. And management flagged a timing risk heading into the back half of the year, noting that expectations around Apple's next iPhone lineup could push device volume into the fourth quarter and early next year rather than this one. Guidance itself points to a slower pace ahead. ATRenew expects third-quarter revenue of RMB 6.3 billion to RMB 6.4 billion, growth of 23.1% to 25.1%, a clear step down from the 32.4% posted this quarter.
#billion #business

2 months ago
Generating $3,100 a month in dividends requires $1.06M at a 3.5% yield, but only $372,000 at a 10% yield.
High-yield portfolios often erode principal over time, while a 3.5% dividend growing 8% annually doubles income in just nine years.
Barbelling dividend-growth stocks with a monthly payer like O targets a ~4% blended yield, requiring roughly $930,000 in capital.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Replacing $3,100 a month in dividend income means generating $37,200 a year from a portfolio you build yourself. That number lands between a Social Security supplement and a modest salary replacement, and hitting it is a math problem before it is an investing problem. Divide the income target by the yield your portfolio earns, and you get the capital required. This piece walks through what that capital looks like at three yield tiers, using dividend-payer examples from the current market, and explains why the highest yield rarely produces the best long-term result.
#best
2 months ago
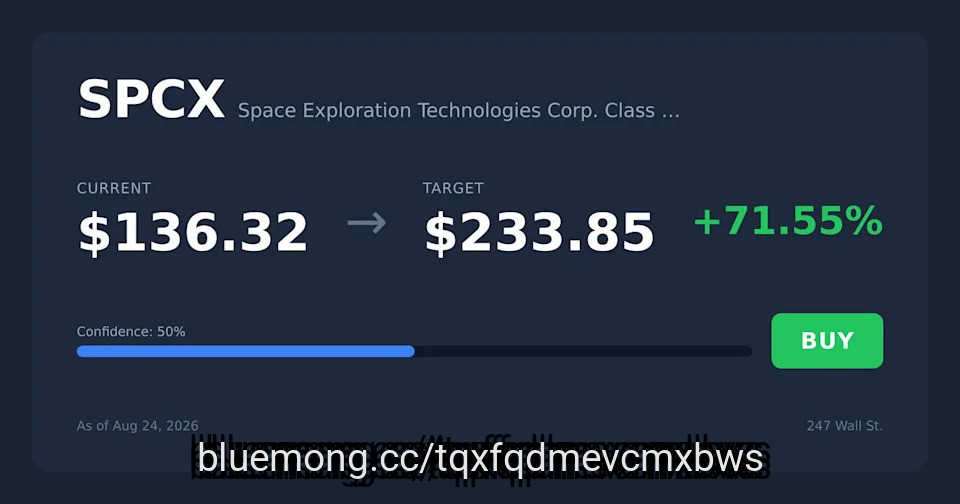
Musk accelerated **** eX's (SPCX) orbital data center launch to Q4 2027, and JPMorgan held its $240 price target, implying roughly 75% upside from current levels.
NVIDIA (NVDA) reports Wednesday, and **** e peers like RKLB sitting out the rally confirm **** eX's surge is a targeted AI-compute repricing, not a sector rotation.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
SpaceX (NASDAQ:SPCX) stock is up 3% to $139.06 midday Tuesday, breaking from a lukewarm **** e complex that hasn't followed the move. The Procure **** e ETF (NASDAQ:UFO) is up 0.1% to $44.71, well behind the single-name headline **** eX is driving in the sector. Meanwhile, the Invesco QQQ Trust (NASDAQ:QQQ) is up 0.64% to $710.82, a broad-tape backdrop that hardly explains the outsized single-name pop.
The catalyst is twofold. **** eX Founder Elon Musk posted on X Monday afternoon that his company has designed a **** e-optimized Vera Rubin NVL72 system for launch to orbit in Q4 next year, pulling its first orbital data center milestone forward from a previously stated 2028 target. JPMorgan **** yst Doug Anmuth followed Tuesday with a maintained Overweight rating and a $240 price target on **** eX stock, implying substantial upside from current levels.
#NASDAQ #target #NVIDIA #tuesday

2 months ago
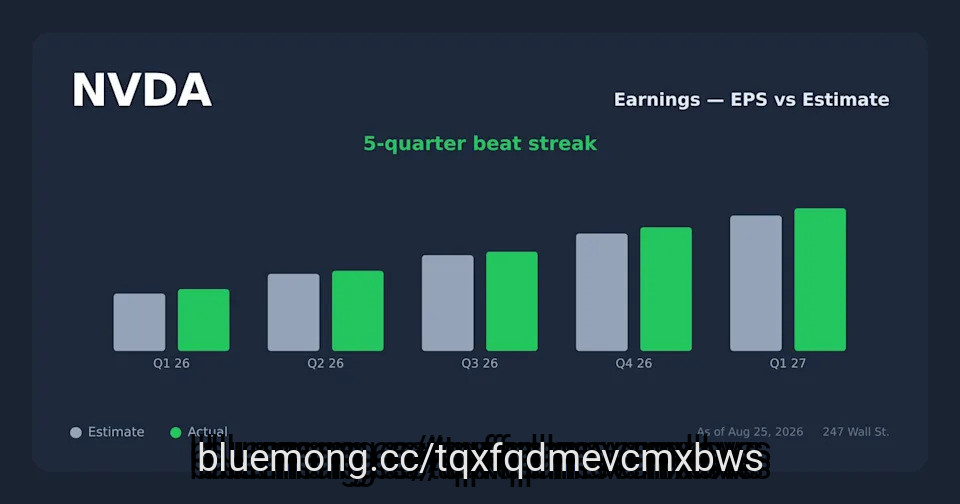
Nvidia (NASDAQ: NVDA) stock has been a disappointment for some investors in 2026. The stock price is up 15%, which is beating the broader market's 12% rise, but it isn't outperforming the way it has in the previous three years. In 2026, Nvidia has reported strong results so far that suggest the growth thesis continues, yet the market has grown skeptical.
This makes now a great time to consider buying. Just know that the window could be closing fast. On Wednesday, Aug. 26, Nvidia reports fiscal 2027 second-quarter results (for the quarter ending July 30). Because Nvidia is valued at an attractive level heading into earnings, this could be the last chance investors have to buy the stock cheaply, as there is a good shot the stock experiences a strong, significant rally following the report.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Given its continued stellar growth rate and reasonable valuation, I can think of few stocks that are better buys. All of that could change depending on the quality of Nvidia's earnings and the market's reaction afterward.
Nvidia makes computing equipment, with most of its products centered around its GPU ecosystem. Nvidia GPUs are the industry standard in AI computing right now, and nearly every product that launches is compared to theirs. So, checking Nvidia's valuation versus its competitors is a smart move.
#signal #investors #makes


2 months ago
NVDA posts 85% revenue growth at a forward PEG of just 0.605, supporting a $270.26 price target and a high-conviction BUY recommendation.
AVGO typically trades at a richer forward multiple than NVDA's 25x despite being a supplier, making NVDA's valuation look conservative against its own peer group.
Even the bear case projects an 8.2% gain, backed by 75% gross margins and $49 billion in quarterly free cash flow.
Don't wait: the ****** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
NVIDIA (NASDAQ:NVDA) trades at $215.17 as of Friday afternoon. After running the numbers, the stock looks reasonably priced relative to its growth.
#nvda #Growth #trades