3 days ago
Jim Carrey may have just married Min Ah, but there's another special woman in his life — his only daughter, Jane Erin.
The star has kept his bond with his child out of the spotlight, but previously credited her for being one of the most important people in his life.
Here's what we know about the actor's offspring and the role she has played in his life.
Jane supported Jim during his hand and footprints cement ceremony on November 2, 1995 (@ Getty Images)
Jane was born to Jim and his ex-wife, Melissa Womer, in 1987. It was a whirlwind romance for Jim and Melissa who met at a comedy store. Jane was welcomed by the couple after they'd been married for six months.
#melissa #married #womer


14 days ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management

15 days ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic


15 days ago
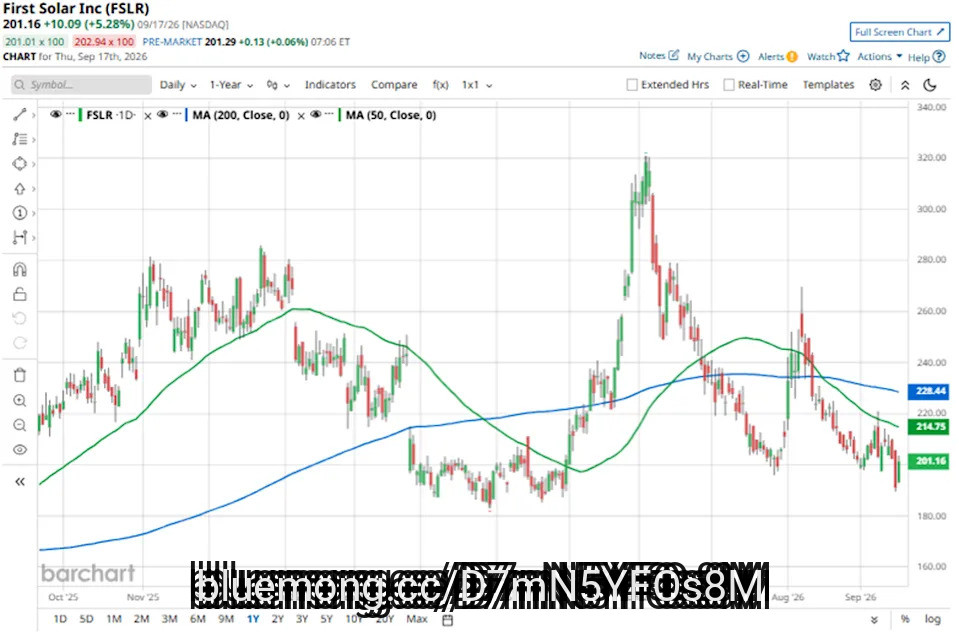
Tempe, Arizona-based First Solar, Inc. (FSLR) is a leading photovoltaic (PV) solar technology and manufacturing company. The company develops and manufactures solar modules using its proprietary thin-film semiconductor technology, offering an alternative to conventional crystalline silicon PV modules. First Solar operates a global manufacturing network spanning the United States, India, Malaysia, and Vietnam. With a market cap of $21.6 billion, the company is one of the largest solar manufacturers.
Companies worth $10 billion or more are generally described as "large-cap stocks," and First Solar fits this description. The company is also one of the few major solar manufacturers with a significant U.S. manufacturing footprint, positioning it to benefit from domestic-content incentives and the broader push to expand U.S. solar manufacturing capacity. First Solar ended the second quarter with a contracted sales backlog of approximately 45.1 GW extending through 2030.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Solar #first #billion #tempe

16 days ago
On September 4, RTX Corporation (NYSE:RTX) announced that its Pratt & Whitney business was investing $25 million to expand its manufacturing facility in Niepołomice, Poland.
The site produces complex tubular ****** emblies for both military and commercial engines. The expanded facility will begin operations in 2028 and create over 120 jobs.
Niepołomice already delivers precision components for several engines, including the F135, Pratt & Whitney GTF, and the PW800. The initiative complements the $100 million investment announced in April to boost production and enhance capabilities at the company's facility in Rzeszów, Poland.
The capacity expansion reflects the company's confidence in sustained demand for both commercial and military engine production over the coming years, which is supported by a record backlog of $289 billion at the end of Q2, increasing 22% year-over-year.
This further strengthens RTX Corporation (NYSE:RTX)'s manufacturing footprint in Europe, especially in Poland – which is already the company's largest presence outside the U.S. with more than 9,500 employees. The expansion will enhance its regional supply chain capabilities.
#Manufacturing
16 days ago
On September 9, 2026, Reuters reported that U.S. Transportation Secretary Sean Duffy sent a letter to Ford Motor Company (NYSE:F) CEO Jim Farley criticizing the automaker's business relationships with Chinese battery maker CATL and Chinese automakers Geely and BYD as raising "profound concern."
It specifically flagged Ford's licensed CATL battery technology at its Marshall, Michigan plant, its joint venture with Geely in Spain, and its decision not to move Lincoln Nautilus production out of China until 2030. Ford responded that Duffy's letter was "a wrongheaded attempt to capture headlines," noting that it owns the Marshall plant, controls its operations, and employs the workforce there, unlike companies that simply import Chinese-made batteries.
Ford Motor Company (NYSE:F) can argue that its CATL partnership still solidifies U.S. battery manufacturing rather than becoming more dependent on Chinese imports. Ford owns and operates its Marshall, Michigan battery plant. It allows the company to manufacture batteries domestically while licensing CATL technology. That structure could help Ford expand its U.S. EV production capacity and reduce the need to import finished Chinese battery packs.
Ford's improving financial performance gives the firm more flexibility to manage the political pressure. The automaker raised its full-year adjusted EBIT guidance to $10 billion-$11 billion after second-quarter results exceeded expectations, with record Bronco sales and a stronger product mix supporting the improvement. Stronger operating earnings could give Ford more resources to adjust its battery strategy if policymakers impose more restrictions on Chinese technology.
The company's existing U.S. manufacturing footprint could become a competitive advantage if Washington tightens restrictions on Chinese automotive technology. Ford has already invested in domestic battery production instead of relying entirely on imported battery packs. Model e losses have narrowed for three consecutive quarters. If policymakers force automakers to cut Chinese supply-chain reliance, Ford can use its existing U.S. factories to adapt faster than rivals that depend heavily on Chinese parts.
#ford #catl #motor

16 days ago
Comments from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman calling for a more measured approach to frontier AI development contributed to a sharp selloff across neoclouds and data center stocks. Bernstein identified CoreWeave Inc. (NASDAQ:CRWV) as the most exposed name because of its rural footprint and focus on AI training. The concern represents a genuine structural argument. However, it marks the second time this year that the same group of stocks has faced concerns over the sustainability of AI demand. There is also an important tension within Bernstein's own note, which highlights CoreWeave's exposure while acknowledging that most of its backlog remains shielded by contracts.
Bernstein cautioned that a slowdown in AI training could weigh on data center developers. The warning followed Amodei's weekend comments urging the industry to deliberately slow the pace of frontier AI capability gains, along with similar remarks from Sam Altman. According to ****** yst Madison Rezaei, slower training activity would likely reduce demand for rural data center sites designed for latency-insensitive workloads. The ****** yst pointed out that rural and Tier 3 markets account for 70% of the industry's 488GW pipeline. CoreWeave was identified as the most exposed name in the firm's coverage. ****** yst Madison Rezaei remarked:
We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets.
However, there is a key counterpoint within Bernstein's own note:
The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there but could see a pullback in demand for the contracted-not-yet-sold rural power if training development slows.
#training #analyst
16 days ago
Generac Holdings (GNRC) shares ripped higher on Sept. 17 after management announced a multi-billion-dollar commercial partnership with Amazon (AMZN). In its press release, GNRC said its pivotal supply agreement with the cloud and e-commerce giant is designed to furnish backup power solutions for its expanding data center footprint.
The AMZN news brings much-needed reprieve to Generac stock that was otherwise down roughly 40% versus its year-to-date high in late June.
Why It's Time to Load Up on Nvidia Stock
ORCL Stock Layoffs: What to Know About the Latest Oracle Job Cuts
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#amzn #holdings #load


18 days ago
Dallas, Texas-based CBRE Group, Inc. (CBRE) operates as a commercial real estate services and investment company. Valued at $40.8 billion by market cap, the company offers property management, valuation, real estate investment, and advisory services. CBRE operates offices, data centers, multi-family, hotels, gaming, and retail sectors.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CBRE perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the real estate services industry. CBRE dominates commercial real estate through unmatched global scale, deep end-to-end advisory services, and a massive operational footprint that creates powerful data network effects.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#estate



18 days ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#Solar


18 days ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

18 days ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#project #next

18 days ago
Dallas, Texas-based CBRE Group, Inc. (CBRE) operates as a commercial real estate services and investment company. Valued at $40.8 billion by market cap, the company offers property management, valuation, real estate investment, and advisory services. CBRE operates offices, data centers, multi-family, hotels, gaming, and retail sectors.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CBRE perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the real estate services industry. CBRE dominates commercial real estate through unmatched global scale, deep end-to-end advisory services, and a massive operational footprint that creates powerful data network effects.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#estate #investment


18 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Vishay Precision Group, Inc. (NYSE:VPG). Headquartered in Malvern, Pennsylvania, Vishay Precision Group, Inc. (NYSE:VPG) specializes in precision measurement and sensing technologies. On September 14, 2026, Vishay Precision Group, Inc. (NYSE:VPG) closed at $60.49 per share. Over the past month, Vishay Precision Group, Inc. (NYSE:VPG) declined 10.77%, while its shares gained 85.95% over the past 52 weeks. Vishay Precision Group, Inc. (NYSE:VPG) has a market capitalization of $805.75 million, and its shares traded within a 52-week range of $28.71 and $151.78.
Prosper Stars & Stripes stated the following regarding Vishay Precision Group, Inc. (NYSE:VPG) in its Q2 2026 investor letter:
"Vishay Precision Group, Inc. (NYSE:VPG) was the largest contributor to our long book during the second quarter of 2026. Vishay's core technologies, bulk metal foil resistors and bonded foil strain gauges, are niche, designed-in sensor solutions embedded in precision instruments, such as semiconductor test equipment and aerospace, medical, military, and robotics applications. Vishay has done a lot of work during the industrial downturn to improve its footprint to have more profitable growth as the industrial economy recovers after years of tepid performance. In addition, Vishay is pursuing a substantial secular growth opportunity in humanoid robotics, with $500 to $1,200 in content per robot. Management is executing on both sides of the ledger: cutting costs while strengthening the leadership bench with new Chief Operating Officer and Chief Product Officer roles. Together, these initiatives are expected to lift gross margins and EBITDA margins from 39% and 8% in 2025 toward long-term targets of 46% and 20% over the next several years. We reduced and then exited our position in Vishay during the quarter but still see good value in th
18 days ago
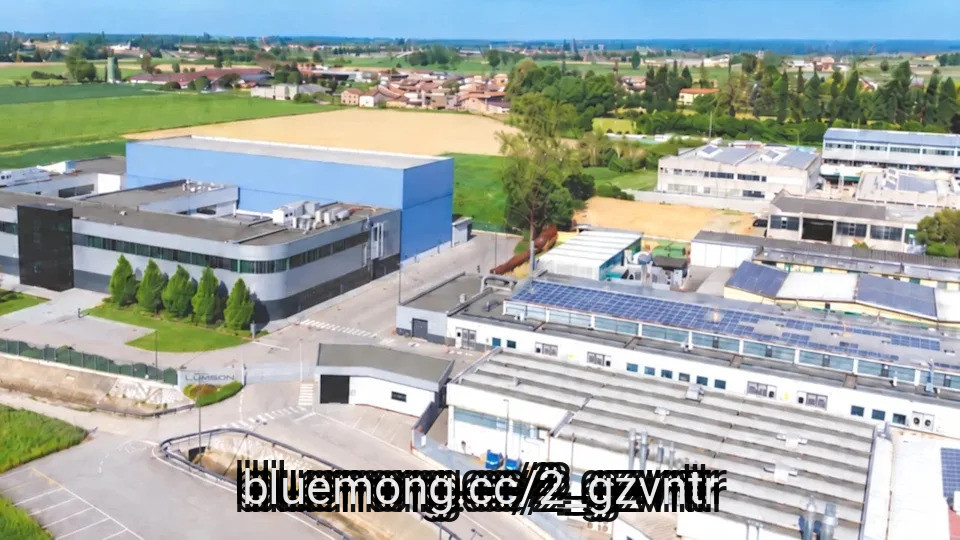
Lumson has purchased Lombardi Design and Manufacturing in the US, along with full ownership of Lombardi Design & MFG in Asia.
Financial terms of the deals remain undisclosed.
The deals form part of Lumson's wider international expansion plan and are intended to add to its industrial and technological capacity while extending its reach in primary packaging for the beauty and personal care sector.
With the two transactions, Lumson has a direct presence in Europe, North America and Asia.
The broader footprint will support work with international clients, help build industrial and commercial ties across markets, and open access to regions.
#financial #Europe

20 days ago
Following an impressive second quarter FY27, Navan Inc. (NASDAQ:NAVN) announced its acquisition of BoomPop, an AI-powered meetings and events platform that has been recognized by Inc. as one of the fastest-growing private companies in America. Launched in 2023, BoomPop offers end-to-end event management solutions to enterprises, by leveraging artificial intelligence capabilities. Its offerings cover the entire spectrum of event management procedures including venue selection, vendor sourcing, contractual agreement, payments, and more. For Navan, this deal build on an existing alliance between the two entities, which was announced earlier in February. It marks the company's strategic push to expand its footprint across the meetings and events segment, where a large chunk of the spending is still done outside managed platforms.
LStockStudio/Shutterstock.com
The BoomPop acquisition follows a persistent enterprise market momentum reported by the company in its second quarter results, allowing Navan to enter into collaborative agreements with several leading companies during the quarter. These included Enbridge, Ingersoll Rand, ****** mins, and Evotec. Navan also concluded the deal to acquire Smartrips, a well-reputed travel management business, with the aim of bolstering its presence across a rapidly-growing Latin American market.
Notably, Navan registered adjusted net income of $14 million during the second quarter compared to an $8 million loss in Q2 FY26. It came at the back of year-over-year growth figures of 39% and 35% for subscription revenue and usage revenue, respectively.
Through full integration of BoomPop's staff and technology, Navan intends to expand its current meetings and events operations, accelerate its product development timeline, and satisfy growing customer interest. The company aims to deliver a more seamless experience covering travel, expense, meetings, and events.
#navan

20 days ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
20 days ago
Walmart (WMT) recently took another step into restaurant delivery, announcing a national partnership with Inspire Brands that puts it more directly in competition with DoorDash (DASH) and Uber Technologies' (UBER) Uber Eats. But the expansion announced recently is still largely limited to restaurants operating as tenants inside Walmart stores, where the logistics are considerably easier to manage. The bigger question is what happens when the company moves beyond these in-store tenants and takes on the more difficult parts of the restaurant delivery market. Until then, the current expansion says more about Walmart's ambition than its ability to become a structural competitor to the established players.
Walmart is expanding its restaurant delivery strategy through a new collaboration with Inspire Brands, whose portfolio includes Arby's, Jimmy John's, Dunkin, Baskin-Robbins, and Sonic. The partnership will bring restaurant delivery into Walmart's app. Dunkin' will be the first brand to launch, starting with 150 in-store tenant locations. Walmart and Dunkin' then plan to expand the offering to most of Dunkin's roughly 10,000 U.S. restaurants, including locations outside Walmart's stores. The broader opportunity is built around Walmart's existing physical footprint. A customer could place a restaurant order alongside a Walmart purchase and receive both through the same delivery. The retail giant says its footprint is located within 10 miles of about 90% of the U.S. population.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#uber #Stock #inspire #launch

20 days ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


20 days ago
CHATTANOOGA, Tenn. — Kenco opened a 30,000-square-foot Innovation Lab on Sept. 10, tripling a testing footprint the third-party logistics provider first built in 2015.
The larger facility allows Kenco to run warehouse automation testing on larger and more complex systems. It also allows more of those systems to run side by side. Testing takes place inside a building designed to mirror real-world warehouse conditions so results carry over to a live distribution center.
Ainsley Williams, vice president of automation and innovation at Kenco, described the expansion as benefiting both manufacturers and customers.
"The Innovation Lab has long stood as the convergence point for leading technologies and real-world applications, helping both manufacturers and customers identify and realize what's possible," Williams said. "By tripling our innovation footprint, we can further provide a ***** e for OEMs to continue experimenting with their products in a real environment and for customers to explore product and value without having to invest in them."
The original lab was created to help the company understand how emerging technologies such as automation would affect its operations.
#real #customers #larger

22 days ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
23 days ago
Nucor Corporation (NUE) is the largest steel producer and recycler in the U.S., with operations spanning steel mills, steel products, and raw materials. Headquartered in Charlotte, North Carolina, the company produces a broad range of steel, from sheet and structural steel to joists, girders, and tubing, serving critical end markets such as construction, infrastructure, manufacturing, and energy.
With a market capitalization of $58.2 billion, NUE firmly sits in the large-cap category, reflecting its scale, industry influence, and leadership within the U.S. steel sector. Unlike traditional blast-furnace producers, Nucor primarily uses scrap-based electric arc furnaces (EAFs), giving it greater production flexibility and a comparatively lower environmental footprint.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for **** e
#steel #north


23 days ago
Casey's General Stores Inc. (NASDAQ:CASY), the third-largest convenience chain and fifth-biggest pizza brand within the U.S., released its first quarter results, showing early traction from the company's recently announced three-year strategic plan. For the recent quarter, inside same-store sales jumped 3.2% year-over-year, and 7.7% on a two-year stacked basis, leading to inside margins of 42.2%. Total inside gross profit stood at $749.8 million, rising 6.3% compared to the same period last year. The company posted net income of $273.7 million, exhibiting a 27.1% increase relative to Q1 last year. This translated into a 27.7% jump in diluted EPS which rose to $7.37.
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest

23 days ago
Apple Inc. (NASDAQ:AAPL) and Intel Corporation (NASDAQ:INTC) represent two sides of a historical silicon transition. A September 2 report from MacRumors highlighted a key milestone: Apple notified developers that universal Mac App Store apps requiring macOS 13 or later can now drop support for Intel-based Macs. Removing Intel binary slices simplifies app development and reduces download sizes. While symbolic, the move underscores Apple's completed transition to Apple Silicon and highlights Intel's diminishing footprint within Apple's high-margin ecosystem.
Financially, Apple is faring significantly better than Intel.
For Q3 2026 (ended June 27, 2026), Apple reported record quarterly revenue of $109.4 billion, up 16% year-over-year, driven by double-digit growth across iPhone, Mac, and Services. The company's gross margin reached 50.1%, supported by a 2 percentage point favorable impact from tariff refunds. Diluted earnings per share (EPS) surged 29% year-over-year to $2.02, which included a $0.11 favorable boost from tariff refunds. Operating cash flow and active installed base both set new June quarter records.
Intel's Q2 2026 financial results (ended June 27, 2026) delivered $16.1 billion in quarterly revenue, up 25% year-over-year, marking its fastest top-line growth in over 15 years. Intel reported a GAAP net loss of $11.0 billion (GAAP EPS of -$2.16), largely driven by non-cash charges and mark-to-market adjustments. However, on a non-GAAP basis, net income reached $2.2 billion ($0.42 diluted EPS), nearly doubling consensus expectations. Non-GAAP gross margin expanded to 41.8% (40.4% GAAP) on strong product mix and factory yields.
Apple's bull case centers on expanding Services margins, strong ecosystem lock-in, and the potential for Apple Intelligence to drive further demand and engagement across iOS and macOS devices, supporting high-margin growth. On the other hand, Apple faces risks from elevated valuation multiples, sluggish growth in Greater China, where Q3 revenue reached $14.7 billion, and ongoing global antitrust scrutiny over App Store fees.
#revenue

23 days ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
23 days ago
Chinese e-commerce giants such as Shein and Temu have reshaped the retail landscape amid economic uncertainty, higher prices, and cautious consumer spending by offering shoppers a wide range of products at extremely low prices.
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first

24 days ago
The artificial intelligence (AI) boom is fueling a nuclear renaissance. For the industry to grow, massive amounts of energy-intensive compute power will need to be built. As a low-carbon, high-baseload energy source, nuclear power is a promising solution.
NuScale Power (NYSE: SMR) is the only small modular reactor (SMR) developer in the U.S. approved by regulators to construct an SMR facility. SMRs are ideal for the AI data center build-out, given that they can be built more quickly and at a lower cost than conventional nuclear plants. This smaller footprint allows an SMR to be constructed near the data center infrastructure itself.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Despite growth potential, NuScale shares are down 40% this year. Skepticism is reasonable. Only two SMR systems currently exist worldwide. NuScale has never commercialized any of its SMR designs. Plus, the company already experienced a sizable failure in 2023 when its biggest customer (at the time) canceled its project.
While NuScale operates in an industry that should see long-term growth, the nuclear stock's future may hinge on a single upcoming catalyst.
#nuclear

24 days ago
Stanley Black & Decker, Inc. (NYSE:SWK) entered into a definitive agreement to sell Excel Industries to Bad Boy Mowers. Excel Industries, which includes the Hustler Turf Equipment brand, is expected to generate approximately $300 million of fiscal 2026 revenue.
The purchase price and expected proceeds were not disclosed. The transaction remains subject to regulatory approval and customary closing conditions. Until closing, Excel Industries will remain in continuing operations and will not be classified as a discontinued operation.
Stanley Black & Decker, Inc. (NYSE:SWK) does not expect the transaction to dilute adjusted EPS. Adjusted EPS is a company-defined non-GAAP measure calculated as diluted GAAP EPS excluding certain gains and charges, including divestiture-related items, restructuring, footprint actions, and gains or losses on business sales.
The sale advances the portfolio-simplification strategy of Stanley Black & Decker, Inc. (NYSE:SWK). Divesting a specialized turf-equipment platform could reduce complexity and concentrate investment on larger brands and markets.
Stanley Black & Decker, Inc. (NYSE:SWK) plans to continue investing in its Outdoor business, including electrical products and high-performance residential ride-on and zero-turn mowers. The remaining portfolio includes DEWALT, CRAFTSMAN, Cub Cadet, Troy-Bilt and BLACK+DECKER, providing established platforms for outdoor growth.
#black #industries
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
24 days ago
Bloom Energy (NYSE: BE), a developer of solid oxide fuel cells (SOFCs), has been one of the market's hottest growth stocks. Its shares surged more than 2,500% over the past two years, while its backlog swelled to $20 billion at the end of 2025. That's ten times the $2.0 billion in revenue it generated in 2025. ******* ysts expect its revenue to more than double to $4.1 billion this year, then grow 65% to $6.8 billion in 2027 and 46% to $9.9 billion in 2028.
That growth trajectory is impressive, but the recent introduction of its Power Connect system -- which could reduce its on-site installation time by more than 40% -- could help it exceed those bullish estimates. Let's see why this upgrade could matter more than the size of its backlog.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Bloom's SOFCs can convert natural gas, biogas, propane, and hydrogen into electricity without any combustion. Its systems can also be deployed on-site in less than three months and bypass traditional electrical grids, which can require years to set up new connections.
Those advantages make SOFC systems a popular choice for data centers seeking to quickly expand their cloud and AI infrastructure while maintaining a smaller carbon footprint. Oracle, CoreWeave, Nebius, Equinix, and other data center giants already use its SOFC systems. Brookfield ******* et Management (NYSE: BAM), one of the world's largest ******* et managers, funds Bloom's development and deployment of those SOFC systems via a $25 billion partnership.
#systems #signal #years #sofcs
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

26 days ago
A mall chain many consumers around the United States grew up visiting has closed another 25 stores over the last three months.
Earlier this year, we saw a number of mall retailers close locations, despite July 2026 Placer.ai data revealing that foot traffic across all three mall formats grew year over year. As part of my retail coverage for TheStreet, I reported on Vera Bradley cutting its traditional mall footprint by more than 43%, and Fossil Group quietly closing 219 stores over five years.
Most retailers choosing not to renew their mall leases are shifting their strategies. Some are pivoting to open-air shopping centers, which have been outperforming traditional malls for a while, while others are responding to changing consumer preferences by investing more in their online presence.
Founded in 1924, Genesco is a footwear-first company and the engine behind popular brands focused on kids, teens, and young adults. These include Little Burgundy, Journeys, and Schuh.
Genesco has closed another 25 stores across its portfolio, including 17 Journeys Group locations, in the second quarter of fiscal 2027, according to the company's latest earnings release.
#stores #retailers