12 days ago
First Phosphate Corp. (CSE:PHOS, NASDAQ:PHOS, FRA:KD0, OTCQX:FRSPF) earlier this week highlighted Swiss government support for financing linked to its Bégin-Lamarche mine, as CEO John Passalacqua outlined the company's efforts to ***** emble a capital stack designed to limit shareholder dilution.
Proactive: Really big news out from the company today. It really jumps off the page: a guarantee of $212.5 million for CapEx for First Phosphate, coming from the Swiss government. Tell me a little bit about this, John.
John Passalacqua: Yeah, so this is the Swiss government that's guaranteeing up to 85% of exports from Switzerland that are aimed towards the mine at Bégin-Lamarche. So you've got a very nice debt-to-equity ratio there. 85% is almost unheard of in the industry. And it's obviously based on the credibility of the mine, based on the fact that we've been endorsed by the G7, based on the fact that we have other export credit agencies at the table.
EIFO from Denmark was there already, if you remember, for €170 million. So little by little, we're putting together the whole capital stack here for the project, which can be done quite non-dilutively.
And that's a key to this because they're looking at about 85% of the cost, and potentially more if that happens. But it does get to the point where your shareholders are very well protected here.
#john #government #little #first

14 days ago
Lam Research Corporation (NASDAQ: LRCX) stock has struggled recently, shedding 16.6% in the last week alone. The shares have seen some volatility since their April-June rally peaked at a June 30 record high of $438.50. LRCX was last seen down 2.3% at $267.22 today, though it still boasts a roughly 56% year-to-date lead. Plus, the recent pullback has found support at the 200-day moving average, a trendline with historically bullish implications.
Per Schaeffer's Senior Quantitative ***** yst Rocky White, LRCX has traded within 0.75 times the 200-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred five other times over the last decade, after which the stock was higher one month later 80% of the time, averaging a 6.9% gain.
Furthermore, LRCX's 14-day Relative Strength Index (RSI) of 28.7 sits in "oversold" territory, which often precedes a short-term bounce.
#Stock #Research

16 days ago
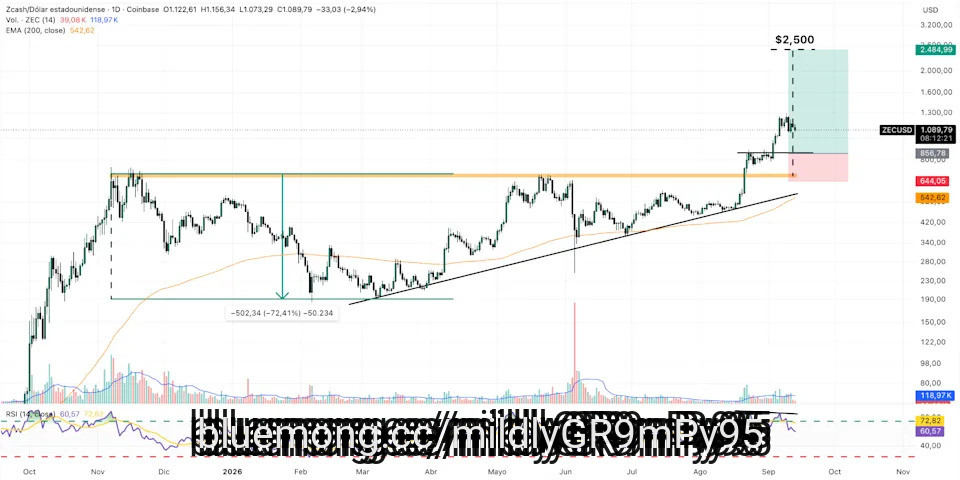
Zcash (ZEC) has dropped by nearly 6% in the past 7 days following a massive rally that pushed the token to its highest levels in a decade.
Trading volumes remain quite high at $1.4 billion, accounting for over 7% of the ******* et's circulating market cap.
The price hit a strong sell wall at $1,300 as macroeconomic conditions in the United States deteriorated.
A stable inflation print on Friday kickstarted a short-lived rally across crypto ******* ets but quickly faded, as odds of a rate hike during the next FOMC meeting rose to nearly 90%.
The Federal Open Market Committee (FOMC) is expected to convene on September 16. Comments from the new Chairman of the central bank, Kevin Warsh, will be scrutinized to get a sense of how the institution plans to curb inflation.
#inflation #zcash #trading #states

24 days ago
On August 5, Clear Secure (NYSE:YOU) reported second-quarter results that hit almost every mark investors watch: revenue, bookings, margins, and cash flow all moved in the right direction. The company even raised its full-year free cash flow target. But buried in its own forecast for the current quarter is a hint that the breakneck growth pace investors have gotten used to may be starting to ease.
Clear's core numbers left little to complain about. Revenue reached $277.8 million in the quarter, up 26.6% from a year earlier, while Total Bookings climbed 32.8% to $295.9 million, a figure management treats as a leading indicator of where revenue is headed next. That growth came from a membership base that keeps expanding: Total CLEAR Members hit 43.5 million as of June 30, up 30% year over year, and Active CLEAR+ subscribers reached 8.3 million, up 15.2%. The company also kept widening its physical footprint, launching CLEAR+ lanes in Northwest Arkansas and Indianapolis during the quarter to bring its airport count to 62, alongside 280 retail locations offering TSA PreCheck enrollment. Its newer eGates technology is now live in 50 airports as of August 5, with a network-wide rollout still targeted for later this year, and its premium Concierge service has expanded to 39 airports.
Profitability climbed even faster than revenue. Operating income hit $83 million, a 29.9% margin, while Adjusted EBITDA reached $101.1 million at a 36.4% margin, an expansion of 900 basis points from a year ago that pushed the company past its own 35% long-term target. Free cash flow of $189 million for the quarter gave management enough confidence to raise its full-year free cash flow guidance to at least $480 million, up from a prior floor of $465 million, implying growth of at least 39.9% for the year. The board also declared a quarterly dividend of $0.15 per share, payable September 24 to shareholders of record as of September 10 on top of $22.2 million already returned to shareholders during the quarter.
The tension in this story sits in Clear's own forecast. After growing bookings 32.8% and revenue 26.6% in the second quarter, the company's third quarter guidance calls for meaningfully less: revenue growth of 24.6% at the midpoint and bookings growth of just 20.5%. That is a real step down from what the business just delivered, and it comes directly from management rather than outside speculation. The capital return picture has shifted too.
#quarter #year #Growth
28 days ago
Interested in MongoDB, Inc.? Here are five stocks we like better.
MongoDB's fiscal Q2 2027 revenue rose 30% to $772 million, driven by accelerating Atlas cloud database and Enterprise Advanced demand. The company added a record 2,900 customers, reaching 70,600 total customers, while its non-GAAP operating margin expanded to 24%.
AI adoption is gaining momentum through Atlas Vector Search, Voyage AI models and the company's managed Model Context Protocol server. Management said the strongest demand is coming from production-scale, customer-facing applications, although AI remains a relatively small contributor today.
MongoDB raised its fiscal 2027 outlook to $2.99 billion–$3.03 billion in revenue and increased its Atlas growth and operating-margin expectations. Enterprise Advanced revenue grew 36% year over year and is becoming a more durable growth driver alongside Atlas.
5 Stocks to Buy in September Before Wall Street Catches On
#mongodb #advanced #customers
30 days ago
On August 4, Archer-Daniels-Midland (NYSE:ADM) executives told investors on an earnings call that the company would expand capacity at four US oilseed-crushing plants, a roughly $100 million push into a business that just posted its strongest quarter in years. The plants sit in Frankfort, Indiana; Deerfield, Missouri; Lincoln, Nebraska; and Spiritwood, North Dakota, the last a joint venture with Marathon Petroleum. Together, the upgrades are expected to add about 700,000 metric tons of crush capacity by 2028 or 2029, and six more sites have already been flagged for possible future growth.
CEO Juan Luciano framed the projects as a cheap way to add output, estimating the cost at roughly a quarter of what a brand-new facility would require. That math matters because ADM just reported second-quarter adjusted earnings per share of $1.84, well above the $1.44 ***** ysts expected, and raised its full-year 2026 adjusted EPS guidance to a range of $5.15 to $5.60 from a prior $4.15 to $4.70. Operating profit in the ag services and oilseeds segment, ADM's largest, jumped 129% year over year to $867 million, with the crushing subsegment alone up $330 million as oilseed volumes climbed about 5%.
The company has now identified 10 US soy processing plants for potential expansion in total, and Luciano said top buyer China appears on track to meet its commitment to purchase 25 million metric tons of US soybeans this year. Nutrition, long a laggard, also grew 51% to $172 million on strength in flavors. Even so, Luciano described the crushing expansion as a "phased approach to allow for offramps," language that suggests management wants room to pull back if the current environment does not hold. The projects are expected to fit inside ADM's existing 2026 capital expenditure range of $1.3 billion to $1.5 billion, following expansions at two Brazilian plants last year and an extension completed this year in Uberlandia.
The strength behind these numbers leans heavily on conditions ADM does not control. Finalized 2026 and 2027 renewable volume obligations under the US Renewable Fuel Standard, locked in only this past March, are doing much of the work behind crushing margins, alongside energy prices that climbed after the Iran war. Roughly $100 million of the ag services and oilseeds profit came from net positive mark-to-market and timing impacts, gains tied to commodity pricing swings rather than the underlying business.
Not every part of the portfolio moved in the same direction. The refined products and other subsegment posted a 3% profit decline on negative mark-to-market impacts and supply and demand imbalances in South America, and equity earnings from ADM's stake in Wilmar fell 22%. Those soft spots, paired with a crush expansion built with explicit offramps, hint that management sees more uncertainty in the setup than the headline guidance raise suggests.
#luciano #quarter #expected
1 month ago
Nvidia risks a 20% drop to $165 if it misses earnings, with virtually no margin for error built into its current stock price.
Customers Microsoft and Meta are building competing AI chips, threatening the near-monopoly behind Nvidia's $91 billion quarterly revenue forecast.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
How low can a stock go if it misses earnings? Well, look at its 52-week low. If that happens to Nvidia (NASDAQ: NVDA), the stock would drop 20% to $165, where it was in late March. That was when AI suddenly fell out of vogue amid worries it wasn't the greatest invention of all time.
Oracle(NYSE: ORCL) missed earnings, dropping more than half, but it is considered the weakest of the large tech companies. IBM (NYSE: IBM) fell 20% on a miss, but it is a third-tier company. Before Meta (NASDAQ: META) posted poor results, it fell 20% and is down over 25% for the year.
#NVIDIA #Microsoft #NYSE

1 month ago
With great certainty, I can say there will be a bear market. What I can't tell you is when, though I expect one sooner than later. Right now, with the market trading near all-time highs, investors appear to be shrugging off a lot of bad news. Even JPMorgan Chase (NYSE: JPM) CEO Jamie Dimon has been offering warnings about the increasing risk of a downturn, so I'm not going out on a limb here. But if there is a bear market ahead, now or in a more distant future, the smartest investors prepare before the inevitable downturn.
I've lived through numerous bear markets, including the very deep dot-com crash and the Great Recession, when there were legitimate concerns about the stability of the global financial system. When stock prices fall day after day, week after week, month after month, and year after year, it is hard not to panic. You are watching your wealth slip away little by little and, at some point, you feel like you need to stop the bleeding before you lose it all.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
There are no free lunches on Wall Street, as the old saying goes. You have to take the good with the bad. And bear markets are part of that story, but, historically, they've always been followed by new bull markets. You may feel like the bleeding will never stop, but history says it will. And that the market will eventually post even higher highs.
So the big thing you need to do is remember the history, so you have the wherewithal not to panic and follow the crowd. A really simple approach is to buy a low-cost S&P 500 index fund, such as Vanguard S&P 500 ETF (NYSEMKT: VOO) and its 0.03% expense ratio, and just keep buying. Right through the downturn, as well, since you'll be able to buy more shares of the exchange-traded fund (ETF) while they are cheap. That's known as dollar-cost averaging, and it can be a very powerful wealth-creation tool.
#NVIDIA #right


1 month ago
The Treasury General Account ballooned to $950 billion. Nearly double Biden's $550-$600 billion target. Giving Bessent firepower to fund expanded bond buybacks.
Treasury doubled its long-bond buyback program to at least $4 billion, sending the 30-year yield to 5.23%, a level not seen since 2007.
Draining the TGA creates a thinner debt-ceiling cushion, estimated around winter or early spring, and restoring it would require selling additional bonds.
Don't wait: the ******* yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
The federal government's checking account at the Federal Reserve has quietly ballooned to around $950 billion, roughly the size of Switzerland's economy. On Monday, CNBC's Steve Liesman reported, citing two senior Treasury officials, that Secretary Scott Bessent could tap that cash pile to fund the department's recently expanded bond buyback program. Officials would not say how much would be used or when, but conveyed that the balance "is considered to be available." Under the Biden administration, the stated target was around $550 billion to $600 billion. The gap is the story.
#officials
1 month ago
At first glance, Target Corporation (NYSE:TGT) and Walmart Inc. (NASDAQ:WMT) may look similar from a dividend investor's perspective. Both are long-time retailers with decades of annual dividend increases. However, the two stocks offer very different income profiles.
Target currently pays $1.16 per share each quarter, or $4.64 annually, after raising its dividend by 1.8% in June 2026. With the stock recently trading around $160, that puts the yield at roughly 2.9%. Walmart's annual dividend is $0.99 per share, following a 5% increase, but the stock's recent price near $117 puts the yield at only about 0.8%. For someone looking for income today, Target has a clear advantage.
Niloo / Shutterstock.com
Both companies have unusually strong dividend records. Target Corporation (NYSE:TGT) is on track for its 55th consecutive year of dividend increases in 2026 and has paid a dividend every quarter since going public in 1967. Walmart Inc. (NASDAQ:WMT) is close behind with 53 consecutive years of increases. The more interesting part is what has happened recently. Target Corporation (NYSE:TGT)'s latest increase was only 1.8%, while Walmart Inc. (NASDAQ:WMT) raised its dividend by 5%. That suggests Walmart currently has more room to grow the payout, even though its starting yield is much lower. For investors focused on long-term dividend growth, that difference matters.
Cash flow is where the comparison gets more interesting. Target Corporation (NYSE:TGT) generated about $6.6 billion in operating cash flow in fiscal 2025 and paid roughly $2.1 billion in dividends. After spending about $3.7 billion on capital expenditures, it had around $2.8 billion in free cash flow. The dividend was covered, but the cushion was not especially wide. Target also expects to spend around $5 billion on capital projects in 2026, including store remodels, supply-chain investments, technology, and new stores. In other words, much of the company's cash still needs to be reinvested in the business.
#target #corporation #billion
1 month ago
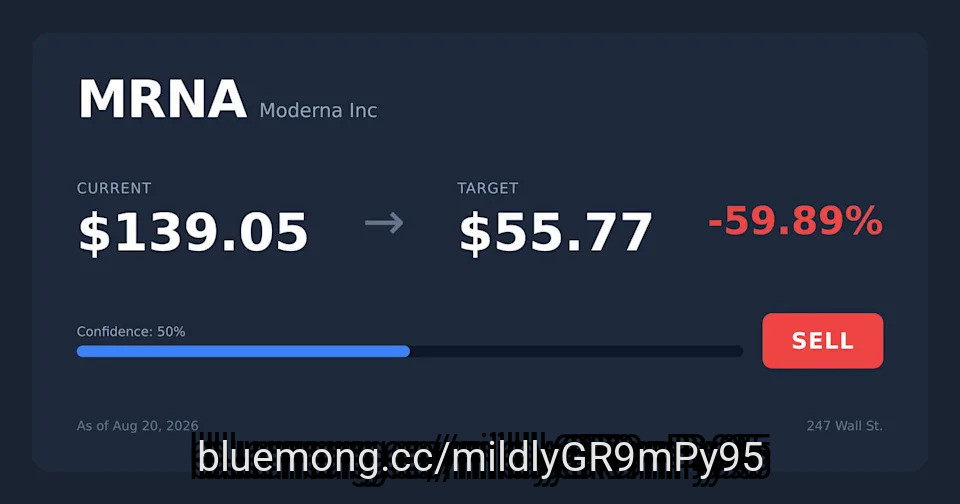
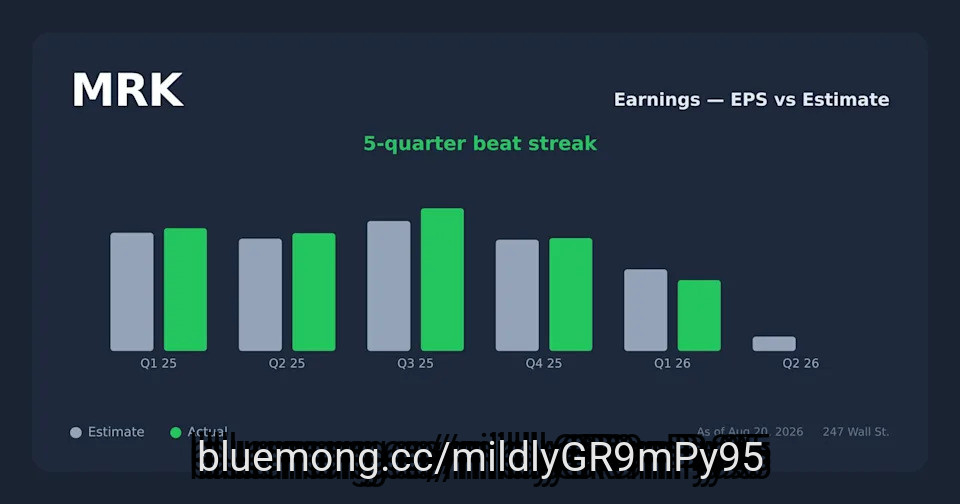
Moderna (MRNA) surged 177% and Merck (MRK) rose 12.5% after their mRNA cancer vaccine met key Phase 3 melanoma trial goals.
Phase 2b data showed a 49% reduction in recurrence or death versus Keytruda alone, with nine studies now underway across multiple cancer types.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Merck didn't make the cut. Grab the names FREE today.
Moderna (NASDAQ:MRNA) shares have crashed 20% as of 12:00 PM ET on Thursday after delivering one of the biotech sector's most extraordinary single-day moves of 2026. CNBC co-anchor Andrew Ross Sorkin told viewers that Moderna's Phase 3 results for its experimental cancer vaccine sent the stock soaring 177% on Wednesday, while partner Merck (NYSE:MRK) rallied 12.5%.
As Sorkin summarized on air, "The mRNA based shot, in combination with Merck's immunotherapy called Keytruda, met key goals in a trial of patients with higher risk or advanced melanoma whose detectable cancer had been removed."
#mrna #merck #phase #sorkin
1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Discover it Secured Cash Back Credit Card doesn't require a credit score to apply. In fact, it helps build up your credit score by offering cash-back rewards as an incentive for responsible credit behavior.
The Discover It Secured Cash Back Credit Card offers good rewards, especially for a secured card:
5% cash back on everyday purchases in rotating quarterly categories (up to the quarterly limit)
1% unlimited cash back on all other purchases
#card #purchases


2 months ago
Over the past decade, power producers were valued as cyclical businesses, as their performance was **** ociated with commodity prices and weather patterns. This notion no longer holds, as the expansion of AI, industrial electrification, and data centers has driven a significant increase in electricity demand. This demand is likely to last for several years rather than quarters.
As of now, the broader market has been rewarding independent power producers and utilities that have reliable generation **** ets, exposure to fast-growing electricity markets, and can tap future cash flows via hedging programs and long-term contracts. Therefore, electricity is now viewed as a critical infrastructure layer beneath the broader AI economy.
Vistra Corp. (NYSE:VST) is not just a merchant power company whose earnings are sensitive to wholesale electricity prices. It is now valued as a strategic power infrastructure platform, which has exposure to AI-backed electricity demand, natural gas expansion, nuclear generation, and long-term contractual opportunities. This thesis was further reinforced by the recent quarterly results. In Q2 2026, Ongoing Operations Adjusted EBITDA saw an increase of over 30% YoY to $1.77 billion, with the company maintaining 97% or greater commercial availability throughout the fleet during strong demand in Texas and PJM.
Furthermore, Vistra Corp. (NYSE:VST)'s management reaffirmed FY 2026 guidance, expecting Ongoing Operations Adjusted EBITDA and Ongoing Operations Adjusted FCFbG (Adjusted Free Cash Flow before Growth) of $6.8 billion - $7.6 billion and $3.925 billion - $4.725 billion, respectively. For FY 2027, it gave an Ongoing Operations Adjusted EBITDA midpoint opportunity range of $7.4 billion - $7.8 billion.
Apart from the financial results, Wall Street lauded the visibility rooted in the business. As of early August, the company already hedged ~100% of expected generation volumes for FY 2026, 94% for FY 2027, and 72% for FY 2028. This offers strong forward visibility of cash flows.
#ebitda #generation