

2 days ago
Hong Kong Sixes 2026 schedule: Start date, time and squads listed originally appeared on Cricket News. Add Cricket News as a Preferred Source by clicking here.
The 22nd Hong Kong Sixes runs from October 30 to November 1 at Tin Kwong Road Recreation Ground in Kowloon.
Twelve teams are split into four groups of three, with Pakistan, India and UAE in Group C.
Defending champions Pakistan are led by Abbas Afridi, while India have named Bhuvneshwar ****** ar as captain.
Hong Kong's six-a-side tournament returns this month for its 22nd edition, and Pakistan arrive as the team to beat. They won last year's ****** le by beating Kuwait in the final, a record sixth Sixes championship. India, meanwhile, finished 12th out of 12 teams.
#hong #sixes #kong #teams


2 days ago
I'm a fan of David Samson. The former Marlins executive turned host at Meadowlark Media speaks candidly, and usually supports his positions with solid evidence. He's been gracious with his time to our writers over the years. His prior conversations with Pablo Torre and John Skipper on The Sporting Class always made me think. Whether Marlins and Expos fans like him or his opinions are right more than wrong doesn't change my position.
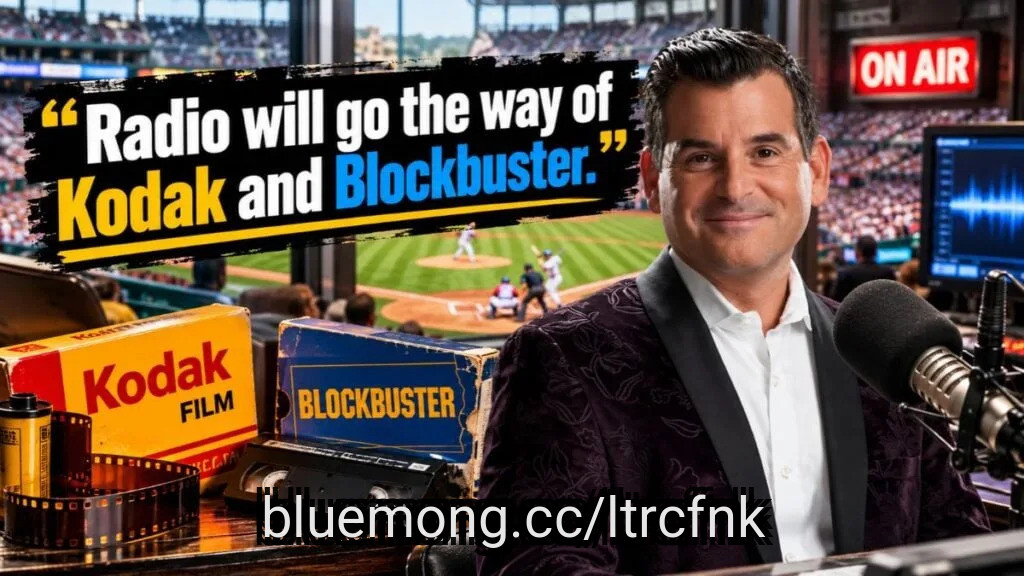
But earlier this week, David stepped on a landmine. He declared that we don't need baseball on the radio anymore. David said, "We all live by the clock that is kernels of sand through an hourglass. So, radio will go the way of Kodak and Blockbuster. It doesn't mean the voices will go away. The voices will find a different way to get into your brain because you have a different way of engaging with content."
In my opinion, David couldn't be more wrong. The response to those remarks has been huge across social media. Most feel similar to yours truly. I respect David's knowledge of the baseball business. He ran the Miami Marlins for 15 years. He spent a few years with the Expos too. He's been a part of media deals on the team's side pointing out that teams "buy a block of time, and then go out and sell ads." Some clubs do that. But most big brands don't. Let's examine the issue a little deeper.
Reach matters in today's media climate. Nielsen data shows AM/FM radio reaches 87% of U.S. adults every week. Those numbers aren't from 10-15 years ago. They are from the first quarter of 2026. That beat smartphones at 82%, TV-connected devices at 78% and live TV at 71%. Even among adults 18-34, radio reaches 81%.
Is radio's revenue down from its peak? Yes. The industry produced over 21 billion in 2006. BIA projects local radio will earn $12.2 billion in 2026. That's still a lot of money even if it's less than what existed 20 years ago. Still, Samson said there is no money in radio. Twelve billion Benjamin's suggests otherwise.
#still

2 days ago
Ford has now announced the cars, the colors, the concert, the cable channel and the charity fund for its Veterans Day Classic at Daytona. What it hasn't announced, at least in the material it has published so far, is how long the race runs or how a winner gets picked. That gap is the story, and it's why the lineup tells you more than the poster does.
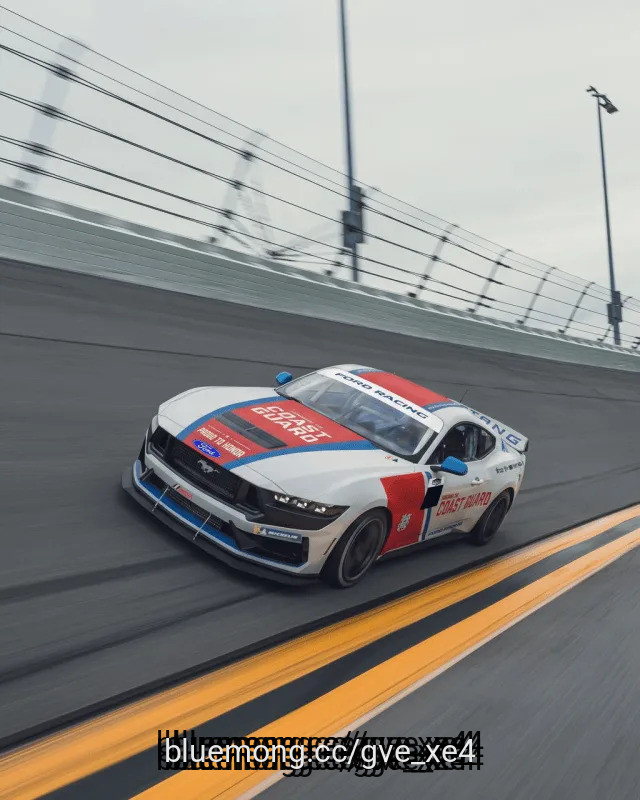
The event is set for Wednesday, Nov. 11, at Daytona International Speedway, three days after the Cup Series finale at Homestead (here's how that November calendar stacks up). Ford is running it in collaboration with NASCAR, Blue Star Families, IMSA and HSR, according to Ford's own announcement. Twelve Ford Racing drivers will split into six teams, one for each branch of the U.S. military, all in Mustang Dark Horse R race cars.
Think about what that means. In a normal NASCAR weekend, Ford's pitch to its fans is simple: beat Chevrolet and Toyota. Here there is **** ody to beat. Every driver, every car and every logo on the grid is Ford, so the manufacturer has to build the stakes from scratch. Its answer is the military branch as team identity, and Ford says the teams are racing for bragging rights.
That is a smart device and a fragile one. A one-make race can't borrow rivalry from the paddock. It has to earn it in two hours of television, which is why the details Ford hasn't filled in matter more than usual.
Ford's lineup pairs the drivers like this: Army gets Joey Hand and Brad Keselowski, the Marine Corps gets Ryan Blaney and Ben Hobson, the Navy gets Logan Sargeant and Ryan Preece, the Air Force gets Frankie Muniz and Austin Cindric, the **** e Force gets Noah Gragson and Layne Riggs, and the Coast Guard gets Joey Logano and Ty Majeski.
#every #joey #ryan



24 days ago
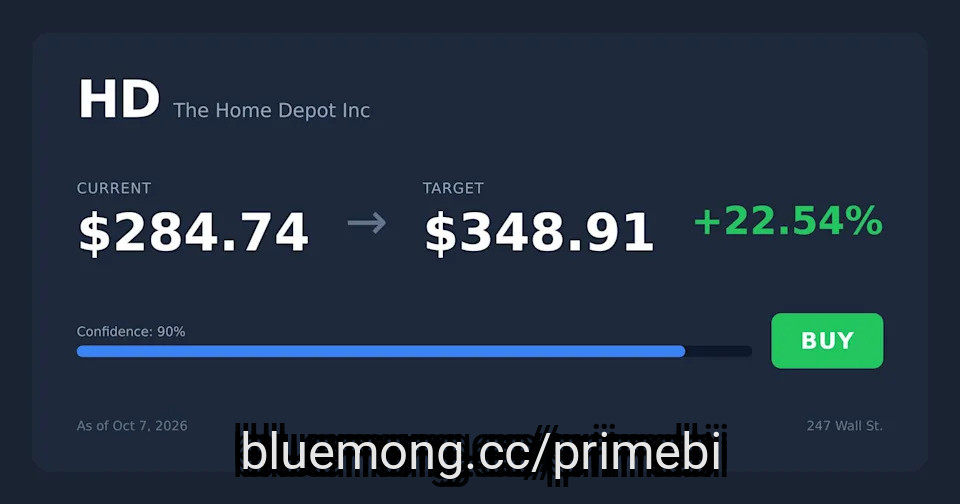
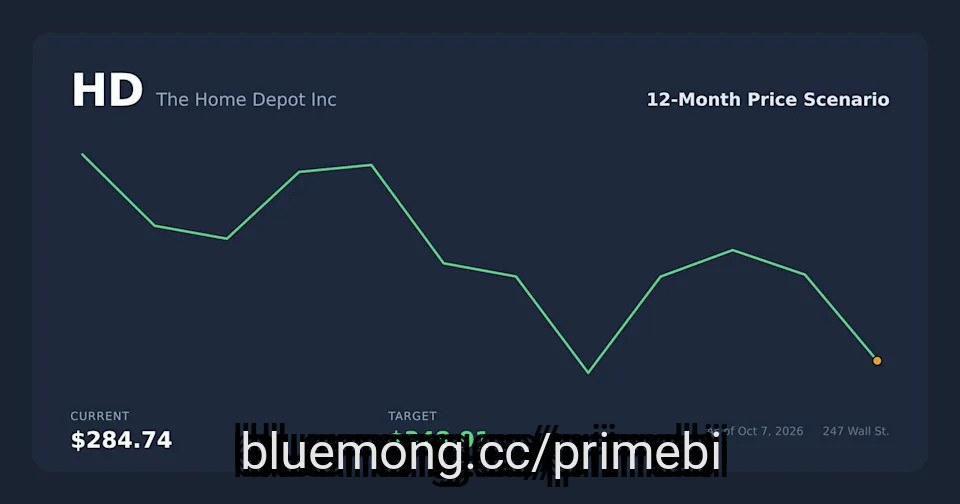
Home Depot (HD) has dropped 15% year to date, yet even the model's conservative one-year price target of $319 sits above today's $285.
A 3.75% dividend yield anchors the buy threshold at $243, requiring a further 15% decline from current levels before reassessment.
The 52-week low of $277 sits just 3% below today's price, making it too thin a margin to serve as a meaningful buy trigger.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Shares of Home Depot (NYSE:HD) traded at $285.10 as of 10:01 AM ET on October 7, 2026, down 0.55% in Wednesday's session. The stock has fallen 15.33% year to date and 24.68% over the past twelve months. Most of the damage is recent. Shares are down 11.2% over the past month.
#down

25 days ago
AbbVie Inc. (NYSE:ABBV) was trading at around $263 on October 5, up 14.18% over twelve months. Its payout ratio is 190.40%. The company distributes nearly twice what it reports as profit.
A dividend that large is either about to be cut or is being paid out of something the earnings line does not show.
READ ALSO: Here is Why Tripadvisor (TRIP) is a Bad Investment at Today's Price
AbbVie reported net income of $6.27 billion and generated $16.87 billion of free cash flow. Dividends are paid from the second number, so a ratio measured against the first is describing depressed earnings rather than a company living beyond its means.
The margins show what depresses them. Operating margin is 40.04%. Net margin is 9.80%. Thirty points vanish between those lines, and where they vanish matters. Costs that high sitting below the operating line are not the business failing to earn. They are the amortization of a drug portfolio AbbVie bought rather than discovered, plus interest on the debt that bought it.
#paid
25 days ago
The Boeing Company (NYSE:BA) was trading at around $193 on October 5, down 11.91% over twelve months. Boeing reported net income of $2.09 billion over the past twelve months. Its EBITDA over the same period was negative $2.9 billion.
Those two figures describe the same year and point in opposite directions. Only one of them tells you what the business did.
READ ALSO: GE Aerospace (GE) vs. RTX (RTX): Which Is the Better Stock to Buy?
Start with the figure that describes the aircraft business itself. Boeing's operating margin is 0.00%. On $93.99 billion of revenue, building and selling airplanes earned nothing.
That is not a rounding problem. Gross profit was $4.43 billion on that revenue, under five percent for a manufacturer, which means the cost of building the aircraft very nearly equals what customers pay for them.
#same
1 month ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


1 month ago
Eli Lilly (LLY) trades near $1,150, up about 52% over the past year, and is now worth more than a trillion dollars. At that size the easy read is that the big money has been made. But Lilly has barely started selling Foundayo, its oral obesity medicine, outside the United States. So how much is left? The scenario below starts from Lilly's own trailing numbers, but the growth, margin, and multiple it ***** umes are ours. It is not a forecast and not a price target.
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue

1 month ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
1 month ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

1 month ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast

1 month ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson


1 month ago
Generac (GNRC) trades at the highest earnings multiple in its five-company peer group on a trailing basis. Yet it ranks last of the five on revenue growth over the past year, and fourth on operating margin. The case for paying up rests on something the trailing numbers do not show yet: a data center order book that ships mostly in 2027.
How Does The Past Year's Slowest Grower Carry The Highest Multiple?
AZZ trades at 20.0 times earnings, about half of Generac's 39.9. It grew revenue 5.7% over the last twelve months, against 0.6% for Generac. It also runs an operating margin of 16.2%, against Generac's 9.5%.
GNRC
RRX
#highest #past
How Does The Past Year's Slowest Grower Carry The Highest Multiple?
AZZ trades at 20.0 times earnings, about half of Generac's 39.9. It grew revenue 5.7% over the last twelve months, against 0.6% for Generac. It also runs an operating margin of 16.2%, against Generac's 9.5%.
GNRC
RRX
#highest #past

1 month ago
Vertiv (VRT) supplies the power and cooling systems inside AI data centers, and its stock sits near $240, about 64% of its 52-week high. It is still up about 73% over the past twelve months. The open question is delivery, after some revenue from large projects slipped out of the second quarter of 2026. Even so, Vertiv's operating margin has widened in each of the last three years.
How Far Has Vertiv's Operating Margin Climbed?
Vertiv's operating margin was 9.6% three years ago. It rose to 15.1%, then 17.4%, and reached 19.4% over the last twelve months. That is roughly twice as much operating profit from every dollar of sales.
For the adjusted margin gain in the second quarter of 2026, management cites productivity and pricing that ran ahead of costs. Tariffs took back part of it. The company expects price to stay ahead of cost across 2026, tariffs included.
Does The Delivery Slip Show Up In Vertiv's Profits?
#Margin


1 month ago
Autodesk (ADSK) stock has 23.6% of room above it before it meets a ceiling that has turned it back three times, and 5% below it before the reason to be there stops being true. In dollars: $272.34 overhead, $220.31 Wednesday, $209.29 underneath. The stock has lost about 31% over the past twelve months, so the easy read is that the business broke. Its own numbers say it did not.
Would You Have Made Money Buying Autodesk Here Before?
Buyers have stepped in at this price zone eight times before. Three of those eight produced a completed advance, averaging a 34.3% gain to the peak that followed, with a median of 459 days from the defense to that peak. The other five have not yet risen above their own starting price, so they are not in that average at all. The ceiling overhead asks for less than that average of the three that paid.
The last two years are the problem. Autodesk entered this price band on five separate occasions over the last twenty-four months, and counting only a 20% gain before any 5% fall as a defense, one held and four broke 5% lower first. The path up is not clear either: the stock has to get through $248.16 and $261.04, both pauses rather than proven ceilings.
Is Autodesk In Better Shape Than The Last Time It Sat Here?
#last #Stock #above #times


1 month ago
Intuitive Surgical (ISRG), maker of the da Vinci surgical robots, trades at about $382, some 36% below its 52-week high. Even so, you pay about 35.9 times trailing adjusted earnings. That is normalized net income with stock-based compensation added back, a basis meant to sit closer to the one ****** ysts forecast on, though the two are not defined identically. ****** ysts' forecasts run to 2027, the year Intuitive plans to start lowering what customers pay per use on some instruments.
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures


1 month ago
Palantir Technologies (PLTR) trades near $172.56, and the options market has already drawn the year ahead in dollars. The one-year band runs from $96.77 at the floor to $307.69 at the ceiling. That is not a forecast. It is the size of the uncertainty you are holding, and it raises a question about position size rather than direction.
What You Are Actually Risking On A Palantir Position
That range is where the options market puts roughly a two-in-three chance over the twelve months ahead. On a $10,000 holding, that is about $4,400 at risk down to the floor. Up to the ceiling there is about $7,800 of room. The two sides are not the same size because a stock cannot fall below zero but can rise without limit.
Outside that band sit two tails: roughly a one-in-six chance the stock finishes above the ceiling, and the same chance it finishes below the floor. So $96.77 is the edge of the ordinary, not the bottom of it.
Palantir Has Been Moving More Than Its Options Imply
#options #position

1 month ago
Cadence Design Systems (CDNS) trades at 54.5 times trailing earnings. A multiple that high is a requirement rather than an opinion. The price only works if the business grows into it, and you can work out exactly how much growth it takes. The harder question is whether that calculation deserves your trust here.
What Is Cadence's Price Already ***** uming?
Three things have to be true, and none is a forecast. Each is an ***** umption the price has already made, and each one is worth testing.
First, the market gives Cadence four years to grow into the multiple. Second, the multiple then settles at 28.8 times, where a mature, scaled software franchise usually lands. Third, net margin holds near 24.3%, roughly where Cadence's net margin has run over the past twelve months.
So How Fast Would Cadence Have To Grow?
#times #design


1 month ago
GE Aerospace (GE) has more engine work booked than it can currently perform, and that visibility is much of why people own the shares. The option chain does not treat the stock as settled. At about $307, contracts running twelve months out carry a band from near $216.93 to near $434.6, with roughly a two-in-three chance the stock finishes inside it.
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band

1 month ago
Caterpillar (CAT) trades around $780. The market puts roughly a two-in-three chance that the stock finishes somewhere between about $525 and about $1,170 a year from now. That is not a forecast of direction. It is the size of the swing a holder is already carrying, and Caterpillar's own record says it is no exaggeration.
Measured from around $780, the floor of that range sits roughly a third below today's price and the ceiling close to half again above it. The extra room on the upside is arithmetic, not optimism. A stock cannot fall below zero and can rise without limit, so the upper end is always the longer one. There is also roughly a one-in-six chance of finishing above the band, and the same chance of finishing below it.
A third of the money in the position can go, and the band's low end is not the worst case. The same market pricing that drop is pricing a larger gain on the other side. The size of your position decides how much of that drop, or that gain, you actually feel.
None of that width is theoretical here. Caterpillar returned 83% over the past twelve months, against about 17% for the S&P 500, and it still trades about 26% below its 52-week high. Both of those belong to the same year. A stock that can do both is the kind an options market prices this wide.
Implied volatility of 39.9% is running level with the 40.0% the stock has actually delivered over the trailing year. The market is quoting the recent past forward rather than charging extra for fear. What could make the year ahead different sits inside the business.
#market #below #chance #around

1 month ago
PepsiCo (PEP) has gone nowhere for a year, down 1.8% over the past twelve months while the S&P 500 returned 16.6%. At about $135 a share it trades at 17.7 times earnings, against an S&P 500 median of 22.5. A big cash generator priced below the market is what value buyers hunt for, so is this discount impatience or a verdict?
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing

1 month ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue

1 month ago
Netflix (NFLX) trades at about $80, and its own options put a price on how far that can travel over the twelve months ahead: a floor near $54.21 and a ceiling near $119. The options market is charging nothing unusual for that range. Ordinary, for Netflix, already means a range wide enough to take a third of your money.
Your $10,000 Stake Could Be Worth $6,750 Or $14,800 A Year Out
From today's price the ceiling is about 48% higher and the floor about 33% lower. A $10,000 stake could end the year near $6,750 or near $14,800. The upside is larger in dollars for a mechanical reason: a share price stops at zero and has no top.
Those bounds are odds rather than a forecast: roughly a two-in-three chance of finishing between them, and about a 16% chance of ending beyond each one. Nothing in that says which way. It says how much room a holder has to give, and Netflix has needed that room before.
Netflix Just Had A Year Almost This Volatile
#year #price #floor #ceiling


1 month ago
Accenture (ACN) stock trades near $195, and the options market prices roughly a two-in-three chance that it ends the coming twelve months between about $123 and about $308. That floor is about where the stock bottomed over the past year, and the ceiling is above the high it has already given back. For a holder, the question is whether a band that wide is more than you signed up for.
How Much Of Your Position Is On The Table Each Way?
The floor sits about 37% below today's price, a fall of $71.59, and the ceiling about 58% above it, a rise of $113.12. The bigger upside figure is not a lean: a share price can rise without limit and cannot fall below zero, so the band is always wider in dollars on the way up.
Has Accenture Stock Moved This Much Before?
It has. The stock traded between $122.96 and $282.71 over the past 52 weeks, and it lost 17.5% over the trailing twelve months while the S&P 500 gained 17%. Realized volatility over that year was 44.9%, and the one-year options carry implied volatility of 45.5%, a ratio of 1.01. The chain is pricing another year of movement about the size of the last one.
#twelve #floor

1 month ago
Boeing (BA) grew revenue faster over the past twelve months than any of its aerospace and defense peers, GE Aerospace included, and its stock still fell. It is also the only one in that group running an operating loss. The growth has come with rising airplane deliveries, and the market is waiting to see whether those airplanes earn a margin.
GE Aerospace is the sharpest comparison. It grew revenue 21.7% over the trailing twelve months, close to Boeing's 24.8%, on an operating margin of 18.7%, and its stock returned 13.4%. Boeing's operating margin over the same twelve months was negative 5.4%. Its stock returned negative 4.4%.
BA
RTX
LMT
#aerospace #twelve #months #operating

1 month ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price

1 month ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine


1 month ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash

2 months ago
Matt LaFleur spent his entire offseason promising Green Bay Packers would finally learn how to finish games. Sunday in Minneapolis put that promise to the test immediately. The Packers built a healthy second-half lead, the same type of cushion that slipped away repeatedly last season, and it vanished again. What happened next, both on the field and in the press conference that followed, left fans furious.
Green Bay looked in control for most of Sunday's opener at U.S. Bank Stadium. The Packers led 22-10 in the third quarter behind Jordan Love, who threw for 387 yards and two touchdowns. Then everything unraveled. Minnesota Vikings scored 29 unanswered points in the second half, turning a comfortable lead into a 39-22 defeat.
The turning point came in the fourth quarter. With Green Bay up 25-17 after a penalty wiped a Vikings field goal off the board, LaFleur chose to go for it on fourth-and-1 instead of taking the points. Love was stopped on a quarterback sneak, and Minnesota took over on downs. The Vikings never let go from there.
Sep 12, 2021; Jacksonville, Florida, USA; Green Bay Packers head coach Matt LaFleur during the first half against the New Orleans Saints at TIAA Bank Field. Mandatory Credit: Tommy Gilligan-USA TODAY Sports
Love was sacked four times after halftime, lost a fumble and threw a tipped interception during the fourth-quarter collapse. Twelve Packers penalties for 98 yards, several on Minnesota's go-ahead drive, compounded the damage.
#lafleur #half


2 months ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted



