1 day ago
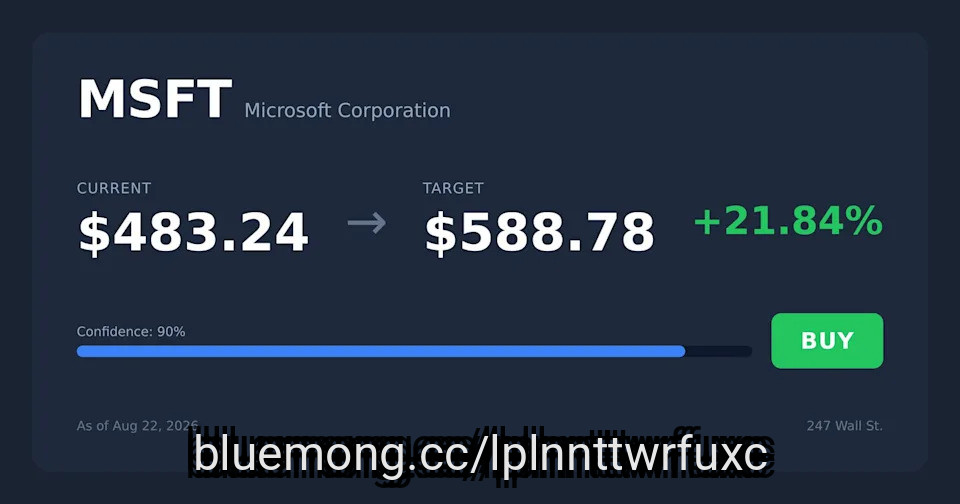
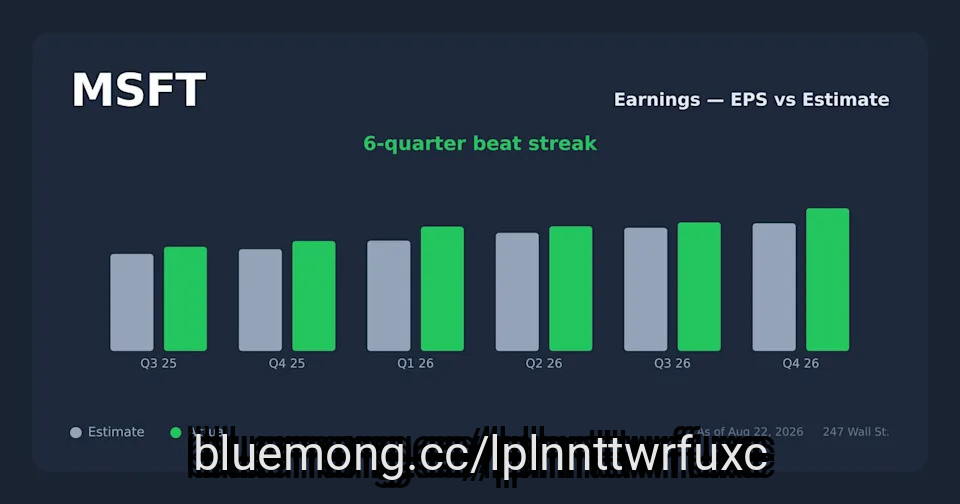
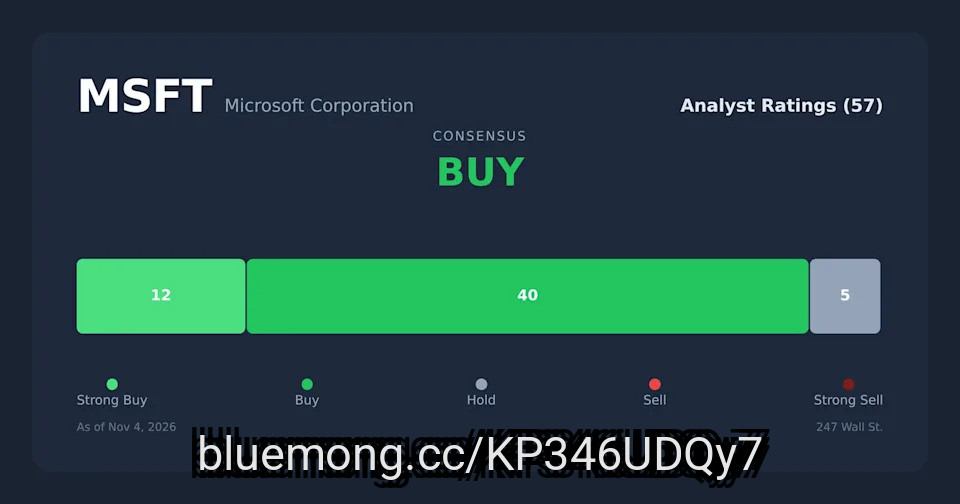
A $1,000 investment in MSFT today could reach $1,587 by 2029 under the base case, or as high as $1,911 in a bull scenario.
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price
Azure revenue surged 48% last quarter, and CFO Amy Hood guided next-quarter growth of between 49% and 50% in constant currency.
Microsoft's contracted backlog jumped 73% to $677 billion, with Copilot daily users up over 5x year over year.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Microsoft (NASDAQ:MSFT) is one of the biggest stocks you can own to get exposure to enterprise AI, so it makes sense to ask what $1,000 put in today could grow into by 2029. Our price-prediction model uses a reference price of $525.63 per share.
#year #email #price

1 month ago
A breakup can be shocking enough, but being told it's over with "no warning" is another story entirely. Elon Musk's girlfriend Shivon Zillis revealed on X on October 2 that their romance is officially done.
The 40-year-old Neuralink executive gave a lengthy statement about their split on her ex-boyfriend's social media platform after five years together. They also share four children: fraternal twins Strider and Azure, 4, daughter Arcadia, 2, and son Seldon, 1.
More from SheKnows
Why Jim Carrey's New Marriage Is a Major Departure From Renée Zellweger & Jenny McCarthy Romances
"It's hard to go from in love to let go in a week with no warning, but that's just how it is sometimes," she wrote, confirming the breakup was a one-sided situation.
#shivon #zillis #neuralink #azure
The 40-year-old Neuralink executive gave a lengthy statement about their split on her ex-boyfriend's social media platform after five years together. They also share four children: fraternal twins Strider and Azure, 4, daughter Arcadia, 2, and son Seldon, 1.
More from SheKnows
Why Jim Carrey's New Marriage Is a Major Departure From Renée Zellweger & Jenny McCarthy Romances
"It's hard to go from in love to let go in a week with no warning, but that's just how it is sometimes," she wrote, confirming the breakup was a one-sided situation.
#shivon #zillis #neuralink #azure



1 month ago
Shivon Zilis says she feels grateful towards Elon Musk for their four kids amid their breakup
The tech executive said Musk recently ended their relationship abruptly in a post on X
The former couple shares twins Strider and Azure plus daughter Arcadia and son Seldon
Elon Musk's ex Shivon Zilis says she's grateful for their four kids following their abrupt breakup.
In a lengthy post on X on Friday, Oct. 2, Zilis, a tech executive, said she is "beyond grateful" for the former couple's four kids while sharing that she and the Tesla CEO have split. Zilis and Musk are parents to twins Strider and Azure, born in 2021, daughter Arcadia, born in 2024, and their youngest, son Seldon, whose birth was announced in early 2025.
#grateful #kids #strider
The tech executive said Musk recently ended their relationship abruptly in a post on X
The former couple shares twins Strider and Azure plus daughter Arcadia and son Seldon
Elon Musk's ex Shivon Zilis says she's grateful for their four kids following their abrupt breakup.
In a lengthy post on X on Friday, Oct. 2, Zilis, a tech executive, said she is "beyond grateful" for the former couple's four kids while sharing that she and the Tesla CEO have split. Zilis and Musk are parents to twins Strider and Azure, born in 2021, daughter Arcadia, born in 2024, and their youngest, son Seldon, whose birth was announced in early 2025.
#grateful #kids #strider



1 month ago
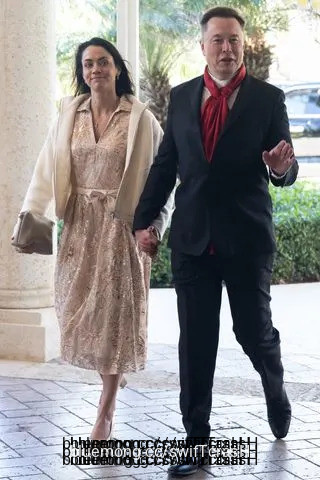
Elon Musk and his on-and-off girlfriend have broken up.
In a post shared on X on Friday, October 2, Shivon Zilis, who shares four children with the Tesla cofounder, 55, revealed that Musk had let her "go" with "no warning" just a week after seemingly being "in love."
"I feel happy that I got to show Elon how it feels to be deeply understood, nurtured, and peacefully loved with stability and gentleness. Given the tumultuous nature of his early life, his often tortured soul, and how hard he fights for humanity, I wanted him to feel the deepest and most stable form of love this world can provide. My heart is full knowing I got to do that, and I hope it leaves a lasting good effect," Zilis, 40, wrote.
Calling her and their four children together, twins Strider and Azure, 4, Arcadia, 2, and Seldon, 1, his "safe ******* e," Zilis said their home life served as a place for the tech giant to unwind after tough days in the field.
"We were always his safe ******* e. A place where all of us were overjoyed to see him and one that was always full of happiness and love, not war, in contrast to his otherwise militant existence (a needed break from the battlefield where he could recharge his heart and soul before heading back out)," the director of operations and special projects at Neuralink continued. "I loved being that counterbalancing place of safety, sense of calm, and love — and delighted in bringing a smile back to his face when he was down."
#love #musk #children #life
In a post shared on X on Friday, October 2, Shivon Zilis, who shares four children with the Tesla cofounder, 55, revealed that Musk had let her "go" with "no warning" just a week after seemingly being "in love."
"I feel happy that I got to show Elon how it feels to be deeply understood, nurtured, and peacefully loved with stability and gentleness. Given the tumultuous nature of his early life, his often tortured soul, and how hard he fights for humanity, I wanted him to feel the deepest and most stable form of love this world can provide. My heart is full knowing I got to do that, and I hope it leaves a lasting good effect," Zilis, 40, wrote.
Calling her and their four children together, twins Strider and Azure, 4, Arcadia, 2, and Seldon, 1, his "safe ******* e," Zilis said their home life served as a place for the tech giant to unwind after tough days in the field.
"We were always his safe ******* e. A place where all of us were overjoyed to see him and one that was always full of happiness and love, not war, in contrast to his otherwise militant existence (a needed break from the battlefield where he could recharge his heart and soul before heading back out)," the director of operations and special projects at Neuralink continued. "I loved being that counterbalancing place of safety, sense of calm, and love — and delighted in bringing a smile back to his face when he was down."
#love #musk #children #life



1 month ago
Shivon Zilis posted a statement on X on Friday saying Elon Musk ended their relationship without warning after the two had been together and built a family of four children.
"It's hard to go from in love to let go in a week with no warning, but that's just how it is sometimes," Zilis wrote.
The post offered a rare public look at one of Musk's most private relationships. Zilis is an artificial intelligence executive who has worked with several of Musk's ventures, including Neuralink, according to Newsweek. The pair share fraternal twins Strider and Azure, born in 2021, a daughter named Arcadia, born in 2024, and a son named Seldon, whose birth was announced in early 2025, according to People.
In her statement, Zilis described her household as a refuge for Musk from what she called his "otherwise militant existence," writing that it was "always full of happiness and love, not war." She said her aim had been to offer him stability.
"I feel happy that I got to show Elon how it feels to be deeply understood, nurtured, and peacefully loved with stability and gentleness," she wrote.
#musk #warning
"It's hard to go from in love to let go in a week with no warning, but that's just how it is sometimes," Zilis wrote.
The post offered a rare public look at one of Musk's most private relationships. Zilis is an artificial intelligence executive who has worked with several of Musk's ventures, including Neuralink, according to Newsweek. The pair share fraternal twins Strider and Azure, born in 2021, a daughter named Arcadia, born in 2024, and a son named Seldon, whose birth was announced in early 2025, according to People.
In her statement, Zilis described her household as a refuge for Musk from what she called his "otherwise militant existence," writing that it was "always full of happiness and love, not war." She said her aim had been to offer him stability.
"I feel happy that I got to show Elon how it feels to be deeply understood, nurtured, and peacefully loved with stability and gentleness," she wrote.
#musk #warning

2 months ago
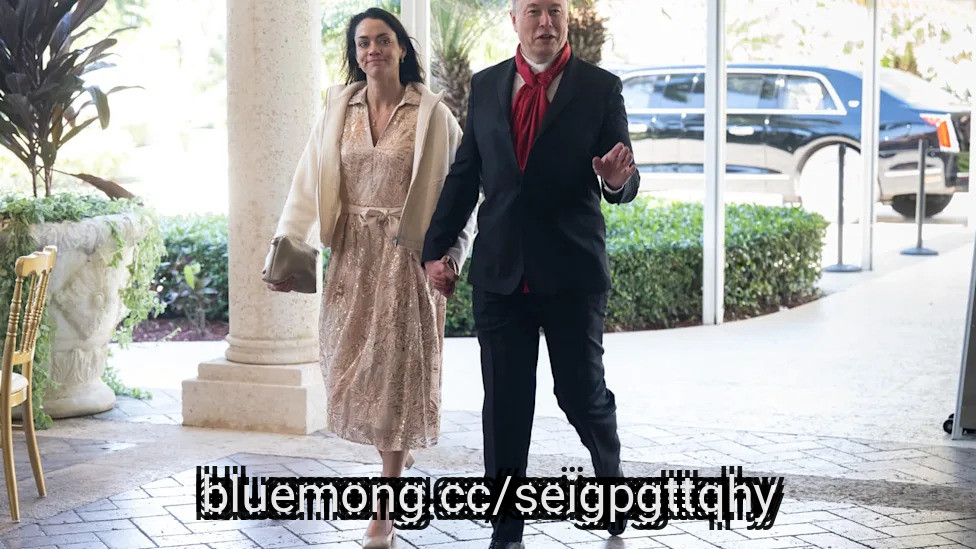
Alphabet's (GOOGL) Search revenue grew 17% to $63B and Cloud surged 82% to $25B, even as GOOGL still trades at a market-level P/E of 15.
Alphabet's cloud is outpacing Azure's growth at a cheaper multiple than Microsoft (MSFT), while Meta (META) owns none of Alphabet's cloud, OS, or Waymo ***** ets.
Alphabet's $175B+ CapEx pushed free cash flow negative, but a $460B cloud backlog and 34% operating margin justify the infrastructure bet.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Google made the cut. Enter your email to see the other nine names and why GOOGL earned its spot. The report is free. Enter your email and see the full list.
I keep adding to my position in Alphabet (NASDAQ:GOOGL) because the loudest bear case, that AI would gut Google Search and hollow out the ad engine, keeps getting louder while the numbers keep going the other way. The skeptics said generative AI would strip clicks out of the funnel. Instead, AI is actively boosting the advertising business, and my cost basis has been rising alongside the buy ***** on.
#free
Alphabet's cloud is outpacing Azure's growth at a cheaper multiple than Microsoft (MSFT), while Meta (META) owns none of Alphabet's cloud, OS, or Waymo ***** ets.
Alphabet's $175B+ CapEx pushed free cash flow negative, but a $460B cloud backlog and 34% operating margin justify the infrastructure bet.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Google made the cut. Enter your email to see the other nine names and why GOOGL earned its spot. The report is free. Enter your email and see the full list.
I keep adding to my position in Alphabet (NASDAQ:GOOGL) because the loudest bear case, that AI would gut Google Search and hollow out the ad engine, keeps getting louder while the numbers keep going the other way. The skeptics said generative AI would strip clicks out of the funnel. Instead, AI is actively boosting the advertising business, and my cost basis has been rising alongside the buy ***** on.
#free

2 months ago
Interested in 3M Company? Here are five stocks we like better.
3M says it is ahead of its 2027 targets, citing 5.4% second-quarter organic growth, higher margins, improved execution and on-time, in-full delivery rising to about 90%.
Data centers are a major growth priority. Its expanded beam optics technology has been standardized by Microsoft Azure, is being evaluated by five other hyperscalers, and could address a market approaching $2 billion within the next two years.
Innovation and cost reductions are supporting the outlook: 3M plans more than 350 new-product launches this year, is consolidating factories, expects to offset $150 million–$175 million in oil-related costs through pricing, and is tracking above its 25% operating-margin goal for next year.
3 Stocks Whose Charts May Be Signaling the Next Big Move
#company
3M says it is ahead of its 2027 targets, citing 5.4% second-quarter organic growth, higher margins, improved execution and on-time, in-full delivery rising to about 90%.
Data centers are a major growth priority. Its expanded beam optics technology has been standardized by Microsoft Azure, is being evaluated by five other hyperscalers, and could address a market approaching $2 billion within the next two years.
Innovation and cost reductions are supporting the outlook: 3M plans more than 350 new-product launches this year, is consolidating factories, expects to offset $150 million–$175 million in oil-related costs through pricing, and is tracking above its 25% operating-margin goal for next year.
3 Stocks Whose Charts May Be Signaling the Next Big Move
#company


2 months ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o

2 months ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of

2 months ago
After holding Microsoft (NASDAQ: MSFT) for more than 10 years, I wouldn't sell a single share, not even today. The company I bought back in 2016 has changed dramatically, but mostly in ways that strengthen the original reason I owned it. Microsoft has shifted from a PC-centric software business to one built on cloud, subscriptions, enterprise software, and artificial intelligence.
So the question now is whether those changes can support another decade of compounding, and whether the stock is still a buy at today's valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When I first bought Microsoft, the business was much smaller. In fiscal 2016, it generated $85.3 billion in revenue and $20.2 billion in operating income. By fiscal 2026, revenue had reached $331.8 billion and operating income $155.2 billion. Azure alone passed $100 billion in annual revenue.
The bigger change is where that growth came from. Microsoft expanded Microsoft 365, Azure, LinkedIn, Dynamics, GitHub, security, and other cloud products across largely the same enterprise customer base.
#Microsoft #revenue #company
So the question now is whether those changes can support another decade of compounding, and whether the stock is still a buy at today's valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When I first bought Microsoft, the business was much smaller. In fiscal 2016, it generated $85.3 billion in revenue and $20.2 billion in operating income. By fiscal 2026, revenue had reached $331.8 billion and operating income $155.2 billion. Azure alone passed $100 billion in annual revenue.
The bigger change is where that growth came from. Microsoft expanded Microsoft 365, Azure, LinkedIn, Dynamics, GitHub, security, and other cloud products across largely the same enterprise customer base.
#Microsoft #revenue #company

2 months ago
Azure crossed $100B annually with 43% growth, and Microsoft's commercial backlog surged 84% to $678B, explaining why markets shrugged off AI safety calls.
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning


2 months ago
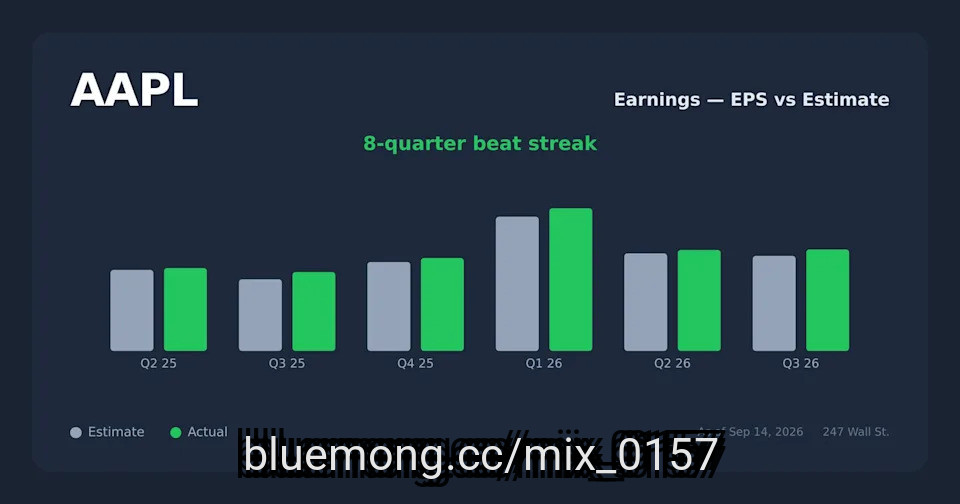
Apple trades at 37x earnings after a 45% one-year run; Microsoft sits at 27x and is up just 3% year to date, offering a cheaper AI entry point.
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks



2 months ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
2 months ago
Microsoft (MSFT) is coming off the most profitable stretch it has posted in years, and its stock trades at $493.95, about 92% of its 52-week high. Nothing here is broken. The risk is quieter than that. The spending that came with those margins is still climbing, and the company has already told shareholders what it expects that to do to fiscal 2027.
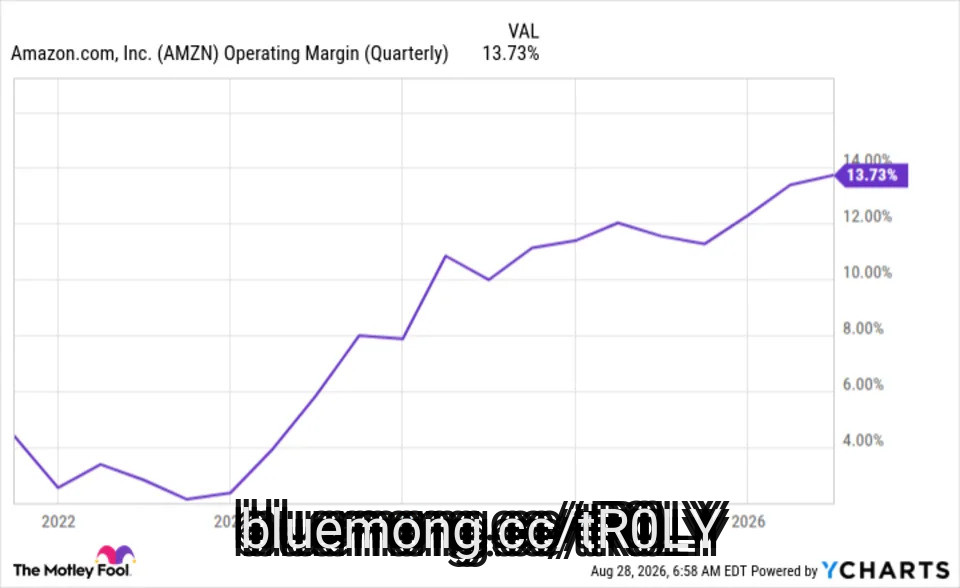
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash

2 months ago
On September 2, NetApp Inc. (NASDAQ:NTAP) reported its Q1 FY27 results, posting record quarterly net revenue of $2.03 billion. Topline for the Intelligent Data Infrastructure company expanded by 30% compared to the first quarter in FY26. The quarter saw a broad-based growth across its core segments, resulting in a record adjusted earnings per share of $2.58, and a quarterly cash dividend of $0.52 per share. The company also strengthened its existing engagements with major players, covering a range of underlying functions.
During the first quarter, all-flash array net revenue went up 47% year-over-year, hitting a record $1.3 billion mark. This drove the overall net revenue for its Hybrid Cloud segment to $1.8 billion, translating into a 30% year-over-year growth. Public Cloud, which accounts for a smaller chunk of the business, saw its net revenue climb by 28%, also setting a record of $206 million. NetApp's total billings clocked in at $2.06 billion, exhibiting a 36% growth compared to Q1 FY26, while its non-GAAP operating margin reached 31.9%.
During the quarter, NetApp finalized the acquisition of an AI-enabled data infrastructure business, DataPelago. The deal is aimed toward facilitating customers streamline and accelerate large-scale AI deployments. On the product front, the company launched StorageGRID 12.1, to support scaling of AI workload through a federated global namespace. It also introduced Instaclustr for its fully managed Model Context Protocol Gateway, along with enhanced support for Azure NetApp Files up to 64 TiB.
NetApp also revealed new features for NetApp Trident software 26.06. These include deeper integration of OpenShift Virtualization, non-disruptive iSCSI rebalancing, efficient volume placement, and additional cloud support.
Despite encouraging numbers reported during the quarter, the free cash flows settled at $401 million. This was a 35% drop compared to figures reported for Q1 FY26. Additionally, NetApp remains heavily dependent on its Hybrid Cloud business, which generated roughly 90% of quarterly revenue, while Public Cloud still contributes a relatively small fraction of the topline despite growing 28% during the recent quarter. This leads to concerns regarding how much of the company's growth story is truly cloud-native compared to conventional on-premises hardware refresh cycles that are strongly tied to AI infrastructure investments. For the underlying all-flash arrays, such AI-linked demand trend could prove to be front-loaded or cyclical in case enterprise capital expenditure decelerates.
#netapp #Growth
During the first quarter, all-flash array net revenue went up 47% year-over-year, hitting a record $1.3 billion mark. This drove the overall net revenue for its Hybrid Cloud segment to $1.8 billion, translating into a 30% year-over-year growth. Public Cloud, which accounts for a smaller chunk of the business, saw its net revenue climb by 28%, also setting a record of $206 million. NetApp's total billings clocked in at $2.06 billion, exhibiting a 36% growth compared to Q1 FY26, while its non-GAAP operating margin reached 31.9%.
During the quarter, NetApp finalized the acquisition of an AI-enabled data infrastructure business, DataPelago. The deal is aimed toward facilitating customers streamline and accelerate large-scale AI deployments. On the product front, the company launched StorageGRID 12.1, to support scaling of AI workload through a federated global namespace. It also introduced Instaclustr for its fully managed Model Context Protocol Gateway, along with enhanced support for Azure NetApp Files up to 64 TiB.
NetApp also revealed new features for NetApp Trident software 26.06. These include deeper integration of OpenShift Virtualization, non-disruptive iSCSI rebalancing, efficient volume placement, and additional cloud support.
Despite encouraging numbers reported during the quarter, the free cash flows settled at $401 million. This was a 35% drop compared to figures reported for Q1 FY26. Additionally, NetApp remains heavily dependent on its Hybrid Cloud business, which generated roughly 90% of quarterly revenue, while Public Cloud still contributes a relatively small fraction of the topline despite growing 28% during the recent quarter. This leads to concerns regarding how much of the company's growth story is truly cloud-native compared to conventional on-premises hardware refresh cycles that are strongly tied to AI infrastructure investments. For the underlying all-flash arrays, such AI-linked demand trend could prove to be front-loaded or cyclical in case enterprise capital expenditure decelerates.
#netapp #Growth


2 months ago
On August 25, EPAM Systems (NYSE:EPAM) announced a partnership with Wiz, the cloud and AI security platform now owned by Google Cloud, joining the Wiz Partner Alliance to help large organizations turn cloud risk data into actual engineering fixes. The timing is notable. Just weeks earlier, on August 6, EPAM reported second-quarter revenue growth of only 4.5% and pointed to a much slower pace ahead. A cybersecurity push gives the company a fresh growth story just as its core business decelerates.
The Wiz deal pairs Wiz's AI Application Protection Platform with EPAM's AI-native engineering and cloud modernization work, aiming to move clients from simply spotting cloud risks to actually remediating them across Google Cloud, AWS, Azure, and other environments. White Hat, an EPAM company, adds an offensive security layer of defensive, offensive, and incident response specialists to test whether flaws found by Wiz are actually exploitable, rather than just theoretical. EPAM says this formalizes work already underway, having delivered Wiz implementation programs across six industries: media and entertainment, transportation and logistics, life sciences and healthcare, financial services, automotive, and retail and consumer goods. That existing footprint gives the partnership a running start rather than a cold launch.
The financial backdrop supports the case that EPAM has room to invest here. Second quarter GAAP income from operations rose to 10.8% of revenue from 9.3% a year earlier, while non-GAAP operating margin climbed to 16.4% from 15%. GAAP diluted EPS reached $1.97, up 26.3% year over year, and non-GAAP diluted EPS hit $3.38, up 22%. The company also returned $409 million to shareholders through buybacks in the first half of 2026, including $85 million in the second quarter alone.
The numbers behind the Wiz announcement tell a more cautious story. EPAM's full-year revenue growth guidance now sits at 3.2% to 4.2%, with organic constant currency growth pegged at just 2.0% to 3.0%. The third quarter outlook is softer still: revenue of $1.410 billion to $1.425 billion implies year-over-year growth of roughly 1.7% at the midpoint, a sharp step down from the 4.5% posted in the second quarter.
Cash flow moved in the wrong direction too. EPAM used $38.8 million in operating activities during the first half of 2026, compared with $77.4 million generated over the same period in 2025. Total cash, equivalents and restricted cash fell 39% to $794.3 million as of June 30, from $1.301 billion at the end of 2025, a decline driven in part by continued share repurchases. Headcount growth was modest as well, with delivery professionals up just 0.3% from the prior quarter, suggesting a company being deliberate rather than aggressive about scaling capacity even as it adds new service lines like Wiz implementation.
#epam #cloud #year #company
The Wiz deal pairs Wiz's AI Application Protection Platform with EPAM's AI-native engineering and cloud modernization work, aiming to move clients from simply spotting cloud risks to actually remediating them across Google Cloud, AWS, Azure, and other environments. White Hat, an EPAM company, adds an offensive security layer of defensive, offensive, and incident response specialists to test whether flaws found by Wiz are actually exploitable, rather than just theoretical. EPAM says this formalizes work already underway, having delivered Wiz implementation programs across six industries: media and entertainment, transportation and logistics, life sciences and healthcare, financial services, automotive, and retail and consumer goods. That existing footprint gives the partnership a running start rather than a cold launch.
The financial backdrop supports the case that EPAM has room to invest here. Second quarter GAAP income from operations rose to 10.8% of revenue from 9.3% a year earlier, while non-GAAP operating margin climbed to 16.4% from 15%. GAAP diluted EPS reached $1.97, up 26.3% year over year, and non-GAAP diluted EPS hit $3.38, up 22%. The company also returned $409 million to shareholders through buybacks in the first half of 2026, including $85 million in the second quarter alone.
The numbers behind the Wiz announcement tell a more cautious story. EPAM's full-year revenue growth guidance now sits at 3.2% to 4.2%, with organic constant currency growth pegged at just 2.0% to 3.0%. The third quarter outlook is softer still: revenue of $1.410 billion to $1.425 billion implies year-over-year growth of roughly 1.7% at the midpoint, a sharp step down from the 4.5% posted in the second quarter.
Cash flow moved in the wrong direction too. EPAM used $38.8 million in operating activities during the first half of 2026, compared with $77.4 million generated over the same period in 2025. Total cash, equivalents and restricted cash fell 39% to $794.3 million as of June 30, from $1.301 billion at the end of 2025, a decline driven in part by continued share repurchases. Headcount growth was modest as well, with delivery professionals up just 0.3% from the prior quarter, suggesting a company being deliberate rather than aggressive about scaling capacity even as it adds new service lines like Wiz implementation.
#epam #cloud #year #company

2 months ago
Amazon (NASDAQ: AMZN) and Microsoft (NASDAQ: MSFT) are two of the largest cloud computing providers. But which one of these hyperscalers makes for the better buy? I think there's one key metric that separates the two firms, and once you recognize it, it will be hard to consider investing in the other.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In terms of market share, Amazon Web Services (AWS) is the largest cloud computing provider in the world, with Microsoft Azure coming in second. That makes both firms very important, but of the two, it's pretty clear Amazon is growing at a faster pace.
At first glance, that **** ysis seems wrong. In their latest quarters, Azure grew by 43%, while AWS grew by 37%. But that's not what I'm talking about.
I'm looking more at the trend lines, and it's clear that AWS' growth is accelerating rapidly. During Q1, AWS's growth rate was 28%. In Q4 2025, its growth rate was 24%. Rewinding to Q3 2025, its growth rate was 20%. That's some rapid acceleration over the past year, and considering Amazon is still pouring hundreds of billions of dollars into expanding its cloud computing capacity, I won't be surprised to see AWS' growth rate continue to accelerate over the next few quarters.
#computing
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In terms of market share, Amazon Web Services (AWS) is the largest cloud computing provider in the world, with Microsoft Azure coming in second. That makes both firms very important, but of the two, it's pretty clear Amazon is growing at a faster pace.
At first glance, that **** ysis seems wrong. In their latest quarters, Azure grew by 43%, while AWS grew by 37%. But that's not what I'm talking about.
I'm looking more at the trend lines, and it's clear that AWS' growth is accelerating rapidly. During Q1, AWS's growth rate was 28%. In Q4 2025, its growth rate was 24%. Rewinding to Q3 2025, its growth rate was 20%. That's some rapid acceleration over the past year, and considering Amazon is still pouring hundreds of billions of dollars into expanding its cloud computing capacity, I won't be surprised to see AWS' growth rate continue to accelerate over the next few quarters.
#computing


2 months ago
On August 24, ePlus (NASDAQ:PLUS) announced it had completed the acquisition of the **** ets of Daymark Solutions, a Massachusetts-based IT services provider, with the deal having closed three days earlier on August 21. The announcement landed three weeks after the company posted first-quarter fiscal 2027 results on August 4, showing sales climbing even as profit slipped. Together, the two headlines capture where ePlus stands right now: reaching for new growth in cloud and security while working through pressure on its existing business.
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first


2 months ago
Microsoft announced a new financial reporting structure on Wednesday, collapsing its three operating segments into two as artificial intelligence reshapes how the company organizes its business. The change takes effect in fiscal year 2027.
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents


2 months ago
On August 18, Commvault (NASDAQ:CVLT) expanded its Cloud Rewind platform, tripling the number of Microsoft Azure resource types it can protect and recover after a cyberattack or outage. The move follows the company's fiscal first quarter 2027 results, reported on July 28, when subscription revenue rose 16% year over year to $267 million. Together, the two updates show a company betting on cloud recovery as its next growth engine, even as some of the underlying numbers complicate that story.
Cloud Rewind sits at the center of that bet. The August update makes it three times more capable on Azure, reaching 62% of the enterprise-relevant resource types available on that cloud. The tool continuously discovers cloud resources, maps how applications depend on each other, and orchestrates rebuilding the infrastructure and configurations an app needs, not just its files. New Protection Groups tie application data and cloud configuration into one recovery workflow, and policy-based protection can auto-enroll resources by tag, region, and type instead of onboarding each one by hand. Allcargo Group, a logistics customer, said the tool let it restore its operational environment in hours.
That kind of speed lines up with how fast Commvault itself is growing: subscription annualized recurring revenue reached $1,054 million in the quarter, up 22% year over year, while SaaS revenue crossed $100 million for the first time, up 39%, and free cash flow jumped 71% to $51 million. Commvault also struck a multi-year deal with Microsoft to sell its resilience tools as a native service on Azure, and Gartner named it a Magic Quadrant Leader in backup and data protection for the 15th straight year.
The numbers also show where the strain sits. Commvault's GAAP operating margin was just 8.2% in the quarter, far below the 22.8% non-GAAP margin the company highlights, a gap wide enough to suggest real costs are being adjusted away. Guidance points to more of the same rather than acceleration: management expects second-quarter subscription revenue of $264 million to $268 million, essentially flat against the $267 million just reported, and it guided full-year non-GAAP EBIT margin to about 21%, below the 22.8% just posted.
Even the marquee Cloud Rewind expansion has a gap built in. Tripling Azure coverage still leaves the platform reaching 62% of enterprise-relevant resource types, meaning well over a third of what enterprises run on Azure sits outside its recovery net, and the announcement says nothing about extending that coverage to AWS or Google Cloud. For a company competing on breadth of recovery, that is a real limitation until it is addressed.
#year #recovery
Cloud Rewind sits at the center of that bet. The August update makes it three times more capable on Azure, reaching 62% of the enterprise-relevant resource types available on that cloud. The tool continuously discovers cloud resources, maps how applications depend on each other, and orchestrates rebuilding the infrastructure and configurations an app needs, not just its files. New Protection Groups tie application data and cloud configuration into one recovery workflow, and policy-based protection can auto-enroll resources by tag, region, and type instead of onboarding each one by hand. Allcargo Group, a logistics customer, said the tool let it restore its operational environment in hours.
That kind of speed lines up with how fast Commvault itself is growing: subscription annualized recurring revenue reached $1,054 million in the quarter, up 22% year over year, while SaaS revenue crossed $100 million for the first time, up 39%, and free cash flow jumped 71% to $51 million. Commvault also struck a multi-year deal with Microsoft to sell its resilience tools as a native service on Azure, and Gartner named it a Magic Quadrant Leader in backup and data protection for the 15th straight year.
The numbers also show where the strain sits. Commvault's GAAP operating margin was just 8.2% in the quarter, far below the 22.8% non-GAAP margin the company highlights, a gap wide enough to suggest real costs are being adjusted away. Guidance points to more of the same rather than acceleration: management expects second-quarter subscription revenue of $264 million to $268 million, essentially flat against the $267 million just reported, and it guided full-year non-GAAP EBIT margin to about 21%, below the 22.8% just posted.
Even the marquee Cloud Rewind expansion has a gap built in. Tripling Azure coverage still leaves the platform reaching 62% of enterprise-relevant resource types, meaning well over a third of what enterprises run on Azure sits outside its recovery net, and the announcement says nothing about extending that coverage to AWS or Google Cloud. For a company competing on breadth of recovery, that is a real limitation until it is addressed.
#year #recovery


2 months ago
AI is soaking up the headlines these days, but the cloud, while older news, remains a powerful force in the tech industry. Cloud services, such as AWS and Azure, are true giants, with many millions of subscribers and tens of billions in revenue. At the same time, the cloud, like AI, has been powering the rapid expansion of data centers.
Some numbers tell the tale. In 2025, per Markets and Markets, the cloud computing sector was valued at nearly $1.295 trillion. That's impressive, but it's also growing quickly, and is expected to reach $2.281 trillion as early as 2030, for a 12% CAGR through the forecast period.
Growth on that scale always generates solid investment opportunities, and the eye will naturally be drawn to the cloud giants. But Wall Street's **** ysts are reminding us of a basic truth in the stock game: that there are sound investments at every scale. They're saying to look under the radar, where we can find overlooked stocks that offer plenty of potential.
Promotion
55% Off TipRanks
#trillion #scale #wall
Some numbers tell the tale. In 2025, per Markets and Markets, the cloud computing sector was valued at nearly $1.295 trillion. That's impressive, but it's also growing quickly, and is expected to reach $2.281 trillion as early as 2030, for a 12% CAGR through the forecast period.
Growth on that scale always generates solid investment opportunities, and the eye will naturally be drawn to the cloud giants. But Wall Street's **** ysts are reminding us of a basic truth in the stock game: that there are sound investments at every scale. They're saying to look under the radar, where we can find overlooked stocks that offer plenty of potential.
Promotion
55% Off TipRanks
#trillion #scale #wall


2 months ago
MSFT earns a BUY rating and $610 price target as Azure crosses $100 billion in annual revenue with 43% growth and 45% guidance ahead.
GOOGL trades at just a 15 P/E versus MSFT's 29, while ORCL's rival growth came with $24 billion in negative free cash flow.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The trillion-dollar question hanging over Microsoft (NASDAQ:MSFT) is whether its $115.9 billion AI capex bet earns a return worthy of a mega-cap multiple, or ends up as the largest overbuild in tech history. That answer determines where the stock goes over the next twelve months.
Our 24/7 Wall St. price target for Microsoft is $609.58, implying 18.7% upside from the current price of $513.53. We rate the shares a buy with high confidence at 90%.
#earns
GOOGL trades at just a 15 P/E versus MSFT's 29, while ORCL's rival growth came with $24 billion in negative free cash flow.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The trillion-dollar question hanging over Microsoft (NASDAQ:MSFT) is whether its $115.9 billion AI capex bet earns a return worthy of a mega-cap multiple, or ends up as the largest overbuild in tech history. That answer determines where the stock goes over the next twelve months.
Our 24/7 Wall St. price target for Microsoft is $609.58, implying 18.7% upside from the current price of $513.53. We rate the shares a buy with high confidence at 90%.
#earns


2 months ago
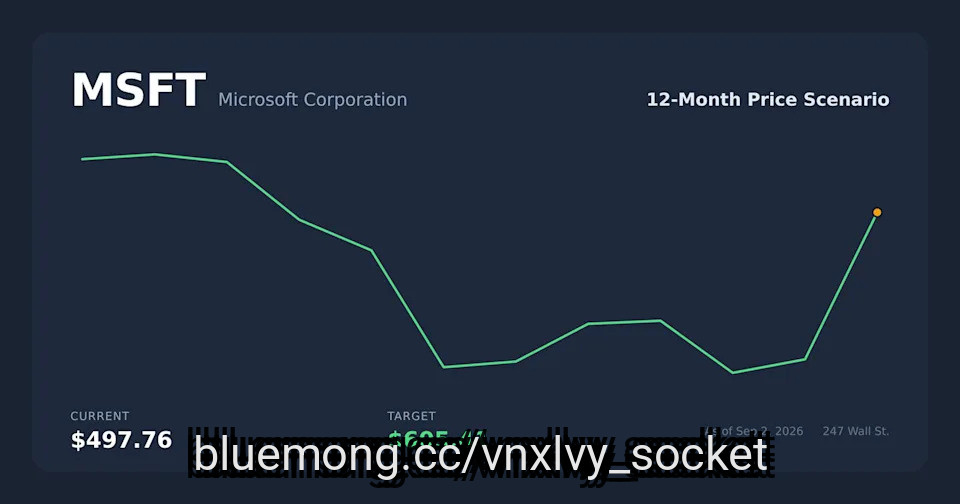
Microsoft (NASDAQ: MSFT) CEO Satya Nadella has enjoyed a tremendous increase in his total compensation over the past decade, with his pay rising from just $18 million in 2015 to $96.5 million at the end of fiscal 2025. That has made him one of the world's highest-paid CEOs.
The massive jump was the result of more than 95% of Nadella's pay being directly tied to performance stock units linked to Microsoft's shares. The better Microsoft stock performs, the higher Nadella's compensation becomes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
With Microsoft's stock surging 942% since 2015, it's no wonder Nadella's pay has accelerated. And as impressive as his pay is, the two reasons for Microsoft's growth over the past decade or so have been equally as remarkable.
When Nadella took over Microsoft in 2014, he famously shifted the company's focus to what he called a "mobile first, cloud first" approach. That meant funneling talent and capital into the company's cloud computing services, particularly Azure.
#Stock #nadella #past
The massive jump was the result of more than 95% of Nadella's pay being directly tied to performance stock units linked to Microsoft's shares. The better Microsoft stock performs, the higher Nadella's compensation becomes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
With Microsoft's stock surging 942% since 2015, it's no wonder Nadella's pay has accelerated. And as impressive as his pay is, the two reasons for Microsoft's growth over the past decade or so have been equally as remarkable.
When Nadella took over Microsoft in 2014, he famously shifted the company's focus to what he called a "mobile first, cloud first" approach. That meant funneling talent and capital into the company's cloud computing services, particularly Azure.
#Stock #nadella #past


2 months ago
Citizens' $515 price target for Alphabet Inc. (NASDAQ:GOOGL) may look like a stretch, sitting at a street-high above the $425 average. However, this aggressive target is based on something concrete, representing approximately 32 times its 2027 estimated GAAP earnings per share for the company.
Analyst Andrew Boone reiterated the target on August 26, along with a Market Outperform rating. As per the firm, the rating depends on Alphabet's consumer distribution across search, YouTube and Android platforms, with growth of Google Cloud Platform and the company's leading profit margins acting as supporting factors.
Photo by Kai Wenzel on Unsplash
While online advertising makes up a major part of Google's revenue, Google Cloud is becoming a major part of Alphabet Inc. (NASDAQ:GOOGL)'s business. Google Cloud's growth rate surged to 82% growth in Q2 2026, outpacing even Amazon Web Services and Microsoft Azure.
This growth rate was a sequential acceleration from the 63% growth rate reported in the first quarter and the 48% growth rate in the fourth quarter of 2025; largely driven by massive enterprise demand for artificial intelligence.
#rate #alphabet #cloud #rating
Analyst Andrew Boone reiterated the target on August 26, along with a Market Outperform rating. As per the firm, the rating depends on Alphabet's consumer distribution across search, YouTube and Android platforms, with growth of Google Cloud Platform and the company's leading profit margins acting as supporting factors.
Photo by Kai Wenzel on Unsplash
While online advertising makes up a major part of Google's revenue, Google Cloud is becoming a major part of Alphabet Inc. (NASDAQ:GOOGL)'s business. Google Cloud's growth rate surged to 82% growth in Q2 2026, outpacing even Amazon Web Services and Microsoft Azure.
This growth rate was a sequential acceleration from the 63% growth rate reported in the first quarter and the 48% growth rate in the fourth quarter of 2025; largely driven by massive enterprise demand for artificial intelligence.
#rate #alphabet #cloud #rating


2 months ago
BEIJING/SINGAPORE, Aug 26 (Reuters) - China's Moonshot AI is negotiating revenue-sharing agreements with Microsoft, Amazon and Alphabet's Google that would allow the U.S. cloud giants to host its blockbuster Kimi K3 model, three people familiar with the talks said.
Any deal could mark the first big revenue-sharing pact between a Chinese AI firm and a major U.S. cloud company.
The discussions highlight how China's leading AI models, often far cheaper than Western offerings, are gaining traction in the U.S., despite national security concerns in Washington that have led to bans on exports of AI chips to China. They are also taking place despite critical comments about Moonshot from senior U.S. officials.
IPO-bound Moonshot is seeking up to a 30% share of revenue generated from K3-related services on Microsoft's Azure, Amazon Web Services and Google Cloud, according to the sources who declined to be identified because the discussions are private.
That would be in line with terms that sources have said the startup has outlined for major customers using the open-weight model.
#revenue
Any deal could mark the first big revenue-sharing pact between a Chinese AI firm and a major U.S. cloud company.
The discussions highlight how China's leading AI models, often far cheaper than Western offerings, are gaining traction in the U.S., despite national security concerns in Washington that have led to bans on exports of AI chips to China. They are also taking place despite critical comments about Moonshot from senior U.S. officials.
IPO-bound Moonshot is seeking up to a 30% share of revenue generated from K3-related services on Microsoft's Azure, Amazon Web Services and Google Cloud, according to the sources who declined to be identified because the discussions are private.
That would be in line with terms that sources have said the startup has outlined for major customers using the open-weight model.
#revenue

2 months ago
MSFT earns a BUY with a $590 price target as Azure crosses $100B in annual revenue and Copilot surpasses 30 million paid seats.
AMZN trades at P/E 36 versus MSFT's 27 despite AWS growing slower than Azure's 43%, making the $590 target look conservative.
Full-year capex hit $116B while free cash flow fell 23%, but net income still grew 31%, making demand normalization the lone bear-case risk.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft has become the quiet outlier in the AI trade. While NVIDIA (NASDAQ:NVDA) absorbs the spotlight and hyperscaler rivals chase headlines, Microsoft (NASDAQ:MSFT) is quietly compounding the deepest enterprise AI moat in software.
#Microsoft #free #making #azure
AMZN trades at P/E 36 versus MSFT's 27 despite AWS growing slower than Azure's 43%, making the $590 target look conservative.
Full-year capex hit $116B while free cash flow fell 23%, but net income still grew 31%, making demand normalization the lone bear-case risk.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft has become the quiet outlier in the AI trade. While NVIDIA (NASDAQ:NVDA) absorbs the spotlight and hyperscaler rivals chase headlines, Microsoft (NASDAQ:MSFT) is quietly compounding the deepest enterprise AI moat in software.
#Microsoft #free #making #azure


2 months ago
Microsoft (MSFT) cut a $6.8 billion dividend check in fiscal year 2026 while spending $116 billion on AI capex, an amount 4.5 times greater.
Applied Materials (AMAT) led the other 25 ex-dividend companies that same day at $421 million, less than 7% of Microsoft's single-day payout.
Amy Hood committed to staying free cash flow positive in FY2027 even as capex could reach $175 billion, with Azure already crossing $100 billion in annual revenue.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) went ex-dividend on August 20, 2026 at $0.91 a share, cutting a check to holders of record for $6,757,245,950, payable September 10, 2026. That single distribution was the largest of the 26 companies going ex-dividend that day, and it dwarfed the runner-up: Applied Materials (NASDAQ:AMAT) at $420,798,270. Marriott (NASDAQ:MAR), SBA Communications (NASDAQ:SBAC), and LKQ (NASDAQ:LKQ) also went ex-dividend the same day, but none came close to Microsoft's scale.
#Microsoft #billion #amat
Applied Materials (AMAT) led the other 25 ex-dividend companies that same day at $421 million, less than 7% of Microsoft's single-day payout.
Amy Hood committed to staying free cash flow positive in FY2027 even as capex could reach $175 billion, with Azure already crossing $100 billion in annual revenue.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) went ex-dividend on August 20, 2026 at $0.91 a share, cutting a check to holders of record for $6,757,245,950, payable September 10, 2026. That single distribution was the largest of the 26 companies going ex-dividend that day, and it dwarfed the runner-up: Applied Materials (NASDAQ:AMAT) at $420,798,270. Marriott (NASDAQ:MAR), SBA Communications (NASDAQ:SBAC), and LKQ (NASDAQ:LKQ) also went ex-dividend the same day, but none came close to Microsoft's scale.
#Microsoft #billion #amat



2 months ago
According to Rosenblatt's Scott Devitt, Amazon (NASDAQ:AMZN)'s leading position in artificial intelligence remains underappreciated. This bold claim was made in a recent research note on August 19, where Devitt initiated coverage on the stock with a $335 price target.
The firm anticipates AWS to exit 2026 at a 45% growth rate, compared with the Street's 38% expectations. The firm further noted that AWS is seen on a path to $335 billion by 2028.
The AWS acceleration claim is supported by recent numbers. AWS growth has climbed for five consecutive quarters, from 17% in Q2 2025 to 37% in Q2 2026. This strengthens the argument that AI demand is adding another growth cycle. Amazon's Q2 fiscal 2026 results filed July 30, 2026 also showed AWS accelerating to $42.23 billion, its fastest pace in 18 quarters. AWS backlog, meanwhile, stood at $496 billion, growing triple digits year-over-year. The company's AI and Chips businesses also each cleared $25 billion annualized run rates in Q2 with triple-digit growth.
AWS's 37% growth may be the best it has gained in years, but it is still the slowest of the Big Three hyperscalers. Google Cloud grew 82%, Azure grew 43%, while AWS grew 37%. AWS grew at less than half the pace of Alphabet Inc.'s (NASDAQ:GOOGL) Google Cloud unit, and also trailed behind Microsoft's Azure.
Google Cloud's 82% growth is not a one-quarter spike, rather, the unit also witnessed growth of 63% year-over-year in the first quarter of 2026. For Azure, Microsoft Corporation (NASDAQ:MSFT) only posts the growth rate, and revenue for the full fiscal 2026 cross $100 billion, putting it behind AWS and ahead of Google Cloud. Looking at the growth percentages, it seems that AWS is the laggard of the three. However, AWS brings in far more revenue overall. It brought $42.2 billion in revenue last quarter, putting it on a $169 billion annualized run rate. This makes AWS larger in size, and its also adding more actual dollars in revenue than Google Cloud each quarter because of its much larger base.
#billion #NASDAQ #grew #azure
The firm anticipates AWS to exit 2026 at a 45% growth rate, compared with the Street's 38% expectations. The firm further noted that AWS is seen on a path to $335 billion by 2028.
The AWS acceleration claim is supported by recent numbers. AWS growth has climbed for five consecutive quarters, from 17% in Q2 2025 to 37% in Q2 2026. This strengthens the argument that AI demand is adding another growth cycle. Amazon's Q2 fiscal 2026 results filed July 30, 2026 also showed AWS accelerating to $42.23 billion, its fastest pace in 18 quarters. AWS backlog, meanwhile, stood at $496 billion, growing triple digits year-over-year. The company's AI and Chips businesses also each cleared $25 billion annualized run rates in Q2 with triple-digit growth.
AWS's 37% growth may be the best it has gained in years, but it is still the slowest of the Big Three hyperscalers. Google Cloud grew 82%, Azure grew 43%, while AWS grew 37%. AWS grew at less than half the pace of Alphabet Inc.'s (NASDAQ:GOOGL) Google Cloud unit, and also trailed behind Microsoft's Azure.
Google Cloud's 82% growth is not a one-quarter spike, rather, the unit also witnessed growth of 63% year-over-year in the first quarter of 2026. For Azure, Microsoft Corporation (NASDAQ:MSFT) only posts the growth rate, and revenue for the full fiscal 2026 cross $100 billion, putting it behind AWS and ahead of Google Cloud. Looking at the growth percentages, it seems that AWS is the laggard of the three. However, AWS brings in far more revenue overall. It brought $42.2 billion in revenue last quarter, putting it on a $169 billion annualized run rate. This makes AWS larger in size, and its also adding more actual dollars in revenue than Google Cloud each quarter because of its much larger base.
#billion #NASDAQ #grew #azure
2 months ago
Microsoft Corporation (NASDAQ:MSFT)'s shares have witnessed a major turnaround in 2026. They are up by 2% year-to-date, primarily on the back of 23.7% gain since late July. The shares closed a strong 15.5% higher on July 30th, the day after Microsoft Corporation (NASDAQ:MSFT) reported its fiscal fourth quarter earnings. The results saw the firm beat ***** yst revenue and earnings estimates, and more importantly, its Azure cloud computing business saw revenue jump by 43% annually to beat even the most optimistic ***** yst estimates. With investors focused on AI returns, Microsoft Corporation (NASDAQ:MSFT)'s shares were rewarded. On August 17th, Cramer discussed the earnings and their impact:
"Yeah that's gutsy. I think a lot of people hanging their hat on that. Because, they do so much good work. But, of the, of the Magnificent 7, that's the one that, I think is still kind of vulnerable. After Microsoft did that tour de force conference call. The Microsoft conference call was maybe the best conference call in the quarter. Because it turned a huge cohort of people in favor of it versus against it. We didn't see that with Google and we're still waiting for it with Meta. I still believe that if Mark Zuckerberg wanted to, he could take that stock off the near 52 week low. . .and turn it around. But he needs to say, you know what, I've really thought about this. And we're going to rent out. Because we have so much demand and then they name like three companies that need some of their cloud business. I wish they could finish that thing in Louisiana."
Additionally, Microsoft Corporation (NASDAQ:MSFT) shared two key updates for its cloud computing and AI initiatives. The firm guided 45% in Azure growth for the first quarter to beat estimates. CEO Satya Nadella also remarked that Microsoft Corporation (NASDAQ:MSFT) had achieved efficiency gains of as much as 40% through using custom chips and external AI technologies. Overall, the firm's operating margin sat at 45% to fuel the bullish viewpoint of AI profitability and strong execution.Commercial bookings decelerated to 12% as CapEx jumped 35% ($13.87B), driving a 23% drop in free cash flow and signaling margin compression risks.
Commercial bookings decelerated to 12% as CapEx jumped 35% ($13.87B), driving a 23% drop in free cash flow and signaling margin compression risks.
As for Meta Platforms, Inc. (NASDAQ:META), the shares are down by 15.5% year-to-date. As is the case with MSFT, the debate for the firm is also about AI and whether the spending will yield results. However, unlike MSFT, Meta Platforms, Inc. (NASDAQ:META) does not have a cloud computing business. Therefore, all focus is on its advertising business and the tailwinds it generates courtesy of AI. Naturally, Cramer also discussed this aspect as he commented on the firm renting out cloud capacity. Overall, the firm's Q2 advertising revenue jumped by 27% while its ad impressions jumped by 14% and the firm guided as much as 17% annual growth
"Yeah that's gutsy. I think a lot of people hanging their hat on that. Because, they do so much good work. But, of the, of the Magnificent 7, that's the one that, I think is still kind of vulnerable. After Microsoft did that tour de force conference call. The Microsoft conference call was maybe the best conference call in the quarter. Because it turned a huge cohort of people in favor of it versus against it. We didn't see that with Google and we're still waiting for it with Meta. I still believe that if Mark Zuckerberg wanted to, he could take that stock off the near 52 week low. . .and turn it around. But he needs to say, you know what, I've really thought about this. And we're going to rent out. Because we have so much demand and then they name like three companies that need some of their cloud business. I wish they could finish that thing in Louisiana."
Additionally, Microsoft Corporation (NASDAQ:MSFT) shared two key updates for its cloud computing and AI initiatives. The firm guided 45% in Azure growth for the first quarter to beat estimates. CEO Satya Nadella also remarked that Microsoft Corporation (NASDAQ:MSFT) had achieved efficiency gains of as much as 40% through using custom chips and external AI technologies. Overall, the firm's operating margin sat at 45% to fuel the bullish viewpoint of AI profitability and strong execution.Commercial bookings decelerated to 12% as CapEx jumped 35% ($13.87B), driving a 23% drop in free cash flow and signaling margin compression risks.
Commercial bookings decelerated to 12% as CapEx jumped 35% ($13.87B), driving a 23% drop in free cash flow and signaling margin compression risks.
As for Meta Platforms, Inc. (NASDAQ:META), the shares are down by 15.5% year-to-date. As is the case with MSFT, the debate for the firm is also about AI and whether the spending will yield results. However, unlike MSFT, Meta Platforms, Inc. (NASDAQ:META) does not have a cloud computing business. Therefore, all focus is on its advertising business and the tailwinds it generates courtesy of AI. Naturally, Cramer also discussed this aspect as he commented on the firm renting out cloud capacity. Overall, the firm's Q2 advertising revenue jumped by 27% while its ad impressions jumped by 14% and the firm guided as much as 17% annual growth

2 months ago
Microsoft's $678 billion commercial backlog and Azure's explosive growth underpin a $590 price target implying 22% upside.
MSFT's $332 billion in recurring revenue tops NVDA's total, while GOOGL trades cheaper at a forward P/E of 17 versus MSFT's 24.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) has spent the last year alongside NVIDIA (NASDAQ:NVDA) as the two poster children of the AI trade. But Microsoft has one thing Nvidia does not: a $678 billion contracted commercial backlog that turns AI demand into recurring, subscription-grade revenue.
Our 24/7 Wall St. price target for Microsoft is $590.43, and that backlog is a big reason the model sees room to run.
#NASDAQ #recurring
MSFT's $332 billion in recurring revenue tops NVDA's total, while GOOGL trades cheaper at a forward P/E of 17 versus MSFT's 24.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) has spent the last year alongside NVIDIA (NASDAQ:NVDA) as the two poster children of the AI trade. But Microsoft has one thing Nvidia does not: a $678 billion contracted commercial backlog that turns AI demand into recurring, subscription-grade revenue.
Our 24/7 Wall St. price target for Microsoft is $590.43, and that backlog is a big reason the model sees room to run.
#NASDAQ #recurring