

1 hr. ago
Altria has raised its dividend 61 times in 57 years and yields ~6%, while Realty Income has raised its payout 115 consecutive quarters and yields ~6%.
Kinder Morgan carries a $9.6 billion project backlog, over 60% tied to power generation, while AT&T uses just 46% of adjusted EPS to fund its dividend.
VICI Properties yields ~7.5% with 100% portfolio occupancy and 39.6-year average lease terms, but its stock trades well below the average **** yst target of $31.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Retirees need two things from a dividend stock: the check must arrive on schedule, and it must grow faster than the cost of groceries. This month's list covers five cash-generating businesses in five different industries: tobacco, net-lease real estate, gaming real estate, natural gas pipelines, and telecom. In every case, earnings or cash flow will cover the payout, and each company has years of payment history behind it. Several of them pay in November, including Realty Income (NYSE:O), whose next monthly dividend of $0.2715 a share is scheduled to arrive on November 13.
#november #raised


1 hr. ago
College-town states like Ohio (93) and Tennessee (92) beat Florida's (103) cost-of-living index, cutting a retired couple's required savings by over $205,000.
Pennsylvania exempts 401(k) and IRA withdrawals from its 3.07% flat income tax for qualifying retirees, while Ohio taxes non-Social Security income above $26,050.
Ohio residents 60 and older can audit Ohio State courses tuition-free and access a major academic medical center, though game days and student rents add real trade-offs.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Most people who talk about where to retire end up on the coast. Florida ranked first in net adjusted gross income gained through state-to-state moves in IRS migration data for 2022-2023, at $20.6 billion. The less talked-about option is a town built around a university.
#college #Social #security


1 day ago
Welcome to Week 8 of the fantasy football season! Below I have some players I think you should start and some I think you should sit. As usual, your mileage may vary depending on your available choices, so don't just blindly bench someone if you don't have a better option!
Houston Texans, New Orleans Saints, New York Giants, and San Francisco 49ers
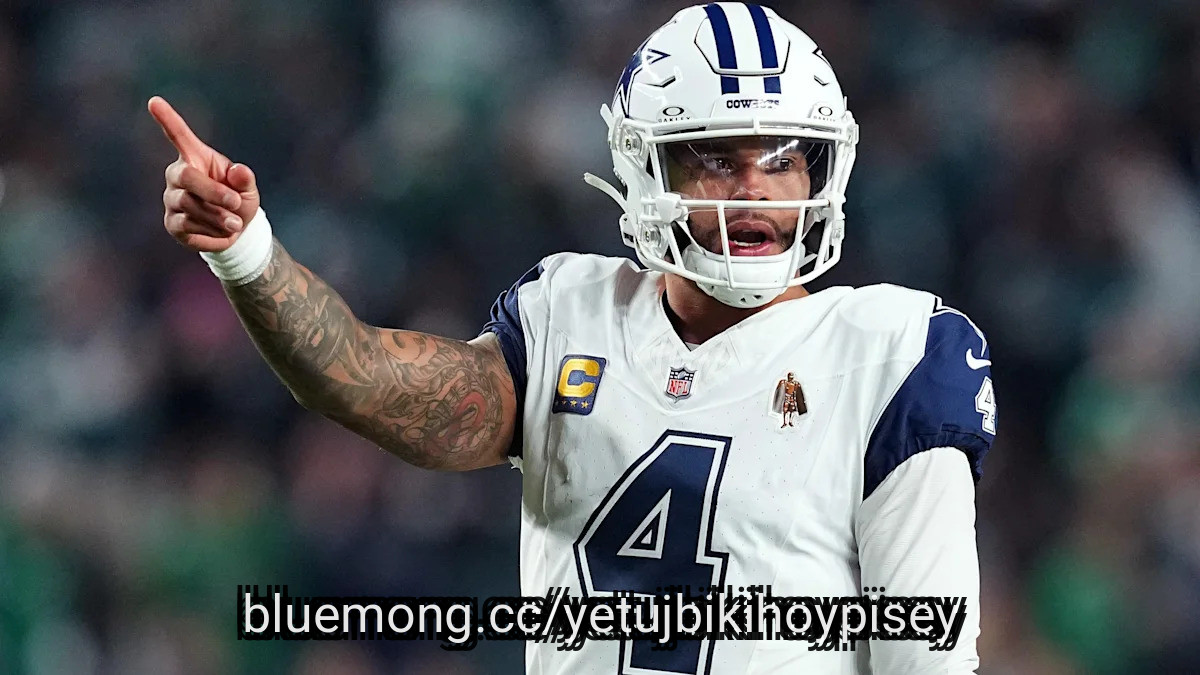
Prescott has been up and down this season, but he's coming off a strong Monday night game against the Eagles and now faces a bad Cardinals pass defense. Arizona has given up the most adjusted yards per attempt, the most receiving touchdowns, the second worst QB rating, and the second most yards per completion. Prescott is poised to pick up where he left off on Monday night.
If the Cardinals had better backup quarterbacks, I would be worried that Brissett might be benched during a game, but they don't. This week, as long as Brissett plays the whole game, it will be difficult for him not to accumulate fantasy points. I expect the Cowboys will be able to score on the Cardinals, while Brissett inefficiently tries to keep up through the air. Dallas, so far, has allowed the third worst completion percentage, the seventh worst average yards per attempt, and the third-worst yards per completion to opposing quarterbacks.
Murray continued to play poorly last week, but the Vikings also continued to win. Not trailing in games hurts Murray, as he doesn't need to run and throw as much to try to make up points. This week they'll face a Lions offense that should have more success against Brian Flores' top defense than any team this year. The Lions defense also remains the absolute worst at giving up fantasy points to quarterbacks. That has a lot to do with the Lions keeping teams throwing the ball from a deficit, but the results are hard to ignore.
#brissett

2 days ago
June Jones, the cutting-edge coach who brought the run-and-shoot offense to Hawaii and led the Rainbow Warriors to their greatest era and an undefeated regular season that catapulted them all the way to the Sugar Bowl, died on Thursday. He was 73.
Hawaii's football program in a statement did not list a cause of death for Jones, who coached the Atlanta Falcons for three seasons in the 1990s before his stint at Hawaii. The Honolulu Star-Advertiser cited a close family friend as saying Jones had entered hospice two weeks ago in his native Oregon.
"Coach Jones was a father figure, a mentor, and a visionary who revolutionized the game," said Timmy Chang, the current Hawaii coach who set the NCAA record for career passing yards (since broken) under Jones. "He believed in a young kid from Hawaii and gave me the opportunity of a lifetime to run his offense."
Hawaii was one of three schools where Jones played quarterback in college, but it was his decision to transfer to Portland State that shaped the rest of his football career.
He played under Mouse Davis, who is largely credited with bringing to the big-time an offense that featured four receivers who adjusted their routes on the fly, rarely ran the football and, most of all, moved fast.
#jones #hawaii #Career #played


23 days ago
Taylor Swift and Travis Kelce's plans for a more private Ohio retreat have run into some very public objections. Neighbors of the $5.35 million Lake Erie estate are challenging proposed landscaping and fencing, raising concerns about a shared sewer line, wildlife, and how the changes could affect their longtime homes.
A six-foot fence has already received approval, but parts of the landscaping remain unresolved. The property's representatives, meanwhile, say they have adjusted the plans, paid for sewer repairs and added gates to accommodate residents.
ZUMAPRESS.com / MEGA
According to the Daily Mail, the dispute centers on an estate in Bratenahl, a village outside Cleveland. Property records cited by the outlet show that an LLC linked to Kelce purchased the mansion in March. The 21,000-square-foot property features eight bedrooms, 11 bathrooms, and a two-bedroom guest cottage. Built in 1895, it also has a former ballroom converted into a game room and home theater.
But proposed changes to the grounds have become a sticking point with nearby residents. Katherine Bolton, who has lived next door for 35 years, described news of the new owners as a "tremendous blow" to "the peace and quiet in Bratenahl."
#estate



23 days ago
For an average single person planning to stop working at 64, a $1.2 million 401(k) account and $2,800 Social Security benefit could provide enough income to make ends meet during retirement. Widely used guidelines suggest your annual income may be around $81,600, which may or may not be more than your annual expenses. Much depends on individual circumstances, including the kind of retirement lifestyle you desire, your location and future trends of inflation, taxes and investment returns. To get a comprehensive workup of your retirement budget, take the question to a financial advisor.
Income and expenses represent the two sides of your retirement budget. Both are equally important and decisions you make regarding either can affect the overall accuracy and dependability of the budget.
You can estimate expenses by using averages for typical retirees or by considering specifics of your situation with estimate for categories such as housing, healthcare and taxes. Similarly, you can estimate future income with general guidelines or by accounting for specifics such as your personal investment preferences.
In your case, we'll start with income since we have information about that. Despite the possibility that Social Security benefits will be cut by about 20% after 2035, your $2,800 Social Security benefit can probably be relied upon. And benefits are indexed to a cost-of-living benchmark, providing protection against inflation.
Note, however, that if you wait to claim benefits, your monthly amount will increase every year until you are 70. By claiming at age 64 rather than waiting until your full retirement age of 67, you are receiving 20% less. If you wait until age 70, you'll get 24% more than at 67. And you'll receive the higher amount, adjusted annually for cost of living, as long as you live.
#Retirement #benefits

23 days ago
Amcor plc (NYSE:AMCR) isn't a flashy business. Most people probably don't know much about the company, even though they come across its products every day. The company makes the packaging used for food, drinks, healthcare products, beauty products, and plenty of other everyday items.
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE

24 days ago
The 2020s will go down in history as one of the best times to be a stock market investor. After a brief dip in 2022, the benchmark S&P 500 (SNPINDEX: ^GSPC) has soared by an average of roughly 21% per year -- double its 100-year average annual return of 10%.
That said, history shows us that significant drawdowns often follow periods of unusually elevated stock market gains as the market reverts to its long-running mean. Let's discuss some of the challenges facing this bull market to try to figure out what might come next.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By now, most investors have probably heard about the cyclically adjusted price-to-earnings (CAPE) ratio. This metric compares the price of the S&P 500 with its average inflation-adjusted earnings over the past decade. The long time frame smooths out short-term fluctuations, providing a clearer picture of the market's value relative to historical norms.
Right now, the CAPE ratio stands at 40.5, which is well above its average of 17.4. The other two major peaks occurred before the Great Depression in 1929 and during the dot-com bubble in 1999, when it hit its all-time high of 44.19. Both milestones were followed by substantial declines in equity prices over the subsequent years as the speculative bubbles deflated.
#missed #Stock #long #investors

24 days ago
When a farm sells for a lump sum, IRS rules split proceeds across five ******* et types, and only market cattle profits count as Social Security self-employment earnings.
In a hypothetical sale generating $500,000 in gains, only $100,000 from market cattle counts toward Social Security's earnings test, while land and equipment gains register $0.
Land gains escape the Social Security earnings test but still raise adjusted gross income, potentially making up to 85% of benefits taxable.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Freeman Family Ranches covered 87,953 acres across the North Texas and Oklahoma panhandles. The three properties, in the family for four generations, sold in late July after being listed at nearly $128 million.
#Social #gains #family #market

24 days ago
Realty Income (NYSE: O) buyers who entered at the 2013 acquisition milestone turned $1,000 into $2,444, a 144% total return through October 2026.
Buying when Realty Income joined the Dividend Aristocrats in 2020 at $54.21 left investors with just 0.07% total return after six years, as dividends failed to offset share price decline.
Prestige-driven entries consistently underperformed, while the best recent result came after shares already fell, with the 2024 Spirit Realty entry returning 13%.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Realty Income (NYSE:O) built its reputation on reliable monthly income. (Seven of our favorite monthly payers are rounded up in this free report.) Among the key milestones discussed here, its first two were excellent entry points; the three that followed were poor ones. Each return below runs from the milestone's adjusted price to the October 6, 2026, close of $54.25, adjusted for splits and dividends.
#income #october #dividends #price

24 days ago
XOM has raised its dividend for 43 straight years, while CVX yields 3.45% with Hess acquisition synergies running 50% above initial targets.
EPD's distributable cash flow covered its 6% distribution 1.9x last quarter, with a trailing payout ratio of just 56% on adjusted cash flow.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Energy has a reputation for boom and bust, yet the sector's largest companies have turned volatile commodities into some of the market's most reliable income. Exxon Mobil (NYSE:XOM) alone has grown its annual dividend per share for 43 consecutive years. The four large caps below split into two integrated oil majors and two midstream toll-road operators. Each pairs a well-covered payout with strong cash generation, making them natural candidates for a long-term income portfolio.
At a recent price of $163.83, Exxon's annualized forward dividend of $4.12 per share works out to a 2.51% yield. The quarterly payout is $1.03, up from $0.99 after a 4% raise late last year.
#income

24 days ago
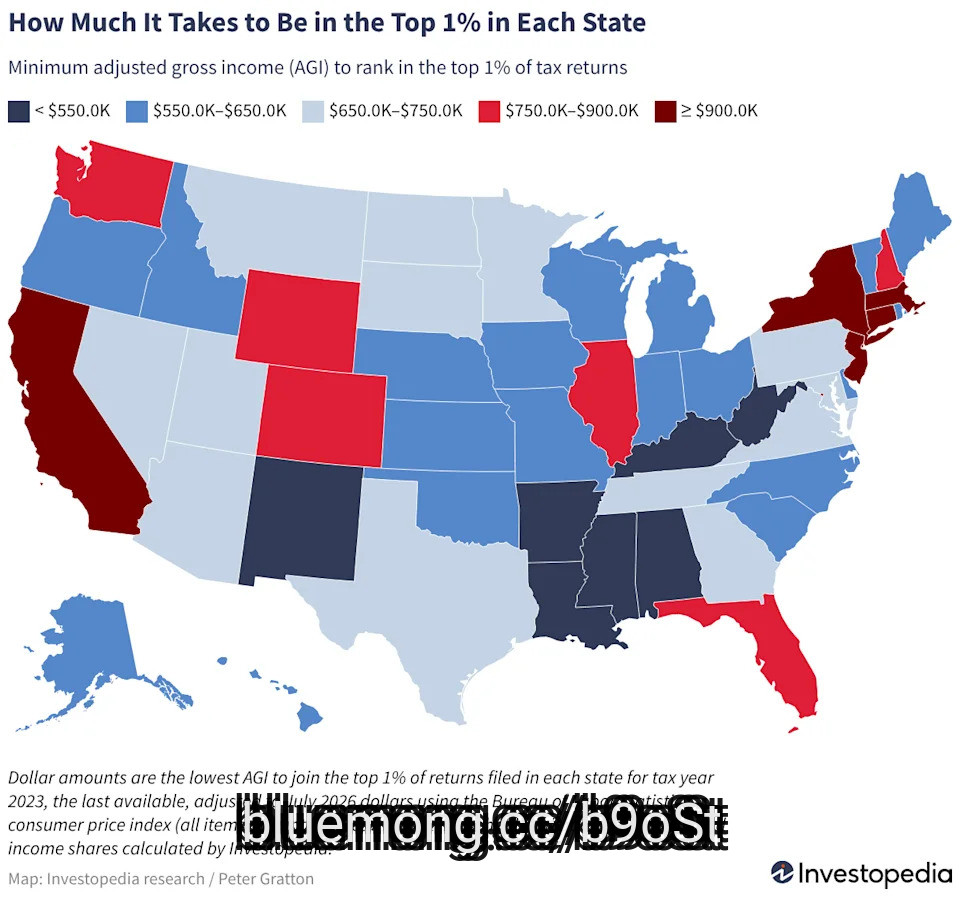
Newly released IRS data put the top-1% cutoff at about $748,000 nationally, ranging from about $426,000 in West Virginia to $1.1 million in Washington, D.C.
Only D.C. and Connecticut clear $1 million; nationally, the cutoff rose less than inflation in the latest year.
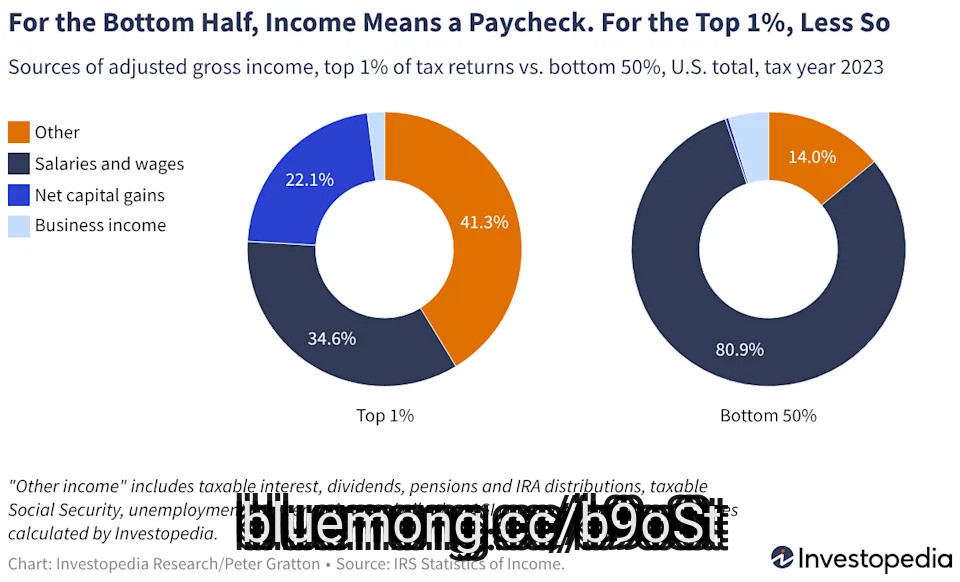
Wages make up 81% of income for the bottom half of filers, but just 35% for the top 1%, with capital gains accounting for another 22%.
The top 1% starts in a very different place depending on where you file your taxes.
The IRS's newly released state data put the income floor for the top 1% nationally at about $748,000 in adjusted gross income (AGI), according to an Investopedia **** ysis. The data was from 2023 but adjusted to 2026 dollars. In D.C., it takes about $1.1 million, while in West Virginia, it's about $426,000.
#income

25 days ago
Investors aren't exactly short on reasons to worry.
The Shiller cyclically adjusted price-to-earnings (CAPE) ratio, which measures stock prices against 10-year inflation-adjusted earnings, and the Buffett indicator, the ratio of stock prices to GDP, show that the S&P 500 (SNPINDEX: ^GSPC) is historically expensive. Leadership has been extraordinarily concentrated in megacap tech stocks. Inflation is well above 3%. Long-term Treasury yields are at multidecade highs. And beneath the surface of the major indexes, market breadth has weakened considerably.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Any one of those could sound like a reason to prepare for the next market crash. But decades of stock market history suggest investors may be obsessing over the wrong things.
Instead of asking if and when stock prices will fall next, I'd ask a much simpler question: How long can you stay invested?
#earnings


25 days ago
What if I told you that the biggest risk from the next market crash isn't the crash itself? It might be what investors do to their portfolios to try to avoid the crash.
In today's economic environment, there are legitimate reasons for concern. Inflation is high. Oil prices have soared. Interest rates are on the rise. The Shiller CAPE ratio, which measures stock prices relative to inflation-adjusted earnings over the past 10 years, is at its second-highest level of all time.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But selling stocks and moving to cash to avoid the decline creates a whole new set of problems. First, you have to be correct in your prediction that a crash is coming and the timing of it. Second, you have to decide when the right time is to get back into stocks (and have the actual discipline to do it).
I'd rather own an ETF that gives me the confidence to remain invested in stocks through the crash.
#missed #investors #prices


1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

1 month ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
1 month ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

1 month ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
1 month ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue
1 month ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo

1 month ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
1 month ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


1 month ago
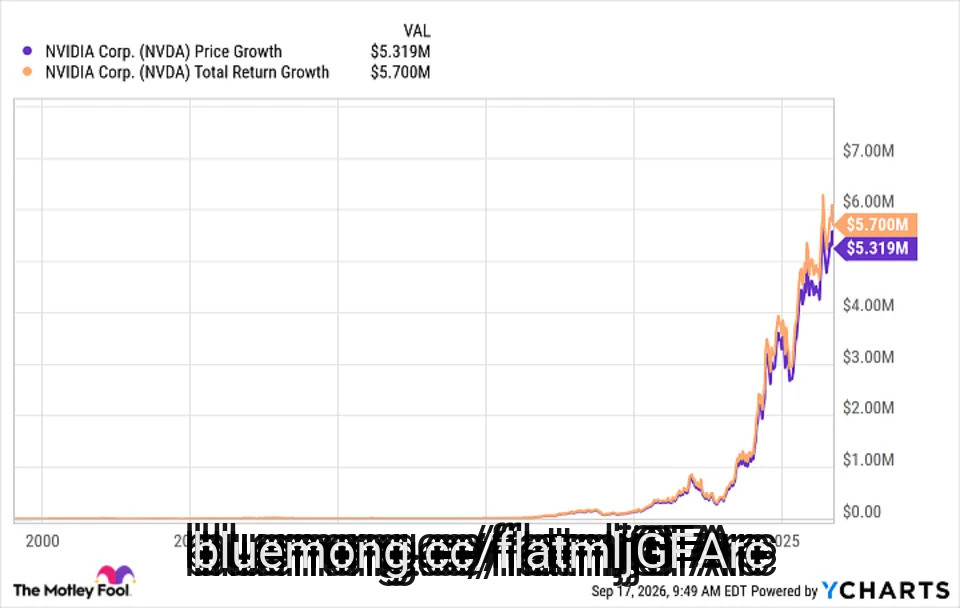
Nvidia (NASDAQ: NVDA) is one of the most successful stocks in history. Since launching its IPO in 1999, the stock has earned unprecedented returns, especially considering the 27-year time frame. So high are the gains that an investment of $1,000 at that time would deliver millions.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The semiconductor stock launched its IPO on Jan. 22, 1999, at a split-adjusted price of $0.025 per share. At the time, that would have bought 40,000 split-adjusted shares worth $5.32 million. Add in the dividend income over that time, and the overall total grows to $5.70 million.
NVDA data by YCharts
Nvidia made its initial fortune as a leader in graphics cards. It later moved on to GPUs and, later, AI accelerators, which have made it an industry-leading chip stock. With that, it won the AI training race, or at least the first phase of it.
#missed #phase

1 month ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record

1 month ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
1 month ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year

1 month ago
On Sept. 15, 2016, Shopify (NASDAQ:SHOP) stock closed at a split-adjusted $4.18 per share. As of this writing, shares trade around $130. That comes out to about 31 times the initial investment -- enough to make a $10,000 stake bought that day worth about $311,000 today.
And because Shopify does not pay a dividend, the share price did all the work.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
For comparison, the S&P 500 (SNPINDEX:^GSPC) had an outstanding decade of its own. The same $10,000 in an index fund that tracks the benchmark, with dividends reinvested, would have become about $41,000 during that period.
Most investors would be delighted with that outcome. Shopify's was more than seven times better.
#sept



