

25 days ago
Florida exempts a $600,000 IRA from Medicaid's $2,000 ***** et limit once the account enters payout status through RMDs or regular distributions.
Every IRA distribution counts as income against Florida's $2,982 monthly cap, and nearly all of it goes directly to the nursing home.
A named IRA beneficiary keeps the remaining balance out of probate, blocking Florida's estate recovery claim under Fla. Stat. § 409.9101.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A Florida retiree entering long-term care with $600,000 in her IRA looks like an automatic Medicaid denial. A single applicant there can't hold more than $2,000 in countable ***** ets. Thankfully, Florida's IRA Medicaid rules leave a narrow opening: once a retirement account is in payout status, the state can exclude the balance from the ***** et count. This means withdrawals still count, each distribution is treated as income, and that income ends up paying most of her nursing home bill.
#Florida #once #account

1 month ago
Teck Resources Ltd (NYSE:TECK) stock's pullback from its Sept. 8 record high of $72.56 has found support at the 60-, 80-, and 100-day moving averages. The 100-day trendline in particular is a historically bullish signal that presents an intriguing 'buy the dip' angle.
Per Schaeffer's Senior Quantitative ******* yst Rocky White, TECK has traded within 0.75 times the 100-day moving average's 20-day average true range (ATR) after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above the trendline. This setup has occurred eight other times over the last decade, after which the stock was higher one month later 75% of the time, averaging a large 13.8% gain.
Short interest accounts for a healthy 7.5% of the stock's available float, leaving ample sideline buying power should some of these bearish bets begin to unwind. TECK's 14-day Relative Strength Index (RSI) of 28.4 also sits in "oversold" territory, which often precedes a short-term bounce.
Plus, TECK's Schaeffer's Volatility Scorecard (SVS) sits at 81 out of 100, suggesting the shares have tended to outperform options traders' volatility expectations during the past year.
#resources

2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Space Exploration Technologies Corp. CEO Elon Musk has reaffirmed that the commercial ***** eflight company will put NVIDIA Corp's orbital AI computing system in ***** e by next year.
On Sunday, user RyanFox.eth took to the social media platform X, referencing an unnamed YouTuber saying that data centers in ***** e could become a reality by 2035 if the cooling aspect were solved. "People really don't get it," the user said.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#space #exploration
2 months ago
Most of the media hype goes to Nvidia, Broadcom, Google and the other major AI plays. We dug deeper into billionaire Ray Dalio's Bridgewater ******* ociates Q2 13F filings to see what new AI stocks the fund was buying.
ServiceNow, Inc. (NYSE:NOW) was one of them. Bridgewater opened a position of about 635,000 shares worth roughly $63 million, a 0.26% portfolio weight. Nutanix, Inc. (NASDAQ:NTNX) was the other. The fund bought about 999,000 shares worth roughly $51 million, a 0.21% weight.
NOW regularly gets the limelight in the media, so let's focus on NTNX. The stock is down 11% over the past year.
Nutanix ended fiscal 2026 with recurring revenue of $2.55 billion, up 16%, and added more than 3,000 new customers during the year.
Why Nutanix's business can keep growing
#nutanix #ntnx #roughly #million

2 months ago
Salesforce (CRM) trades at 20.6 times earnings, below the S&P 500 median of 22.6, after losing 2.8% over the past twelve months while the index gained 17.9%. A profitable software company priced under the market is the setup value buyers wait for. The question is whether that is a good business on sale or a fair price for a legacy platform facing disintermediation from next-generation AI architectures.
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
2 months ago
HIVE Digital Technologies, a Canada-based Bitcoin miner and data center operator that trades on the Nasdaq and Toronto Stock Exchange, has appointed Mark Volk as Senior Vice President of Revenue at BUZZ HPC, its wholly owned AI cloud and high-performance computing subsidiary.
Volk's mandate is to build BUZZ HPC's revenue engine and scale it globally. He will lead the company's go-to-market strategy across enterprise, government, sovereign AI, hyperscale, research and academic markets, overseeing commercialization of its GPU-powered infrastructure, including sovereign AI cloud, GPU-as-a-Service, colocation and hybrid AI solutions.
Related: Elon Musk warns 'if the ship of America sinks, we all sink with it'
Volk brings roughly 30 years of experience across AI, high-performance computing, cloud and enterprise infrastructure.
He is not a new face internally, he has worked with HIVE as a consultant for approximately nine months, during which he helped build BUZZ HPC's current GPU cloud demand pipeline.
#buzz #volk #performance #across

2 months ago
Annuity payouts look higher because they blend interest with returned principal, but a dividend portfolio keeps your capital invested and available to heirs.
AT&T cut its dividend in 2022 and has held it flat since, while Duke Energy targets 5% to 7% annual EPS growth through 2030.
Splitting $930,000 between an annuity covering fixed expenses and a dividend portfolio for growth offers a viable third path beyond the binary choice.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
You have $930,000 and one question: Does an insurance company writing a lifetime check produce more monthly income than a dividend portfolio you control? Most of the confusion comes from comparing two numbers that do not measure the same thing.
#Dividend

2 months ago
This story was originally published on QSR. To receive daily news and insights, subscribe to our free daily QSR AM Jolt.
SupplyCaddy has received growth investment from CEAS Investments, which is a partner in the business.
Established in 2020, SupplyCaddy supplies customised packaging and supply chain services to restaurant groups.
It currently works with more than 70 brands, among them sweetgreen, Dave's Hot Chicken, Huey Magoo's and Burger King, covering over 6,500 sites in North America and nine overseas markets.
The business collaborates with foodservice distribution groups such as Sysco, US Foods, Gordon Food Service, Performance Food Group, Imperial Dade and McLane.
#Food #groups #jolt #Investments
2 months ago
On August 20, Charter Communications, Inc. (NASDAQ:CHTR) and Liberty Broadband Corporation (NASDAQ:LBRDK) made major waves after announcing a multi-party transaction alongside **** Communications. Charter acquired Liberty Broadband while issuing ~46 million shares to **** , absorbing $12 billion of **** debt, and retiring 38.6 million Charter shares previously held by Liberty. The combined entity will eventually rebrand its parent name to **** Communications while operating as Spectrum. However, looking past the complex corporate restructuring, a comparison of their Q2 2026 financials reveals distinct operational realities for both companies.
Charter Communications, Inc. (NASDAQ:CHTR) generated Q2 2026 revenue of $13.5 billion, down 1.7% year-over-year, primarily dragged down by a 9.7% drop in residential video revenue. Net income totaled $1.3 billion, while Adjusted EBITDA declined 4.3% to $5.4 billion. Charter's underlying business faced notable headwinds: broadband net additions turned negative with a loss of 172,000 Internet customers, bringing total Internet subscribers to 29.4 million. The bright spot remained Spectrum Mobile, which added 406,000 mobile lines in Q2 to reach 12.5 million lines, driving mobile revenue up 18.9% to $1.095 billion.
Liberty Broadband Corporation (NASDAQ:LBRDK) historically operated primarily as a holding vehicle for its stake in Charter alongside ownership of GCI (Alaska's dominant telecom provider). For Q2 2026, Liberty Broadband's standalone performance reflected GCI's steady operational baseline, generating steady regional revenue and positive free cash flow. However, because over 80% of Liberty Broadband's net **** et value was tied directly to its Charter common stock ownership, Liberty's financial health was effectively a leveraged reflection of Charter's core performance.
In terms of financial strength, CHTR is performing better execution-wise as an operating entity. While facing cable broadband saturation, Charter generates massive operational scale with $3.9 billion in quarterly operating cash flow and $969 million in free cash flow. LBRDK, while maintaining a cleaner balance sheet, lacked independent organic growth drivers to outpace Charter's operating cash generation.
Charter Communications' bull case is supported by the transaction's potential to simplify its ownership structure by eliminating the Liberty holding company discount while integrating **** 's **** ets, creating a combined company with approximately 31.5 million customer relationships. Wireless convergence also continues to gain traction, with Spectrum Mobile lines increasing 15.5% year over year and providing a potential long-term growth engine to offset losses in the core cable business. Meanwhile, subsidized rural expansion, including 127,000 additional passings in Q2, creates opportunities to capture untapped regional market share.
#lbrdk

2 months ago
, WSJ Leadership Institute
Listen
(2 min)
Good morning. This is Megan Graham filling in for Nat Ives. A golf-focused media company and Callaway have apologized after posting a video that depicted a man shoving a woman to the ground after she tried to pick up his golf club.
#leadership #institute #megan #ives
Listen
(2 min)
Good morning. This is Megan Graham filling in for Nat Ives. A golf-focused media company and Callaway have apologized after posting a video that depicted a man shoving a woman to the ground after she tried to pick up his golf club.
#leadership #institute #megan #ives

2 months ago
Stock Spirits Group has secured a listing in the UK for some of its Sierra RTD Tequila ******* tails with local big-box retailer Morrisons.
The group sold its lime and strawberry-flavoured Tequila RTDs in UK Lidl stores last year for a limited period.
"Morrisons is our first full listing for the RTDs", Rob Curteis, managing director of Stock Spirits' UK distributor The Drinks Company, told Just Drinks.
The group's 6% abv Sierra Grapefruit Paloma and Lime Margarita RTDs will be available at 460 Morrisons supermarkets from 7 September, a statement from the Sierra brand said.
The 250ml ******* tail cans will be sold with an RRP of £2.60 ($3.54) per can. The drinks will also be part of the retailer's "multi-buy" deal of four drinks for £6.00 and five for £7.00.
#sierra #group #lime #listing

2 months ago
When Michael Burry decided to short Nvidia (NVDA), he wasn't betting against the company's technology. It was a bet against the AI financing structure and macroeconomic conditions. We know today that he is losing money on this bet as Nvidia inches toward its all-time highs. But Burry isn't sitting idle with his short position. He recently took to social media platform X, posting about a startup that could challenge Nvidia's dominance.
Here's what Burry's post is about. A small startup is making a big claim against Nvidia. Founded by a group of Harvard dropouts, Etched is building a chip called Sohu. What the chip does is run transformer models, the architecture behind most of today's artificial intelligence. By designing the chip to do only that, Etched says it can run AI inference far faster and cheaper than Nvidia's general-purpose GPUs. It recently raised money at a $21 billion valuation. But to see why challengers like Etched are emerging, it helps to understand how AI actually runs.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#burry

2 months ago
When Nvidia (NVDA) reports its must read earnings report on Wednesday evening, it will be confronting this frustrating reality.
Strong earnings reports haven't been too kind to Nvidia's stock of late!
Nvidia shares have fallen in response to earnings in six of the past eight quarters including the last four, per Yahoo Finance AlphaSpace ***** ysis.
The reality is that the market is positioned for the company to post something great and for CEO Jensen Huang to sound super bullish on the earnings call.
The market also knows there is minimal downside risk to Nvidia's growing investment portfolio, given the rising valuations (see Anthropic (ANTH.PVT), for example) being afforded to most privately held names in artificial intelligence.
#strong


2 months ago
By Christy Santhosh and Shashwat Chauhan
Aug 19 (Reuters) - Moderna shares more than doubled on Wednesday, adding about $30 billion to its market value, after promising late-stage data on its personalized mRNA cancer therapy developed with Merck sent investors piling into the stock.
The therapy is central to Moderna's efforts to prove that its mRNA technology can succeed beyond its COVID-19 vaccine franchise and infectious disease shots, as it seeks to build a more durable revenue base. The company recently added a flu vaccine to its portfolio and is advancing experimental vaccines for conditions including norovirus and Lyme disease.
Analysts had noted the cancer vaccine data could be an important catalyst for the company and potentially strengthen investor sentiment.
"A successful trial gives investors stronger evidence that mRNA technology can have a meaningful future beyond infectious diseases," said Lale Akoner, global market strategist for eToro.
#market #cancer #Therapy #investors

2 months ago
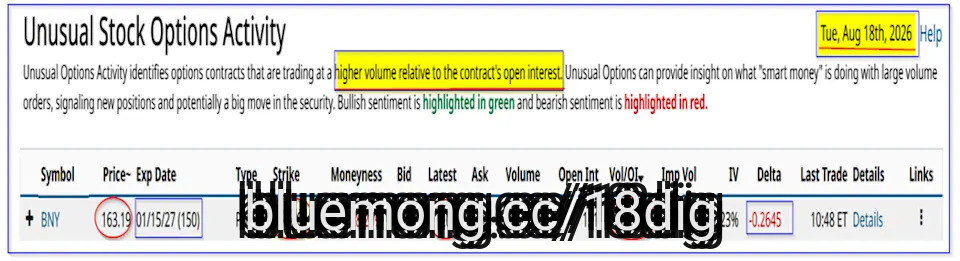
Today, massive put option trading in Bank of NY Mellon (BNY) shows that some investors are earning a 3.33% 150-day short-put yield. That could imply investors are shorting these puts to establish a potential lower buy-in point for BNY stock ahead of its upcoming earnings, especially if BNY dips.
BNY is at $163.44 in midday trading, and the strike price of this huge volume of BNY puts is $150.00, expiring on Jan. 15, 2027. The chart below shows that BNY stock has been on a 3-month upward trek.
Huge Unusual Long-Dated Call Options in Oracle Corp - A Covered Call ORCL Play?
QQQ Just 'Gamma Flipped' as Market Makers Were Forced to Sell. Here's What Our Top Chart Expert is Tracking Next.
Why There Might Be a Case for Taiwan Semiconductor Stock at $450 in September
#huge #chart #investors


3 months ago
On August 6, Cable One (NYSE:CABO) walked investors through a quarter that reads like two different companies. Residential broadband customers kept leaving, yet management pointed to improving connect trends, rising average revenue per user, and an aggressive debt paydown as signs the business is stabilizing underneath the subscriber losses. The result is a report that gives both the bulls and the bears real ammunition.
Cable One's acquisition numbers moved in the right direction in the second quarter. Connect activity improved sequentially from the first quarter and grew in each month of Q2, and door-to-door sales have more than doubled as a share of quarterly connects over the past year. Residential broadband ARPU also rose sequentially, lifted by promotional roll-offs, changes to the AutoPay Plus program, and customers adding higher-value products. Essentially all of Cable One's network can already deliver gigabit speeds, and the company expects most customers on multi-gig infrastructure by year-end, upgrades it credits to disciplined investment rather than new capital spending.
Business services found firmer ground too, with enterprise, wholesale, and carrier offerings benefiting from long-term contracts and recurring revenue, and Cable One rounded out that lineup with a new unified communications product called UCaaS. Underneath all of it, the company cut its debt balances by $63 million in the quarter, close to $60 million of that through voluntary repurchases at a discount, pushing year-to-date debt reduction to nearly $130 million with $700 million still undrawn on its revolver.
The subscriber numbers remain the core problem. Cable One lost 17,000 residential broadband customers in the second quarter as elevated churn persisted, and residential data revenue fell 7.3% year-over-year on a 6.6% drop in subscribers even as ARPU held roughly flat. Total revenue slid to $348.9 million from $381.1 million a year earlier, and the SMB broadband business stayed under pressure while business data revenue fell 6.6% year over year, partly reflecting tower ****** ets the company sold earlier in the year.
Profitability moved the wrong way as well. Adjusted EBITDA fell to $173.5 million, or 49.7% of revenue, down from 53.3% of revenue a year earlier, while capital expenditures climbed to $74 million, up $5.6 million year-over-year. That combination pushed adjusted EBITDA less capex down to $99.5 million from $134.8 million a year ago. Cable One also booked non-cash impairment charges tied to its franchise agreements, goodwill, and its MBI investment, and net leverage stood at 4.2 times against a gross debt load of $3.06 billion, as management flagged continued competitive intensity in fiber overbuild markets.
#residential

3 months ago
Birkenstock Holding plc (BIRK) is proving that consumers may be cutting back, but they're not ready to give up their favorite pair of sandals just yet. Shares of the German footwear maker jumped 11.59% on Aug. 13 after its fiscal 2026 third-quarter results showed stronger-than-expected revenue, solid online growth, and enough confidence from management to lift its full-year guidance.
Sure, the company also delivered a slight earnings miss, but investors clearly focused on the bigger picture. Birkenstock's latest numbers point to resilient demand for its premium footwear, even as shoppers remain cautious with their discretionary spending. And the raised outlook adds another vote of confidence in the brand's ability to keep growing. So, with the latest results giving investors plenty to like, let's take a closer look at Birkenstock's performance and what could be next for BIRK shares.
Analysts Keep Hiking Micron's Revenue and Price Forecasts - Shorting MU Puts Works Here
GOOGL Stock Alert: Google Unleashes Its Biggest Weapon Against Apple
Applied Materials Stock Is Down on Earnings. Here's What Barchart Options Data Says Could Come Next for AMAT.
#earnings #keep


3 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Technology Solutions revenue was constrained by hardware vendor delivery times extending from historical 30-60 day windows to over 200 days, resulting in a 65% year-over-year increase in backlog.
The AZT Protect business is transitioning toward larger enterprise accounts, which involve longer 18-24 month sales cycles due to complex procurement processes and internal stakeholder alignment.
Management is pivoting its sales strategy to engage higher-level IT decision-makers earlier, as these stakeholders often control the budgets even when OT teams advocate for the technology.
Strategic focus has shifted toward OEM partnerships, such as the Acronis integration, to embed AZT Protect directly into third-party products for long-term recurring revenue.
#protect #revenue #year #sales
3 months ago
By Mike Dolan
Aug 10 (Reuters) -
What matters in U.S. and global markets today
By Mike Dolan, Editor-at-Large, Finance and Markets
Even though it allowed Wall Street stocks to clock another record high on Friday, the surprise drop in July U.S. payrolls didn't shift interest rate markets as much as the initial gasp might have suggested.
#reuters

3 months ago
Investors often weigh the potential of a retail recovery against the stability of defense contracts. Comparing Advance Auto Parts Inc (NYSE:AAP) and BWX Technologies Inc (NYSE:BWXT) reveals two distinct strategies for long-term growth.
Advance Auto Parts provides essential vehicle components to a wide range of customers, focusing on operational improvements to drive value. BWX Technologies serves critical defense and energy needs through nuclear innovation and government partnerships. While one targets a consumer turnaround, the other capitalizes on specialized industrial demand and expanding government budgets.
Advance Auto Parts sells automotive replacement parts, accessories, and maintenance items to both professional installers and do-it-yourself customers. The company operates thousands of stores across North America and recently expanded an AI-powered delivery partnership with OneRail to improve fulfillment speed. This strategic focus on professional accounts like local garages and service stations is intended to recapture market share in a highly competitive environment.
In FY 2025, revenue reached $8.6 billion, representing a year-over-year decline of approximately 5.4%. Despite the sales dip, the company managed to report a net income of $44 million, resulting in a net margin of approximately 0.5% for the fiscal year. The company is currently implementing a multi-year restructuring plan to optimize its supply chain, reduce costs, and enhance its competitive position in a fragmented market.
As of its January 2026 balance sheet, the debt-to-equity ratio is nearly 2.4x. This metric compares total debt to shareholder equity and indicates a significant reliance on borrowed capital to fund operations. Free cash flow for the year was negative $298 million, defined as cash from operations minus capital expenditures.
#parts #NYSE #technologies #government

3 months ago
This story was originally published on Retail Dive. To receive daily news and insights, subscribe to our free daily Retail Dive newsletter.
Bed Bath & Beyond Inc. is changing its corporate name to Neighborhood Intelligence and will begin trading on the Nasdaq under the ticker symbol NXH, effective Aug. 17. As a result, the company's last day trading on the New York Stock Exchange will be Aug. 14.
The company is also relocating its headquarters from Murray, Utah, to Nashville, Tennessee, according to a Tuesday announcement.
The changes underscore the company's three-pillared turnaround strategy, focused on omnichannel retail and commerce; digital, financial, insurance and blockchain services; and beyond home, which includes an AI-powered home operating system.
The corporate name change and headquarters relocation mark the latest moves from the company to establish the next era of Bed Bath & Beyond.
#bath #name #company

3 months ago
For the second day in a row, Sandisk (NASDAQ: SNDK) stock is soaring, up 8% through 10:35 a.m. ET Tuesday.
Sandisk stock gained a strong 6% higher on Monday after ******* ysts at Morgan Stanley sounded the all-clear for artificial intelligence stocks, confirming revenues are growing fast enough to provide AI hyperscalers the cash they need to buy the semiconductor chips they want. Today, Sandisk's getting an even more Sandisk-specific catalyst:
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Its concept of using flash computer memory as a substitute for DRAM is catching on.
Sandisk and SK Hynix collaborate
#flashing #NASDAQ #morgan

3 months ago
Spring, Texas-based Hewlett Packard Enterprise Company (HPE) delivers solutions that allow customers to capture, ****** yze, and act upon data seamlessly. Valued at $63.2 billion by market cap, the company provides servers, advanced storage products, high-performance computing, AI-driven platforms, and more. The global technology leader is expected to announce its fiscal third-quarter earnings for 2026 in the near term.
Ahead of the event, ****** ysts expect Hewlett Packard Enterprise to report a profit of $0.80 per share on a diluted basis, up 128.6% from $0.35 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Dear ****** eX Stock Fans, Mark Your Calendars for August 6
Amazon Stock Just Hit a Major Hurdle Ahead of Earnings
Elon Musk Just Revealed a Quiet Win for Tesla's AI Ambitions
#Share #spring


3 months ago
Bengen's 2025 research drops the safe withdrawal rate to 4.2% for a 50-year retirement, undercutting the standard 4% rule for anyone retiring at 55.
Retiring at 55 forces a full decade of self-funded healthcare before Medicare at 65, a cost the original 4% rule never accounted for.
BLS data shows household spending peaks between ages 45 and 54, meaning early retirees exit income at their highest-spending years, not during natural tapering.
Don't wait: the ******* yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
The 4% withdrawal rule has been a fixture of retirement planning for three decades and for good reason. It is simple, intuitive, and, for the right retiree, it can and has worked well. The challenge is that it was never designed for someone who would stop working at 55.
#spending
3 months ago
South Korean contract development and manufacturing organisation (CDMO) Samsung Biologics has been on a steep upward growth trajectory since receiving its first licence to produce biologic drug substances in 2015.
That FDA approval was followed in 2016 by a Certificate of Good Manufacturing Practice (GMP) compliance from the EMA for biologics drug substance and drug product, and the company now has over 450 approvals from regulators around the world. The expansion of Samsung's manufacturing licences is mirrored in the growth of its performance, which saw it achieve revenues of $3.1bn (Won4,557bn) in 2025, a 30% increase from the previous year.
Until now, that work has been centred on the Songdo Bio Cluster in the South Korean city of Incheon, where Samsung will have three campuses, having recently acquired land for Bio Campus III, which will be set aside for future modalities including work on cell and gene therapies and vaccines. The cluster will also be the location for Samsung's forthcoming open innovation centre, which is due to open in 2027 and is being built in partnership with Lilly Gateway Labs. But a key part of the company's plans for continued growth involves adding capacity outside its home country.
On 20 July 2026, Samsung unveiled its plans for the $1.8bn (SFr1.46bn) acquisition of PolyPeptide Group, which specialises in peptide-based active pharmaceutical ingredients (APIs) and produces one third of the commercially approved peptides in the world. In addition to expanding Samsung's capabilities beyond antibodies and ADCs and into peptide therapeutics, including GLP-1s, its deal with the Swiss CDMO also comes with a network of sites across Sweden, Belgium, France, the US, and India, together with a corporate office in Switzerland and an innovation centre in Strasbourg, France.
The PolyPeptide deal is expected to close before the end of 2026, when it will build on Samsung's first major M&A transaction of the year. That saw the South Korean CDMO complete its $280M acquisition of GSK's Rockville, MD, US facility on March 31, 2026. The agreement gave Samsung its first US manufacturing presence and an additional 60,000L of drug substance capacity, increasing its global capacity to 845,000L.
#south
4 months ago
Harris Oakmark recently released its second-quarter 2026 investor letter for the "Oakmark Fund". A copy of the letter can be downloaded here. The objective of the fund is to deliver capital appreciation by investing in a diverse set of large-cap US companies. In the quarter, the Fund (investor class) underperformed the S&P 500 Index, returning 2.45% vs. 15.20% for the index. The industrials and financials contributed to performance at the sector level, while information technology and energy detracted. Investing in AI-benefited enterprises kept market leadership narrow during the quarter. In addition, you can check the Fund's top five holdings to determine its best picks for 2026.
In its Q2 2026 investor letter, Oakmark Fund highlighted ConocoPhillips (NYSE:COP). ConocoPhillips (NYSE:COP) is a US-based energy company that produces, transports, and markets crude oil, bitumen, natural gas, liquefied natural gas (LNG), and natural gas liquids. On July 13, 2026, ConocoPhillips (NYSE:COP) closed at $112.85 per share, reflecting a market capitalization of $137.48 billion. ConocoPhillips (NYSE:COP) posted a one-month return of 1.36%, while its shares gained 21.93% over the past 52 weeks.
Oakmark Fund stated the following regarding ConocoPhillips (NYSE:COP) in its Q2 2026 investor update:
"ConocoPhillips (NYSE:COP) was the top detractor during the quarter. The U.S.-headquartered oil and gas exploration and production company's stock declined as crude prices, which had risen on Middle East disruptions, eased. Positively, the company's underlying fundamentals continue to track our expectations. We value management's focus on shareholder returns and see a long runway for growth from the company's geographically diverse and inventory-deep energy portfolio."
ConocoPhillips (NYSE:COP) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 74 hedge fund portfolios held ConocoPhillips (NYSE:COP) at the end of the first quarter, up from 65 in the previous quarter. While we acknowledge the potential of ConocoPhillips (NYSE:COP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.





