

6 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Moody's Economist Mark Zandi on Monday voiced concern over the rising possibility of a significant Federal Reserve policy error, as markets anticipate a rate hike on Wednesday.
Zandi took to X to express his apprehension about the Federal Reserve's potential policy misstep. He stated, "The odds of a serious Fed policy mistake are uncomfortably high and rising."
He further added, "But the economy is already growing near potential (2% real GDP growth) and operating at full employment (unemployment a bit above 4%)."
Don't Miss:
#policy
Moody's Economist Mark Zandi on Monday voiced concern over the rising possibility of a significant Federal Reserve policy error, as markets anticipate a rate hike on Wednesday.
Zandi took to X to express his apprehension about the Federal Reserve's potential policy misstep. He stated, "The odds of a serious Fed policy mistake are uncomfortably high and rising."
He further added, "But the economy is already growing near potential (2% real GDP growth) and operating at full employment (unemployment a bit above 4%)."
Don't Miss:
#policy

7 days ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
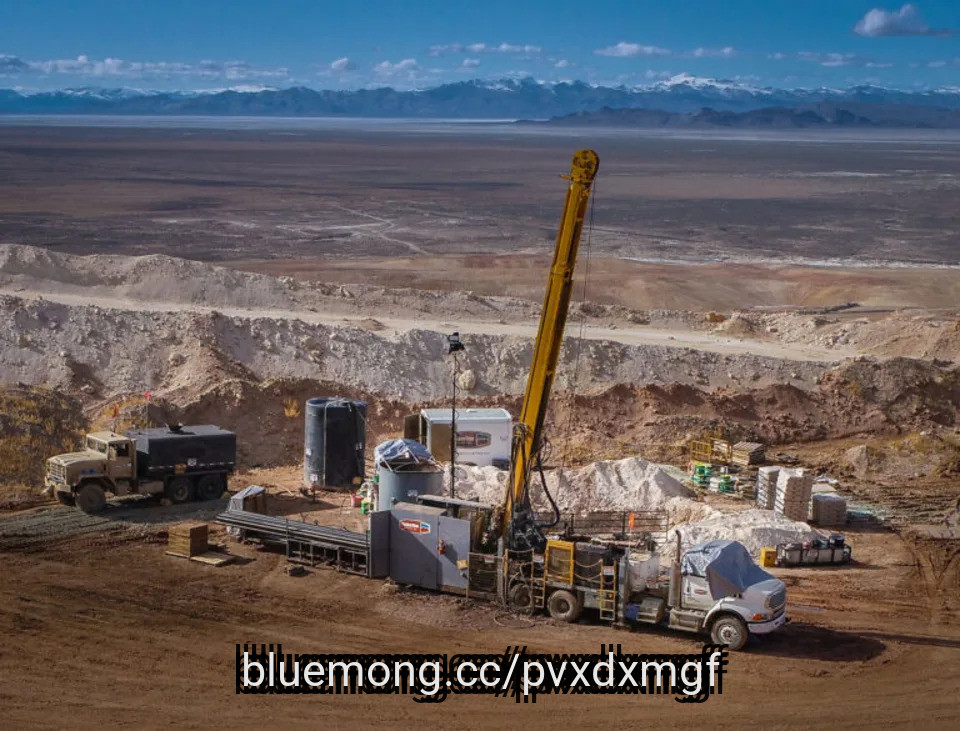
Photo from Hycroft Mining website
#quarter #asset #management #focus
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#quarter #asset #management #focus


13 days ago
ASML Holding N.V. (NASDAQ:ASML) and Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) have given investors a clearer view of their next manufacturing transition. The important distinction is when each company might earn a return.
Their September 8 announcement says TSMC intends to introduce ASML's High-NA extreme ultraviolet technology into high-volume advanced-node manufacturing starting in 2030. A separate initiative targets a larger photomask pilot line in 2031 and corresponding lithography systems for advanced production in 2033.
Image: Courtesy of ASML
Those dates describe successive stages, not a single launch delayed until 2033. Initial production would use existing six-inch masks; the later transition would introduce twelve-inch masks.
For ASML, a major customer's stated adoption plan strengthens the long-term demand case. More advanced AI chips require increasingly complex manufacturing, and TSMC expects more layers to need High-NA technology as nodes progress.
#high #advanced #transition #technology
Their September 8 announcement says TSMC intends to introduce ASML's High-NA extreme ultraviolet technology into high-volume advanced-node manufacturing starting in 2030. A separate initiative targets a larger photomask pilot line in 2031 and corresponding lithography systems for advanced production in 2033.
Image: Courtesy of ASML
Those dates describe successive stages, not a single launch delayed until 2033. Initial production would use existing six-inch masks; the later transition would introduce twelve-inch masks.
For ASML, a major customer's stated adoption plan strengthens the long-term demand case. More advanced AI chips require increasingly complex manufacturing, and TSMC expects more layers to need High-NA technology as nodes progress.
#high #advanced #transition #technology

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
19 days ago
On August 13, Kodiak Sciences Inc. (NASDAQ:KOD) reported second-quarter financial results for the period ended June 30, alongside an update on its three late-stage eye disease programs. The clinical-stage biotech told investors it now sits within months of three separate Phase 3 readouts, a stretch CEO Victor Perlroth called the payoff of years of disciplined execution. For a company with no approved products and a widening cash burn, those trial results are about to decide a lot.
Kodiak's near-term story rests on Zenkuda and KSI-501, both being tested in the Phase 3 DAYBREAK study for treatment-naive wet age-related macular degeneration, with one-year primary endpoint topline data due in September 2026. Zenkuda already has four completed Phase 3 studies behind it. In GLOW1 and GLOW2, every patient remained on extended six-month dosing at one year, and in BEACON, nearly half of Zenkuda patients needed no further treatment in the second six months while matching aflibercept on vision and anatomical outcomes. That durability comes from a mean ocular half-life of 20 days, roughly three times longer than approved anti-VEGF drugs.
Behind DAYBREAK sits PEAK, evaluating KSI-101 in macular edema secondary to inflammation, where Kodiak finished enrolling the first 300-patient cohort during the quarter and expects Pivotal ***** ysis 1 data in December 2026. Earlier Phase 1b data showed more than half of MESI patients gaining at least 15 letters of vision, with over 90% resolution of retinal fluid by week eight. Kodiak also began enrolling patients in the roughly 910-patient ALTO study testing KSI-501 against aflibercept in diabetic macular edema, its second registrational trial for that molecule. Zenkuda and KSI-501 together are aimed at a $15 billion anti-VEGF market.
None of that comes cheap. Kodiak's net loss widened to $65.6 million in the second quarter of 2026, or $1.05 per share, up from $54.3 million and $1.03 per share a year earlier. R&D spending jumped to $56.1 million from $42.8 million, as the company ramped up clinical activity across PEAK and PINNACLE and stepped up manufacturing for its Phase 3 programs. General and administrative costs eased slightly to $10.8 million from $12.8 million, but that was not enough to offset the R&D increase.
Kodiak ended the quarter with $125.9 million in cash and equivalents, which management says covers operations into 2027, but working capital fell from $169.3 million at the end of 2025 to $78.6 million by June 30, and stockholders' equity dropped from $157.4 million to $61.1 million over the same stretch. With three separate trials due to report between September and December, any delay or disappointing result would hit a balance sheet that already has less room to absorb it.
#data
Kodiak's near-term story rests on Zenkuda and KSI-501, both being tested in the Phase 3 DAYBREAK study for treatment-naive wet age-related macular degeneration, with one-year primary endpoint topline data due in September 2026. Zenkuda already has four completed Phase 3 studies behind it. In GLOW1 and GLOW2, every patient remained on extended six-month dosing at one year, and in BEACON, nearly half of Zenkuda patients needed no further treatment in the second six months while matching aflibercept on vision and anatomical outcomes. That durability comes from a mean ocular half-life of 20 days, roughly three times longer than approved anti-VEGF drugs.
Behind DAYBREAK sits PEAK, evaluating KSI-101 in macular edema secondary to inflammation, where Kodiak finished enrolling the first 300-patient cohort during the quarter and expects Pivotal ***** ysis 1 data in December 2026. Earlier Phase 1b data showed more than half of MESI patients gaining at least 15 letters of vision, with over 90% resolution of retinal fluid by week eight. Kodiak also began enrolling patients in the roughly 910-patient ALTO study testing KSI-501 against aflibercept in diabetic macular edema, its second registrational trial for that molecule. Zenkuda and KSI-501 together are aimed at a $15 billion anti-VEGF market.
None of that comes cheap. Kodiak's net loss widened to $65.6 million in the second quarter of 2026, or $1.05 per share, up from $54.3 million and $1.03 per share a year earlier. R&D spending jumped to $56.1 million from $42.8 million, as the company ramped up clinical activity across PEAK and PINNACLE and stepped up manufacturing for its Phase 3 programs. General and administrative costs eased slightly to $10.8 million from $12.8 million, but that was not enough to offset the R&D increase.
Kodiak ended the quarter with $125.9 million in cash and equivalents, which management says covers operations into 2027, but working capital fell from $169.3 million at the end of 2025 to $78.6 million by June 30, and stockholders' equity dropped from $157.4 million to $61.1 million over the same stretch. With three separate trials due to report between September and December, any delay or disappointing result would hit a balance sheet that already has less room to absorb it.
#data

20 days ago
October WTI crude oil (CLV26) is up +0.43 (+0.48%) today, and October RBOB gasoline (RBV26) is up +0.0126 (+0.40%).
Crude oil and gasoline prices are moving higher today, with crude oil posting a fresh 6-week high. Crude has support as hostilities escalated between the US and Iran, raising concerns about prolonged disruptions to energy flows through the Strait of Hormuz. Crude prices also gained after weekly EIA inventories unexpectedly declined. However, crude gains are limited amid signs of larger crude supplies leaving the Strait of Hormuz, easing supply concerns.
I've Been Taking a Beating on This AI Energy Stock. Here's Where I'm Looking to Add More Shares – and Why.
This Geothermal Stock Is Soaring Today After a Major Google Deal
As US Bond Selloff Accelerates, Treasury Secretary Scott Bessent Says a Stronger Yen is Coming
#today #strait #energy #gasoline
Crude oil and gasoline prices are moving higher today, with crude oil posting a fresh 6-week high. Crude has support as hostilities escalated between the US and Iran, raising concerns about prolonged disruptions to energy flows through the Strait of Hormuz. Crude prices also gained after weekly EIA inventories unexpectedly declined. However, crude gains are limited amid signs of larger crude supplies leaving the Strait of Hormuz, easing supply concerns.
I've Been Taking a Beating on This AI Energy Stock. Here's Where I'm Looking to Add More Shares – and Why.
This Geothermal Stock Is Soaring Today After a Major Google Deal
As US Bond Selloff Accelerates, Treasury Secretary Scott Bessent Says a Stronger Yen is Coming
#today #strait #energy #gasoline

21 days ago
Private equity firm Trident Management appears to be an early mover in bolting together small courier businesses onto a platform that can offer shippers greater regional density and reach as an alternative to large, legacy parcel carriers.
Trident-backed Priority Courier Experts, which serves B2B customers in the Minneapolis-St. Paul area and upper Midwest, last week said it acquired Priority Dispatch Inc. and Diamond Expedited, Midwest providers of same-day courier and box-truck freight services for the healthcare and e-commerce industries, and Atlanta-based Inpax Shipping Solutions.
Priority Dispatch was founded in Cincinnati in 1973. Diamond Expedited began serving the greater Chicago area in 1995. The companies, which were bought from the same individual, also cover Columbus, Cleveland, Dayton and Toledo, Ohio; Indianapolis; Detroit and Milwaukee, with 43 employees and more than 500 independent-contractor drivers. Their combined delivery traffic is about 250,000 orders per year.
Inpax is active in seven markets across the South, including Charlotte and Raleigh, North Carolina, Tennessee, South Carolina and Florida. With 75 employees and more than 335 owner-operators it delivers more than 400,000 orders per year. In addition to e-commerce pickup and delivery, it offers local and regional truck brokerage and tractor trailer freight.
In December 2024, Priority Courier Experts purchased Indianapolis-based Now Courier.
#Experts #indianapolis
Trident-backed Priority Courier Experts, which serves B2B customers in the Minneapolis-St. Paul area and upper Midwest, last week said it acquired Priority Dispatch Inc. and Diamond Expedited, Midwest providers of same-day courier and box-truck freight services for the healthcare and e-commerce industries, and Atlanta-based Inpax Shipping Solutions.
Priority Dispatch was founded in Cincinnati in 1973. Diamond Expedited began serving the greater Chicago area in 1995. The companies, which were bought from the same individual, also cover Columbus, Cleveland, Dayton and Toledo, Ohio; Indianapolis; Detroit and Milwaukee, with 43 employees and more than 500 independent-contractor drivers. Their combined delivery traffic is about 250,000 orders per year.
Inpax is active in seven markets across the South, including Charlotte and Raleigh, North Carolina, Tennessee, South Carolina and Florida. With 75 employees and more than 335 owner-operators it delivers more than 400,000 orders per year. In addition to e-commerce pickup and delivery, it offers local and regional truck brokerage and tractor trailer freight.
In December 2024, Priority Courier Experts purchased Indianapolis-based Now Courier.
#Experts #indianapolis
26 days ago
Companies worried for years about whether an employee's password had been stolen.
Now they have to worry about AI "workers," too.
Okta (OKTA) reported fiscal second-quarter revenue of $805 million, up 11%, while subscription revenue reached $793 million, up 12%. Remaining performance obligations increased 17% to nearly $4.86 billion.
The company boosted its yearly outlook as organizations increasingly face a category of identity that was virtually nonexistent in mainstream commercial IT only a few years ago: autonomous AI agents.
"Every agent needs a trusted identity and clear controls over what it can access and do," CEO Todd McKinnon said.
#okta #years #every #mckinnon
Now they have to worry about AI "workers," too.
Okta (OKTA) reported fiscal second-quarter revenue of $805 million, up 11%, while subscription revenue reached $793 million, up 12%. Remaining performance obligations increased 17% to nearly $4.86 billion.
The company boosted its yearly outlook as organizations increasingly face a category of identity that was virtually nonexistent in mainstream commercial IT only a few years ago: autonomous AI agents.
"Every agent needs a trusted identity and clear controls over what it can access and do," CEO Todd McKinnon said.
#okta #years #every #mckinnon


28 days ago
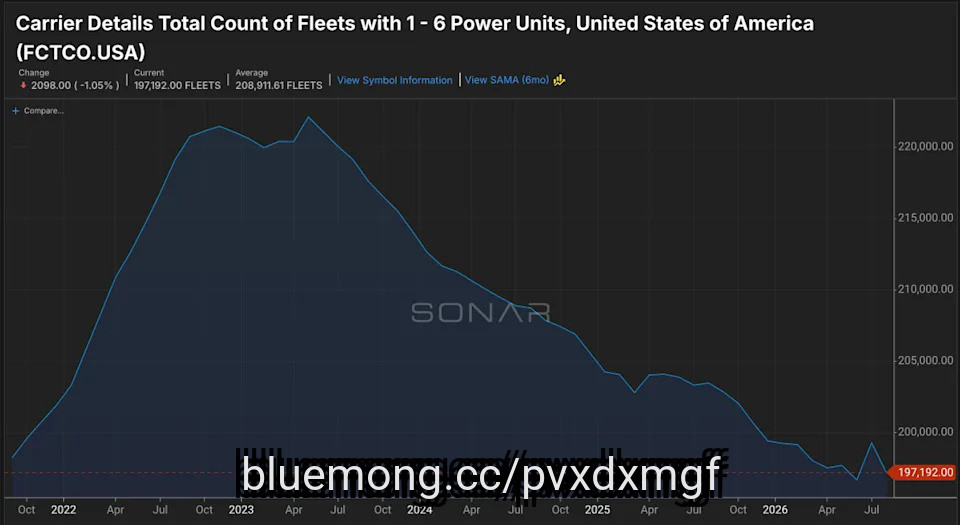
There is a question hanging over the small carrier world right now, and two of the most knowledgeable transportation attorneys in the country did not flinch from it when they sat down separately on The Long Haul. The question is whether the small carrier, the one-truck owner-operator and the five-truck fleet, still has a viable future as an independent business, or whether the forces set in motion by the Supreme Court's Montgomery decision are quietly pushing that operator toward extinction as an independent and into the arms of a larger carrier.
Neither attorney sugarcoated it. Brian Nelson, a partner at Taylor Nelson Slattery Bernard in St. Petersburg, Florida, who spent years as general counsel inside a broker, a motor carrier, and a 3PL under one roof, walked through the legal machinery now bearing down on carriers. Greg Feary, president and managing partner of Scopelitis, the firm the biggest fleets in the country call when things go wrong, went further and named the outcome he is already seeing. Together, their two conversations form the clearest picture available of where the small carrier stands, and it is a picture every independent operator needs to see.
Start with the ruling itself, because everything else flows from it. In Montgomery v. Caribe Transport, decided this May by a unanimous 9-0 Supreme Court, the justices answered a single question: do brokers have a duty to select carriers that operate safely over the roadways? The Court said yes. As Nelson explained, that put brokers back into what he called the firing squad, meaning they can no longer get a negligent selection lawsuit dismissed early on the grounds that federal law preempts it.
Before May 14, in most of the country, a broker sued after a crash could file a motion to dismiss and often walk out of the litigation quickly on preemption grounds. Nelson described the old routine: file the answer, file the motion to dismiss, argue there is no valid claim, and get out. That door is now closed. As Nelson put it, brokers can no longer rely on that early exit, which means they now have to go through discovery and potentially all the way to summary judgment. That longer, more expensive path is why insurance companies are raising rates, because they know they will have to pay defense costs deeper into every case.
Nelson was careful to note that causation still matters. A plaintiff still has to prove that the specific thing the broker was negligent about, say, selecting a carrier with poor vehicle maintenance, actually caused the crash. But he explained how plaintiffs get around that requirement using what is called the reptile theory. The argument runs that if a carrier is bad at one thing, hours of service, for instance, a jury will believe they must be bad at everything, including whatever actually caused the wreck. The practical consequence, Nelson said, is that a carrier can no longer afford to be excellent at four things and poor at one. In his words, you have to take a hol
Neither attorney sugarcoated it. Brian Nelson, a partner at Taylor Nelson Slattery Bernard in St. Petersburg, Florida, who spent years as general counsel inside a broker, a motor carrier, and a 3PL under one roof, walked through the legal machinery now bearing down on carriers. Greg Feary, president and managing partner of Scopelitis, the firm the biggest fleets in the country call when things go wrong, went further and named the outcome he is already seeing. Together, their two conversations form the clearest picture available of where the small carrier stands, and it is a picture every independent operator needs to see.
Start with the ruling itself, because everything else flows from it. In Montgomery v. Caribe Transport, decided this May by a unanimous 9-0 Supreme Court, the justices answered a single question: do brokers have a duty to select carriers that operate safely over the roadways? The Court said yes. As Nelson explained, that put brokers back into what he called the firing squad, meaning they can no longer get a negligent selection lawsuit dismissed early on the grounds that federal law preempts it.
Before May 14, in most of the country, a broker sued after a crash could file a motion to dismiss and often walk out of the litigation quickly on preemption grounds. Nelson described the old routine: file the answer, file the motion to dismiss, argue there is no valid claim, and get out. That door is now closed. As Nelson put it, brokers can no longer rely on that early exit, which means they now have to go through discovery and potentially all the way to summary judgment. That longer, more expensive path is why insurance companies are raising rates, because they know they will have to pay defense costs deeper into every case.
Nelson was careful to note that causation still matters. A plaintiff still has to prove that the specific thing the broker was negligent about, say, selecting a carrier with poor vehicle maintenance, actually caused the crash. But he explained how plaintiffs get around that requirement using what is called the reptile theory. The argument runs that if a carrier is bad at one thing, hours of service, for instance, a jury will believe they must be bad at everything, including whatever actually caused the wreck. The practical consequence, Nelson said, is that a carrier can no longer afford to be excellent at four things and poor at one. In his words, you have to take a hol

28 days ago
Coty Inc. (NYSE:COTY) traded about 7% lower shortly after its earnings release, with the after-hours decline later approaching 8.5%, as a fourth-quarter revenue beat was accompanied by a wider-than-expected adjusted loss and weaker near-term profit guidance. Revenue increased 1.3% to $1.27 billion, outperforming the consensus forecast for a 4.6% decline. However, the company-defined adjusted loss was $0.02 per share versus the $0.01 consensus loss, like-for-like sales fell 1%, and the reported net loss widened to $141 million.
The larger red flag is visibility. Coty Inc. (NYSE:COTY) expects first-quarter company-defined adjusted earnings of $0.11 to $0.13 per share, below the $0.14 consensus estimate, while like-for-like revenue is projected to decline by a low- to mid-single-digit percentage. Management also withheld fiscal 2027 guidance and described the period as a transition year, even though fiscal 2025 carried the same label.
The revenue beat showed that Coty Inc. (NYSE:COTY) still owns brands with meaningful consumer demand. Fourth-quarter like-for-like sales declined only 1%, improving substantially from the 7% decline in the third quarter. Fragrance demand remains comparatively resilient, supporting a portfolio centered on brands such as Burberry, Hugo Boss, Calvin Klein, Marc Jacobs and Chloé.
Portfolio simplification could also strengthen Coty Inc. (NYSE:COTY)'s balance sheet. Coty received $250 million at the signing of the Gucci Beauty agreement and is due another $150 million by September 30, 2027, subject to a possible holdback of up to $30 million. The immediate proceeds can support debt reduction and investment in core brands. Potential sales of CoverGirl, Rimmel, or other Consumer Beauty **** ets could further reduce complexity and concentrate capital on higher-return prestige fragrances.
The first-quarter outlook leaves Coty Inc. (NYSE:COTY) without a demonstrated earnings inflection point. Management is forecasting another like-for-like sales decline, adjusted earnings below consensus, and no full-year framework. Investors therefore lack a clear bridge between the restructuring program and sustainable earnings or free-cash-flow growth.
#coty #earnings #quarter #revenue
The larger red flag is visibility. Coty Inc. (NYSE:COTY) expects first-quarter company-defined adjusted earnings of $0.11 to $0.13 per share, below the $0.14 consensus estimate, while like-for-like revenue is projected to decline by a low- to mid-single-digit percentage. Management also withheld fiscal 2027 guidance and described the period as a transition year, even though fiscal 2025 carried the same label.
The revenue beat showed that Coty Inc. (NYSE:COTY) still owns brands with meaningful consumer demand. Fourth-quarter like-for-like sales declined only 1%, improving substantially from the 7% decline in the third quarter. Fragrance demand remains comparatively resilient, supporting a portfolio centered on brands such as Burberry, Hugo Boss, Calvin Klein, Marc Jacobs and Chloé.
Portfolio simplification could also strengthen Coty Inc. (NYSE:COTY)'s balance sheet. Coty received $250 million at the signing of the Gucci Beauty agreement and is due another $150 million by September 30, 2027, subject to a possible holdback of up to $30 million. The immediate proceeds can support debt reduction and investment in core brands. Potential sales of CoverGirl, Rimmel, or other Consumer Beauty **** ets could further reduce complexity and concentrate capital on higher-return prestige fragrances.
The first-quarter outlook leaves Coty Inc. (NYSE:COTY) without a demonstrated earnings inflection point. Management is forecasting another like-for-like sales decline, adjusted earnings below consensus, and no full-year framework. Investors therefore lack a clear bridge between the restructuring program and sustainable earnings or free-cash-flow growth.
#coty #earnings #quarter #revenue

1 month ago
Anthropic is ******* embling a revolving credit facility expected to surpass its roughly $10 billion target, as the AI company moves toward a public listing, according to Reuters.
Banks are competing for a share of the expanded credit line, viewing involvement as a way to bolster their standing when Anthropic selects underwriters for its IPO, according to Reuters, citing Bloomberg News. The company behind the Claude chatbot confidentially filed for a U.S. initial public offering in June.
The structure of the facility ******* igns different commitment levels based on a bank's level of involvement. Banks taking the most prominent arranging roles have received requests for commitments of about $1.25 billion apiece, with those in a secondary tier being guided toward roughly $1 billion. Banks with smaller roles in the deal are expected to contribute somewhere below $750 million.
The talks remain ongoing, and Anthropic could still opt to cap the facility at its original target or even below it.
#anthropic #expected
Banks are competing for a share of the expanded credit line, viewing involvement as a way to bolster their standing when Anthropic selects underwriters for its IPO, according to Reuters, citing Bloomberg News. The company behind the Claude chatbot confidentially filed for a U.S. initial public offering in June.
The structure of the facility ******* igns different commitment levels based on a bank's level of involvement. Banks taking the most prominent arranging roles have received requests for commitments of about $1.25 billion apiece, with those in a secondary tier being guided toward roughly $1 billion. Banks with smaller roles in the deal are expected to contribute somewhere below $750 million.
The talks remain ongoing, and Anthropic could still opt to cap the facility at its original target or even below it.
#anthropic #expected

1 month ago
Interested in Grabagun Digital Holdings Inc.? Here are five stocks we like better.
Revenue and gross margin improved: Second-quarter revenue rose 9.4% to $23.2 million, while gross profit increased 39% to $3.1 million and gross margin expanded to 13.5%. Growth was driven by higher-priced firearms, larger customer orders, pricing optimization and favorable product mix.
Profitability remained pressured by investment costs: Operating expenses climbed to $5.7 million due to public-company costs, PEW Logistics investments and added infrastructure, resulting in a $1.8 million net loss and $1.7 million adjusted EBITDA loss.
PEW Logistics is expanding, while leadership changes: The platform processed more than $1.9 million in gross merchandise value and added Backwoods Suppressors as its third manufacturer partner. CFO and co-founder Justin Hilty plans to retire and will be succeeded by Jonathan Terry, formerly of YETI.
Grabagun Digital (NYSE:PEW) reported second-quarter revenue growth and a sharp improvement in gross margin as higher-priced firearms sales, pricing initiatives and product mix supported profitability at the gross-profit level. The company also highlighted early progress at its PEW Logistics platform and announced a planned chief financial officer transition.
#million #Margin #digital
Revenue and gross margin improved: Second-quarter revenue rose 9.4% to $23.2 million, while gross profit increased 39% to $3.1 million and gross margin expanded to 13.5%. Growth was driven by higher-priced firearms, larger customer orders, pricing optimization and favorable product mix.
Profitability remained pressured by investment costs: Operating expenses climbed to $5.7 million due to public-company costs, PEW Logistics investments and added infrastructure, resulting in a $1.8 million net loss and $1.7 million adjusted EBITDA loss.
PEW Logistics is expanding, while leadership changes: The platform processed more than $1.9 million in gross merchandise value and added Backwoods Suppressors as its third manufacturer partner. CFO and co-founder Justin Hilty plans to retire and will be succeeded by Jonathan Terry, formerly of YETI.
Grabagun Digital (NYSE:PEW) reported second-quarter revenue growth and a sharp improvement in gross margin as higher-priced firearms sales, pricing initiatives and product mix supported profitability at the gross-profit level. The company also highlighted early progress at its PEW Logistics platform and announced a planned chief financial officer transition.
#million #Margin #digital

2 months ago
Platinum ****** et Management, an investment management company, released its Q2 2026 investor letter for "Platinum International Brands Fund". A copy of the letter can be downloaded here. The fund returned over 4% in the quarter but lost 14% over the past year, primarily due to the dominance of tech stocks amid an AI investment boom. Consumer-focused sectors underperformed due to weak sentiment and challenges such as high interest rates and rising oil prices, which have contributed to record-low consumer confidence. However, the fund's holdings remain fundamentally strong, with top holdings averaging 13% sales growth and 19% profit growth. The letter noted that positive developments include resumed job growth, reduced oil prices, and easing fiscal policy, which potentially enhance consumer sentiment. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Platinum International Brands Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On July 28, 2026, Zoetis Inc. (NYSE:ZTS) closed at $77.51 per share. One-month return of Zoetis Inc. (NYSE:ZTS) was 6.98%, and its shares lost 47.91% over the past 52 weeks. Zoetis Inc. (NYSE:ZTS) has a market capitalization of about $32.49 billion.
Platinum International Brands Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor update:
"Our worst performer was Zoetis (-35%). Simply, we got this wrong. Zoetis Inc. (NYSE:ZTS) makes medicines for pets and livestock and has long been the great innovator of its field, having pioneered and dominated the huge markets for canine dermatology and three-in-one parasiticides.
Unfortunately, its rivals have caught up and its commercial response has disappointed. In fairness, it likely expected its promising new arthritis treatment to comfortably offset any erosion. However, a social media scare campaign derailed its US launch largely because their commercial response was again inadequate.
#brands #investor
In its Q2 2026 investor letter, Platinum International Brands Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On July 28, 2026, Zoetis Inc. (NYSE:ZTS) closed at $77.51 per share. One-month return of Zoetis Inc. (NYSE:ZTS) was 6.98%, and its shares lost 47.91% over the past 52 weeks. Zoetis Inc. (NYSE:ZTS) has a market capitalization of about $32.49 billion.
Platinum International Brands Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor update:
"Our worst performer was Zoetis (-35%). Simply, we got this wrong. Zoetis Inc. (NYSE:ZTS) makes medicines for pets and livestock and has long been the great innovator of its field, having pioneered and dominated the huge markets for canine dermatology and three-in-one parasiticides.
Unfortunately, its rivals have caught up and its commercial response has disappointed. In fairness, it likely expected its promising new arthritis treatment to comfortably offset any erosion. However, a social media scare campaign derailed its US launch largely because their commercial response was again inadequate.
#brands #investor

2 months ago
Shares of Iqvia (IQV) surged past a buy point Tuesday after the provider of clinical research services beat second-quarter estimates and raised guidance.
Revenue climbed 8.7% to $4.368 billion year over year, while adjusted earnings increased 12% to $3.15 a share. ****** ysts, on average, expected revenue of $4.310 billion. The consensus earnings estimate was $3.03 per share, with the highest estimate at $3.08, according to FactSet.
Second-quarter new bookings rose 19% to $3.15 billion. The backlog for its Research & Development Solutions business (which handles clinical trials) was $34.2 billion. Iqvia expects that about $9.2 billion of it will convert to revenue over the next 12 months.
Citing improved organic revenue growth, the company raised full-year revenue guidance to $17.275 billion-$17.475 billion, an increase of 6.5% at the midpoint. It had earlier forecast a 5.8% increase. The new guidance ****** umes about 200 basis points from acquisitions vs. 150 basis points in the previous guidance. It expects a smaller tailwind from foreign exchange than before.
Durham, N.C.-based Iqvia also forecast adjusted EPS of $12.80 to $13 for 2026. The previous guidance was $12.65 to $12.95.
#second #clinical #quarter #raised
Revenue climbed 8.7% to $4.368 billion year over year, while adjusted earnings increased 12% to $3.15 a share. ****** ysts, on average, expected revenue of $4.310 billion. The consensus earnings estimate was $3.03 per share, with the highest estimate at $3.08, according to FactSet.
Second-quarter new bookings rose 19% to $3.15 billion. The backlog for its Research & Development Solutions business (which handles clinical trials) was $34.2 billion. Iqvia expects that about $9.2 billion of it will convert to revenue over the next 12 months.
Citing improved organic revenue growth, the company raised full-year revenue guidance to $17.275 billion-$17.475 billion, an increase of 6.5% at the midpoint. It had earlier forecast a 5.8% increase. The new guidance ****** umes about 200 basis points from acquisitions vs. 150 basis points in the previous guidance. It expects a smaller tailwind from foreign exchange than before.
Durham, N.C.-based Iqvia also forecast adjusted EPS of $12.80 to $13 for 2026. The previous guidance was $12.65 to $12.95.
#second #clinical #quarter #raised

2 months ago
By Ross Kerber, Bianca Flowers and Simon Jessop
July 28 (Reuters) - As U.S. President Donald Trump intensifies his campaign against diversity programs, appointments of women and racial minorities to S&P 500 boards have dropped to their lowest level in more than a decade, threatening to unwind years of gains in corporate boardroom diversity.
The shift is evident in new research by recruiting firms that study leadership diversity and Reuters interviews with more than a dozen boardroom recruiters, investors and human resource ******* ysts.
It follows a series of Trump administration actions targeting diversity, equity and inclusion initiatives known as DEI. Across corporate America, major investors who once pressed companies to diversify their boards have retreated, while legal challenges have upended DEI policies in recent years.
RECORD DIVERSITY MASKS SHIFT IN NEW APPOINTMENTS
#Trump #shift #boards #investors
July 28 (Reuters) - As U.S. President Donald Trump intensifies his campaign against diversity programs, appointments of women and racial minorities to S&P 500 boards have dropped to their lowest level in more than a decade, threatening to unwind years of gains in corporate boardroom diversity.
The shift is evident in new research by recruiting firms that study leadership diversity and Reuters interviews with more than a dozen boardroom recruiters, investors and human resource ******* ysts.
It follows a series of Trump administration actions targeting diversity, equity and inclusion initiatives known as DEI. Across corporate America, major investors who once pressed companies to diversify their boards have retreated, while legal challenges have upended DEI policies in recent years.
RECORD DIVERSITY MASKS SHIFT IN NEW APPOINTMENTS
#Trump #shift #boards #investors


2 months ago
Argentina's massive shale oil and gas boom is going from strength to strength. The economically crisis-prone South American country yet again reported record monthly oil and natural gas production for May 2026. This couldn't come at a better time for Argentina and South America. Rising global geopolitical risks, notably due to war in the Middle East, and domestic economic hazards hold the potential to derail the significant economic gains Argentina has made over the last two years.
Ministry of Economy data shows May 2026 oil production hit an all-time high of 887,227 barrels per day. This represents a 0.6% increase month over month and is an impressive 19% greater than the same period a year earlier. Natural gas output also rose to 5.5 billion cubic feet per day, which was just shy of the record 5.7 billion cubic feet daily reported for July 2025. Indeed, May 2026 natural gas production was 5.4% greater than a month prior and a stunning 11% higher year over year.
It is the massive shale boom underway in the 8.6-million-acre Vaca Muerta formation that is responsible for this solid production growth. For May 2026, shale oil comprised 70.6% of Argentina's total oil production, while shale gas made up 69.8% of total output. Those ratios are at record highs for shale oil and gas as a proportion of Argentina's total hydrocarbon output. This is a game changer for Argentina, which recently overtook Colombia to cement its place as South America's fourth largest oil producer.
The Vaca Muerta shale formation, which is regularly compared to the Eagle Ford shale, is in the early stages of development. Drillers in the formation are still in that phase of deciding where the core producing areas are located. The Vaca Muerta is regarded as one of the most promising unconventional oil and gas plays globally, containing an estimated 16 billion barrels of recoverable oil and 308 trillion cubic feet of recoverable natural gas resources. This all points to tremendous future unconventional hydrocarbon production growth for Argentina.
Many of the Vaca Muerta shale formation's characteristics are superior to U.S. shales, even the prolific Permian, which is the largest oil-producing basin in the United States. The formation's shale is significantly thicker than the Permian, with it estimated to be at least double the width, allowing for more horizontal landings per pad and more frac stages per well. The Vaca Muerta's organic content exceeds that found in most U.S. shale plays, while its reservoir pressure is significantly higher.
#record
Ministry of Economy data shows May 2026 oil production hit an all-time high of 887,227 barrels per day. This represents a 0.6% increase month over month and is an impressive 19% greater than the same period a year earlier. Natural gas output also rose to 5.5 billion cubic feet per day, which was just shy of the record 5.7 billion cubic feet daily reported for July 2025. Indeed, May 2026 natural gas production was 5.4% greater than a month prior and a stunning 11% higher year over year.
It is the massive shale boom underway in the 8.6-million-acre Vaca Muerta formation that is responsible for this solid production growth. For May 2026, shale oil comprised 70.6% of Argentina's total oil production, while shale gas made up 69.8% of total output. Those ratios are at record highs for shale oil and gas as a proportion of Argentina's total hydrocarbon output. This is a game changer for Argentina, which recently overtook Colombia to cement its place as South America's fourth largest oil producer.
The Vaca Muerta shale formation, which is regularly compared to the Eagle Ford shale, is in the early stages of development. Drillers in the formation are still in that phase of deciding where the core producing areas are located. The Vaca Muerta is regarded as one of the most promising unconventional oil and gas plays globally, containing an estimated 16 billion barrels of recoverable oil and 308 trillion cubic feet of recoverable natural gas resources. This all points to tremendous future unconventional hydrocarbon production growth for Argentina.
Many of the Vaca Muerta shale formation's characteristics are superior to U.S. shales, even the prolific Permian, which is the largest oil-producing basin in the United States. The formation's shale is significantly thicker than the Permian, with it estimated to be at least double the width, allowing for more horizontal landings per pad and more frac stages per well. The Vaca Muerta's organic content exceeds that found in most U.S. shale plays, while its reservoir pressure is significantly higher.
#record

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a relatively safe and steady way to grow your cash, consider a CD or bond ladder. These two strategies are designed to manage interest rate risk and provide periodic access to your cash.
But which option is better for your goals? Learn what CD ladders and bond ladders are, the key differences between them, and how to decide which one you should choose.
A CD ladder is a strategy in which you spread your money across multiple certificates of deposit (CDs) with staggered maturity dates. As each CD matures, you get access to a portion of your cash over time instead of waiting for a singular maturity date to access all of your funds at once.
This strategy can help mitigate risk by giving you the recurring opportunity to either renew individual CDs or withdraw your cash. It also lets you take advantage of whichever CD term is offering the best interest rate.
#bond
If you're looking for a relatively safe and steady way to grow your cash, consider a CD or bond ladder. These two strategies are designed to manage interest rate risk and provide periodic access to your cash.
But which option is better for your goals? Learn what CD ladders and bond ladders are, the key differences between them, and how to decide which one you should choose.
A CD ladder is a strategy in which you spread your money across multiple certificates of deposit (CDs) with staggered maturity dates. As each CD matures, you get access to a portion of your cash over time instead of waiting for a singular maturity date to access all of your funds at once.
This strategy can help mitigate risk by giving you the recurring opportunity to either renew individual CDs or withdraw your cash. It also lets you take advantage of whichever CD term is offering the best interest rate.
#bond

2 months ago
American Airlines Group (NASDAQ:AAL) reported better-than-expected second-quarter earnings on Thursday, but its shares fell more than 5% in premarket trading after the carrier issued a weaker-than-anticipated profit outlook for the third quarter and the full year.
While record revenue reflected continued demand for travel, higher fuel costs weighed on the company's earnings forecast.
American Airlines posted adjusted earnings of $0.15 per share for the second quarter, well above **** ysts' consensus estimate of $0.03.
Revenue reached a record $16.7 billion, an increase of 16.3% from the same period last year and broadly in line with Wall Street expectations.
Despite the stronger quarterly performance, investors focused on the company's cautious guidance, sending the stock lower in premarket trading.
#quarter
While record revenue reflected continued demand for travel, higher fuel costs weighed on the company's earnings forecast.
American Airlines posted adjusted earnings of $0.15 per share for the second quarter, well above **** ysts' consensus estimate of $0.03.
Revenue reached a record $16.7 billion, an increase of 16.3% from the same period last year and broadly in line with Wall Street expectations.
Despite the stronger quarterly performance, investors focused on the company's cautious guidance, sending the stock lower in premarket trading.
#quarter

2 months ago
Energy stocks have regained momentum in 2026. Oil prices remain well above their long-term averages, global demand for liquefied natural gas (LNG) continues to grow, and electricity consumption is accelerating as artificial intelligence (AI) data centers and electrification place new demands on the power grid.
Not every energy company will benefit equally. But if you're looking for stocks with clear catalysts over the next 12 months, these three stand out.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
ExxonMobil (NYSE: XOM) has built one of the oil industry's lowest-cost, highest-return businesses. And its biggest advantage is Guyana, where the company has now discovered more than 11 billion barrels of recoverable oil equivalent, making it one of the largest oil discoveries in decades. Production recently surpassed 700,000 barrels per day, and management expects Guyana to produce about 1.7 million barrels per day by 2030.
That country is also one of the world's lowest-cost oil sources, with break-even prices estimated at less than $35 per barrel. That allows Exxon to remain highly profitable even if crude prices sink.
#guyana #energy #flashing #remain
Not every energy company will benefit equally. But if you're looking for stocks with clear catalysts over the next 12 months, these three stand out.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
ExxonMobil (NYSE: XOM) has built one of the oil industry's lowest-cost, highest-return businesses. And its biggest advantage is Guyana, where the company has now discovered more than 11 billion barrels of recoverable oil equivalent, making it one of the largest oil discoveries in decades. Production recently surpassed 700,000 barrels per day, and management expects Guyana to produce about 1.7 million barrels per day by 2030.
That country is also one of the world's lowest-cost oil sources, with break-even prices estimated at less than $35 per barrel. That allows Exxon to remain highly profitable even if crude prices sink.
#guyana #energy #flashing #remain

2 months ago
US drug and medical supplies distributor Cardinal Health has simultaneously acquired urology-focused medical supplier Strive Medical and AdaptHealth's diabetes business in a deal duo totalling $360m that is positioned to advance its home care business service provision.
Regarding diabetes, the buyout of AdaptHealth's business unit follows Cardinal's buyout of Advanced Diabetes Supply (ADS) in April 2025.
Meanwhile, the acquisition of Strive Medical follows Cardinal's recent moves to advance its urology provision, with the $1.9bn buyout of Solaris Health in August 2025, Academic Urology & Urogynecology in the same month, and buyouts of Urology America and Potomac Urology in April 2025.
The latest acquisition duo is intended to support the advancement of Cardinal's at-home solutions business while expanding its ability to "deliver high-quality service at scale", the company stated.
"These strategic transactions build on the synergies created by our recent investments in home care," said Cardinal CEO Jason Hollar.
#diabetes
Regarding diabetes, the buyout of AdaptHealth's business unit follows Cardinal's buyout of Advanced Diabetes Supply (ADS) in April 2025.
Meanwhile, the acquisition of Strive Medical follows Cardinal's recent moves to advance its urology provision, with the $1.9bn buyout of Solaris Health in August 2025, Academic Urology & Urogynecology in the same month, and buyouts of Urology America and Potomac Urology in April 2025.
The latest acquisition duo is intended to support the advancement of Cardinal's at-home solutions business while expanding its ability to "deliver high-quality service at scale", the company stated.
"These strategic transactions build on the synergies created by our recent investments in home care," said Cardinal CEO Jason Hollar.
#diabetes

3 months ago
Meta Platforms (META) shares are inching higher on Thursday after the tech behemoth said it will invest $9 billion to set up its first-ever Canadian data center in Alberta.
The 1-gigawatt facility will be dedicated to scaling its massive artificial intelligence (AI) workload and Llama models, the company's management confirmed in a press release.
Jeff Bezos Says 'We Don't Have a Revenue Problem' in America — Bottom Half Paying Just 3% of Taxes Means 'We Can Find 3%'
SpaceX Has Massive Multiyear Put Options Volume As SPCX Falls Below IPO Price
Intel Stock Is 'Too Good to Ignore' as HSBC Sets a New Street-High Price Target
The 1-gigawatt facility will be dedicated to scaling its massive artificial intelligence (AI) workload and Llama models, the company's management confirmed in a press release.
Jeff Bezos Says 'We Don't Have a Revenue Problem' in America — Bottom Half Paying Just 3% of Taxes Means 'We Can Find 3%'
SpaceX Has Massive Multiyear Put Options Volume As SPCX Falls Below IPO Price
Intel Stock Is 'Too Good to Ignore' as HSBC Sets a New Street-High Price Target


3 months ago
Interested in Amazon.com, Inc.? Here are five stocks we like better.
Hyperscalers like Amazon are shifting away from commercial GPUs toward proprietary chips such as Trainium 3, pushing Taiwanese suppliers to raise shipment volumes sharply.
Amazon is pricing reserved GPU capacity higher while its AWS custom silicon pipeline reaches an estimated $225 billion in committed customer revenue.
Taiwan Semiconductor Manufacturing Co. benefits as the sole foundry for major hyperscalers' custom chips, running 3nm capacity at full utilization with expanding margins.
Hyperscalers are quietly ending their dependence on legacy graphics processing unit (GPU) makers by aggressively migrating to building their own chips. For years, the major cloud providers operated essentially as toll collectors. They bought commercial GPUs off the shelf at a premium and rented out that compute power to enterprise clients.
Hyperscalers like Amazon are shifting away from commercial GPUs toward proprietary chips such as Trainium 3, pushing Taiwanese suppliers to raise shipment volumes sharply.
Amazon is pricing reserved GPU capacity higher while its AWS custom silicon pipeline reaches an estimated $225 billion in committed customer revenue.
Taiwan Semiconductor Manufacturing Co. benefits as the sole foundry for major hyperscalers' custom chips, running 3nm capacity at full utilization with expanding margins.
Hyperscalers are quietly ending their dependence on legacy graphics processing unit (GPU) makers by aggressively migrating to building their own chips. For years, the major cloud providers operated essentially as toll collectors. They bought commercial GPUs off the shelf at a premium and rented out that compute power to enterprise clients.

3 months ago
For years electric vehicles were the auto industry's most significant growth story.
That story has become more complicated.
Demand has been patchy. Losses have stung. Car producers have been compelled to re-evaluate how swiftly they should invest in battery factories, electric lorries and software-heavy automobiles.
Now, Bank of America sees a different kind of potential emerging from that same industrial foundation.
The timing is everything. The artificial intelligence explosion is presenting a big electrical dilemma for technology companies, utilities and industrial suppliers.
That story has become more complicated.
Demand has been patchy. Losses have stung. Car producers have been compelled to re-evaluate how swiftly they should invest in battery factories, electric lorries and software-heavy automobiles.
Now, Bank of America sees a different kind of potential emerging from that same industrial foundation.
The timing is everything. The artificial intelligence explosion is presenting a big electrical dilemma for technology companies, utilities and industrial suppliers.

3 months ago
Viking Therapeutics (NASDAQ: VKTX) stock rose by 19.2% in June, according to data from S&P Global Market Intelligence. The move comes as optimism rises over the company's pipeline development program, notably in weight-loss drugs, and the initiation of a Phase 1 study in a new class of weight-loss drugs that offers a different mechanism from the current GLP-1/GIP class.
Speaking of GLP-1/GIP class drugs, Viking's lead drug candidate, VK2735, is a GLP-1/GIP agonist. It's part of a crowded field that includes blockbuster weight loss drugs from Eli Lilly (NYSE: LLY) and Novo Nordisk (NYSE: NVO).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That said, VK2735 does have some distinguishing characteristics that mark it out from rivals. As previously discussed, VK2735 has demonstrated a steeper rate of weight loss in the treated groups in Phase 2 clinical trials for both oral and injectable formulations. The hope is that Viking will demonstrate similar efficacy with no safety or tolerability issues in the ongoing Phase 3 trial for injectable VK2735, as well as in the Phase 3 trial for oral VK2735, which is due to start later this year. Investors will probably have to wait until 2027 and 2028, respectively, for the results of those trials.
The second major plus about VK2735 is that it's being developed as a dual-formulation therapy, with the potential for an initial injectable dose to achieve rapid weight loss, followed by an orally administered maintenance dose. In fact, Viking has an ongoing Phase 1 maintenance trial with initial results (for the 19-week injectable dose) due in the third quarter, followed by results for the oral maintenance dose, set for early 2027.
Speaking of GLP-1/GIP class drugs, Viking's lead drug candidate, VK2735, is a GLP-1/GIP agonist. It's part of a crowded field that includes blockbuster weight loss drugs from Eli Lilly (NYSE: LLY) and Novo Nordisk (NYSE: NVO).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That said, VK2735 does have some distinguishing characteristics that mark it out from rivals. As previously discussed, VK2735 has demonstrated a steeper rate of weight loss in the treated groups in Phase 2 clinical trials for both oral and injectable formulations. The hope is that Viking will demonstrate similar efficacy with no safety or tolerability issues in the ongoing Phase 3 trial for injectable VK2735, as well as in the Phase 3 trial for oral VK2735, which is due to start later this year. Investors will probably have to wait until 2027 and 2028, respectively, for the results of those trials.
The second major plus about VK2735 is that it's being developed as a dual-formulation therapy, with the potential for an initial injectable dose to achieve rapid weight loss, followed by an orally administered maintenance dose. In fact, Viking has an ongoing Phase 1 maintenance trial with initial results (for the 19-week injectable dose) due in the third quarter, followed by results for the oral maintenance dose, set for early 2027.

3 months ago
AbbVie Inc. (NYSE:ABBV) is one of the top trending US stocks to buy now. AbbVie Inc. (NYSE:ABBV) and Apogee Therapeutics announced on June 22 their entry into a definitive agreement under which AbbVie Inc. (NYSE:ABBV) will acquire Apogee and its diverse pipeline of multiple clinical-stage candidates in development across immunological and inflammatory diseases, which includes asthma and atopic dermatitis. Management stated that the acquisition complements the company's present immunology portfolio and bolsters its clinical presence in the respiratory **** e.
The company further stated that, according to the terms of the transaction, AbbVie Inc. (NYSE:ABBV) will acquire all outstanding shares of Apogee for $135.11 per share in cash, with the transaction valuing Apogee at a total equity value of approximately $10.9 billion. The transaction was unanimously approved by the boards of directors of both companies, and management expects the transaction to close in fiscal Q3 2026. This is subject to customary closing conditions, including Apogee shareholder approval and receipt of regulatory approvals.
AbbVie Inc. (NYSE:ABBV) is a research-based pharmaceutical company that develops and sells products to treat chronic diseases in oncology, gastroenterology, rheumatology, dermatology, virology, and various other serious health conditions.
While we acknowledge the potential of ABBV as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.
The company further stated that, according to the terms of the transaction, AbbVie Inc. (NYSE:ABBV) will acquire all outstanding shares of Apogee for $135.11 per share in cash, with the transaction valuing Apogee at a total equity value of approximately $10.9 billion. The transaction was unanimously approved by the boards of directors of both companies, and management expects the transaction to close in fiscal Q3 2026. This is subject to customary closing conditions, including Apogee shareholder approval and receipt of regulatory approvals.
AbbVie Inc. (NYSE:ABBV) is a research-based pharmaceutical company that develops and sells products to treat chronic diseases in oncology, gastroenterology, rheumatology, dermatology, virology, and various other serious health conditions.
While we acknowledge the potential of ABBV as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.

3 months ago
Antipodes Partners published its "Antipodes Global Strategy" first-quarter 2026 investor letter, highlighting the key performance stocks, portfolio changes, and the market outlook. A copy of the letter can be downloaded here. The first quarter of 2026 was highly volatile. Early optimism shifted to a historic energy shock caused by US-Israeli strikes on Iran. Global equities dropped 3.2% in USD, with US equities falling 4.6%, and value stocks outperformed growth stocks as the rotation away from mega-cap tech accelerated due to AI fears. The strategy outperformed the benchmark over the quarter and the 12 months to March 31, 2026. Exposure in North America, Korea, Western Europe, and Latin America regions boosted performance, while Canada and the UK lagged. Energy, consumer discretionary, industrials, and healthcare sectors led the performance, while financials, real estate, and materials lagged. To manage risk, the firm increased its holdings in defensive sectors during the quarter. For insights into their key selections for 2026, please review the Strategy's top five holdings.
In its first-quarter 2026 investor letter, Antipodes Global Strategy highlighted Keysight Technologies, Inc. (NYSE:KEYS) as a notable contributor. Keysight Technologies, Inc. (NYSE:KEYS) is a technology company that designs and manufactures electronic design and test solutions for communications, electronics, and aerospace and defense (A&D) industries. On June 24, 2026, Keysight Technologies, Inc. (NYSE:KEYS) closed at $351.30 per share. One-month return of Keysight Technologies, Inc. (NYSE:KEYS) was 3.59%, and its shares gained 112.99% over the past 52 weeks. Keysight Technologies, Inc. (NYSE:KEYS) has a market capitalization of $60.04 billion.
Antipodes Global Strategy stated the following regarding Keysight Technologies, Inc. (NYSE:KEYS) in its Q1 2026 investor letter:
"Electronics testing company Keysight Technologies, Inc. (NYSE:KEYS) pushed higher following a Q1 FY26 earnings beat and raised outlook. The company reported revenue and EPS exceeding forecasts, demonstrating accelerating demand across communications, aerospace/defence and semiconductor testing markets. Results were supported by strong order growth (~22 % year-on-year) and improving backlog, which led to an uplift in earnings expectations. Management highlighted structural drivers including AI infrastructure, next-generation connectivity and defence modernisation as key tailwinds."
Keysight Technologies, Inc. (NYSE:KEYS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 66 hedge fund portfolios held Keysight Technologies, Inc. (NYSE:KEYS) at the end of the fourth quarter, up from 51 in the previous quarter. Keysight Technologies, Inc. (NYSE:KEYS) revenue grew 31% on a reported basis in the second quarter of fiscal 2026 to $1.72 billion. While we acknowledge the potential of Keysight Technologies, Inc. (NYSE:KEYS) as an investment, we believe cer
In its first-quarter 2026 investor letter, Antipodes Global Strategy highlighted Keysight Technologies, Inc. (NYSE:KEYS) as a notable contributor. Keysight Technologies, Inc. (NYSE:KEYS) is a technology company that designs and manufactures electronic design and test solutions for communications, electronics, and aerospace and defense (A&D) industries. On June 24, 2026, Keysight Technologies, Inc. (NYSE:KEYS) closed at $351.30 per share. One-month return of Keysight Technologies, Inc. (NYSE:KEYS) was 3.59%, and its shares gained 112.99% over the past 52 weeks. Keysight Technologies, Inc. (NYSE:KEYS) has a market capitalization of $60.04 billion.
Antipodes Global Strategy stated the following regarding Keysight Technologies, Inc. (NYSE:KEYS) in its Q1 2026 investor letter:
"Electronics testing company Keysight Technologies, Inc. (NYSE:KEYS) pushed higher following a Q1 FY26 earnings beat and raised outlook. The company reported revenue and EPS exceeding forecasts, demonstrating accelerating demand across communications, aerospace/defence and semiconductor testing markets. Results were supported by strong order growth (~22 % year-on-year) and improving backlog, which led to an uplift in earnings expectations. Management highlighted structural drivers including AI infrastructure, next-generation connectivity and defence modernisation as key tailwinds."
Keysight Technologies, Inc. (NYSE:KEYS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 66 hedge fund portfolios held Keysight Technologies, Inc. (NYSE:KEYS) at the end of the fourth quarter, up from 51 in the previous quarter. Keysight Technologies, Inc. (NYSE:KEYS) revenue grew 31% on a reported basis in the second quarter of fiscal 2026 to $1.72 billion. While we acknowledge the potential of Keysight Technologies, Inc. (NYSE:KEYS) as an investment, we believe cer




