
5 days ago
Disney's 2006 all-stock Pixar deal gave Jobs about 138 million DIS shares worth $3.5 billion, outpacing his AAPL stake by more than 4 times.
Apple stock rose about 4 times from its 2006 level while Disney gained just 1.23 times, narrowing the gap between Jobs's two largest holdings by 2011.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Steve Jobs lost his place at Apple (NASDAQ:AAPL) in 1985. What he did next ended up tying his fortune to Disney (NYSE:DIS) as much as to the company he co-founded.
#times #Apple
23 days ago
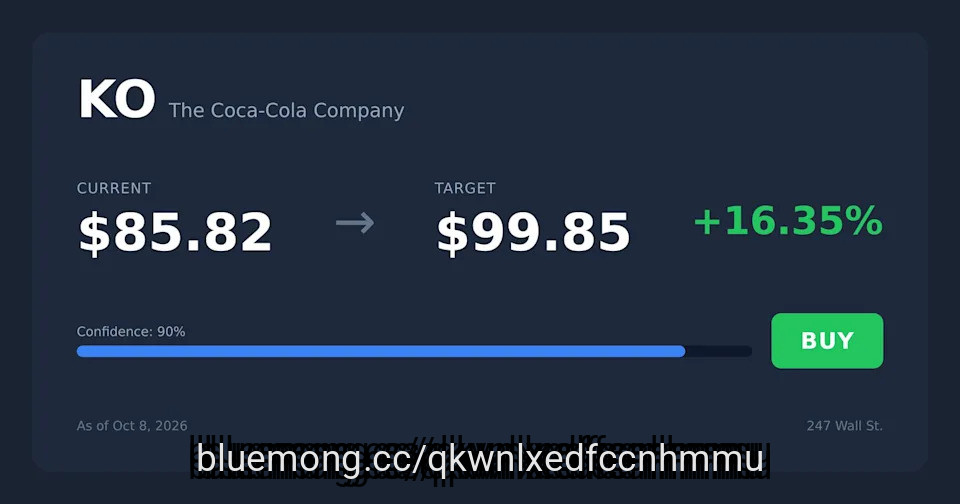
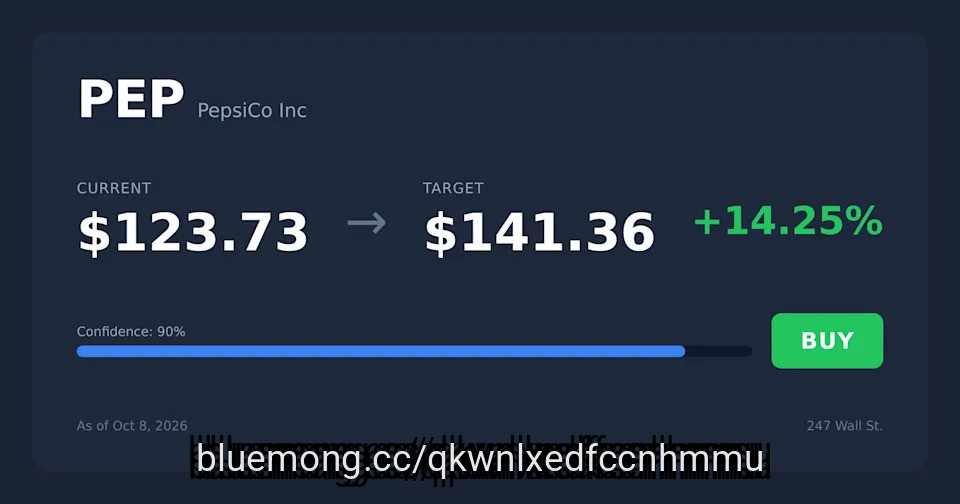
Coca-Cola ($KO) beats PepsiCo ($PEP) for generational portfolios with 63 consecutive dividend increases, wider margins, and 182% 10-year share gains versus 60%.
PepsiCo's free cash flow barely covers its 4.44% dividend yield, while Coca-Cola's expected $12.4B free cash flow dwarfs its $8.8B dividend payout.
A pending IRS appeals ruling and a premium P/E of 28 are the two risks that could crack Coca-Cola's otherwise dominant long-term case.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coca-Cola didn't make the cut. Enter your email to see the names that beat KO. The report is free. Enter your email and see if any of your stocks made the cut.
Coca-Cola (NYSE:KO) or PepsiCo (NASDAQ:PEP): Which one better suits someone investing for retirement right now, knowing the shares may pass to the next generation? Looked at over several decades, Coca-Cola wins. PepsiCo pays the bigger yield today. Coca-Cola has the safer dividend, the stronger brand economics and fewer structural cracks.
#stocks


25 days ago
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
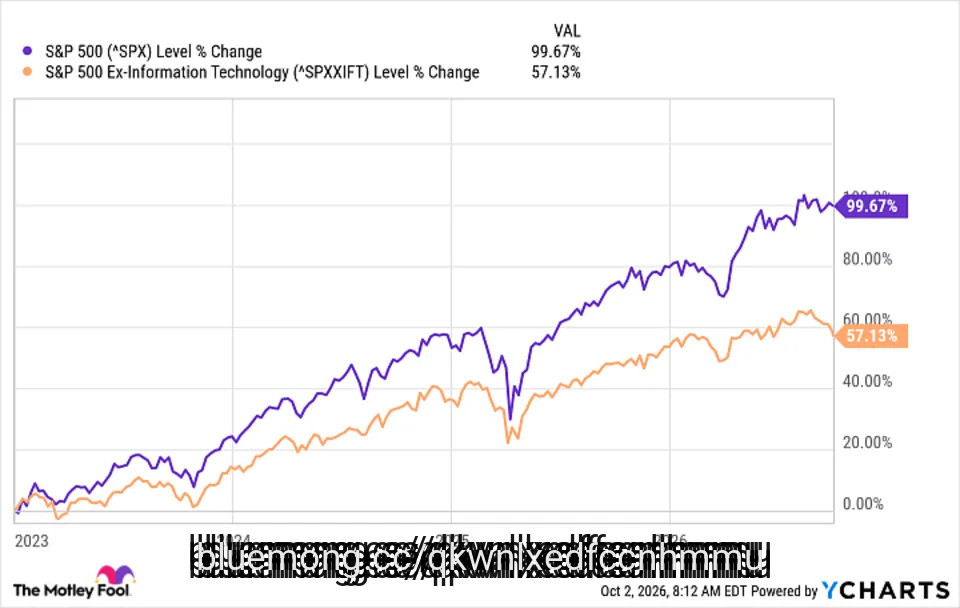
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing

1 month ago
Titan International, Inc. (NYSE:TWI) announced a definitive agreement on September 21 to sell its Italtractor ITM undercarriage business to USCO S.p.A. The initial purchase price is approximately $207 million, while the stated total cash value reaches up to approximately $285 million. Understanding that difference is central to ******* sing the financial flexibility the disposal could create.
Titan International, Inc. (NYSE:TWI) expects approximately $23 million from closing adjustments and $11 million in dividends before closing. A further $6 million depends on ITM meeting specified 2026 performance criteria. The headline also includes $38 million in dividends received in earlier years.
Subtracting those historical dividends leaves approximately $247 million in potential future gross receipts, including the earnout, or $241 million without it. These calculations use the announced estimates and span different payment dates. Final adjustments, taxes, and transaction costs will determine how much cash becomes available for deployment.
The disclosed dollar amounts were translated at €1.00 to $1.148, the September 18, 2026 exchange rate. Currency movements could increase or reduce the eventual dollar receipts.
Titan International, Inc. (NYSE:TWI) intends to use part of the proceeds to reduce debt and pursue growth investments, including acquisitions and partnerships. The disposal would also concentrate resources on wheel and tire operations.
#september #announced
1 month ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
1 month ago
Valero Energy Corporation (NYSE:VLO) has been on a strong rally, posting gains of over 140% since the beginning of 2026. The strong performance is fuelled by an unusually sharp surge in global refining margins as the ongoing disruptions have significantly reduced the world's refining capacity and tightened supplies of gasoline, diesel, and jet fuel.
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong

1 month ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents

1 month ago
Recent initial public offering NB Bancorp (NBBK) is the IPO Stock Of The Week as it attempts to find support at a key level and with the stock within striking distance of a new buy point. This regional banking name also sits on Investor's Business Daily's IPO Leaders screen.
Massachusetts-based NB Bancorp is the holding company for Needham Bank, which was founded in 1892.
On July 22, NB Bancorp said its earnings growth accelerated to 33% in the second quarter, up from 9% in the first quarter. That was fueled by net interest margin expansion to 4% along with solid loan and deposit growth. Revenue jumped 46% from the year-ago period, to $74.7 million.
For the third quarter, ***** ysts expect NB Bancorp to earn 59 cents per share on revenue of $77.3 million. Those are respective year-over-year increases of 30% and 49%. Also, third-quarter earnings come due in late October.
And for the full year, Wall Street expects the banking leader to earn $2.14 per share, a 25% year-over-year increase. ***** ysts see further growth of 22% in 2027, according to IBD MarketSurge.
#revenue
1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a secure place to store your savings, a certificate of deposit (CD) may be a great choice. These accounts often provide higher interest rates than traditional checking and savings accounts. However, CD rates can vary widely. Learn more about CD rates today and where to find high-yield CDs with the best rates available. Here is a look at some of the best CD rates available today from our verified partners:
Today's CD rates vary quite a bit. In general, however, CD rates have been declining for quite some time due to the Fed's decision to cut its benchmark rate three times in the latter part of 2024 and three times in 2025. Even so, with the Fed leaving rates unchanged so far in 2026, some banks are still offering competitive CD rates.
For institutions offering competitive rates, top rates reach about 4% APY. This is especially true for shorter terms of one year or less.
Today, Friday, September 18, 2026, the highest CD rate is 4.40%, and it's offered by Happen Bank on its 2-year CD.
#quite #rate


1 month ago
Generac Holdings (GNRC) shares ripped higher on Sept. 17 after management announced a multi-billion-dollar commercial partnership with Amazon (AMZN). In its press release, GNRC said its pivotal supply agreement with the cloud and e-commerce giant is designed to furnish backup power solutions for its expanding data center footprint.
The AMZN news brings much-needed reprieve to Generac stock that was otherwise down roughly 40% versus its year-to-date high in late June.
Why It's Time to Load Up on Nvidia Stock
ORCL Stock Layoffs: What to Know About the Latest Oracle Job Cuts
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#amzn #holdings #load


1 month ago
XLE has surged 46% year-to-date while XLY dropped 7%, with defensive XLP up 9% as markets rotate away from consumer exposure.
XLF's soft 4% gain signals financial stocks aren't pricing a healthy cycle, with the 10-year/2-year Treasury spread flattened to 0.33%.
Torres pegs $120 WTI as the consumer spending breaking point, still 20% above current prices but reminiscent of 2022's economy-crushing oil surge.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
The national average price of regular gasoline jumped 16 cents in a single week to $4.32 a gallon on September 14, 2026, a move that puts the pump price in the 90th percentile of the past year and caps a 7.8% jump in one month. The proximate cause sits upstream: WTI crude cleared $97.26 a barrel on September 9 after running up 16.1% in a month, and Brent has traded through the $100 line. On Fed decision day, a CNBC Morning Call panel put a number on where this stops being an inconvenience and starts being a recession.
#september #cnbc
1 month ago
The death of a spouse triggers an avalanche of decisions: paperwork, accounts, insurance claims, legal matters and well-meaning relatives with opinions about what to do with the money. Suze Orman's advice for navigating all of it is simple.
"The one crucial piece of advice I have for the surviving spouse is to move slowly and make as few financial decisions as possible," Orman wrote on her website. "The last thing you need is the stress of making big money decisions when grieving is most fierce."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#advice #make

1 month ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Every month, Washington releases a closely watched number intended to show Americans how quickly their living costs are changing.
But "Rich Dad Poor Dad" author Robert Kiyosaki says that number is not simply another piece of economic data. In his telling, it is evidence of a quiet theft that has already taken place.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A record 45% of central banks plan to grow gold reserves — and many investors are following suit. Get your free gold IRA guide from Priority Gold
#moneywise #poor
2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
He doesn't get as much media attention as Larry Fink or Bill Ackman, but David Booth, chairman of Dimensional Fund Advisors, has played a foundational role in the creation of the modern ***** et management industry. Working alongside Rex Sinquefield since the early 1980s, Booth has championed the idea that academic research is superior to Wall Street intuition.
During that time, Dimensional has grown from a fledgling business operating out of a spare room of Booth's Brooklyn brownstone to a global investment manager with $1.1 trillion in ***** ets under management. He's no longer running the company, having passed the reins to current co-CEOs Dave Butler and Gerard O'Reilly, but Booth is still intimately involved in setting Dimensional's direction at a time when innovation in the exchange-traded fund market and related trends are driving another sea change in how professional portfolios are built.
Sign up for The Daily Upside at no cost for premium ***** ysis on all your favorite stocks.
READ ALSO: Your Client's Big Tech Company Just IPO'd. Now What? and Investors Need Real Talk About Interval Funds
#company

2 months ago
Lowe's edges out Home Depot as the safer income hold, with a 6.93% FCF yield covering its 2.39% dividend yield by a far wider margin.
Home Depot's Pro contractor pivot drove 1.7% comp sales growth versus Lowe's 0.2%, but its free cash flow still shrank 22% and its payout ratio sits higher.
Lowe's steady raises from $1.05 to $1.25 quarterly signal a longer dividend growth runway than Home Depot's token 1.3% ***** p to $2.33.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Home Depot didn't make the cut. Enter your email to see the names that beat HD. The report is free. Enter your email and see if any of your stocks made the cut.
For an income investor weighing Home Depot (NYSE:HD) against Lowe's (NYSE:LOW), the real question is which dividend holds up better when the housing market stays frozen. Existing home sales sit at 3.98M annualized, the lowest reading in the trailing twelve-month history and inside what the series classifies as the soft range ***** ociated with high mortgage rates. Home Depot's CFO said housing turnover has "never been lower as a percentage of the housing stock". When people stop moving, they stop renovating. That is the identical headwind facing both payouts, and it sharpens the question of which one is actually safer.
#home #depot #Dividend #housing


2 months ago
On September 10, Piper Sandler **** yst Bill Carcache initiated coverage of Q2 Holdings, Inc. (NYSE:QTWO), giving the stock an Overweight rating and setting the price target at $82.
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue

2 months ago
A Brazilian federal judge ordered the immediate suspension of all environmental licenses held by Sigma Mineração S.A., the operating subsidiary of Sigma Lithium Corporation (NASDAQ:SGML), for the Grota do Cirilo project. The September 4 preliminary order also halted mining activities following a civil action brought by the Federation of Quilombola Communities of Minas Gerais.
The dispute centers on whether the project lies within the area of influence of the Baú Quilombola Community and therefore required free, prior, and informed consultation. The judge cited studies placing the community's territory approximately 2.7 kilometers from the project's directly affected area, within the 8-kilometer presumptive regulatory impact radius applicable to mining projects outside Brazil's Legal Amazon under Interministerial Ordinance No. 60/2015. Sigma Lithium Corporation (NASDAQ:SGML) has argued that the project is outside the relevant impact zone.
The court ordered independent georeferencing and barred Minas Gerais and its environmental agency from issuing new licenses, amendments, or corrective approvals until the community-protection requirements are completed.
Two routes remain. If independent georeferencing supports the boundary position, Sigma Lithium Corporation (NASDAQ:SGML) could seek favorable court relief modifying or reversing the suspension. This provides an alternative to completing the consultation requirements.
If the project falls within the regulated impact area, Sigma Lithium Corporation (NASDAQ:SGML) would need Incra approval of the Quilombola Component Study, Basic Quilombola Environmental Plan and Final Execution Report, plus free, prior and informed consultation with the Baú community. Completing those requirements could preserve the project if acceptable mitigation is agreed.
#corporation #sgml #project #community

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Gold can act as a hedge against inflation, but it doesn't reliably rise whenever inflation does. Some investors use gold to help preserve purchasing power as prices rise, but inflation is only one of several factors that can influence gold prices.
If you've researched gold as an investment, you've probably come across financial experts **** erting that gold is a hedge against inflation. Understanding what that actually means — and what it doesn't — can help put gold's role in an investment portfolio into perspective.
An inflation hedge is an investment or strategy intended to help offset the loss of purchasing power caused by rising prices.
As inflation rises, each dollar buys a little less than it did before. For example, imagine a cart of groceries that costs $100 today. If those same groceries cost $105 next year, your $100 no longer buys as much as it did before.
#Gold #Help #doesn 't #power


2 months ago
American Century Investments, an investment management company, released its first-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ******* ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Broadcom Inc. (NASDAQ:AVGO) as a newly added position. Broadcom Inc. (NASDAQ:AVGO) is a leading American company that designs and develops various semiconductor devices and infrastructure software solutions. On September 08, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $368.56 per share, reflecting a market capitalization of $1.75 trillion. Over the past month, Broadcom Inc. (NASDAQ:AVGO) declined 13.20%, while its shares lost 2.29% over the past 52 weeks.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO). We initiated a position in this technology conglomerate because of its leading market position in its custom ASIC and networking chips businesses. While its software businesses are mature, we believe rapid artificial intelligence-driven growth in semiconductors has been very appealing."
Broadcom Inc. (NASDAQ:AVGO) ranks 8 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 170 hedge fund portfolios held Broadcom Inc. (NASDAQ:AVGO) at the end of the second quarter, compared to 173 in the previous quarter. While we acknowledge the potential of Broadcom Inc. (NASDAQ:AVGO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#american #Investments #fund

2 months ago
SAN FRANCISCO, Calif. — Maybe there is a public embrace to be had by dueling executives Vlad Tenev and Adam Aron.
"I'm open to it, you know, I love debates. I'm open to many things," Robinhood (HOOD) co-founder and CEO Vlad Tenev told Yahoo Finance from the Goldman Sachs Communacopia & Tech Conference (video above).
A fierce public war of words erupted on X between AMC Entertainment (AMC) CEO Adam Aron (known as the "Silverback" on X) and Tenev over the brokerage's extensive use of stock tokens that track AMC shares.
Aron ignited the dispute by blasting tokenization — the practice of issuing digital versions of ***** ets, such as stocks, on a blockchain network — as "contemptible," "vile," and "disgusting," demanding a cease-and-desist order while threatening legal action.
"What's the concern?" Tenev fired back, insisting that Robinhood's debt-backed derivatives do not require permission from the underlying companies.
#vlad #open #calif #maybe


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Bitcoin (CRYPTO: $BTC) has once again formed a bullish "golden cross" chart pattern, suggesting that further gains are likely for the largest digital ******* et.
A golden cross is a closely watched and widely tracked chart pattern that investors see as a bullish momentum indicator.
The golden cross chart pattern forms when an ******* et's 50-day moving average rises above its 200-day moving average.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#Bitcoin

2 months ago
CNBC reported that The Goodyear Tire & Rubber Company (NASDAQ:GT) has extended the timeline for its "Goodyear Forward" turnaround plan after key financial targets went unmet.
CEO Mark Stewart told CNBC the company is trying to reach a 10% operating margin and generate meaningful cash flow, but debt remained above $7 billion at the end of the second quarter. Goodyear posted a $453 million net loss through the first half of the year against operating income of just $131 million, a 1.6% margin. The business has been hit by tariffs, elevated raw material costs, and expanding competition from cheaper Chinese tire imports. Capital expenditures, which ran roughly $2 billion combined in 2024 and 2025, are expected to fall to $725 million this year as the company prioritizes debt paydown and refinancing.
Copyright: baranq / 123RF Stock Photo
The core business is still generating a positive operating margin even amid a large net loss. Operating income of $131 million over six months shows The Goodyear Tire & Rubber Company (NASDAQ:GT)'s core tire operations are not losing money at the operating level, suggesting the much larger net loss stems mainly from the cost of servicing its debt rather than the core business itself failing.
Management is showing real capital discipline and not just promises since cutting planned capital expenditures to $725 million this year from roughly $1 billion annually in 2024 and 2025 combined is a measurable step toward freeing up cash for debt reduction. Moreover, tangible customer-facing investments, like the new retail concept store Stewart showcased in Detroit.
#goodyear #tire

2 months ago
NVIDIA Corporation (NASDAQ:NVDA) has officially committed billions on AI developer platform Hugging Face for a $12.9 billion. The deal signifies the chipmaker's move beyond hardware and up the AI stack.
The AI chipmaker buying the open-source model hub millions of developers are already using reads differently when compared to Broadcom's earlier forecast to double its AI chip revenue to roughly $230 billion in fiscal 2028.
Even though AVGO is facing increased competition in Google's TPU programs, it is also gaining ground with customers such as OpenAI and Anthropic. This makes Nvidia's recent move look more like insurance rather than opportunism.
In response to the acquisition, Needham ******* yst Rajvindra Gill reiterated a Buy rating on Nvidia on September 4, ******* igning a $300.00 price target.
"Yesterday, NVIDIA announced its agreement to buy Hugging Face for $12.930BN. Hugging Face is the open source platform for hosting open source and open weight models and datasets enabling developers to easily access ready-to-use models instead of building and training them from scratch."
#developers
2 months ago
Cash App segment is becoming a major driver of the growth story for Block Inc. (NYSE:XYZ) in 2026, as the underlying lending operations within the segment standout as key determinants of management's outlook for the remainder of the year. Recent initiatives around the company's proprietary credit signal support the narrative and broaden the company's lending reach. For the first time, Block will open its Cash App Score for external lenders by collaborating with Nova Credit's Cash Flow Intelligence Platform.
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#year #Growth #gross #profit
2 months ago
On July 1, QXO Inc. (NYSE:QXO) finalized its cash-and-stock acquisition of TopBuild Corp. for a $17 billion consideration. This makes QXO North America's largest distributor and installer of insulation, the largest distributor of waterproofing products, and the second-largest distributor of roofing products.. Chairman and CEO, Brad Jacobs, noted that the acquisition will enable QXO to explore rapidly expanding end markets such as data centers and broaden its product portfolio. Let's explore QXO's acquisitive growth strategy within the building products distribution segment and what potential does it offer to the company going forward.
QXO's acquisition of TopBuild is anticipated to be a highly accretive deal, with the company expecting at least $300 million of annual synergies by 2030. These will be linked with pricing, procurement, and cross-selling opportunities. Along with previous transactions involving $2.25 billion purchase of Kodiak Building Partners back in April and $11 billion acquisition of Beacon Roofing Supply in 2025, it makes QXO one of the top names across roofing, insulation, waterproofing, and building materials categories within North America.
The company's financials also appear encouraging. On August 13, QXO announced its second quarter results. The company posted $3.25 billion in revenue compared to $1.91 billion during Q2 2025. Adjusted EBITDA clocked in at $272 million, exhibiting 33% year-on-year growth. Adjusted net income came in at $130 million, up by more than 19% relative to the same period last year. The comparison, however, is influenced by acquisition timing. This is because the 2026 quarter included Kodiak and a full quarter of Beacon, while the prior-year period included Beacon only from its April 29, 2025 acquisition date.
CEO and Chairman acknowledged the company's technological progress and financial growth during the quarter. He stated:
"We are focused on our plan to more than double EBITDA by 2030 and reach $50 billion in revenue within the decade."
#building
2 months ago
On August 5, Magnolia Oil & Gas (NYSE:MGY) reported second-quarter results that more than doubled profits and cash generation from a year earlier, all while the company was in the middle of financing its biggest acquisition to date. Net income came in at $181.8 million, up 124% from $81 million, and diluted earnings per share climbed to $0.97 from $0.41. The jump traces back to a straightforward combination: stronger oil and NGL prices layered on top of steady production growth out of Giddings.
Adjusted EBITDAX reached $370.3 million for the quarter, and Magnolia spent just $125 million on drilling and completions, roughly 34% of that total. Keeping the reinvestment rate that low let free cash flow more than double year over year to $234.6 million, while the business converted revenue into operating income at a 50% pretax margin. Net cash from operations came in at $384 million, giving the company room to fund its plans without leaning hard on outside capital.
Production backed up the numbers. Total output rose 8% year over year to 106.1 Mboe/d, and oil volumes grew 5% to 41.9 Mbbls/d, both ahead of the company's own guidance. Giddings, the field doing most of the heavy lifting, grew production 10%, with oil volumes up 7%, strong enough that management raised full-year 2026 production growth guidance to 6% from 5%.
Shareholders also got a direct share of the improvement. Magnolia repurchased 1.7 million shares for $49.3 million during the quarter and raised its quarterly dividend 9% to $0.18 per share, which was payable to those who held shares as of an August 10 record date, representing an annualized $0.72. In total, the company returned $80.1 million, 34% of free cash flow, to shareholders. On July 20, Magnolia also agreed to acquire WildFire Energy. This deal will more than double its Giddings acreage and combine two complementary **** et bases into more than 1.25 million combined net acres, with drilling upside still ahead across multiple benches, among them the Woodbine, Eagle Ford, and Austin Chalk.
Paying for that acquisition isn't free. Magnolia is funding roughly half of the WildFire deal with debt and half with equity, issuing 53.3 million new shares that brought net proceeds of about $1.23 billion and adding $500 million of new debt through senior notes priced at 6.625% and maturing in 2034. Both transactions closed in the days after the quarter ended, on July 22 and August 5, meaning more shares outstanding and a new layer of fixed interest expense for a company that had just spent the quarter shrinking its own share count by 4%.
#cash #company
2 months ago
By
Sept. 4, 2026 6:16 am ET
Listen
(1 min)
Good morning, I’m filling in for Spencer Jakab. Markets are little changed this morning as investors awaited the August jobs report. But in a reminder of the inflation pressure facing the Fed, diesel prices hit a new all-time high of $5.85 a gallon, surpassing their previous record from 2022.
#sept #markets #august #filling

2 months ago
Last October, shares of NuScale Power (NYSE: SMR) hit an all-time high of about $57. Today, shares trade at just under $10, representing a massive 84% decline.
What happened? Nothing that an 84% decline might suggest: no bankruptcy, no regulatory complications, no nuclear accidents (thank goodness). The drawback was more likely a sign that investors had lost patience with an overvalued nuclear stock with no reactor operating in the real world, and no firm first customer.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Funny thing is, NuScale actually looks better positioned as a company than it did at the height of its AI-nuclear boom. Investors looking for a value may want to reconsider NuScale, especially with a multi-state project moving closer to a signed deal.
If you're new to NuScale, here's a quick catch-up: The company wants to build and sell small modular reactors (SMRs), which are essentially compact nuclear power plants designed to generate carbon-free electricity from a much smaller physical footprint than your traditional nuclear facility. It is currently the only company in the U.S. with an NRC-approved SMR design, but it has not yet built a reactor for a customer.
#nuscale #power #time

2 months ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#insm #artisan #global #quarter