
3 days ago
Investors love to check automakers' quarterly (or otherwise) delivery figures, especially when it comes to young electric vehicle (EV) makers that are surviving amid low volume and scale. Rivian's (NASDAQ: RIVN) R2 has been long-hyped, and on June 9, 2026, customers finally began receiving their prized ride. However, while Wall Street ****** ysts obsess over delivery charts and the smallest gains or losses, savvy investors know the R2 is about much more than increasing deliveries and revenue for the young EV maker. Here is one big development that's often forgotten.
One of Rivian's underappreciated strengths is its ability to bring in investment from larger companies that see value in Rivian's software technology or vehicles as a service. In this case, Rivian's mass-market R2 was a solid choice for Uber Technologies (NYSE: UBER) to add to its numerous investments for robotaxi joint ventures. Uber will invest up to $1.25 billion in Rivian through 2031, after it meets certain conditions and milestones, and the statement from Uber CEO Dara Khosrowshahi emphasizes Rivian's growing value with its vertical integration.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
"We're big believers in Rivian's approach -- designing the vehicle, compute platform, and software stack together, while maintaining end-to-end control of scaled manufacturing and supply in the U.S.," Khosrowshahi said in a press release.
Uber and Rivian expect to deploy 10,000 fully autonomous R2 robotaxis during their joint venture's first phase. San Francisco and Miami are circled in red to host the initial R2 robotaxi deployments in 2028, with the target of entering 25 additional cities by 2031. If all goes well for the joint venture, there's an option for the companies to negotiate the purchase of up to 40,000 additional R2 vehicles beginning in 2030.
#uber #delivery #young
One of Rivian's underappreciated strengths is its ability to bring in investment from larger companies that see value in Rivian's software technology or vehicles as a service. In this case, Rivian's mass-market R2 was a solid choice for Uber Technologies (NYSE: UBER) to add to its numerous investments for robotaxi joint ventures. Uber will invest up to $1.25 billion in Rivian through 2031, after it meets certain conditions and milestones, and the statement from Uber CEO Dara Khosrowshahi emphasizes Rivian's growing value with its vertical integration.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
"We're big believers in Rivian's approach -- designing the vehicle, compute platform, and software stack together, while maintaining end-to-end control of scaled manufacturing and supply in the U.S.," Khosrowshahi said in a press release.
Uber and Rivian expect to deploy 10,000 fully autonomous R2 robotaxis during their joint venture's first phase. San Francisco and Miami are circled in red to host the initial R2 robotaxi deployments in 2028, with the target of entering 25 additional cities by 2031. If all goes well for the joint venture, there's an option for the companies to negotiate the purchase of up to 40,000 additional R2 vehicles beginning in 2030.
#uber #delivery #young

4 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Record quarterly revenue of $87.1 million was driven by vigorous fleet expansion and strong market rates across both tanker and dry bulk segments.
Net income for the first half of 2026 reached $62.8 million, already exceeding the total profitability for the full year of 2025.
Operational utilization decreased to 73.5% due to a strategic decision to manage a concentrated schedule of six dry dockings to ensure future efficiency.
Suezmax rates surged in excess of $200 thousand a day following the end of the ceasefire period and Houthi-led trade disruptions in the Red Sea.
#houthi #analysts
Record quarterly revenue of $87.1 million was driven by vigorous fleet expansion and strong market rates across both tanker and dry bulk segments.
Net income for the first half of 2026 reached $62.8 million, already exceeding the total profitability for the full year of 2025.
Operational utilization decreased to 73.5% due to a strategic decision to manage a concentrated schedule of six dry dockings to ensure future efficiency.
Suezmax rates surged in excess of $200 thousand a day following the end of the ceasefire period and Houthi-led trade disruptions in the Red Sea.
#houthi #analysts
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
8 days ago
On August 5, Murphy USA (NYSE:MUSA) reported second-quarter results that make the case for its unglamorous business model. Net income came in at $209.1 million, or $11.27 per diluted share, up from $145.6 million and $7.36 per share in the same quarter of 2025. Adjusted EBITDA climbed to $377.3 million from $286.0 million. For a company that mostly sells gasoline and convenience store snacks, that is a striking jump, and it did not come from a single lucky quarter.
The engine behind the gain was fuel. Total fuel contribution reached 40.6 cents per gallon in the quarter, up from 32.0 cents a year earlier, while the retail fuel margin alone rose 20.2% to 35.1 cents per gallon. Volume grew at the same time, with total retail gallons up 3.9% and same-store sales volumes up 0.5%, so Murphy USA was not just pricing better; it was also moving more gas through its pumps. Merchandise held up its end too, with contribution dollars up 4.0% to $227.4 million on unit margins of 20.1%, as nicotine contribution rose 6.1% and non-nicotine contribution grew 2.9%.
The company kept returning cash to shareholders through it all, buying back 143.1 thousand shares for $76.8 million and raising its quarterly dividend 28.0% year over year to $0.64 per share. In May, it issued $500 million of notes due 2034 and used the proceeds to retire $300 million of 2027 notes, pushing out its debt maturities while continuing to open new stores, with 6 net additions in the quarter and 36 more under construction.
The quarter's growth came with a heavier expense load. Total store and other operating expenses rose to $308.7 million from $275.2 million, and the company said two-thirds of that increase came from payment processing fees, which climb automatically as retail fuel prices rise. SG&A costs increased to $60.5 million from $50.9 million on higher employee costs and incentive accruals, and the effective tax rate ticked up to 24.7% from 24.4%, with guidance now pointing to the higher end of the company's 23% to 25% full-year range.
Fuel supply contribution, excluding renewable credits, was negative $54.9 million, a wider loss than the negative $25.9 million posted a year earlier. Management's own full-year outlook ***** umes some cooling ahead: its projection of roughly $636 million in net income and $1.25 billion in Adjusted EBITDA is built on second-half fuel margins averaging 35 cents per gallon, down from 37.9 cents in the first half. Capital expenditures are also being guided to the higher end of the $475 million to $525 million range, meaning the spending pace is not slowing even as margins are expected to.
#million #cents #total #Share
The engine behind the gain was fuel. Total fuel contribution reached 40.6 cents per gallon in the quarter, up from 32.0 cents a year earlier, while the retail fuel margin alone rose 20.2% to 35.1 cents per gallon. Volume grew at the same time, with total retail gallons up 3.9% and same-store sales volumes up 0.5%, so Murphy USA was not just pricing better; it was also moving more gas through its pumps. Merchandise held up its end too, with contribution dollars up 4.0% to $227.4 million on unit margins of 20.1%, as nicotine contribution rose 6.1% and non-nicotine contribution grew 2.9%.
The company kept returning cash to shareholders through it all, buying back 143.1 thousand shares for $76.8 million and raising its quarterly dividend 28.0% year over year to $0.64 per share. In May, it issued $500 million of notes due 2034 and used the proceeds to retire $300 million of 2027 notes, pushing out its debt maturities while continuing to open new stores, with 6 net additions in the quarter and 36 more under construction.
The quarter's growth came with a heavier expense load. Total store and other operating expenses rose to $308.7 million from $275.2 million, and the company said two-thirds of that increase came from payment processing fees, which climb automatically as retail fuel prices rise. SG&A costs increased to $60.5 million from $50.9 million on higher employee costs and incentive accruals, and the effective tax rate ticked up to 24.7% from 24.4%, with guidance now pointing to the higher end of the company's 23% to 25% full-year range.
Fuel supply contribution, excluding renewable credits, was negative $54.9 million, a wider loss than the negative $25.9 million posted a year earlier. Management's own full-year outlook ***** umes some cooling ahead: its projection of roughly $636 million in net income and $1.25 billion in Adjusted EBITDA is built on second-half fuel margins averaging 35 cents per gallon, down from 37.9 cents in the first half. Capital expenditures are also being guided to the higher end of the $475 million to $525 million range, meaning the spending pace is not slowing even as margins are expected to.
#million #cents #total #Share

9 days ago
On August 4, Hamilton Lane (NASDAQ:HLNE) posted a first fiscal quarter that showed just how far the private markets manager has scaled. Revenue jumped 56% year over year to $275.3 million, fee-related earnings climbed 49% to $124.5 million, and the firm's total ******* et footprint pushed past $1.1 trillion. That kind of quarter would normally be the whole story. Instead, it came wrapped around three separate balance sheet payouts and a candid admission that client flows have gotten choppier than the headline numbers suggest.
Hamilton Lane's specialized funds are doing the heavy lifting. Fee-earning ******* ets under management in that category grew 25% year over year to $42.6 billion, and that mix shift toward higher-fee products pushed the blended fee rate up to 69 basis points. Management and advisory fees rose 21% to $161.4 million, and FRE margin expanded to 53% from 51% a year earlier, a sign the extra revenue is reaching the bottom line rather than getting absorbed by costs.
The Evergreen platform, Hamilton Lane's semi-liquid product line built for individual and smaller institutional investors, generated $640 million of net inflows and ended the quarter with $19 billion in ******* ets. Ten of twelve funds took in net new money, and none of them needed to gate redemptions even as the broader alternatives industry has wrestled with liquidity questions. The company also added six senior Evergreen sales professionals poached from Fidelity, BlackRock, PIMCO, JPMorgan, Morgan Stanley and Monroe Capital, and just landed its multi-strategy equity fund on a third wirehouse platform.
Fundraising on the closed-end side was equally strong. The sixth direct equity fund closed at $3.8 billion combined, 57% larger than its predecessor, while the seventh secondary fund and second venture fund each held first closes, at $1.3 billion and $370 million. On top of that, Hamilton Lane is set to book roughly $33 million in combined gains from monetizing its stakes in Russell Investments and Canoe, on top of a newly public stake in Securitize.
Not every part of the story is clean. Hamilton Lane's non-US multi-strategy equity fund swung to net outflows for the quarter, and management pointed to a broader hesitancy taking hold. Co-CEO Erik Hirsch acknowledged "a slowdown in flows on certain products and the general hesitancy with investors," a rare moment of candor from a company that otherwise leaned on strong numbers.
#fund #lane
Hamilton Lane's specialized funds are doing the heavy lifting. Fee-earning ******* ets under management in that category grew 25% year over year to $42.6 billion, and that mix shift toward higher-fee products pushed the blended fee rate up to 69 basis points. Management and advisory fees rose 21% to $161.4 million, and FRE margin expanded to 53% from 51% a year earlier, a sign the extra revenue is reaching the bottom line rather than getting absorbed by costs.
The Evergreen platform, Hamilton Lane's semi-liquid product line built for individual and smaller institutional investors, generated $640 million of net inflows and ended the quarter with $19 billion in ******* ets. Ten of twelve funds took in net new money, and none of them needed to gate redemptions even as the broader alternatives industry has wrestled with liquidity questions. The company also added six senior Evergreen sales professionals poached from Fidelity, BlackRock, PIMCO, JPMorgan, Morgan Stanley and Monroe Capital, and just landed its multi-strategy equity fund on a third wirehouse platform.
Fundraising on the closed-end side was equally strong. The sixth direct equity fund closed at $3.8 billion combined, 57% larger than its predecessor, while the seventh secondary fund and second venture fund each held first closes, at $1.3 billion and $370 million. On top of that, Hamilton Lane is set to book roughly $33 million in combined gains from monetizing its stakes in Russell Investments and Canoe, on top of a newly public stake in Securitize.
Not every part of the story is clean. Hamilton Lane's non-US multi-strategy equity fund swung to net outflows for the quarter, and management pointed to a broader hesitancy taking hold. Co-CEO Erik Hirsch acknowledged "a slowdown in flows on certain products and the general hesitancy with investors," a rare moment of candor from a company that otherwise leaned on strong numbers.
#fund #lane
9 days ago
On August 25, nCino (NASDAQ:NCNO) posted second-quarter fiscal 2027 results that outran the company's own guidance on every line item that matters. Total revenue rose 8% year over year to $161 million, subscription revenue climbed 10% to $143.5 million, and free cash flow jumped 170% to $34 million. Behind those headline numbers sits a company pushing its banking customers toward an AI-heavy pricing model while one legacy piece of the business, mortgage lending, keeps losing ground to a stubbornly high interest rate environment.
The clearest signal in nCino's quarter came from its largest customers. Four of the company's top 20 US enterprise accounts, representing institutions holding more than $900 billion in ******* ets, renewed their contracts ahead of schedule and increased their annual contract value by more than 10% on average. Those customers made the move specifically to gain access to nCino's expanding AI toolset, and 48% of total annual contract value now sits on the new platform pricing model, up from 40% just one quarter earlier.
That AI push is already producing measurable results. One enterprise customer told nCino it expects to save 160,000 hours a year, worth more than $5.5 million, just from using the company's Locate and File banking adviser tool. More than 230 customers have now purchased AI intelligence units, and management said it has begun charging some of them for additional units after they burned through their initial bundles. International expansion added to the momentum, with non-US subscription revenue up 13% to $30.9 million on new customer wins in ******* an and Germany.
The company's capital moves backed up that confidence. Non-GAAP operating income grew 36% to $40.8 million, professional services margin improved 600 basis points to 3%, and nCino repurchased 10.2 million shares for $165 million during the quarter, including the completion of a $100 million accelerated buyback program. The board then authorized another $100 million in repurchases, and full-year guidance moved higher across the board.
Not every part of the business is moving in the same direction. US mortgage subscription revenue fell 1% year over year to $20.6 million, and management cut its forecast further, now expecting about $20 million in the third quarter and $18.5 million in the fourth, reductions of $700,000 and $1.2 million from prior guidance. The culprit is the same one that has dogged the mortgage industry for two years: rates that have stayed higher for longer than expected, which is pushing independent mortgage banks toward consolidation and away from nCino's platform.
#million #customers #ncino #subscription
The clearest signal in nCino's quarter came from its largest customers. Four of the company's top 20 US enterprise accounts, representing institutions holding more than $900 billion in ******* ets, renewed their contracts ahead of schedule and increased their annual contract value by more than 10% on average. Those customers made the move specifically to gain access to nCino's expanding AI toolset, and 48% of total annual contract value now sits on the new platform pricing model, up from 40% just one quarter earlier.
That AI push is already producing measurable results. One enterprise customer told nCino it expects to save 160,000 hours a year, worth more than $5.5 million, just from using the company's Locate and File banking adviser tool. More than 230 customers have now purchased AI intelligence units, and management said it has begun charging some of them for additional units after they burned through their initial bundles. International expansion added to the momentum, with non-US subscription revenue up 13% to $30.9 million on new customer wins in ******* an and Germany.
The company's capital moves backed up that confidence. Non-GAAP operating income grew 36% to $40.8 million, professional services margin improved 600 basis points to 3%, and nCino repurchased 10.2 million shares for $165 million during the quarter, including the completion of a $100 million accelerated buyback program. The board then authorized another $100 million in repurchases, and full-year guidance moved higher across the board.
Not every part of the business is moving in the same direction. US mortgage subscription revenue fell 1% year over year to $20.6 million, and management cut its forecast further, now expecting about $20 million in the third quarter and $18.5 million in the fourth, reductions of $700,000 and $1.2 million from prior guidance. The culprit is the same one that has dogged the mortgage industry for two years: rates that have stayed higher for longer than expected, which is pushing independent mortgage banks toward consolidation and away from nCino's platform.
#million #customers #ncino #subscription
10 days ago
David Tepper is one of the greatest hedge fund managers of all time. He started Appaloosa Management in 1993 and went on to produce annualized returns of about 25% through mid-2019, at which point he had returned most of his outside investors' money.
Tepper has continued to produce excellent returns, now mostly managing his own money, taking concentrated and often contrarian positions to drive results. Appaloosa generated a massive 32% gross return in the first half of 2026 alone.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So, it's worth paying attention to the moves Tepper's making -- and you can, because he, like everyone who manages more than $100 million in **** ets, is required to disclose his fund's end-of-quarter holdings via a Form 13F four times a year.
Appaloosa's 13F for the second quarter (filed on schedule about 45 days after that period ended) showed that during the quarter, he sold two of the hottest stocks in the market: Micron (NASDAQ: MU) and Sandisk (NASDAQ: SNDK). Not only that, but he also bought put options (the right to sell shares at a set price within a preset period) on one of their biggest customers, which may suggest he sees something the market doesn't.
#signal #appaloosa
Tepper has continued to produce excellent returns, now mostly managing his own money, taking concentrated and often contrarian positions to drive results. Appaloosa generated a massive 32% gross return in the first half of 2026 alone.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So, it's worth paying attention to the moves Tepper's making -- and you can, because he, like everyone who manages more than $100 million in **** ets, is required to disclose his fund's end-of-quarter holdings via a Form 13F four times a year.
Appaloosa's 13F for the second quarter (filed on schedule about 45 days after that period ended) showed that during the quarter, he sold two of the hottest stocks in the market: Micron (NASDAQ: MU) and Sandisk (NASDAQ: SNDK). Not only that, but he also bought put options (the right to sell shares at a set price within a preset period) on one of their biggest customers, which may suggest he sees something the market doesn't.
#signal #appaloosa

11 days ago
Sept 01, 2026, 1:54 pm EDT
Berkshire Hathaway
BRK.B
+0.58%
CEO Greg Abel plans to give a TV interview Wednesday and could use the appearance to talk about any number of corporate developments, including Berkshire’s stock repurchase plan.
BRK.B
+0.58%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#berkshire #abel #wednesday #jones
Berkshire Hathaway
BRK.B
+0.58%
CEO Greg Abel plans to give a TV interview Wednesday and could use the appearance to talk about any number of corporate developments, including Berkshire’s stock repurchase plan.
BRK.B
+0.58%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#berkshire #abel #wednesday #jones

11 days ago
By Michael S. Derby
NEW YORK, Sept 1 (Reuters) - Federal Reserve Governor Michael Barr said on Tuesday that if inflation does not cool quickly, it will be time for the U.S. central bank to increase interest rates.
"Inflation remains too high — and has been for over five years," Barr said in the text of a speech prepared for delivery before the Second Chance Lending Forum.
Flagging the Fed's September 15-16 monetary policy meeting and the ******* e it gives officials to weigh policy choices, Barr said, "If inflation appears not to be moderating sufficiently, then I think we should act decisively to raise rates."
"If trends in the data give me some confidence that inflation is moderating on a path to 2%, then I think we can take a bit more time to ******* s our policy stance," he added.
#inflation #rates #derby
NEW YORK, Sept 1 (Reuters) - Federal Reserve Governor Michael Barr said on Tuesday that if inflation does not cool quickly, it will be time for the U.S. central bank to increase interest rates.
"Inflation remains too high — and has been for over five years," Barr said in the text of a speech prepared for delivery before the Second Chance Lending Forum.
Flagging the Fed's September 15-16 monetary policy meeting and the ******* e it gives officials to weigh policy choices, Barr said, "If inflation appears not to be moderating sufficiently, then I think we should act decisively to raise rates."
"If trends in the data give me some confidence that inflation is moderating on a path to 2%, then I think we can take a bit more time to ******* s our policy stance," he added.
#inflation #rates #derby

12 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Organic growth of 5% was driven by broad-based strength and an improving outlay environment, allowing for faster conversion of backlog into revenue.
Management achieved a recompete win rate exceeding 90%, which provides a secure base for future growth and reduces historical revenue headwinds.
Project Orbit has transitioned to the implementation phase, focusing on removing 'gunk' from systems through procurement rigor, automated onboarding, and Agentic AI tools.
The company is shifting toward a more disciplined bidding approach, prioritizing fewer, mission-oriented pursuits in intelligence, **** e, and national security domains.
#revenue #NVIDIA #tell #agentic
Organic growth of 5% was driven by broad-based strength and an improving outlay environment, allowing for faster conversion of backlog into revenue.
Management achieved a recompete win rate exceeding 90%, which provides a secure base for future growth and reduces historical revenue headwinds.
Project Orbit has transitioned to the implementation phase, focusing on removing 'gunk' from systems through procurement rigor, automated onboarding, and Agentic AI tools.
The company is shifting toward a more disciplined bidding approach, prioritizing fewer, mission-oriented pursuits in intelligence, **** e, and national security domains.
#revenue #NVIDIA #tell #agentic
12 days ago
Two new working papers circulated by the authoritative National Bureau of Economic Research show the double squeeze the U.S. dollar and the Treasury market are facing both overseas and at home.
The first, from a team of European Central Bank and Banque de France economists, show how official demand for dollar ******* ets is waning as central banks increasingly seek sanctuary in gold after Russian ******* ets were frozen following the launch of the war on Ukraine in 2022. It's a topic that has certainly been discussed, but the paper quantifies that shift, finding nonaligned countries have moved nearly one-third of total reserve portfolios away from foreign-currency claims.
'It's not fair': My twin brother and I were left houses by our parents. Can I make him pay his share for taxes and upkeep?
'I feel tricked': My contractor handed my $42,000 pool upgrade to a subcontractor I had already rejected. What can I do?
Perhaps the more intriguing new paper comes from Massachusetts Institute of Technology economist Ricardo Caballero, who talks about a safe-debt Laffer Curve. The Laffer Curve represents the theory that, at a certain level, revenue actually starts to fall rather than rise as tax rates increase. Caballero's novel idea is that, at a certain level, federal debt actually hurts aggregate demand rather than helps it.
#curve #central #debt
The first, from a team of European Central Bank and Banque de France economists, show how official demand for dollar ******* ets is waning as central banks increasingly seek sanctuary in gold after Russian ******* ets were frozen following the launch of the war on Ukraine in 2022. It's a topic that has certainly been discussed, but the paper quantifies that shift, finding nonaligned countries have moved nearly one-third of total reserve portfolios away from foreign-currency claims.
'It's not fair': My twin brother and I were left houses by our parents. Can I make him pay his share for taxes and upkeep?
'I feel tricked': My contractor handed my $42,000 pool upgrade to a subcontractor I had already rejected. What can I do?
Perhaps the more intriguing new paper comes from Massachusetts Institute of Technology economist Ricardo Caballero, who talks about a safe-debt Laffer Curve. The Laffer Curve represents the theory that, at a certain level, revenue actually starts to fall rather than rise as tax rates increase. Caballero's novel idea is that, at a certain level, federal debt actually hurts aggregate demand rather than helps it.
#curve #central #debt


13 days ago
Napco Security Technologies (NASDAQ:NSSC) held its fiscal fourth quarter 2026 earnings call on August 24, and the numbers it reported were close to a best-case scenario in the company's own history. Net revenue hit a quarterly record of $55.8 million, full-year revenue crossed the $200 million mark for the first time, and the company raised its dividend while sitting on $138 million in cash and zero debt. Buried in the same call, though, is a $16 million litigation charge still working its way through the income statement.
The engine under all of this is Napco's StarLink radio business, which reports monitoring fees the way a cable company reports subscriptions. Recurring service revenue reached $25.3 million in the quarter, up 12.9%, and carried a gross margin of 90.1%. Based on July 2026 activity, the company said its annualized recurring revenue run rate is now around $103 million. Starlink radio sales grew 40% year over year and 30% sequentially in the quarter, which CEO Kevin S. Buchel called one of the highest growth rates in company history, adding, "Radio sold today becomes recurring revenue tomorrow." That growth has a long runway attached, since Buchel said the shift away from copper phone lines will keep running until the end of the decade across more than 2 million buildings still needing to switch to cellular communicators.
The rest of the business held up its end too. Intrusion and access control sales rose 20.9% in the quarter, powered by a 35.8% jump in intrusion products including StarLink radios, and door locking revenue climbed 11.1% for the full year on a 19.7% increase in Alarm Lock sales. Adjusted EBITDA for the quarter grew 44.3% to $20.6 million, and full-year non-GAAP diluted EPS rose 34.5% to $1.60. Free cash flow reached $59.2 million for the year, funding a dividend increase to $0.17 per share, a 13.3% raise payable Oct. 2, 2026, while the balance sheet carried $138 million in cash and marketable securities as of June 30, 2026, and no debt at all.
The headline profit numbers hide a rougher full-year picture in one spot. A $16 million litigation settlement recorded in the fiscal third quarter pulled full-year operating income down 1.3% to $45.6 million, even though quarterly operating income jumped 52.5%. Some of the quarter's gross margin expansion to 61.3% also came from a source that will not repeat indefinitely, since about 600 basis points of it was tariff refunds tied to the American Infrastructure and Industrial Power Act. CFO Andrew J. Vuono also flagged that data center expansion is pushing up the cost of electronic parts, even as the company says it can still ship on time.
#year
The engine under all of this is Napco's StarLink radio business, which reports monitoring fees the way a cable company reports subscriptions. Recurring service revenue reached $25.3 million in the quarter, up 12.9%, and carried a gross margin of 90.1%. Based on July 2026 activity, the company said its annualized recurring revenue run rate is now around $103 million. Starlink radio sales grew 40% year over year and 30% sequentially in the quarter, which CEO Kevin S. Buchel called one of the highest growth rates in company history, adding, "Radio sold today becomes recurring revenue tomorrow." That growth has a long runway attached, since Buchel said the shift away from copper phone lines will keep running until the end of the decade across more than 2 million buildings still needing to switch to cellular communicators.
The rest of the business held up its end too. Intrusion and access control sales rose 20.9% in the quarter, powered by a 35.8% jump in intrusion products including StarLink radios, and door locking revenue climbed 11.1% for the full year on a 19.7% increase in Alarm Lock sales. Adjusted EBITDA for the quarter grew 44.3% to $20.6 million, and full-year non-GAAP diluted EPS rose 34.5% to $1.60. Free cash flow reached $59.2 million for the year, funding a dividend increase to $0.17 per share, a 13.3% raise payable Oct. 2, 2026, while the balance sheet carried $138 million in cash and marketable securities as of June 30, 2026, and no debt at all.
The headline profit numbers hide a rougher full-year picture in one spot. A $16 million litigation settlement recorded in the fiscal third quarter pulled full-year operating income down 1.3% to $45.6 million, even though quarterly operating income jumped 52.5%. Some of the quarter's gross margin expansion to 61.3% also came from a source that will not repeat indefinitely, since about 600 basis points of it was tariff refunds tied to the American Infrastructure and Industrial Power Act. CFO Andrew J. Vuono also flagged that data center expansion is pushing up the cost of electronic parts, even as the company says it can still ship on time.
#year
15 days ago
Aug 28, 2026, 4:50 pm EDT
Sometimes, stocks get everything they need—and even though the market barely moved at all, this may have been one of those weeks.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#reserved #everything
Sometimes, stocks get everything they need—and even though the market barely moved at all, this may have been one of those weeks.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#reserved #everything

16 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management reported extremely robust underlying earnings momentum, with adjusted EPS growing 38% on top of 39% growth last year, excluding the impact of tariff refunds.
The company received approximately $55 million in tariff refunds in Q2, which management has strategically decided to reinvest into the business to deliver sharper values for customers in the back half of the year.
Total sales growth of 11% was significantly driven by an aggressive new store opening program, with 178 gross new stores opened on a trailing 12-month basis.
Comp store sales increased 2%, which included a 1.5 percentage point headwind from new store cannibalization, an impact management views as acceptable given the attractive overall economics of the new store program.
#management #sales #program #NVIDIA
Management reported extremely robust underlying earnings momentum, with adjusted EPS growing 38% on top of 39% growth last year, excluding the impact of tariff refunds.
The company received approximately $55 million in tariff refunds in Q2, which management has strategically decided to reinvest into the business to deliver sharper values for customers in the back half of the year.
Total sales growth of 11% was significantly driven by an aggressive new store opening program, with 178 gross new stores opened on a trailing 12-month basis.
Comp store sales increased 2%, which included a 1.5 percentage point headwind from new store cannibalization, an impact management views as acceptable given the attractive overall economics of the new store program.
#management #sales #program #NVIDIA
17 days ago
Aristotle Capital Management, LLC, an investment management company, released its "Value Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a 4.32% total return in Q2 2026, underperforming the 13.87% gain for the Russell 1000 Value Index and the 15.20% return for the S&P 500, while its 1.99% year-to-date return also lagged the Russell 1000 Value Index's 16.26% and the S&P 500's 10.21%. The Fund attributed the performance gap largely to limited exposure to the AI infrastructure spending boom, noting that the U.S. has about 4,000 existing data centers and nearly 3,000 more planned or under construction, while AI-related demand has created bottlenecks in processors and memory. The letter highlighted the scale of the cycle, with industry cash flows in key AI hardware areas rising sharply, while the Russell 1000 Value Index's top 10 contributors gained an average 182% year to date and accounted for 9.29 percentage points of the index's 16.23% return. Looking ahead, the fund expects investors to eventually reassess the sustainability of current AI infrastructure earnings and valuations. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like Alphabet Inc. (NASDAQ:GOOGL). Alphabet Inc. (NASDAQ:GOOGL) operates Google Search, YouTube, Google Cloud, and a broad portfolio of digital products and technology businesses. The one-month return of Alphabet Inc. (NASDAQ:GOOGL) was -4.35% while its shares traded between $206.20 and $408.61 over the last 52 weeks. On August 27, 2026, Alphabet Inc. (NASDAQ:GOOGL) stock closed at approximately $342.00 per share, with a market capitalization of about $4.17 trillion.
Aristotle Value Equity Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOGL) in its Q2 2026 investor letter:
Alphabet Inc. (NASDAQ:GOOGL), the parent company of Google and YouTube, was a primary contributor during the period. We initiated our position in the first quarter of 2025, when investors were concerned that generative AI tools would fundamentally alter search behavior and erode Google's advertising franchise. Since then, Alphabet has continued to demonstrate the strength of its ecosystem and the resilience of its core businesses. Google Search has remained strong, with AI-powered features increasing user engagement while supporting advertising growth, and Google Cloud has continued to benefit from robust enterprise demand for AI infrastructure and services. Importantly, Alphabet appears increasingly capable of monetizing these new experiences in a manner consistent with its historical strengths, through advertising, distribution, and integration across a broad user base rather than relying solely on paid subscriptions. YouTube also remains well positioned to benefit from continued growth in advertising and subscription revenues, including YouTube TV, as consume
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like Alphabet Inc. (NASDAQ:GOOGL). Alphabet Inc. (NASDAQ:GOOGL) operates Google Search, YouTube, Google Cloud, and a broad portfolio of digital products and technology businesses. The one-month return of Alphabet Inc. (NASDAQ:GOOGL) was -4.35% while its shares traded between $206.20 and $408.61 over the last 52 weeks. On August 27, 2026, Alphabet Inc. (NASDAQ:GOOGL) stock closed at approximately $342.00 per share, with a market capitalization of about $4.17 trillion.
Aristotle Value Equity Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOGL) in its Q2 2026 investor letter:
Alphabet Inc. (NASDAQ:GOOGL), the parent company of Google and YouTube, was a primary contributor during the period. We initiated our position in the first quarter of 2025, when investors were concerned that generative AI tools would fundamentally alter search behavior and erode Google's advertising franchise. Since then, Alphabet has continued to demonstrate the strength of its ecosystem and the resilience of its core businesses. Google Search has remained strong, with AI-powered features increasing user engagement while supporting advertising growth, and Google Cloud has continued to benefit from robust enterprise demand for AI infrastructure and services. Importantly, Alphabet appears increasingly capable of monetizing these new experiences in a manner consistent with its historical strengths, through advertising, distribution, and integration across a broad user base rather than relying solely on paid subscriptions. YouTube also remains well positioned to benefit from continued growth in advertising and subscription revenues, including YouTube TV, as consume

18 days ago
According to the Wall Street Journal, Google is relocating its AI responsibility unit from Google DeepMind to its global affairs division, the part of the company that handles lobbying and public policy.
The roughly 90-person team — whose work includes evaluating Google's AI models for chemical, biological, radiological, and nuclear hazards and examining user behavior and the psychological effects of chatbots — is set to complete the transition at the beginning of September, the Journal reported after reviewing an internal email about the shift. Some employees on the team have raised concerns that the reassignment will limit their independence and reduce their access to the researchers developing Google's Gemini models.
Helen King, a vice president at Google DeepMind who runs the responsibility team, sought to reassure staff in the email, writing that the team's focus on emerging and frontier topics in responsible AI would remain unchanged and that publishing research externally "continues to be supported and important." King added that the team's access to DeepMind would be preserved, along with its computing infrastructure and staffing levels.
"Many teams across Google work on AI safety and responsibility, and by bringing our AI responsibility teams closer together we're strengthening their ability to inform safety for our models and products," a Google spokesperson said in a statement.
The shift is part of broader organizational changes that are integrating DeepMind more tightly with the rest of Google. According to the Journal, functions such as HR and policy are similarly being transferred from DeepMind to Google's central organization. The reorganization follows a leadership change in which DeepMind co-founder Demis Hassabis stepped aside from his CEO role into a new chairman position focused on external engagements. Koray Kavukcuoglu has taken over as head of DeepMind with the **** le of senior vice president.
#Google #models #part
The roughly 90-person team — whose work includes evaluating Google's AI models for chemical, biological, radiological, and nuclear hazards and examining user behavior and the psychological effects of chatbots — is set to complete the transition at the beginning of September, the Journal reported after reviewing an internal email about the shift. Some employees on the team have raised concerns that the reassignment will limit their independence and reduce their access to the researchers developing Google's Gemini models.
Helen King, a vice president at Google DeepMind who runs the responsibility team, sought to reassure staff in the email, writing that the team's focus on emerging and frontier topics in responsible AI would remain unchanged and that publishing research externally "continues to be supported and important." King added that the team's access to DeepMind would be preserved, along with its computing infrastructure and staffing levels.
"Many teams across Google work on AI safety and responsibility, and by bringing our AI responsibility teams closer together we're strengthening their ability to inform safety for our models and products," a Google spokesperson said in a statement.
The shift is part of broader organizational changes that are integrating DeepMind more tightly with the rest of Google. According to the Journal, functions such as HR and policy are similarly being transferred from DeepMind to Google's central organization. The reorganization follows a leadership change in which DeepMind co-founder Demis Hassabis stepped aside from his CEO role into a new chairman position focused on external engagements. Koray Kavukcuoglu has taken over as head of DeepMind with the **** le of senior vice president.
#Google #models #part

19 days ago
TerraPower CEO Chris Levesque said that hyperscalers are driving demand for nuclear power companies, as his company is set to announce a deal with a data center customer for a new nuclear power plant this year. Levesque, who was joined by Bloomberg News energy reporter Will Wade, also said that TerraPower is aiming to get construction time and consumer costs lower so that nuclear can become a larger energy source for the US.
#nuclear #levesque #energy #wade
#nuclear #levesque #energy #wade


20 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Warren Buffett is best known as one of the greatest stock market investors of all time.
But some of the investments he has spoken most glowingly about aren't stocks at all.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#wealth #finance #buffett #bezos
Warren Buffett is best known as one of the greatest stock market investors of all time.
But some of the investments he has spoken most glowingly about aren't stocks at all.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
#wealth #finance #buffett #bezos

22 days ago
The dollar index (DXY00) fell by -0.02% on Friday, holding just above Thursday's 3.25-month low. Strength in stocks on Friday reduced demand for dollar liquidity. The dollar is still weighed down by negative carryover from Wednesday, when the US Treasury boosted liquidity and announced plans to increase buybacks of long-dated bonds. Friday's US economic news was mixed for the dollar, with the Aug S&P manufacturing PMI falling more than expected, but the Aug S&P services PMI rising more than expected.
The US Aug S&P manufacturing PMI fell -0.7 to 53.2, weaker than expectations of no change at 53.9, but the Aug S&P services PMI unexpectedly rose +2.8 to 56.8, stronger than expectations of a decline to 54.0 and the fastest pace of expansion in 4.5-years.
Dollar Little Changed as Stocks Climb and Crude Oil Stabilizes
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
The markets are discounting a 40% probability of a +25 bp rate hike at the next FOMC meeting on September 15-16.
#fell #expected
The US Aug S&P manufacturing PMI fell -0.7 to 53.2, weaker than expectations of no change at 53.9, but the Aug S&P services PMI unexpectedly rose +2.8 to 56.8, stronger than expectations of a decline to 54.0 and the fastest pace of expansion in 4.5-years.
Dollar Little Changed as Stocks Climb and Crude Oil Stabilizes
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
The markets are discounting a 40% probability of a +25 bp rate hike at the next FOMC meeting on September 15-16.
#fell #expected
24 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall,
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On August 18, 2026, NVIDIA Corporation (NASDAQ:NVDA) closed at $219.74 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 3.62% and its shares gained 25.28% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.32 trillion.
Eagle Capital Management stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"NVIDIA Corporation (NASDAQ:NVDA) has dominated the market for Al accelerator chips and has become the most profitable company in the U.S. However, its largest customers have internal silicon programs that are likely to reduce NVIDIA's share over time. Google TPUs and Amazon's Trainium chips are the most competitive, but Microsoft, Meta, OpenAl, and Anthropic all have programs in various stages. When the market was small, custom programs were uneconomic. At today's scale, R&D can be amortized across the larger base. Moreover, NVIDIA's 75-80% gross margin implies it is marking up Taiwan Semiconductor ("TSMC") wafers by 4-5x. Custom programs don't have to be as good as NVIDIA to offer better price/performance to the end customer.
NVIDIA is investing in the neocloud industry to support demand for its chips and weaken hyperscalers' position. Ironically, by selling its chips at high prices, it makes the neoclouds high-cost operators, and therefore less likely to succeed against vertically integrated hyperscalers over the long term. As NVIDIA's market share crests and begins to fall,

25 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
BHP just got a copper-colored glow-up.
The world's biggest miner still digs plenty of iron ore, but investors are now looking at a company increasingly powered by the metal behind AI, electrification and the grid buildout.
BHP reported a stronger full-year result for the year ended June 30 with copper overtaking iron ore as its biggest earnings driver for the first time.
Revenue rose 15% to $58.8 billion, while underlying EBITDA increased 27% to $32.9 billion. Net operating cash flow climbed 17% to $21.8 billion, and underlying profit jumped 30% to $13.2 billion, ahead of expectations.
#biggest #june
BHP just got a copper-colored glow-up.
The world's biggest miner still digs plenty of iron ore, but investors are now looking at a company increasingly powered by the metal behind AI, electrification and the grid buildout.
BHP reported a stronger full-year result for the year ended June 30 with copper overtaking iron ore as its biggest earnings driver for the first time.
Revenue rose 15% to $58.8 billion, while underlying EBITDA increased 27% to $32.9 billion. Net operating cash flow climbed 17% to $21.8 billion, and underlying profit jumped 30% to $13.2 billion, ahead of expectations.
#biggest #june

1 month ago
Updated Aug 07, 2026, 4:38 pm EDT / Original Aug 07, 2026, 8:07 am EDT
Tesla
TSLA
+2.83%
stock rose Friday, helping shares snap a three-week
losing streak
. Retail traders, as usual, are helping.
TSLA
+2.83%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#company
Tesla
TSLA
+2.83%
stock rose Friday, helping shares snap a three-week
losing streak
. Retail traders, as usual, are helping.
TSLA
+2.83%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#company
1 month ago
The air keeps escaping from Nike's (NKE) stock price.
According to Yahoo Finance AlphaSpace, Nike stock is now underperforming the S&P 500 (^GSPC) by the largest margin in 25 years (see the chart below). The stock is down 35% year to date compared to a 13% advance for the S&P 500.
Since Nike CEO Elliott Hill officially took over as CEO on Oct. 14, 2024, the stock has shed about 49%.
The only thing Nike is "just doing" is serving up stretches of weak quarters and outlooks.
In late June, Nike reported fiscal fourth quarter revenue of $11.0 billion, reflecting a 1% decline on a reported basis and a 4% drop on a currency-neutral basis.
#according #finance #alphaspace
According to Yahoo Finance AlphaSpace, Nike stock is now underperforming the S&P 500 (^GSPC) by the largest margin in 25 years (see the chart below). The stock is down 35% year to date compared to a 13% advance for the S&P 500.
Since Nike CEO Elliott Hill officially took over as CEO on Oct. 14, 2024, the stock has shed about 49%.
The only thing Nike is "just doing" is serving up stretches of weak quarters and outlooks.
In late June, Nike reported fiscal fourth quarter revenue of $11.0 billion, reflecting a 1% decline on a reported basis and a 4% drop on a currency-neutral basis.
#according #finance #alphaspace


1 month ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved first utility-scale power in-service for Socrates Phase 1 in under 18 months, validating the speed-to-market capability of the Power Innovation platform.
Acquired Momentum Midstream for $5.5 billion to solidify the company's position as the largest Haynesville gas gatherer connected to the Transco pipeline system.
Performance beat driven by strong results in the Gulf and Transmission and Gulf segment, which improved about 6%, led by the Gulf business which grew 23%. due to recent expansion projects.
Strategic financing JV with Blackstone provides $5.34 billion in committed capital at a capped 6.35% cost of equity, preserving balance sheet capacity for rapid power scaling.
#billion #socrates
Achieved first utility-scale power in-service for Socrates Phase 1 in under 18 months, validating the speed-to-market capability of the Power Innovation platform.
Acquired Momentum Midstream for $5.5 billion to solidify the company's position as the largest Haynesville gas gatherer connected to the Transco pipeline system.
Performance beat driven by strong results in the Gulf and Transmission and Gulf segment, which improved about 6%, led by the Gulf business which grew 23%. due to recent expansion projects.
Strategic financing JV with Blackstone provides $5.34 billion in committed capital at a capped 6.35% cost of equity, preserving balance sheet capacity for rapid power scaling.
#billion #socrates
1 month ago
Big Tech just closed out its second-quarter 2026 earnings season, and the results looked, on paper, like a triumph. Microsoft, Amazon, and Alphabet all posted numbers that blew past Wall Street's estimates, and headlines celebrated growth rates that haven't been seen in years.
Dig one layer deeper, and a strange pattern connects all three reports. A meaningful chunk of that growth has nothing to do with ads, cloud contracts, or software subscriptions. It comes from something these companies don't even sell.
S&P 500 earnings grew more than 48% year over year last quarter. Exclude the investment gains tied to private AI stakes, and that growth falls to roughly 29%, according to recent **** ysis, bringing underlying earnings growth much closer to expectations.
Gil Luria, managing director and head of technology research at D.A. Davidson, put it plainly. "The headline earnings numbers were very much inflated by equity gains in OpenAI, Anthropic and **** eX," he told CNBC, adding that these swings tend to even out over time, which is why most **** ysts strip them out of non-GAAP estimates.
Related: Jeff Bezos just named Amazon's next big pillar
#estimates #even
Dig one layer deeper, and a strange pattern connects all three reports. A meaningful chunk of that growth has nothing to do with ads, cloud contracts, or software subscriptions. It comes from something these companies don't even sell.
S&P 500 earnings grew more than 48% year over year last quarter. Exclude the investment gains tied to private AI stakes, and that growth falls to roughly 29%, according to recent **** ysis, bringing underlying earnings growth much closer to expectations.
Gil Luria, managing director and head of technology research at D.A. Davidson, put it plainly. "The headline earnings numbers were very much inflated by equity gains in OpenAI, Anthropic and **** eX," he told CNBC, adding that these swings tend to even out over time, which is why most **** ysts strip them out of non-GAAP estimates.
Related: Jeff Bezos just named Amazon's next big pillar
#estimates #even

1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record results driven by hyper-growth in data centers and broad-based strength across the diversified portfolio, with non-data center sales growing mid-single-digits.
Leveraged the 'OneWesco' cross-selling strategy to secure a record backlog, which increased 60% year-over-year across all three business units.
Transformed the CSS segment into a double-digit EBITDA margin business through improved project execution and increased pull-through of high-margin services.
Expanded the data center value proposition from 'grid to rack' by integrating power solutions and mission-critical cooling capabilities.
#data #record #center #Margin
Achieved record results driven by hyper-growth in data centers and broad-based strength across the diversified portfolio, with non-data center sales growing mid-single-digits.
Leveraged the 'OneWesco' cross-selling strategy to secure a record backlog, which increased 60% year-over-year across all three business units.
Transformed the CSS segment into a double-digit EBITDA margin business through improved project execution and increased pull-through of high-margin services.
Expanded the data center value proposition from 'grid to rack' by integrating power solutions and mission-critical cooling capabilities.
#data #record #center #Margin

1 month ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #683a6f6e -8d26-11f1-af82-1ccb12bb2c30
#reference #denied #automation
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #683a6f6e -8d26-11f1-af82-1ccb12bb2c30
#reference #denied #automation
2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the Q2 EBITDA tripling to the materialization of three strategic pillars: automotive volume recovery, footprint optimization, and the expiration of uneconomic legacy supply contracts.
Automotive shipments reached a two-year high, allowing finishing lines to return to healthy utilization levels and improving unit cost absorption.
The company credits Section 232 and recent trade enforcement for accelerating domestic manufacturing investment and eliminating 'escape valves' for transshipped steel from Mexico and Canada.
Management **** erts that Cleveland-Cliffs has become the 'supplier of choice' for the U.S. auto sector, claiming market share gains from both domestic integrated competitors and mini-mills.
#management #domestic #NVIDIA #Mexico
Management attributes the Q2 EBITDA tripling to the materialization of three strategic pillars: automotive volume recovery, footprint optimization, and the expiration of uneconomic legacy supply contracts.
Automotive shipments reached a two-year high, allowing finishing lines to return to healthy utilization levels and improving unit cost absorption.
The company credits Section 232 and recent trade enforcement for accelerating domestic manufacturing investment and eliminating 'escape valves' for transshipped steel from Mexico and Canada.
Management **** erts that Cleveland-Cliffs has become the 'supplier of choice' for the U.S. auto sector, claiming market share gains from both domestic integrated competitors and mini-mills.
#management #domestic #NVIDIA #Mexico

2 months ago
Custom Health Holdings Inc (TSX:CHLT) has signed a binding letter of intent to acquire Wisconsin-based Evergreen Pharmacy LLC in a deal expected to add more than US$78 million in annual revenue to the company.
Under the terms of the letter of intent, Custom Health will pay a total purchase price of US$3.5 million, including at least US$1 million of prescription drug inventory and US$450,000 of net working capital. The purchase price is payable in cash on closing, subject to a US$175,000 indemnity holdback for six months following closing.
The acquisition is expected to strengthen Custom Health's ability to support patients managing complex therapies and expand its operating footprint across the US Midwest.
Shares of Custom Health were up 8.3% in Canada.
Evergreen is licensed to provide pharmacy services in Wisconsin, Illinois and Michigan, with the ability to expand into Minnesota.
#letter
Under the terms of the letter of intent, Custom Health will pay a total purchase price of US$3.5 million, including at least US$1 million of prescription drug inventory and US$450,000 of net working capital. The purchase price is payable in cash on closing, subject to a US$175,000 indemnity holdback for six months following closing.
The acquisition is expected to strengthen Custom Health's ability to support patients managing complex therapies and expand its operating footprint across the US Midwest.
Shares of Custom Health were up 8.3% in Canada.
Evergreen is licensed to provide pharmacy services in Wisconsin, Illinois and Michigan, with the ability to expand into Minnesota.
#letter

2 months ago
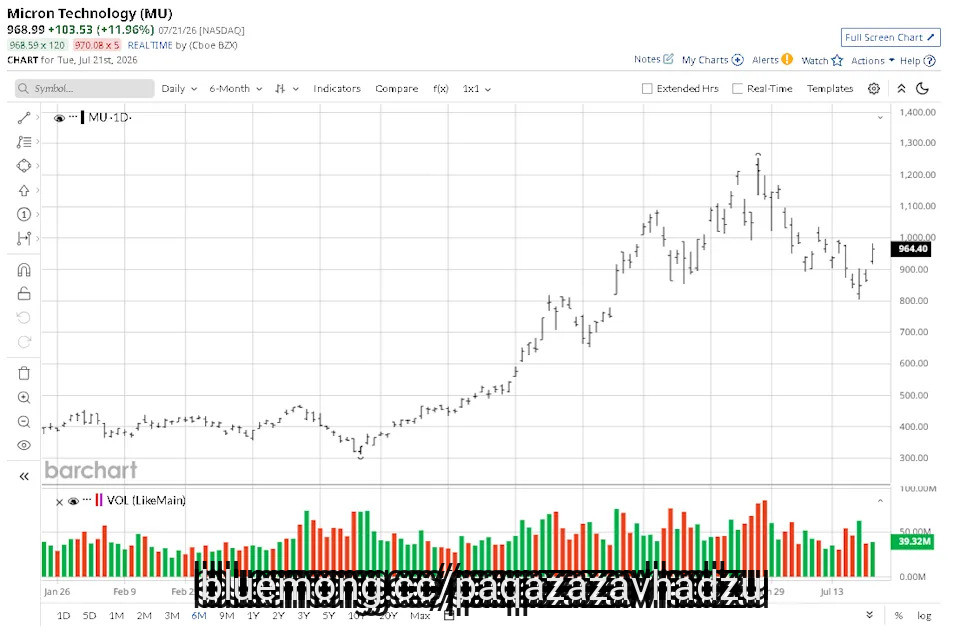
Micron Technology (MU) stock closed comfortably in the green on Tuesday after Bank of America Securities added the memory chips specialist to its "U.S. 1 List." The firm's senior ****** yst Vivek Arya maintains a "Buy" rating on MU, with a bullish $1,550 price target signaling potential upside of about 55% from current levels.
Micron stock's addition to BofA's highest conviction buy calls is significant given it is already up more than 200% year-to-date.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#micron #technology #vivek
Micron stock's addition to BofA's highest conviction buy calls is significant given it is already up more than 200% year-to-date.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#micron #technology #vivek