5 hours ago
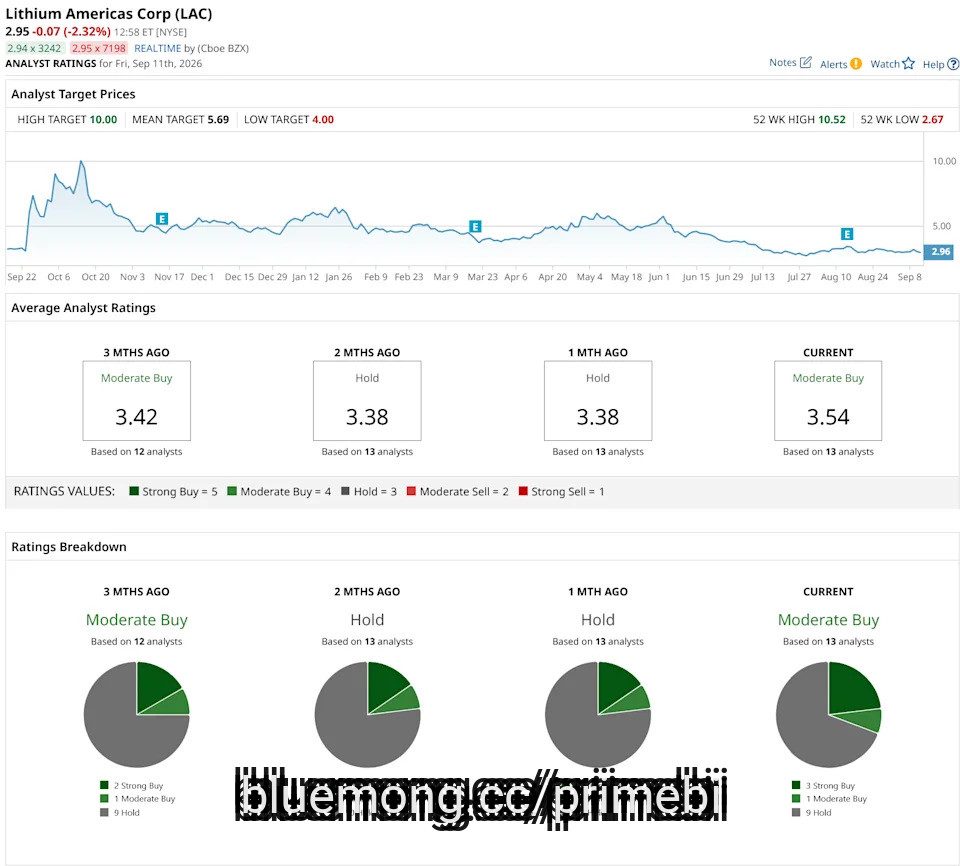
Lithium Americas Corp. (LAC) is back on Wall Street's radar after JPMorgan turned bullish on the lithium developer, upgrading the stock to an "Overweight" rating from "Neutral" and setting a $6 price target. The target implies close to 100% upside from the stock's previous close, giving investors a potentially significant re-rating opportunity if the bank's bullish **** umptions play out.
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play


5 hours ago
After spending years trading like a premium-priced AI leader, Nvidia may now be among the cheapest names in Piper Sandler's AI universe. NVIDIA Corporation (NASDAQ:NVDA) is trading at an attractive valuation according to Piper Sandler's forecast, with rapid AI growth backing its trajectory.
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company


11 hours ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda

12 hours ago
Oil futures have been rising, but recently hit a peak. ConocoPhillips (COP) reported strong Q2 earnings on Aug. 6, and COP stock may be fairly valued. However, shorting COP puts and vertical put credit spreads are attractive alternatives for value investors.
COP closed at $137.35 on Friday, Sept. 11, a recent three-, six-, and 12-month peak. That followed WTI Oct. futures contract (CLV26) spiking above $104 late Thursday, Sept. 10.
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The market clearly believes that Conoco's Q3 earnings and cash flow will be strong, given how high oil and gas prices have been this quarter. Barchart's CLV26 chart below shows the recent peak in oil futures.
Oil has been rising due to ongoing tensions and kinetic action between the U.S. and Iran, as well as in other areas in the Middle East where oil is transported.
#sept
COP closed at $137.35 on Friday, Sept. 11, a recent three-, six-, and 12-month peak. That followed WTI Oct. futures contract (CLV26) spiking above $104 late Thursday, Sept. 10.
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The market clearly believes that Conoco's Q3 earnings and cash flow will be strong, given how high oil and gas prices have been this quarter. Barchart's CLV26 chart below shows the recent peak in oil futures.
Oil has been rising due to ongoing tensions and kinetic action between the U.S. and Iran, as well as in other areas in the Middle East where oil is transported.
#sept



12 hours ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months

13 hours ago
On August 10, Red Violet Inc. (NASDAQ:RDVT) reported second-quarter 2026 results for the period ended June 30 that showed the company converting growth into profit at an accelerating clip. Revenue rose 23% to $26.7 million, and net income nearly doubled to $5 million. For a company built on selling identity intelligence to businesses, watching net margin move from 12% to 19% says that growth is not costing more to produce.
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million

13 hours ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations

13 hours ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance

13 hours ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


13 hours ago
On September 10, IBEX Limited (NASDAQ:IBEX) held its fourth-quarter and full fiscal year 2026 earnings call, and the numbers backed up a message management has been building toward for months. The company posted record full-year revenue, adjusted EBITDA, and free cash flow, all while pitching itself as a business that has flipped the AI narrative in its favor rather than becoming its next casualty. For a sector that has spent the last two years bracing for automation to gut it, that is a notable claim to back with actual client wins.
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth


13 hours ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


14 hours ago
On September 10, Tsakos Energy Navigation (NYSE:TEN) reported a first half of 2026 that reads like a fantasy year for a decades-old tanker operator. Net income hit $228 million, more than triple what the company earned over the same six months a year earlier, while diluted EPS climbed to $7.12 from $1.70. Behind those numbers sits a rare combination: a fleet locked into billions in forward earnings, war-driven cargo detours pushing rates higher, and a newbuilding bet that has already paid off before half the ships have even hit the water.
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion

17 hours ago
AVAV surged 6% on delayed earnings digestion after posting record Q1 revenue of $481M and a $1.5B funded backlog up 37% year over year.
ONDS gained just 2% and RCAT slipped 0.6% while the drone ETF DRNZ rose only 0.4%, confirming today's move belongs entirely to AeroVironment.
Despite the rally, AVAV remains 36% below its year-start price, and investors should watch for follow-through sessions before sizing up exposure.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
AeroVironment (NASDAQ:AVAV) stock is up 6% to $155.22 midday Monday, extending a post-earnings recovery the rest of the drone group hasn't joined. The move follows the defense contractor's fiscal first-quarter results reported earlier this month. The gain still leaves AeroVironment shares down 36% year to date.
#avav #move
ONDS gained just 2% and RCAT slipped 0.6% while the drone ETF DRNZ rose only 0.4%, confirming today's move belongs entirely to AeroVironment.
Despite the rally, AVAV remains 36% below its year-start price, and investors should watch for follow-through sessions before sizing up exposure.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
AeroVironment (NASDAQ:AVAV) stock is up 6% to $155.22 midday Monday, extending a post-earnings recovery the rest of the drone group hasn't joined. The move follows the defense contractor's fiscal first-quarter results reported earlier this month. The gain still leaves AeroVironment shares down 36% year to date.
#avav #move



18 hours ago
Broadcom's AI revenue surged 221% year over year with a forward P/E of 19, making it cheaper than Nvidia despite a similar growth trajectory.
TSMC revenue rose 53% year over year at a forward P/E of 20, and Dell booked a record $61B in AI orders last quarter.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom's custom accelerator business the centerpiece of the case. Bilal countered that "you have to go with the people who are on the leaderboard," naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
#NVIDIA #billion #enter
TSMC revenue rose 53% year over year at a forward P/E of 20, and Dell booked a record $61B in AI orders last quarter.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom's custom accelerator business the centerpiece of the case. Bilal countered that "you have to go with the people who are on the leaderboard," naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
#NVIDIA #billion #enter



19 hours ago
The Cooper Companies, Inc. (NASDAQ:COO) cut its fiscal 2026 profit and revenue forecasts after weaker-than-expected demand for contact lenses weighed on its CooperVision business. The company now expects adjusted earnings of $4.51–$4.55 per share, down from its previous forecast of $4.58–$4.66, while revenue guidance was reduced to $4.23–$4.25 billion from $4.29–$4.32 billion. Third-quarter revenue came in at $1.07 billion, below Wall Street's $1.10 billion estimate, although adjusted EPS of $1.15 beat expectations.
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision

21 hours ago
Apple trades at 37x earnings after a 45% one-year run; Microsoft sits at 27x and is up just 3% year to date, offering a cheaper AI entry point.
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks


2 days ago
Arrow Electronics (ARW) stock has gained about 50% over the past six months and then stopped. It has slipped 1.0% over the past three months and trades roughly 9% below its 52-week high. Underneath the run is a machine that pays owners whether or not the price moves: a shrinking share count. It is shrinking more slowly now, and that changes what you are buying.
How Did Arrow Pay You While Its Profit Went Nowhere?
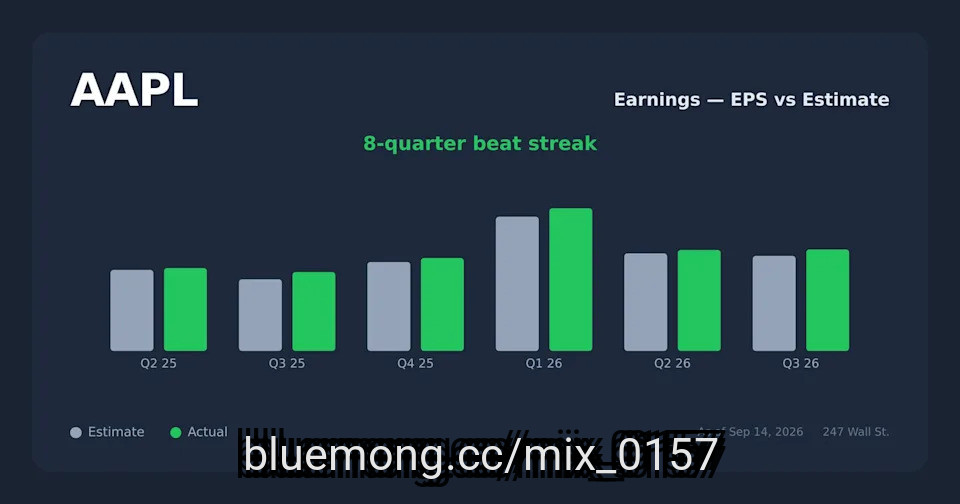
Over the past three years, Arrow's net income grew 0.7% a year on average while earnings per share grew 4.7% a year on average. Most of that gap is arithmetic: it retired about 3.3% of its shares a year on average, so each surviving share held a bigger claim on the same profit. Owners got a bigger slice for doing nothing.
Arrow returned 69% over those three years, about 19.0% a year, and still trailed the 76% the S&P 500 returned over the same span. The stock was up 85% at its three-year peak before giving some back. Retiring shares was one driver of that, alongside earnings growth and a changing multiple.
Can Arrow Afford A Bigger Buyback?
#Share #owners
How Did Arrow Pay You While Its Profit Went Nowhere?
Over the past three years, Arrow's net income grew 0.7% a year on average while earnings per share grew 4.7% a year on average. Most of that gap is arithmetic: it retired about 3.3% of its shares a year on average, so each surviving share held a bigger claim on the same profit. Owners got a bigger slice for doing nothing.
Arrow returned 69% over those three years, about 19.0% a year, and still trailed the 76% the S&P 500 returned over the same span. The stock was up 85% at its three-year peak before giving some back. Retiring shares was one driver of that, alongside earnings growth and a changing multiple.
Can Arrow Afford A Bigger Buyback?
#Share #owners

2 days ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management

2 days ago
AbbVie (ABBV) grew revenue 10.4% over the past twelve months and turned 33.9% of it into operating profit, second only to Eli Lilly among its peers on both counts. Its stock returned 24.9% over the same twelve months, fifth of the six. What the business delivered and what the market paid for it have come apart.
Johnson & Johnson makes the contrast sharpest. JNJ grew revenue 8.1% over the same twelve months on an operating margin of 26.8%—edging out Pfizer's 26.7%—while its stock returned 53.9%. It also trades at 30.5 times earnings, where AbbVie trades at 71.5.
ABBV
JNJ
PFE
#abbvie #grew #operating
Johnson & Johnson makes the contrast sharpest. JNJ grew revenue 8.1% over the same twelve months on an operating margin of 26.8%—edging out Pfizer's 26.7%—while its stock returned 53.9%. It also trades at 30.5 times earnings, where AbbVie trades at 71.5.
ABBV
JNJ
PFE
#abbvie #grew #operating
2 days ago
Salesforce (CRM) trades at 20.6 times earnings, below the S&P 500 median of 22.6, after losing 2.8% over the past twelve months while the index gained 17.9%. A profitable software company priced under the market is the setup value buyers wait for. The question is whether that is a good business on sale or a fair price for a legacy platform facing disintermediation from next-generation AI architectures.
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion

2 days ago
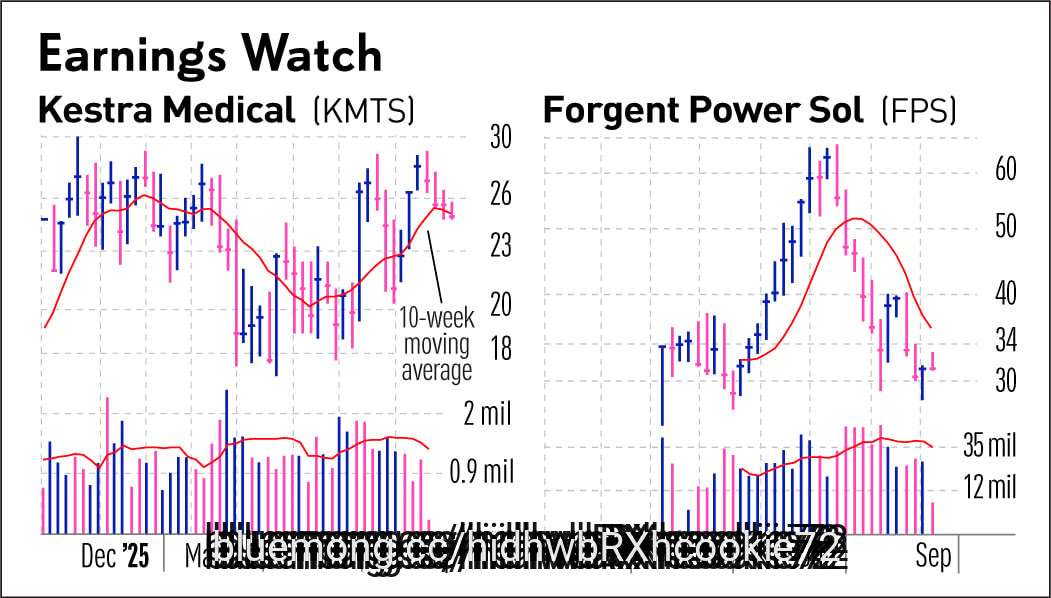
Restaurant stock Dave & Buster's Entertainment (PLAY) and healthcare name Kestra Medical Technologies (KMTS) will kick off earnings reports during a week when investors will be squarely focused on the Federal Reserve and a possible interest-rate hike Wednesday. Forgent Power Solutions (FPS) is also on the docket, with its stock trying to recover after a lengthy sell-off.
Friday's stock market rally notwithstanding, the Dow Jones Industrial Average and the Russell 2000 small-cap index have come under the most pressure amid surging oil prices and spiking bond yields, as investors worry about pesky inflation and escalating tension between the U.S. and Iran.
While the Dow is testing major support near 52,000, the Russell fell below its 50-day moving average in late August and has been below the support level ever since. The Nasdaq composite, meanwhile, bounced off its 50-day line with conviction Friday, helped by a tame report on consumer prices. The S&P 500 also moved off its 50-day line Friday.
Results from Lennar (LEN) are due Wednesday after the close. Lennar stock tried to break out in late June, but was turned away at its 200-day line and went into a downtrend. It tried to clear the 200-day line several times again in August but to no avail. With interest rates on the rise, heavy-volume selling has picked up the pace in recent weeks.
Forgent, which sells electrical distribution equipment to data centers, reports early Tuesday. The company priced its IPO at 27 on Feb. 4, at the midpoint of a proposed range of 25-29.
#line #forgent #august #lennar
Friday's stock market rally notwithstanding, the Dow Jones Industrial Average and the Russell 2000 small-cap index have come under the most pressure amid surging oil prices and spiking bond yields, as investors worry about pesky inflation and escalating tension between the U.S. and Iran.
While the Dow is testing major support near 52,000, the Russell fell below its 50-day moving average in late August and has been below the support level ever since. The Nasdaq composite, meanwhile, bounced off its 50-day line with conviction Friday, helped by a tame report on consumer prices. The S&P 500 also moved off its 50-day line Friday.
Results from Lennar (LEN) are due Wednesday after the close. Lennar stock tried to break out in late June, but was turned away at its 200-day line and went into a downtrend. It tried to clear the 200-day line several times again in August but to no avail. With interest rates on the rise, heavy-volume selling has picked up the pace in recent weeks.
Forgent, which sells electrical distribution equipment to data centers, reports early Tuesday. The company priced its IPO at 27 on Feb. 4, at the midpoint of a proposed range of 25-29.
#line #forgent #august #lennar

2 days ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
2 days ago
The Cooper Companies Inc. (NASDAQ:COO), a leading medical device company, announced its third quarter fiscal 2026 results on September 9. Topline went up 1% to $1.066 billion in comparison with the same quarter last year, which also included 1% organic growth. The company posted quarterly adjusted diluted EPS of $1.15, which represented a 4% jump from Q3 FY25. During the quarter, $339.1 million was spent on repurchasing around 4.9 million of the company's common shares. This leaves management with $1.5 billion of repurchase capacity, which remains available after the Board had raised its buyback authorization from $2 billion to $3 billion.
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash
2 days ago
Apple (AAPL) is selling iPhones and Macs faster than it can build them, but the number a holder should fear most is the gross margin underneath those sales. Leaving out tariff refunds, that margin fell in the June quarter and is guided lower again for the September quarter. Management puts both steps down to rising memory prices, while the stock's price-to-earnings multiple sits near the top of its 10-year range.
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year


2 days ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare

2 days ago
Ciena surged 5% Friday to erase its post-earnings selloff, with Arista Networks also gaining 5% as money rotated into networking equipment as a group.
IYW gained just 2% and SPY 1% while networking stocks surged 4-5%, confirming the move as a targeted sector rotation, not a broad tech rally.
Ciena's 10.7% weekly gain makes it the group's swing name, where the post-earnings gap is nearly filled and further upside requires fresh buyers or a new catalyst.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Cisco Systems didn't make the cut. Enter your email to see the names that beat CSCO. The report is free. Enter your email and see if any of your stocks made the cut.
Ciena (NYSE:CIEN) stock is up 5% to $351.38 in early Friday afternoon trading, extending a rebound that's now stretched across the full week. The move reverses the post-earnings selloff that followed Ciena's September 3 fiscal third quarter release. Today's advance has effectively closed the door on the initial negative reaction to the report and pushed the stock back through the level it held before the release.
#Stock #Friday
IYW gained just 2% and SPY 1% while networking stocks surged 4-5%, confirming the move as a targeted sector rotation, not a broad tech rally.
Ciena's 10.7% weekly gain makes it the group's swing name, where the post-earnings gap is nearly filled and further upside requires fresh buyers or a new catalyst.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Cisco Systems didn't make the cut. Enter your email to see the names that beat CSCO. The report is free. Enter your email and see if any of your stocks made the cut.
Ciena (NYSE:CIEN) stock is up 5% to $351.38 in early Friday afternoon trading, extending a rebound that's now stretched across the full week. The move reverses the post-earnings selloff that followed Ciena's September 3 fiscal third quarter release. Today's advance has effectively closed the door on the initial negative reaction to the report and pushed the stock back through the level it held before the release.
#Stock #Friday



2 days ago
On September 9, AeroVironment Inc. (NASDAQ:AVAV) revealed its Q1 FY27 results, posting its highest ever first quarter revenue. Topline figure of $480.5 million marked a 6% year-over-year growth, fueled by a $15.5 million jump in product sales and a $10.3 million expansion of service revenue. The company reported a book-to-bill ratio of 1.4, after total bookings for the quarter came in at $0.7 billion. Let's explore the underlying drivers of AeroVironment's impressive first quarter print.
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first
2 days ago
U.S. Bancorp (NYSE:USB) has raised its quarterly dividend by 3.8% to $0.54 per share. That brings the annualized payout at $2.16 and the yield at 3.5%.
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth

3 days ago
It should surprise exactly no one that players, who were out of eligibility under NCAA rules, going through NFL training camp and filing lawsuits to play college football for another year was the last straw.
A week later, the Protect College Sports Act, dead in the water a month ago, is close to passing the Senate because the chaos finally got to be too much. It is, according to Team Chaos, bad for athletes.
It appears Sen. Thune has enough votes to pass the Protect College Sports Act.
Last night, I contacted many U.S. Senators’ offices to tell them the truth about the bill.
The PCSA is bad for athletes. A lot of money is being spent in an effort to convince people otherwise. pic.twitter.com/tShgI0sp9T
This is what happens when you make everybody despise you.
When your position is that you have to have megaconferences, more ******* ding of revenue by the conferences at the top, a stupid college basketball Thanksgiving week event in Las Vegas backed by all the worst people in existence (the Emiratis and David Ellison chief among them), more private equity backing, more helmet games, unlimited transfers, unlimited tampering with mid-major rosters, unlimited college eligibility and freedom to go back and forth between college and the pros as you please, all so that athletes can maximize their earnings…
#college #protect #sports #people
A week later, the Protect College Sports Act, dead in the water a month ago, is close to passing the Senate because the chaos finally got to be too much. It is, according to Team Chaos, bad for athletes.
It appears Sen. Thune has enough votes to pass the Protect College Sports Act.
Last night, I contacted many U.S. Senators’ offices to tell them the truth about the bill.
The PCSA is bad for athletes. A lot of money is being spent in an effort to convince people otherwise. pic.twitter.com/tShgI0sp9T
This is what happens when you make everybody despise you.
When your position is that you have to have megaconferences, more ******* ding of revenue by the conferences at the top, a stupid college basketball Thanksgiving week event in Las Vegas backed by all the worst people in existence (the Emiratis and David Ellison chief among them), more private equity backing, more helmet games, unlimited transfers, unlimited tampering with mid-major rosters, unlimited college eligibility and freedom to go back and forth between college and the pros as you please, all so that athletes can maximize their earnings…
#college #protect #sports #people


3 days ago
NBA rookies can sign contracts worth millions before they receive their first regular paycheck. The number on a rookie deal may grab attention, but the timing of those payments works very differently from what many fans **** ume.
Draymond Green recently explained how NBA players receive their salaries and why rookies can face a long wait before their first check. The system also allows players to negotiate how some of that money reaches them.
Green said NBA players are normally paid twice each month, but rookies enter the league under a different timeline. Their contracts can include an advance before the regular salary schedule begins, which gives new players some access to their earnings during that gap.
Apr 10, 2026; Sacramento, California, USA; Golden State Warriors forward Draymond Green (23) gestures toward the Sacramento Kings bench during the third quarter at Golden 1 Center. Mandatory Credit: Robert Edwards-Imagn Images
"Most people are paid every 1st and the 15th all year, an NBA rookie can take an advance up to 15% of their salary once they're signed," Green said. "What you should understand about rookies is the rookies don't get their 1st paycheck till November 15th, a month and a half into the season."
#rookies #draymond #sacramento #first
Draymond Green recently explained how NBA players receive their salaries and why rookies can face a long wait before their first check. The system also allows players to negotiate how some of that money reaches them.
Green said NBA players are normally paid twice each month, but rookies enter the league under a different timeline. Their contracts can include an advance before the regular salary schedule begins, which gives new players some access to their earnings during that gap.
Apr 10, 2026; Sacramento, California, USA; Golden State Warriors forward Draymond Green (23) gestures toward the Sacramento Kings bench during the third quarter at Golden 1 Center. Mandatory Credit: Robert Edwards-Imagn Images
"Most people are paid every 1st and the 15th all year, an NBA rookie can take an advance up to 15% of their salary once they're signed," Green said. "What you should understand about rookies is the rookies don't get their 1st paycheck till November 15th, a month and a half into the season."
#rookies #draymond #sacramento #first