1 month ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda

1 month ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock

1 month ago
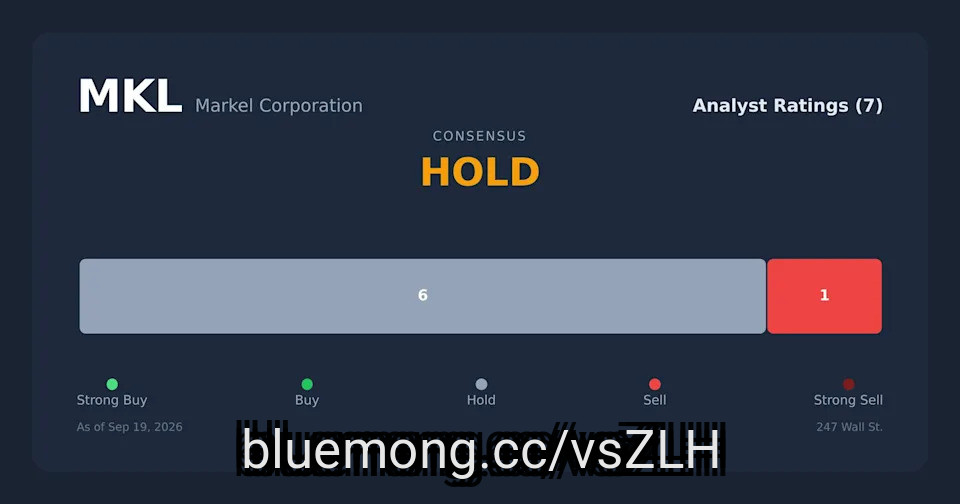
Markel mirrors Berkshire's three-engine model of insurance, equities, and operating businesses, with $18.84 billion in float and $429.5 million in 2025 buybacks, but its $22 billion market cap makes it a fundamentally different species.
Markel's combined ratio improved to 94.6% in 2025, yet shares are down 17% year to date while trailing Berkshire's 10-year return by 155 percentage points.
Three signals determine the Markel thesis: whether the combined ratio holds in the low 90s, buybacks sustain pace, and Markel Ventures remains inside the group.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Berkshire Hathaway didn't make the cut. Enter your email to see the names that beat BRK-B. The report is free. Enter your email and see if any of your stocks made the cut.
Warren Buffett has stepped down as board chair of Berkshire Hathaway, with Greg Abel now running the company. The handoff has revived a question value investors have batted around for a decade: with the Oracle off the field, is Markel Group (NYSE:MKL) the closest thing left to early Berkshire Hathaway (NYSE:BRK-B)?
#hathaway #group #market


1 month ago
On September 14, L3Harris Technologies, Inc. (NYSE:LHX) said it had secured a $60 million contract from the U.S. Air Force to continue producing sensors that let aircrews choose the precise detonation altitude.
SpaceKris/Shutterstock.com
The DSU-43/B ******* pit Selectable Height of Burst Sensors (C-HOBS) allow crews to adjust the munition's effect to different targets and mission environments. The system will provide enhanced radar-guided performance, advanced sensing features, and manual and ******* pit-selectable burst heights, the company said in a press release.
The production will take place at L3Harris' Cincinnati facility. The order comes at a time when the defense contractor is expanding the output capacity of proximity fuzes and sensors for the U.S. military to support a wartime footing.
Investors should view the C-HOBS contract as evidence of the company's recurring business with the Air Force on precision-guidance electronics. Despite being small in magnitude, such low-risk and steady order flow underpins the bull thesis for the stock.
#cockpit


1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Elon Musk doubled down on his solar thesis on Tuesday, predicting the technology will eventually dominate energy production, with Texas offering a real-world example of rapid adoption.
"The solar power exponential will continue until all other energy sources are
Elon Musk doubled down on his solar thesis on Tuesday, predicting the technology will eventually dominate energy production, with Texas offering a real-world example of rapid adoption.
"The solar power exponential will continue until all other energy sources are
1 month ago
On September 9, 2026, Academy Sports and Outdoors, Inc. (NASDAQ:ASO) posted second-quarter results for the period ended August 1, 2026. Net sales rose 3.0% to $1.65 billion, adjusted earnings per share climbed 19.1% to $2.31 from $1.94, and gross margin widened 440 basis points to 40.4%. Management lifted full-year adjusted EPS guidance to $6.50 to $6.90 and gross margin guidance to 35.5% to 36.0%. What the quarter did not deliver was a positive comp, which fell 0.4%.
Telsey Advisory came away seeing nothing that changes the thesis, calling the risk-reward attractive and pushing its target on Academy Sports and Outdoors, Inc. (NASDAQ:ASO) to $63 from $60 while staying at Outperform.
Wells Fargo's Ike Boruchow described himself as cautiously optimistic at current levels, arguing that both the quarter itself and management's forward commentary delivered upside surprise; his target moved to $55 from $50, though the rating stayed Equal Weight.
Barclays **** yst Adrienne Yih focused on the fact that Academy Sports and Outdoors, Inc. (NASDAQ:ASO) held its fiscal 2026 sales and comp guidance despite a tougher consumer backdrop and sequential demand deceleration, lifting her target to $53 from $50 at Equal Weight.
Supporting the case: e-commerce sales grew 12.8%, Sports and Recreation rose 6%, myAcademy loyalty membership passed 15 million, and the company raised adjusted free cash flow guidance to $300 million to $350 million after repurchasing $182.1 million of stock in the first half.
#sports #guidance #sales #target


1 month ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects


1 month ago
In this episode of Motley Fool Hidden Gems Investing, Motley Fool contributors Jon Quast, Matt Frankel, and Rachel Warren discuss:
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt


1 month ago
Investors continue to ask for more timely information, even as the volume available to them expands. A 2026 CFA Institute survey of 2,500 **** ysts and portfolio managers found that 62% opposed replacing quarterly reporting with semiannual reporting. Nearly 85% expressed concern about comparability if companies and investment managers could determine their own reporting frequency and format. Access remains important, while interpretation requires a separate discipline.
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute

1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus

1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands


1 month ago
Wolfe Research upgraded two prominent pharmaceutical companies to Outperform on August 13. The firm upgraded both Biogen Inc. (NASDAQ:BIIB) and AbbVie Inc. (NYSE:ABBV)'s ratings from Peer Perform, with Wolfe ***** igning them similar $300 price targets. The firm's logic in each case was based on a comparable set of factors: pipelines that the market appears to undervalue, and valuations that Wolfe believes are too low given each company's growth track.
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical

1 month ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


1 month ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival


1 month ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter #investor


1 month ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) provides strategy and consulting, industry X, song, and technology and operation services. On September 14, 2026, Accenture plc (NYSE:ACN) closed at $195.00 per share. Over the past month, Accenture plc (NYSE:ACN) was up 12.35%, and its shares lost 17.96% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $119.33 billion.
Broyhill ******* et Management stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"Accenture plc (NYSE:ACN) fell 38%, and we exited in June. Our case rested on unpriced optionality appearing as revenue per employee, and that measure grew only marginally while bookings declined 3% and the managed services book to-bill fell below one. Management's response was to raise the acquisition guide to $9 billion. An inflection in bookings was a key point in the thesis, and the fact that management fell back on acquisitions when it came in weak does not inspire confidence in the core business. We sold the position following these results."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#management #investor

1 month ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter

1 month ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ***** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#biontech #survival


1 month ago
Piper Sandler believes Broadcom Inc. (NASDAQ:AVGO) is the leader in ASIC chips, holding 75% share of the ASIC market for AI inference. On September 9, firm ******* yst David O'Connor initiated coverage on the stock with an Overweight rating and a $460 price target.
O'Connor estimates demand running twice the available supply for Broadcom, which makes the ability to deliver chips central to his thesis. Even though the chipmaker boasts demand, component availability and deployment timing will determine its conversion into earnings.
The biggest advantage that Broadcom holds is that it doesn't need to win new customers, but to keep expanding what it ships to the ones it already has. The company is already ramping Meta's MTIA program and OpenAI's Jalapeno chips, along with two other customers.
Google's TPU program remains Broadcom's major volume ASIC program, while Anthropic is also scaling deployments using AVGO-enabled TPU compute. Broadcom also boasts a rising networking attach rate, which is currently around 30%. This would likely generate an estimated $20-30 billion of total content per gigawatt of deployed capacity.
The firm has a line of sight to 12 gigawatts of demand in fiscal 2027, rising toward an estimated 38 gigawatts by fiscal 2030. This underpins a roughly 51% EPS compound growth rate through the decade.
#asic


1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth

1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

1 month ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen
2 months ago
Lili Reinhart kept things effortlessly cool during a recent outing in London, pairing a delicate slip dress with a rugged leather jacket for a look that balanced soft and edgy in equal measure. The actress stepped out for a visit to Capital Buzz on September 8, drawing attention for her laid-back take on off-duty style.
Lili Reinhart pairs delicate slip dress with Saint Laurent leather jacket in London. Reinhart wore the Theory Velima Slip Dress, a cream-toned piece held up by nothing more than two thin straps. The dress featured a loose, tiered silhouette that fell just above the knee, with soft, flowing fabric that gave the look an airy, undone quality despite its minimal strap construction.
Over the dress, Reinhart layered a black leather biker jacket from Saint Laurent, noted as a secondhand find rather than a new purchase. The structured, moto-inspired jacket added a sharp contrast to the softness of the slip dress underneath, giving the overall look a lived-in, rock-and-roll edge.
She finished the outfit with Golden Goose's Kurt Boots, a slouchy black leather style priced at $1,130, along with Elisa Johnson's Dakota Sunglasses, retailing at $135. Photos from the outing show Reinhart walking confidently along a London street, her blonde hair loose and tousled as the jacket slipped slightly off one shoulder.
The London stop comes in the middle of a packed press run for Reinhart's new film, "The Love Hypothesis." Just a day after this street style moment, she stunned at the film's London premiere in an archival plunging Emanuel Ungaro dress, and she recently wore a custom Rodarte beaded tulle gown for the film's German premiere.
#dress #leather #lili


2 months ago
Digital Realty Trust, Inc. (NYSE:DLR) announced the opening of its 6.4-megawatt NBO2 data center in Nairobi on September 7, expanding the campus alongside NBO1. The opening coincides with subsidiary iColo's transition to the parent's brand in Kenya and Mozambique.
The attraction extends beyond additional server ****** e. Customers can access the campus's community of more than 100 networks, two internet exchanges and a satellite teleport, which connects terrestrial networks with satellite services. These are connectivity options, not a disclosure of NBO2's leased capacity or customer count.
For Digital Realty Trust, Inc. (NYSE:DLR), the opportunity is to turn that concentration of networks into recurring customer relationships. The opening announcement did not disclose development cost, pre-leasing, occupancy, or expected revenue, leaving the financial payoff unresolved.
Interconnection can give customers a reason to choose a facility beyond price. Physical connections between customers and network providers can reduce latency and support more reliable data exchange. For businesses serving several markets, having carriers and partners close together can simplify how traffic moves between them.
That creates a potential network effect for Digital Realty Trust, Inc. (NYSE:DLR). More useful connections can attract additional customers, making the location more valuable to others. Once customers build several connections into their operations, relocating can become more disruptive. The resulting retention advantage could support recurring revenue, although it remains an investment thesis rather than a demonstrated NBO2 result.
#digital #connections
2 months ago
A cryptocurrency ETF is an exchange-traded fund that gives investors exposure to cryptocurrency through a regular brokerage account with no crypto wallet, exchange, or private keys required. The most important type is the spot ETF, which holds the actual cryptocurrency (Bitcoin, Ether, etc.) in secure custody, so the fund's price tracks the real-time price of the coin. When you buy a share, you're getting direct exposure to the underlying **** et, wrapped in the familiar, regulated ETF structure. One technical note: U.S. spot crypto funds are structured as exchange-traded products — grantor trusts registered under the Securities Act of 1933 — rather than as 1940 Act ETFs, so they trade just like ETFs but do not carry all of the same investor protections.
This is a big deal because it removes the biggest barriers to crypto investing: custody risk, exchange hacks, and technical complexity. It also brings crypto into tax-advantaged accounts and lets investors hold it alongside their stocks and bonds in one place.
Spot Bitcoin ETFs launched in the U.S. in January 2024 and have become the fastest-growing ETF category ever. In 2026 they dominate the crypto ETF landscape.
IBIT (iShares Bitcoin Trust) was one of the first to market and is the runaway leader, with roughly $71 billion in **** ets — well over half of the entire spot Bitcoin ETF market. BlackRock's fund has become the default vehicle for institutional and retail Bitcoin exposure alike, prized for its deep liquidity and low cost. FBTC (Fidelity Wise Origin Bitcoin Fund) is second with about $18 billion, and GBTC (Grayscale Bitcoin Trust), the converted legacy fund, holds around $15 billion despite its higher fee. For most investors seeking Bitcoin exposure, IBIT and FBTC are the go-to, low-cost choices.
Spot Ethereum ETFs followed in July 2024 and form the second pillar of the crypto ETF world. ETHA (iShares Ethereum Trust) leads with roughly $11 billion in **** ets, followed by FETH (Fidelity Ethereum Fund) at about $2.3 billion. Ethereum offers a different investment thesis than Bitcoin as it's the backbone of decentralized applications, smart contracts, and much of the tokenization trend. This means ether ETFs give investors exposure to a distinct part of the digital-asset ecosystem.
#Bitcoin


2 months ago
Wall Street has bid up defense contractors on geopolitical tensions alongside expanded missile-defense funding, but Northrop Grumman Corporation (NYSE:NOC) remains an outlier. On September 4, 2026, the company secured a $508.5 million Missile Defense Agency contract for ICBM and IRBM target flight-test support running through 2035. The non-competitive contract follows the $3 billion (approx.) in framework agreements to expand solid-rocket-motor production for PAC-3 and THAAD interceptors. Despite these bookings, stock slipped 2.5% to $515. The stock is trading near 16 times earnings and 33% below its peak, making Northrop one of the lowest-multiple prime defense contractors.
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop

2 months ago
During a segment on the September 3 episode, Mad Money host Jim Cramer shared a detailed bullish thesis on Amazon.com, Inc. (NASDAQ:AMZN). He stated:
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi

2 months ago
Jeff Klingelhofer, CFA, Managing Director, Portfolio Manager & Senior Research **** yst, Securitized **** ets at Aristotle Pacific didn't set out to be a bond guy but a launchpad at PIMCO, stops in Tokyo and London, and a Chicago MBA detour into a scrappy five-person hedge fund rewired how he thinks about fixed income. The internship stuck, with Klingelhofer building out Thornburg's taxable fixed income desk from employee #3 to Head of Investments, before joining Aristotle Pacific in 2024. The firm is a 15-year-old franchise (formerly Pacific **** et Management) now running roughly $16 billion and, as of July 30, three brand-new ETFs: the Aristotle Core Plus Income ETF (ARCP), the Aristotle Multi-Sector Income ETF (ARMS), and the Aristotle Short Term Income ETF (SDUR).
The pitch isn't about taking on more risk to boost returns but about capturing returns with minimal risk, and that means shopping across every fixed income silo instead of hunting inside one. Klingelhofer gives the example of February 2020, when American Airlines' corporate bond and its aircraft-backed EETC both priced at 3.75% with the same issuer, same tenor, same yield. A month later, COVID hit and the corporate bond cratered to 27 cents on the dollar while the EETC held at 65 cents. Same company, wildly different outcomes because Wall Street desks looked at each instrument in isolation instead of comparing across the capital stack. That's the whole Aristotle Pacific thesis, and it's why he sees the same mispricing setting up today in data center financing.
The three funds slot into that framework by risk level, with SDUR as a low-duration, active-credit alternative to cash, ARCP as a core-bond upgrade aiming to beat the Agg by 100-150bps, and ARMS as the full relative-value expression targeting 250bps over a cycle with real flexibility to shift credit quality. Macro-wise, Klingelhofer thinks the market is underestimating new Fed Chair Warsh, who, unlike his predecessor, inherits a purely high-inflation world with no disinflationary tailwind. It means the firm is positioning the funds slightly long duration as a hedge against credit risk elsewhere in the book. His closing advice to advisors was a cautionary and practical one, that they shouldn't expect Aristotle to work in every environment (no fund does), and to pair its bottom-up process with top-down managers like PIMCO so the two zig and zag differently throughout market cycles.
To learn more about Aristotle Pacific, go here, or you can learn more about their new ETFs here.
#pacific #same #fixed


2 months ago
Earnings season refuses to end. While others may have had enough, earnings reports are my lifeblood! Well, that and 1,500 milligrams of caffeine a day.
I'm glad earnings season rages on because it gives us the very latest insights on all things AI. This is super helpful information as I embark for the Super Bowl of tech conferences: the Goldman Sachs Communacopia tech gathering. More on that in a moment.
The past two weeks have been bonkers for the AI investment thesis. Any talk about peak AI needs to be tossed aside.
Broadcom's (AVGO) revenue surged 86% year over year in its most recent quarter. Adjusted earnings per share exploded 96%. Both metrics easily thumped ***** yst estimates.
The massive outperformance was fueled by relentless hyperscaler demand for custom AI chips and networking gear, with quarterly AI semiconductor revenue alone tripling to $16.7 billion.
#super #season #revenue #sachs

2 months ago
"Hearst Magazines and Yahoo may earn commission or revenue on some items through these links."
THE RUNDOWN
Lili Reinhart channeled Kate Hudson's iconic How to Lose a Guy in 10 Days look for her latest The Love Hypothesis press appearance.
The actress wore a 2000s Caché dupe of the Carolina Herrera dress Hudson wore in the film.
Reinhart's stylist tells ELLE that the star will be paying homage to several famous rom-com leads during her press tour.
#rundown #kate