4 hours ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda

6 hours ago
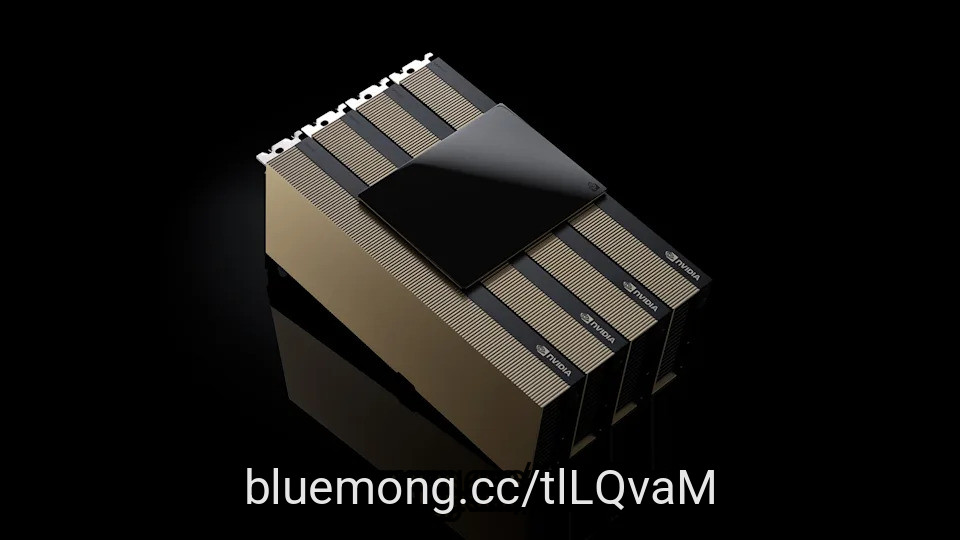
NVIDIA Corporation (NASDAQ:NVDA) has an argument against rapid hardware obsolescence: older accelerators still command rental prices. For CoreWeave, Inc. (NASDAQ:CRWV), which sells access to computing infrastructure, the harder question is how much of that rent becomes a return.
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return

6 hours ago
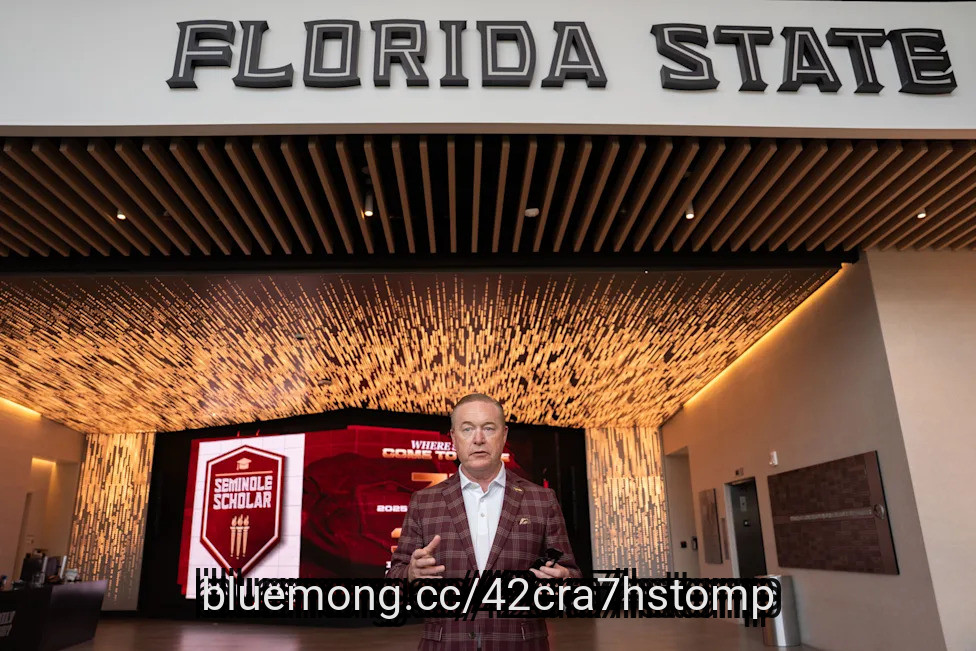
Florida State is in search of a new athletic director after the university fired Michael Alford on Monday, Sep. 14, four years after he was hired.
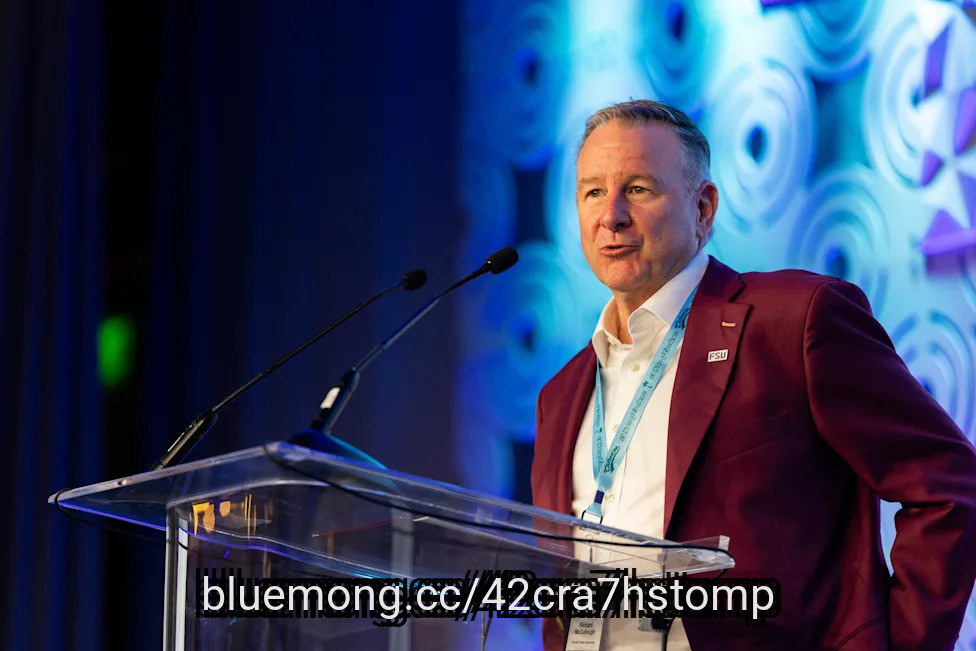
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate


6 hours ago
On August 10, Red Violet Inc. (NASDAQ:RDVT) reported second-quarter 2026 results for the period ended June 30 that showed the company converting growth into profit at an accelerating clip. Revenue rose 23% to $26.7 million, and net income nearly doubled to $5 million. For a company built on selling identity intelligence to businesses, watching net margin move from 12% to 19% says that growth is not costing more to produce.
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million

7 hours ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy

10 hours ago
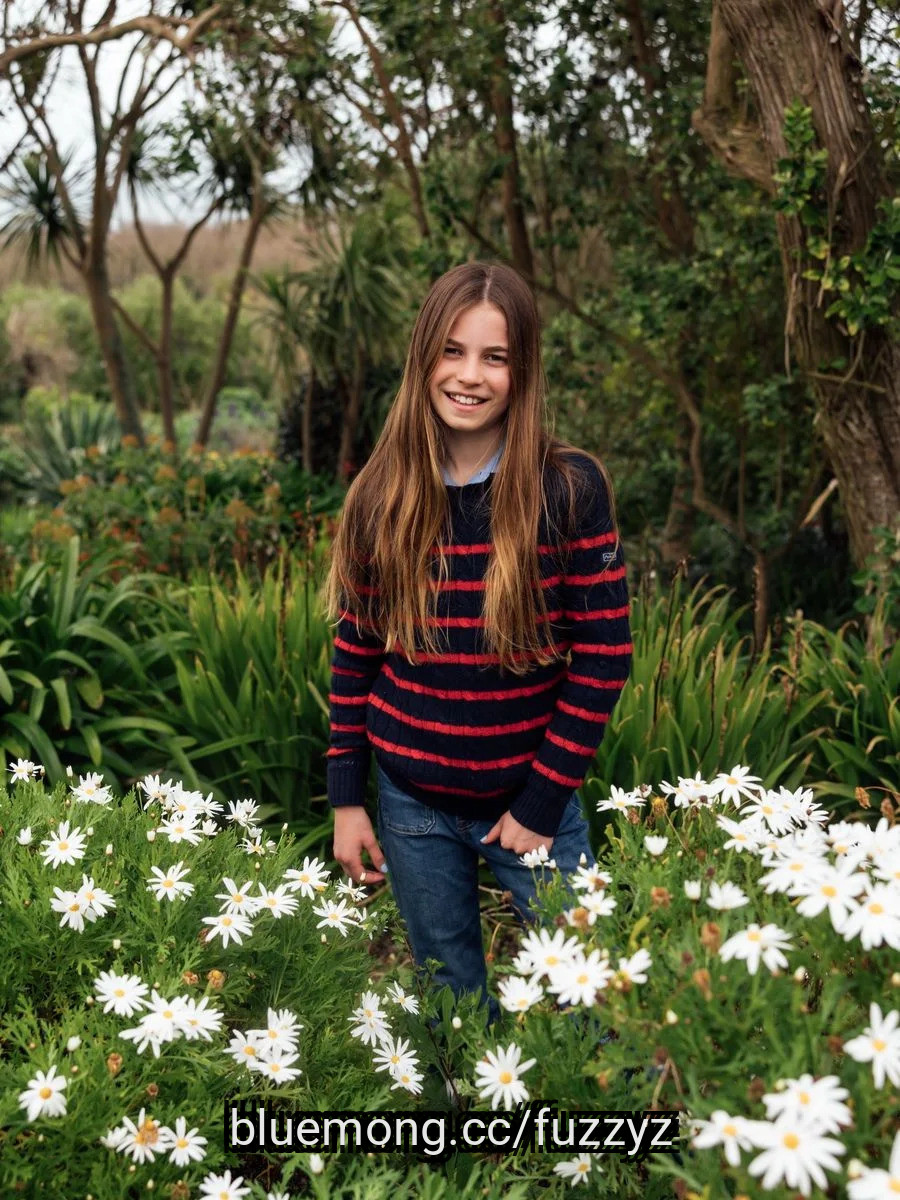
Princess Charlotte has revealed a new sporting passion, and it has a surprisingly strong connection to her royal family history. The 11-year-old princess has been seen showing off her cricket skills in family footage released by the Prince and Princess of Wales, drawing attention to a sport that was once a favorite of her great-grandfather, Prince Philip.
Prince Louis reveals what Princess Charlotte really thinks of his surprising new skill (@ Karwai Tang)
Now cricket is also getting an upgrade at Sandringham, King Charles III's private Norfolk estate, and the location of Anmer Hall, the Prince and Princess of Wales' country home. Plans call for improvements to the estate's cricket ground, creating an intriguing link between Charlotte's newfound enthusiasm, her grandfather's royal estate, and a sporting tradition that stretches back generations.
According to an exclusive report in The Sun, the Sandringham and Dersingham Cricket Club, which has long used the cricket ground on the royal estate, is planning to install an all-weather artificial surface.
A planning application submitted to the Borough Council of King's Lynn and West Norfolk details the £9,000 project, which is designed to extend playing hours and help protect the natural grass during periods of heavy rain or intensive use.
#Cricket #prince #norfolk
Prince Louis reveals what Princess Charlotte really thinks of his surprising new skill (@ Karwai Tang)
Now cricket is also getting an upgrade at Sandringham, King Charles III's private Norfolk estate, and the location of Anmer Hall, the Prince and Princess of Wales' country home. Plans call for improvements to the estate's cricket ground, creating an intriguing link between Charlotte's newfound enthusiasm, her grandfather's royal estate, and a sporting tradition that stretches back generations.
According to an exclusive report in The Sun, the Sandringham and Dersingham Cricket Club, which has long used the cricket ground on the royal estate, is planning to install an all-weather artificial surface.
A planning application submitted to the Borough Council of King's Lynn and West Norfolk details the £9,000 project, which is designed to extend playing hours and help protect the natural grass during periods of heavy rain or intensive use.
#Cricket #prince #norfolk


10 hours ago
The fashion and costume designer Bob Mackie, whose glittering creations have been worn by Cher, Dolly Parton, Tina Turner and Miley Cyrus, has died at age 87, according to his social accounts.
"It is with a heavy heart that we share the news that Mr. Bob Mackie passed away today. He lived his 87 years to the fullest, fulfilling his dream of being a Fashion and Costume Designer, which is all he ever wanted to do," read a post on his Instagram account. "His genius and extraordinary designs will live on forever, continuing to bring beauty into this world."
Mackie became known for his glamorous designs after collaborating with Cher, dressing her on television and on tour. He also served as the costume designer for "The Carol Burnett Show," responsible for Burnett's entire wardrobe. Nicknamed the Sultan of Sequins, the Rajah of Rhinestones and the Guru of Glitter, Mackie's ostentatious, flattering looks became instantly recognizable over the course of his career. His popularity continued into the modern day, with his archive coveted by a new generation of stars.
For his stage and screen work, Mackie has been awarded nine Emmys, an induction into the Television Academy Hall of Fame and three Academy Award nominations. In 1999, he received a retrospective at the Museum at FIT. More recently, he won a Tony Award for the musical "The Cher Show" and a lifetime achievement award by the Council of Fashion Designers of America.
Fern Mallis, former executive director of CFDA and founder of New York Fashion Week, credited him with many of the red carpet trends we continue to see today.
#costume #show #academy #television
"It is with a heavy heart that we share the news that Mr. Bob Mackie passed away today. He lived his 87 years to the fullest, fulfilling his dream of being a Fashion and Costume Designer, which is all he ever wanted to do," read a post on his Instagram account. "His genius and extraordinary designs will live on forever, continuing to bring beauty into this world."
Mackie became known for his glamorous designs after collaborating with Cher, dressing her on television and on tour. He also served as the costume designer for "The Carol Burnett Show," responsible for Burnett's entire wardrobe. Nicknamed the Sultan of Sequins, the Rajah of Rhinestones and the Guru of Glitter, Mackie's ostentatious, flattering looks became instantly recognizable over the course of his career. His popularity continued into the modern day, with his archive coveted by a new generation of stars.
For his stage and screen work, Mackie has been awarded nine Emmys, an induction into the Television Academy Hall of Fame and three Academy Award nominations. In 1999, he received a retrospective at the Museum at FIT. More recently, he won a Tony Award for the musical "The Cher Show" and a lifetime achievement award by the Council of Fashion Designers of America.
Fern Mallis, former executive director of CFDA and founder of New York Fashion Week, credited him with many of the red carpet trends we continue to see today.
#costume #show #academy #television


12 hours ago
Southern Company (SO) and Vistra (VST) both profited from AI power demand, yet VST shares are down 30% over the past year.
U.S. electricity prices climbed 4% over the past year, outpacing headline inflation and directly contradicting Musk's claim that AI data centers lower consumer bills.
The $180 annual savings Musk cited applies to one Georgia utility's contract; new AI-driven generation will land in rate bases all ratepayers fund.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Southern Company didn't make the cut. Enter your email to see the names that beat SO. The report is free. Enter your email and see if any of your stocks made the cut.
At 10:18 a.m. ET on Monday, Elon Musk told his audience that "AI data centers resulting in lower electricity prices for consumers" and pointed to a post claiming Georgia Power's new large-load contracts, overwhelmingly data centers, will save customers nearly a billion dollars, erasing about $180 per year from their bills. The post reached more than 503,000 impressions. Twelve days earlier, West Virginia Governor Patrick Morrisey made the same argument on CNBC, saying net electricity prices will be lower when data centers come in. It is becoming an industry talking point. It is also colliding with the price data Americans actually pay.
#data #centers #company #musk
U.S. electricity prices climbed 4% over the past year, outpacing headline inflation and directly contradicting Musk's claim that AI data centers lower consumer bills.
The $180 annual savings Musk cited applies to one Georgia utility's contract; new AI-driven generation will land in rate bases all ratepayers fund.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Southern Company didn't make the cut. Enter your email to see the names that beat SO. The report is free. Enter your email and see if any of your stocks made the cut.
At 10:18 a.m. ET on Monday, Elon Musk told his audience that "AI data centers resulting in lower electricity prices for consumers" and pointed to a post claiming Georgia Power's new large-load contracts, overwhelmingly data centers, will save customers nearly a billion dollars, erasing about $180 per year from their bills. The post reached more than 503,000 impressions. Twelve days earlier, West Virginia Governor Patrick Morrisey made the same argument on CNBC, saying net electricity prices will be lower when data centers come in. It is becoming an industry talking point. It is also colliding with the price data Americans actually pay.
#data #centers #company #musk



13 hours ago
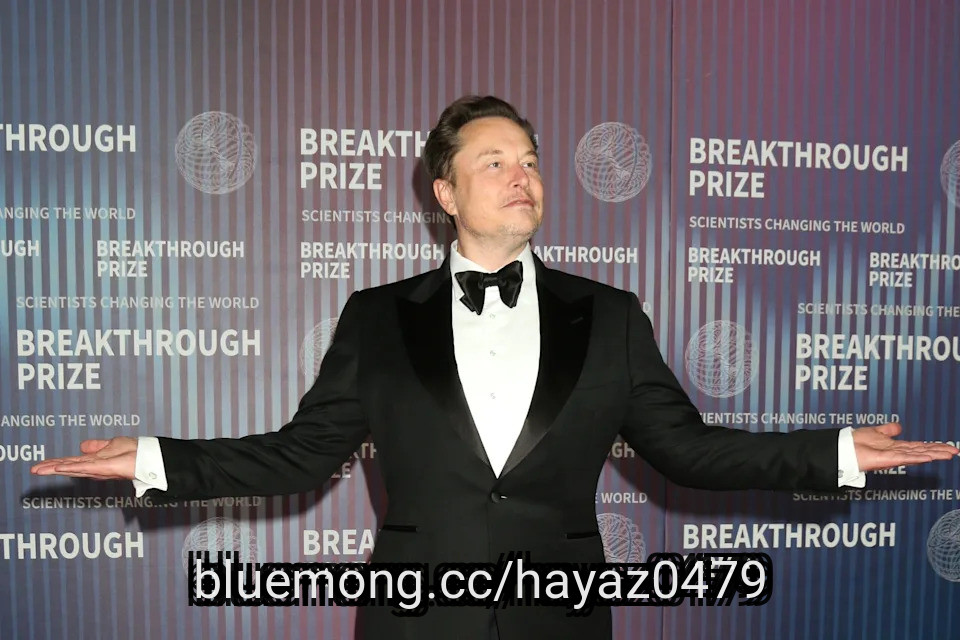
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing

13 hours ago
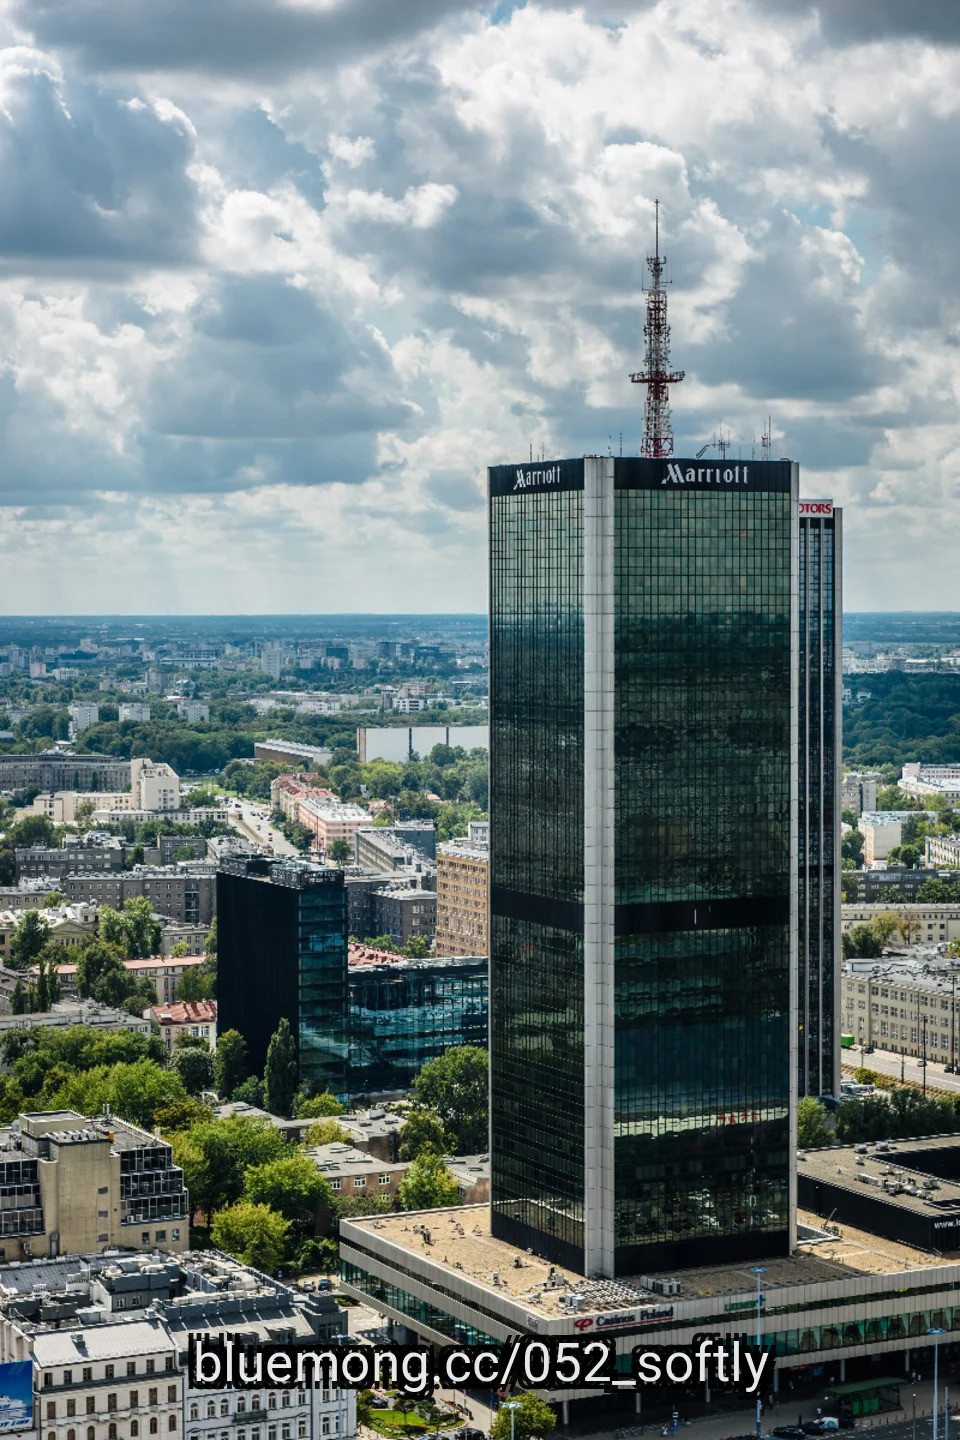
Marriott International, Inc. (NASDAQ:MAR)'s Middle East business showed a meaningful improvement in July, with revenue per available room (RevPAR) declining 12% year over year, a sharp improvement from the 43% decline in the second quarter. The improvement came despite continued regional conflict, suggesting that demand is proving more resilient than initially feared. More importantly, Marriott's global business remains strong: global room revenue increased 7% in July, with the U.S. and Canada up 8%.
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room
However, the Middle East remains a risk to Marriott International, Inc. (NASDAQ:MAR)'s growth strategy. The region represents only about 3% of Marriott's global fees but 6% of its development pipeline, meaning prolonged conflict can have an outsized impact on future hotel openings. Supply-chain disruptions and restricted capital flows have already delayed projects, pushing Marriott toward the lower end of its full-year net unit growth target.
The biggest positive is that the Middle East headwind appears to be easing faster than expected. Moving from a 43% RevPAR decline in the second quarter to just 12% in July suggests travel demand can recover even as geopolitical risks remain elevated. If the conflict stabilizes, Marriott International, Inc. (NASDAQ:MAR) could see a relatively quick rebound in regional occupancy and room rates.
More importantly, the Middle East is not large enough to overwhelm Marriott's broader global performance. The company generated a 7% increase in global room revenue in July, while U.S. and Canadian room revenue rose 8%. RevPAR growth was also broad-based across luxury, premium/select and mid-scale brands, suggesting that Marriott's strength is not dependent solely on wealthy travelers.
Marriott also benefits from an ***** et-light, fee-driven model, meaning stronger hotel demand can translate into attractive cash generation without requiring the company to own most of the underlying properties. Barron's has highlighted the resilience of this model, alongside the strength of Marriott Bonvoy and additional growth opportunities from its credit-card partnerships.
#marriott #middle #room

13 hours ago
The energy outside Cipriani, in Lower Manhattan, across from the Charging Bull statue on Broadway, seemed conspicuously suspended in a different time. It was as if crossing the threshold into the Financial District sent me back a decade, to the genesis of this current generation's cultural aesthetic—to the lines at VFiles, the SoHo clothing store whose Howard St. storefront once served as epicenter of the nascent fusion of the worlds of streetwear, hip-hop, and high fashion. All of this was because Kai Cenat, the popular Twitch streamer and content creator, was making his runway debut. The fashion show for his brand Vivet's first collection drew a crowd of the current generation's innovators, giving a reminiscent feeling to the last time a popular figure came crashing through the gates of mainstream fashion.
In attendance that night were popular streamers like Jasontheween, Rakai, and Duke Dennis, alongside more traditional celebrity names: Jaden Smith, Luka Sabbat, Lauryn Hill (!). Popular fashion podcasters and journalists from the New York Times filtered through the crowd as well. It reminded me of the pre-pandemic days of fashion week pop-ups in the shadow of Ye's YZY Szn launches, when the crowds outside seemed as consequential as whoever had a seat inside. Social media had given a generation of streetwear obsessives and aspiring artists a way to build their own audiences, and fashion was beginning to accommodate them. At Cipriani, the streamers had brought another audience into the room.
More from Rolling Stone
Big Sean and Kanye West Reunite After Feud With Surprise Appearance in Chicago
Drake Turns Kick Stream Into a 20-v-1 Dating Show, Warns Rap Rivals His 'Pen Isn't Dry'
#outside #seemed #time #streetwear
In attendance that night were popular streamers like Jasontheween, Rakai, and Duke Dennis, alongside more traditional celebrity names: Jaden Smith, Luka Sabbat, Lauryn Hill (!). Popular fashion podcasters and journalists from the New York Times filtered through the crowd as well. It reminded me of the pre-pandemic days of fashion week pop-ups in the shadow of Ye's YZY Szn launches, when the crowds outside seemed as consequential as whoever had a seat inside. Social media had given a generation of streetwear obsessives and aspiring artists a way to build their own audiences, and fashion was beginning to accommodate them. At Cipriani, the streamers had brought another audience into the room.
More from Rolling Stone
Big Sean and Kanye West Reunite After Feud With Surprise Appearance in Chicago
Drake Turns Kick Stream Into a 20-v-1 Dating Show, Warns Rap Rivals His 'Pen Isn't Dry'
#outside #seemed #time #streetwear


13 hours ago
Dow Inc. (NYSE:DOW) is reportedly considering selling its 35% stake in Sadara Chemical, its $20 billion chemicals joint venture with Saudi Aramco, as the company continues to reshape its portfolio amid a prolonged downturn in the global chemicals industry. No final decision has been made, and Aramco or another strategic or financial investor could potentially acquire Dow's stake.
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals

14 hours ago
Stanley Druckenmiller has quite a long and distinguished career as an investor. Much of this has to do with high-risk bets that have paid off enormously, such as when he and his boss, George Soros at Quantum Fund, shorted the U.K. pound for a handsome profit of what was reported to be around $1 billion.
For that reason, the trades Druckenmiller makes with his Duquesne family office matter, and his picks are taken seriously. One of the more intriguing ones is Duquesne's largest holding currently -- and for eight quarters now. It's not a famous name; rather, it's a next-generation healthcare diagnostics company that was once something of a sleeper. Here's a bit more about it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This huge bet on the future is Natera (NASDAQ: NTRA), a medical diagnostics company that uses unique, state-of-the-art technology to evaluate a patient's blood sample. Natera isn't the only business providing these liquid biopsies, as they're known, but its personalized, tumor-informed approach makes it a best-in-class screener in numerous use cases.
The major one is oncology, which is hardly surprising given the prevalence of cancer. Natera has a set of tests for this, led by Signatera, a highly personalized one constructed from the patient's tumor profile. With this, it detects circulating tumor DNA in the blood. To say this is useful in cancer detection is an understatement, so it's hardly surprising that Natera processed roughly 296,700 oncology tests in the company's second quarter. That was up a highly impressive 57% year over year.
#tumor
For that reason, the trades Druckenmiller makes with his Duquesne family office matter, and his picks are taken seriously. One of the more intriguing ones is Duquesne's largest holding currently -- and for eight quarters now. It's not a famous name; rather, it's a next-generation healthcare diagnostics company that was once something of a sleeper. Here's a bit more about it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This huge bet on the future is Natera (NASDAQ: NTRA), a medical diagnostics company that uses unique, state-of-the-art technology to evaluate a patient's blood sample. Natera isn't the only business providing these liquid biopsies, as they're known, but its personalized, tumor-informed approach makes it a best-in-class screener in numerous use cases.
The major one is oncology, which is hardly surprising given the prevalence of cancer. Natera has a set of tests for this, led by Signatera, a highly personalized one constructed from the patient's tumor profile. With this, it detects circulating tumor DNA in the blood. To say this is useful in cancer detection is an understatement, so it's hardly surprising that Natera processed roughly 296,700 oncology tests in the company's second quarter. That was up a highly impressive 57% year over year.
#tumor


2 days ago
ATLANTA − Tennessee football played its first road game of the season at Georgia Tech but it sure didn't look that way.
UT fans helped sell out Bobby Dodd Stadium as the No. 18 Vols (2-0) beat Georgia Tech 45-24 on Sept. 12. UT coach Josh Heupel noticed the support from the fans before he stepped on the field to play the Yellow Jackets (0-2).
"We leave our hotel and you see nothing but orange and white on our way here," Heupel said. "From older fans who have been here for a lot of generations to some younger ones who don't know how to tie their shoes yet, you walk into the stadium 60 minutes before kickoff and a majority of the crowd is Tennessee orange. It's pretty special."
Freshman quarterback Faizon Brandon, making the first road start of his college career, said UT fans gave him and his teammates a distinct advantage when operating the offense.
"It was a lot of orange," Brandon said. "It definitely made things easier. Wasn't too much noise. Definitely got a little rowdy sometimes, but seeing all the orange, it definitely made me proud."
#orange #definitely #brandon #first
UT fans helped sell out Bobby Dodd Stadium as the No. 18 Vols (2-0) beat Georgia Tech 45-24 on Sept. 12. UT coach Josh Heupel noticed the support from the fans before he stepped on the field to play the Yellow Jackets (0-2).
"We leave our hotel and you see nothing but orange and white on our way here," Heupel said. "From older fans who have been here for a lot of generations to some younger ones who don't know how to tie their shoes yet, you walk into the stadium 60 minutes before kickoff and a majority of the crowd is Tennessee orange. It's pretty special."
Freshman quarterback Faizon Brandon, making the first road start of his college career, said UT fans gave him and his teammates a distinct advantage when operating the offense.
"It was a lot of orange," Brandon said. "It definitely made things easier. Wasn't too much noise. Definitely got a little rowdy sometimes, but seeing all the orange, it definitely made me proud."
#orange #definitely #brandon #first



2 days ago
According to ESPN, Kansas City Chiefs quarterback Patrick Mahomes is the 13th-best fantasy quarterback heading into Week 1 of the 2026 NFL season.
Mahomes is still recovering from his ACL surgery earlier this year and is expected to struggle early in the season. The six-time Pro Bowler has never been a top fantasy quarterback, but after a disappointing finish to his 2025 campaign, Mahomes has something to prove.
For fantasy managers with the two-time MVP in their lineup this week, here are Mahomes predicted stats against the Denver Broncos on 'Monday Night Football'.
On paper, Mahomes should be at a serious disadvantage in Monday's game. Starting offensive lineman Joshua Simmons is out for an undetermined amount of time with a back injury, which leaves Mahomes' blindside in the hands of rookie offensive lineman Khalil Benson. The former Indiana Hoosier went undrafted in 2026 and has now been thrust into the starting lineup to protect a generational quarterback talent.
That being said, I feel good about Mahomes' ability to produce on Monday. With reigning Super Bowl MVP running back Kenneth Walker III in the backfield, head coach Andy Reid can open up the playbook and give Mahomes plenty of opportunities.
#mahomes #week #starting #offensive
Mahomes is still recovering from his ACL surgery earlier this year and is expected to struggle early in the season. The six-time Pro Bowler has never been a top fantasy quarterback, but after a disappointing finish to his 2025 campaign, Mahomes has something to prove.
For fantasy managers with the two-time MVP in their lineup this week, here are Mahomes predicted stats against the Denver Broncos on 'Monday Night Football'.
On paper, Mahomes should be at a serious disadvantage in Monday's game. Starting offensive lineman Joshua Simmons is out for an undetermined amount of time with a back injury, which leaves Mahomes' blindside in the hands of rookie offensive lineman Khalil Benson. The former Indiana Hoosier went undrafted in 2026 and has now been thrust into the starting lineup to protect a generational quarterback talent.
That being said, I feel good about Mahomes' ability to produce on Monday. With reigning Super Bowl MVP running back Kenneth Walker III in the backfield, head coach Andy Reid can open up the playbook and give Mahomes plenty of opportunities.
#mahomes #week #starting #offensive

2 days ago
Dell Technologies (DELL) stock more than quadrupled over the past year, a 323% gain, against about 18% for the S&P 500, and even Hewlett Packard Enterprise (HPE), up 130.6%, finished far behind. Management had described most of the drivers before the run began: customers sitting on old servers, AI orders that had outrun shipments earlier in the year, and costs falling while sales rose. Those signs could not tell you how far the stock would go.
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
2 days ago
Stellantis N.V. (NYSE:STLA)'s long-idled Belvidere ******* embly Plant in Illinois has been a case study for how a plant reopening can be pushed further into the future. The plant has been dormant since February 2023, when Stellantis N.V. (NYSE:STLA) ended the Jeep Cherokee production and laid off over 1,300 employees. A 2027 production target for Belvidere has now shifted, with Stellantis targeting pilot production of the next-generation Cherokee in the first half of 2028 and retail production in the second half of 2029, even as Stellantis portrays the news as a larger investment rather than a delay.
Stellantis N.V. (NYSE:STLA) announced an increase in its Belvidere investment to more than $800 million, up from a previous commitment of $600 million or more, and confirmed that the plant will produce the next-generation Jeep Cherokee on its new STLA One platform, the first vehicle built in the US on that modular design, which the company claims will improve manufacturing efficiency and reduce costs.
However, according to UAW Local 1268 president Matt Frantzen, citing internal records and talks with company executives, the updated schedule pushes pilot production into the first half of 2028, while retail production is not targeted to begin until the second half of 2029, roughly two years later than Stellantis' previous 2027 initial-production target.
The Belvidere news is a grave situation developing north of the border. Unifor, the Canadian union that represents Detroit Three autoworkers, stated that Stellantis N.V. (NYSE:STLA) has signed an MOU with Canadian armored-vehicle maker Roshel outlining a potential sale of its Brampton, Ontario ******* embly plant, which has been idle since 2023. According to union president Lana Payne, Stellantis N.V. (NYSE:STLA) has yet to provide the official year's notice required by the collective agreement. Payne described it as a "lose-lose scenario," claiming Stellantis' 2023 commitment to keep Brampton staffed had been broken.
The two stories are directly related. Brampton had been scheduled to build the Jeep Compass, with retooling beginning in early 2024 before Stellantis N.V. (NYSE:STLA) paused it in 2025 and then, that October, moved Compass manufacturing to the US completely, the same reassignment that sent the model to Belvidere.
#stellantis #NYSE
Stellantis N.V. (NYSE:STLA) announced an increase in its Belvidere investment to more than $800 million, up from a previous commitment of $600 million or more, and confirmed that the plant will produce the next-generation Jeep Cherokee on its new STLA One platform, the first vehicle built in the US on that modular design, which the company claims will improve manufacturing efficiency and reduce costs.
However, according to UAW Local 1268 president Matt Frantzen, citing internal records and talks with company executives, the updated schedule pushes pilot production into the first half of 2028, while retail production is not targeted to begin until the second half of 2029, roughly two years later than Stellantis' previous 2027 initial-production target.
The Belvidere news is a grave situation developing north of the border. Unifor, the Canadian union that represents Detroit Three autoworkers, stated that Stellantis N.V. (NYSE:STLA) has signed an MOU with Canadian armored-vehicle maker Roshel outlining a potential sale of its Brampton, Ontario ******* embly plant, which has been idle since 2023. According to union president Lana Payne, Stellantis N.V. (NYSE:STLA) has yet to provide the official year's notice required by the collective agreement. Payne described it as a "lose-lose scenario," claiming Stellantis' 2023 commitment to keep Brampton staffed had been broken.
The two stories are directly related. Brampton had been scheduled to build the Jeep Compass, with retooling beginning in early 2024 before Stellantis N.V. (NYSE:STLA) paused it in 2025 and then, that October, moved Compass manufacturing to the US completely, the same reassignment that sent the model to Belvidere.
#stellantis #NYSE


2 days ago
Updated Sept 11, 2026, 4:19 pm EDT / Original Sept 11, 2026, 2:41 pm EDT
Shares of power generation technology provider GE Vernova
GEV
+3.61%
are a good example of the AI malaise settling over the market for financial reasons, such as
peak AI spending
by the hyperscalers, and social reasons, such as growing concerns about AI producing
bad outcomes
for humanity.
GEV
+3.61%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#reasons #shares #company #reserved
Shares of power generation technology provider GE Vernova
GEV
+3.61%
are a good example of the AI malaise settling over the market for financial reasons, such as
peak AI spending
by the hyperscalers, and social reasons, such as growing concerns about AI producing
bad outcomes
for humanity.
GEV
+3.61%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#reasons #shares #company #reserved

2 days ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
2 days ago
Investors seeking exposure to artificial intelligence infrastructure must weigh the explosive growth of Astera Labs Inc (NASDAQ:ALAB) against the established scale and diverse portfolio of Marvell Technology Inc(NASDAQ:MRVL) to determine the better buy.
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million

2 days ago
The latest monthly list of new buys by the best mutual funds puts a dazzling spotlight on Lumentum (LITE). These savvy money managers scooped up an eye-catching $13.11 billion worth of Lumentum stock. The optical and photonics giant plays a key role in powering the infrastructure behind artificial intelligence, cloud computing, and next-generation communications. Demand from top funds continues to…
#funds #list
#funds #list

2 days ago
Salesforce (CRM) trades at 20.6 times earnings, below the S&P 500 median of 22.6, after losing 2.8% over the past twelve months while the index gained 17.9%. A profitable software company priced under the market is the setup value buyers wait for. The question is whether that is a good business on sale or a fair price for a legacy platform facing disintermediation from next-generation AI architectures.
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion
Salesforce sells the customer relationship software that companies run their sales and service teams on, and it owns Slack. Deutsche Telekom and FIFA both expanded their AI spending with Salesforce in fiscal Q2 2027. Revenue over the trailing twelve months was $43.94 billion, up 11.2%. The three-year average revenue growth rate is 9.9% a year—ahead of the S&P 500 median of 8.3%—making the last twelve months the faster of the two.
Free cash flow over the same window was $15.15 billion, a 7.6% yield on the market value. Operating margin over those twelve months is 21.5% against an S&P 500 median of 18.6%, and the margin did not thin against the year before.
Free cash flow in fiscal Q2 2027 was $1.1 billion, up 81% from a year earlier. That is one quarter. For the whole of fiscal 2027 management guides free cash flow growth of 4% to 5%, against revenue guided up 11% to 12%, so cash is set to grow at less than half the pace of the top line.
License revenue is a headwind and integration and ******* ytics revenue is volatile, management says, though both only partially offset growth in the newer lines. Near $243, the stock is just 8% off its 52-week high, though it remains about 33% below its two-year peak of $363.22: while the recent rally closed the immediate valuation gap, the longer-term discount reflects that structural hesitation hasn't fully cleared.
#cash #billion

2 days ago
High-performance computing is currently undergoing a massive generational shift. Deciding between Astera Labs Inc (NASDAQ:ALAB) and Applied Materials Inc (NASDAQ:AMAT) means choosing between a fast-growing connectivity specialist and an established ******* an of manufacturing equipment.
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ

2 days ago
Navan Inc. (NASDAQ:NAVN), a global AI-enabled business travel and expense management solutions provider, announced its second quarter results on September 9. The company registered a 45% growth in its gross booking volume (GBV), which reached more than $3 billion. Such growth was fueled by cohort expansion, customer additions and increase in its existing install base. Total revenue for the quarter was $233 million, representing a 35% year-over-year jump. The company's adjusted operating income more than doubled compared to Q2 FY26, and the quarter also saw positive cash flow generation.
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume
Copyright: kentoh / 123RF Stock Photo
Navan delivered robust performance during the recently concluded quarter, driven by a 35% increase in usage revenue which clocked in at $211 million. Subscription revenue was also up 39%, reaching $21 million. Apart from the 45% GBV expansion, a 34% growth was witnessed in Q2 Payment Volume which stood at $1.3 billion. One of the highlights of this quarter was a turnaround in adjusted net income, which jumped from an $8 million loss in Q2 FY26 to a $14 million profit for the reported period.
Enterprise market momentum remained persistent during the period, as the company established partnerships with leading names such as Evotec, Enbridge, ****** mins, and Ingersoll Rand. Significant progress was made around the Navan's proprietary AI agent, Ava, which managed roughly 60% of the total customer interactions. More than 50% of AI calls are now being managed through the company's in-house AI models, compared to 30% for the previous quarter.
Additionally, the company finalized its acquisition of a leading travel management business, Smartrips. This will enable Navan to expand its presence within the swiftly expanding Latin American market. Navan also acquired an AI-led meetings and events management platform, BoomPop.
#volume

2 days ago
As artificial intelligence matures, investors must decide between the high-growth niche players and the foundational giants. Choosing between Astera Labs Inc (NASDAQ:ALAB) and Taiwan Semiconductor Manufacturing Co (NYSE:TSM) involves weighing explosive potential against established dominance.
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
2 days ago
The Cooper Companies Inc. (NASDAQ:COO), a leading medical device company, announced its third quarter fiscal 2026 results on September 9. Topline went up 1% to $1.066 billion in comparison with the same quarter last year, which also included 1% organic growth. The company posted quarterly adjusted diluted EPS of $1.15, which represented a 4% jump from Q3 FY25. During the quarter, $339.1 million was spent on repurchasing around 4.9 million of the company's common shares. This leaves management with $1.5 billion of repurchase capacity, which remains available after the Board had raised its buyback authorization from $2 billion to $3 billion.
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash

2 days ago
With a market cap of $49.4 billion, Vistra Corp. (VST) is a leading integrated electricity and power generation company. The company provides essential energy resources to customers, businesses, and communities across the United States, with a strong focus on reliability, affordability, and sustainability.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Vistra fits this criterion perfectly. Vistra operates a diverse and efficient power generation portfolio spanning natural gas, nuclear, coal, solar, and battery energy storage, complemented by a customer-centric retail business.
Why It's Time to Load Up on Intel Stock
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
#Stock #energy #corp
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Vistra fits this criterion perfectly. Vistra operates a diverse and efficient power generation portfolio spanning natural gas, nuclear, coal, solar, and battery energy storage, complemented by a customer-centric retail business.
Why It's Time to Load Up on Intel Stock
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
#Stock #energy #corp
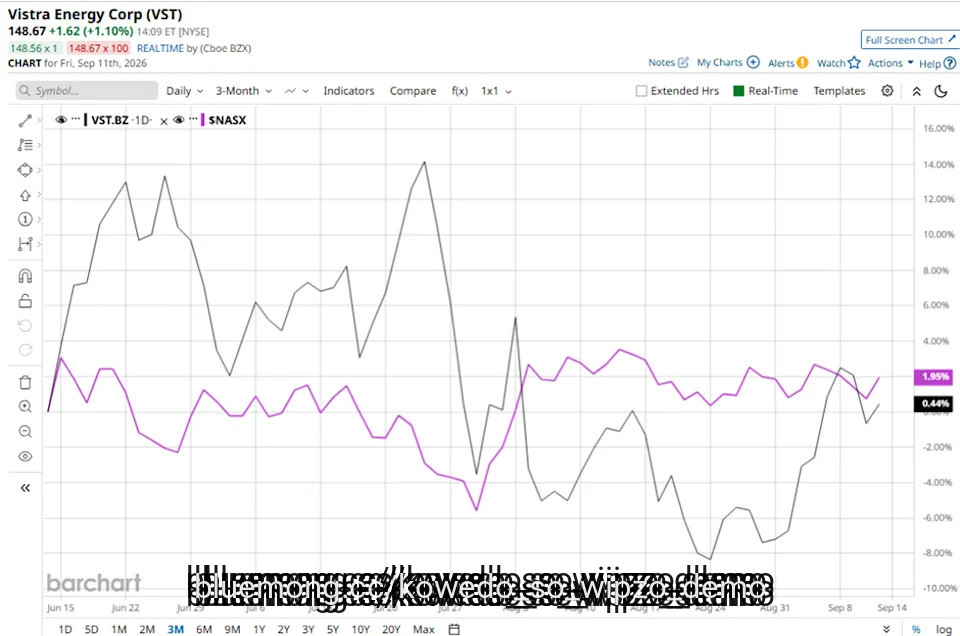


2 days ago
Palo Alto Networks, Inc. (NASDAQ:PANW) is entering its fiscal 2027 with strong momentum, particularly in next-generation security. But investors now demand more from the cybersecurity company after its stock rallied sharply.
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
On September 7, PhillipCapital downgraded Palo Alto stock to Neutral from Accumulate but raised the price target to $346 from $320.
PhillipCapital's move captures the central investment debate. It's that Palo Alto's opportunities are compelling, but the stock's roughly 160% rise from its February low to its August peak has raised the bar for further gains.
Palo Alto Networks, Inc. (NASDAQ:PANW)'s revenue rose 34% YoY to $3.4 billion in fiscal 2026 fourth quarter. More importantly, Next-Generation Security ARR (NGS ARR) surged 63% to $9.10 billion. The company added nearly $1 billion of net new NGS ARR in the quarter. The company targets $20 billion in NGS ARR by fiscal 2030, as it expects platformization and AI infrastructure investment to continue driving growth.
More than 65% of Palo Alto's NGS ARR comes from platformized customers. Meanwhile, AI is expanding the addressable market. As enterprises deploy agents, Palo Alto offerings such as Prisma AIRS and Cortex, alongside CyberArk's identity-security platform, can address emerging needs.
#palo #company #NASDAQ #PANW
2 days ago
NVIDIA Corporation (NASDAQ:NVDA) is expanding its global AI infrastructure ambitions, with Australia emerging as an important new market for its growing portfolio of GPUs, CPUs, networking products, and AI software.
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian

2 days ago
Heat Central: Norman Powell believes the Heat got WAY BETTER with the Giannis trade: "Anytime you get a generational talent like that it automatically puts you into contention. He's a generational player… They got some dawgs. Shoutout my man D Mitch. Off night and Bam. They gonna be good. I'm excited to see how it all comes together. They signed Klay. That's a good pickup for them. They made some good moves"
This article originally appeared on Hoops Hype: "Anytime you get a generational talent like that it …
#generational #heat #powell
This article originally appeared on Hoops Hype: "Anytime you get a generational talent like that it …
#generational #heat #powell