

25 days ago
Medicare calculates Part B and Part D surcharges using income from two years prior, so a profitable ***** et sale can trigger higher premiums long after the money is spent.
IRMAA resets annually, so a one-time income spike typically raises premiums for only one or two years before fading as normal income returns.
Voluntary ***** et sales don't qualify for SSA-44 relief, making pre-sale income planning the only real tool to minimize Medicare surcharges.
Many financial professionals are salespeople paid on what they push, not whether you end up wealthier. A fiduciary is the opposite. The SEC legally requires them to put your interests first. Advisor.com's free matching tool pairs you with vetted fiduciaries from major national firms, all in under three minutes. See who you match with today.
Picture a longtime fan who bought a personal seat license two decades ago, giving him the right to buy the same season tickets year after year. He has climbed the same stadium stairs every fall, watched his knees start to complain and finally decided the ticket rights were worth more to him as cash than as seats he uses a handful of times each season.
#income #medicare #premiums #tool
1 month ago
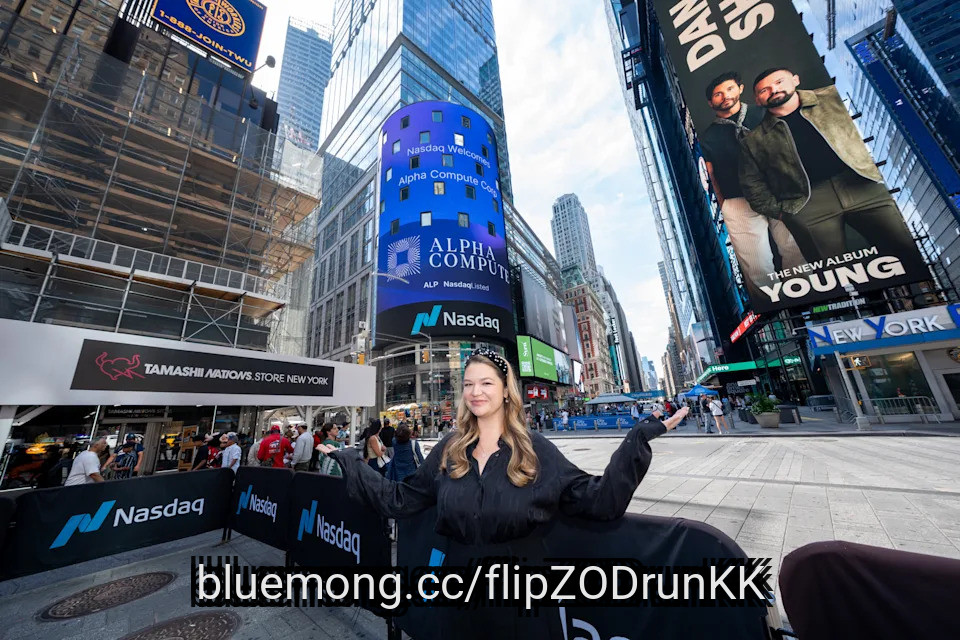
IPO Edge hosted a fireside chat on Aug. 26 at Nasdaq MarketSite with Brittany Kaiser, Chief Executive Officer of Alpha Compute Corp. (Nasdaq: ALP). The in-person interview was joined by Editor-in-Chief John Jannarone and they discussed how the company is building the infrastructure AI runs on with a focus on data privacy, and how its vertically integrated business model is boosting compute revenue.
About Brittany Kaiser
Brittany Kaiser is Chief Executive Officer of Alpha Compute Corp. (Nasdaq: ALP), where she leads strategy in confidential computing, data sovereignty, and AI infrastructure. A globally recognized authority on data rights, digital **** ets, and AI governance, she became a leading voice in the modern privacy movement after serving as a whistleblower in the Cambridge **** ytica scandal.
Kaiser is the author of the international bestseller Targeted and the principal subject of the Emmy- and BAFTA-nominated Netflix documentary The Great Hack. She has advised U.S. congressional committees, governments, and regulators on data ownership, digital **** et policy, and responsible AI, and co-authored legislation shaping the digital economy. A serial entrepreneur and advocate, she is also Co-Founder and President of the Own Your Data Foundation and a sought-after keynote speaker worldwide.
About Alpha Compute Corp (Nasdaq: ALP)
Alpha Compute Corp. (Nasdaq: ALP) is a vertically integrated AI infrastructure company specializing in GPU-as-a-service and AI Confidential Compute. Alpha Compute's mission is to support clients, subsidiaries, and partners across critical sectors including: finance, defense, intelligence, and media with the essential framework for any organization requiring secure, confidential computing environments. For more information, please visit: https://www.alphacompute.a...
Alpha Compute Corp is domiciled in the British Virgin Islands with offices in New York, Los Angeles, Miami, Amsterdam and Toronto. Alpha Compute is a founding partner of the Right2Compute Coalition; more information is available at www.right2compute.com.
#compute #alpha #chief #infrastructure
1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Space Exploration Technologies Corp. CEO Elon Musk says the company will provide discounted access to its Starlink satellite internet services to residents living close to the upcoming Starbase launch site in Louisiana.
In a post on X on Thursday, the official Starlink handle said that residents of Vermillion Parish would be eligible for discounted prices on the Residential plan. "We are applying a 50% discount to Starlink Residential service plans," Starlink said, according to the official its official website linked in the post.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#residential #residents #exploration

1 month ago
Interested in Rocket Lab Corporation? Here are five stocks we like better.
Rocket Lab shares have fallen more than 50% from their May peak amid a sector-wide rotation following the ****** eX IPO, though selling pressure appears to be easing.
The company reported record quarterly revenue and a backlog surpassing $2.3 billion, while continuing to win major defense contracts including NITE-STAR and Flatellite awards.
Analysts maintain a Moderate Buy consensus with a $110.65 average price target, though the stock's high valuation and delayed Neutron rocket debut keep it volatile.
This summer, Rocket Lab (NASDAQ: RKLB) has been a difficult stock to own. After peaking at $151 in May, the shares were swept up in the brutal rotation that followed the ****** eX (NASDAQ: SPCX) IPO, giving back more than half their value as investors fled the ****** e sector.
#though

1 month ago
UPS disclosed Monday that it is investing more than $2 billion across its international, healthcare, and supply chain solutions businesses, revealing the total figure for the first time. The investments began in 2024 and are set to continue through 2028, the company said.
Scott Szwast, UPS vice president of international strategy, framed the spending as an effort to build out capabilities that help customers in specialized sectors navigate increasingly complicated global supply chains. "These investments are really aligned to one of our big strategic areas of focus, which is creating capabilities to enable our customers, particularly in complex industries, to more effectively run their global supply chains," he told CNBC.
Among the initiatives are a new hub in the Philippines slated for this year, a facility in Ontario, Canada, due to open in 2027, and an air hub at Hong Kong International Airport scheduled for 2028. UPS has also opened a technology-enabled logistics center in Taiwan and an Amsterdam facility that integrates freight forwarding, customs brokerage, and cold-chain capabilities under one roof. The Taiwan facility has used automation and robotics to cut total supply chain time by one day, Szwast said. UPS also operates weekly service on the Paris–Hong Kong route and the Shenzhen–Sydney route, each running five days a week.
Szwast said that as global supply chains come under growing strain, companies have moved to spread risk across multiple sourcing and distribution points rather than relying on a single node, even as those same businesses push out new products with unfamiliar logistics demands faster than ever before. "What they find in a lot of cases is that their supply chains look more like their histories than their strategies," he said.
The $2 billion figure encompasses a previously announced $48 million buildout of 27 temperature-controlled facilities across the Americas, Europe, and Asia aimed at handling temperature-sensitive pharmaceuticals, including GLP-1 weight loss drugs. UPS said the healthcare initiative is part of its broader effort to grow in higher-margin logistics services.
#chains #facility #Logistics

1 month ago
On August 13, ARS Pharmaceuticals (NASDAQ:SPRY) held its second-quarter 2026 earnings call, the first for new President and CEO Donn Casale. He used it to lay out three priorities: sharper commercial targeting for neffy, tighter financial discipline, and a pipeline push into chronic spontaneous urticaria. The quarter itself showed a company still early in proving its epinephrine nasal spray can win over prescribers who default to needle-based injectors out of habit.
The headline number is market share. Neffy's total US share reached 5% in the second quarter, double the 2.5% mark from a year earlier. Inside the field sales team's targeted call universe, share jumped further, to 8% from 4%. That targeted approach is showing up in the prescriber data too, with more than 16,000 unique neffy prescribers in the quarter, over three times the year-ago total. Casale pointed to a stark gap between covered and uncovered territory: where the sales team is active, neffy holds 8% share versus roughly 1% where it isn't.
To lead that push, ARS brought on Meg Smith as Chief Commercial Officer, a 25-year veteran Casale worked with at Dynavax. The field organization is now fully built out and pointed at the highest-value prescribers, who represent 44% of the total market opportunity. Beyond neffy, ARS is extending its intranasal epinephrine platform into CSU, a market with no FDA-approved on-demand treatment for acute flares today, a gap the company believes its existing commercial infrastructure is positioned to fill.
The flip side of that story is cost. Second quarter total revenue was $33.7 million, with $26.2 million of that coming from US net product sales, against total operating expenses of $95.1 million, including $12.8 million in cost of goods sold. SG&A alone ran approximately $77.6 million for the quarter, a level Casale acknowledged reflected an earlier strategy built around broad consumer advertising that didn't convert well in what he described as a prevention-based market rather than a treatment market.
The company is now guiding to combined SG&A and R&D expenses of $114 million to $126 million for the back half of 2026, with cash-based spending in that category expected to fall to $100 million to $110 million, a cut of more than 40% in cash SG&A from the first half of the year. That reduced spending pace is expected to hold through 2027. On the pipeline side, the CSU phase II-B interim readout, previously expected by the end of 2026, has slipped to the first quarter of 2027, a delay the company attributed to the trial's design requiring patients to log three separate flare episodes before data can be collected.
#million #market #company #year

1 month ago
NVIDIA Corporation (NASDAQ:NVDA) is heading into its August 26 earnings report with expectations already elevated. Wall Street firm Stifel believes it can clear this high bar, with its bull case built around independent checkpoints scattered across the supply chain.
On August 19, Stifel ******* yst Ruben Roy reiterated a Buy rating on the stock with a $282.00 price target, implying roughly 30% upside from current levels. Stifel anticipates Nvidia to beat estimates and raise guidance, noting how its broader coverage preview reinforces the demand case for the stock.
One company behind Stifel's bullish call is Foxconn, legally known as Hon Hai Precision Industry Co., Ltd. Foxconn is the world's largest electronics contract manufacturer and a key Nvidia partner in its artificial intelligence buildout. The company reported second-quarter revenue of NT $2.53 trillion, jumping 41% year-over-year. Operating profit increased 68%, while net profit increased 35% backed by continued strong demand for AI.
Roy cited how Foxconn had its cloud and networking segment cross 50% of revenue for the first time with full-year AI rack shipments guided to more than double. CEO Michael Chiang reinforced this by noting that AI-related business performance will continue to grow in the third quarter and that the company expects significant quarter-on-quarter growth and strong year-on-year growth.
Another company supporting Stifel's bullish case is Super Micro Computer Inc (NASDAQ:SMCI). Super Micro is a global technology leader that designs and builds servers, storage systems, and complete rack-scale hardware for data centers. These AI servers and hardware sit at the core of data centers running Nvidia accelerators.
#NASDAQ
1 month ago
Aristotle Capital Boston, LLC, an investment advisor, released its "Small Cap Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned 13.69% in the second quarter of 2026, trailing the Russell 2000 Index's 21.49% gain as security selection in information technology and industrials weighed on performance despite positive allocation effects. Top contributors included MACOM Technology Solutions and Mercury Systems, which benefited from strong demand in semiconductor, aerospace, and defense markets, while Alamos Gold and Huron Consulting Group detracted due to operational challenges, weaker gold prices, and investor concerns surrounding artificial intelligence disruption. During the quarter, the fund initiated positions in IPG Photonics and UMB Financial, citing opportunities tied to advanced manufacturing, automation, reshoring trends, and diversified financial services, while exiting Americold Realty Trust, Byline Bancorp, and Verra Mobility. Looking ahead, management remains constructive on U.S. small-cap equities, noting that valuations remain attractive relative to large caps and that earnings growth is expected to accelerate into late 2026 and 2027. Factors such as increased merger and acquisition activity, improving domestic manufacturing due to reshoring and infrastructure investments, and a favorable regulatory environment are expected to support this ******* et class in the long term. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Small Cap Equity Fund highlighted stocks like Verra Mobility Corporation (NASDAQ:VRRM). Verra Mobility Corporation (NASDAQ:VRRM) provides smart mobility technology and transportation solutions for commercial fleets, government programs, and parking management. The one-month return of Verra Mobility Corporation (NASDAQ:VRRM) was 19.62% while its shares traded between $3.4000 and $25.56500 over the last 52 weeks. On August 19, 2026, Verra Mobility Corporation (NASDAQ:VRRM) stock closed at approximately $4.500 per share, with a market capitalization of about $709.74 million.
Aristotle Small Cap Equity Fund stated the following regarding Verra Mobility Corporation (NASDAQ:VRRM) in its Q2 2026 investor letter:
Verra Mobility Corporation (NASDAQ:VRRM) is a provider of automated enforcement, tolling and parking technologies and solutions. We exited the position after the loss of a significant customer contract materially changed our investment thesis, reducing confidence in the company's long-term earnings and growth outlook. The proceeds were redeployed into higher-conviction opportunities.
#vrrm
1 month ago
Treasury Secretary Scott Bessent recently declared that the K-shaped economy "is over." New research says he might be right.
After a prolonged period of sharp divergence between higher and lower-income household spending and earning patterns — dubbed the K-shaped economy because higher earners have continued to spend, forming the top branch of the K, while lower earners, the bottom of the K, pulled back — the gap is beginning to narrow again, economists at the Bank of America Institute led by David Tinsley wrote in a report last week.
"As of July, spending and wage growth have largely converged across income cohorts, with the exception of the top 5% of earners, who continue to outpace the rest," the report said.
Debit and credit card spending across all income levels was up 5% in July from a year ago, with lower-income households showing a 5.4% gain. Middle-income earners, meanwhile, spent 4.9% more than last year.
Read more: How to find the best credit cards with no annual fee
#shaped #economy #higher

2 months ago
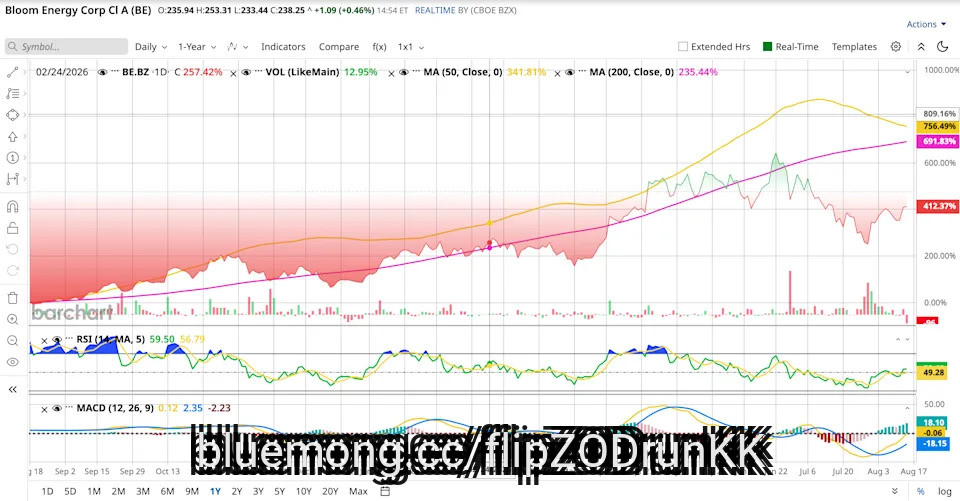
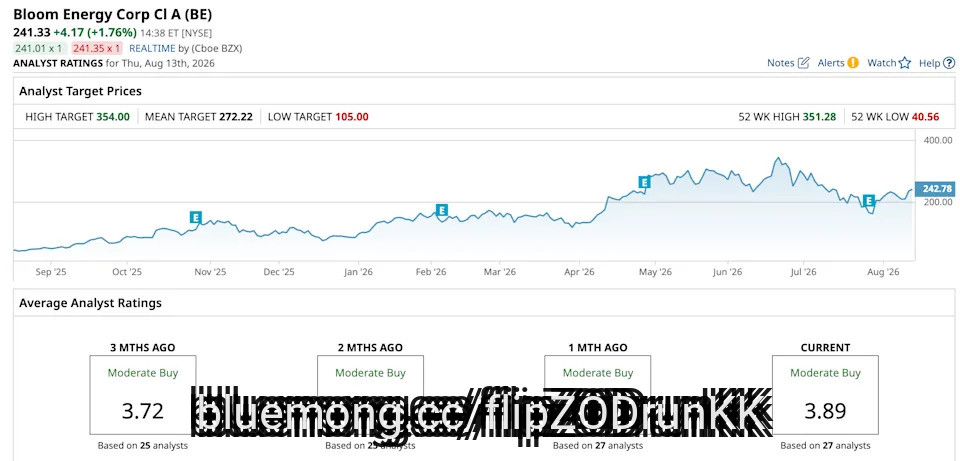
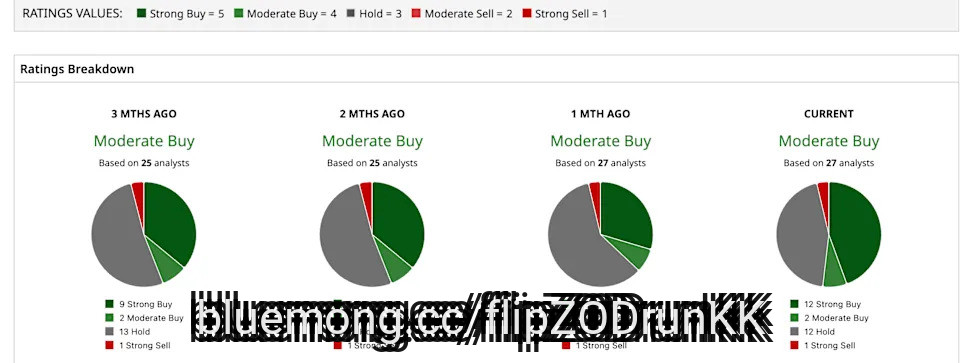
Nebius Group N.V. (NBIS) recently released its quarterly results, and management had some encouraging things to say about Bloom Energy Corporation (BE). During the Q2 earnings call, Chief Communications Officer Tom Blackwell said switching to Bloom's fuel-cell technology would significantly enhance the company's planned 300-megawatt AI data center in Vineland, New Jersey, particularly from a community perspective.
Chief Product and Infrastructure Officer Andrey Korolenko added that Bloom's fuel cells should be deployed quickly, with no significant impact expected on the project timeline. Investors liked what they heard, sending BE stock 12.3% higher on Wednesday, Aug. 12.
Elon Musk Said Tesla Short Sellers Would Be 'Obliterated' Even Bill Gates — Yet They've Made $9 Billion This Year Shorting the Stock
Sergey Brin Wants Google to Double Down on Gemini. What That Means for GOOGL Stock.
Alphabet Stock to $515: 3 Reasons the Bull Case Is Getting Stronger
#officer
2 months ago
HCA Healthcare, Inc. (NYSE:HCA) reported its second-quarter 2026 financial results on July 24, confirming the figures previewed earlier in the month. While top-line growth remained healthy, a visible deterioration in payer mix and a revision to full-year profitability guidance triggered immediate target cuts across Wall Street.
In its Q2 results, HCA Healthcare, Inc. reported that revenue increased 8.7% year-over-year to $20.23 billion from $18.61 billion in Q2 2025. The firm's net income attributable to the company rose 2.8% to $1.69 billion, while diluted EPS increased 11.6% to $7.62 (or $7.59 on an adjusted basis). Adjusted EBITDA grew 4.6% to $4.027 billion compared to $3.849 billion in the prior-year period. Operational volume remained positive overall, with same-facility admissions up 2.5%, equivalent admissions up 2.7%, and emergency room visits rising 3.6%. However, same-facility inpatient surgeries dropped 2.3%, and outpatient surgeries fell 3.4%.
Despite the top-line expansion, management was forced to adjust its full-year 2026 outlook downward. The company now expects 2026 diluted EPS of $28.70 to $30.50 (down from $29.10 to $31.50) and Adjusted EBITDA of $15.40 billion to $16.10 billion (down from $15.55 billion to $16.45 billion), while narrowing revenue guidance to $77.00 billion to $79.50 billion.
The primary culprit was a policy-driven payer mix shift: an uptick in uninsured volume following Medicaid redeterminations and the lapse of health insurance exchange coverage wiped out roughly $400 million from Q2 pre-tax income. HCA now anticipates the full-year exchange-related drag to reach $1.00 billion to $1.20 billion, partially offset by $300 million to $500 million in net Medicaid Supplemental Payment Program benefits.
Following the report, ***** ysts swiftly adjusted their models. On July 28, Mizuho lowered its price target on HCA to $475 from $525 while keeping an Outperform rating, citing slower post-Q2 growth expectations. The same day, Morgan Stanley reduced its price target to $380 from $425 and maintained an Underweight rating. Morgan Stanley ***** yst noted that while lower guidance "puts numbers in a better place," core EBITDA performance was "disappointing," warning of a full valuation alongside a rising risk profile in payer mix.
#year #payer #guidance
2 months ago
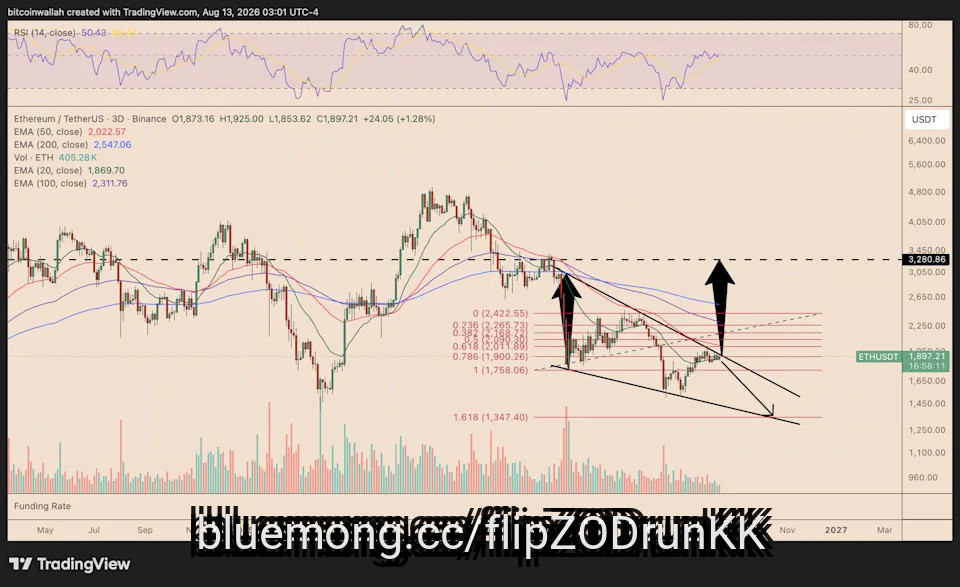
Ethereum's native token, Ether (ETH), could rally more than 50% toward $3,000 in the coming weeks, according to crypto ***** yst Michaël van de Poppe, who argues that the current price range offers an attractive accumulation opportunity before a potential breakout.
In an Aug. 12 post, Van de Poppe said the "ideal moment" to position in Ethereum is "literally right now," arguing that investors waiting for definitive bullish confirmation could risk entering after a substantial portion of the move has already occurred.
His three-day ETH/USD chart highlights previous accumulation phases around the $1,500–$2,000 region that preceded sharp upside moves.
In one example, Ethereum rallied roughly 60% within less than a week after escaping a similar consolidation range. Van de Poppe also pointed to comparable price behavior in 2023, suggesting ETH could repeat the pattern "in a matter of days/weeks."
A rally toward Van de Poppe's $3,000 target would represent gains of approximately 57% from the current price.
#price #range #accumulation


2 months ago
ExxonMobil (NYSE:XOM) reported second-quarter 2026 results on July 31, and the headline number disappointed. Adjusted earnings came in at $3.52 per share, short of the $3.60 ***** ysts expected, even though that figure was up sharply from a year earlier. Reported earnings were $14.5 billion, or $3.48 per share. But the company also generated $23.6 billion in cash from operations and $17.2 billion in free cash flow, enough to fund $9.4 billion in shareholder distributions with room to spare. The miss made headlines. The cash didn't miss anything.
Exxon's operating results told a different story than the earnings line. The company posted its highest upstream production in more than two decades, excluding disruptions in the Middle East, and Permian output topped 1.8 million oil-equivalent barrels per day, a record pace consistent with its planned 9% annual growth rate through 2030. A fifth Guyana production vessel set sail during the quarter, with startup on track for the fourth quarter of 2026 and 250,000 barrels per day of new capacity coming online. Diesel production also hit a second-quarter record. None of that shows up directly in a per-share earnings number, but it is the foundation the company is building future cash flow on.
Cost discipline reinforced the picture. Exxon has now banked $16.3 billion in ***** ulative structural cost savings since 2019, including $1.2 billion added in the first half of 2026 alone, a total the company says exceeds what BP, Chevron, Shell, and TotalEnergies have saved combined. It kept investing anyway, spending $13.0 billion in cash capital expenditures through midyear, about 20% more than its nearest rival. Growing production while cutting costs is the combination that funds a rising dividend.
The earnings miss wasn't the only soft spot. The first quarter of 2026 generated just $2.7 billion in free cash flow against $9.2 billion in shareholder distributions, forcing Exxon to lean on its balance sheet, with debt-to-capital reaching 15.4% at the time. Zoom out to the full first half and the math is tighter than the strong second quarter suggests: $19.9 billion in free cash flow covered $18.6 billion in distributions, leaving only about $1.3 billion of cushion. The company reduced debt by $7 billion in the second quarter and brought net debt-to-capital down to 11%, but the episode is a reminder that commodity earnings swing hard from quarter to quarter, and the roughly $37 billion a year Exxon is committing to dividends and buybacks needs strong quarters to keep showing up.
#quarter #cash

2 months ago
Core Scientific, Inc. (NASDAQ:CORZ) announced a major infrastructure partnership with Advanced Micro Devices, Inc. (NASDAQ:AMD) on July 28, giving the chipmaker's ecosystem access to more than 500 megawatts of U.S. data-center capacity beginning in 2027. The arrangement can expand to 2.5 gigawatts. Core Scientific shares rallied in premarket trading.
The agreement is more substantial than the initial announcement suggested. Core Scientific's earnings release described 15-year agreements covering approximately 530 megawatts across five sites, with more than $14 billion of potential base contracted revenue. Its regulatory filing provided an important distinction: AMD directly leased 377 megawatts, while an unnamed neocloud leased another 152 megawatts under agreements that give AMD certain equipment protections and rights if that customer defaults.
The larger story, however, began nine months earlier. Core Scientific shareholders rejected an all-stock acquisition by CoreWeave whose announcement-date implied equity value was approximately $9 billion. The fixed exchange ratio valued CORZ at $20.40 per share when the transaction was announced in July 2025, but the value shareholders would have received at closing was not fixed and moved with CoreWeave's share price.
In January, Gullane Capital Partners founder Trip Miller, who had opposed the sale, predicted that Core Scientific would secure new AI customers. "I expect them to announce deals for AI with third parties other than CoreWeave," he told Business Insider.
The new agreements appear to deliver precisely that customer diversification. Taken together, AMD's 377-megawatt direct lease and the neocloud's 152-megawatt lease exceed Miller's roughly 400-megawatt expectation, although AMD itself did not directly lease the full 529 megawatts. The question is whether the agreements prove that shareholders were right to preserve Core Scientific's independence, or merely give the company a large, capital-intensive opportunity whose ultimate value remains uncertain.
#lease