42 mins. ago
In XRP news today, its 30-day liquidity index on Binance has climbed to 0.0675, the highest reading in about six months. Its 30-day turnover recovered to approximately $4.6 billion after sinking to between $2 billion and $3 billion during July and August.
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading
The rebound signals that XRP liquidity conditions have meaningfully improved, but a deeper order book supports both accumulation and distribution equally well, and is leaving the question of which side actually controls this market unanswered.
The liquidity index measures how easily traders can move XRP in and out of positions without moving the price against themselves, calculated against how quickly XRP turns over relative to what Binance holds on its books. A rising reading means faster turnover and tighter execution, which is exactly what the data shows.
XRP closed August up about 28.5%, its strongest August performance since 2021, while U.S. spot XRP ETF products pulled in $153.55 million of inflows that month.
Now, the flow data from the end of last week complicates a clean bullish read. More than 91 million XRP moved into Binance on the 11th, and over 113 million XRP moved out, both six-month highs in single-day volume. Withdrawals outpaced deposits by 22.7 million XRP, yet Binance's total XRP holdings rose just 0.43% over the full week.
#reading


59 mins. ago
Once upon a time, the 'space race' meant the grand strategic competition between the USA and the USSR to gain control of the heavens. The superpowers designed and built satellites, manned capsules, orbital **** ecraft and long-endurance **** e stations, and NASA even sent the Apollo landers to put men on the Moon.
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once


1 hr. ago
Palantir Technologies (PLTR) and Nebius Group (NBIS) have joined forces in a partnership that directly supports both companies' growth stories. Palantir gets a compute partner that can support its push into sovereign AI, while Nebius gains access to a prominent enterprise distribution channel through Palantir. That makes the deal appear straightforward and mutually beneficial on paper. Still, both stocks face growing investor skepticism. Palantir's valuation remains a major point of debate among investors, and Nebius still needs to show that its capital-heavy build-out will eventually lead to durable profitability.
Palantir has designated Nebius as its preferred sovereign AI infrastructure partner. The company plans to integrate Nebius' compute and inference endpoints into the Palantir enterprise perimeter following an integration period. The partnership will allow eligible Palantir customers to use Nebius' infrastructure while maintaining control over their own compute, models, and data. The companies will also collaborate to expand compute capacity more quickly, including through modular data center builds at sites with available power.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#palantir #compute #still
Palantir has designated Nebius as its preferred sovereign AI infrastructure partner. The company plans to integrate Nebius' compute and inference endpoints into the Palantir enterprise perimeter following an integration period. The partnership will allow eligible Palantir customers to use Nebius' infrastructure while maintaining control over their own compute, models, and data. The companies will also collaborate to expand compute capacity more quickly, including through modular data center builds at sites with available power.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#palantir #compute #still



3 hours ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
4 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market

5 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter #investor

5 hours ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700

6 hours ago
With Agentic AI accelerating CPU server chip demand, Wall Street believes Advanced Micro Devices, Inc. (NASDAQ:AMD) is one of the primary beneficiaries taking share. On September 9, Piper Sandler ******* yst David O'Connor initiated coverage on AMD (NASDAQ: AMD) with an Overweight rating and a $600 price target.
Analyst O'Connor estimates revenue for FY26-30 to grow at a 50% CAGR, while earnings per share compound at 65%.
The server-CPU share gain story for AMD is simple, Agentic AI is expected to increase demand for server CPUs. This is because the workloads require continuous control-plane activity, API calls, database queries and tool execution. AMD will benefit from this use based on its high-frequency and general-purpose processors with its Venice portfolio.
Even AMD executives have highlighted that AMD is now transitioning from merely a semiconductor supplier to a provider of rack-scale systems and software. It is also positioning its server CPU portfolio for increased demand from agentic AI workloads.
The company reported second-quarter revenue of $11.5 billion, beating ******* yst estimates. This includes $6.7 billion from data centers, up 107% year-over-year. The segment performance was attributed to EPYC processors and Instinct GPUs.
#workloads
Analyst O'Connor estimates revenue for FY26-30 to grow at a 50% CAGR, while earnings per share compound at 65%.
The server-CPU share gain story for AMD is simple, Agentic AI is expected to increase demand for server CPUs. This is because the workloads require continuous control-plane activity, API calls, database queries and tool execution. AMD will benefit from this use based on its high-frequency and general-purpose processors with its Venice portfolio.
Even AMD executives have highlighted that AMD is now transitioning from merely a semiconductor supplier to a provider of rack-scale systems and software. It is also positioning its server CPU portfolio for increased demand from agentic AI workloads.
The company reported second-quarter revenue of $11.5 billion, beating ******* yst estimates. This includes $6.7 billion from data centers, up 107% year-over-year. The segment performance was attributed to EPYC processors and Instinct GPUs.
#workloads


7 hours ago
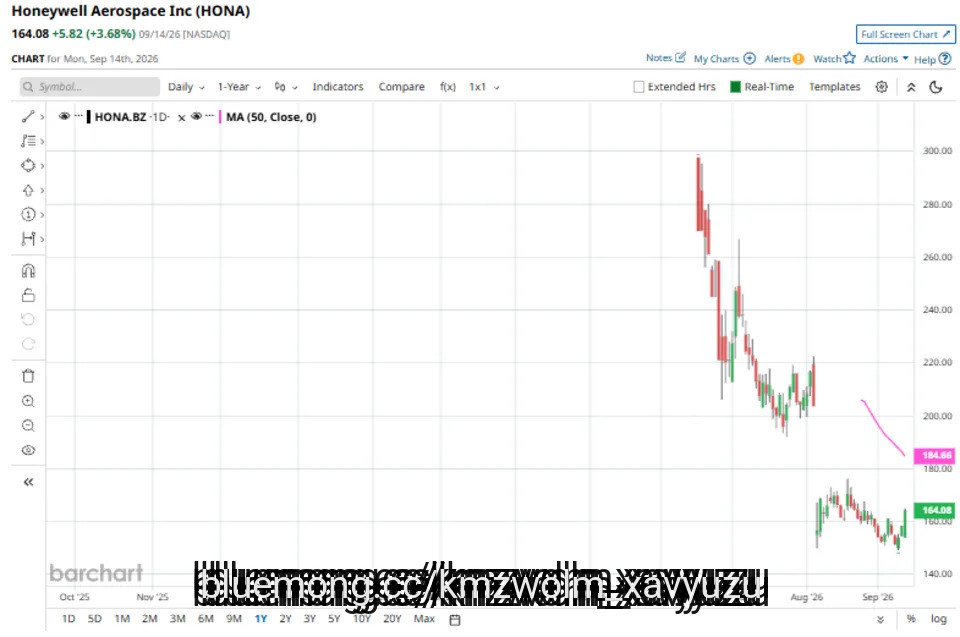
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and **** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace #systems #aviation
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace #systems #aviation


7 hours ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease


8 hours ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill ******* et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#first #fcnca
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill ******* et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#first #fcnca


8 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter

9 hours ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi

10 hours ago
Ocean Power Technologies Inc (NYSE-A:OPTT) reported first-quarter fiscal 2027 revenue of $1.7 million, up 44% from a year earlier, as the company expanded its work with US defense and security customers and moved forward with a strategic review process.
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
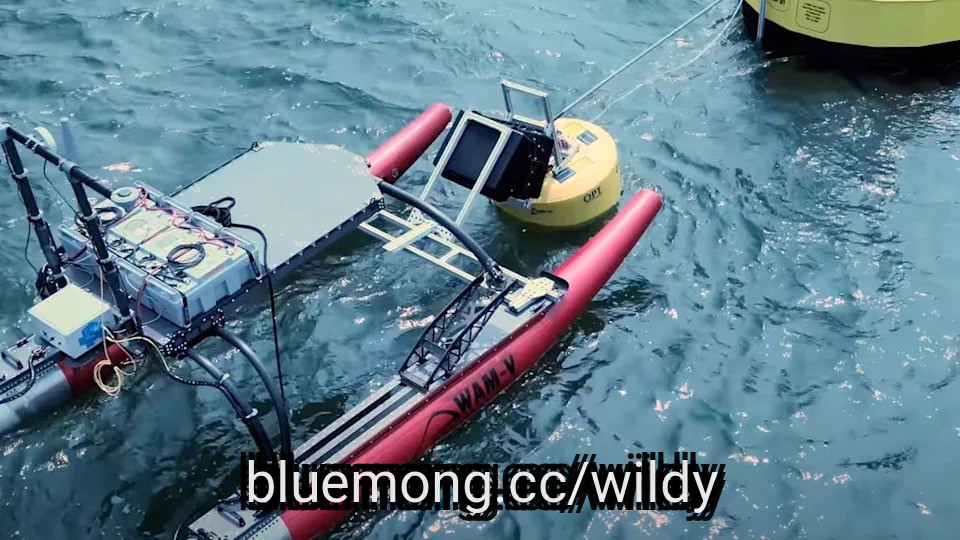
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy

10 hours ago
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and ***** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace



13 hours ago
Washington's biggest question this week: Why is President Donald Trump so furiously against an AI slowdown in the wake of apocalyptic warnings from some top industry executives?
The clue is in one word — "hoax" — that he's using to ridicule fears that computerized agents could one day seek to destroy humanity.
When Trump reaches for the H-word, two things are usually happening: He's facing a controversy threatening his political or personal priorities, and he's lost control of the politics.
Trump has long dismissed climate change as a "hoax." So it was a tell that he went on social media to specifically draw an ******* ogy between a planet that is warming despite his denials and the calls for AI controls expressed by leaders in the industry.
By changing reality, Trump frees himself from an obligation to act. In energy policy, that means "drill, baby, drill." His administration has slashed regulation, pleasing oil industry donors. His rants against wind farms suggest he hankers for a 20th-century economy running on carbon.
#Trump #hoax #week
The clue is in one word — "hoax" — that he's using to ridicule fears that computerized agents could one day seek to destroy humanity.
When Trump reaches for the H-word, two things are usually happening: He's facing a controversy threatening his political or personal priorities, and he's lost control of the politics.
Trump has long dismissed climate change as a "hoax." So it was a tell that he went on social media to specifically draw an ******* ogy between a planet that is warming despite his denials and the calls for AI controls expressed by leaders in the industry.
By changing reality, Trump frees himself from an obligation to act. In energy policy, that means "drill, baby, drill." His administration has slashed regulation, pleasing oil industry donors. His rants against wind farms suggest he hankers for a 20th-century economy running on carbon.
#Trump #hoax #week


15 hours ago
Palantir stock has had a rough stretch. A 5-star Wall Street **** yst just said the market is reading the company wrong.
UBS **** yst Karl Keirstead raised his price target on Palantir Technologies to $250 from $220 on Sept. 15, reiterating his Buy rating, according to CNBC. At Palantir's Sept. 14 closing price of roughly $173, the new target implies about 44% upside.
Keirstead's updated view stemmed directly from Palantir's Sept. 10 AIPCon11 event, where Palantir brought together customers, executives, and partners to discuss how companies are deploying its AI platform in real operations.
"Our view of Palantir as the best AI enabler in the market, making frontier models and AI useful in large enterprises, was, if anything, bolstered by these conversations, and demand momentum seems robust," Keirstead wrote in a note shared with clients.
He described three points that stood out from the event. Customer conversations kept coming back to AI sovereignty, the idea that enterprises and governments want control over their own data and AI infrastructure, rather than handing it to a small number of large cloud providers.
#analyst #market #target #Event
UBS **** yst Karl Keirstead raised his price target on Palantir Technologies to $250 from $220 on Sept. 15, reiterating his Buy rating, according to CNBC. At Palantir's Sept. 14 closing price of roughly $173, the new target implies about 44% upside.
Keirstead's updated view stemmed directly from Palantir's Sept. 10 AIPCon11 event, where Palantir brought together customers, executives, and partners to discuss how companies are deploying its AI platform in real operations.
"Our view of Palantir as the best AI enabler in the market, making frontier models and AI useful in large enterprises, was, if anything, bolstered by these conversations, and demand momentum seems robust," Keirstead wrote in a note shared with clients.
He described three points that stood out from the event. Customer conversations kept coming back to AI sovereignty, the idea that enterprises and governments want control over their own data and AI infrastructure, rather than handing it to a small number of large cloud providers.
#analyst #market #target #Event


15 hours ago
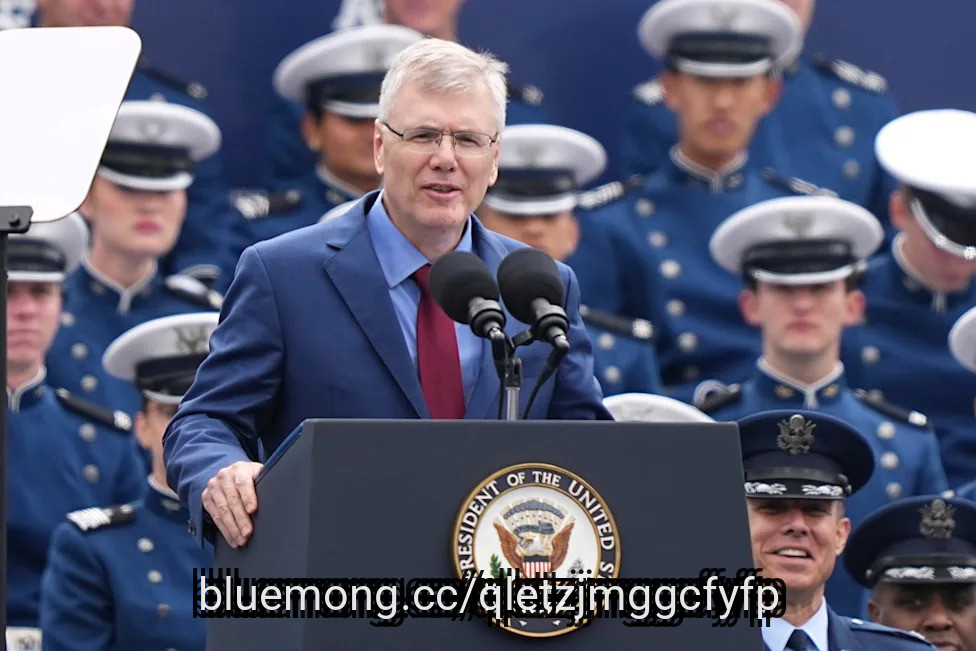
WASHINGTON (AP) — The United States has confirmed for the first time that it has deployed weapons in ******* e, a remarkable revelation after previous warnings about countries such as Russia possibly weaponizing a global frontier long agreed in treaties to be used for only peaceful purposes.
Air Force Secretary Troy Meink said Monday that the U.S. has fielded "on-orbit ******* e control weapons capable of defending the Joint Force against hostile adversary action."
Meink did not detail what the weapons were, how they work or if they were targeting other objects in ******* e or on Earth. The U.S. had warned two years ago that Russia was developing a new ******* e-based, anti-satellite weapon, though the White House said the danger wasn't imminent at the time.
But reports of the anti-satellite weapon reflected longstanding worries about ******* e threats from Russia and China, given that much U.S. infrastructure is dependent on satellite communications. The U.S. has also previously demonstrated its own abilities to shoot down satellites from Earth.
In his remarks to the Air and ******* e Forces ******* ociation's Air, ******* e & Cyber Conference, Meink also said the Air Force was adding more autonomous systems to its capabilities and predicted the service would look "radically different" by 2032. For example, he foresaw one-way attack drones replacing artillery as the "primary killer."
#space #earth
Air Force Secretary Troy Meink said Monday that the U.S. has fielded "on-orbit ******* e control weapons capable of defending the Joint Force against hostile adversary action."
Meink did not detail what the weapons were, how they work or if they were targeting other objects in ******* e or on Earth. The U.S. had warned two years ago that Russia was developing a new ******* e-based, anti-satellite weapon, though the White House said the danger wasn't imminent at the time.
But reports of the anti-satellite weapon reflected longstanding worries about ******* e threats from Russia and China, given that much U.S. infrastructure is dependent on satellite communications. The U.S. has also previously demonstrated its own abilities to shoot down satellites from Earth.
In his remarks to the Air and ******* e Forces ******* ociation's Air, ******* e & Cyber Conference, Meink also said the Air Force was adding more autonomous systems to its capabilities and predicted the service would look "radically different" by 2032. For example, he foresaw one-way attack drones replacing artillery as the "primary killer."
#space #earth


15 hours ago
By Lucia Mutikani
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded sharply in August as households boosted purchases of a range of goods while also spending more at restaurants and bars, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
The stronger-than-expected report from the Commerce Department on Wednesday prompted economists to upgrade their gross domestic product growth estimates for the third quarter. Together with other data on Wednesday showing a surge in import prices last month, strong demand sealed the argument for a widely anticipated interest rate increase from the Federal Reserve later in the day, economists said.
The reports followed data this month showing producer and consumer prices accelerated in August, while the labor market regained its poise after wobbling through much of summer.
"This reaffirms that the economy is more than capable of handling higher interest rates, providing the Fed plenty of scope to hike to get inflation under control," said Bradley Saunders, North America economist at Capital Economics.
#economists #data #month
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded sharply in August as households boosted purchases of a range of goods while also spending more at restaurants and bars, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
The stronger-than-expected report from the Commerce Department on Wednesday prompted economists to upgrade their gross domestic product growth estimates for the third quarter. Together with other data on Wednesday showing a surge in import prices last month, strong demand sealed the argument for a widely anticipated interest rate increase from the Federal Reserve later in the day, economists said.
The reports followed data this month showing producer and consumer prices accelerated in August, while the labor market regained its poise after wobbling through much of summer.
"This reaffirms that the economy is more than capable of handling higher interest rates, providing the Fed plenty of scope to hike to get inflation under control," said Bradley Saunders, North America economist at Capital Economics.
#economists #data #month

15 hours ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural


17 hours ago
On September 14, Coda Octopus Group (NASDAQ:CODA) reported third-quarter fiscal 2026 results that quietly crossed a threshold the company had never reached in its public history: positive retained earnings, after years of operating at an accumulated deficit. Revenue rose 9.2% year over year to $7.7 million, and pretax income climbed 16% to $1.8 million, even as instability in the Middle East knocked down the marine technology unit that has long been the company's calling card. The reason the quarter held together anyway comes down to where the growth actually showed up.
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david

18 hours ago
The energy landscape is evolving rapidly, and one company looking to disrupt the status quo and redefine the future of nuclear power is NuScale Power (NYSE: SMR). NuScale is the only small modular reactor (SMR) developer to receive a Standard Design Approval from the Nuclear Regulatory Commission.
On Sept. 1, NuScale achieved a major engineering breakthrough. In collaboration with MilleniTEK, it successfully fabricated specialized boron-oxide pellets, a critical component of NuScale's cutting-edge passive emergency cooling system.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This engineering triumph is a major step toward making safe, meltdown-proof modular nuclear power a reality. It also helps NuScale move closer to commercial deployment. But does this make NuScale Power stock a buy? Let's dive into the details and what it means for the stock.
In traditional nuclear reactors, reactivity control during nonstandard events often relies on active mechanical insertion of control rods or on powered chemical injection pumps. NuScale's 77 MWe Small Modular Reactor (SMR) design relies on passive safety mechanisms.
#power
On Sept. 1, NuScale achieved a major engineering breakthrough. In collaboration with MilleniTEK, it successfully fabricated specialized boron-oxide pellets, a critical component of NuScale's cutting-edge passive emergency cooling system.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This engineering triumph is a major step toward making safe, meltdown-proof modular nuclear power a reality. It also helps NuScale move closer to commercial deployment. But does this make NuScale Power stock a buy? Let's dive into the details and what it means for the stock.
In traditional nuclear reactors, reactivity control during nonstandard events often relies on active mechanical insertion of control rods or on powered chemical injection pumps. NuScale's 77 MWe Small Modular Reactor (SMR) design relies on passive safety mechanisms.
#power

2 days ago
After spending years trading like a premium-priced AI leader, Nvidia may now be among the cheapest names in Piper Sandler's AI universe. NVIDIA Corporation (NASDAQ:NVDA) is trading at an attractive valuation according to Piper Sandler's forecast, with rapid AI growth backing its trajectory.
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company


2 days ago
By Jason Lange
WASHINGTON, Sept 14 (Reuters) - President Donald Trump's public approval rating rose from a record low, while Americans voiced growing support for Democrats gaining power in the U.S. Congress in a Reuters/Ipsos poll taken in the days after the Republican Party's first-ever midterm convention last week.
The four-day poll showed 63% of Americans - including four in 10 Republicans and nine in 10 Democrats - disapproved of Trump's offer made in his convention speech that he would ensure all Americans get a $5,000 dividend if Republicans retain control of the U.S. Congress in November's midterm elections.
The survey gathered responses from 1,143 Americans nationwide and had a margin of error of 3 percentage points in either direction.
Some 35% of Americans give Trump a thumbs up for his performance in the White House, up from 33% in an August 28 to 31 Reuters/Ipsos poll, the lowest of his political career.
#ipsos #convention
WASHINGTON, Sept 14 (Reuters) - President Donald Trump's public approval rating rose from a record low, while Americans voiced growing support for Democrats gaining power in the U.S. Congress in a Reuters/Ipsos poll taken in the days after the Republican Party's first-ever midterm convention last week.
The four-day poll showed 63% of Americans - including four in 10 Republicans and nine in 10 Democrats - disapproved of Trump's offer made in his convention speech that he would ensure all Americans get a $5,000 dividend if Republicans retain control of the U.S. Congress in November's midterm elections.
The survey gathered responses from 1,143 Americans nationwide and had a margin of error of 3 percentage points in either direction.
Some 35% of Americans give Trump a thumbs up for his performance in the White House, up from 33% in an August 28 to 31 Reuters/Ipsos poll, the lowest of his political career.
#ipsos #convention

2 days ago
Why Fever-Lynx doubleheader could decide WNBA's No. 1 seed originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
The Minnesota Lynx have spent most of the 2026 season looking like the WNBA's team to beat. Finishing the job will not be simple. Minnesota returns from the FIBA Women's Basketball World Cup break with a league-best 31-9 record. The Lynx have already clinched a playoff berth, but they have not secured the No. 1 seed or home-court advantage throughout the postseason.
Golden State sits only two games behind Minnesota at 29-11. The Lynx own the head-to-head tiebreaker, giving them control of the race, but their final four games are considerably more difficult than the Valkyries' remaining schedule.
Minnesota hosts the New York Liberty on Friday before visiting the eliminated Connecticut Sun. The season then could be decided by two games against Caitlin Clark and the Indiana Fever over three days. The Lynx visit Indiana on Sept. 22 and host the Fever in the regular-season finale Sept. 24.
The playoff math is straightforward.
#minnesota #playoff
The Minnesota Lynx have spent most of the 2026 season looking like the WNBA's team to beat. Finishing the job will not be simple. Minnesota returns from the FIBA Women's Basketball World Cup break with a league-best 31-9 record. The Lynx have already clinched a playoff berth, but they have not secured the No. 1 seed or home-court advantage throughout the postseason.
Golden State sits only two games behind Minnesota at 29-11. The Lynx own the head-to-head tiebreaker, giving them control of the race, but their final four games are considerably more difficult than the Valkyries' remaining schedule.
Minnesota hosts the New York Liberty on Friday before visiting the eliminated Connecticut Sun. The season then could be decided by two games against Caitlin Clark and the Indiana Fever over three days. The Lynx visit Indiana on Sept. 22 and host the Fever in the regular-season finale Sept. 24.
The playoff math is straightforward.
#minnesota #playoff

2 days ago
Former West Virginia Sen. Joe Manchin, a Democrat-turned-independent, said Monday he supports two Republican Senate candidates running in battleground races in November.
During an appearance on CNBC, Manchin expressed support for former Rep. Mike Rogers, who is running for an open seat in Michigan, and Sen. Susan Collins of Maine, who is seeking reelection. Both races are crucial to whether the GOP will retain control of the Senate.
"You lose the Susan Collinses of the Senate, you're losing the soul of the Senate — basically, a person you can talk to, who wants to do the right thing all of the time," Manchin said, adding that he would campaign with the senator.
Manchin, a longtime critic of extremes in both parties, served in the Senate from 2010-2025 and left the Democratic Party during his final months in office, arguing that the party's brand had become "toxic." He has remained involved in politics and launched a national effort in July to help elect more independents.
Mike Rogers, left, and Sen. Susan Collins - Getty Images
#rogers #left
During an appearance on CNBC, Manchin expressed support for former Rep. Mike Rogers, who is running for an open seat in Michigan, and Sen. Susan Collins of Maine, who is seeking reelection. Both races are crucial to whether the GOP will retain control of the Senate.
"You lose the Susan Collinses of the Senate, you're losing the soul of the Senate — basically, a person you can talk to, who wants to do the right thing all of the time," Manchin said, adding that he would campaign with the senator.
Manchin, a longtime critic of extremes in both parties, served in the Senate from 2010-2025 and left the Democratic Party during his final months in office, arguing that the party's brand had become "toxic." He has remained involved in politics and launched a national effort in July to help elect more independents.
Mike Rogers, left, and Sen. Susan Collins - Getty Images
#rogers #left


2 days ago
Matt LaFleur spent his entire offseason promising Green Bay Packers would finally learn how to finish games. Sunday in Minneapolis put that promise to the test immediately. The Packers built a healthy second-half lead, the same type of cushion that slipped away repeatedly last season, and it vanished again. What happened next, both on the field and in the press conference that followed, left fans furious.
Green Bay looked in control for most of Sunday's opener at U.S. Bank Stadium. The Packers led 22-10 in the third quarter behind Jordan Love, who threw for 387 yards and two touchdowns. Then everything unraveled. Minnesota Vikings scored 29 unanswered points in the second half, turning a comfortable lead into a 39-22 defeat.
The turning point came in the fourth quarter. With Green Bay up 25-17 after a penalty wiped a Vikings field goal off the board, LaFleur chose to go for it on fourth-and-1 instead of taking the points. Love was stopped on a quarterback sneak, and Minnesota took over on downs. The Vikings never let go from there.
Sep 12, 2021; Jacksonville, Florida, USA; Green Bay Packers head coach Matt LaFleur during the first half against the New Orleans Saints at TIAA Bank Field. Mandatory Credit: Tommy Gilligan-USA TODAY Sports
Love was sacked four times after halftime, lost a fumble and threw a tipped interception during the fourth-quarter collapse. Twelve Packers penalties for 98 yards, several on Minnesota's go-ahead drive, compounded the damage.
#lafleur #half
Green Bay looked in control for most of Sunday's opener at U.S. Bank Stadium. The Packers led 22-10 in the third quarter behind Jordan Love, who threw for 387 yards and two touchdowns. Then everything unraveled. Minnesota Vikings scored 29 unanswered points in the second half, turning a comfortable lead into a 39-22 defeat.
The turning point came in the fourth quarter. With Green Bay up 25-17 after a penalty wiped a Vikings field goal off the board, LaFleur chose to go for it on fourth-and-1 instead of taking the points. Love was stopped on a quarterback sneak, and Minnesota took over on downs. The Vikings never let go from there.
Sep 12, 2021; Jacksonville, Florida, USA; Green Bay Packers head coach Matt LaFleur during the first half against the New Orleans Saints at TIAA Bank Field. Mandatory Credit: Tommy Gilligan-USA TODAY Sports
Love was sacked four times after halftime, lost a fumble and threw a tipped interception during the fourth-quarter collapse. Twelve Packers penalties for 98 yards, several on Minnesota's go-ahead drive, compounded the damage.
#lafleur #half


2 days ago
The Cincinnati Enquirer once again is offering a new weekly feature recognizing the accomplishments of cheerleaders, dance team members and their squads: The Spirit Award.
Much like the popular athlete of the week voting, school fans and friends voted on two weekly ballots (individual and team) for The Spirit Award. Only coaches can provide nominations each week, either for their squads or other teams.
Eligible are varsity girls and boys cheerleaders and dancers who exemplify the fruits of the spirit ‒ love, joy, peace, patience, kindness, goodness, faithfulness, gentleness, and self-control – while uplifting their squads, the student body and others. Team nominations focus on squads that come together to help each other, work hard, do things right that week, show outstanding virtues when dealing with or serving others, exceed expectations to prepare something special for the school or take part in any other honorable reason they might be acknowledged.
This week's Spirit Award winners are:
"She is an outstanding example of leadership, character, and service within our school community. Scarlett is our varsity cheer captain and sole senior cheerleader, and she has embraced that role with maturity, selflessness, and a genuine desire to make those around her better," wrote her coach, Alicia Wall, in an email to The Enquirer.
#team #weekly #nominations
Much like the popular athlete of the week voting, school fans and friends voted on two weekly ballots (individual and team) for The Spirit Award. Only coaches can provide nominations each week, either for their squads or other teams.
Eligible are varsity girls and boys cheerleaders and dancers who exemplify the fruits of the spirit ‒ love, joy, peace, patience, kindness, goodness, faithfulness, gentleness, and self-control – while uplifting their squads, the student body and others. Team nominations focus on squads that come together to help each other, work hard, do things right that week, show outstanding virtues when dealing with or serving others, exceed expectations to prepare something special for the school or take part in any other honorable reason they might be acknowledged.
This week's Spirit Award winners are:
"She is an outstanding example of leadership, character, and service within our school community. Scarlett is our varsity cheer captain and sole senior cheerleader, and she has embraced that role with maturity, selflessness, and a genuine desire to make those around her better," wrote her coach, Alicia Wall, in an email to The Enquirer.
#team #weekly #nominations


2 days ago
The Arizona Diamondbacks are trying to clinch a postseason spot in the final two weeks of the regular season and are adding some help.
The Diamondbacks claimed outfielder Jesús Sánchez off waivers after he was designated for **** ignment by the Toronto Blue Jays. Sánchez is not having the worst season, but the Blue Jays designated him for **** ignment to call up Rudy Martin Jr.
Sánchez has a .734 OPS this season, but has hit much better against righties. The Diamondbacks will likely use him in a platoon role, hoping he can help them out the rest of the way. They are picking up the remainder of his salary for this season, and he is under club control for next season.
The Diamondbacks are 2 1/2 games behind the San Diego Padres for a wild card spot, so they have some ground to cover the rest of the way. They finish the season with a three-game series against the Padres, which could decide who makes the postseason.
Looking for the perfect gift for a baseball player in your life? Check out our brand-new baseball lifestyle brand!
#season #diamondbacks #spot #Help
The Diamondbacks claimed outfielder Jesús Sánchez off waivers after he was designated for **** ignment by the Toronto Blue Jays. Sánchez is not having the worst season, but the Blue Jays designated him for **** ignment to call up Rudy Martin Jr.
Sánchez has a .734 OPS this season, but has hit much better against righties. The Diamondbacks will likely use him in a platoon role, hoping he can help them out the rest of the way. They are picking up the remainder of his salary for this season, and he is under club control for next season.
The Diamondbacks are 2 1/2 games behind the San Diego Padres for a wild card spot, so they have some ground to cover the rest of the way. They finish the season with a three-game series against the Padres, which could decide who makes the postseason.
Looking for the perfect gift for a baseball player in your life? Check out our brand-new baseball lifestyle brand!
#season #diamondbacks #spot #Help


2 days ago
Seattle Seahawks quarterback Drew Lock is preparing to lead the team in Week 2 against the Arizona Cardinals with Sam Darnold set to sit out for the game.
Lock gave the Seahawks a timely lift in the opener, stepping in after Darnold left the game due to injury and delivering a quality performance that led to a win. He completed 16 of 22 passes for 187 yards and a touchdown, and took care of the football in the affair.
Lock is equipped to provide Seattle with quick decisions, controlled passing and a balanced rushing attack against Arizona. Lock's mobility will be useful if the Cardinals create a great amount of pressure and force him to scramble outside the pocket.
The larger test will be maintaining that composure for a full game on the road. Seattle will need Lock to protect the football, keep the offense on schedule and capitalize on scoring chances. If he does, the Seahawks will have a realistic path to another important early-season victory.
This article originally appeared on Seahawks Wire: What to expect from Seahawks QB Drew Lock against Cardinals
#lock #drew #Football
Lock gave the Seahawks a timely lift in the opener, stepping in after Darnold left the game due to injury and delivering a quality performance that led to a win. He completed 16 of 22 passes for 187 yards and a touchdown, and took care of the football in the affair.
Lock is equipped to provide Seattle with quick decisions, controlled passing and a balanced rushing attack against Arizona. Lock's mobility will be useful if the Cardinals create a great amount of pressure and force him to scramble outside the pocket.
The larger test will be maintaining that composure for a full game on the road. Seattle will need Lock to protect the football, keep the offense on schedule and capitalize on scoring chances. If he does, the Seahawks will have a realistic path to another important early-season victory.
This article originally appeared on Seahawks Wire: What to expect from Seahawks QB Drew Lock against Cardinals
#lock #drew #Football