

2 months ago
Medtronic (NYSE: MDT), one of the world's largest medical device makers, was once considered a stable blue chip stock. But over the past five years, it has declined by more than 30% due to supply chain constraints, higher costs, quality control issues, and competitive pressure. However, Medtronic's stock is worth buying again for four simple reasons.
In fiscal 2026 (which ended this April), Medtronic's revenue grew 8.4% (and 5.8% organically) to $36.4 billion, marking its strongest top-line growth in ten years.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That acceleration was driven by 9.3% organic growth in its cardiovascular business, which accounted for more than 38% of its enterprise revenue. All of its other segments (neuroscience, medical surgical, and diabetes) also grew organically.
Medtronic expects its organic revenue to rise 7.25%-7.75% in fiscal 2027, representing another multi-year high and easily exceeding its historical average of around 5%. Once again, that growth will be led by its rising sales of cardiovascular devices. From fiscal 2026 to fiscal 2029, ****** ysts expect its reported revenue to grow at a 5% CAGR.
#fiscal #NVIDIA

2 months ago
In the world of robotic surgery, one company is both the undisputed leader and the most expensive option, forcing investors to ask if operational excellence is worth the premium.
Intuitive Surgical (ISRG), the pioneer of robotic-assisted surgery, trades around $370, a share after a tough year. The stock has delivered a -21% return over the last twelve months, badly trailing the S&P 500's +19.2% gain. Yet, within its peer group, it commands the highest valuation. Why does the market charge a top-tier price for the company with the group's worst-performing stock?
By the numbers, Intuitive Surgical's operational lead is real, even if Globus Medical sits close behind at 19.7%. The company's revenue grew 21% over the last twelve months, well ahead of diversified rivals like Medtronic, which grew at 8.4%.. Its 31% operating margin also leads the pack, again comfortably ahead of Medtronic's 18.8%. This is a business that executes at a higher level than its competition. The market sees this performance and charges accordingly. Intuitive Surgical trades at 42.5 times earnings, the highest multiple in its group. For comparison, Medtronic trades at a much lower 24.2 times earnings. The mismatch is stark: investors are paying a premium for leading fundamentals, but so far, that premium has not translated into positive returns.
ISRG
MDT
#robotic


2 months ago
With a market cap of $117.8 billion, Medtronic plc (MDT) is a leading global healthcare technology company focused on addressing complex health challenges through innovative medical solutions. With a global workforce serving patients across more than 150 countries, its technologies span cardiac devices, surgical robotics, insulin pumps, surgical tools, and patient monitoring systems.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#surgical #guided


2 months ago
With a market cap of $117.8 billion, Medtronic plc (MDT) is a leading global healthcare technology company focused on addressing complex health challenges through innovative medical solutions. With a global workforce serving patients across more than 150 countries, its technologies span cardiac devices, surgical robotics, insulin pumps, surgical tools, and patient monitoring systems.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ******* ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Health #surgical #Companies


2 months ago
Boston Scientific (NYSE:BSX), a global medical device maker, closed at $48.17, down 3.38%. Premarket reports said a cybersecurity incident disrupted global operations and shipping. The company also announced a product recall for certain types of its percutaneous catheters, further weighing on the stock. Investors are watching how quickly the company restores its systems and whether the recall exacerbates the interruption. Trading volume reached 31.8M shares, coming in about 48% above its three-month average of 21.4M shares.
S&P 500 (SNPINDEX:^GSPC) fell 0.04% to 7,675, and the Nasdaq Composite (NASDAQINDEX:^IXIC) slipped 0.08% to 26,130. Among medical devices and interventional medtech peers, Abbott Laboratories (NYSE:ABT) closed at $114.10, down 1.75%, while Medtronic (NYSE:MDT) finished at $92.01, up 0.95%, as Boston Scientific's cyber disruption stood out.
Boston Scientific has seen its stock drop 55% over the last year, and today's double dose of bad news didn't help things. The product recall is tied to the company's ENROUTE Transcarotid Neuroprotection System (NPS) following the FDA's concerns about the potential separation of the product's arterial sheath tip.
Making matters worse, the company also disclosed a cybersecurity incident that disrupted its global operations, potentially disrupting the processing and shipping of customers' orders. Management noted that it was working to restore lost functions but couldn't yet determine whether the event would have a material impact on BSX shares.
Following several quarters of weaker-than-expected earnings results, disappointing Watchman sales, slashed guidance, and a major acquisition now weighing on Boston Scientific's balance sheet, the stock has shifted from a steady compounder to more of a turnaround or value type of stock -- especially after today's news. While BSX stock is on my watch list, I'd need to see some type of positive developments before I consider buying.
#boston #NYSE #global #following


2 months ago
Turnarounds in the healthcare sector do not all look the same. Some companies recover because management executes better, launches stronger products, and improves operations, while others do so because the industries they serve begin improving after prolonged downturns.
Medtronic (NYSE:MDT) and Thermo Fisher Scientific (NYSE:TMO) are two of healthcare's most closely watched recovery stories, but they are being driven by very different forces. The question for investors is whether Medtronic's (NYSE:MDT) internally driven turnaround or Thermo Fisher's (NYSE:TMO) improving end markets offer the stronger long-term opportunity.
The latest results reinforce that Medtronic's (NYSE:MDT) turnaround is beginning to translate into measurable financial performance. The company reported its highest annual revenue growth in a decade, suggesting that years of investment in new technologies are beginning to gain traction.
Furthermore, Medtronic's (NYSE:MDT) cardiac segment is emerging as one of the most prominent growth drivers for the company, as the Cardiac Ablation Solutions revenue rose 78% globally, including 124% U.S. growth. Several of the company's newer product launches are beginning to contribute meaningfully to growth, helping strengthen its competitive position in several high-growth markets. It is also heavily investing in innovation and M&A, along with targeted investments in high-growth segments such as ICE catheter technology.
While Medtronic's (NYSE:MDT) recovery is being driven by internal execution and product innovation, Thermo Fisher's (NYSE:TMO) outlook increasingly depends on improving customer spending across the life sciences industry. What stood out most from Thermo Fisher's (NYSE:TMO) quarter was the breadth of the recovery across its life sciences businesses. Management highlighted improving customer activity across pharmaceutical and biotechnology markets, while multiple operating segments returned to healthy growth. That is an important distinction because broader participation across business segments suggests customer spending is becoming healthier rather than merely stabilizing in one niche.
#improving #driven


2 months ago
Healthcare investors are beginning to see signs of recovery across several parts of the industry, but not every recovery looks the same. Danaher (NYSE:DHR) is benefiting from improving demand in life sciences after a prolonged post-pandemic slowdown, while Medtronic (NYSE:MDT) is finally beginning to show the results of years of investment in new products and operational execution. Both companies reported encouraging results, but very different factors are driving their recoveries. The question for investors is which recovery story offers the greater long-term upside.
The strongest argument supporting Medtronic (NYSE:MDT) is that its turnaround is no longer being driven by cost controls alone. The company's latest results suggest its newer growth platforms are beginning to contribute meaningfully to revenue. The company reported its highest annual revenue growth in 10 years in its fiscal Q4 and full-year 2026 results. Q4 revenue reached $9.8 billion, up 9.9% as reported and 6.6% organic, and FY 26 revenue was $36.4 billion, with adjusted revenue of $36.3 billion, up 8.4% as reported and 5.8% organic. The trends suggest that the company is exhibiting continued operational rigor and building momentum in its highest growth opportunities, including Affera, Symplicity, Hugo, Altaviva, and Stealth AXiS.
Furthermore, Medtronic's (NYSE:MDT) cardiac segment is emerging as one of the most prominent growth drivers for the company, as the Cardiac Ablation Solutions revenue rose 78% globally, including 124% U.S. growth. That is significant for investors because cardiac devices remain one of the company's highest-margin and fastest-growing businesses.
Danaher's story, however, depends much more on improving customer spending across its Life Sciences business, which delivered its strongest performance in several years. Although bioprocessing revenue was affected by customer project timings, the underlying order trends remained strong, with bioprocessing orders growing mid-teens in the quarter. This shows that the underlying demand for bioprocessing remained strong, which includes consumables and equipment necessary to make biologic drugs.
Danaher Corporation (NYSE:DHR) also stated that a little over $100 million of revenue has shifted into next year, primarily from the second and third quarters. This suggests that customer demand has been delayed rather than cancelled, potentially supporting future revenue growth.
#revenue
2 months ago
Medtronic plc (NYSE:MDT) and Tenet Healthcare Corporation (NYSE:THC) offer investors two very different healthcare growth stories. Medtronic's (NYSE:MDT) thesis rests on whether a new generation of medical devices can produce a durable turnaround across its enormous portfolio. Tenet (NYSE:THC), meanwhile, is generating stronger earnings by improving hospital profitability and focusing its ambulatory business on higher-acuity procedures.
The comparison ultimately comes down to whether investors prefer Medtronic's (NYSE:MDT) innovation-led recovery or Tenet's (NYSE:THC) stronger operating leverage.
Medtronic (NYSE:MDT) reported its highest annual revenue growth in a decade in its fiscal Q4 and full-year 2026 results, suggesting that years of investment in faster-growing technologies are beginning to produce meaningful results. Growth opportunities including Affera, Symplicity, Hugo, Altaviva, and Stealth AXiS give the company several potential drivers rather than leaving its recovery dependent on a single product.
Cardiac Ablation Solutions has emerged as a particularly important contributor. Revenue increased 78% globally, including 124% growth in the United States, as newer products strengthened Medtronic's (NYSE:MDT) position in the expanding cardiac-ablation market. The company is also investing in innovation and acquisitions, including targeted investments in intracardiac echocardiography catheter technology.
The breadth of Medtronic's (NYSE:MDT) pipeline supports the possibility that its recent acceleration can spread across more of the portfolio. Improving sentiment toward the wider medical-technology sector could provide an additional catalyst if the company maintains its execution. BTIG has argued that MedTech may be stabilizing following a period of underperformance, although company-specific results will ultimately matter more than broader sector sentiment.
#results #medtronic #healthcare

3 months ago
Intuitive Surgical (NASDAQ: ISRG) can be hard to own because the stock is ***** e to deep drawdowns. It is in a drawdown right now, with the stock down roughly 40% from its early 2025 high. Even after that drop, the price-to-earnings ratio remains lofty at 42x. This is not a stock for the faint of heart.
However, if you are a growth-oriented investor, you shouldn't give up on Intuitive Surgical. Historically, the stock has recovered from deep drawdowns and gone on to reach higher highs. There's a difference this time around due to increasing competition from medical device peers such as Medtronic (NYSE: MDT) and Johnson & Johnson (NYSE: JNJ). But that probably shouldn't stop more aggressive investors. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Intuitive Surgical was an early leader in the surgical robotics ***** e. The company's da Vinci system basically helped create the industry niche. So, early on, the question was about medical providers being willing to adopt a new technology. Surgical robotics is now a far more mature and well-accepted technology, generally enabling less invasive surgeries with better outcomes.
In late 2025, Medtronic received approval for its Hugo surgical robotic system in the United States. In mid-2026, J&J received approval for its OTTAVA surgical robot system. Both Medtronic and J&J are well-established competitors with strong industry connections. There is no doubt that they will be fierce competitors to Intuitive Surgical.
#surgical #Stock


3 months ago
Shares of Medtronic (NYSE: MDT), one of the world's largest medical device makers, have declined by more than 30% over the past five years. Higher costs, supply chain bottlenecks, quality control issues, and competitive pressure in surgical robotics all weighed on its stock.
Yet Wall Street remains bullish on Medtronic, with an average price target of $98.44 and a top target of $121. I believe it could rise more than 40% from its current price of $86 and hit that high-end target by the end of this year for a few simple reasons.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Back in March, Medtronic spun off its diabetes unit as MiniMed (NASDAQ: MMED) to streamline its business. It's also restructuring its business to expand its higher-margin cardiovascular and neuroscience portfolios and to integrate more AI features into its surgical planning products.
In fiscal 2026 (which ended in April), Medtronic's revenue grew 8.4% to $36.4 billion (or 5.8% organically) and marked its strongest top-line growth in ten years. From fiscal 2026 to fiscal 2029, **** ysts expect its revenue and EPS to grow at CAGRs of 5% and 13%, respectively.
#NVIDIA #years #surgical


3 months ago
Prioritizing cash flow and stability can be crucial for investors who are in their retirement years. As investors age, it becomes more important to preserve capital rather than risk it in growth stocks that may or may not achieve their lofty ambitions.
Three stocks that retirees may want to consider for their portfolios today include Verizon Communications (NYSE: VZ), Medtronic (NYSE: MDT), and Duke Energy (NYSE: DUK). These dividend stocks can add diversification, generate a ton of dividend income over the years, and be fairly safe investments to hang on to, even amid market instability.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Cash flow is what retirees can expect from Verizon Communications stock. They can generate a boatload of it from the stock's lavish dividend, which yields close to 6.1%. It's a payout that almost seems too good to be true for a top telecom stock. The stock has risen 14% this year and has begun to rally after a pullback that spanned multiple years. Rising interest rates have weighed on many telecom stocks, even though their underlying businesses remain sound. Verizon is a prime example of that.
The business pays its shareholders a ton of cash and also generates plenty of it. In the trailing 12 months, Verizon's free cash flow has totaled more than $20 billion, easily enough to cover the roughly $12 billion it paid in dividends during that period. That also puts it in an excellent position to raise its cash dividend payments in the future.
#cash


3 months ago
Galway, Ireland-based Medtronic plc (MDT) develops, manufactures, and sells device-based medical therapies to healthcare systems, physicians, clinicians, and patients. Valued at $109.3 billion by market cap, the company's principal products include those for bradycardia pacing, tachyarrhythmia management, atrial fibrillation management, heart failure management, heart valve replacement, malignant and non-malignant pain, and movement disorders.
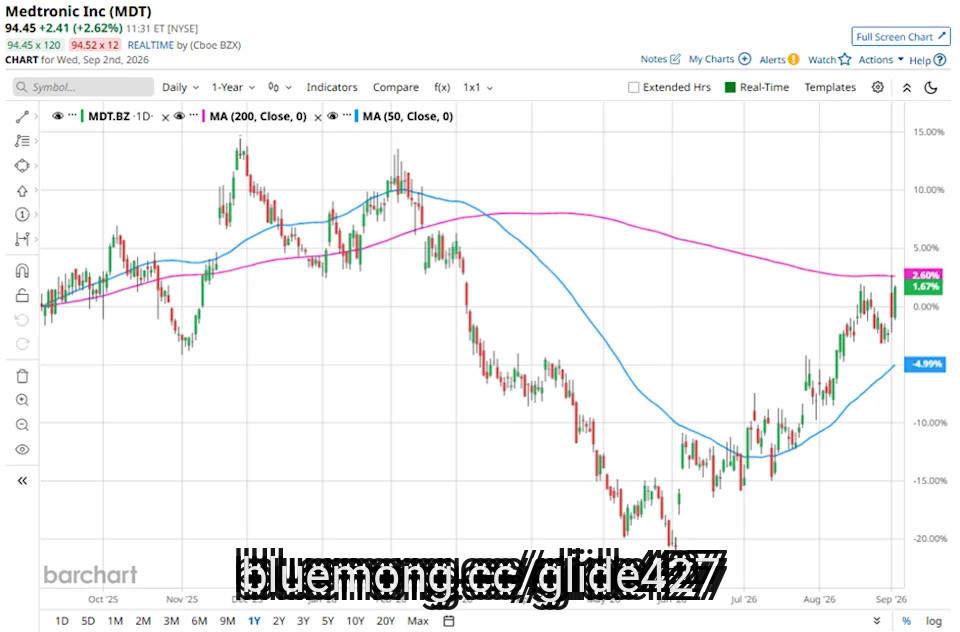
Shares of this medical devices giant have underperformed the broader market over the past year. MDT has declined 3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 21.8%. In 2026, MDT stock is down 9.8%, compared to the SPX's 11% rise on a YTD basis.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 ****** anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#management #market #heart #galway



3 months ago
Intuitive Surgical (ISRG) stock tumbled Tuesday, alongside shares of other medtech leaders like Abbott Laboratories (ABT), Stryker (SYK) and Medtronic (MDT), after HCA Healthcare trimmed its full-year earnings outlook, suggesting a drop in surgical procedures.
HCA Healthcare, the largest for-profit hospital operator, said inpatient surgeries declined 2.3% while outpatient procedures fell 3.4% in the second quarter compared with the year-ago period.
As a result, HCA now projects $6.3 billion to $6.7 billion in net income and adjusted earnings before interest, taxes, depreciation and amortization, or EBITDA, of $15.4 billion to $16.1 billion. That's down from the prior outlook for roughly $6.5 billion to $7.04 billion in net income and adjusted EBITDA of $15.55 billion to $16.45 billion.
HCA also narrowed its sales guidance, now projecting $77 billion to $79.5 billion. The midpoint of the new outlook, $78.25 billion, matches the company's prior view.

4 months ago
Amid the largest IPO in history, which we recently witnessed, and the booming artificial intelligence industry that continues to show highly attractive prospects, there remain serious economic and geopolitical tensions that could eventually significantly cool much of the excitement on Wall Street. Inflation is on the rise, some economists continue to warn that a recession may be coming, and although the United States and Iran seem to be working toward a deal, it remains hard to predict how that situation will evolve.
In the current environment, it is a good idea to consider investing in dividend stocks. They may not be particularly "exciting" choices right now, but solid dividend payers can help stabilize a portfolio in case the going gets rough and smooth out market losses in a downturn. With that said, let's consider two excellent dividend stocks that are worth investing in right now: Pfizer (NYSE: PFE) and Medtronic (NYSE: MDT). Both healthcare leaders could deliver competitive returns through the next decade.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Pfizer has not performed well in recent years due to poor financial results and upcoming patent cliffs, notably for its anticoagulant Eliquis, one of its best-selling drugs. It will lose patent exclusivity by the end of the decade. However, the company is developing new products that could help it overcome these challenges. Pfizer has significantly expanded its pipeline in recent years, partly thanks to acquisitions, and now boasts a deep portfolio of investigational medicines.
The most promising might be in oncology and weight loss. In the latter therapeutic area, Pfizer is developing an anti-obesity medicine, MET-097i, which it hopes will be highly differentiated from current market leaders, thanks to its better safety profile and long-acting properties.


4 months ago
Renaissance Investment Management, an investment management company, released its Q1 2026 "Large Cap Growth Strategy." A copy of the letter can be downloaded here. Stocks fell sharply in the first quarter due to the Iran conflict. The Energy and Materials sectors outperformed, Financials and Consumer Discretionary lagged. Large-cap stocks underperformed smaller-cap stocks, and Value outperformed Growth. The portfolio outperformed the S&P 500's -4.3% return but lagged the Russell 1000 Growth Index, which fell 9.8%. In this uncertain environment, the firm remains aware of the risks and emerging investment opportunities. In addition, you can check the Strategy's top 5 holdings for its best picks for 2026.
In its first-quarter 2026 investor letter, Renaissance Investment Large Cap Growth Strategy highlighted Boston Scientific Corporation (NYSE:BSX). Boston Scientific Corporation (NYSE:BSX) is a medical technology company that manufactures and markets medical devices for use in various interventional medical specialties. On June 16, 2026, Boston Scientific Corporation (NYSE:BSX) closed at $46.92 per share. One-month return of Boston Scientific Corporation (NYSE:BSX) was -17.20%, and its shares lost 53.71% over the past 52 weeks. Boston Scientific Corporation (NYSE:BSX) has a market capitalization of $69.74 billion.
Renaissance Investment Large Cap Growth Strategy stated the following regarding Boston Scientific Corporation (NYSE:BSX) in its Q1 2026 investor letter:
"Boston Scientific Corporation (NYSE:BSX) dropped despite reporting solid operating results. The stock declined after initial 2026 guidance came in below expectations, driven by revenue growth deceleration in its electrophysiology segment. This segment has contributed substantially to revenue growth in the past, and the deceleration suggests that the company's main competitor, Medtronic, may be gaining market share."
Boston Scientific Corporation (NYSE:BSX) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 110 hedge fund portfolios held Boston Scientific Corporation (NYSE:BSX) at the end of the fourth quarter, up from 102 in the previous quarter. In the first quarter of 2026, Boston Scientific Corporation (NYSE:BSX) delivered consolidated revenue of $5.203 billion, representing 11.6% year-over-year growth compared to Q1 2025. While we acknowledge the potential of Boston Scientific Corporation (NYSE:BSX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


5 months ago
Investing in healthcare hasn't been all that exciting an option for investors in recent years. But over the long term, it can lead to significant returns. Healthcare is not only essential but a growing part of the economy. Companies that are key to the sector's long-term growth can make for excellent investments.
The stock that may be the best one to buy in healthcare today is Medtronic (NYSE: MDT). The medical device maker's business has been taking off. And when you combine its financials and long-term growth opportunities with its valuation and dividend income, it may be the ultimate healthcare stock to own right now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Last week, Medtronic posted its year-end numbers for fiscal 2026 (which ended April 24). The results were impressive, with the healthcare company boasting of the highest growth rate it achieved in 10 years. While sales didn't double or triple, they rose by 8.4% for the full year. That's high for a business that in recent years has struggled to grow its top line. Management credits the results to "disciplined execution across our portfolio and continued operational rigor." Meanwhile, it still expects to generate more growth in the long run, particularly as it makes more investments in its pipeline.
The company's products and therapies help treat 70 different health conditions. And with a presence in over 150 countries, this is a vast and diversified business to invest in, giving you exposure to opportunities in healthcare that expand beyond just the U.S. market.



