

21 days ago
$100,000 split across MO and ET alone generates roughly $2,548 annually, backed by 60 and 19 consecutive dividend raises respectively.
Verizon's CFO called its 6.1% dividend "ironclad" after free cash flow surged 27% to $6.43 billion in Q2.
Exxon anchors the basket with 43 straight years of dividend growth and a fortress balance sheet carrying just 0.55x net debt-to-EBITDA.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Exxon Mobil didn't make the cut. Enter your email to see the names that beat XOM. The report is free. Enter your email and see if any of your stocks made the cut.
Split $100,000 equally across five blue-chip dividend payers in tobacco, pipelines, telecom, net-lease real estate and integrated oil, and today's yields produce roughly $5,436 in annual income. That works out to about $20,000 per name. Dividend safety depends on more than yield. These companies back their payouts with long records of raises, real cash generation and a balance sheet that can handle a rough patch. That combination is what turns a one-time investment into a durable income stream.
#across #free #cash #balance
1 month ago
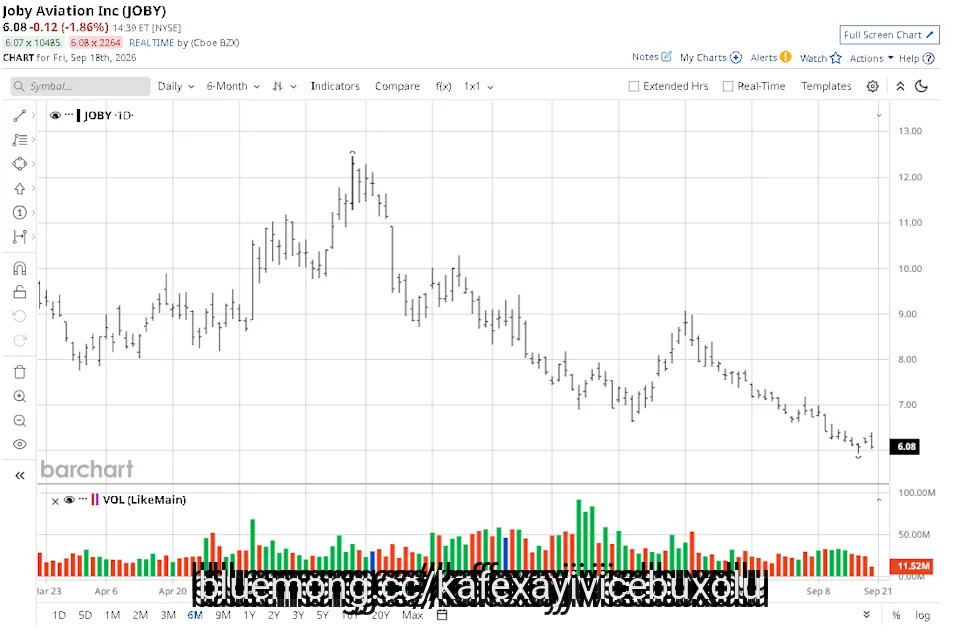
Joby Aviation (JOBY) remains firmly in the spotlight on Sept. 18 after the eVTOL specialist announced a major technological milestone. In its press release, the company said a modified Cessna Caravan equipped with its autonomy suite completed a 3,199-mile flight across the U.S. without control inputs from an onboard safety pilot.
Note that JOBY shares have been in a sharp downtrend in 2026, currently trading at less than half their price at the start of this year.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#joby #America #declared #generational


1 month ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
1 month ago
The Children's Place, Inc. (NASDAQ:PLCE) reported on September 14 that fiscal second-quarter net sales declined 18.9% year over year to $241.8 million. Reported gross margin rose to 34.4% from 34.0% a year earlier for the quarter ended August 1, 2026.
The apparent margin improvement depended heavily on $39 million of tariff refunds recognized as a reduction of cost of sales. That benefit was equivalent to nearly 47% of reported gross profit of $83.3 million.
Management said gross margin excluding the refunds declined 1,550 basis points, or 15.5 percentage points, year over year. This non-GAAP comparison removes the cost-of-sales benefit. The central question is whether inventory cleanup can establish a healthier operating base.
The Children's Place, Inc. (NASDAQ:PLCE) reduced inventory to $340.2 million, down 23.2% from $442.7 million a year earlier. A smaller inventory position allows management to improve the merchandise mix and reduce future exposure to aging products.
Clearing excess stock can release working capital and create room for products better aligned with demand. The eventual benefit depends on rebuilding sales with less discounting, but reducing the stock burden is a useful starting point.
#reported #Margin
1 month ago
Dow Jones futures rose modestly early Wednesday, along with S&P 500 futures and Nasdaq futures. The Federal Reserve is expected to raise interest rates amid soaring oil prices and Treasury yields.
The stock market saw further losses Tuesday with the Nasdaq and S&P 500 dropping below their 50-day moving averages. The 10-year Treasury yield is at 5% while crude oil prices jumped amid global conflicts.
Salesforce (CRM) fell slightly amid its annual Dreamforce conference but is still near entries. ServiceNow (NOW) rose within a buy zone while Twilio (TWLO) and Dynatrace (DT) reclaimed buy points. Cybersecurity plays Qualys (QLYS), Fortinet (FTNT) and Palo Alto Networks (PANW) flashed buy signals.
Outside of software, Energy play APA Corp. (APA) and Guardant Health (GH) are actionable.
Guardant Health and Twilio are on Leaderboard. Twilio stock, Salesforce and Guardant are on SwingTrader. Salesforce stock is on the IBD 50. Fortinet stock, Salesforce and Dynatrace are on the IBD Big Cap 20.
#Stock #futures

1 month ago
The 10-year U.S. Treasury yield ($TNX) surged to 5.041% earlier today, marking its highest level since July 2007 and representing an 86-basis-point climb since the start of 2026. This 19-year high in benchmark borrowing costs has arrived at a critical juncture, with the Federal Reserve commencing its two-day policy meeting Tuesday and a rate decision expected Wednesday afternoon.
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#since #rate

2 months ago
Is it better to own a company already selling drugs or one with a potential blockbuster in testing? Investors are weighing Axsome Therapeutics (NASDAQ:AXSM) against Viking Therapeutics (NASDAQ:VKTX) to decide.
Axsome focuses on commercializing treatments for depression and sleep disorders, showing significant revenue growth. Viking is a clinical-stage developer targeting the massive obesity market but has no products on the market yet. Both represent different stages of growth within the biotech world, making them popular choices for healthcare-minded portfolios.
Axsome develops and sells treatments for central nervous system conditions such as depression, migraines, and narcolepsy. It is a prominent name among biotech stocks, with a portfolio that includes Auvelity, Sunosi, and Symbravo. The company recently entered a settlement that grants license rights to five generic manufacturers for Sunosi starting in 2040, providing long-term clarity on its patent life and market position. In its latest annual report, filed in early 2026, the company noted it had over 900 full-time employees to support its commercial reach.
In FY 2025, revenue reached nearly $638.5 million, marking growth of close to 65.5% compared to the prior year. This increase was driven by the continued expansion of its key central nervous system treatments into new geographic markets. The company reported a net loss of approximately $183.2 million, resulting in a negative net margin, which is the percentage of revenue left after all expenses are paid, of roughly 28.7%. Some investors focus on the P/S ratio to value the business relative to this growing revenue.
As of December 2025, the debt-to-equity ratio was nearly 2.7x, meaning the company uses significant debt relative to its equity. The current ratio of approximately 1.6x indicates it has $1.60 in ****** ets for every $1.00 in liabilities due within a year. Free cash flow, or cash from operations minus capital spending, was nearly negative $93.9 million as the company continues to invest in its commercial pipeline. This spending is intended to support the long-term growth of its approved products and the development of new candidates.
#ratio #therapeutics
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
RTX Corporation (NYSE:RTX) is increasingly benefiting from surging demand for missiles, air-defense systems, and other military equipment as geopolitical tensions rise and governments expand defense spending. The stock is already up about 9% year-to-date, as investors increasingly price in the company's growing defense backlog and stronger long-term demand.
On September 1, the U.S. Department of War awarded RTX Corporation (NYSE:RTX)'s Raytheon business a $42.48 million cost-plus-fixed-fee contract for technical and engineering services supporting Navy air-traffic systems. The work includes engineering and restoration services for air-traffic navigation and coordination systems.
While relatively small compared with Raytheon's larger weapons contracts, the award comes amid a broader acceleration in defense spending.
Photo by Somchai Kongkamsri from Pexels
On August 17, Raytheon was awarded a $22.9 billion contract to accelerate production of Tomahawk cruise missiles. The agreement supports the annual production ramp-up of more than 1,000 Tomahawk missiles, along with **** ociated support and services.
#corporation #raytheon #tomahawk #demand

2 months ago
OpenAI launched Daybreak for Frontline Defenders on September 3, committing $1 billion in subsidized Daybreak access, training, technical support and partnerships. Separately, the Daybreak Defense Network now includes more than 35 enterprise products and partner-operated services. Cloudflare is offering invitation-only access to an AI vulnerability-discovery and remediation service built with GPT-5.6 Cyber, while SentinelOne is adding Daybreak models to its Wayfinder services. Cloudflare, Inc. (NYSE:NET) and SentinelOne, Inc. (NYSE:S) therefore enter the same program with different routes to revenue.
Cloudflare's model starts at the network and developer edge. It can combine authorized source-code ****** ysis with traffic and security context, then propose code patches and WAF mitigations for customer review. That distribution creates a credible cross-sell path because customers already use Cloudflare for performance and security. Insider Monkey counted 87 hedge funds holding NET at June 30, versus 84 at March 31. AQR Capital Management owned 2,076,835 shares after raising its position by 129%.
The weakness is monetization. Early access is not general availability, and subsidized services can prove usefulness before they prove willingness to pay. Cloudflare must also prevent automated discovery from producing noise or unsafe fixes. Its premium valuation leaves little tolerance for a long gap between product attention and revenue.
SentinelOne approaches the opportunity from endpoint and security operations. Wayfinder can use the new models for code-risk ****** sment, compromise investigation, and malware ****** ysis, placing AI inside workflows staffed by security teams. Forty-one hedge funds held SentinelOne, Inc. (NYSE:S) in Q2, up from 37 in Q1. AQR reported 23,327,991 shares, a 19% quarterly increase.
SentinelOne's risk is competition and services intensity. If Wayfinder depends heavily on expert labor, the offering may scale less efficiently than software. The company also faces Microsoft, CrowdStrike, Palo Alto Networks, and other platforms that can bundle adjacent tools.
#security #access #code #network

2 months ago
(Bloomberg) -- Gold held a gain as US President Donald Trump appeared to rule out prolonged military action in the Middle East, easing inflationary concerns driven by a renewed spike in energy prices.
Most Read from Bloomberg
Apple Maps Renames Lake Ontario 'Lake America' After Trump Order
Uber to Cut 10% of Jobs, or 3,300 Roles, to Slash Bureaucracy
Bessent's Bond Gains Wiped Out as Treasury Yields Jump Again
#bloomberg #Gold #president #middle
Most Read from Bloomberg
Apple Maps Renames Lake Ontario 'Lake America' After Trump Order
Uber to Cut 10% of Jobs, or 3,300 Roles, to Slash Bureaucracy
Bessent's Bond Gains Wiped Out as Treasury Yields Jump Again
#bloomberg #Gold #president #middle

2 months ago
Interested in Yatsen Holding Limited Sponsored ADR? Here are five stocks we like better.
Revenue grew 5.1% to RMB1.14 billion, driven by a 40.4% increase in skincare sales, which accounted for 71.5% of revenue. This was partially offset by a 35.8% decline in color cosmetics revenue amid portfolio optimization and SKU reductions.
Profitability weakened significantly: gross margin fell to 73.9% due largely to inventory provisions, while higher marketing expenses pushed the company's net loss to RMB90.8 million from RMB19.5 million a year earlier.
Yatsen plans to improve profitability by diversifying beyond Tmall and Douyin into business-to-business, offline, duty-free and professional channels. It forecasts third-quarter revenue of RMB898.6 million to RMB998.4 million, implying roughly flat to 10% year-over-year decline.
Yatsen (NYSE:YSG) reported second-quarter 2026 revenue growth of 5.1% as continued strength in its skincare portfolio offset a sharp decline in color cosmetics sales, while higher inventory provisions and increased marketing spending widened the company's losses.
#profitability #offset
2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
A decade ago, if you said GoPro was the Allbirds of the action sports world, it would've been a compliment to both the action-sports camera company and the one hawking sustainable sneakers.
But in 2026, it means that the companies have effectively become public shells for vaguely worded AI and data center plays.
To that end, GoPro stock soared about 50% on Tuesday before settling and is up nearly 100% over the last week after Starman Optical, a photonics company, agreed to acquire every Red Bull drinker's favorite helmet-mounted camera in a $285 million transaction, or about $1.14 per share. GoPro shareholders will retain about 10% of the company, and the deal will also wipe about $92 million of debt off the balance sheet.
The deal's expected to close by the end of this year, the companies say.
#gopro #Stock #action
2 months ago
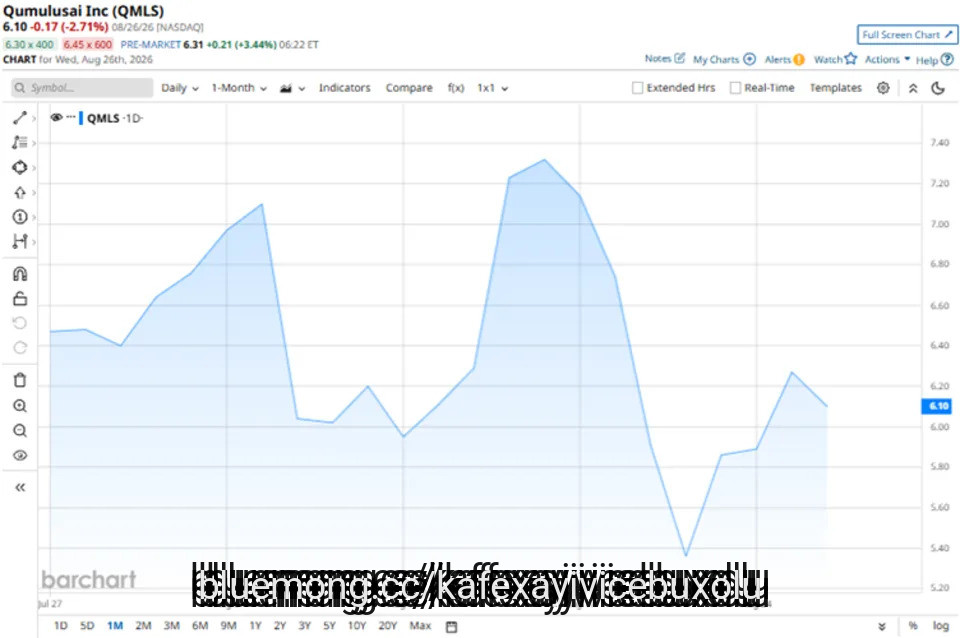
After going public in July following a direct listing, QumulusAI (QMLS) has gained attention on Wall Street as an artificial intelligence (AI) name and cloud partner of Nvidia (NVDA). QumulusAI buys and deploys Nvidia GPUs to run AI training and inference workloads for customers.
Recently, the neocloud provider scored a huge data center win. In an amendment to its surface lease at its Oklahoma data center, the company extended its potential tenure at the site through Jan. 31, 2044. This replaces the original lease's single five-year renewal option with three consecutive five-year renewal options.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#NVIDIA #fans
2 months ago
Nvidia (NASDAQ:NVDA) has steadily delivered one thing in particular to investors quarter after quarter: Mind-blowing earnings growth that's reached record levels well into the billions of dollars. This is thanks to the company's dominance in the high-growth market of artificial intelligence (AI) chips and its expansion into related products and services. In fact, Nvidia has built an AI empire, and in the latest three-month period, this translated into $96 billion in revenue and $59 billion in profit.
In the earliest stages of the AI boom, this growth resulted in stock price gains, with the shares climbing 800% over the past five years. But in recent times, Nvidia stock has faltered here and there. For example, in the first quarter of the year, it slipped 6.4%, and its year-to-date gain of 16% isn't huge for such a high-growth company.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So, it's perfectly logical to wonder where Nvidia stock will be after the company's latest explosive earnings report. History offers us some answers.
Image source: The Motley Fool.
#NVIDIA #Growth #signal

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Budgeting for regular bills and monthly necessities is helpful, but what about those expenses that only come occasionally? Irregular expenses can be hard to plan for, but a sinking fund can help.
A sinking fund helps you save for an irregular, but planned, expense over time. Rather than taking on debt or dipping into your emergency fund, sinking funds encourage you to save a little bit each month for that upcoming vacation, wedding, or major purchase.
Continue reading to learn more about sinking funds, how they work, and how to create one.
A sinking fund is a tool to help you save for irregular expenses over time. Like other line items on your budget, you allot a specific amount of money each month for your sinking fund. But instead of spending that money each month, the fund grows over time until you're ready to spend it.
#save #time #Help


2 months ago
The market has crowned Verizon the winner in its telecom peer group, but its operating report card tells a different story.
Verizon Communications (VZ) stock has delivered for investors over the past year, returning +21% and outpacing the S&P 500. That performance makes it the leader in its competitive group. But when you line up the telecom giants side-by-side, a sharp mismatch appears between the stock's rank and the company's actual business results. Has the market correctly identified a fundamental turnaround before it fully appears in the numbers, or has this stock's price simply gotten ahead of its story?
Why Is The Top-Performing Stock Not The Top Operator?
On paper, Verizon's business performance is solid, but it doesn't lead the pack. Over the last twelve months, its revenue growth ranked third among its peers. T-Mobile US, for instance, grew much faster at 9.7%, yet its stock returned -27% over the same period. That's a significant step up from rivals like AT&T, which trades at 8.3 times earnings despite posting slightly better revenue growth. The market is clearly rewarding Verizon for something that its trailing results don't fully capture, pricing its stock like a class leader while its operational report card is closer to the middle of the pack.
VZ
#market #group #card
2 months ago
On August 13, Nu Holdings Ltd. (NYSE:NU) reported second-quarter results built around a number the digital bank had never posted before: $1.1 billion in net income, up 49% year over year and 17% from the first quarter. The company also crossed 139 million customers across Brazil, Mexico and Colombia, and a newly approved banking license turned what had been a credit-first fintech in Mexico into a full-scale bank. Behind that headline figure sits a business leaning harder on artificial intelligence and new customer tiers to keep growth compounding, even as expenses and past-due loans both crept higher in the same period.
Profitability improved across nearly every measure management pointed to. Net interest margin expanded 180 basis points to 22.9%, and risk-adjusted net interest margin jumped to 12.4% from 9.5% the prior quarter, driven mostly by credit income and a lower cost of credit. Return on equity held at 33% even as the company kept investing in three markets at once. Nubank is also trying to capture more of each customer's wallet rather than just adding new ones.
In July, it launched Croma, a subscription tier aimed at a "Super Core" segment between its mass-market base and its Ultravioleta high-income brand, where purchase volumes grew 41% year over year. It already counts 6.8 million small-business customers, more than any other financial institution in Brazil. Mexico may be the bigger story long term. At a similar stage of adult-population penetration, Nubank's Mexican customers are generating $12.3 in average revenue per active customer versus $5.6 in Brazil at that same point, and the company reached breakeven there in six years versus eight in Brazil.
Underneath all of it sits NuFormer, the company's proprietary AI model, which management said now handles more than 60% of Brazilian customer-support conversations at ratings on par with humans, after a redesign that quadrupled training and inference speed.
Not every metric moved in the right direction. Loans more than 90 days past due rose 35 basis points to 6.9%, which the company attributed to the normal seasonal migration of earlier delinquencies rather than a shift in underlying credit quality. Operating expenses jumped 20% sequentially to $806 million as real estate and marketing costs shifted between quarters and international expansion spending picked up, pushing the efficiency ratio to 19.5% after an unusually low 17.6% in the first quarter that management had already flagged as not sustainable.
#quarter #company #first
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Yum! Brands, Inc. (NYSE:YUM). Yum! Brands, Inc. (NYSE:YUM) develops, operates, and franchises traditional and non-traditional quick service restaurants in the United States and internationally. On August 24, 2026, Yum! Brands, Inc. (NYSE:YUM) closed at $157.35 per share. The one-month return of Yum! Brands, Inc. (NYSE:YUM) was 4.4%, and its shares gained 6.7% over the past 52 weeks. Yum! Brands, Inc. (NYSE:YUM) has a market capitalization of $42.84 billion.
SGA Global Growth Strategy stated the following regarding Yum! Brands, Inc. (NYSE:YUM) in its Q2 2026 investor letter:
"We met with Jon Hixon, Yum! Brands, Inc.'s (NYSE:YUM) Chief Sustainability Officer, as well as members of legal and human resources teams to discuss several topics relevant to our investment thesis, including human capital management, geopolitical and reputational risks, corporate governance, and sustainability reporting. During the discussion, we were pleased to hear that Yum's next sustainability report would include, for the first time, disclosures aligned with the Taskforce on Nature-related Financial Disclosures (TNFD) framework, alongside its existing climate-related reporting. The addition of TNFD reporting reflects the company's ongoing efforts to ******* s and disclose nature-related dependencies, impacts, risks, and opportunities across its agricultural supply chain. A key focus of the engagement was Pizza Hut's ongoing strategic review and the ******* ociated human capital implications. Management outlined several retention initiatives designed to support workforce stability during the review process, including broad-based retention bonuses for employees and targeted retention awards for critical leadership and operational roles. While the company had experienced a modest increase in employee turnover, management indicated that attrition remai

2 months ago
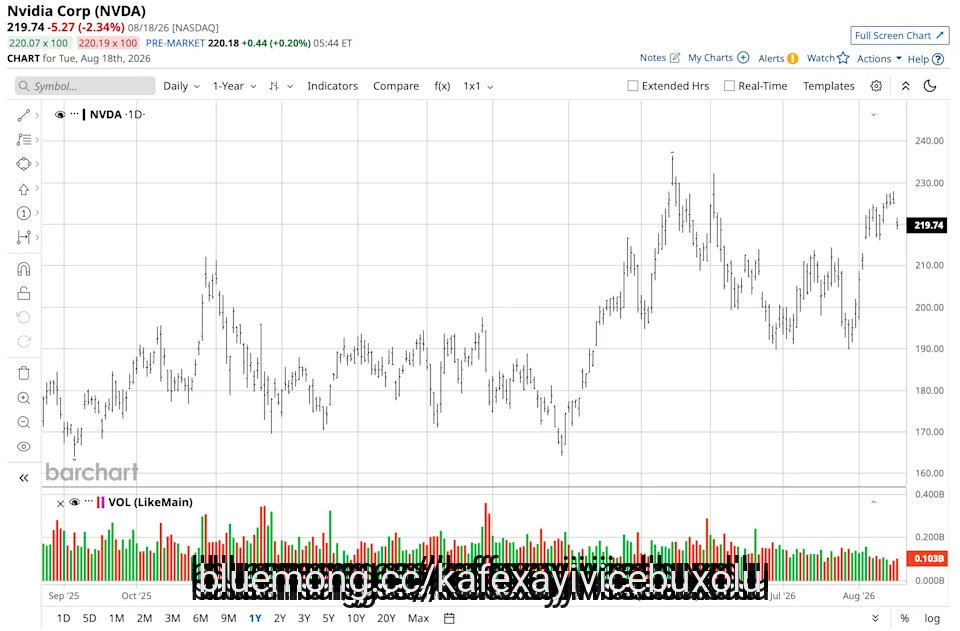
Whale Rock Capital Management executed a number of noteworthy portfolio changes during the second quarter, yet one deserves special attention. Namely, the hedge fund sharply reduced its exposure to Nvidia (NVDA) in Q2.
According to the most recent 13F filing from the firm, Whale Rock decreased its Nvidia holding from approximately 1.04 million shares to 377,204 shares in Q2. This marks a reduction of about 64%, which is quite a significant step for a company at the heart of the AI infrastructure boom. On the other hand, Whale Rock increased its Advanced Micro Devices (AMD) stake from just 69,211 shares to roughly 1.51 million shares. Therefore, one can safely say that this was not a complete selloff of AI semiconductor stocks. Let's take a closer look.
Google Lost About $186 Billion After 4 of Its Top AI Researchers Left, but Sundar Pichai Says Google Will Be 'A Founding Investor' Anyway
Microsoft vs. Broadcom: One Has 85% Upside, But I'm Picking the Other
Rocket Lab and AST **** eMobile Are Priced for the Big Bang. One **** e Stock Already Delivered.
#whale #Google #namely

2 months ago
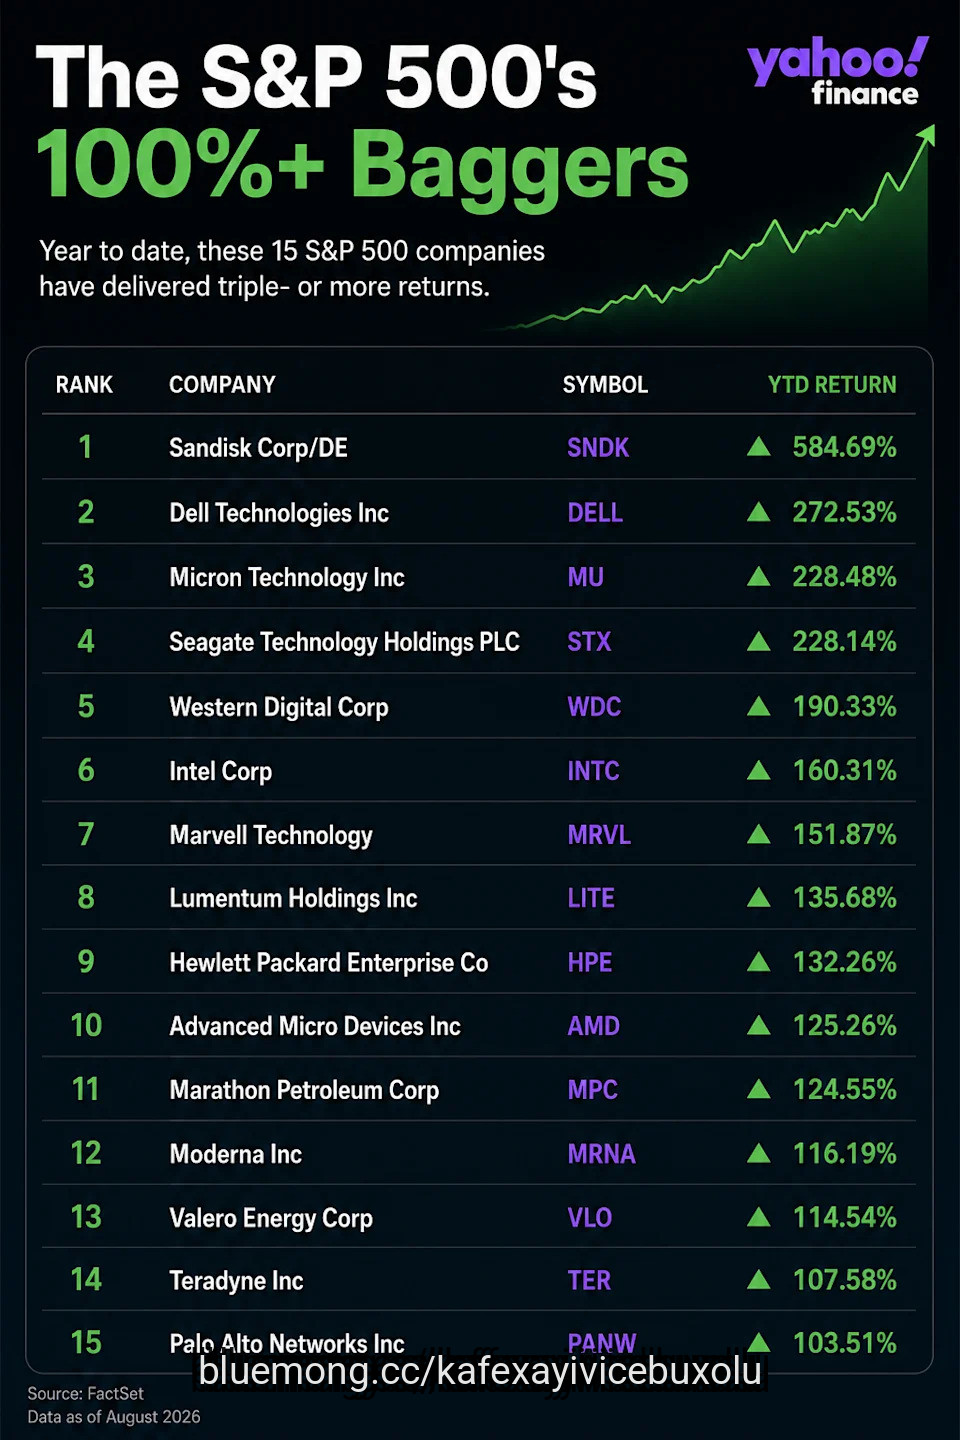
It has been a big year for executives and investors at 15 companies in the S&P 500 (^GSPC), and it's all because of one factor.
You guessed it: the Great AI Boom.
There are now 15 companies in the S&P 500 up 100% or more this year (see chart below), per Yahoo Finance **** ysis. Sandisk (SNDK) is leading the way with an almost 600% gain on the year amid strong demand for its memory chips at ever higher prices.
The list is interesting for several reasons.
First of all, chip king Nvidia (NVDA) isn't on the list, as its stock is "only" up 18% year to date.
#finance #sandisk #sndk
3 months ago
Qiagen (NYSE:QGEN) walked into its second quarter of 2026 bracing investors for a roughly 2% sales decline. Instead, net sales came in flat at $535 million on August 6, and adjusted diluted EPS hit $0.62, both ahead of the company's own outlook. For a diagnostics and life sciences supplier still working through the loss of discontinued product lines, beating a cautious bar is one thing. What happens next, as management leans on a stack of new launches to carry the back half of the year, is the more interesting question.
The company's so-called growth pillars, the businesses management is counting on to outpace the broader market, expanded 5% at constant exchange rates in the quarter. Sample Technologies led with 9% CER growth, driven by automated consumables and higher instrument sales. QIAcuity, the digital PCR platform, posted double-digit consumables growth even as weaker OEM demand offset some of that strength. QuantiFERON, the tuberculosis test that had flagged a sharp drop in US immigration testing demand back in the first quarter, still managed to return to growth as demand across other testing groups more than made up the difference.
Behind those numbers sits a wave of product activity. QIAsymphony Connect launched commercially, QIAsprint Connect placements are drawing what management called strong pharma customer acceptance, and two new bloodstream infection panels for QIAstat launched in Europe, detecting 33 pathogens and 28 resistance markers in about an hour, with US FDA approval targeted by year-end. Parse, the single-cell ****** ysis business, is running ahead of its roughly $40 million 2026 sales target and was selected for a NASA-supported research program aboard the International ****** e Station. Qiagen also completed a $500 million share repurchase in January and raised its annual dividend 40% to $0.35 per share.
The flat top line masks uneven performance underneath. Diagnostic solutions overall declined 2% at constant currency, and PCR and nucleic acid amplification sales fell 8%, with QIAstat-Dx down 7% as a tough prior-year comparison in respiratory testing outweighed gains in gastrointestinal and meningitis panels. Profitability also gave ground. Adjusted operating income fell 2% to $157 million, with the margin slipping to 29.4% from 29.9% a year earlier, and adjusted gross margin declined to 66.2% from 66.7% on product mix shifts.
Regionally, EMEA sales fell 2% CER as declines in Germany, France, and Italy outweighed gains elsewhere, and Asia Pacific sales fell 2% CER as China dropped in the low teens, even though it improved sequentially. Inventory days outstanding also climbed to 153 from 149, tied to stockpiling ahead of new launches. The company is now guiding to a jump from roughly negative 1% CER sales growth in the first half to 3% to 4% in the second half, a swing that leans heavily on new products, easier comparisons and the fading drag from discontinued lines all landing on schedule.
#Growth #adjusted #ro

3 months ago
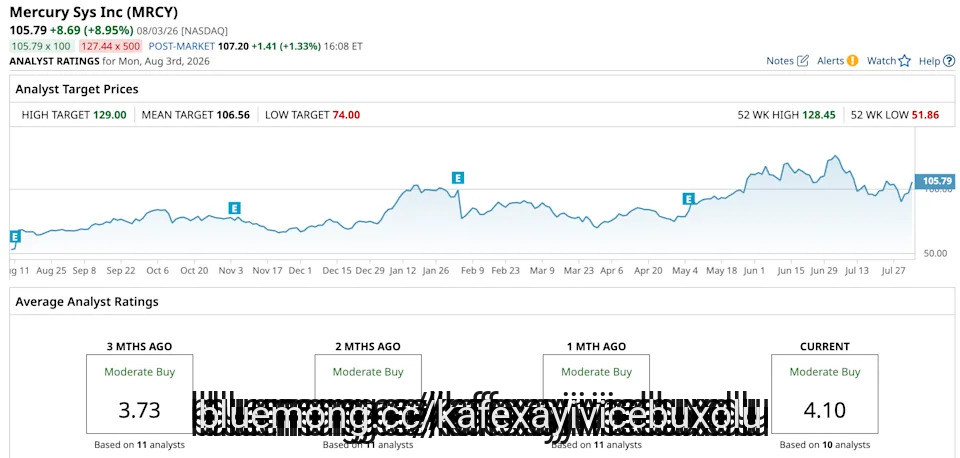
Mercury Systems (MRCY) has partnered with Palantir Technologies (PLTR) to automate factory operations and material planning, aiming to accelerate delivery of critical defense technology for U.S. military programs. The collaboration supports the Department of Defense's push to boost throughput and shorten delivery timelines for essential components across the defense industrial base.
Through two initial workflows, Mercury will streamline material planning and reduce manual workloads, strengthening its ability to scale production without extending delivery times or driving up costs. By integrating its data sources onto Palantir's Foundry platform, Mercury aims to speed up design and delivery processes to meet growing customer demand.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 **** anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#mercury #defense #palantir


3 months ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
I am selling my house and the price is $504,999. After paying off this house I will net $400,000. Do I have to pay a capital gains tax as I'm planning to pay off my retirement home with the money I netted?
– Thomas
The answer is solidly "it depends," both in terms of whether you'll have to pay capital gains tax and how much you might have to pay. Let's talk about the rules around this situation first, and then we can get into some examples to see how they work.
The IRS allows single filers to exclude up to $250,000 of capital gains from the sale of their home, and married couples filing jointly to exclude up to $500,000, if they meet certain criteria.
#capital #gains #thomas #commission


3 months ago
Starbucks (SBUX) kept its growth story piping hot in the third quarter as CEO Brian Niccol leads the company into year three of its turnaround plan.
Starbucks posted same-store sales growth of 7.9%, more than the 5.7% growth Wall Street expected, according to Bloomberg data, and above the 6.2% jump seen in Q2. Last year, the company saw a 2% decline in overall same-store sales growth in the third quarter.
The coffee chain reported adjusted earnings per share of $0.85, higher than the Street's $0.56 forecast and up from $0.50 per share in the same period last year. Revenue of $9.3 billion came in above the Street's $9.2 billion estimate but was down from $9.5 billion in the same period last year due to the transition of its China business to a joint venture.
"It's clear proof that our Back to Starbucks plan is working," Niccol told investors on the company's earnings call.
Starbucks stock rose more than 2% on Thursday as investors ****** sed the report.
#last #billion #niccol #Third

3 months ago
A decline in public consumption of alcoholic drinks since the end of the Covid-19 pandemic has been a major factor in declining revenue in the beer, wine, and spirits sectors leading certain companies to file for bankruptcy protection.
128-year-old beer, wine, and spirits distributor Republic National Distributing Company was a major company affected as it filed for Chapter 11 bankruptcy protection, seeking going concern sales of its remaining ****** ets, a wind down of operations, completion of transition services agreements, and approval of its equity holder settlement.
National Distributing Company Inc. is not a part of the Chapter 11 filing, the company said in a statement on its website.
A company spokesperson was not immediately available for comment.
Republic National Distributing Company filed its petition as its business's financial position deteriorated after the Covid-19 pandemic subsided in late 2022 and demand for off-premises alcohol consumption plummeted.
#company #chapter #consumption #major

3 months ago
Nebius Group extended its winning streak to a third consecutive day on Tuesday, jumping 18.78 percent to finish at $216.92 apiece, after Nvidia Corp. helped boost investor confidence in the company following its acquisition of a 9.3 percent stake.
The purchase followed the two companies' investment and partnership announcement earlier this year, under which they will collaborate on developing and deploying next-generation hyperscale cloud for the AI market.
Nvidia also invested $2 billion in Nebius Group NV (NASDAQ:NBIS), reflecting its confidence in the latter's business and unique depth of engineering expertise across the full AI technology stack.
For illustration purposes only. Photo by Brett Sayles on Pexels
Under the terms of the partnership, Nebius Group NV (NASDAQ:NBIS) and Nvidia will collaborate on AI factory design and support, including access to partner design material, design review processes and acceptance, early samples and system software support, bring-up support, and regular system partner business and technical reviews.
#nbis
3 months ago
Madison Dividend Income Fund, managed by Madison Funds, released its Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund aims to generate income and capital appreciation from a high-quality, high-dividend portfolio. The Fund (class I) returned +1.8% in the second quarter, which compared to the S&P 500 Index, Russell 1000 Value Index, and Lipper Equity Income peer group returns of +15.2%, +13.9%, and +9.7%, respectively. YTD, the Fund returned +7.7%, compared with +10.2%, +16.3%, and +9.9% for the indexes, respectively. The Technology sector performed strongly, while Energy lagged. The firm sees the Energy sector's decline as an opportunity to buy undervalued energy stocks with good dividends. With S&P 500 valuations at all-time highs, risks include market correction and multiple contraction. The Fund aims to mitigate these risks by maintaining a diversified mix of high-quality, high-yield stocks in undervalued sectors. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Madison Dividend Income Fund highlighted ExxonMobil Holdings Corporation (NYSE:XOM). ExxonMobil Holdings Corporation (NYSE:XOM) is a leading energy company that engages in the exploration and production of crude oil and natural gas. On July 21, 2026, ExxonMobil Holdings Corporation (NYSE:XOM) closed at $151.71 per share, reflecting a market capitalization of $628.83 billion. ExxonMobil Holdings Corporation (NYSE:XOM) posted a one-month return of 10.82%, while its shares gained 38.01% over the past 52 weeks.
Madison Dividend Income Fund stated the following regarding ExxonMobil Holdings Corporation (NYSE:XOM) in its Q2 2026 investor update:
"One of the fund's top holdings is ExxonMobil Holdings Corporation (NYSE:XOM). XOM is the world's premier integrated oil and gas company. It has attractive upstream exploration and production ****** ets in the low-cost Permian Basin and a unique, ultra-low-cost growth opportunity in Guyana, along with developing liquid natural gas (LNG) ****** ets for data centers. The company has a downstream Product Solutions segment that refines energy, chemical and specialty products. Its low-cost position, diversified ****** et base, scale, integrated ****** ets and strong balance sheet provide a sustainable competitive advantage, in our view.
XOM's five-year "Plan to 2030" provides a framework for higher growth and substantial capital returns. It targets 65% of upstream production from its "advantaged" ****** ets by 2030, up from 59% today, which will drive a favorable mix shift and expand margins. The company thinks it can add $25 billion in earnings and $35 billion in cash flow while keeping capital expenditures flat in the $22-27 billion range.
#NYSE #madison
3 months ago
Apple recently filed a trade secrets lawsuit against OpenAI, accusing the AI company of a pattern of misconduct aimed at getting current and former Apple employees to share confidential information. (In response, OpenAI said it is "not aware of any evidence that this complaint has merit.")
On the latest episode of TechCrunch's Equity podcast, Kirsten Korosec, Sean O'Kane, and I debated whether this lawsuit will cast a shadow over OpenAI's much-discussed plans to get into the hardware business (starting with a mobile smart speaker) and go public.
"Even setting aside whether or not the court grants any kind of injunctive relief or any kind of restraining order over what OpenAI is doing, it just naturally can lead to that sort of situation where it's going to cause some delays in what OpenAI is working on," Sean suggested. "Which I'm sure was probably part of the reasoning behind Apple doing this. They don't do this stuff willy nilly."
With all those plans on the line, will OpenAI try to settle this as quickly as possible, or did it learn from its recent courtroom victory against Elon Musk that it can endure the cost and embarrassment of a trial? Kirsten, at least, predicts the latter.
Keep reading for a preview of our conversation, edited for length and clarity.

3 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #1470d91a -8450-11f1-9d68-e554247ac0ce
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #1470d91a -8450-11f1-9d68-e554247ac0ce




