21 days ago
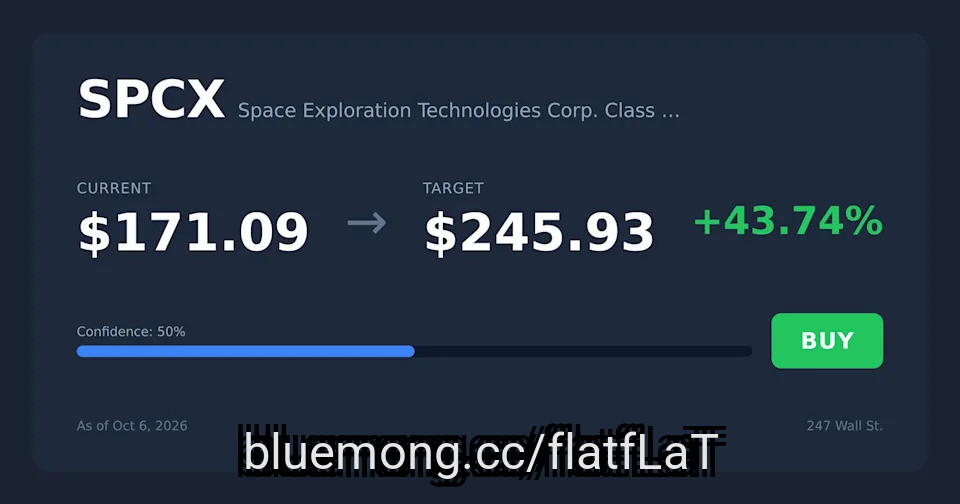
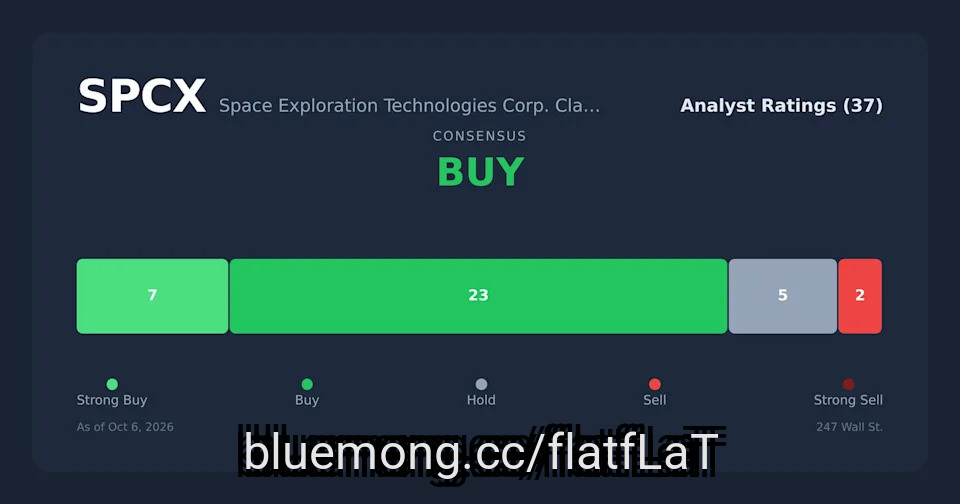
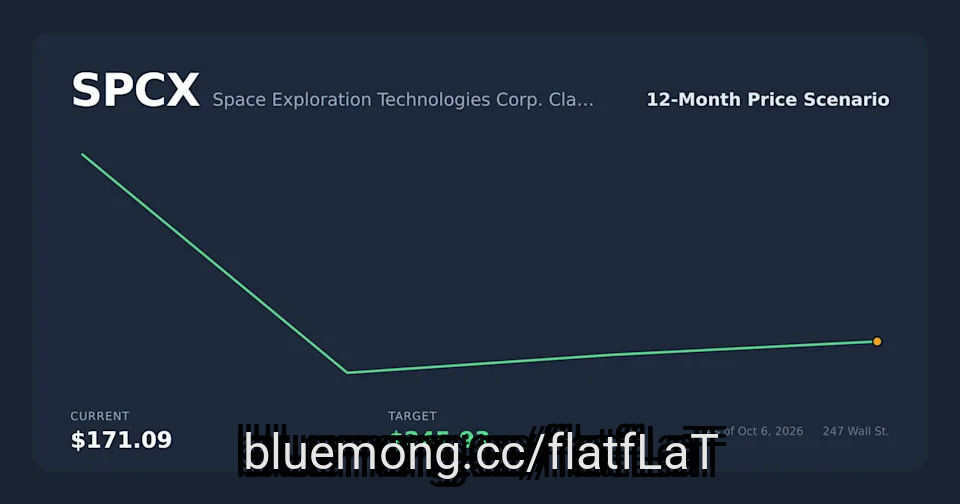
SpaceX shares surged 8% Monday after Morgan Stanley reiterated its $300 price target, calling the stock "cheap and getting cheaper."
Musk confirmed plans to rename ****** eX's AI unit to ****** eXSI, adopting Trump's preferred "super intelligence" term, with no timetable given.
The rally pushed Musk's estimated net worth above $1.03 trillion, exceeding Taiwan's entire annual GDP of $977 billion.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Shares of ****** eX (NASDAQ:SPCX) rose sharply Monday after two developments. First, CEO Elon Musk said the company plans to rename its artificial intelligence unit. Then Morgan Stanley (NYSE:MS) repeated its price target on the stock. The last quote was $171.40 as of 6:42 PM ET on October 5, 2026, in after-hours trading. At that point the after-hours move stood at 0.18%, according to Pluang. That figure covers post-close trading only and does not show how the regular session went.
#Monday #plans

1 month ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel


1 month ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


1 month ago
In June, ****** eX (NASDAQ: SPCX) successfully completed its blockbuster IPO, raising more than $85 billion. In the days that followed, ****** eX's market cap soared from an initial IPO valuation of $1.77 trillion to nearly $2.8 trillion. Shares corrected hard after the surge, however, and ****** eX's valuation now hovers just below $2 trillion -- a 36% decline versus the company's all-time high.
Morgan Stanley (NYSE: MS) ****** ysts remain unfazed regarding the ****** e stock's long-term growth potential. On Sept. 15, the bank reiterated its "buy" rating on shares, affirming its $300 price target. That price target implies more than 100% in near-term upside over the next 12 months.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Why does Morgan Stanley remain so bullish? The answer might surprise you.
Morgan Stanley appears all-in on the ****** e economy. The bank, in many ways, predicted ****** eX's meteoric rise years before much of the public caught on.
#trillion #valuation


1 month ago
On September 15, Needham ***** yst James Ricchiuti lifted the firm's price target on Teledyne Technologies Incorporated (NYSE:TDY) to $760 from $750, and reiterated a Buy rating. The revised price target reflected an upside of 27% from the close of the note.
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september


1 month ago
On September 2, 2026, Phreesia, Inc. (NYSE:PHR) reported second-quarter fiscal 2027 results for the period ended July 31, 2026. Revenue rose 10% to $129.5 million and adjusted EBITDA climbed to $32.9 million from $22.1 million a year earlier, a 25% margin. Net income reached $1.9 million, marking the company's fifth consecutive quarter of profitability. Management reaffirmed full-year revenue guidance of $510 million to $520 million and adjusted EBITDA of $125 million to $135 million.
The disagreement on Wall Street is about what that reaffirmation actually signals.
Wells Fargo found the highlight in Network Solutions, which grew 9% year-over-year, and pointed to the ProviderConnect pilot delivering a 4% prescription lift in a GLP-1 campaign that management says is generating follow-on business; the firm raised its target on Phreesia, Inc. (NYSE:PHR) to $10 from $9 while holding an Equal Weight rating.
DA Davidson stayed at Buy despite trimming its target on Phreesia, Inc. (NYSE:PHR) to $13 from $14, arguing the stock sold off on a reiterated guide even though network solutions activity is tracking more encouragingly than the prior outlook and AccessOne is opening a growing opportunity in alternative consumer payment options.
Baird ******* yst Joe Vruwink lifted his target to $11 from $10 at Neutral after updating his model.
#million #solutions

1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


1 month ago
Palantir stock has had a rough stretch. A 5-star Wall Street **** yst just said the market is reading the company wrong.
UBS **** yst Karl Keirstead raised his price target on Palantir Technologies to $250 from $220 on Sept. 15, reiterating his Buy rating, according to CNBC. At Palantir's Sept. 14 closing price of roughly $173, the new target implies about 44% upside.
Keirstead's updated view stemmed directly from Palantir's Sept. 10 AIPCon11 event, where Palantir brought together customers, executives, and partners to discuss how companies are deploying its AI platform in real operations.
"Our view of Palantir as the best AI enabler in the market, making frontier models and AI useful in large enterprises, was, if anything, bolstered by these conversations, and demand momentum seems robust," Keirstead wrote in a note shared with clients.
He described three points that stood out from the event. Customer conversations kept coming back to AI sovereignty, the idea that enterprises and governments want control over their own data and AI infrastructure, rather than handing it to a small number of large cloud providers.
#analyst #market #target #Event


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #fund #conventum #global

1 month ago
Dow Jones futures fell early Monday, along with S&P 500 futures and especially Nasdaq futures. Crude oil prices jumped while AI stocks are under pressure after artificial intelligence leaders called for slowing AI model development. Treasury yields and the upcoming Federal Reserve meeting also are key this week.
The stock market fell last week, but rebounded Friday, with Apple (AAPL), Moderna (MRNA) and NetApp (NTAP) flashing buy signals. The S&P 500 index declined 0.8% and the Nasdaq fell 0.7%, both above their 50-day moving averages. The Dow Jones Industrial Average lost 1.6% in last week's stock market trading. The small-cap Russell 2000 shed 2.4%. Both are below their 50-day lines.
A number of stocks flashed buy signals or are setting up, but the choppy index action and rapid sector rotation has been a difficult environment.
U.S. crude oil futures spiked 9.4% to $100.05 a barrel last week, even with Friday's 2.4% decline. Oil prices shot up 20% in the last two weeks amid the widening U.S.-Iran conflict, threatening further oil supply routes.
The 10-year Treasury yield surged 19 basis points to 4.97%, the highest since nearly hitting 5% in October 2023. Markets are betting on a Fed rate hike, even as President Donald Trump reiterated his call for rate cuts.
#last #NASDAQ

1 month ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management

2 months ago
While much of the clothing and footwear industry has spent this earnings season explaining away low consumer demand, Birkenstock Holding plc (NYSE:BIRK) showed an entirely different story, and investors rewarded it accordingly.
Shares of the German footwear manufacturer rose up to 20% on August 13 after the company published fiscal third-quarter earnings that exceeded expectations and prompted management to improve its full-year guidance. Revenue for the quarter came in at €720 million (about $829 million), up 13% on a reported basis and 15% in constant currency, exceeding ****** ysts expectations of around €713-715 million. Meanwhile, adjusted earnings per share of €0.74 happened to be somewhat lower than the €0.76 consensus, though this fact did little to dampen enthusiasm given the report's overall strength.
The headline change was direction. Birkenstock Holding plc (NYSE:BIRK) now targets fiscal 2026 revenue growth of 15% on a constant-currency basis, up from its previous range of 13% to 15%, putting the company at the upper end of its own previous objective rather than just reiterating it. Management also increased its adjusted EBITDA forecast to at least €710 million, up from a previous floor of €700 million, and now expects reported revenue to be at the high end of the €2.30 billion-€2.35 billion range.
According to Birkenstock Holding plc (NYSE:BIRK), the reason for some of the strength is simple: full-price demand from affluent buyers who haven't reduced their discretionary spending in the same manner that the broader consumer has. Strong pricing power and brand loyalty helped shield companies catering to wealthier customers from the broader spending pullback affecting much of the apparel and footwear sector, and Birkenstock's results reflect this across all regions it operates in, with the Americas growing 14%, EMEA 15%, and Asia-Pacific rising the fastest at 23%, all in constant currency terms.
Birkenstock Holding plc (NYSE:BIRK) has also carefully managed its balance sheet during this period of strength. On June 30, the company executed an accelerated share buyback program of €230 million, decreasing its outstanding share count by about 6 million shares. The move helped enhance per-share earnings growth, with adjusted EPS rising 19% year-over-year.
#million #birk #company


2 months ago
On September 2, Shell Offshore, a subsidiary of Shell plc (NYSE:SHEL), announced the acquisition of a 30% working interest in Conifer, an exploration prospect operated by BP p.l.c. (NYSE:BP) in the U.S. Gulf of Mexico. Located offshore within Keathley Canyon near BP's Kaskida host development, Conifer represents a significant deep-water play. BP retains operatorship, with the initial exploration well expected to spud in 2027. While the deal reflects shared risk and capital efficiency in high-cost offshore basins, comparing the two giants' Q2 2026 earnings shows that Shell is currently executing from a position of superior financial strength.
Shell plc (NYSE:SHEL) delivered an exceptionally clean Q2 2026 report. Adjusted earnings reached $9.8 billion, driven by record upstream production in Brazil and record refinery utilization, which offset Middle East operational outages. Cash flow from operations (CFFO) came in at $21.4 billion, supported by higher realized prices and a $3.4 billion working capital inflow. Shell maintained strict capital discipline, reiterating its full-year capex outlook of $24 billion–$26 billion while completing $5.8 billion in structural cost reductions since 2022. Balance sheet health remains robust, with gearing at 19% and net debt at $42 billion ($12 billion excluding leases).
BP p.l.c. (NYSE:BP) also turned in a solid Q2 recovery, but its headline metrics lag behind Shell's scale. BP reported underlying replacement cost profit (its proxy for net income) of $5.7 billion, a 78% quarter-over-quarter rebound fueled by strong refining margins and oil trading. Operating cash flow reached $10.9 billion after absorbing a $1.0 billion working capital build. BP used strong cash generation to trim net debt down to $22.25 billion, while guiding full-year capex to $13.5 billion–$14.0 billion.
Although BP raised its quarterly dividend by 4% to 8.66 cents, Shell's cash engine allowed it to announce its 19th consecutive quarter of at least $3 billion in share buybacks, distributing 44% of CFFO over the trailing 12 months.
Shell's bull case centers on superior capital allocation, aggressive portfolio high-grading, including the ARC Resources acquisition targeting a 4% production CAGR through 2030, and consistent share buybacks. The bear case focuses on execution risks in integrated gas and LNG amid volatile market conditions, as well as the challenges of integrating large-scale acquisitions.
#cost

2 months ago
On September 3, AbbVie Inc. (NYSE:ABBV) finalized its acquisition of clinical-stage biotech Apogee Therapeutics, Inc. (NASDAQ:APGE) for $135.11 per share in cash. The $10.9 billion buyouts immediately fold Apogee's promising inflammatory and immunology (I&I) pipeline into AbbVie's commercial engine. On the exact same day, AbbVie separately reported positive Phase 3 Cervino trial results for its bispecific T-cell engager, etentamig, in relapsed/refractory multiple myeloma. Together, the dual catalysts emphasize how mega-cap pharmaceutical giants are deploying cash flow from legacy franchises to lock in next-generation immunology and oncology ***** ets.
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth

2 months ago
On September 2, Michael Genovese from Rosenblatt Securities reiterated his Neutral rating for Credo Technology Group Holding Ltd (NASDAQ:CRDO). The **** yst increased his price target for the stock from $215 to $235, which implies upside potential of almost 38% as of September 4 closing. Genovese's upward adjustment in price target in based on the company's recently announced Q1 FY27 results, leading him to increase his projections for FY27 and FY28. Despite that, he has a Neutral stance because he still wants more visibility around the company's ZeroFlap Optical Transceivers proof points, as well as the incremental revenues from its acquisition of Dust Photonics in May.
Photo by Yogesh Phuyal on Unsplash
Credo's acquisition of DustPhotonics gives it a vertically integrated connectivity stack covering DSP, silicon photonics, SerDes and system integration. This allows the company to tap into both optical and electrical interconnects across the entire AI infrastructure buildout. Together with its optical DSPs and ZeroFlap transceivers, the deal is expected to be a key growth driver in FY27, supported by resilient hyperscale customer sentiment.
Following the DustPhotonics transaction, Credo reported a strong first quarter for FY27. Topline of $479 million jumped 115% compared to Q1 in FY26. Adjusted non-GAAP net income of $236.3 million was up 140% year-over-year, as the company broadens its connectivity portfolio stack. It now spans copper and optical solutions, ranging from millimeters to kilometers, which enables Credo to meet the scaling needs of AI infrastructure with energy-efficient and reliable products.
For FY27, Credo expects a strong inflection with optical revenues expected to exceed $600 million. Management projects contributions over $100 million each from silicon photonics, ZeroFlap optics, and optical DSPs. Full-year revenue growth is expected to be over 85% year-over-year. Adjusted gross margins are likely to remain consistent with fiscal 2026 levels, along with adjusted net margins of around 50%.
#expected


2 months ago
Etsy Inc (NASDAQ:ETSY) stock is down 2.6% to trade at $70.20 today amid broader market pressure, though Argus reiterated its "buy" rating and lifted its price target to $89 from $67. The $70 level has served as both support and resistance in recent months and could provide a potential pivot point for the shares. What's more, the e-commerce name is now within striking distance of a historically bullish trendline.
According to Schaeffer's Senior Quantitative ***** yst Rocky White, Etsy stock is trading within 0.75 times the 100-day moving averages' 20-day average true range (ATR), after spending at least 80% of the previous two weeks and 80% of the prior 42 trading sessions above that trendline. This setup has appeared 13 other times over the last decade, after which the stock was higher one month later 77% of the time, averaging a 10.3% gain.
Short interest represents 10.8% of the stock's available float, and would take shorts over three days to cover at the stock's average pace of trading. A move higher could pressure some of these bearish bettors to exit their positions, creating additional buying power.
Now also looks like a good time to weigh in on ETSY's next move with options. The stock's Schaeffer's Volatility Index (SVI) of 49% sits in the low 10th percentile of its annual range, suggesting options traders are pricing in relatively low volatility expectations at the moment.
#trading #volatility #within


2 months ago
Wall Street sees Apple Inc. (NASDAQ:AAPL) entering a significant hardware cycle ahead of its "Surprise and Shine" event streaming live on Wednesday, September 9, 2026. Bank of America, in particular, expects a broad slate of new Apple devices led by new iPhones and a Foldable iPhone.
On September 8, BofA Securities ***** yst Wamsi Mohan reiterated a Buy rating on the stock with a $380.00 price target. While Bofa may be bullish, it must be noted that one of Apple's anticipated products is launching in a market where competitors are already pushing foldable technology forward.
Chinese tech giants revealed timed foldable products ahead of Apple's launch, sharpening competition. Both unveiled foldables days before Apple's event, offering a fresh look at the competition Apple is about to face.
Pixabay/Public Domain
According to the Wall Street firm, Apple is anticipated to announce three new phones: the iPhone 18 Pro, Pro Max, and the tech giant's first foldable iPhone. This will likely be branded as the Ultra or the Fold.
#foldable #street
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Prince Harry and Meghan Markle were "surprised" by the letter circulated by Buckingham Palace reiterating their non-royal status, it emerged on Sept. 8
The letter was released to inform U.K. government departments and others of the arrangements in the light of the couple's return to the U.K. in August
The Duke and ****** ss of Sussex are believed to be staying in a private home outside of London, and their children Prince Archie, 7, and Princess Lilibet, 5, are starting school
Prince Harry and Meghan Markle were "surprised" by the timing of the letter circulated by Buckingham Palace clarifying their non-working royal status, PEOPLE understands.
In a guidance letter released on Monday, Sept. 7, a senior palace official reiterated the official positions of the Duke and ****** ss of Sussex. The letter, issued on behalf of Harry's father King Charles, was said to have been shared with the Sussexes' team.
#sept

2 months ago
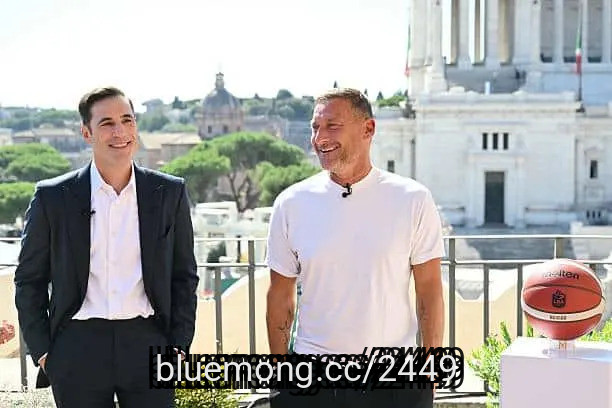
Roma is in, but Francesco Totti prefers not to rush things.
The former Giallorossi captain, now an advisor for Maxima Roma, spoke to Rai Sport on the sidelines of the presentation of the capital's basketball team, also focusing on the ***** le race.
Regarding the potential battle for first place, Totti names two teams but postpones any decision: "Roma and Inter are the candidates for the ***** le, we're not saying anything and we'll wait for the rest of the season. We'll see in 10 or 15 matchdays."
Meanwhile, his bond with the Giallorossi remains intact. Totti doesn't hide his satisfaction with the team's start and reiterates what Roma means to him: "I will never put Roma aside, it's my skin. We're here, we've started well, and I hope it can continue at this level."
The former number 10 then rejected the idea that the new adventure could be a response to those who didn't involve him in other projects: "Am I taking revenge on those who didn't seek me out? It's not a reprisal, but a project that's excited me. I'm happy because for me, sport comes first."
#giallorossi #we 're #we 'll

2 months ago
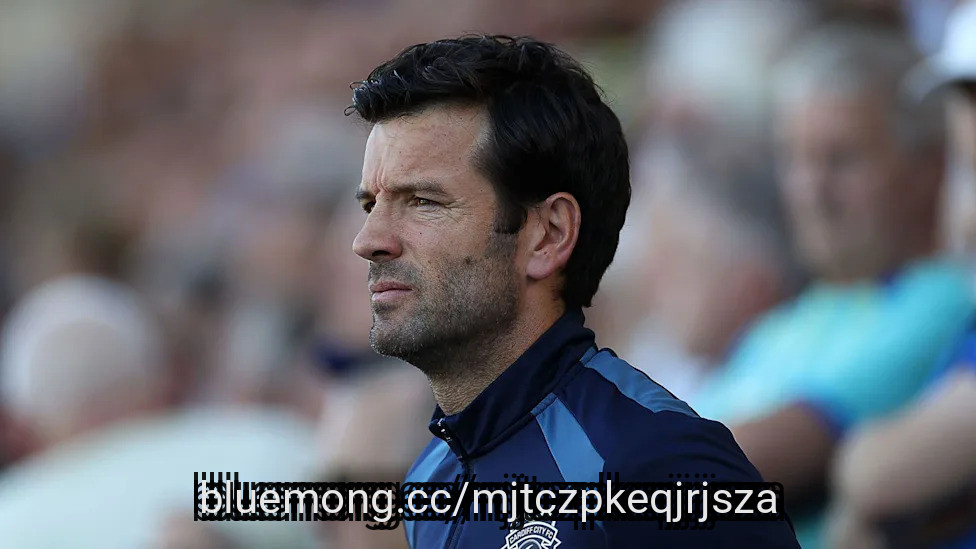
Brian Barry-Murphy insists Cardiff should not be too downbeat about their unfavourable league position after a winless start to the Championship campaign.
The Bluebirds begin the week in the relegation places following a 2-0 defeat to Portsmouth on Saturday which leaves them on three points after five games.
Stoke will arrive at the Cardiff City Stadium for Tuesday evening's game (19:45 BST) buoyed by their 4-0 thrashing of Charlton over the weekend.
But head coach Barry-Murphy has urged supporters and players to remain calm, and reiterated that there is still a long way to go this season.
"It's a tough schedule. We knew these games were very close together in this opening period. With the squad the size of ours, that has its challenges," said the Irishman.
#games #bluebirds
2 months ago
NVIDIA Corporation (NASDAQ:NVDA) has officially committed billions on AI developer platform Hugging Face for a $12.9 billion. The deal signifies the chipmaker's move beyond hardware and up the AI stack.
The AI chipmaker buying the open-source model hub millions of developers are already using reads differently when compared to Broadcom's earlier forecast to double its AI chip revenue to roughly $230 billion in fiscal 2028.
Even though AVGO is facing increased competition in Google's TPU programs, it is also gaining ground with customers such as OpenAI and Anthropic. This makes Nvidia's recent move look more like insurance rather than opportunism.
In response to the acquisition, Needham ******* yst Rajvindra Gill reiterated a Buy rating on Nvidia on September 4, ******* igning a $300.00 price target.
"Yesterday, NVIDIA announced its agreement to buy Hugging Face for $12.930BN. Hugging Face is the open source platform for hosting open source and open weight models and datasets enabling developers to easily access ready-to-use models instead of building and training them from scratch."
#developers
2 months ago
King Charles' new guidance reiterates that Prince Harry and Meghan Markle's "His and Her Royal Highness" styles remain in abeyance and are not used
Harry and Meghan retained their HRH styles after stepping back as working royals in 2020, but agreed they would no longer use them publicly
The clarification comes after a "number of requests" for guidance following the Duke and **** ss of Sussex's return to the U.K.
Prince Harry and Meghan Markle's return to the U.K. isn't changing their royal **** les — or the important distinction in how they use them.
In new guidance issued at King Charles' direction following the Duke and **** ss of Sussex's move back to Britain, the couple are repeatedly referred to by their Sussex **** les, reaffirming the **** les they have held since their 2018 wedding.
#meghan #prince


2 months ago
On August 18, Austin Moeller from Canaccord Genuity reiterated his Buy rating for Intuitive Machines (NASDAQ:LUNR). Despite cutting his price target from $41 to $39, his estimates result in almost 165% upside potential as of September 1 closing. Moeller's stance is based on the company's second quarter announcement on August 13. The management reiterated its full-year 2026 guidance, projecting topline figures between $900 million and $1 billion, along with positive adjusted EBITDA. Chief Executive Officer, Steve Altemus, reflected on the company's performance by stating:
"We delivered a strong quarter, highlighted by revenue over four times Q2 2025 as we executed across our programs, recorded unprecedented bookings and backlog, and positioned the Company for the next phase of growth."
Sergey Nivens/Shutterstock.com
The second quarter saw Intuitive Machines (NASDAQ:LUNR) posting record quarterly revenue figures of $206.17 million. This equates to a 310% growth compared to a $50.31 million topline during the same period last year. This can be attributed to execution across the company's commercial lunar payload services, omnibus multidisciplinary engineering services, near ****** e network services, and ****** ecraft production programs. During the second quarter, it booked additional $920 million of awards and ended the quarter with an order backlog of $1.8 billion. This represented a substantial jump compared with December-end backlog of $213.1 million. It is pertinent to highlight that $612.8 million of the total order backlog is linked to the company's acquisition of Lanteris, earlier in 2026.
The business mix exhibited a material shift during the second quarter. National security programs saw a notable jump in revenue contribution, accounting for roughly 30% of the topline compared to just 3% in Q2 2025. The company has been actively pursuing opportunities to expand its pipeline of defense and satellite communication programs. It recently received authorization to proceed on a $600 million multi-satellite communications infrastructure program. The company will leverage its IM 1300 satellite platform to design, manufacture, integrate, and support multiple ****** ecraft. This award validates the Intuitive Machines' IM 1300 platform for large-scale procurements, and strengthens its footprint in satellite communications infrastructure.
#intuitive #machines #company
2 months ago
It has been a tough year for NuScale Power (NYSE: SMR). Shares have fallen nearly 40% since 2026. One Wall Street **** yst remains unfazed.
In early August, Rinny Singh, an **** yst at Bank of America, reiterated her buy rating on SMR stock, setting a share price target of $12, implying roughly 24% upside over the next 12 months.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Why does Singh remain so bullish despite recent share price weakness? Her bull thesis comes down to one key catalyst -- a catalyst that may soon receive some much-needed momentum.
Singh's bull thesis on NuScale stock largely comes down to one critical factor: Can NuScale convert its customer pipeline into revenue-generating projects? The biggest mover from this perspective is the company's 6-gigawatt (GW) project with its financing partner, ENTRA1, and utility provider, the Tennessee Valley Authority (TVA).
#NVIDIA #analyst #Share #price

2 months ago
Shares of CrowdStrike Holdings, Inc. (NASDAQ:CRWD) have rallied more than 83% year-to-date as of September 3. The stock has significantly outperformed the broader S&P 500 Index, which has seen a 13% rise so far this year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has also returned more than 400% over the past three years.
Additionally, ******* ysts are positive on the stock, with a consensus Buy rating and a median 12-month price target of $240, suggesting about 13% upside from current levels.
On September 2, DA Davidson reiterated its Buy rating on CrowdStrike Holdings, Inc. (NASDAQ:CRWD) with a price target of $245 after attending the company's annual user conference, Fal.Con 2026, in Las Vegas.
DA Davidson said discussions with CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) customers and partners at the conference were positive. The firm noted signs of strong demand for AI Detection & Response, along with continued vendor consolidation on CrowdStrike. The conference also included several new product and partnership announcements.
The research firm expects the company to provide an early look at fiscal 2028 Net New ARR growth. This could give investors greater visibility into CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) longer-term growth prospects.
#holdings #year #Stock #positive

2 months ago
Shares of CrowdStrike Holdings, Inc. (NASDAQ:CRWD) have rallied more than 83% year-to-date as of September 3. The stock has significantly outperformed the broader S&P 500 Index, which has seen a 13% rise so far this year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has also returned more than 400% over the past three years.
Additionally, ******* ysts are positive on the stock, with a consensus Buy rating and a median 12-month price target of $240, suggesting about 13% upside from current levels.
On September 2, DA Davidson reiterated its Buy rating on CrowdStrike Holdings, Inc. (NASDAQ:CRWD) with a price target of $245 after attending the company's annual user conference, Fal.Con 2026, in Las Vegas.
DA Davidson said discussions with CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) customers and partners at the conference were positive. The firm noted signs of strong demand for AI Detection & Response, along with continued vendor consolidation on CrowdStrike. The conference also included several new product and partnership announcements.
The research firm expects the company to provide an early look at fiscal 2028 Net New ARR growth. This could give investors greater visibility into CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) longer-term growth prospects.
#crwd #Stock
2 months ago
Palantir Technologies' stock jumped approximately 8% on Thursday, recovering from the previous session's nearly 6% decline and trading near $183.
The rebound came even as prominent short-seller Michael Burry, known for his role in "The Big Short," renewed his long-standing bearish critique of the company.
In a detailed post on X early Thursday, Burry reiterated that Palantir is back in the stratosphere and that the facts have not changed. He described the firm as a consultant riding a bubble of AI FOMO demand and warned that its market cap could eventually fall well below $100 billion.
Burry focused on accounts receivable trends, noting that receivables had grown faster than revenue in 9 of the last 12 quarters, with one customer accounting for about 25% of receivables while contributing less than 10% of revenue.
He also highlighted rising days sales outstanding, deferred revenue patterns resembling those of consulting firms like Accenture rather than pure SaaS peers, elevated stock-based compensation, and large net operating losses. Burry disclosed that he remains short the stock and holds put options.
#Stock #revenue



2 months ago
Palladyne AI reported headline growth that looks dramatic: second-quarter revenue rose 470% year over year and 63% sequentially to $5.783 million. Palladyne AI Corp. (NASDAQ:PDYN) ended June with $24.6 million of backlog, up 43% during the quarter after roughly $13 million of new contract awards, net of revenue recognized. Management expects most of that backlog to become revenue over the next 12 to 18 months and reiterated 2026 revenue guidance of $24 million to $27 million, or 357% to 415% growth.
Copyright: ralwel / 123RF Stock Photo
The comparison needs an important qualification. Palladyne said the increase came from acquisitions as well as organic growth. Its 10-Q says second-quarter product revenue was derived mainly from businesses acquired in November 2025, while engineering-services revenue came from one acquired business. Revenue consisted of hardware products, development contracts, and engineering services; the filing explicitly says Palladyne had generated no software-product revenue to date. The quarter therefore does not yet demonstrate scaled sales of its proprietary autonomy software.
The bull case is that backlog and defense awards provide a bridge to that commercialization. Programs involving SwarmOS, Gremlin-X, BRAIN flight computers, and Air Force development work may deepen customer relationships. But award values do not become revenue immediately, and fixed-price development work can produce weak margins if actual costs exceed estimates. Palladyne separately put total estimated contract value at $30.9 million, but that broader figure includes unexercised options and should not be confused with firm backlog.
The loss profile remains severe. Operating loss widened to $13.413 million from $8.094 million a year earlier, and net loss reached $12.326 million. Palladyne held $33.774 million of cash and equivalents plus $9.972 million of marketable securities, totaling $43.746 million. Its reiterated full-year operating-cash-burn outlook was $32 million to $36 million; the company defines that measure as operating cash used plus capital expenditures.
#million #palladyne #quarter


2 months ago
Jefferies reiterated a Hold rating on Adobe Inc. (NASDAQ:ADBE) and raised the price target to $285 from $230 on August 30, citing expectations that the company will deliver results in line with expectations. The research firm has echoed the company's long-term prospects amid heightened focus on user acquisition and engagement.
During the second-quarter earnings call, management reiterated the new focus in response to the way artificial intelligence is changing the way users discover and buy creative and productivity tools. According to CEO Shantanu Narayen, AI is accelerating customer behavior, and Adobe must respond.
Therefore, the focus is on enabling friction-free onboarding for new users through "freemium" artificial intelligence offerings, rather than pushing them into direct paid journeys. Amid the new push, Jefferies expects Adobe to reiterate its fiscal 2026 outlook for 10.2% year-over-year growth in total ending ARR. The company also expects revenue of between $26.5 billion and $26.6 billion for fiscal 2026.
Adobe Inc. (NASDAQ:ADBE)'s opportunity hinges on its ability to turn Firefly, Acrobat AI, and AI-powered Creative Cloud features into monetized products, even as it focuses on attracting new users and enhancing engagement levels. The company is already seeing increasing Firefly adoption and AI-first ARR as Creative Cloud's huge installed base gives it millions of potential new AI customers.
Earlier on August 19, BofA reiterated an Underperform rating on Adobe and raised the price target to $220 from $190. BofA remains concerned that generative AI could pressure Adobe's longer-term growth as lower-cost, AI-native alternatives increase competition and Adobe's AI monetization has yet to materially accelerate overall growth. Additionally, its core products, including Photoshop, are under immense pressure from AI. Free or low cost AI native tools are making it harder for the company to expand its revenue base.
#adobe #creative #users #jefferies


2 months ago
On August 10, Joe Gomes from ***** le Capital reiterated his Outperform rating on CoreCivic Inc. (NYSE:CXW). In the process, the ***** yst increased his target price on the stock from $35 to $42, resulting in a revised upside potential in excess of 24% based on stock's closing price on August 27. This upward adjustment in price target came after an impressive second quarter print above management estimates. Let's explore the underlying drivers of this outperformance, and which additional factors are expected to shape up investor sentiment toward the stock.
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price