7 days ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


8 days ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money


8 days ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment


8 days ago
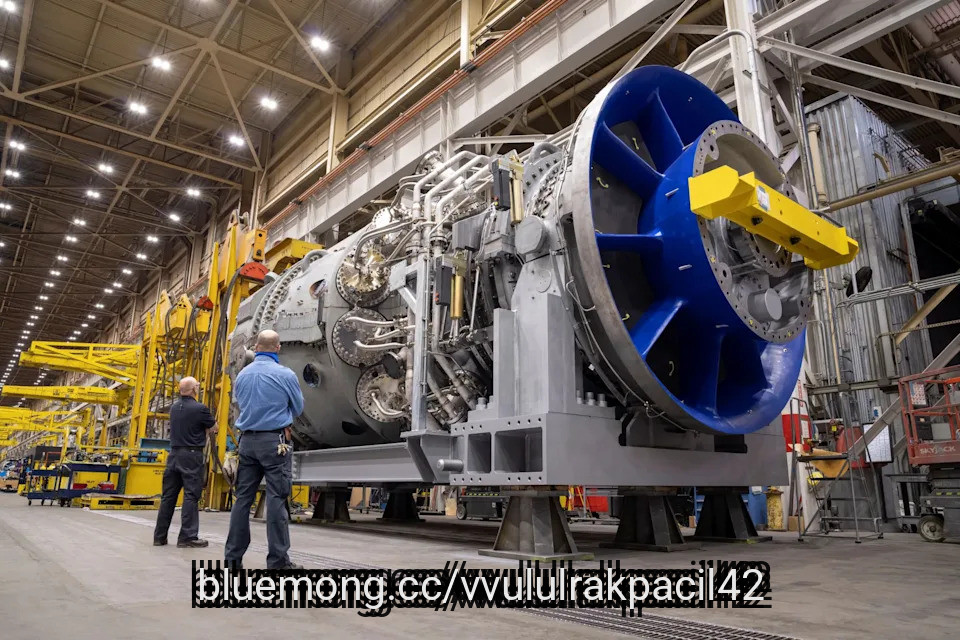
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

8 days ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib

8 days ago
During the September 14 episode of Mad Money, Jim Cramer addressed the broader tech sector pullback and mentioned Broadcom Inc. (NASDAQ:AVGO) as an attractive option for investors looking past short-term volatility. He stated:
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ
8 days ago
The Hain Celestial Group, Inc. (NASDAQ:HAIN) announced on September 14 that it agreed to sell most international operations to AURELIUS for estimated cash consideration of $323 million. Expected net proceeds of $305 million to $310 million would repay debt and leave a business concentrated in North America.
The immediate hurdle is financing. The agreement, signed September 12, requires a credit-agreement amendment by October 12 extending the December 22, 2026 maturity by at least nine months. AURELIUS can terminate if that amendment is not secured by the deadline.
The Hain Celestial Group, Inc. (NASDAQ:HAIN) expects closing in its fiscal second quarter ending December 31, subject to lender agreement and regulatory approvals. The dollar consideration estimates also depend on exchange rates because the purchase price is denominated in sterling.
The transaction could materially reduce the debt burden. The Hain Celestial Group, Inc. (NASDAQ:HAIN) reported $558 million of total debt as of June 30. Subtracting the estimated net proceeds implies approximately $248 million to $253 million remaining, a calculation using rounded figures before subsequent borrowings, repayments, or other changes.
That reduction could lower interest expense and give management more room to stabilize the retained brands. The remaining portfolio includes Celestial Seasonings tea, The Greek Gods yogurt and Earth's Best baby and kids foods.
#december
The immediate hurdle is financing. The agreement, signed September 12, requires a credit-agreement amendment by October 12 extending the December 22, 2026 maturity by at least nine months. AURELIUS can terminate if that amendment is not secured by the deadline.
The Hain Celestial Group, Inc. (NASDAQ:HAIN) expects closing in its fiscal second quarter ending December 31, subject to lender agreement and regulatory approvals. The dollar consideration estimates also depend on exchange rates because the purchase price is denominated in sterling.
The transaction could materially reduce the debt burden. The Hain Celestial Group, Inc. (NASDAQ:HAIN) reported $558 million of total debt as of June 30. Subtracting the estimated net proceeds implies approximately $248 million to $253 million remaining, a calculation using rounded figures before subsequent borrowings, repayments, or other changes.
That reduction could lower interest expense and give management more room to stabilize the retained brands. The remaining portfolio includes Celestial Seasonings tea, The Greek Gods yogurt and Earth's Best baby and kids foods.
#december


8 days ago
Exodus Movement, Inc. (NYSEAMERICAN:EXOD) reported on September 11 that August payment-processing gross transaction volume reached $356.8 million, up from $338.0 million in July. Monthly active cards declined to 757,900 from 783,600.
Separately, Web3 exchange-provider processed volume increased to $376.8 million from $314.8 million, while reported monthly active users remained at 1.4 million. The figures show stronger transaction activity alongside fewer active cards and a stable reported user count.
The question is whether that activity produces enough revenue to improve profitability while Exodus Movement, Inc. (NYSEAMERICAN:EXOD) integrates Monavate and reduces costs.
Payment growth persists after adjusting for currency translation. Exodus Movement, Inc. (NYSEAMERICAN:EXOD) converted sterling payment volumes into dollars using average rates of $1.35 per pound for August and $1.34 for July. Reversing those conversions implies approximately 4.8% growth in underlying sterling volume, compared with 5.6% in reported dollars. Both calculations use rounded disclosed figures.
Web3 exchange-provider volume increased approximately 19.7%. XO Swap partners contributed 23% of volume in both months. The unchanged reported share suggests both the partner channel and the remaining business contributed to growth.
#reported #exodus #nyseamerican
Separately, Web3 exchange-provider processed volume increased to $376.8 million from $314.8 million, while reported monthly active users remained at 1.4 million. The figures show stronger transaction activity alongside fewer active cards and a stable reported user count.
The question is whether that activity produces enough revenue to improve profitability while Exodus Movement, Inc. (NYSEAMERICAN:EXOD) integrates Monavate and reduces costs.
Payment growth persists after adjusting for currency translation. Exodus Movement, Inc. (NYSEAMERICAN:EXOD) converted sterling payment volumes into dollars using average rates of $1.35 per pound for August and $1.34 for July. Reversing those conversions implies approximately 4.8% growth in underlying sterling volume, compared with 5.6% in reported dollars. Both calculations use rounded disclosed figures.
Web3 exchange-provider volume increased approximately 19.7%. XO Swap partners contributed 23% of volume in both months. The unchanged reported share suggests both the partner channel and the remaining business contributed to growth.
#reported #exodus #nyseamerican

9 days ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

9 days ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

9 days ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september

9 days ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity

9 days ago
NEW YORK, Sept 16 (Reuters) - The Federal Reserve raised interest rates on Wednesday and flagged further increases in borrowing costs in coming months, with new US central bank chief Kevin Warsh joining a unanimous decision that effectively acknowledges the Trump administration's inability so far to control inflation.
Speaking in Washington after the decision's release, Warsh echoed the official statement in promising the Fed's policy committee would "deliver price stability." Stocks and bonds sold off late Wednesday afternoon, reflecting expectations that rates may continue to rise for some time.
New policy projections showed 16 of 18 policymakers anticipate at least one more quarter-percentage-point hike by the end of this year, with only two of them seeing rates remaining stable from here. Warsh apparently again did not submit a rate projection.
It's the first policy shift under the new Fed chief, who took office in late May after being selected by Trump with an expectation that he would cut rates.
The Fed's new policy statement and economic projections, to the contrary, show a central bank opening the door on tighter monetary policy through next year, with the policy rate rising to the 4.00%-4.25% range by the end of this year and ending 2027 at the same level.
#rates #warsh #year #chief
Speaking in Washington after the decision's release, Warsh echoed the official statement in promising the Fed's policy committee would "deliver price stability." Stocks and bonds sold off late Wednesday afternoon, reflecting expectations that rates may continue to rise for some time.
New policy projections showed 16 of 18 policymakers anticipate at least one more quarter-percentage-point hike by the end of this year, with only two of them seeing rates remaining stable from here. Warsh apparently again did not submit a rate projection.
It's the first policy shift under the new Fed chief, who took office in late May after being selected by Trump with an expectation that he would cut rates.
The Fed's new policy statement and economic projections, to the contrary, show a central bank opening the door on tighter monetary policy through next year, with the policy rate rising to the 4.00%-4.25% range by the end of this year and ending 2027 at the same level.
#rates #warsh #year #chief


9 days ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still

10 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company

10 days ago
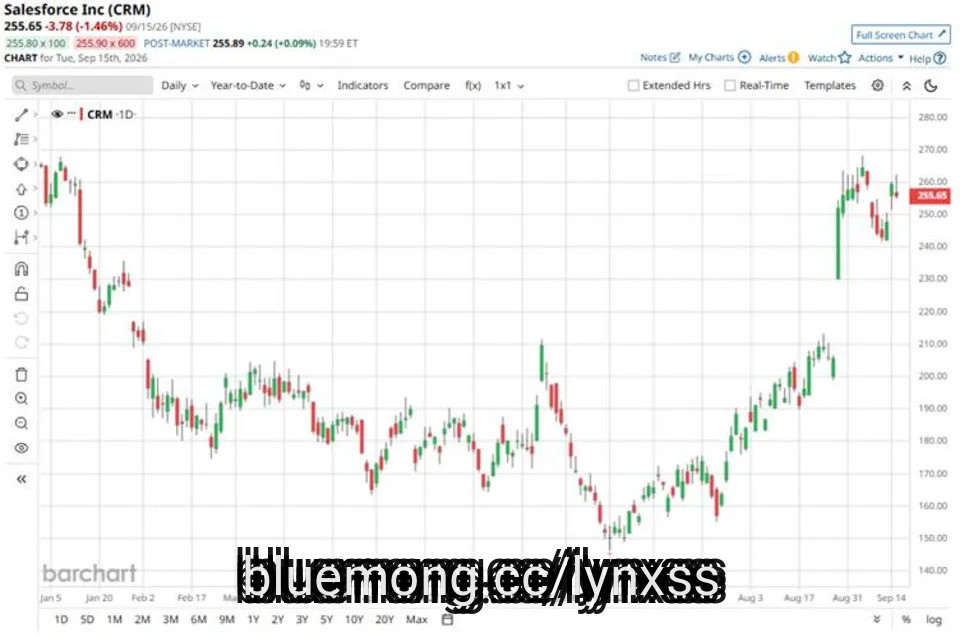
Salesforce (CRM) investors have an important date to watch as the company prepares to host its Investor & ****** yst Session on Wednesday, Sept. 16, during Dreamforce 2026. The event comes at a critical time for Salesforce as investors look for greater clarity on how the company plans to turn rapid artificial intelligence (AI) adoption into sustainable revenue growth. Salesforce recently delivered a strong second-quarter fiscal 2027 report, with current remaining performance obligations rising 14% and management raising its full-year revenue guidance.
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue


10 days ago
Adobe (ADBE) reported a record fiscal Q3 2026 and raised its fiscal 2026 revenue and earnings targets. Revenue rose 13% as reported to $6.76 billion, above the $6.70 billion the company had guided. But the key figure that did not move is the one to hold the quarter against: the fiscal 2026 target for growth in ending annualized recurring revenue, or ARR, still 10.2%.
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative

10 days ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


10 days ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


10 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700

10 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
11 days ago
The fate of Ed Sheeran's Loop Tour is suddenly uncertain after all of the British singer's remaining opening acts quit in solidarity with the rapper Macklemore, who was dropped from the remaining North American dates over pro-Palestinian comments.
Hours after Sheeran released a statement saying it was the promoter's decision to remove Macklemore from the tour and not his, the rest of his supporting acts — Irish singer Aaron Rowe, Danish pop band Lukas Graham and songwriter Finneas — as well as Sheeran's house band, Beoga, announced that they were pulling out in protest.
"Artists must not be silenced when they speak up for the oppressed," Finneas, the brother of Billie Eilish, wrote in a note posted to Instagram. "I have decided to withdraw from my upcoming tour dates with Ed Sheeran. I stand with Palestine and its people."
The Irish artists cited their country's history of oppression in their decisions to drop out.
"I don't take the decision lightly. Ed has been a friend to me and has changed my life, I could never thank him enough for this," Rowe wrote in his own Instagram post. "But as Irish people we know all too well about genocide, forced famine and violent occupation. I cannot stand by and allow billionaires to use their position of power to silence the rightful voices of those who speak up against Israeli genocide and who highlight the savage murder of children."
#irish #Instagram
Hours after Sheeran released a statement saying it was the promoter's decision to remove Macklemore from the tour and not his, the rest of his supporting acts — Irish singer Aaron Rowe, Danish pop band Lukas Graham and songwriter Finneas — as well as Sheeran's house band, Beoga, announced that they were pulling out in protest.
"Artists must not be silenced when they speak up for the oppressed," Finneas, the brother of Billie Eilish, wrote in a note posted to Instagram. "I have decided to withdraw from my upcoming tour dates with Ed Sheeran. I stand with Palestine and its people."
The Irish artists cited their country's history of oppression in their decisions to drop out.
"I don't take the decision lightly. Ed has been a friend to me and has changed my life, I could never thank him enough for this," Rowe wrote in his own Instagram post. "But as Irish people we know all too well about genocide, forced famine and violent occupation. I cannot stand by and allow billionaires to use their position of power to silence the rightful voices of those who speak up against Israeli genocide and who highlight the savage murder of children."
#irish #Instagram


11 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
11 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
11 days ago
Anthropic is moving forward with plans for an initial public offering that could value the company at $2 trillion, with signs pointing to the listing remaining on track, according to Bloomberg. Nasdaq has been selected as the venue for the listing, and Nvidia is reportedly weighing a contribution of around $10 billion to the offering.
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according


11 days ago
BAGHDAD (AP) — Two deadlines are looming for Iraq at the end of the month: the end of a decades-long U.S. military presence and the disarmament of non-state armed groups.
The U.S. withdrawal is underway, and officials say the hundreds of troops remaining in northern Iraq will be out by the Sept. 30 deadline.
The Iraqi government has linked the U.S. withdrawal to an ultimatum for militias to lay down their weapons. But most have indicated they have no plans to do so.
That leaves major questions about what the day after will look like in Iraq.
Iranian-backed Iraqi militias have struck U.S.-linked targets both inside and outside of Iraq since the U.S. and Israel attacked Iran on Feb. 28. They also have coordinated with Yemen's Houthi rebels to attack Saudi Arabia.
#sept #iranian
The U.S. withdrawal is underway, and officials say the hundreds of troops remaining in northern Iraq will be out by the Sept. 30 deadline.
The Iraqi government has linked the U.S. withdrawal to an ultimatum for militias to lay down their weapons. But most have indicated they have no plans to do so.
That leaves major questions about what the day after will look like in Iraq.
Iranian-backed Iraqi militias have struck U.S.-linked targets both inside and outside of Iraq since the U.S. and Israel attacked Iran on Feb. 28. They also have coordinated with Yemen's Houthi rebels to attack Saudi Arabia.
#sept #iranian




11 days ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed

11 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
11 days ago
Willing and Abel: Berkshire's New CEO Makes Huge Portfolio Changes in Q1
American Express raised its 2026 revenue-growth outlook toward 10% after reporting strong first-half trends, including 10% foreign-exchange-adjusted revenue growth, mid-teens EPS growth, 16% card-fee growth and double-digit net interest income growth.
The company plans to direct better-than-expected performance toward customer acquisition, technology and product development, while maintaining long-term aspirations of 10% revenue growth and mid-teens EPS growth.
International, travel and younger-cardmember growth remain key opportunities: international billings have risen about 50% in three years, travel spending is contributing to growth, and Millennials and Gen Z represent 65% of new accounts, with credit metrics remaining stable.
Capital One's Big Bet Faces Rising Credit Risk
#Growth #international #travel #makes
American Express raised its 2026 revenue-growth outlook toward 10% after reporting strong first-half trends, including 10% foreign-exchange-adjusted revenue growth, mid-teens EPS growth, 16% card-fee growth and double-digit net interest income growth.
The company plans to direct better-than-expected performance toward customer acquisition, technology and product development, while maintaining long-term aspirations of 10% revenue growth and mid-teens EPS growth.
International, travel and younger-cardmember growth remain key opportunities: international billings have risen about 50% in three years, travel spending is contributing to growth, and Millennials and Gen Z represent 65% of new accounts, with credit metrics remaining stable.
Capital One's Big Bet Faces Rising Credit Risk
#Growth #international #travel #makes

12 days ago
A'ja Wilson and Aces could steal No. 2 seed during final WNBA week originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
The most dangerous team entering the WNBA playoffs may not be the one sitting atop the standings. Las Vegas returns from the World Cup break with a 27-13 record and a three-game winning streak. The Aces currently occupy the No. 3 seed, but a favorable closing schedule gives them a legitimate opportunity to pass Golden State for second.
Las Vegas trails the Valkyries by two games with four remaining. The Aces own the head-to-head tiebreaker after sweeping their three regular-season meetings with Golden State.
If Las Vegas gains two games during the final week, it would move into the No. 2 seed. The Aces will not face another playoff team before the postseason begins.
They play consecutive games against Seattle, beginning Thursday at Climate Pledge Arena and continuing Sunday in Las Vegas. The Aces then host Los Angeles before completing the regular season at Phoenix.
#games #WNBA
The most dangerous team entering the WNBA playoffs may not be the one sitting atop the standings. Las Vegas returns from the World Cup break with a 27-13 record and a three-game winning streak. The Aces currently occupy the No. 3 seed, but a favorable closing schedule gives them a legitimate opportunity to pass Golden State for second.
Las Vegas trails the Valkyries by two games with four remaining. The Aces own the head-to-head tiebreaker after sweeping their three regular-season meetings with Golden State.
If Las Vegas gains two games during the final week, it would move into the No. 2 seed. The Aces will not face another playoff team before the postseason begins.
They play consecutive games against Seattle, beginning Thursday at Climate Pledge Arena and continuing Sunday in Las Vegas. The Aces then host Los Angeles before completing the regular season at Phoenix.
#games #WNBA