2 days ago
President Donald Trump has been in the White House for nearly six years, spanning two nonconsecutive terms. Over that time, the iconic Dow Jones Industrial Average (DJINDICES:^DJI), benchmark S&P 500 (SNPINDEX:^GSPC), and growth-dependent Nasdaq Composite (NASDAQINDEX:^IXIC) have delivered well-above-average annual returns, compared to most other presidents since the late 1890s.
One of the key catalysts powering Wall Street's bull market, the artificial intelligence (AI) infrastructure build-out, was well underway before Trump's second term began. But make no mistake about it: Wall Street and investors have also benefited immensely from the president's Tax Cuts and Jobs Act (signed into law in December 2017), which lowered the peak marginal corporate income tax rate to 21% (the lowest rate since 1939), fueling record S&P 500 share buybacks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
President Trump's tariff and trade policy may be doing more harm than good. Image source: Official White House Photo by Molly Riley.
President Trump has also made tariffs a huge part of his economic growth plan. Said Trump,
#Trump #NVIDIA #white #House
One of the key catalysts powering Wall Street's bull market, the artificial intelligence (AI) infrastructure build-out, was well underway before Trump's second term began. But make no mistake about it: Wall Street and investors have also benefited immensely from the president's Tax Cuts and Jobs Act (signed into law in December 2017), which lowered the peak marginal corporate income tax rate to 21% (the lowest rate since 1939), fueling record S&P 500 share buybacks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
President Trump's tariff and trade policy may be doing more harm than good. Image source: Official White House Photo by Molly Riley.
President Trump has also made tariffs a huge part of his economic growth plan. Said Trump,
#Trump #NVIDIA #white #House



27 days ago
Like most Gen X-ers, 51-year-old Angelina Jolie likely had to study penmanship in elementary school. (As a fellow Gen X-er, I can attest that this particular class often lowered my grade point average.) But now that many schools place less emphasis on cursive, younger generations might struggle not only to write it, but to read it, too.
A recent post on the How Everything Works Instagram page shared a thank-you note reportedly written by Jolie for hotel staff. As the note goes viral, many have weighed in, calling it mostly illegible. This is causing quite a stir between generations, with some blaming a lack of education on this subject as the culprit.
The original poster added, for context, "Angelina Jolie left a handwritten thank you note for the staff after staying at a luxury hotel, but the internet quickly became more interested in trying to read it. Her distinctive cursive proved so difficult to decipher that people began sharing their guesses about what the note actually said, turning a simple message into an unexpected online puzzle. Some words were easier to make out than others, but the handwriting became the main attraction, with fans collectively trying to decode the entire note. What started as a thoughtful gesture from Jolie ended up becoming a viral guessing game over her handwriting."
Many commenters tried to transcribe the letter, which appears to have first been shared back in October, 2023. One commenter immediately notes how difficult it might be for Gen Z to read it. She first shares her take on what the note says. "'Thank you for a restful stay at your beautiful resort. The 'Maria' crew had a lovely time here. With love, Angelina Jolie' — With some context and if you know cursive, you can make most of it out. I don't think any GenZ's would know what this said."
Others suggested it was some kind of medical professional "script." This Instagrammer explains, in part, " This is NOT script. It's just her sloppy 'style' of writing. Yes. I'm a nurse."
#angelina #cursive #others
A recent post on the How Everything Works Instagram page shared a thank-you note reportedly written by Jolie for hotel staff. As the note goes viral, many have weighed in, calling it mostly illegible. This is causing quite a stir between generations, with some blaming a lack of education on this subject as the culprit.
The original poster added, for context, "Angelina Jolie left a handwritten thank you note for the staff after staying at a luxury hotel, but the internet quickly became more interested in trying to read it. Her distinctive cursive proved so difficult to decipher that people began sharing their guesses about what the note actually said, turning a simple message into an unexpected online puzzle. Some words were easier to make out than others, but the handwriting became the main attraction, with fans collectively trying to decode the entire note. What started as a thoughtful gesture from Jolie ended up becoming a viral guessing game over her handwriting."
Many commenters tried to transcribe the letter, which appears to have first been shared back in October, 2023. One commenter immediately notes how difficult it might be for Gen Z to read it. She first shares her take on what the note says. "'Thank you for a restful stay at your beautiful resort. The 'Maria' crew had a lovely time here. With love, Angelina Jolie' — With some context and if you know cursive, you can make most of it out. I don't think any GenZ's would know what this said."
Others suggested it was some kind of medical professional "script." This Instagrammer explains, in part, " This is NOT script. It's just her sloppy 'style' of writing. Yes. I'm a nurse."
#angelina #cursive #others

1 month ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

1 month ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ


1 month ago
Merck (MRK) stock returned about 87% over the past twelve months, climbing from roughly $79 to about $147. Nothing in the year's results looks like that. The medicines Merck sells today grew at their usual pace. Investors spent the year repricing what comes next.
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson
Revenue over the trailing twelve months was $66.6 billion, up 4.6% and in line with its own three-year pace. Profitability did not follow. Its operating margin over the same twelve months was 10.5%, versus a three-year average of 22.4%.
Most of that gap is one purchase. Merck took a $5.7 billion charge in the second quarter of 2026, about 9% of a year's sales. It bought Terns Pharmaceuticals, and with it MK-4208, a candidate for chronic myeloid leukemia. The bill hits earnings now and the medicine arrives later.
The proof matters because of the risk hanging over this stock. The KEYTRUDA family was just over half of Merck's revenue in the second quarter of 2026. The company is openly planning for the end of that exclusivity when Keytruda loses primary U.S. patent protection in 2028. Management describes the stretch as more of a hill than a cliff, with a shallow dip and a fast return to growth.
Johnson & Johnson (JNJ) returned 56% over the same twelve months and Pfizer (PFE) 23%, so a good year for pharmaceuticals explains some of this but not Merck's lead. What separated Merck was evidence. The FDA approved LIPFENDRA, the first and only oral PCSK9 inhibitor. In the CORALreef Lipids trial it lowered LDL cholesterol by up to 60% when added to a statin.
#year #johnson


1 month ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter


1 month ago
Lyft (LYFT) stock has been in a sharp downtrend this month, but senior Guggenheim ****** yst Michael Morris believes a swift near-term recovery is unlikely. In a research note this morning, Morris downgraded LYFT to "Neutral" and lowered his price target to $16, signaling a lack of meaningful upside from current levels.
At the time of writing, Lyft shares are already down about 23% versus the start of this year.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#lyft
At the time of writing, Lyft shares are already down about 23% versus the start of this year.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#lyft


2 months ago
Lululemon fell 18% after Meghan Frank delivered a second guidance cut, dropping the full-year EPS outlook to roughly $9.60 from last year's $13.26.
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook



2 months ago
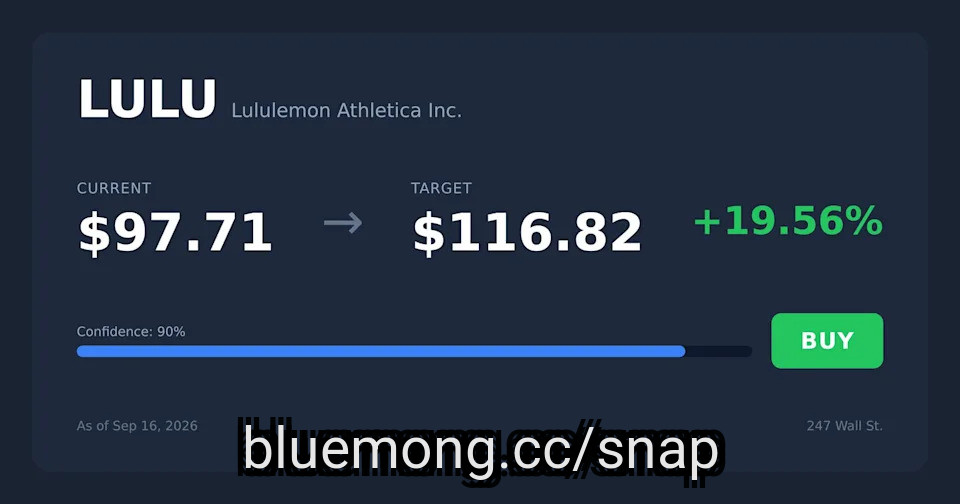
PepsiCo (PEP) has gone nowhere for a year, down 1.8% over the past twelve months while the S&P 500 returned 16.6%. At about $135 a share it trades at 17.7 times earnings, against an S&P 500 median of 22.5. A big cash generator priced below the market is what value buyers hunt for, so is this discount impatience or a verdict?
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing

2 months ago
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four


2 months ago
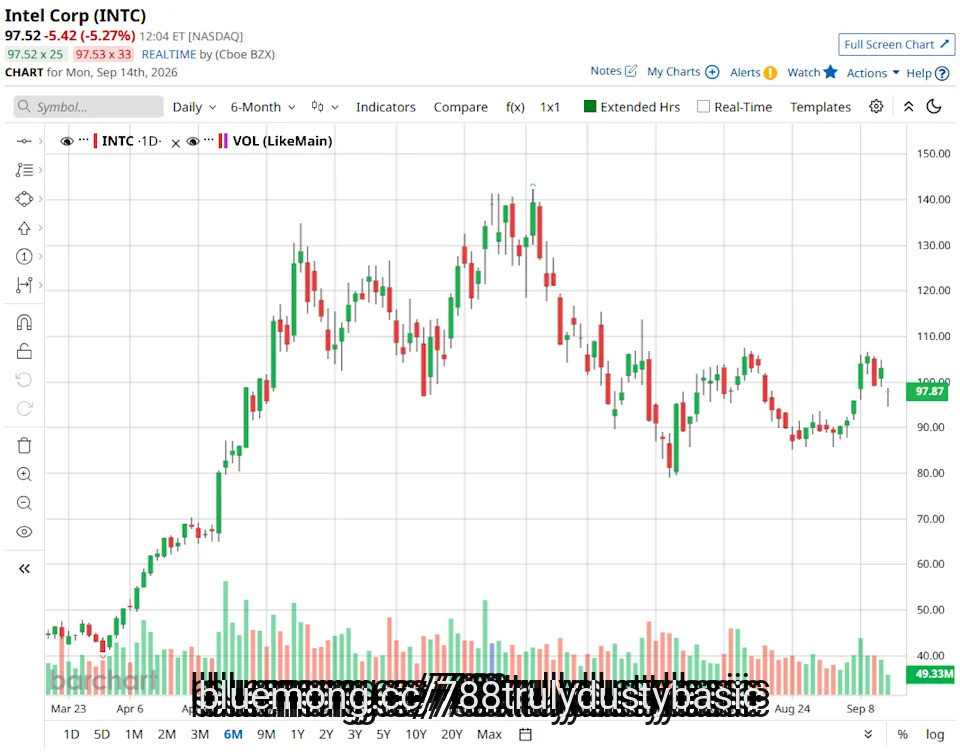
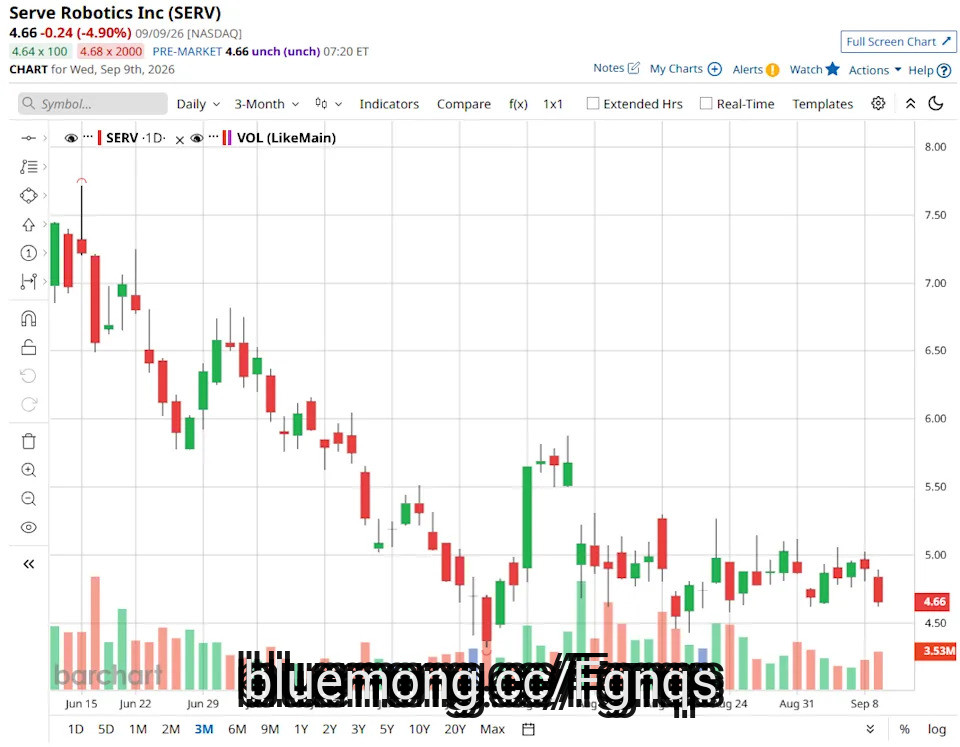
Serve Robotics (SERV) shares have tumbled roughly 20% since the autonomous delivery company lowered its 2026 revenue guidance on Aug. 6. The cut came despite quarterly revenue surging 404% year-over-year (YOY). Serve Robotics also said it may not renew its foundational partnership with Uber (UBER) after it expires in early 2027. The development follows Serve's first decline in Uber Eats delivery volume in 17 consecutive quarters. However, Serve has $240 million in cash and is intentionally expanding into DoorDash (DASH), healthcare robotics, and advertising. The debate now is whether the reset reflects deeper trouble or a strategic effort to diversify beyond a weakening partnership.
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company


2 months ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen

2 months ago
Something strange is currently happening with interest rates and inflation.
The United States Federal Funds Rate -- essentially the price banks charge each other to borrow money overnight -- currently sits at 3.75%. The rate has remained at 3.75% throughout 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For much of 2023 and 2024, the Fed Funds Rate was pegged at 5.5% to battle stubbornly high inflation. As inflation fears eased, the rate was gradually lowered to today's 3.75% level.
Despite a low and stable Fed Funds Rate, however, mortgage interest rates have begun to climb. According to the Wall Street Journal, average U.S. mortgage rates have climbed to a 15-month high of nearly 7%. Treasury yields, meanwhile, are approaching multi-year highs.
#NVIDIA #high
The United States Federal Funds Rate -- essentially the price banks charge each other to borrow money overnight -- currently sits at 3.75%. The rate has remained at 3.75% throughout 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For much of 2023 and 2024, the Fed Funds Rate was pegged at 5.5% to battle stubbornly high inflation. As inflation fears eased, the rate was gradually lowered to today's 3.75% level.
Despite a low and stable Fed Funds Rate, however, mortgage interest rates have begun to climb. According to the Wall Street Journal, average U.S. mortgage rates have climbed to a 15-month high of nearly 7%. Treasury yields, meanwhile, are approaching multi-year highs.
#NVIDIA #high


2 months ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
2 months ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
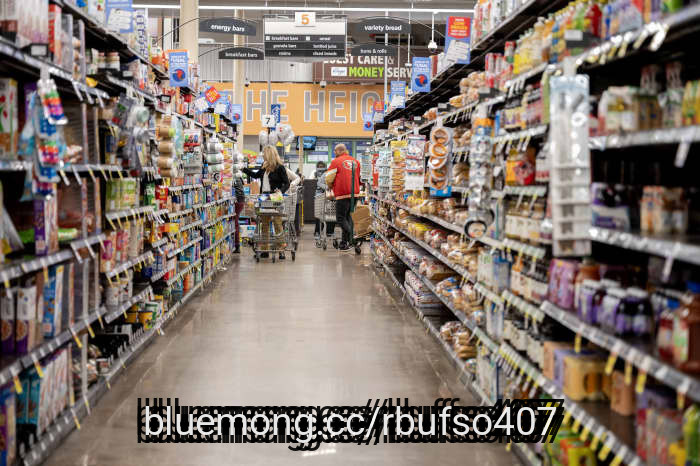
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare

2 months ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap

2 months ago
First Citizens BancShares, Inc. (NASDAQ:FCNCA), through its First-Citizens Bank & Trust Company subsidiary, completed the acquisition of 138 BMO Bank N.A. branches on September 4. The locations span 11 states across the Midwest, Great Plains and West.
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens



2 months ago
Royalty Pharma plc (NASDAQ:RPRX) disclosed that pelacarsen failed the Phase 3 Lp(a)HORIZON cardiovascular-outcomes trial conducted by Novartis AG (NYSE:NVS). The randomized, double-blind study enrolled 8,323 patients with elevated lipoprotein(a), or Lp(a), and established cardiovascular disease.
Pelacarsen lowered Lp(a), but the study did not meet its primary endpoint of reducing cardiovascular events compared with placebo in the overall population. The endpoint combined cardiovascular death, nonfatal heart attack, nonfatal stroke, and urgent coronary revascularization requiring hospitalization. Complete results have not yet been presented.
Royalty Pharma plc (NASDAQ:RPRX) provided Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) with $500 million in January 2023. The transaction allocated $150 million to pelacarsen royalties and $350 million to Spinraza royalties. The clinical failure shifts the financial focus from uncertain pelacarsen upside to recovery through Spinraza.
Royalty Pharma plc (NASDAQ:RPRX) acquired 25% of the Spinraza royalties received by Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) through 2027. That share increases to 45% in 2028 on Spinraza annual sales of up to $1.5 billion.
Following the HORIZON result, the Spinraza interest will revert after aggregate payments to Royalty Pharma plc (NASDAQ:RPRX) reach $550 million, equal to 1.1 times the original funding. Management expects the structure to recover the entire investment and generate a modest positive return despite the clinical failure.
#royalty #pharma #cardiovascular #horizon
Pelacarsen lowered Lp(a), but the study did not meet its primary endpoint of reducing cardiovascular events compared with placebo in the overall population. The endpoint combined cardiovascular death, nonfatal heart attack, nonfatal stroke, and urgent coronary revascularization requiring hospitalization. Complete results have not yet been presented.
Royalty Pharma plc (NASDAQ:RPRX) provided Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) with $500 million in January 2023. The transaction allocated $150 million to pelacarsen royalties and $350 million to Spinraza royalties. The clinical failure shifts the financial focus from uncertain pelacarsen upside to recovery through Spinraza.
Royalty Pharma plc (NASDAQ:RPRX) acquired 25% of the Spinraza royalties received by Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) through 2027. That share increases to 45% in 2028 on Spinraza annual sales of up to $1.5 billion.
Following the HORIZON result, the Spinraza interest will revert after aggregate payments to Royalty Pharma plc (NASDAQ:RPRX) reach $550 million, equal to 1.1 times the original funding. Management expects the structure to recover the entire investment and generate a modest positive return despite the clinical failure.
#royalty #pharma #cardiovascular #horizon


2 months ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
2 months ago
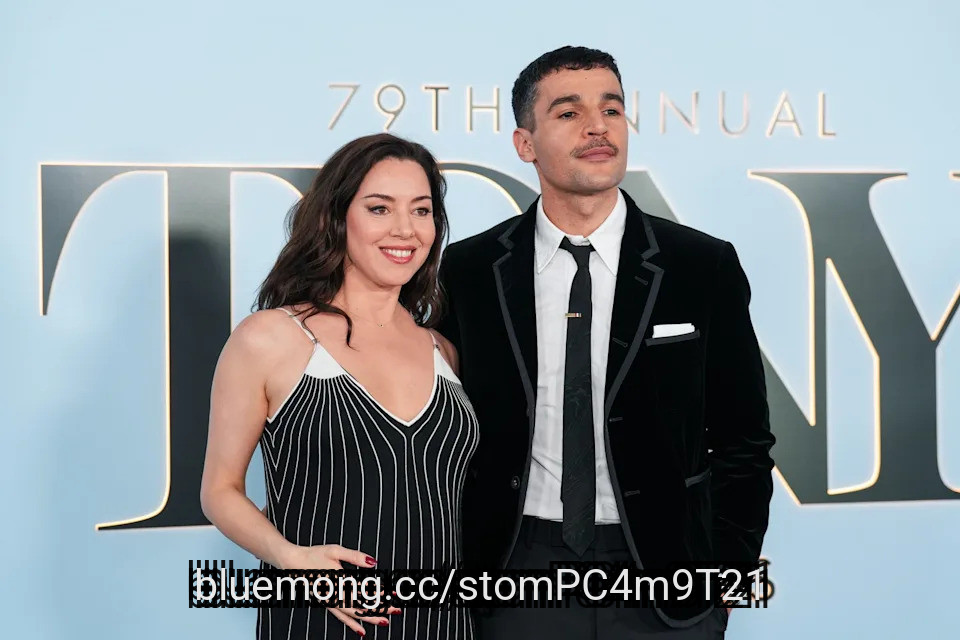
Actress Aubrey Plaza offloaded the Los Angeles property her late spouse Jeff Baena died in by suicide for $4.4 million—nearly one year after she put it on the market for $6.5 million.
Plaza, 42, who is recently gave birth to her first child with partner Christopher Abbott, originally purchased the home for $4.7 million in October 2022, when it became a marital home for the onscreen star and Baena.
However, in January 2025, Baena tragically died by suicide inside the property, and eight months later, Plaza chose to put it on the market, with an asking price of $6.5 million. That ask was lowered to $5.75 million just a few months later.
Still, the actress struggled to find a buyer—with sources telling Realtor.com® at the time that, while the four-bedroom abode had come under offer several times, the deals always fell through before they could officially close.
By May of this year, the property had been removed from the market altogether, before being relisted a few days later, with a new agent—Carl Gambino of The Gambino Group at Compass—and a much lower asking price: $5.3 million.
#plaza #baena #market #died
Plaza, 42, who is recently gave birth to her first child with partner Christopher Abbott, originally purchased the home for $4.7 million in October 2022, when it became a marital home for the onscreen star and Baena.
However, in January 2025, Baena tragically died by suicide inside the property, and eight months later, Plaza chose to put it on the market, with an asking price of $6.5 million. That ask was lowered to $5.75 million just a few months later.
Still, the actress struggled to find a buyer—with sources telling Realtor.com® at the time that, while the four-bedroom abode had come under offer several times, the deals always fell through before they could officially close.
By May of this year, the property had been removed from the market altogether, before being relisted a few days later, with a new agent—Carl Gambino of The Gambino Group at Compass—and a much lower asking price: $5.3 million.
#plaza #baena #market #died


2 months ago
General Motors Company (NYSE:GM) reached a tentative three-year labor deal with Unifor that Canadian workers ratified on August 29 and 30, securing more than C$1 billion ($791 million) in new and previously announced investment across Ontario, covering over 4,600 workers.
GM will spend C$144 million to bring next-generation Heavy-Duty GMC Sierra production to Oshawa, adding to a previously committed C$343 million there. At St. Catharines, GM will invest C$215 million in a new transmission program starting late 2029, on top of a previously announced C$691 million for V8 engine production. GM also pledged not to immediately sell or close its CAMI plant in Ingersoll while it studies alternatives, including possible defense work if it lands a Canadian Armed Forces contract. The deal lands as Canada's auto sector faces 25% U.S. tariffs, with Trump threatening to double that to 50% on January 1, 2027, and U.S. and Canada trade talks still stalled.
General Motors Company (NYSE:GM) enters this deal from a position of financial strength. GM beat second-quarter expectations with adjusted earnings per share of $3.57 versus the $3.18 estimate and revenue of $48 billion versus the $46.99 billion forecast. The company also raised its full-year guidance for the second time this year, while adjusted automotive free cash flow reached $5 billion, up $2.2 billion year over year. That cash generation gives GM room to fund its Canadian commitments without putting significant pressure on its balance sheet.
The tariff environment has also become more favorable for GM. After the Supreme Court invalidated tariffs imposed under emergency powers, GM lowered its full-year gross tariff-cost estimate to $2.5 billion-$3.5 billion from $3 billion-$4 billion. Protecting Canadian production now could reduce the risk of costly disruptions as GM adjusts its North American manufacturing footprint and responds to changing trade policies.
The agreement also protects GM's pickup and SUV business, which generates some of the company's highest margins. CEO Mary Barra said North American demand remains strong for these vehicles, while the return of Heavy-Duty Sierra production to Oshawa will give GM additional North American capacity for a key product line. Producing more trucks within the region could also help GM reduce its exposure to cross-border tariff costs.
#million
GM will spend C$144 million to bring next-generation Heavy-Duty GMC Sierra production to Oshawa, adding to a previously committed C$343 million there. At St. Catharines, GM will invest C$215 million in a new transmission program starting late 2029, on top of a previously announced C$691 million for V8 engine production. GM also pledged not to immediately sell or close its CAMI plant in Ingersoll while it studies alternatives, including possible defense work if it lands a Canadian Armed Forces contract. The deal lands as Canada's auto sector faces 25% U.S. tariffs, with Trump threatening to double that to 50% on January 1, 2027, and U.S. and Canada trade talks still stalled.
General Motors Company (NYSE:GM) enters this deal from a position of financial strength. GM beat second-quarter expectations with adjusted earnings per share of $3.57 versus the $3.18 estimate and revenue of $48 billion versus the $46.99 billion forecast. The company also raised its full-year guidance for the second time this year, while adjusted automotive free cash flow reached $5 billion, up $2.2 billion year over year. That cash generation gives GM room to fund its Canadian commitments without putting significant pressure on its balance sheet.
The tariff environment has also become more favorable for GM. After the Supreme Court invalidated tariffs imposed under emergency powers, GM lowered its full-year gross tariff-cost estimate to $2.5 billion-$3.5 billion from $3 billion-$4 billion. Protecting Canadian production now could reduce the risk of costly disruptions as GM adjusts its North American manufacturing footprint and responds to changing trade policies.
The agreement also protects GM's pickup and SUV business, which generates some of the company's highest margins. CEO Mary Barra said North American demand remains strong for these vehicles, while the return of Heavy-Duty Sierra production to Oshawa will give GM additional North American capacity for a key product line. Producing more trucks within the region could also help GM reduce its exposure to cross-border tariff costs.
#million

2 months ago
On August 6, Xponential Fitness (NYSE:XPOF) reported results for the second quarter ended June 30, and the numbers came in well short of where the boutique-fitness franchisor wanted to be. Revenue fell 13% year over year to $66 million, and the company swung to a net loss of $4.8 million after posting net income in the same period last year. CEO Mike Nuzzo said the quarter came in "below expectations." The bigger story sits in the outlook section, where the company trimmed nearly every full-year target it had set.
Despite the weak headline numbers, Xponential kept adding to its network. The company opened 67 gross new studios and sold 53 franchise licenses during the quarter, a sign that franchisee demand for its brands hasn't disappeared. North America system-wide sales held essentially flat at $437.3 million, which means new locations are offsetting some of the softness at existing studios rather than the whole system contracting. Even after cutting its 2026 targets, the company still expects to open roughly 150 net new studios for the year and generate North America system-wide sales of $1.7 billion to $1.75 billion. Full-year adjusted EBITDA guidance, while lowered, still points to $91 million to $97 million, meaning the business is still projected to be solidly profitable on that measure.
The details underneath the topline number are worse than the revenue decline alone suggests. North America same-store sales fell 6.8%, a sharp reversal from 2.4% growth in the same period a year earlier, and the quarterly run-rate average unit volume dropped to $659,000 from $686,000. Franchise revenue slipped 3% to $44 million on that same-store weakness plus brand divestitures completed in 2025, while equipment revenue dropped 26% to $7.1 million as fewer studio openings and license sales meant fewer installations. Merchandise revenue nearly vanished, falling 90% to $0.5 million as the company shifted from an in-house wholesale model to an outsourced retail arrangement, a transition it admitted came with its own challenges.
Costs moved the wrong direction too, with selling, general and administrative expenses up 33% to $32 million on higher legal expenses, and marketing fund expenses up 29% to $11.4 million. Adjusted EBITDA fell 22% to $21.9 million, and adjusted net income collapsed to $0.8 million from $14.5 million a year earlier. The balance sheet adds another concern, with just $25 million in cash, cash equivalents, and restricted cash against $522.4 million in total long-term debt, and $25.7 million in cash used in operating activities during the quarter. Management responded by cutting full-year revenue guidance to $250 million to $260 million, a 19% decline at the midpoint from 2025 and down from a prior forecast of $260 million to $270 million.
#million #quarter #north #sales
Despite the weak headline numbers, Xponential kept adding to its network. The company opened 67 gross new studios and sold 53 franchise licenses during the quarter, a sign that franchisee demand for its brands hasn't disappeared. North America system-wide sales held essentially flat at $437.3 million, which means new locations are offsetting some of the softness at existing studios rather than the whole system contracting. Even after cutting its 2026 targets, the company still expects to open roughly 150 net new studios for the year and generate North America system-wide sales of $1.7 billion to $1.75 billion. Full-year adjusted EBITDA guidance, while lowered, still points to $91 million to $97 million, meaning the business is still projected to be solidly profitable on that measure.
The details underneath the topline number are worse than the revenue decline alone suggests. North America same-store sales fell 6.8%, a sharp reversal from 2.4% growth in the same period a year earlier, and the quarterly run-rate average unit volume dropped to $659,000 from $686,000. Franchise revenue slipped 3% to $44 million on that same-store weakness plus brand divestitures completed in 2025, while equipment revenue dropped 26% to $7.1 million as fewer studio openings and license sales meant fewer installations. Merchandise revenue nearly vanished, falling 90% to $0.5 million as the company shifted from an in-house wholesale model to an outsourced retail arrangement, a transition it admitted came with its own challenges.
Costs moved the wrong direction too, with selling, general and administrative expenses up 33% to $32 million on higher legal expenses, and marketing fund expenses up 29% to $11.4 million. Adjusted EBITDA fell 22% to $21.9 million, and adjusted net income collapsed to $0.8 million from $14.5 million a year earlier. The balance sheet adds another concern, with just $25 million in cash, cash equivalents, and restricted cash against $522.4 million in total long-term debt, and $25.7 million in cash used in operating activities during the quarter. Management responded by cutting full-year revenue guidance to $250 million to $260 million, a 19% decline at the midpoint from 2025 and down from a prior forecast of $260 million to $270 million.
#million #quarter #north #sales


2 months ago
C3.ai's fiscal first-quarter results replaced a speculative earnings setup with a mixed turnaround test. The company reported $52.4 million of revenue, within its $50 million to $54 million guidance but down 25% from $70.3 million a year earlier. Subscription revenue was $49.2 million, or 94% of total revenue, compared with $60.3 million in the prior-year quarter. C3.ai, Inc. (NYSE:AI) therefore stabilized within management's lowered expectations, without yet returning to growth.
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE

2 months ago
Tyson Foods lowered its fiscal 2026 revenue growth forecast to 1.5%-2.0%, down from 2.5%-3.5%.
The company expects significant losses in its beef segment due to volatile cattle prices and shortages.
Tyson Foods shares dropped 7% after the revised outlook and are down 11% year-to-date.
Tyson Foods updated its fiscal 2026 outlook Thursday. Investors aren't too pleased.
Shares of Tyson Foods (TSN) sank roughly 7% in morning trading after the meat giant reduced its full-year revenue growth and adjusted operating income projections, "primarily driven by significant margin compression amid volatile cattle prices and one of the most severe cattle shortages in U.S. history, as well as the expected impact of lower cattle prices on the value of live cattle inventories."
#foods #prices #shares
The company expects significant losses in its beef segment due to volatile cattle prices and shortages.
Tyson Foods shares dropped 7% after the revised outlook and are down 11% year-to-date.
Tyson Foods updated its fiscal 2026 outlook Thursday. Investors aren't too pleased.
Shares of Tyson Foods (TSN) sank roughly 7% in morning trading after the meat giant reduced its full-year revenue growth and adjusted operating income projections, "primarily driven by significant margin compression amid volatile cattle prices and one of the most severe cattle shortages in U.S. history, as well as the expected impact of lower cattle prices on the value of live cattle inventories."
#foods #prices #shares



2 months ago
Ryanair, the biggest low-fare airline in Europe, on Wednesday lowered its winter traffic target to reduce exposure to high unhedged oil prices, and warned the some of its less well-hedged competitors could struggle to survive this winter amid high fuel costs.
Since the Iran war slashed deliveries of crude oil and petroleum products from the Middle East, rising jet fuel prices have eaten into the profitability of all airlines globally.
Ryanair is one of the most hedged airlines, with about 80% of fuel costs hedged at $67 per barrel. However, the remaining unhedged 20% is highly exposed to the jet fuel prices currently trading at about $140 per barrel, Ryanair said in its August 2026 traffic stats.
In light of the high unhedged oil prices, "it is sensible to strategically reduce the Group's exposure to unhedged jet fuel during the unprofitable winter schedule (from Nov. to Mar.)," the budget airline said.
Ryanair cut its winter traffic target to 214 million from 216 million passengers, expecting traffic to be broadly flat year-over-year.
#airline
Since the Iran war slashed deliveries of crude oil and petroleum products from the Middle East, rising jet fuel prices have eaten into the profitability of all airlines globally.
Ryanair is one of the most hedged airlines, with about 80% of fuel costs hedged at $67 per barrel. However, the remaining unhedged 20% is highly exposed to the jet fuel prices currently trading at about $140 per barrel, Ryanair said in its August 2026 traffic stats.
In light of the high unhedged oil prices, "it is sensible to strategically reduce the Group's exposure to unhedged jet fuel during the unprofitable winter schedule (from Nov. to Mar.)," the budget airline said.
Ryanair cut its winter traffic target to 214 million from 216 million passengers, expecting traffic to be broadly flat year-over-year.
#airline


2 months ago
Hennessy Fund's Q2 2026 investor letter for the Hennessy Equity and Income Fund. The letter can be downloaded here. The letter discusses portfolio changes, emphasizing opportunities in equity and fixed income markets that can withstand economic uncertainty. The portfolio held businesses with a 23.0% pre-tax return on invested capital versus 16.1% for the S&P 500. The letter notes a reversal in U.S. equities, driven by AI spending and strong earnings, despite cautious sentiment among lower-income households. The focus on high-quality firms with durable advantages is expected to yield positive outcomes as valuation pressures mount, indicating that future market performance may hinge on fundamentals rather than speculative trends. The portfolio aims to capitalize on the overlooked valuations of quality companies, presenting significant investment opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
2 months ago
PG&E (PGC) is on track to close meaningfully lower on Aug. 31 after Wells Fargo downgraded the utility company to "Equal Weight" and lowered its price target to $24. While ******* yst Shahriar Pourreza's revised price target still implies about an 80% upside from here, the downgrade signals a pivot to a far more cautious stance.
Following today's decline, PG&E stock is down about 30% versus its year-to-date high.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#equal
Following today's decline, PG&E stock is down about 30% versus its year-to-date high.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#equal
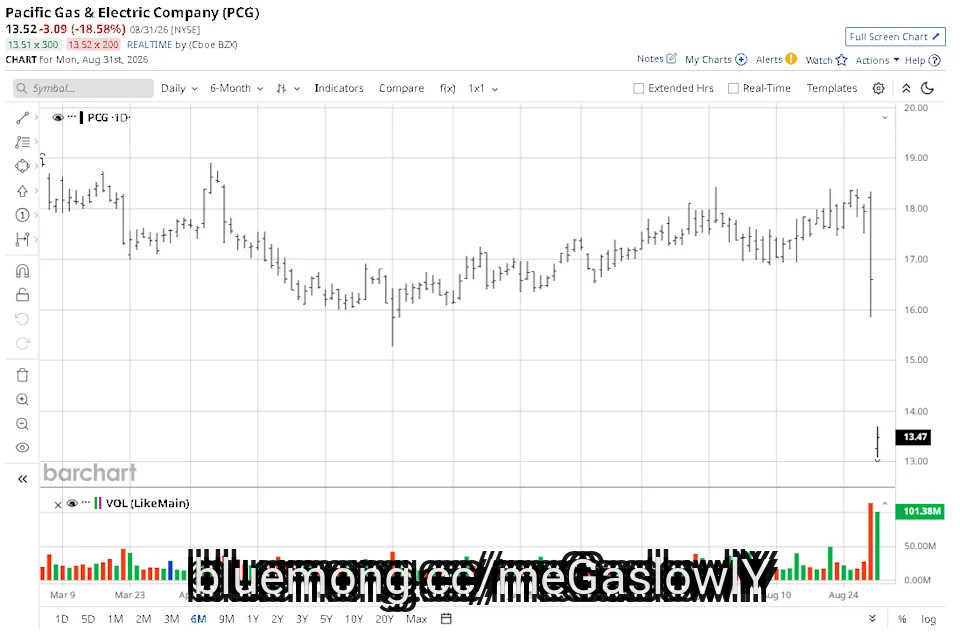

2 months ago
NASCAR's new superspeedway package didn't completely transform the racing at Daytona, but it showed enough improvement to deserve another opportunity.
The package debuted during Saturday's ******* e Zero Sugar 400 with the rear spoiler reduced from seven inches to four and horsepower lowered from 510 to 465. NASCAR's goal was to reduce drag and give drivers a better opportunity to move through the field instead of relying so heavily on fuel-saving strategies to gain track position. NASCAR
From a viewer's perspective, there were encouraging signs.
The field still raced three-wide, but the cars didn't appear permanently locked into place. After approximately 10 to 15 laps, the bottom and top lanes began separating as handling became more important. Denny Hamlin noticed the same development, explaining on his podcast, Actions Detrimental with Denny Hamlin, that the field could run three-wide for roughly 10 to 15 laps before the middle lane disappeared. The bottom lane would then move down the track while the top lane moved higher as drivers searched for clean air and additional room to move side to side. Actions Detrimental with Denny Hamlin
That separation created more room for drivers to search for clean air and attempt moves. Bubba Wallace said the runs felt slightly larger and that drivers could make some passes. Chase Briscoe and runner-up Daniel Suárez went further, saying the package allowed drivers to create runs and make moves that were more difficult under the previous configuration. Postrace driver reactions
#drivers #move
The package debuted during Saturday's ******* e Zero Sugar 400 with the rear spoiler reduced from seven inches to four and horsepower lowered from 510 to 465. NASCAR's goal was to reduce drag and give drivers a better opportunity to move through the field instead of relying so heavily on fuel-saving strategies to gain track position. NASCAR
From a viewer's perspective, there were encouraging signs.
The field still raced three-wide, but the cars didn't appear permanently locked into place. After approximately 10 to 15 laps, the bottom and top lanes began separating as handling became more important. Denny Hamlin noticed the same development, explaining on his podcast, Actions Detrimental with Denny Hamlin, that the field could run three-wide for roughly 10 to 15 laps before the middle lane disappeared. The bottom lane would then move down the track while the top lane moved higher as drivers searched for clean air and additional room to move side to side. Actions Detrimental with Denny Hamlin
That separation created more room for drivers to search for clean air and attempt moves. Bubba Wallace said the runs felt slightly larger and that drivers could make some passes. Chase Briscoe and runner-up Daniel Suárez went further, saying the package allowed drivers to create runs and make moves that were more difficult under the previous configuration. Postrace driver reactions
#drivers #move


2 months ago
Sep. 1—ABERDEEN — In a deep field of individual standouts and top teams, the Mitchell High School boys golf team finished tied for 12th on Tuesday at the Hub City Invitational at Lee Park Golf Course.
Mitchell shot 317 as a team, which was the Kernels' second-best team score of the season so far, but it still landed Mitchell well off the pace of the top teams.
Sioux Falls Lincoln and O'Gorman tied with 294 team strokes at the top, as Lincoln won the second tiebreaker because the Patriots' sixth golfer scored better than O'Gorman's. Both teams' fifth golfer shot 74, moving the tiebreaker down to the No. 6 slot on each varsity team.
The individual medalist honors went to Aberdeen Roncalli's Harper Schnabel, who shot 3-under-68 to win the tournament by two strokes. Schnabel had five birdies in the round, including shooting 2-under-par on the course's back nine. Sioux Falls Jefferson's Trevor Rick, Rapid City Stevens' Cole Jansen and Watertown's Max Stemwedel each shot 1-under-70 and Roncalli's Lucas Daggett shot even-par-71 to round out the top-five places.
Mitchell was led by senior Asher Dannenbring, who shot a 4-over-75 on the day, finishing in 25th place in a field of 98 golfers. Kernel freshman Eli Konrad shot a season-best round of 79, and checked in at 48th place. Ian Weber also lowered his season-best score and shot a round of 80, which landed him in 55th place.
#mitchell #aberdeen
Mitchell shot 317 as a team, which was the Kernels' second-best team score of the season so far, but it still landed Mitchell well off the pace of the top teams.
Sioux Falls Lincoln and O'Gorman tied with 294 team strokes at the top, as Lincoln won the second tiebreaker because the Patriots' sixth golfer scored better than O'Gorman's. Both teams' fifth golfer shot 74, moving the tiebreaker down to the No. 6 slot on each varsity team.
The individual medalist honors went to Aberdeen Roncalli's Harper Schnabel, who shot 3-under-68 to win the tournament by two strokes. Schnabel had five birdies in the round, including shooting 2-under-par on the course's back nine. Sioux Falls Jefferson's Trevor Rick, Rapid City Stevens' Cole Jansen and Watertown's Max Stemwedel each shot 1-under-70 and Roncalli's Lucas Daggett shot even-par-71 to round out the top-five places.
Mitchell was led by senior Asher Dannenbring, who shot a 4-over-75 on the day, finishing in 25th place in a field of 98 golfers. Kernel freshman Eli Konrad shot a season-best round of 79, and checked in at 48th place. Ian Weber also lowered his season-best score and shot a round of 80, which landed him in 55th place.
#mitchell #aberdeen



2 months ago
Lamine Camara will be staying at Monaco after the Senegal midfielder's £47.1m move to Chelsea collapsed.
The 22-year-old had already completed a medical with Chelsea but his switch fell through shortly after the 23:00 BST deadline.
They had two bids rejected by the Ligue 1 side before Monaco eventually lowered their asking price when Folarin Balogun's move to Everton came into renewed doubt.
Chelsea made their move for Camara in an attempt to bolster midfield options with Enzo Fernandez closing in on a joint-British transfer record £125m switch to Manchester City.
They had also held talks with Roma's Manu Kone and another unnamed Premier League option.
#Chelsea #move #folarin #everton
The 22-year-old had already completed a medical with Chelsea but his switch fell through shortly after the 23:00 BST deadline.
They had two bids rejected by the Ligue 1 side before Monaco eventually lowered their asking price when Folarin Balogun's move to Everton came into renewed doubt.
Chelsea made their move for Camara in an attempt to bolster midfield options with Enzo Fernandez closing in on a joint-British transfer record £125m switch to Manchester City.
They had also held talks with Roma's Manu Kone and another unnamed Premier League option.
#Chelsea #move #folarin #everton