

8 hours ago
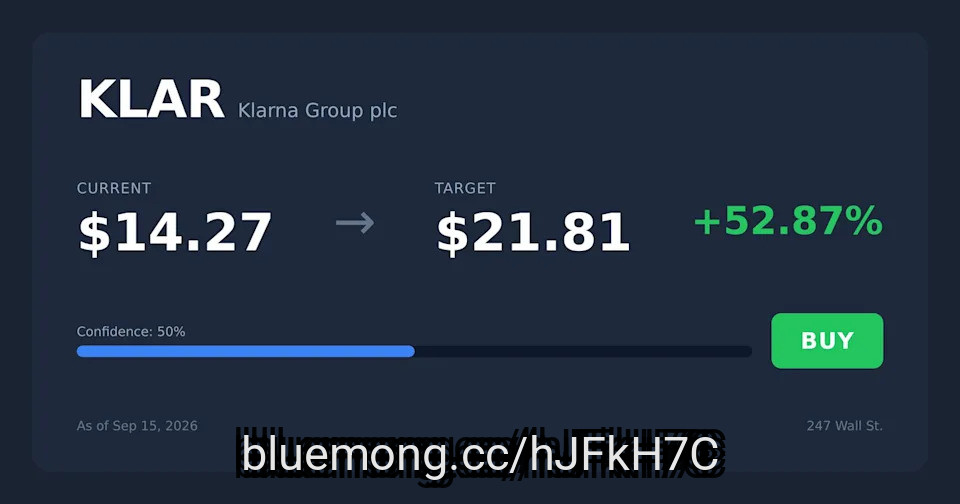
Klarna stock has cratered 51% year to date and 32% in just the past month, trading near its 52-week low of $12.
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month



8 hours ago
The dollar index (DXY00) rose by +0.14% on Tuesday, just below Monday's 1.5-week high. Tuesday's +4% surge in WTI crude oil prices raised inflation expectations and could persuade the Fed to tighten monetary policy, supporting the dollar. Also, Tuesday's increase in the 10-year T-note yield to a 19-year high of 5.04% strengthens the dollar's interest rate differentials. In addition, expectations that the Fed will raise interest rates by 25 bp at the Tue/Wed FOMC meeting support the dollar. The dollar fell from its best level on Tuesday after the Sep Empire manufacturing survey came in weaker than expected.
The US Sep Empire manufacturing survey of general business conditions fell -13.0 points to 7.6, weaker than expectations of 15.0.
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Supported by Higher Crude Prices and T-Note Yields
Dollar Climbs as Stocks Sink and Crude Oil Surges
#crude #prices #high
The US Sep Empire manufacturing survey of general business conditions fell -13.0 points to 7.6, weaker than expectations of 15.0.
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Supported by Higher Crude Prices and T-Note Yields
Dollar Climbs as Stocks Sink and Crude Oil Surges
#crude #prices #high

9 hours ago
Sept 15, 2026, 2:38 pm EDT
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana


10 hours ago
Adobe (ADBE) reported a record fiscal Q3 2026 and raised its fiscal 2026 revenue and earnings targets. Revenue rose 13% as reported to $6.76 billion, above the $6.70 billion the company had guided. But the key figure that did not move is the one to hold the quarter against: the fiscal 2026 target for growth in ending annualized recurring revenue, or ARR, still 10.2%.
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative

10 hours ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft

10 hours ago
In some markets, it costs less to rent than to buy — by a lot. And it could be a great way to save a ton of money during your retirement years.
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent
Mortgage and financial consultant Cody Schuiteboer of Best Interest Financial said many retirees never even consider renting as a serious option.
"There is an unshakeable mentality that buying is always the right choice, but the opposite is often true in retirement," he said. "If renting is actually cheaper in that market, renting lets retirees stretch their nest egg further."
MoneyLion ran the rent-versus-ownership numbers in the top retirement destinations along the East Coast and found the cities offering the greatest savings to renters. The homeownership numbers ****** umed a 10% down payment and a 6.53% interest rate, using average home price and rent numbers from Zillow.
Best of all, the following retirement hubs all have a total monthly expenditure cost under $4,000 according to BLS data, and adults over 65 make up at least 20% of the population.
#rent

11 hours ago
ARK Invest sold over 142,000 CRCL shares Monday across ARKK and ARKW, pushing Circle Internet down 8% despite a 25% monthly gain.
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin



11 hours ago
On September 11, Dell Technologies Inc. (NYSE:DELL) shares jumped more than 11% after RBC Capital Markets initiated coverage of the company with an Outperform rating and a price target of $640.
The latest rally adds to an already strong year for Dell Technologies Inc. (NYSE:DELL), with the stock having gained over 300% so far in 2026. The company has become one of the biggest vendors for Nvidia-based servers and related equipment, benefiting from strong demand for AI infrastructure from cloud companies and enterprises.
Photo by Pok Rie on Pexels
RBC ***** yst David Paige wrote in a note that Dell Technologies Inc. (NYSE:DELL) is showing no signs of slowing. RBC believes that the company "continues to be well positioned to benefit from a multi-year AI infrastructure spending cycle."
Paige pointed out that "Dell Technologies Inc.'s (NYSE:DELL) best-in-class supply chain represents a competitive moat that differentiates the company during periods of supply disruption, as customers increasingly turn to Dell Technologies Inc. (NYSE:DELL) for a 'calming hand' during periods of supply volatility/constraints."
#paige
The latest rally adds to an already strong year for Dell Technologies Inc. (NYSE:DELL), with the stock having gained over 300% so far in 2026. The company has become one of the biggest vendors for Nvidia-based servers and related equipment, benefiting from strong demand for AI infrastructure from cloud companies and enterprises.
Photo by Pok Rie on Pexels
RBC ***** yst David Paige wrote in a note that Dell Technologies Inc. (NYSE:DELL) is showing no signs of slowing. RBC believes that the company "continues to be well positioned to benefit from a multi-year AI infrastructure spending cycle."
Paige pointed out that "Dell Technologies Inc.'s (NYSE:DELL) best-in-class supply chain represents a competitive moat that differentiates the company during periods of supply disruption, as customers increasingly turn to Dell Technologies Inc. (NYSE:DELL) for a 'calming hand' during periods of supply volatility/constraints."
#paige


11 hours ago
A European independent power producer is expanding its ******* et base on the continent. Israel-headquartered Econergy on September 15 said it is entering the French market with a €134-million ($155 million) acquisition of Escofi, a private wind energy platform of about 740 MW.Econergy, which has offices across Europe, said the deal significantly expands the company's European wind ******* et base, bringing its total renewable portfolio to 13 GW. Escofi, founded in 1988, originates, finances, builds, and operates onshore wind projects, with its wind energy portfolio across four development stages: 128 MW in commercial operation, 34 MW under construction, 147 MW in advanced development stage (with building permits and grid connection approvals in place and construction due to commence between 2028 and 2030), and 432 MW in early and mid-stage development.Escofi's portfolio is concentrated in the Hauts-de-France and Grand Est regions of northern France, which officials said have the strongest onshore wind conditions and regulatory environments in the country.
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy

11 hours ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period

11 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted H&R Block, Inc. (NYSE:HRB). H&R Block, Inc. (NYSE:HRB) provides ***** isted and do-it-yourself (DIY) tax preparation solutions. On September 14, 2026, H&R Block, Inc. (NYSE:HRB) closed at $45.74 per share. Over the past month, H&R Block, Inc. (NYSE:HRB) declined 10.21%, and its shares lost 8.87% over the past 52 weeks. H&R Block, Inc. (NYSE:HRB) has a market capitalization of $5.64 billion, and its stock has traded within a 52-week range of $28.16 and $58.67.
Conventum – Alluvium Global Fund stated the following regarding H&R Block, Inc. (NYSE:HRB) in its Q2 2026 investor letter:
"Last quarter we mentioned in regard to H&R Block, Inc. (NYSE:HRB), the tax agents, that a "SAASpocalypse" did not necessarily apply across the board, and that there was a mispricing opportunity so we bought more. Somewhat ironically, during its results call in early May, management stated that rather than AI replacing its products, it is using AI to build better products which are being well received. After returning 21.3% during the quarter, it now accounts for 4.6% of the Fund. Although it is now trading at a more respectable price, H&R Block achieves high returns on its capital, and trades at double digit cash flow and earnings yields. In no way do we see it as expensive."
H&R Block, Inc. (NYSE:HRB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 33 hedge fund portfolios held H&R Block, Inc. (NYSE:HRB) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of H&R Block, Inc. (NYSE:HRB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted H&R Block, Inc. (NYSE:HRB). H&R Block, Inc. (NYSE:HRB) provides ***** isted and do-it-yourself (DIY) tax preparation solutions. On September 14, 2026, H&R Block, Inc. (NYSE:HRB) closed at $45.74 per share. Over the past month, H&R Block, Inc. (NYSE:HRB) declined 10.21%, and its shares lost 8.87% over the past 52 weeks. H&R Block, Inc. (NYSE:HRB) has a market capitalization of $5.64 billion, and its stock has traded within a 52-week range of $28.16 and $58.67.
Conventum – Alluvium Global Fund stated the following regarding H&R Block, Inc. (NYSE:HRB) in its Q2 2026 investor letter:
"Last quarter we mentioned in regard to H&R Block, Inc. (NYSE:HRB), the tax agents, that a "SAASpocalypse" did not necessarily apply across the board, and that there was a mispricing opportunity so we bought more. Somewhat ironically, during its results call in early May, management stated that rather than AI replacing its products, it is using AI to build better products which are being well received. After returning 21.3% during the quarter, it now accounts for 4.6% of the Fund. Although it is now trading at a more respectable price, H&R Block achieves high returns on its capital, and trades at double digit cash flow and earnings yields. In no way do we see it as expensive."
H&R Block, Inc. (NYSE:HRB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 33 hedge fund portfolios held H&R Block, Inc. (NYSE:HRB) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of H&R Block, Inc. (NYSE:HRB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#conventum

11 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter

11 hours ago
Nvidia's (NVDA) Vera Rubin GPUs claim 70% of the $4M VR200 rack bill of materials, while Micron (MU) benefits from the 22% memory slice.
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera

11 hours ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos


12 hours ago
Enova International Inc (NYSE:ENVA) withdrew regulatory applications for its planned Grasshopper Bancorp acquisition on Tuesday, sending shares sharply lower despite reaffirmed growth forecasts and plans for faster buybacks.
Shares fell 25% to $169.50 following the company's acquisition update.
The technology and ******* ytics company pulled applications with the Office of the Comptroller of the Currency and the Federal Reserve after reviewing the transaction and bank approval process.
CEO Steve Cunningham said withdrawing the applications was the best choice for Enova and its shareholders, adding that the company can keep growing without becoming a bank.
He argued that banking rules have not kept pace with the credit needs of consumers and small businesses that banks do not adequately serve.
#acquisition #bank #international
Shares fell 25% to $169.50 following the company's acquisition update.
The technology and ******* ytics company pulled applications with the Office of the Comptroller of the Currency and the Federal Reserve after reviewing the transaction and bank approval process.
CEO Steve Cunningham said withdrawing the applications was the best choice for Enova and its shareholders, adding that the company can keep growing without becoming a bank.
He argued that banking rules have not kept pace with the credit needs of consumers and small businesses that banks do not adequately serve.
#acquisition #bank #international


12 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in

12 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset

12 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
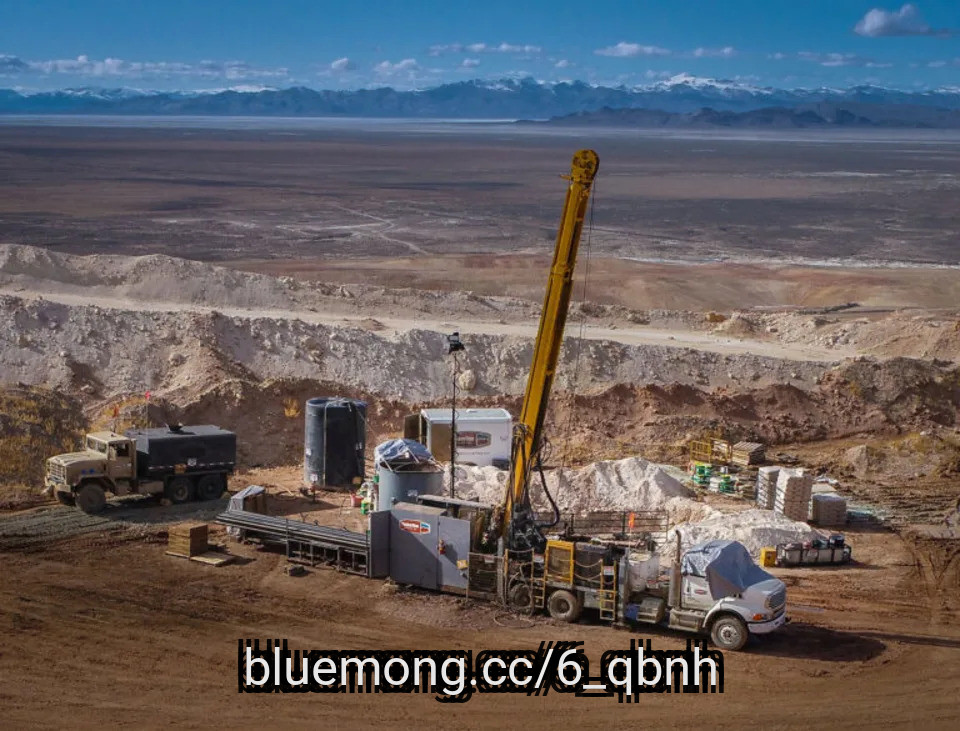
Photo from Hycroft Mining website
#letter
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#letter

12 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


12 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval

12 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te

12 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend

12 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

13 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market

13 hours ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year

13 hours ago
Uniswap (UNI) has jumped by more than 6% in the past 24 hours, and it is the best-performing token in the top 20, as on-chain data shows that protocol fees have exploded in September.
In the past 30 days alone, this token has doubled its value, primarily amid the success of its launch on the Robinhood Chain.
Trading volumes in the past 24 hours have surged by 80%, to nearly $640 million. At those levels, they account for almost 15% of the ****** et's circulating market cap.
UNI has managed to defy a challenging macroeconomic backdrop marked by expectations of multiple upcoming rate hikes.
According to data from FedWatch, the Federal Reserve will increase interest rates by 25 basis points tomorrow. Meanwhile, it appears that ****** ysts are leaning toward a second rate increase in December, as high inflation in the United States persists.
#past #token #increase
In the past 30 days alone, this token has doubled its value, primarily amid the success of its launch on the Robinhood Chain.
Trading volumes in the past 24 hours have surged by 80%, to nearly $640 million. At those levels, they account for almost 15% of the ****** et's circulating market cap.
UNI has managed to defy a challenging macroeconomic backdrop marked by expectations of multiple upcoming rate hikes.
According to data from FedWatch, the Federal Reserve will increase interest rates by 25 basis points tomorrow. Meanwhile, it appears that ****** ysts are leaning toward a second rate increase in December, as high inflation in the United States persists.
#past #token #increase
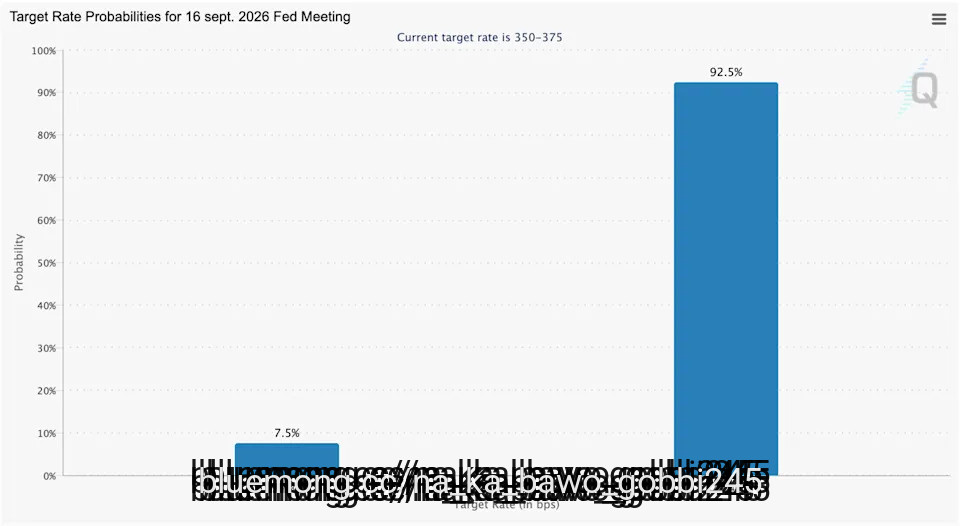

13 hours ago
The dollar index (DXY00) is up +0.11% today and is just below Monday's 1.5-week high. Today's +1% rise in WTI crude oil prices raises inflation expectations and could persuade the Fed to tighten monetary policy, which supports the dollar. Also, today's increase in the 10-year T-note yield to a 19-year high of 5.04% strengthens the dollar's interest rate differentials. In addition, expectations that the Fed will raise interest rates by 25 bp at the Tue/Wed FOMC meeting support the dollar. The dollar fell from its best level today after the Sep Empire manufacturing survey came in weaker than expected.
The US Sep Empire manufacturing survey of general business conditions fell -13.0 points to 7.6, weaker than expectations of 15.0.
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Rises on Surging Crude Prices and T-Note Yields
Dollar Climbs as Stocks Sink and Crude Oil Surges
#empire #stocks #note #year
The US Sep Empire manufacturing survey of general business conditions fell -13.0 points to 7.6, weaker than expectations of 15.0.
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Rises on Surging Crude Prices and T-Note Yields
Dollar Climbs as Stocks Sink and Crude Oil Surges
#empire #stocks #note #year

13 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Rentokil Initial plc (NYSE:RTO). Rentokil Initial plc (NYSE:RTO) is a route-based service provider that offers a range of pest control services. On September 14, 2026, Rentokil Initial plc (NYSE:RTO) closed at $22.55 per share. Over the past month, Rentokil Initial plc (NYSE:RTO) declined 5.34%, but its shares are down 10.61% over the past year. Rentokil Initial plc (NYSE:RTO) has a market capitalization of $11.2 billion, and its stock has traded within a 52-week range of $22.24 to $34.67.
Broyhill **** et Management stated the following regarding Rentokil Initial plc (NYSE:RTO) in its Q2 2026 investor letter:
"Rentokil Initial plc (NYSE:RTO) declined 9%. North American pest organic growth of 2.8% was entirely price, and customer retention remains near 80%. Our thesis is that the significant valuation discount to peer Rollins (almost half at the end of the second quarter) narrows as the Terminix integration is delivered."
Rentokil Initial plc (NYSE:RTO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 15 hedge fund portfolios held Rentokil Initial plc (NYSE:RTO) at the end of the second quarter, compared to 19 in the previous quarter. While we acknowledge the potential of Rentokil Initial plc (NYSE:RTO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter #investor

13 hours ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter


14 hours ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted ServiceNow, Inc. (NYSE:NOW). ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On September 14, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $142.35 per share. Over the past month, ServiceNow, Inc. (NYSE:NOW) returned 18.32%, but its shares are down 24.15% over the past year. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $147.19 billion, and its stock has traded within a 52-week range of $81.24 to $194.73.
Broyhill ***** et Management stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"ServiceNow, Inc. (NYSE:NOW), added in May, fell 21%. The general argument against software fits it poorly. The Now ***** ist annual contract value target was raised by 50% to $1.5 billion, customers spending more than $1 million on it grew 130% year over year, more than half of new business is now priced on consumption rather than seats, and the gross renewal rate is 97%. That is not the profile of an obvious AI victim. While we exited other related exposure where we could not frame the range of outcomes with enough confidence to hold the position (HubSpot and Intuit), we added to ServiceNow."
ServiceNow, Inc. (NYSE:NOW) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 115 hedge fund portfolios held ServiceNow, Inc. (NYSE:NOW) at the end of the second quarter, compared to 108 in the previous quarter. While we acknowledge the potential of ServiceNow, Inc. (NYSE:NOW) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#servicenow #management #quarter #investor
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted ServiceNow, Inc. (NYSE:NOW). ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On September 14, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $142.35 per share. Over the past month, ServiceNow, Inc. (NYSE:NOW) returned 18.32%, but its shares are down 24.15% over the past year. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $147.19 billion, and its stock has traded within a 52-week range of $81.24 to $194.73.
Broyhill ***** et Management stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"ServiceNow, Inc. (NYSE:NOW), added in May, fell 21%. The general argument against software fits it poorly. The Now ***** ist annual contract value target was raised by 50% to $1.5 billion, customers spending more than $1 million on it grew 130% year over year, more than half of new business is now priced on consumption rather than seats, and the gross renewal rate is 97%. That is not the profile of an obvious AI victim. While we exited other related exposure where we could not frame the range of outcomes with enough confidence to hold the position (HubSpot and Intuit), we added to ServiceNow."
ServiceNow, Inc. (NYSE:NOW) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 115 hedge fund portfolios held ServiceNow, Inc. (NYSE:NOW) at the end of the second quarter, compared to 108 in the previous quarter. While we acknowledge the potential of ServiceNow, Inc. (NYSE:NOW) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#servicenow #management #quarter #investor



