12 days ago
Helfstein estimates META needs 115 million paying Muse subscribers at $20/month to unlock $28 billion in AI revenue, but doubts it happens.
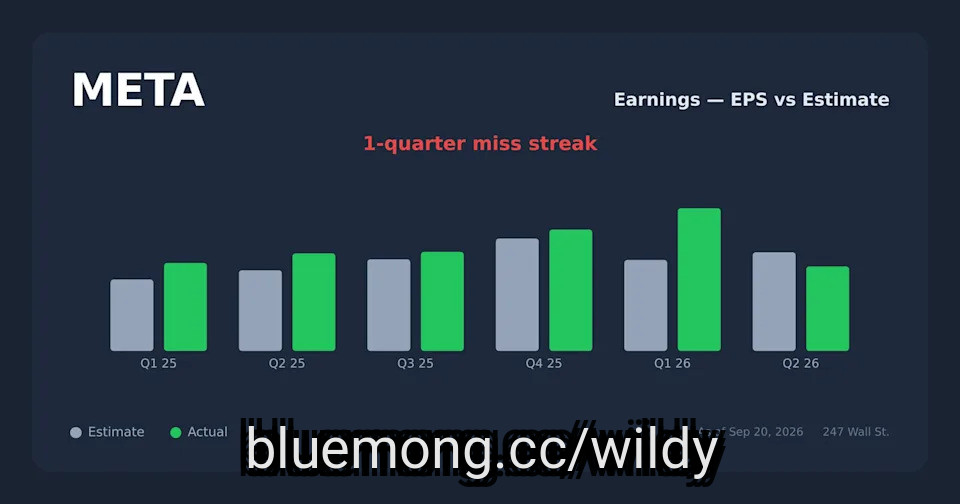
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million

15 days ago
A fresh wave of nuclear stock listings is sweeping Wall Street as the explosive growth of data centers puts mounting pressure on electricity grids and reignites investor appetite for nuclear power. Joining this initial public offering (IPO) frenzy is nuclear stock Holtec Nuclear, which is gearing up for its public debut this month. The company plans to offer 50 million shares of Class A common stock at a price range of $15 to $18 per share, potentially raising up to $900 million and valuing the company at as much as $10.2 billion.
Holtec plans to list on the Nasdaq Global Select Market and Nasdaq Texas under the ticker symbol "HNUC" on Sept. 18. The underwriters also have a 30-day option to purchase up to an additional 7.5 million shares. Leading the offering as joint lead book-running managers are J.P. Morgan, Guggenheim Securities, Goldman Sachs, Citigroup, and BofA Securities, while Morgan Stanley, Cantor, BMO Capital Markets, and Oppenheimer & Co. round out the group of joint book-running managers.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#shares #securities

16 days ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Wells Fargo upgraded Ulta Beauty (ULTA) to Equal Weight from Underweight with a price target of $525, up from $450, after meeting with management. The firm says the company is navigating industry headwinds better than expected.
Oppenheimer upgraded Etsy (ETSY) to Outperform from Perform with a $90 price target. The firm cites the company's AI search benefits, product improvements, and app engagement for the upgrade.
Berenberg upgraded Eli Lilly (LLY) to Buy from Hold with a price target of $1,400, up from $1,220. The firm says its 2026 return on investment **** ysis confirms Eli Lilly's "strong track record of delivering best-in-class returns on investment."
Bernstein upgraded Agilon Health (AGL) to Outperform from Market Perform with a price target of $125, up from $86. The company is undergoing a turnaround focused on risk-taking discipline and incremental medical cost improvements, the firm tells investors in a research note.
#firm #outperform #perform
27 days ago
Wall Street is fairly bullish on ****** eX (SPCX) stock, and Oppenheimer's latest price target raise is pushing that narrative further.
Oppenheimer ****** yst Timothy Horan increased his price target on ****** eX stock to $280 from $250, according to TipRanks. His price target implies about 87% upside, as ****** eX is trading near $150. The raise is a result of Horan's growing confidence that ****** eX can become a real AI giant.
On the surface, MarketBeat's data shows 27 of 42 ****** ysts covering the stock rate ****** eX a buy, and this fresh take from Oppenheimer makes the stock look very attractive.
The stock closed 6.42% higher following this ****** yst call. But does the thesis make sense?
The core valuation question is whether you believe that it can capture the market it said it aspires to capture in its S-1. ****** eX's S-1 states that the company estimates its total addressable market (TAM) at $28.5 trillion, of which $26.5 trillion, or 92.98%, is expected to come from AI.
#price #capture

28 days ago
Get your expectations in check, bulled-up investors: One of Goldman Sachs' top stock strategists sees more gradual stock gains over the next 12 months.
"We should acknowledge that the S&P 500 and indeed other equity markets around the world have had a phenomenal return over the course of the last year and year to date," Goldman Sachs chief global equity strategist Peter Oppenheimer told Yahoo Finance in an exclusive interview on Opening Bid (video above). "So we've already had a lot of good returns behind us. We would expect lower returns from here."
Oppenheimer has a loyal following on the Street for many prescient calls on stocks over the years. In early March, he took a cautious view of markets before stocks hit their lows for the year later that month.
"In most cases, we're talking about mid- to high-single-digit [percentage] returns over the next 12 months, lower than we've been seeing in every region in the last 12 months," Oppenheimer added. "But still, you know, relatively decent so long as economic growth continues. That's our expectation."
To be sure, the factors are in place for a more muted backdrop for stocks heading into the end of the year, after a 12% gain for the S&P 500 (^GSPC) so far in 2026.
#year #months #returns #next


1 month ago
A clean beat-and-raise, record data center strength, and a newly expanded Alphabet Inc. (NASDAQ:GOOGL) Google partnership should have helped Marvell Technology Inc. (NASDAQ: MRVL) win a major boost from Wall Street. Yet, shares fell more than 8% anyway.
On August 28, Oppenheimer raised its price target on the stock to $325 from $300 while maintaining an Outperform rating. His note serves as a bull case that explains why the selloff was wrong, while the market reaction serves as the bear case for why it wasn't.
Several factors led Oppenheimer to raise its price target and reiterate its Outperform rating. For starters, Marvell's revenue rose 37% to $2.7 billion, $39 million above the company's guidance. The firm noted that the company has raised its calendar year 2026 revenue outlook to $12 billion, up from $11.5 billion last quarter. Marvell now anticipates calendar year 2027 revenue of $18 billion, up from its $16.5 billion outlook in May and $15 billion in March.
A majority of this raise is driven by interconnect products, while the rest is driven by custom chip programs. Its Trainium and Maia programs also remain on track, with Maia likely to contribute $700 million in revenue next year. The quarter highlighted strong AI-related demand across the company's data center portfolio, with data center representing 79% of total revenues.
Speaking of the Google-Marvell expanded partnership announced recently, the firm noted how the full vesting of warrants would imply roughly $120 billion in **** ulative Google purchases over an estimated seven years if milestones are met.
#billion #Google #year #oppenheimer

1 month ago
Nvidia reports August 26. The stock has had a rough few weeks. Bond yields spiked, the broader market sold off, and AI infrastructure names got hit harder than most.
Michael Burry flagged a startup. The circular financing debate keeps resurfacing. There is no shortage of reasons to be cautious heading into next week.
Oppenheimer is not cautious. The firm just reiterated its bullish case with numbers specific enough to be worth examining before the report lands.
Oppenheimer maintained its Outperform rating and $265 price target on Nvidia on August 20, according to Investing.com.
The stock trades at a P/E of 33.64 with a PEG ratio of 0.3. Nvidia has delivered 71% revenue growth over the past 12 months. Market cap sits at $5.31 trillion. Gross profit margin is 74%.
#NVIDIA #oppenheimer #michael #burry

1 month ago
An Oppenheimer star is stepping away from acting after admitting that he feels "frustrated" and "fed up." The actor known for the Nolan epic as well as Supergirl, announced the news this week.
David Krumholtz looks to be stepping back from Hollywood for now. The veteran actor made the unexpected announcement on social media before deleting the post.
"I kinda sorta put my acting career on hold the other day. It's been something I've been petrified to do for years. Specifically, the fear was that I'd go broke and not be able to handle being out of the game. But I sent the definitive email," Krumholtz posted on Threads, per The Hollywood Reporter. "And gotta say, a huge wave of relief washed over me. Not sure what I'm going to do for money instead, or how I'm going to do it, but I just removed a humongous burden, one that I truly didn't fathom the weight of until it was gone. Frustrated, fed up, fried."
The post drew a lot of attention right away, and the 48-year-old stayed engaged by answering fans in the comments. Addressing the reactions, the Numb3rs actor explained, "The love and encouragement re: my last post is overwhelmingly surprising. Acting professionally is a very different concept than the exercise of acting itself. I've enjoyed every single minute of exercising the muscle. I've enjoyed the fanfare. There was a time when being competitive and self-involved really served my pursuit. That time has passed. Much to MY overwhelming surprise. There will always be great joy in the exercise. But for me, the profession has lost its gleam."
As reported by Deadline, David Krumholtz went on to clarify that he's "not quitting entirely," noting, "Just taking a bit of a step back and an indefinite break. The stress of the moment has me wondering if there's a higher calling to pursue. Thanks for the very kind thought. Means the world."
#stepping


1 month ago
David Krumholtz will be taking a step back from Hollywood after the actor from Supergirl and Oppenheimer got real in a series of social media posts.
The actor made the decision to take "an indefinite break" after expressing being "frustrated, fed up, fried" with the business, as "the profession has lost its gleam."
More from Deadline
'The Odyssey' Passes 'Oppenheimer's $330M U.S. Lifetime B.O. In 13 Days Before 'Spider-Man' Swings In - Box Office Update
Christopher Nolan Says He Wouldn't Have Been Able To Make 'The Odyssey' Without 'Oppenheimer'
#oppenheimer #krumholtz #hollywood
1 month ago
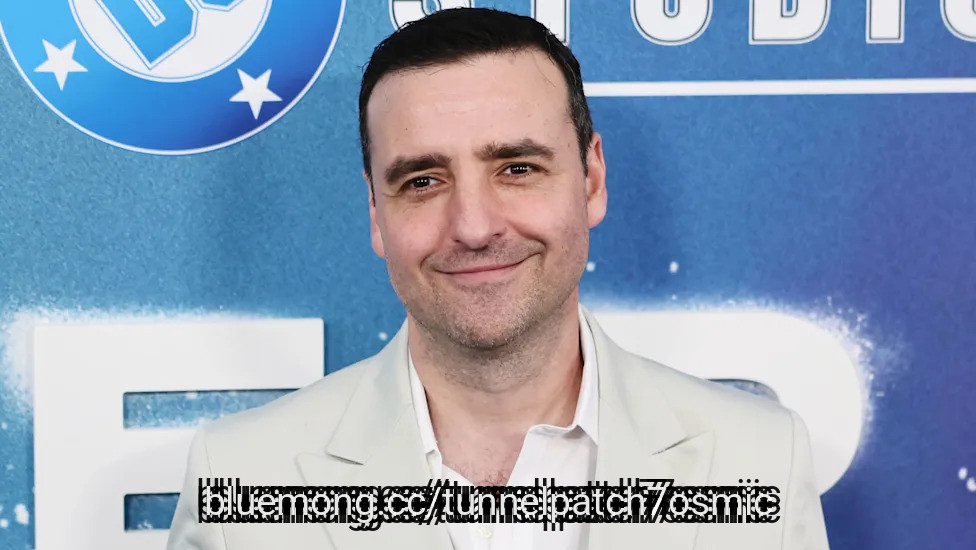
David Krumholtz shared that he's taking an "indefinite break" from acting, saying he hopes to pursue "a higher calling" moving forward.
The veteran actor, known for his performances in "Numb3rs," "The Santa Clause," "10 Things I Hate About You," "Oppenheimer" and "Supergirl," issued a career update on Threads Monday, writing (before later deleting), "I kinda sorta put my acting career on hold the other day. It's been something I've been petrified to do for years … Specifically, the fear was that I'd go broke and not be able to handle being out of the game."
He added: "But I sent the definitive email … And gotta say, a huge wave of relief washed over me. Not sure what I'm going to do for money instead, or how I'm going to do it, but I just removed a humongous burden, one that I truly didn't fathom the weight of until it was gone. Frustrated, fed up, fried."
After the post picked up steam on Threads, with many friends and fans speaking out in support of Krumholtz, the actor clarified that he wasn't officially retiring – just "redefining [his] terms."
"Ain't over, rather, redefining my terms," he wrote. "Hoping to find a new, more rewarding passion. Me, my product, and I mentality is not working anymore. I want to try to be of service. No crystal ball."
#going #redefining #david


1 month ago
David Krumholtz, who played Kor-El in this year's "Supergirl" and appeared in "Oppenheimer" and "The Studio," said on Threads Monday that he's done with acting and ready to start a "new life."
However, he later deleted the posts that spoke of his frustration with getting jobs in Hollywood, leading fans to speculate whether he is truly ready to turn in his SAG/AFTRA card.
More from Variety
John Oliver Takes Shots at Own Company's DC Superhero Movies on 'Last Week Tonight'
Marvel, 'Star Wars' and DC's Biggest Fans Discuss Why Their Favorite Franchises Are Struggling: 'I'm Still Waiting for "Blade"'
#krumholtz #oppenheimer #Monday

2 months ago
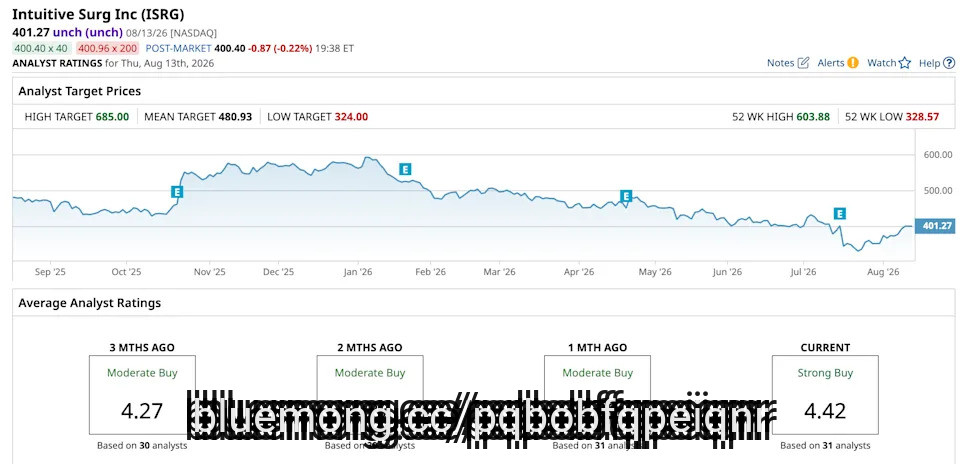
Analysts at Oppenheimer recently upgraded the medtech company Intuitive Surgical (ISRG) from "Perform" to "Outperform" and set a $500 price target, implying a 24.6% upside from current levels. Expecting the company to benefit from the growth in robotic surgery, Oppenheimer **** ysts expect Intuitive to maintain a leading position in the market despite increasing competition.
Intuitive also has a vision regarding the usage of artificial intelligence (AI) in such surgeries, helping medical personnel achieve better outcomes. The company is developing AI as a capability stack that leverages real-world surgical data to build advanced vision-language and reasoning models capable of answering complex surgical questions.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#Stock #analysts

2 months ago
Snowflake (SNOW) stock has already delivered a powerful rally in 2026, but Oppenheimer believes the data cloud company still has plenty of room to run. The firm raised its price target to $400 from $295 while maintaining an "Outperform" rating, representing a roughly 36% increase in its target.
The bullish call comes as Oppenheimer sees stronger consumption trends across regions and industries, along with accelerating adoption of Snowflake's AI coding agent, CoCo. For a company whose revenue depends heavily on how much customers use its platform, that is an important development.
Mark Cuban Says If You Win The Lottery, Don't Take The Lump Sum — And Tell People Who Ask for Money No, But 'Be Nice. No One Likes a Mean Billionaire'
Analysts Keep Hiking Micron's Revenue and Price Forecasts - Shorting MU Puts Works Here
JPMorgan Just Upgraded Salesforce Stock. Here's Why.
#oppenheimer


2 months ago
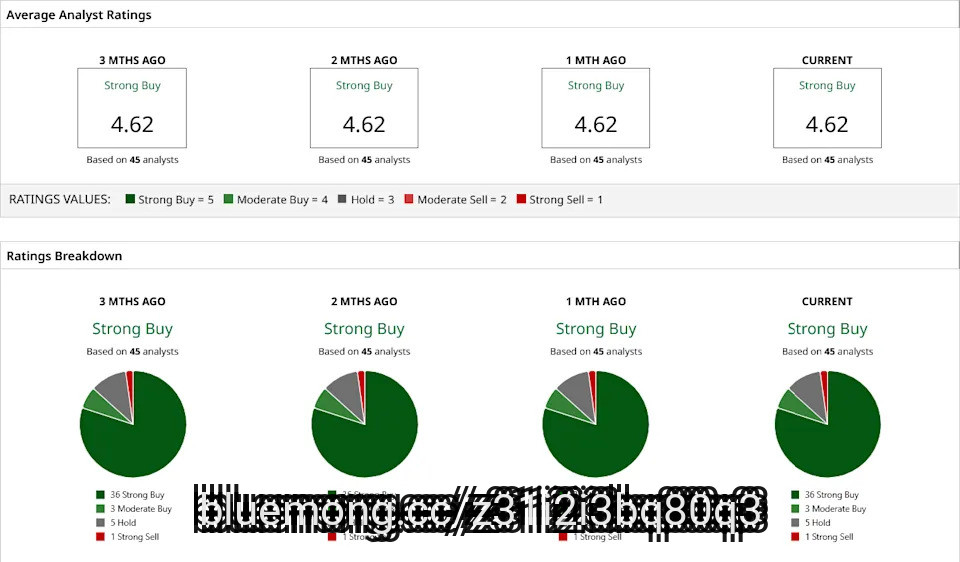
Oppenheimer downgraded Walmart stock to a neutral rating, citing reduced outperformance potential.
Analysts highlighted U.S. pharmacy revenue headwinds, valuation concerns, and overly optimistic Street forecasts.
Shares of Walmart started the year strong. Now they've cooled, and some ***** ysts are offering up reasons for further caution.
Oppenheimer ***** ysts on Tuesday downgraded Walmart (WMT) stock to a neutral "perform" rating, withdrawing a $140 per share price target that represented a 26% premium to yesterday's close around $111 and was roughly in line with the Visible Alpha mean.
The ***** ysts cited three reasons they now see a "less compelling outperformance case" for the stock: revenue headwinds facing the U.S. pharmacy business that could hurt same-store sales, a "peakish" valuation, and Wall Street forecasts that they characterized as "well ahead" of the company's guidance.
#walmart #downgraded #outperformance


2 months ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Deutsche Bank upgraded Palantir (PLTR) to Buy from Hold with an unchanged price target of $200. The firm views the company's Q2 report as "exceptional."
Oppenheimer upgraded Inspire Medical (INSP) to Outperform from Perform with an $85 price target. The firm notes the company's Q2 revenues of $201M slightly outpaced estimates, and argues that at these levels, there is "noisy" value to the story as a mid to high single digit grower.
UBS upgraded BBB Foods (TBBB) to Buy from Neutral with a price target of $51, up from $43. The company has delivered same-store-sales well ahead of inflation and its business benefits from consumers seeking value, the firm tells investors in a research note.
Leerink upgraded Replimune (REPL) to Outperform from Market Perform with a price target of $17, up from $11. The firm has "high conviction" the FDA will grant RP-1 plus nivolumab accelerated approval.
#price #target #calls


2 months ago
By Nandan Mandayam
Aug 4 (Reuters) - Caterpillar raised its annual revenue growth forecast after beating second-quarter profit estimates on Tuesday, benefiting from a buildout of AI data centers that has spurred demand for its power-generation and construction equipment.
Shares of the company jumped 11% in premarket trading, sending Dow futures up 0.6%, after it cut its full-year tariff costs forecast to around $2.2 billion from the previously expected $2.2 billion to $2.6 billion.
Over the last few quarters, the equipment giant has seen a surge in orders for construction equipment amid a nationwide buildout of data centers as well as the backup power equipment needed for such buildings.
"Construction leading growth in the quarter was a standout," Oppenheimer ***** yst Kristen Owen said. The stock's reaction "reflects the importance of the durability of core Caterpillar businesses in sustaining the stock's momentum."
#Growth #forecast


2 months ago
Palantir (PLTR) will report second-quarter results on Aug. 3, and the ******* ysts covering PLTR stock cannot seem to agree on what is coming. PLTR stock fell about 6% after Cleveland Research flagged signs of weak spending among Palantir's commercial customers. The note was a rare cautious voice on a stock that has mostly drawn praise, and it was enough to worry investors. Baird ******* yst William Power pushed back the same day, however, reiterating an "Outperform" rating and a $200 price target. A day before that, Oppenheimer ******* yst Param Singh also kept an "Outperform" rating and a $200 target. Singh expects revenue to grow roughly 85% in Q2. For reference, Palantir's own Q2 guidance points to revenue of about $1.8 billion, which would mean growth of roughly 80%. So, the ******* yst believes Palantir will beat its own forecast, something it has done quarter after quarter.
That pattern is why the bulls feel confident. Last quarter, Palantir raised its full-year revenue guidance by its largest amount ever, and management said the real problem is not demand but keeping up with it. CEO Alex Karp noted that U.S. growth is being limited because the company has been unable to fulfill demand. This goes directly against Cleveland's warning about commercial spending softening.
CoreWeave Just Scored a Leidos Partnership. What That Means for CRWV Stock Here.
Palantir Is Set to Deliver Strong Q2. ******* ysts See 60% Upside Potential for PLTR Stock.
Earnings, PMI and Other Key Things to Watch this Week
#analyst


2 months ago
AI data centers are putting pressure on the US electrical grid in ways that did not seem possible just a few years ago, and that strain is a direct benefit to heavy equipment manufacturers, not just chipmakers. US data center power consumption is expected to increase by 22% in a single year, with total grid demand nearly tripling to 134.4 GW by 2030 as hyperscale buildouts gain speed.
Considering grid capacity cannot be increased quickly enough to meet that curve, on-site and backup power production has become a significant portion of AI infrastructure spending, with Caterpillar Inc. (NYSE:CAT) alone accounting for an estimated 18% of the data center generator market. Notably, the company has come to be one of the Dow's best-performing stocks so far in 2026, with a year-to-date return of 47.81%.
The company's Q1 2026 revenue came in at $17.4 billion, up 22% year-over-year, with adjusted EPS of $5.54, above expectations. The backlog behind that expansion seems to be the real story, with Caterpillar Inc. (NYSE:CAT) closing the quarter with a record $63 billion in order backlog, an increase of 79% year-over-year and $11.5 billion sequentially, owing to major project wins like Altus and Chevron, growing rental demand, and strong Mining segment order conversion.
CEO Joe Creed told ****** ysts that the company's massive engine backlog, which directly powers AI data centers, has grown by over 3.5x since Caterpillar first revealed capacity expansion plans back in January 2024.
This backlog progress led Oppenheimer to lift Caterpillar's price target to $1,105 from $980 on July 13, while keeping an Outperform rating, expecting high-margin Power & Energy deliveries to accelerate in the second half of the year. However, underlying margin trends indicate rising friction. Resource Industries segment margins fell by over 700 basis points year on year in Q1, to 10%, owing to roughly $600 million in quarterly tariff charges. With full-year tariff headwinds of $2.2 billion to $2.4 billion, Caterpillar's cost structure is under significant pressure even as top-line demand grows.
#caterpillar #power #grid #demand
2 months ago
AI data centers are putting pressure on the US electrical grid in ways that did not seem possible just a few years ago, and that strain is a direct benefit to heavy equipment manufacturers, not just chipmakers. US data center power consumption is expected to increase by 22% in a single year, with total grid demand nearly tripling to 134.4 GW by 2030 as hyperscale buildouts gain speed.
Considering grid capacity cannot be increased quickly enough to meet that curve, on-site and backup power production has become a significant portion of AI infrastructure spending, with Caterpillar Inc. (NYSE:CAT) alone accounting for an estimated 18% of the data center generator market. Notably, the company has come to be one of the Dow's best-performing stocks so far in 2026, with a year-to-date return of 47.81%.
The company's Q1 2026 revenue came in at $17.4 billion, up 22% year-over-year, with adjusted EPS of $5.54, above expectations. The backlog behind that expansion seems to be the real story, with Caterpillar Inc. (NYSE:CAT) closing the quarter with a record $63 billion in order backlog, an increase of 79% year-over-year and $11.5 billion sequentially, owing to major project wins like Altus and Chevron, growing rental demand, and strong Mining segment order conversion.
CEO Joe Creed told ******* ysts that the company's massive engine backlog, which directly powers AI data centers, has grown by over 3.5x since Caterpillar first revealed capacity expansion plans back in January 2024.
This backlog progress led Oppenheimer to lift Caterpillar's price target to $1,105 from $980 on July 13, while keeping an Outperform rating, expecting high-margin Power & Energy deliveries to accelerate in the second half of the year. However, underlying margin trends indicate rising friction. Resource Industries segment margins fell by over 700 basis points year on year in Q1, to 10%, owing to roughly $600 million in quarterly tariff charges. With full-year tariff headwinds of $2.2 billion to $2.4 billion, Caterpillar's cost structure is under significant pressure even as top-line demand grows.
#billion #data #grid #centers


2 months ago
Nvidia Corporation (NVDA), the famous Silicon Valley chipmaker powering much of today's artificial intelligence (AI) infrastructure boom, has become one of Wall Street's biggest market stars. The company has reinvented itself as the gold standard for AI computing, cementing its place at the center of the global semiconductor industry.
That leadership is the exact reason Wall Street continues to view Nvidia as the chip stock to beat heading into another earnings season. Oppenheimer recently named NVDA as its top chip stock heading into second-quarter earnings, arguing that the AI infrastructure buildout remains far from over.
Our exclusive Barchart Brief newsletter is your FREE midday guide to what's moving stocks, sectors, and investor sentiment - delivered right when you need the info most. Subscribe today!
Analyst Rick Schafer sees hyperscale cloud providers pouring hundreds of billions into AI data centers, while enterprise AI, sovereign AI initiatives, and next-generation cloud platforms continue to widen Nvidia's runway. The **** yst expects the company's relentless product cadence – from Blackwell to Vera Rubin – to keep extending its technological lead, with future AI revenue opportunities still not fully reflected in estimates.
Let's dig into some details to understand why Oppenheimer remains firmly in Nvidia's camp heading into the Q2 earnings season.


2 months ago
International Business Machines Corporation (NYSE:IBM) lost 25.2% on July 14, erasing about $68 billion in market value in the stock's worst session on record. At first glance, the sell-off appears contradictory amid the still-robust AI investment cycle. Gartner expects worldwide AI spending to jump 47% to $2.59 trillion in 2026, with $1.43 trillion going to infrastructure. So IBM didn't crash because of any weakening in AI spending, but because that spending shifted toward hardware just as the company missed mainframe targets and couldn't close major deals.
IBM revealed the damage eight days before its scheduled earnings report. Preliminary second-quarter revenue rose just 1% to $17.2 billion, about $660 million below the LSEG consensus, while adjusted earnings of $2.93 per share missed the $3.02 estimate. Software growth slowed to 5%, Consulting was flat, and Infrastructure fell 7%. However, the numbers alone did not look bad enough to wipe out a quarter of IBM's value; it was the unscheduled warning and CEO Arvind Krishna's blunt admission that the company had "faltered".
JuliusKielaitis / Shutterstock.com
In his July 14 investor letter, Krishna said clients spent the final weeks of June rushing to secure supply-constrained servers, storage and memory before expected price increases. Cybersecurity concerns also competed for budgets and attention. IBM did capture some of that spending: Distributed Infrastructure revenue jumped 37%. But that strength was overwhelmed by weakness elsewhere. Several large deals slipped beyond the quarter, while IBM Z and its related Transaction Processing software missed expectations. To sum it up, the AI boom didn't really miss IBM; it's just that the money hit the wrong side of its portfolio at the wrong time.
That timing hit a stock priced for reinvention. Reuters Breakingviews noted that IBM has spent more than $50 billion since 2018 on buying Red Hat, HashiCorp, and Confluent. Before IBM released the preliminary figures, its shares traded at roughly 26 times forward earnings after more than doubling in five years. Its generative AI book had reached $12.5 billion, while first-quarter software revenue grew 11%. The second quarter's 5% growth therefore challenged the premise supporting IBM's rerating. Oppenheimer, which had modeled 12% software growth, responded by downgrading the stock and abandoning its $350 target.

3 months ago
NEW YORK – Luke Pettitte's pinstriped bloodlines suggest that his path to Yankee Stadium might be as a pitcher.
Yet, the son of Yankees' lefty legend Andy Pettitte possesses "big power'' as a right-handed hitter.
An eighth-round selection by the Yankees in this past weekend's MLB Draft, Luke Pettitte was "one of the bigger power bats in this draft,'' said Yankees scouting director Damon Oppenheimer.
Yankees scouts liked Pettitte as a right-handed pitcher at Dallas Baptist, but when he underwent Tommy John surgery last year, "we followed him as a hitter.''
In 42 games as a designated hitter for Dallas Baptist this spring, the 6-foot-2, 220-pound Pettitte posted a 1.096 OPS, and a .337 batting average, with 16 home runs.

3 months ago
Sezzle Inc. (NASDAQ:SEZL) is one of the 10 Best Performing American Stocks in June 2026.On June 29, 2026, Oppenheimer downgraded Sezzle Inc. (NASDAQ:SEZL) to Perform from Outperform, "solely on valuation," after a 158% year-to-date rise in the shares. Oppenheimer said it still expects Sezzle to remain one of the fastest gross profit and adjusted EBITDA growers in its coverage, supported by market share gains, Buy Now Pay Later industry expansion, and product innovation. The firm sees room for Sezzle to again raise full year EPS guidance from $5.10, but said the recent share-price strength suggests investors are already pricing in potential 2026 EBITDA outperformance.On June 25, Northland ******* yst Mike Grondahl raised the firm's price target on Sezzle to $170 from $160 and kept an Outperform rating on the shares. After meeting with management during Northland's Growth Conference, Grondahl said he got more insight into the company's marketing strategy and ramp, engagement with Pay in 5 and SezzleCash, and bank charter progress.
Earlier in June, B. Riley raised the firm's price target on Sezzle to $141 from $117 and kept a Buy rating on the shares. B. Riley said Sezzle integrated with Knot's CardSwitcher API to automatically update Sezzle virtual cards as the preferred payment method across merchants, including Amazon (AMZN), Walmart (WMT), and Uber (UBER). The firm said the integration should improve checkout convenience and help drive top-of-wallet behavior among users.Sezzle Inc. (NASDAQ:SEZL) operates as a technology-enabled payments company in the United States and Canada.While we acknowledge the potential of SEZL as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.READ NEXT: 33 Stocks That Should Double in 3 Years and Cathie Wood 2026 Portfolio: 10 Best Stocks to Buy.Disclosure: None. Follow Insider Monkey on Google News.
Earlier in June, B. Riley raised the firm's price target on Sezzle to $141 from $117 and kept a Buy rating on the shares. B. Riley said Sezzle integrated with Knot's CardSwitcher API to automatically update Sezzle virtual cards as the preferred payment method across merchants, including Amazon (AMZN), Walmart (WMT), and Uber (UBER). The firm said the integration should improve checkout convenience and help drive top-of-wallet behavior among users.Sezzle Inc. (NASDAQ:SEZL) operates as a technology-enabled payments company in the United States and Canada.While we acknowledge the potential of SEZL as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.READ NEXT: 33 Stocks That Should Double in 3 Years and Cathie Wood 2026 Portfolio: 10 Best Stocks to Buy.Disclosure: None. Follow Insider Monkey on Google News.

3 months ago
Progress Software Corp. (NASDAQ:PRGS) is one of the best 11 small-cap software infrastructure stocks to buy now.
On July 1, Oppenheimer reduced its target price on the stock from $57 to $50, while reaffirming an Outperform rating based on the company's impressive performance during the second quarter. Despite the downward revision in the price target, the stock carries an upside potential of over 149%.
The firm noted that both topline and profitability figures came in above consensus estimates. It also acknowledged management's operational discipline, which resulted in expense control and the resulting bottom-line outperformance.
Earlier that day, management reported more than $253 million in second-quarter revenue, compared to consensus forecasts of almost $243 million. The topline beat is attributed to persistent momentum across the company's AI-enabled solutions, along with elevated demand for its product portfolio.
Earlier on June 30, Progress Software Corp. (NASDAQ:PRGS) disclosed that its Progress Chef platform now offers lifecycle management of enterprise and configuration features for NVIDIA DGX Spark. It allows IT teams to monitor, allocate, and handle the desktop-based AI supercomputer safely on a large scale.

3 months ago
Wedbush research **** yst Dan Ives recently initiated coverage on **** e Exploration Technologies (NASDAQ: SPCX), marking a notable moment for Elon Musk's newly public company. Following **** eX's historic IPO, Ives published an upbeat **** sment emphasizing the company's **** e industry heritage and its emerging role in artificial intelligence (AI) infrastructure.
Ives' **** ysis frames **** eX as more than a rocket and satellite operator, highlighting its status as a vertically integrated technology business with recurring revenue streams and strategic depth that could deliver long-term gains.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ives **** igned **** eX an outperform rating and a 12-month price target of $190. This implies roughly 18% upside from where it closed Monday's trading session. His optimism is supported by a sum-of-the-parts valuation model anchored to fiscal 2028 estimates, projecting an enterprise value near $2.5 trillion.
Central to the thesis is Starlink's potential to mature into a durable profit engine through steady subscription revenue. Interestingly, Ives is not the only **** yst on Wall Street who sees game-changing potential from Starlink. Timothy Horan of Oppenheimer also cites Starlink's potential to disrupt the telecommunications industry as a major driver of **** eX's future growth.


3 months ago
Remitly Global Inc. (NASDAQ:RELY) ranks among the best fintech stocks to buy as digital payments volume surges. On June 26, Cantor Fitzgerald restated its Overweight rating and $28 price target for Remitly Global Inc. (NASDAQ:RELY). According to the firm, Remitly's core remittance operation is creating additional growth opportunities.
Based on Cantor's ****** sment, the core operations continue to generate significant revenue growth, free cash flow, and improved GAAP profitability. This gives Remitly Global Inc. (NASDAQ:RELY) additional time and resources to broaden its product offerings and monetize its user base through complementary solutions, such as high-value senders, Send Now/Pay Later, and Remitly Business.
Cantor Fitzgerald stated that these initiatives will be based on Remitly's current infrastructure, cost base, and client connections instead of marketing to new customers.
Furthermore, on June 4, Citizens maintained its Market Outperform rating and $26 price target for Remitly Global Inc. (NASDAQ:RELY). The firm stated that the loss of an early-stage investor does not impact its opinion of the company, which it sees as a long-term winner in the digital remittance market.
Remitly Global Inc. (NASDAQ:RELY) provides financial services, specifically cross-border remittance services, globally. The company is based in Seattle, Washington, and was founded in October 2018 by Matthew B. Oppenheimer and Joshua Hug.

3 months ago
Is OPY a good stock to buy? We came across a bullish thesis on Oppenheimer Holdings Inc. on TradersPro's Substack. In this article, we will summarize the bulls' thesis on OPY. Oppenheimer Holdings Inc.'s share was trading at $111.84 as of July 1st. OPY's trailing P/E was 13.33 according to Yahoo Finance.
Pixabay/Public Domain
Oppenheimer Holdings Inc. operates as a middle-market investment bank and full-service broker-dealer. OPY is positioned as a multi-stream financial services platform benefiting from a broad recovery in capital markets activity, where improving IPO issuance, rising M&A pipelines, and stronger wealth management inflows are combining to create a durable earnings expansion story.
Read More: 15 AI Stocks That Are Quietly Making Investors Rich
Read More: Undervalued AI Stock Poised For Massive Gains: 10000% Upside Potential


3 months ago
When **** e Exploration Technologies (SPCX) launched its initial public offering, investor demand swelled to $250 billion in comparison to a $75 billion fundraising plan. Clearly, there is euphoria, and within a few days of listing, SPCX approached $3 trillion in valuation. A cool-off seemed very likely, and the stock has corrected meaningfully from highs to the current market valuation of about $2 trillion.
As SPCX stock takes a breather, it's a good time to accumulate. Recently, Oppenheimer set a price target of $250 for the stock. Timothy Horan, Oppenheimer's tech **** yst, believes that the valuation is based on the potential in the AI **** e. In the near term, **** eX is likely to benefit from the $2 trillion communications market. Further, Horan opines that physical AI will be one of the "fastest-growing areas of AI over the next four to five years."
Memory Demand Sent Seagate Soaring — But This Stock Looks Even Better
Nvidia Is Still a Bargain. **** ysts See 57% Upside in NVDA Stock.
Roblox Shows Huge, Unusual Call Option Activity - Is RBLX Stock Too Cheap?


3 months ago
On June 16, just its third day of trading, ****** e Exploration Technologies (NASDAQ: SPCX), also known as ****** eX, was briefly the fourth-largest company by market cap. Its stock has pulled back since then, but it's still in the top 10 as of June 25.
The ****** e company's fast rise drew comparisons to Nvidia (NASDAQ: NVDA), the chipmaker that's currently the world's most valuable business. Some Wall Street ****** ysts have even predicted that ****** eX's market cap could surpass Nvidia's. Here's a look at the most bullish projections and how these two companies really compare.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's market cap sits at about $4.7 trillion, and multiple ****** ysts have set targets beyond that for ****** eX. Arete ****** yst Andrew Beale gave ****** eX a buy rating and a price target of $401 by the end of next year, which would translate to a market cap of about $5.3 trillion -- enough to surpass Nvidia's current market cap, although there's no telling exactly where it will be in the future.
Oppenheimer ****** yst Tim Horan predicts that ****** eX could be worth $10 trillion within five years. CNBC's Jim Cramer said ****** eX stock could grow very quickly after its IPO due to its small float, and he has made multiple market-cap predictions for it in television appearances, including $5 trillion and $6 trillion.