3 mins. ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na


9 mins. ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st


20 mins. ago
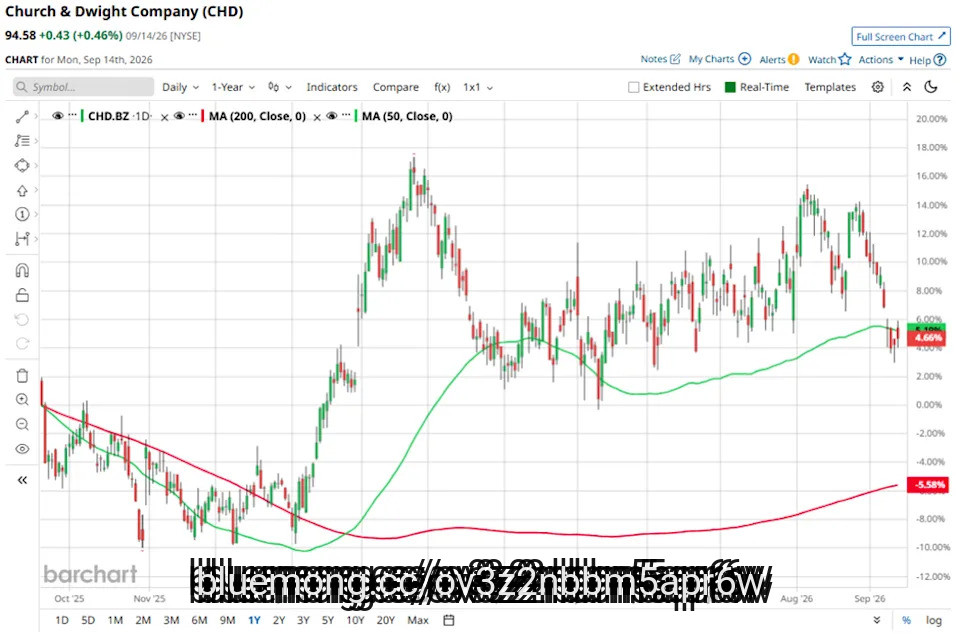
With a market cap of $22.4 billion, Church & Dwight Co., Inc. (CHD) is a leading developer, manufacturer, and marketer of household, personal care, and specialty products. Best known as the U.S. leader in sodium bicarbonate production, the company's portfolio includes iconic power brands such as ARM & HAMMER, Trojan, OxiClean, Waterpik, and Vitafusion.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean

48 mins. ago
Auxier ***** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong

53 mins. ago
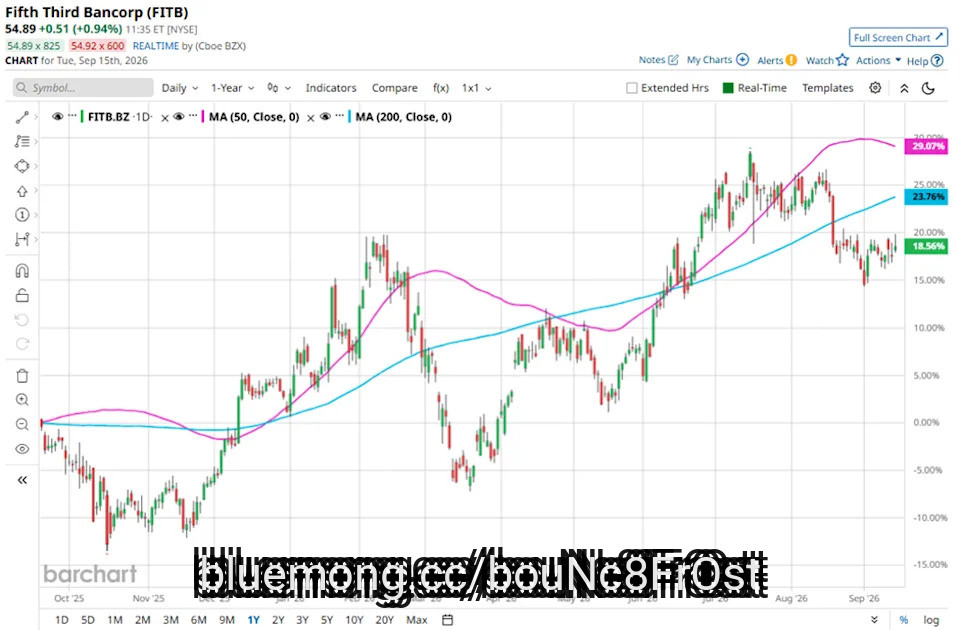
With a market cap of $49.3 billion, Fifth Third Bancorp (FITB) provides a broad range of financial products and services through its principal subsidiary, Fifth Third Bank, National **** ociation. The company operates across three segments: Commercial Banking; Consumer and Small Business Banking; and Wealth and **** et Management, serving individuals, businesses, government entities, and institutional clients.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Fifth Third Bancorp fits this criterion perfectly. The company offers services including lending, deposit products, wealth management, investment advisory, mortgage banking, and insurance solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#management #billion #Services
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Fifth Third Bancorp fits this criterion perfectly. The company offers services including lending, deposit products, wealth management, investment advisory, mortgage banking, and insurance solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#management #billion #Services



1 hr. ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current


2 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an ***** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed ***** ps."
#likely #wednesday
The Federal Reserve raised interest rates on Wednesday, marking its first hike in more than three years, in a move that will likely make borrowing more expensive while giving savers a modest boost.
Fed Chairman Kevin Warsh and the Federal Open Market Committee announced a widely expected quarter-point rate increase and indicated another to come.
The stock market's reaction to the Fed's announcement is likely to draw the most headlines, and John Shugar, a partner at Goldman Sachs, leans toward an optimistic scenario.
"You basically have a market where all of the heavy lifting has actually been done on the earnings side," Shugar said in an ***** ysis. He points to "terrific opportunities" in various AI consumer sectors, though "over the next few weeks, we may have a lot more speed ***** ps."
#likely #wednesday


2 hours ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue



2 hours ago
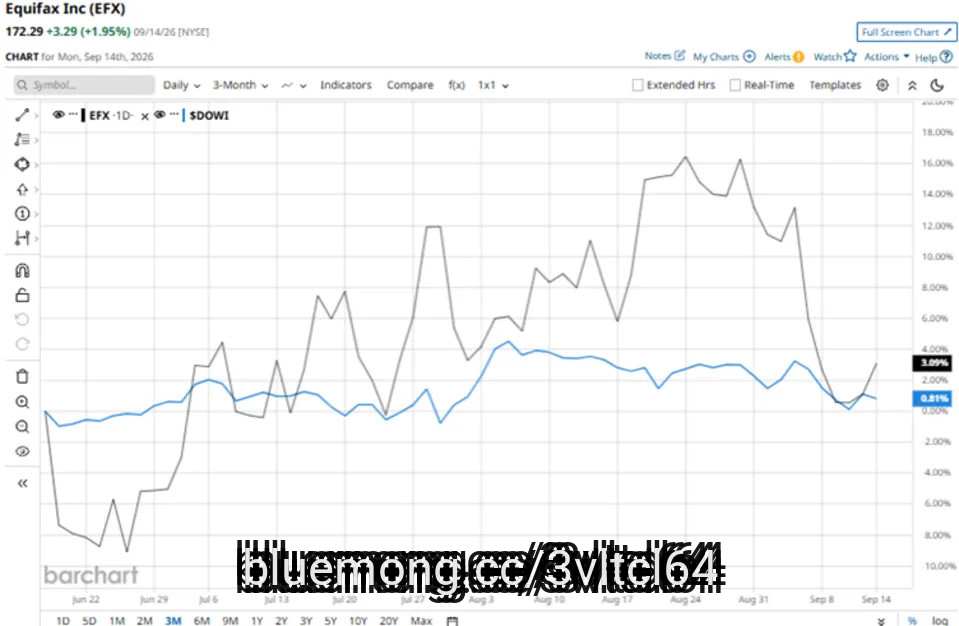
Equifax Inc. (EFX) is a global data, **** ytics, and technology company headquartered in Atlanta, Georgia. It operates as one of the "Big Three" credit bureaus, providing consumer and commercial credit reporting, identity and fraud solutions, and decisioning **** ytics to financial institutions, employers, governments, and other enterprises worldwide. The company has a market capitalization of $20.24 billion, which makes it a "big cap" stock.
The stock reached a 52-week low of $150.74 on June 22, but is up 14.3% from that level. Renewed confidence in Equifax's growth initiatives has sent the stock up 5.2% over the past three months. The broader Dow Jones Industrial Average ($DOWI) is up 2.4% over the same period. Therefore, the stock has outperformed the wider index over this period.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#credit #period #georgia
The stock reached a 52-week low of $150.74 on June 22, but is up 14.3% from that level. Renewed confidence in Equifax's growth initiatives has sent the stock up 5.2% over the past three months. The broader Dow Jones Industrial Average ($DOWI) is up 2.4% over the same period. Therefore, the stock has outperformed the wider index over this period.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#credit #period #georgia



2 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care

3 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#pr
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#pr


3 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea

8 hours ago
Kraft Heinz is a $25 billion global brand selling two million bottles of ketchup a day and it owns more than 200 other brands including Lunchables and Capri Sun. Reporting for TODAY, NBC's Vicky Nguyen sits down with new CEO, Steve Cahillane, to discuss where the company is headed as consumers move toward less-processed foods and more affordable store brands.
#heinz #reporting #today #vicky
#heinz #reporting #today #vicky



9 hours ago
By Lucia Mutikani
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded sharply in August as households boosted purchases of a range of goods while also spending more at restaurants and bars, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
The stronger-than-expected report from the Commerce Department on Wednesday prompted economists to upgrade their gross domestic product growth estimates for the third quarter. Together with other data on Wednesday showing a surge in import prices last month, strong demand sealed the argument for a widely anticipated interest rate increase from the Federal Reserve later in the day, economists said.
The reports followed data this month showing producer and consumer prices accelerated in August, while the labor market regained its poise after wobbling through much of summer.
"This reaffirms that the economy is more than capable of handling higher interest rates, providing the Fed plenty of scope to hike to get inflation under control," said Bradley Saunders, North America economist at Capital Economics.
#economists #data #month
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded sharply in August as households boosted purchases of a range of goods while also spending more at restaurants and bars, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
The stronger-than-expected report from the Commerce Department on Wednesday prompted economists to upgrade their gross domestic product growth estimates for the third quarter. Together with other data on Wednesday showing a surge in import prices last month, strong demand sealed the argument for a widely anticipated interest rate increase from the Federal Reserve later in the day, economists said.
The reports followed data this month showing producer and consumer prices accelerated in August, while the labor market regained its poise after wobbling through much of summer.
"This reaffirms that the economy is more than capable of handling higher interest rates, providing the Fed plenty of scope to hike to get inflation under control," said Bradley Saunders, North America economist at Capital Economics.
#economists #data #month
9 hours ago
U.S. median household income hit a record $87,460 in 2025, but lower-income earners saw no meaningful gains while top earners' income has surged 121% over 58 years.
Gasoline prices surged 27%, shelter rose 3%, and hospital services climbed 5% year-over-year, eroding purchasing power for households already spending most income on essentials.
Investors should favor companies with durable pricing power in essential categories and businesses built to serve cost-conscious consumers trading down on discretionary spending.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The latest Census Bureau data delivers a headline that sounds almost too good to be true: American households earned more in 2025 than ever before. But the numbers also explain why a record income figure can coexist with a persistent sense that the household budget is under pressure.
#income #earners #surged
Gasoline prices surged 27%, shelter rose 3%, and hospital services climbed 5% year-over-year, eroding purchasing power for households already spending most income on essentials.
Investors should favor companies with durable pricing power in essential categories and businesses built to serve cost-conscious consumers trading down on discretionary spending.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The latest Census Bureau data delivers a headline that sounds almost too good to be true: American households earned more in 2025 than ever before. But the numbers also explain why a record income figure can coexist with a persistent sense that the household budget is under pressure.
#income #earners #surged

9 hours ago
XLE has surged 46% year-to-date while XLY dropped 7%, with defensive XLP up 9% as markets rotate away from consumer exposure.
XLF's soft 4% gain signals financial stocks aren't pricing a healthy cycle, with the 10-year/2-year Treasury spread flattened to 0.33%.
Torres pegs $120 WTI as the consumer spending breaking point, still 20% above current prices but reminiscent of 2022's economy-crushing oil surge.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
The national average price of regular gasoline jumped 16 cents in a single week to $4.32 a gallon on September 14, 2026, a move that puts the pump price in the 90th percentile of the past year and caps a 7.8% jump in one month. The proximate cause sits upstream: WTI crude cleared $97.26 a barrel on September 9 after running up 16.1% in a month, and Brent has traded through the $100 line. On Fed decision day, a CNBC Morning Call panel put a number on where this stops being an inconvenience and starts being a recession.
#Consumer #torres
XLF's soft 4% gain signals financial stocks aren't pricing a healthy cycle, with the 10-year/2-year Treasury spread flattened to 0.33%.
Torres pegs $120 WTI as the consumer spending breaking point, still 20% above current prices but reminiscent of 2022's economy-crushing oil surge.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
The national average price of regular gasoline jumped 16 cents in a single week to $4.32 a gallon on September 14, 2026, a move that puts the pump price in the 90th percentile of the past year and caps a 7.8% jump in one month. The proximate cause sits upstream: WTI crude cleared $97.26 a barrel on September 9 after running up 16.1% in a month, and Brent has traded through the $100 line. On Fed decision day, a CNBC Morning Call panel put a number on where this stops being an inconvenience and starts being a recession.
#Consumer #torres

9 hours ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #fund #conventum #global
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #fund #conventum #global

9 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund #letter


9 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth


10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter

10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Revolution Medicines, Inc. (NASDAQ:RVMD) as a new addition. Revolution Medicines, Inc. (NASDAQ:RVMD) is a clinical-stage precision oncology company that develops novel targeted therapies for RAS-addicted cancers. On September 15, 2026, Revolution Medicines, Inc. (NASDAQ:RVMD) closed at $204.86 per share. Over the past month, Revolution Medicines, Inc. (NASDAQ:RVMD) declined 6.53% and its shares gained 358.00% over the past 52 weeks. Revolution Medicines, Inc. (NASDAQ:RVMD) has a market capitalization of $43.91 billion.
Parnassus Growth Equity Fund stated the following regarding Revolution Medicines, Inc. (NASDAQ:RVMD) in its Q2 2026 investor letter:
"In the Health Care sector, we see compelling long-term idiosyncratic growth opportunities in drug discovery, diagnostics and medical innovation. During the quarter, we added Revolution Medicines, Inc. (NASDAQ:RVMD), developer of a promising new drug for pancreatic cancer. Revolution Medicines' lead drug candidate, daraxonrasib, has delivered strong late-stage clinical results in pancreatic cancer, with data suggesting it could become a new standard of care and support significant commercial potential, alongside additional opportunities in other cancers over time."
Revolution Medicines, Inc. (NASDAQ:RVMD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 105 hedge fund portfolios held Revolution Medicines, Inc. (NASDAQ:RVMD) at the end of the second quarter, compared to 106 in the previous quarter. While we acknowledge the potential of Revolution Medicines, Inc. (NASDAQ:RVMD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Tr
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Revolution Medicines, Inc. (NASDAQ:RVMD) as a new addition. Revolution Medicines, Inc. (NASDAQ:RVMD) is a clinical-stage precision oncology company that develops novel targeted therapies for RAS-addicted cancers. On September 15, 2026, Revolution Medicines, Inc. (NASDAQ:RVMD) closed at $204.86 per share. Over the past month, Revolution Medicines, Inc. (NASDAQ:RVMD) declined 6.53% and its shares gained 358.00% over the past 52 weeks. Revolution Medicines, Inc. (NASDAQ:RVMD) has a market capitalization of $43.91 billion.
Parnassus Growth Equity Fund stated the following regarding Revolution Medicines, Inc. (NASDAQ:RVMD) in its Q2 2026 investor letter:
"In the Health Care sector, we see compelling long-term idiosyncratic growth opportunities in drug discovery, diagnostics and medical innovation. During the quarter, we added Revolution Medicines, Inc. (NASDAQ:RVMD), developer of a promising new drug for pancreatic cancer. Revolution Medicines' lead drug candidate, daraxonrasib, has delivered strong late-stage clinical results in pancreatic cancer, with data suggesting it could become a new standard of care and support significant commercial potential, alongside additional opportunities in other cancers over time."
Revolution Medicines, Inc. (NASDAQ:RVMD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 105 hedge fund portfolios held Revolution Medicines, Inc. (NASDAQ:RVMD) at the end of the second quarter, compared to 106 in the previous quarter. While we acknowledge the potential of Revolution Medicines, Inc. (NASDAQ:RVMD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Tr

10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#lumentum #lite #Growth #investor
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#lumentum #lite #Growth #investor

10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #fund
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #fund

10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands


10 hours ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc., a leading subscription-based streaming entertainment platform, detracted from the fund's performance during the quarter. On September 15, 2026, Netflix, Inc. closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. posted a one‑month return of -3.50%, while its shares lost 36.99% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) reported solid first-quarter results, but company management did not raise revenue guidance for the full year, disappointing some investors. Cofounder Reed Hastings announced plans to step down from the board, which may have further weighed on shares."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #investor
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc., a leading subscription-based streaming entertainment platform, detracted from the fund's performance during the quarter. On September 15, 2026, Netflix, Inc. closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. posted a one‑month return of -3.50%, while its shares lost 36.99% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) reported solid first-quarter results, but company management did not raise revenue guidance for the full year, disappointing some investors. Cofounder Reed Hastings announced plans to step down from the board, which may have further weighed on shares."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #investor

11 hours ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#NYSE
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#NYSE

11 hours ago
Walmart and SCAN Health Plan announced a partnership on Wednesday to offer co-branded Medicare Advantage plans in two states, targeting a pool of more than two million Medicare enrollees.
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#plan #Wellness #members #advantage
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#plan #Wellness #members #advantage
12 hours ago
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded more than expected in August as households stepped up purchases of motor vehicles and stocked up for the new school year, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
Retail sales jumped 1.2% last month after a revised 0.5% drop in July, which was the first decline in nine months, the Commerce Department's Census Bureau said on Wednesday. Economists polled by Reuters had forecast retail sales, which are mostly goods and are not adjusted for inflation, rebounding 0.8% after a previously reported 0.6% drop in July. Estimates ranged from as low as a 0.2% gain to as high as a 1.1% increase.
Last month's increase also partially reflected higher gasoline prices, which lifted receipts at service stations.
Households have continued to spend despite stubbornly high inflation because of the oil price shock and supply chain strains from the U.S.-led war with Iran. Consumers have, however, become more selective and are seeking lower-priced goods. Consumer sentiment deteriorated this month.
Spending is being supported by steady wage growth and recent stock market gains. Households are also saving less and tapping into their nest eggs. The strength in retail sales, together with elevated price pressures and a labor market that is regaining its poise after wobbling through much of summer, further strengthens financial market expectations that the Federal Reserve will raise interest rates later on Wednesday.
#sales #wednesday
Retail sales jumped 1.2% last month after a revised 0.5% drop in July, which was the first decline in nine months, the Commerce Department's Census Bureau said on Wednesday. Economists polled by Reuters had forecast retail sales, which are mostly goods and are not adjusted for inflation, rebounding 0.8% after a previously reported 0.6% drop in July. Estimates ranged from as low as a 0.2% gain to as high as a 1.1% increase.
Last month's increase also partially reflected higher gasoline prices, which lifted receipts at service stations.
Households have continued to spend despite stubbornly high inflation because of the oil price shock and supply chain strains from the U.S.-led war with Iran. Consumers have, however, become more selective and are seeking lower-priced goods. Consumer sentiment deteriorated this month.
Spending is being supported by steady wage growth and recent stock market gains. Households are also saving less and tapping into their nest eggs. The strength in retail sales, together with elevated price pressures and a labor market that is regaining its poise after wobbling through much of summer, further strengthens financial market expectations that the Federal Reserve will raise interest rates later on Wednesday.
#sales #wednesday


12 hours ago
Alluvium ****** et Management, an ****** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted LyondellBasell Industries N.V. (NYSE:LYB). LyondellBasell Industries N.V. (NYSE:LYB) is a multinational chemical and plastic manufacturing company. On September 15, 2026, LyondellBasell Industries N.V. (NYSE:LYB) closed at $65.43 per share. Over the past month, LyondellBasell Industries N.V. (NYSE:LYB) declined 0.95% while its shares gained 22.25% over the past 52 weeks. LyondellBasell Industries N.V. (NYSE:LYB) has a market capitalization of $21.14 billion, and its stock has traded within a 52-week range of $41.58 and $83.94.
Conventum – Alluvium Global Fund stated the following regarding LyondellBasell Industries N.V. (NYSE:LYB) in its Q2 2026 investor letter:
"LyondellBasell Industries N.V. (NYSE:LYB), the plastics producer gave back some of that 88.3% return of last quarter, and fell 34.0%, We are continually amazed by the market's response to the war in Iraq. It seems that this so called "ceasefire" (the one where Iran keeps attacking ships in the Strait of Hormuz and the US keeps bombing) has led to expectations that all is well for the affected commodity markets. Management provided results in early May, and reported expectations that the higher prices will be sustained for some time. That makes sense to us. But since then, Polyethylene and Polypropylene prices, for example, have fallen by around 15%. After we sold around two thirds of our holding during the March quarter, we ceased as the price fell to levels below our valuation. It currently accounts for 2.1% of the Fund and we are comfortable with maintaining this position."
LyondellBasell Industries N.V. (NYSE:LYB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 57 hedge fund portfolios held LyondellBasell Industries N.V. (NYSE:LYB) at the end of the second quarter which was 59 in the previous quarter. While we acknowledge the potential of LyondellBasell Industries N.V. (NYSE:LYB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted LyondellBasell Industries N.V. (NYSE:LYB). LyondellBasell Industries N.V. (NYSE:LYB) is a multinational chemical and plastic manufacturing company. On September 15, 2026, LyondellBasell Industries N.V. (NYSE:LYB) closed at $65.43 per share. Over the past month, LyondellBasell Industries N.V. (NYSE:LYB) declined 0.95% while its shares gained 22.25% over the past 52 weeks. LyondellBasell Industries N.V. (NYSE:LYB) has a market capitalization of $21.14 billion, and its stock has traded within a 52-week range of $41.58 and $83.94.
Conventum – Alluvium Global Fund stated the following regarding LyondellBasell Industries N.V. (NYSE:LYB) in its Q2 2026 investor letter:
"LyondellBasell Industries N.V. (NYSE:LYB), the plastics producer gave back some of that 88.3% return of last quarter, and fell 34.0%, We are continually amazed by the market's response to the war in Iraq. It seems that this so called "ceasefire" (the one where Iran keeps attacking ships in the Strait of Hormuz and the US keeps bombing) has led to expectations that all is well for the affected commodity markets. Management provided results in early May, and reported expectations that the higher prices will be sustained for some time. That makes sense to us. But since then, Polyethylene and Polypropylene prices, for example, have fallen by around 15%. After we sold around two thirds of our holding during the March quarter, we ceased as the price fell to levels below our valuation. It currently accounts for 2.1% of the Fund and we are comfortable with maintaining this position."
LyondellBasell Industries N.V. (NYSE:LYB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 57 hedge fund portfolios held LyondellBasell Industries N.V. (NYSE:LYB) at the end of the second quarter which was 59 in the previous quarter. While we acknowledge the potential of LyondellBasell Industries N.V. (NYSE:LYB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-