30 mins. ago
Sept 15, 2026, 2:38 pm EDT
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana


31 mins. ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose

48 mins. ago
Sept 15, 2026, 2:25 pm EDT
Creative Planning is already one of the nation’s largest registered investment advisors serving individual investors. Now, it has ambitions to serve more institutional clients too.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Welcome to Barron's Advisor! Our articles are free to Barron's subscribers and wealth management professionals. To subscribe to Barron's, click here. If you're a wealth management professional and would like access to the Barron's Advisor experience, please provide the information below.
If you're not a wealth management professional, you can find other great financial content at barrons.com. If you have any questions, please contact us at advisor.editorsbarrons.com.
#management #please
Creative Planning is already one of the nation’s largest registered investment advisors serving individual investors. Now, it has ambitions to serve more institutional clients too.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Welcome to Barron's Advisor! Our articles are free to Barron's subscribers and wealth management professionals. To subscribe to Barron's, click here. If you're a wealth management professional and would like access to the Barron's Advisor experience, please provide the information below.
If you're not a wealth management professional, you can find other great financial content at barrons.com. If you have any questions, please contact us at advisor.editorsbarrons.com.
#management #please
53 mins. ago
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
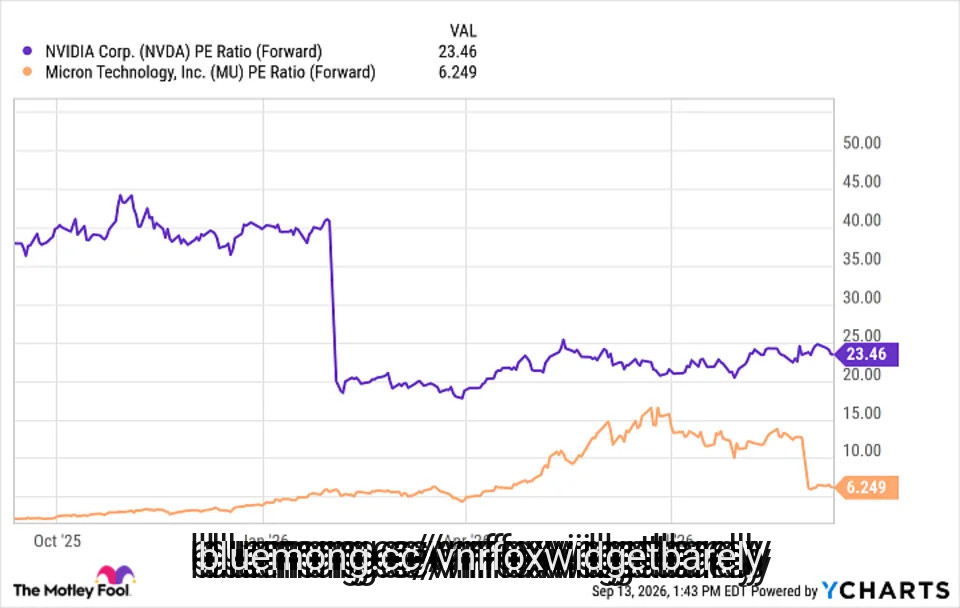
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker


55 mins. ago
By Karen Roman
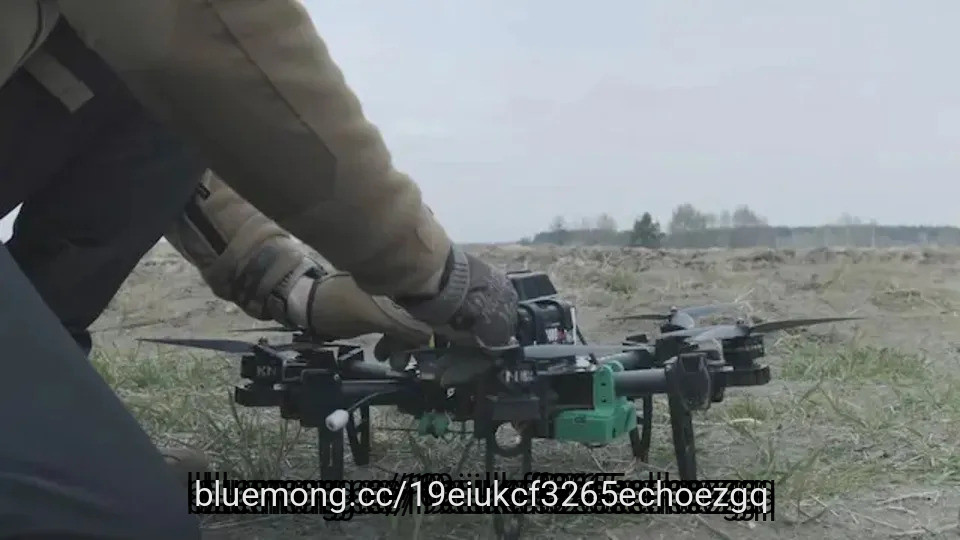
Swarmer, Inc.'s (Nasdaq: SWMR) pending acquisition ofUkrainian unmanned-ground-vehicle maker Ratel Robotics could lead to $200 million in 2027 revenue and $20 million in adjusted EBITDA, according to a research note by Lucid Capital Markets.
Swarmer, which boasts Blackwater founder and industry veteran Erik Prince as its non-executive chairman, is in a definitive agreement to buy Ratel for up to $224 million and it has $86 million in secured contracts and about 37% share of Ukrainian government UGV procurement spending, the note said.
The deal comes as Ukraine's drone industry is beginning a consolidation phase, with more than 500 credible drone companies operating in the country while being home to some of the world's advanced battlefield drone technology, it said.
Swarmer could potentially consolidate Ukraine's fragmented drone industry into a full-stack drones, autonomy software and ground-vehicle platform, the note said.
#swarmer #note #vehicle #roman
Swarmer, Inc.'s (Nasdaq: SWMR) pending acquisition ofUkrainian unmanned-ground-vehicle maker Ratel Robotics could lead to $200 million in 2027 revenue and $20 million in adjusted EBITDA, according to a research note by Lucid Capital Markets.
Swarmer, which boasts Blackwater founder and industry veteran Erik Prince as its non-executive chairman, is in a definitive agreement to buy Ratel for up to $224 million and it has $86 million in secured contracts and about 37% share of Ukrainian government UGV procurement spending, the note said.
The deal comes as Ukraine's drone industry is beginning a consolidation phase, with more than 500 credible drone companies operating in the country while being home to some of the world's advanced battlefield drone technology, it said.
Swarmer could potentially consolidate Ukraine's fragmented drone industry into a full-stack drones, autonomy software and ground-vehicle platform, the note said.
#swarmer #note #vehicle #roman


2 hours ago
Boeing (BA) grew revenue faster over the past twelve months than any of its aerospace and defense peers, GE Aerospace included, and its stock still fell. It is also the only one in that group running an operating loss. The growth has come with rising airplane deliveries, and the market is waiting to see whether those airplanes earn a margin.
GE Aerospace is the sharpest comparison. It grew revenue 21.7% over the trailing twelve months, close to Boeing's 24.8%, on an operating margin of 18.7%, and its stock returned 13.4%. Boeing's operating margin over the same twelve months was negative 5.4%. Its stock returned negative 4.4%.
BA
RTX
LMT
#aerospace #twelve #months #operating
GE Aerospace is the sharpest comparison. It grew revenue 21.7% over the trailing twelve months, close to Boeing's 24.8%, on an operating margin of 18.7%, and its stock returned 13.4%. Boeing's operating margin over the same twelve months was negative 5.4%. Its stock returned negative 4.4%.
BA
RTX
LMT
#aerospace #twelve #months #operating


2 hours ago
Agriscience business Corteva (CTVA) is gearing up to spin off its seed operating segment as an independently traded public company, Vylor, trading under the "VYLR" ticker. Shareholders have already approved the separation, and they are expected to receive one Vylor common share for each Corteva common share they hold. VYLR is set to begin trading on Oct. 1. The company is holding an Investor Day webcast on Sept. 15.
Corteva believes this spinoff will give both companies more flexibility. However, ****** ysts have questioned whether it weakens the entities. Meanwhile, CEO Luke Kissam has highlighted a pipeline Corteva values at $11 billion through 2040 and its plan to introduce 12 products over the next decade. Contrarily, competition from generic products remains, and President Donald Trump's administration is exploring whether consolidation among agricultural suppliers has driven up input costs.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
#corteva
Corteva believes this spinoff will give both companies more flexibility. However, ****** ysts have questioned whether it weakens the entities. Meanwhile, CEO Luke Kissam has highlighted a pipeline Corteva values at $11 billion through 2040 and its plan to introduce 12 products over the next decade. Contrarily, competition from generic products remains, and President Donald Trump's administration is exploring whether consolidation among agricultural suppliers has driven up input costs.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
#corteva



2 hours ago
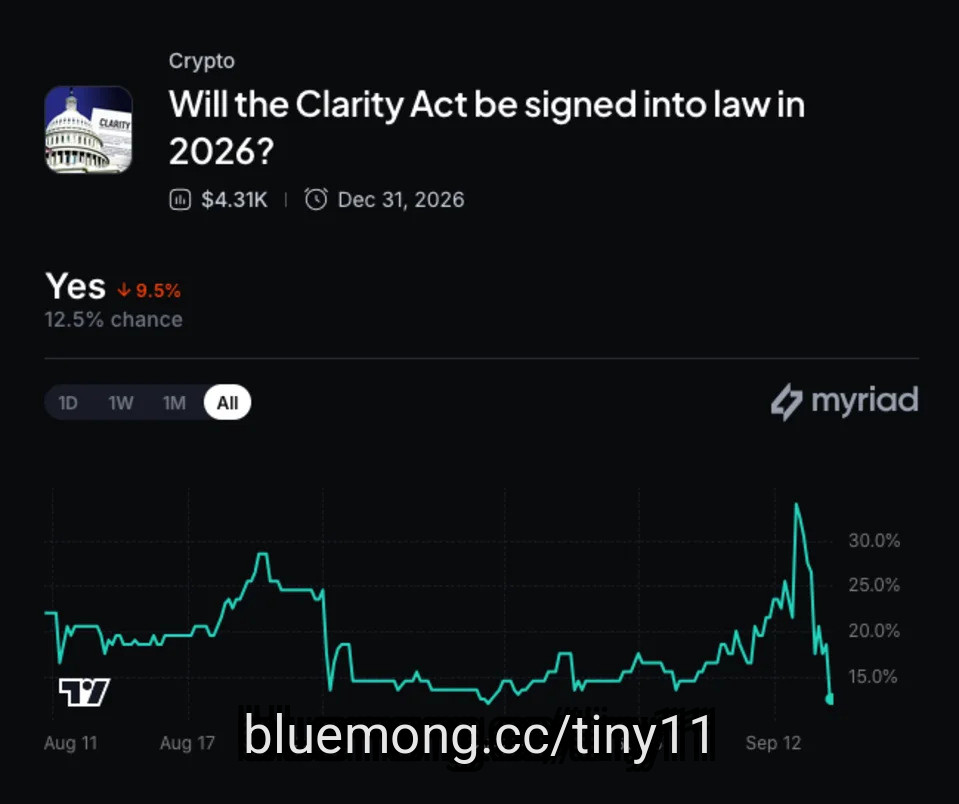
Crypto markets and related stocks moved lower Tuesday as investors braced for two major Washington catalysts: a Senate vote on the CLARITY Act and the Federal Reserve's interest-rate decision Wednesday.
Bitcoin was trading around $76,431, down 2.19% over 24 hours, while Ether fell 1.8% to roughly $2,449 and Solana dropped 1.02% to about $100. The total crypto market capitalization declined 1.2% to $2.61 trillion.
Derivatives traders were also caught in the selloff. Roughly $384 million in crypto positions were liquidated over 24 hours, including about $195 million in longs and $189 million in shorts, while nearly $160 million was wiped out over the previous 12 hours.
Crypto-linked stocks were hit harder.
Related: CLARITY Act faces urgent Democratic counterproposal and growing opposition
#hours #tuesday
Bitcoin was trading around $76,431, down 2.19% over 24 hours, while Ether fell 1.8% to roughly $2,449 and Solana dropped 1.02% to about $100. The total crypto market capitalization declined 1.2% to $2.61 trillion.
Derivatives traders were also caught in the selloff. Roughly $384 million in crypto positions were liquidated over 24 hours, including about $195 million in longs and $189 million in shorts, while nearly $160 million was wiped out over the previous 12 hours.
Crypto-linked stocks were hit harder.
Related: CLARITY Act faces urgent Democratic counterproposal and growing opposition
#hours #tuesday

2 hours ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price


2 hours ago
Updated Sept 15, 2026, 1:23 pm EDT / Original Sept 15, 2026, 12:51 pm EDT
Nicholas Colas doesn’t see
5% Treasury yields
as a stock market spoiler. Instead, the co-founder of DataTrek Research sees them as a healthy reset of interest rates that could pave the way for more sustainable growth.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Rising oil prices and a 10-year Treasury yield climbing to around 5% have raised concerns about consumer spending and restaurant operating costs.
#nicholas
Nicholas Colas doesn’t see
5% Treasury yields
as a stock market spoiler. Instead, the co-founder of DataTrek Research sees them as a healthy reset of interest rates that could pave the way for more sustainable growth.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Rising oil prices and a 10-year Treasury yield climbing to around 5% have raised concerns about consumer spending and restaurant operating costs.
#nicholas

2 hours ago
CrowdStrike (CRWD) shares closed higher on Monday after tech leaders, including Dario Amodei, Sam Altman, and Elon Musk, warned artificial intelligence (AI) capabilities are advancing faster than safety guardrails. The stock's upward momentum has continued on Tuesday.
These high-profile warnings heightened enterprise concerns about autonomous, AI-driven cyber threats capable of executing automated network intrusions at unprecedented speeds.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
#crowdstrike #crwd #elon #goldman
These high-profile warnings heightened enterprise concerns about autonomous, AI-driven cyber threats capable of executing automated network intrusions at unprecedented speeds.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
#crowdstrike #crwd #elon #goldman


2 hours ago
Brent crude climbed above $108 a barrel on Tuesday as traders grew increasingly uncertain about when Saudi Arabia's East-West Pipeline would reopen, with fresh Houthi attacks on the kingdom and suspended oil loadings at its Red Sea export terminal adding to supply fears.
By 1:00 p.m. ET, Brent futures had climbed 3% to $108.88 per barrel, with U.S. West Texas Intermediate up 4.7% at $106.12. A close at those levels would mark the highest settlement for either contract in close to four months, according to Reuters. Prices have risen around 20% this month as fighting in the Persian Gulf has escalated.
According to shipping industry sources who spoke with Reuters, crude loadings at the Yanbu terminal on Saudi Arabia's Red Sea coast had been halted as of Tuesday. Separately, sources told Reuters that Saudi officials had notified European buyers that certain crude shipments scheduled for late September would not proceed.
Saudi Arabia shut down the East-West Pipeline after drone attacks originating from Iraq struck it last week, forcing the kingdom to halt the export route it had been using to bypass the Strait of Hormuz during the U.S.-Iran war. The pipeline can move up to 7 million barrels per day. Saudi officials have described the closure as a precautionary measure but have not provided a damage ******* sment or a timeline for resuming operations. U.K. authorities fear the pipeline may remain mostly shut for six weeks, according to Bloomberg.
Iran-backed Houthi militants in Yemen carried out additional strikes on Saudi Arabia on Monday. According to a spokesperson for the Saudi-led military coalition in Yemen, the group fired drones and ballistic missiles targeting the cities of Khamis Mushait, Abha, and Taif. According to Reuters, the Houthis claimed to have struck a military air base in Khamis Mushait, with their stated targets including hangars, radar installations, runway infrastructure, and stores of ammunition.
#west #east
By 1:00 p.m. ET, Brent futures had climbed 3% to $108.88 per barrel, with U.S. West Texas Intermediate up 4.7% at $106.12. A close at those levels would mark the highest settlement for either contract in close to four months, according to Reuters. Prices have risen around 20% this month as fighting in the Persian Gulf has escalated.
According to shipping industry sources who spoke with Reuters, crude loadings at the Yanbu terminal on Saudi Arabia's Red Sea coast had been halted as of Tuesday. Separately, sources told Reuters that Saudi officials had notified European buyers that certain crude shipments scheduled for late September would not proceed.
Saudi Arabia shut down the East-West Pipeline after drone attacks originating from Iraq struck it last week, forcing the kingdom to halt the export route it had been using to bypass the Strait of Hormuz during the U.S.-Iran war. The pipeline can move up to 7 million barrels per day. Saudi officials have described the closure as a precautionary measure but have not provided a damage ******* sment or a timeline for resuming operations. U.K. authorities fear the pipeline may remain mostly shut for six weeks, according to Bloomberg.
Iran-backed Houthi militants in Yemen carried out additional strikes on Saudi Arabia on Monday. According to a spokesperson for the Saudi-led military coalition in Yemen, the group fired drones and ballistic missiles targeting the cities of Khamis Mushait, Abha, and Taif. According to Reuters, the Houthis claimed to have struck a military air base in Khamis Mushait, with their stated targets including hangars, radar installations, runway infrastructure, and stores of ammunition.
#west #east

2 hours ago
The exchange-traded fund (ETF) market's August numbers look flawless on the surface, until you look at where the money actually went.
The industry held $16.4 trillion in ******* ets through August 31, 2026, with $180 billion in fresh capital pouring in that month alone, 3.8 times the historical August average and the strongest August on record for fund inflows, State Street reported.
New fund creation has been equally prolific, with 1,023 ETFs debuting in the first eight months of 2026, a 52% jump from the previous year's pace.
Active strategies represent more than 80% of the year's new products, and about 25% of August's 134 launches used leveraged or inverse structures, FactSet noted.
Among August's new launches were 18 single-stock ETFs, most of them targeting semiconductor companies to tap into the artificial intelligence infrastructure buildout.
#august #state #street #exchange
The industry held $16.4 trillion in ******* ets through August 31, 2026, with $180 billion in fresh capital pouring in that month alone, 3.8 times the historical August average and the strongest August on record for fund inflows, State Street reported.
New fund creation has been equally prolific, with 1,023 ETFs debuting in the first eight months of 2026, a 52% jump from the previous year's pace.
Active strategies represent more than 80% of the year's new products, and about 25% of August's 134 launches used leveraged or inverse structures, FactSet noted.
Among August's new launches were 18 single-stock ETFs, most of them targeting semiconductor companies to tap into the artificial intelligence infrastructure buildout.
#august #state #street #exchange

3 hours ago
ARK Invest sold over 142,000 CRCL shares Monday across ARKK and ARKW, pushing Circle Internet down 8% despite a 25% monthly gain.
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin



3 hours ago
Saudi Arabia suspends Yanbu oil loadings after halting its East-West pipeline, sending Brent back to $108.
Asia's Oil Crunch Sends Regional Benchmarks to Record Highs
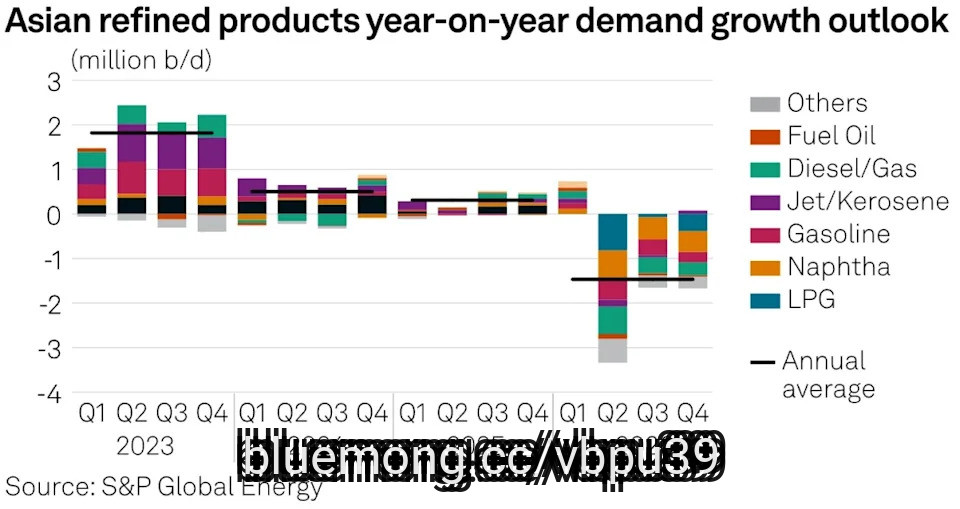
- Asia's oil industry is facing a double whammy of supply shortages and better-than-expected demand, with crude differentials across the region gradually climbing towards record highs.
- Futures prices on China's Shanghai Futures Exchange rose to $138 per barrel on Tuesday, the highest reading on record, as Chinese refiners scramble to put their hands on available October supply.
- Saudi Aramco's announced halt in Yanbu loadings could see some recovery in exports from Saudi terminals in the Gulf, however these flows would be massively constrained by unprecedented freight rates.
#record #highs #supply #west
Asia's Oil Crunch Sends Regional Benchmarks to Record Highs
- Asia's oil industry is facing a double whammy of supply shortages and better-than-expected demand, with crude differentials across the region gradually climbing towards record highs.
- Futures prices on China's Shanghai Futures Exchange rose to $138 per barrel on Tuesday, the highest reading on record, as Chinese refiners scramble to put their hands on available October supply.
- Saudi Aramco's announced halt in Yanbu loadings could see some recovery in exports from Saudi terminals in the Gulf, however these flows would be massively constrained by unprecedented freight rates.
#record #highs #supply #west


3 hours ago
The House Ways and Means Committee will consider legislation Wednesday that would exempt some crypto transaction fees from capital-gains calculations and apply new federal tax rules to stablecoins, staking, mining and digital ***** et trading.
Committee Chairman Jason Smith, R-Mo., introduced the 114-page Digital ***** et Tax Certainty Act, or H.R. 10357. The committee has scheduled its markup for 10 a.m. Eastern on Sept. 16.
During a markup, committee members debate a bill, propose amendments, and decide whether to advance it to the full House.
The legislation would create a "de minimis" exemption for qualifying network or transaction fees of $10 or less. De minimis refers to an amount considered too small to require standard tax treatment.
Paying a blockchain fee with crypto can create a taxable event because the IRS treats digital ***** ets as property. The exemption would allow taxpayers to disregard gains or losses on eligible fees.
#committee #digital #asset
Committee Chairman Jason Smith, R-Mo., introduced the 114-page Digital ***** et Tax Certainty Act, or H.R. 10357. The committee has scheduled its markup for 10 a.m. Eastern on Sept. 16.
During a markup, committee members debate a bill, propose amendments, and decide whether to advance it to the full House.
The legislation would create a "de minimis" exemption for qualifying network or transaction fees of $10 or less. De minimis refers to an amount considered too small to require standard tax treatment.
Paying a blockchain fee with crypto can create a taxable event because the IRS treats digital ***** ets as property. The exemption would allow taxpayers to disregard gains or losses on eligible fees.
#committee #digital #asset

3 hours ago
This story was originally published on CX Dive. To receive daily news and insights, subscribe to our free daily CX Dive newsletter.
More than half of consumers — 56% — have left brands that ignored their feedback, according to a survey of 1,500 consumers and 750 digital leaders from Quantum Metric, released earlier this month.
Fewer than 1 in 5 consumers see surveys as an effective way to provide their feedback, and another one-third said they don't feel heard by digital brands at all.
One-quarter of digital leaders have daily access to recent customer feedback, while about half — 52% — have no formal process for acting on the feedback they do collect, the report found.
Gathering data on customer sentiment and behavior without acting on it is a fruitless exercise, but taking action on data is easier said than done.
#consumers #digital #half #leaders
More than half of consumers — 56% — have left brands that ignored their feedback, according to a survey of 1,500 consumers and 750 digital leaders from Quantum Metric, released earlier this month.
Fewer than 1 in 5 consumers see surveys as an effective way to provide their feedback, and another one-third said they don't feel heard by digital brands at all.
One-quarter of digital leaders have daily access to recent customer feedback, while about half — 52% — have no formal process for acting on the feedback they do collect, the report found.
Gathering data on customer sentiment and behavior without acting on it is a fruitless exercise, but taking action on data is easier said than done.
#consumers #digital #half #leaders


3 hours ago
Nvidia's (NVDA) Vera Rubin GPUs claim 70% of the $4M VR200 rack bill of materials, while Micron (MU) benefits from the 22% memory slice.
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera


3 hours ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects

3 hours ago
Sept 15, 2026, 11:57 am EDT
Guggenheim ******* yst
Michael Ciarmoli
sees a lot of opportunity in the
beaten-up
defense sector. Monday, he launched coverage of almost two dozen stocks. He has a baker’s dozen buys, with some surprising price targets.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Higher borrowing costs could make it harder for restaurant chains to open new locations at the pace investors expect.
#dozen #guggenheim #jones #rights
Guggenheim ******* yst
Michael Ciarmoli
sees a lot of opportunity in the
beaten-up
defense sector. Monday, he launched coverage of almost two dozen stocks. He has a baker’s dozen buys, with some surprising price targets.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Higher borrowing costs could make it harder for restaurant chains to open new locations at the pace investors expect.
#dozen #guggenheim #jones #rights

4 hours ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine


4 hours ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics

4 hours ago
Sept 15, 2026, 11:22 am EDT
Cybersecurity stocks have racked up huge gains spurred by the latest artificial-intelligence safety debate. **** ysts at J.P. Morgan have five names in the sector they’re feeling particularly positive about.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Nicholas Colas, co-founder of DataTrek Research, says “the market is doing the work of the Fed by slowing the economy and reducing inflation pressures.”
#sept #Cybersecurity
Cybersecurity stocks have racked up huge gains spurred by the latest artificial-intelligence safety debate. **** ysts at J.P. Morgan have five names in the sector they’re feeling particularly positive about.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Nicholas Colas, co-founder of DataTrek Research, says “the market is doing the work of the Fed by slowing the economy and reducing inflation pressures.”
#sept #Cybersecurity

4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend

4 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

5 hours ago
KeyBanc targets $400 for MRVL, implying 83% upside, as the stock sits 34% below its 52-week high despite record Q2 revenue up 37% year-over-year.
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits
5 hours ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year


5 hours ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o


5 hours ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

5 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio