

28 days ago
The Boeing Company (NYSE:BA) was trading at around $193 on October 5, down 11.91% over twelve months. Boeing reported net income of $2.09 billion over the past twelve months. Its EBITDA over the same period was negative $2.9 billion.
Those two figures describe the same year and point in opposite directions. Only one of them tells you what the business did.
READ ALSO: GE Aerospace (GE) vs. RTX (RTX): Which Is the Better Stock to Buy?
Start with the figure that describes the aircraft business itself. Boeing's operating margin is 0.00%. On $93.99 billion of revenue, building and selling airplanes earned nothing.
That is not a rounding problem. Gross profit was $4.43 billion on that revenue, under five percent for a manufacturer, which means the cost of building the aircraft very nearly equals what customers pay for them.
#same
Those two figures describe the same year and point in opposite directions. Only one of them tells you what the business did.
READ ALSO: GE Aerospace (GE) vs. RTX (RTX): Which Is the Better Stock to Buy?
Start with the figure that describes the aircraft business itself. Boeing's operating margin is 0.00%. On $93.99 billion of revenue, building and selling airplanes earned nothing.
That is not a rounding problem. Gross profit was $4.43 billion on that revenue, under five percent for a manufacturer, which means the cost of building the aircraft very nearly equals what customers pay for them.
#same

2 months ago
On Monday, Sept. 21, Sandisk (NASDAQ:SNDK) takes a spot in the S&P 100, a subset of the S&P 500 (SNPINDEX:^GSPC) made up of 100 of its largest blue-chip companies. Dell Technologies, Palo Alto Networks, and Arista Networks enter with it. The announcement came from S&P Dow Jones Indices on Sept. 4, and the changes take effect before Monday's open.
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies

2 months ago
Interested in Keysight Technologies Inc.? Here are five stocks we like better.
AI data-center demand is driving strong growth in Keysight's wireline business, particularly around 1.6T and emerging 3.2T networking, silicon photonics, co-packaged optics and system-level testing.
Demand currently exceeds supply, with Keysight expanding manufacturing capacity, supplier agreements and component sourcing; revenue beyond its typical order-to-revenue window was approaching $100 million.
Keysight expects additional growth from 6G, aerospace and defense, semiconductors and software-defined vehicles. The company anticipates 6G acceleration in the first half of 2028 and plans to maintain investment while targeting incremental margins of at least 40% when growth exceeds 5%.
3 Lesser-Known Quantum Plays the Market May Be Overlooking Right Now
#exceeds #lesser
AI data-center demand is driving strong growth in Keysight's wireline business, particularly around 1.6T and emerging 3.2T networking, silicon photonics, co-packaged optics and system-level testing.
Demand currently exceeds supply, with Keysight expanding manufacturing capacity, supplier agreements and component sourcing; revenue beyond its typical order-to-revenue window was approaching $100 million.
Keysight expects additional growth from 6G, aerospace and defense, semiconductors and software-defined vehicles. The company anticipates 6G acceleration in the first half of 2028 and plans to maintain investment while targeting incremental margins of at least 40% when growth exceeds 5%.
3 Lesser-Known Quantum Plays the Market May Be Overlooking Right Now
#exceeds #lesser

2 months ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi


2 months ago
On September 15, Guggenheim ****** yst Michael Ciarmoli initiated coverage of almost two dozen defense stocks, with a bullish, sector-wide buy-the-pullback call.
He issued 13 Buy ratings with an average upside of roughly 50%, with the standout being Applied Aerospace & Defense, Inc. (NYSE:AADX). The ****** yst sees the stock around $30, up by about 150% from the share's closing price that day.
Ciarmoli described AADX as a "merchant supplier of established and proven military subsystems and components". The ****** yst believes the company is well positioned to benefit from favorable growth trends across the aerospace, defense, and ****** e industries.
Several defense stocks have struggled since the advent of the Iran war. Investors are also concerned about the possibility of a split Congress after the midterm elections, which could result in a spending gridlock.
However, Ciarmoli says the fears are overblown. The Guggenheim ****** yst is urging investors to be buyers on the pullback. He expects the current trend of increased spending on autonomous systems, ****** e, and replenishing depleted stockpiles to sustain.
#pullback
He issued 13 Buy ratings with an average upside of roughly 50%, with the standout being Applied Aerospace & Defense, Inc. (NYSE:AADX). The ****** yst sees the stock around $30, up by about 150% from the share's closing price that day.
Ciarmoli described AADX as a "merchant supplier of established and proven military subsystems and components". The ****** yst believes the company is well positioned to benefit from favorable growth trends across the aerospace, defense, and ****** e industries.
Several defense stocks have struggled since the advent of the Iran war. Investors are also concerned about the possibility of a split Congress after the midterm elections, which could result in a spending gridlock.
However, Ciarmoli says the fears are overblown. The Guggenheim ****** yst is urging investors to be buyers on the pullback. He expects the current trend of increased spending on autonomous systems, ****** e, and replenishing depleted stockpiles to sustain.
#pullback


2 months ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
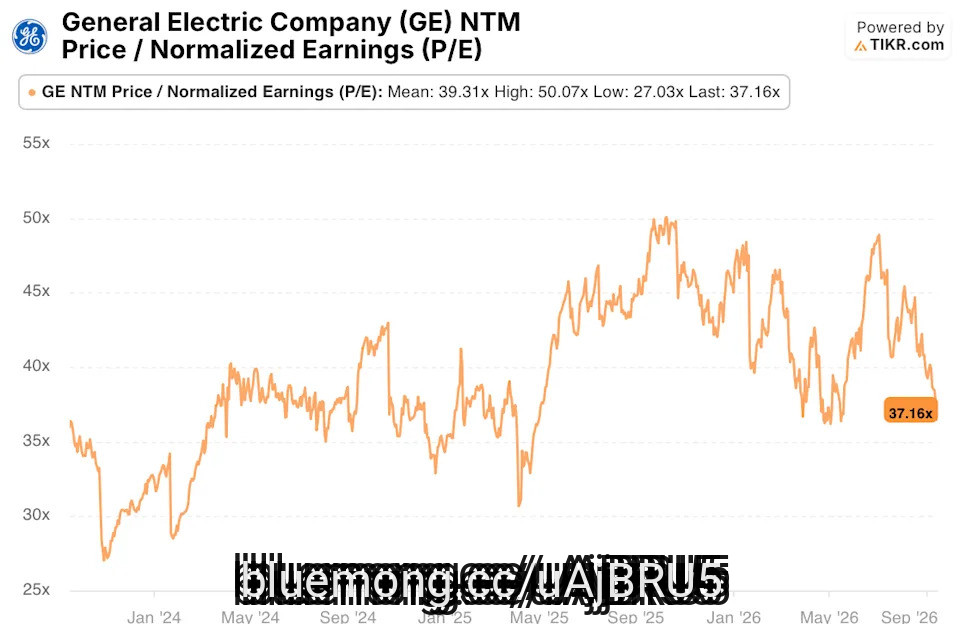
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion



2 months ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply

2 months ago
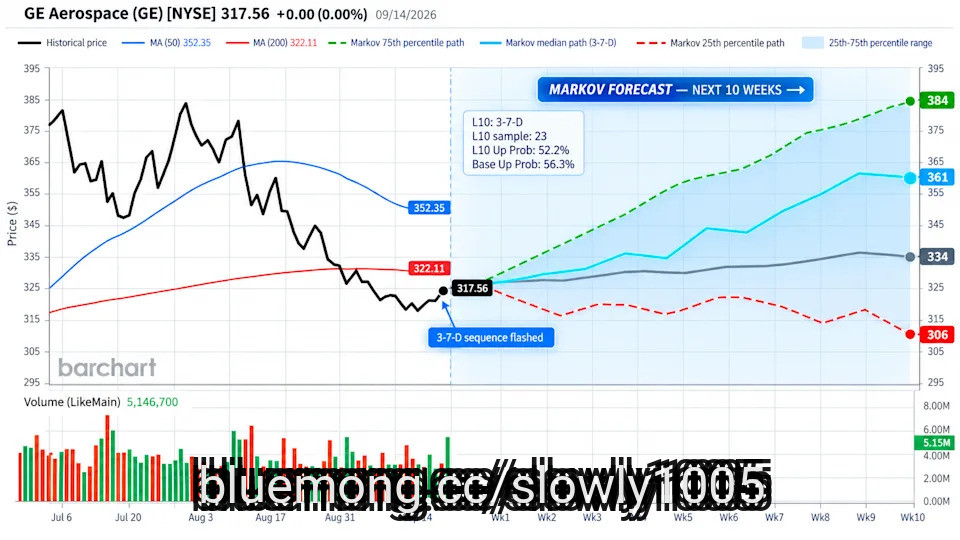
GE Aerospace (GE) has more engine work booked than it can currently perform, and that visibility is much of why people own the shares. The option chain does not treat the stock as settled. At about $307, contracts running twelve months out carry a band from near $216.93 to near $434.6, with roughly a two-in-three chance the stock finishes inside it.
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band
Read that band as money. The ceiling near $434.6 sits about 41.5% above today's price, and the floor near $216.93 sits about 29.4% below it. Whatever money you have in GE, the options market prices about $90 of every $307 coming off, or about $128 going on, inside twelve months.
The two distances are not equal. A share price cannot fall below zero while nothing caps the upside, so the ceiling always sits further out than the floor. That is arithmetic rather than a view on GE.
The floor is the half worth sitting with. Near $216.93, it is well below $272.91, the lowest GE has traded in the past 52 weeks. The chain is not forecasting that price. It prices twelve months as long enough to reach it.
A range is only wide relative to something. The stock's realized volatility over the trailing year, meaning how far it has actually moved, was 33.2%, and the options quote 34.6%. The market is charging about what this stock already delivers.
#near #sits #floor #band
2 months ago
Invesco Aerospace & Defense ETF (NYSEMKT:PPA) offers a long track record and broad industrial exposure, while Global X Defense Tech ETF (NYSEMKT:SHLD) provides a lower-cost, technology-focused approach to the defense sector.
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach

2 months ago
Teradyne, Inc. (TER) is a technology company that designs and manufactures automated test equipment and advanced robotics systems, with a market capitalization of approximately $51.5 billion. Based in North Reading, Massachusetts, the company's semiconductor and electronics testing solutions help customers maintain quality standards, while its collaborative and mobile robots support manufacturing and warehouse operations across businesses of various sizes.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Teradyne comfortably fits this category. Its edge comes from its leading role in automated testing and robotics, serving several industries, from semiconductors to automotive and aerospace. Its diversified product portfolio, strong brand, stable revenue, healthy profit margins, and consistent cash generation support continued investment in technology and long-term growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#robotics #support
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Teradyne comfortably fits this category. Its edge comes from its leading role in automated testing and robotics, serving several industries, from semiconductors to automotive and aerospace. Its diversified product portfolio, strong brand, stable revenue, healthy profit margins, and consistent cash generation support continued investment in technology and long-term growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#robotics #support



2 months ago
Boeing (BA) grew revenue faster over the past twelve months than any of its aerospace and defense peers, GE Aerospace included, and its stock still fell. It is also the only one in that group running an operating loss. The growth has come with rising airplane deliveries, and the market is waiting to see whether those airplanes earn a margin.
GE Aerospace is the sharpest comparison. It grew revenue 21.7% over the trailing twelve months, close to Boeing's 24.8%, on an operating margin of 18.7%, and its stock returned 13.4%. Boeing's operating margin over the same twelve months was negative 5.4%. Its stock returned negative 4.4%.
BA
RTX
LMT
#aerospace #twelve #months #operating
GE Aerospace is the sharpest comparison. It grew revenue 21.7% over the trailing twelve months, close to Boeing's 24.8%, on an operating margin of 18.7%, and its stock returned 13.4%. Boeing's operating margin over the same twelve months was negative 5.4%. Its stock returned negative 4.4%.
BA
RTX
LMT
#aerospace #twelve #months #operating

2 months ago
GE Aerospace (GE) trades near $318, up 13.4% over the past twelve months. Behind that price sits a commercial services backlog of roughly $170 billion, work on engines already flying. The easy read is that the good news is in the price, and the coming three years just work that backlog off. A three-year scenario on the company's own numbers puts a size on what is left.
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price
Revenue does most of the work. The scenario grows it 17.4% a year for three years, down from the 21.7% pace of the past twelve months, and net margin recovers some of the ground it has lost. Together they lift earnings about 67%.
The constraint is not demand. Management said in July that what lies ahead is much more a supply-side challenge than a demand one. Spare parts delinquencies, shipments held up for want of material, grew 20% sequentially in the second quarter of 2026.
GE Aerospace agreed in September to buy the castings maker Consolidated Precision Products. The deal shows where the bottleneck sits.
Then the multiple takes its cut. The scenario trims the P/E from 36.8x to 32.9x, because a slower revenue pace will not support what the market pays today. On those ******* umptions the stock would be worth about $475 in three years, roughly 50% above today.
#aerospace #revenue #price


2 months ago
Browsing through the available strike selections for month-of-October bull call spreads, it's impossible to ignore one glaring idea for GE Aerospace (GE). With a maximum payout of 222.58% in exchange for a net debit (cash outlay) of $310, the risk-reward profile seems unusually favorable. Of course, Wall Street isn't in the business of giving traders a free lunch — and that's where the problem with GE stock lies.
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing

2 months ago
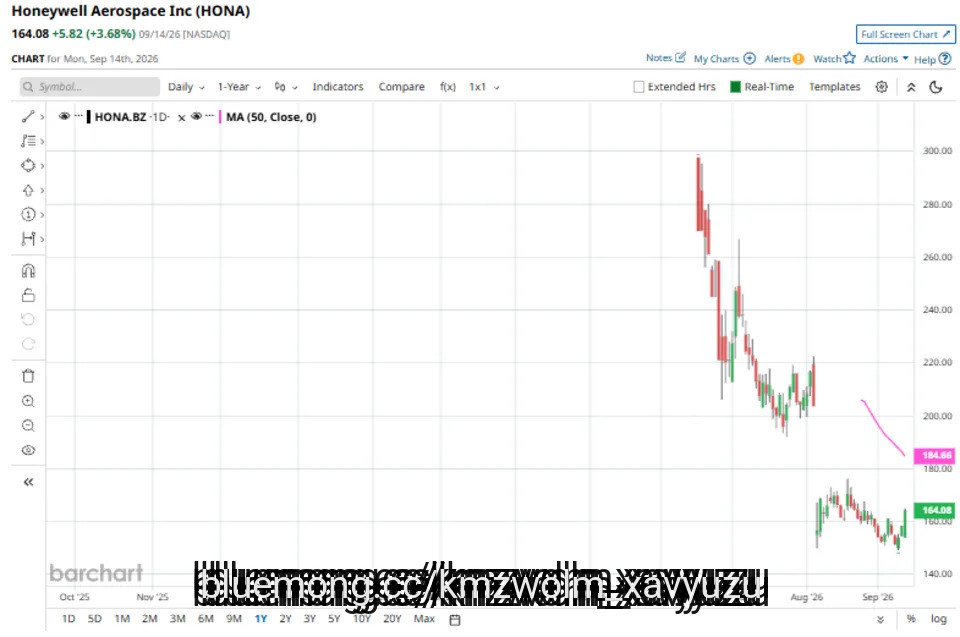
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and **** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace #systems #aviation
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace #systems #aviation


2 months ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket


2 months ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Vishay Precision Group, Inc. (NYSE:VPG). Headquartered in Malvern, Pennsylvania, Vishay Precision Group, Inc. (NYSE:VPG) specializes in precision measurement and sensing technologies. On September 14, 2026, Vishay Precision Group, Inc. (NYSE:VPG) closed at $60.49 per share. Over the past month, Vishay Precision Group, Inc. (NYSE:VPG) declined 10.77%, while its shares gained 85.95% over the past 52 weeks. Vishay Precision Group, Inc. (NYSE:VPG) has a market capitalization of $805.75 million, and its shares traded within a 52-week range of $28.71 and $151.78.
Prosper Stars & Stripes stated the following regarding Vishay Precision Group, Inc. (NYSE:VPG) in its Q2 2026 investor letter:
"Vishay Precision Group, Inc. (NYSE:VPG) was the largest contributor to our long book during the second quarter of 2026. Vishay's core technologies, bulk metal foil resistors and bonded foil strain gauges, are niche, designed-in sensor solutions embedded in precision instruments, such as semiconductor test equipment and aerospace, medical, military, and robotics applications. Vishay has done a lot of work during the industrial downturn to improve its footprint to have more profitable growth as the industrial economy recovers after years of tepid performance. In addition, Vishay is pursuing a substantial secular growth opportunity in humanoid robotics, with $500 to $1,200 in content per robot. Management is executing on both sides of the ledger: cutting costs while strengthening the leadership bench with new Chief Operating Officer and Chief Product Officer roles. Together, these initiatives are expected to lift gross margins and EBITDA margins from 39% and 8% in 2025 toward long-term targets of 46% and 20% over the next several years. We reduced and then exited our position in Vishay during the quarter but still see good value in th
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Vishay Precision Group, Inc. (NYSE:VPG). Headquartered in Malvern, Pennsylvania, Vishay Precision Group, Inc. (NYSE:VPG) specializes in precision measurement and sensing technologies. On September 14, 2026, Vishay Precision Group, Inc. (NYSE:VPG) closed at $60.49 per share. Over the past month, Vishay Precision Group, Inc. (NYSE:VPG) declined 10.77%, while its shares gained 85.95% over the past 52 weeks. Vishay Precision Group, Inc. (NYSE:VPG) has a market capitalization of $805.75 million, and its shares traded within a 52-week range of $28.71 and $151.78.
Prosper Stars & Stripes stated the following regarding Vishay Precision Group, Inc. (NYSE:VPG) in its Q2 2026 investor letter:
"Vishay Precision Group, Inc. (NYSE:VPG) was the largest contributor to our long book during the second quarter of 2026. Vishay's core technologies, bulk metal foil resistors and bonded foil strain gauges, are niche, designed-in sensor solutions embedded in precision instruments, such as semiconductor test equipment and aerospace, medical, military, and robotics applications. Vishay has done a lot of work during the industrial downturn to improve its footprint to have more profitable growth as the industrial economy recovers after years of tepid performance. In addition, Vishay is pursuing a substantial secular growth opportunity in humanoid robotics, with $500 to $1,200 in content per robot. Management is executing on both sides of the ledger: cutting costs while strengthening the leadership bench with new Chief Operating Officer and Chief Product Officer roles. Together, these initiatives are expected to lift gross margins and EBITDA margins from 39% and 8% in 2025 toward long-term targets of 46% and 20% over the next several years. We reduced and then exited our position in Vishay during the quarter but still see good value in th

2 months ago
Based in Phoenix, Arizona, Honeywell Aerospace Inc. (HONA), is an aerospace company that develops engines, avionics, flight controls, navigation, sensors, propulsion systems, and other technologies for commercial aviation, defense, business aviation, and ***** e applications.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Honeywell Aerospace, with a market capitalization of approximately $50.2 billion, comfortably fits this category. Its diversified portfolio spanning avionics, engines, power systems, and controls makes it a key player within the aerospace and defense industry.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#aerospace


2 months ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda

2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product
2 months ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


2 months ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


2 months ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted The Elmet Group Co. (NASDAQ:ELMT). The Elmet Group Co. (NASDAQ:ELMT) manufactures and sells precision-engineered components and high-energy systems for the aerospace, defense and government, industrial, medical, semiconductor and electronics, and energy industries. On September 09, 2026, The Elmet Group Co. (NASDAQ:ELMT) closed at $16.46 per share. Over the past month The Elmet Group Co. (NASDAQ:ELMT) declined 4.02% and its shares lost 15.29% over the past 3 months. The Elmet Group Co. (NASDAQ:ELMT) has a market capitalization of $511.11 million and its stock has traded within a 52-week range of $12.49 to $22.51.
Prosper Stars & Stripes stated the following regarding The Elmet Group Co. (NASDAQ:ELMT) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense (AADX) and The Elmet Group Co. (NASDAQ:ELMT). Elmet's critical materials division supplies inputs for the U.S. military supply chain that are essential to production and increasingly must be sourced domestically, steering business towards the company. We believe the building of domestic supply chains can benefit Elmet and drive better-than-forecast earnings growth as they grow organically and deploy their underutilized balance sheet to broaden their businesses."
The Elmet Group Co. (NASDAQ:ELMT) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 19 hedge fund portfolios held The Elmet Group Co. (NASDAQ:ELMT) at the end of the second quarter which was 0 in the previous quarter. While we acknowledge the potential of The Elmet Group Co. (NASDAQ:ELMT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted The Elmet Group Co. (NASDAQ:ELMT). The Elmet Group Co. (NASDAQ:ELMT) manufactures and sells precision-engineered components and high-energy systems for the aerospace, defense and government, industrial, medical, semiconductor and electronics, and energy industries. On September 09, 2026, The Elmet Group Co. (NASDAQ:ELMT) closed at $16.46 per share. Over the past month The Elmet Group Co. (NASDAQ:ELMT) declined 4.02% and its shares lost 15.29% over the past 3 months. The Elmet Group Co. (NASDAQ:ELMT) has a market capitalization of $511.11 million and its stock has traded within a 52-week range of $12.49 to $22.51.
Prosper Stars & Stripes stated the following regarding The Elmet Group Co. (NASDAQ:ELMT) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense (AADX) and The Elmet Group Co. (NASDAQ:ELMT). Elmet's critical materials division supplies inputs for the U.S. military supply chain that are essential to production and increasingly must be sourced domestically, steering business towards the company. We believe the building of domestic supply chains can benefit Elmet and drive better-than-forecast earnings growth as they grow organically and deploy their underutilized balance sheet to broaden their businesses."
The Elmet Group Co. (NASDAQ:ELMT) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 19 hedge fund portfolios held The Elmet Group Co. (NASDAQ:ELMT) at the end of the second quarter which was 0 in the previous quarter. While we acknowledge the potential of The Elmet Group Co. (NASDAQ:ELMT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring tr

2 months ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Applied Aerospace & Defense, Inc. (NYSE:AADX). Applied Aerospace & Defense, Inc. (NYSE:AADX) designs, engineers, and manufactures integrated aerospace and defense subsystems for **** e and defense applications. On September 09, 2026, Applied Aerospace & Defense, Inc. (NYSE:AADX) closed at $11.94 per share. Over the past month, Applied Aerospace & Defense, Inc. (NYSE:AADX) declined 36.49% and its shares lost 45.95% over the past three months. Applied Aerospace & Defense, Inc. (NYSE:AADX) has a market capitalization of $2.06 billion and its stock has traded within a 52-week range of $11.77 and $24.24.
Prosper Stars & Stripes stated the following regarding Applied Aerospace & Defense, Inc. (NYSE:AADX) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense, Inc. (NYSE:AADX) and Elmet Group (ELMT). Applied Aerospace participates in many of the fastest growing programs in defense as a sole sourced, IP-rich component supplier, enabling high (and rising) EBITDA margins. We believe bookings can accelerate and drive revenues, earnings, and the multiple higher."
rommma/Shutterstock.com
#Equity
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Applied Aerospace & Defense, Inc. (NYSE:AADX). Applied Aerospace & Defense, Inc. (NYSE:AADX) designs, engineers, and manufactures integrated aerospace and defense subsystems for **** e and defense applications. On September 09, 2026, Applied Aerospace & Defense, Inc. (NYSE:AADX) closed at $11.94 per share. Over the past month, Applied Aerospace & Defense, Inc. (NYSE:AADX) declined 36.49% and its shares lost 45.95% over the past three months. Applied Aerospace & Defense, Inc. (NYSE:AADX) has a market capitalization of $2.06 billion and its stock has traded within a 52-week range of $11.77 and $24.24.
Prosper Stars & Stripes stated the following regarding Applied Aerospace & Defense, Inc. (NYSE:AADX) in its Q2 2026 investor letter:
"We are also invested in Applied Aerospace & Defense, Inc. (NYSE:AADX) and Elmet Group (ELMT). Applied Aerospace participates in many of the fastest growing programs in defense as a sole sourced, IP-rich component supplier, enabling high (and rising) EBITDA margins. We believe bookings can accelerate and drive revenues, earnings, and the multiple higher."
rommma/Shutterstock.com
#Equity

2 months ago
American Century Investments, an investment management company, released its first-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ****** ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Rocket Lab Corporation (NASDAQ:RKLB) as a notable contributor to performance. Rocket Lab Corporation (NASDAQ:RKLB) is an end-to-end ****** e company that provides launch services and ****** e systems solutions. On September 09, 2026, Rocket Lab Corporation (NASDAQ:RKLB) closed at $63.07 per share. Over the past month, Rocket Lab Corporation (NASDAQ:RKLB) declined 21.26%, but its shares are up 30.23% over the past year. Rocket Lab Corporation (NASDAQ:RKLB) has a market capitalization of $40.33 billion, and its stock has traded within a 52-week range of $37.57 to $151.00.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Rocket Lab Corporation (NASDAQ:RKLB) in its Q2 2026 investor letter:
"Rocket Lab Corporation (NASDAQ:RKLB). The commercial ****** e company rallied as record revenue and strong guidance were supported by a large backlog and demand for its launch and ****** e systems businesses. After ****** e Exploration Technologies' June initial public offering drove some volatility, Rocket Lab announced plans to acquire satellite operator Iridium Communications."
Rocket Lab Corporation (NASDAQ:RKLB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 52 hedge fund portfolios held Rocket Lab Corporation (NASDAQ:RKLB) at the end of the second quarter, compared to 43 in the previous quarter. While we acknowledge the potential of Rocket Lab Corporation (NASDAQ:RKLB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Rocket Lab Corporation (NASDAQ:RKLB) as a notable contributor to performance. Rocket Lab Corporation (NASDAQ:RKLB) is an end-to-end ****** e company that provides launch services and ****** e systems solutions. On September 09, 2026, Rocket Lab Corporation (NASDAQ:RKLB) closed at $63.07 per share. Over the past month, Rocket Lab Corporation (NASDAQ:RKLB) declined 21.26%, but its shares are up 30.23% over the past year. Rocket Lab Corporation (NASDAQ:RKLB) has a market capitalization of $40.33 billion, and its stock has traded within a 52-week range of $37.57 to $151.00.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Rocket Lab Corporation (NASDAQ:RKLB) in its Q2 2026 investor letter:
"Rocket Lab Corporation (NASDAQ:RKLB). The commercial ****** e company rallied as record revenue and strong guidance were supported by a large backlog and demand for its launch and ****** e systems businesses. After ****** e Exploration Technologies' June initial public offering drove some volatility, Rocket Lab announced plans to acquire satellite operator Iridium Communications."
Rocket Lab Corporation (NASDAQ:RKLB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 52 hedge fund portfolios held Rocket Lab Corporation (NASDAQ:RKLB) at the end of the second quarter, compared to 43 in the previous quarter. While we acknowledge the potential of Rocket Lab Corporation (NASDAQ:RKLB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the


2 months ago
American Century Investments, an investment management company, released its second-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ***** ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century

2 months ago
On September 8, 2026, GE Aerospace (NYSE:GE) agreed to buy Consolidated Precision Products (CPP) for $11.75 billion. The acquisition marks the company's largest bet yet on precision engine castings, a constraint that has been capping GE's growth. Trading already at roughly 40x earnings, the company has now attacked one of its genuine bottlenecks through the deal. But has it paid too much to do it?
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including
Castings, including the superalloy and ******* anium hot-section parts inside the jet engines, have constrained GE's engine production, including programs such as LEAP and GEnx, as well as its high-margin aftermarket. Without these castings, the company can neither build nor service its engines. If the acquisition closes, the company will gain access to CPP's 20-plus plants and about 6,600 workers, which are essential for making those components. The deal would therefore enable GE to control the constraint as well as defend its margins. CEO Larry Culp characterized the move as securing manufacturing capacity to meet simultaneous demand across commercial engines, aftermarket services, and defense contracts.
The valuation is where bulls should slow down. GE is paying roughly 18x 2027 EBITDA including synergies (26x without synergies). The sellers are private equity firms Warburg Pincus and Berkshire Partners. They have basically offloaded a cyclical business near the peak of the aerospace cycle. This is smart money selling to GE instead of the other way around. The real tell is that GE felt compelled to buy its way past this capacity bottleneck instead of scaling organically, which reveals how tight its prized aftermarket really was. Also, CPP also supplies other major aerospace and defense companies such as Pratt & Whitney, Honeywell, and Lockheed Martin, and through the vertical tie-up, the company invites antitrust scrutiny before it closes in late 2027.
GE's 40x multiple rests on its high-margin razor-and-blade business model that services a huge installed base. And the casting supply shortages quietly constrain this aftermarket. Hence, more than merely fixing a supply chain issue, the CPP acquisition defends the company's high margin and multiple. Financially, the transaction is accretive to adjusted EPS and free cash flow in the first year, funded through $7 billion in cash alongside newly issued debt. Insider Monkey data shows 113 hedge funds held GE in Q2 2026, down modestly from 119 in Q1, reflecting firm institutional positioning. Short interest is just 1.3% of float, below peers like Honeywell International (1.6%). Almost no one bets against it.
#aftermarket #acquisition #including

2 months ago
During a September 8 episode of Mad Money, Jim Cramer examined the broader aerospace ecosystem following GE Aerospace's (NYSE:GE) nearly $12 billion agreement to acquire castings specialist Consolidated Precision Products (CPP). Commenting on the strategic importance of supply chain control and the enduring strength of commercial and defense aviation despite rising oil prices, Cramer stated:
I still believe in the data center, but I also want to open your eyes to other opportunities. This morning, for example, GE Aerospace spent nearly $12 billion to buy a castings company called Consolidated Precision Products to integrate this key segment into its supply chain. It's vital for both commercial aircraft and particularly defense, both of which are booming. Now, on a day where oil's up, you might not want to focus on anything airline related, but travel's been booming the whole time, the whole time the Iranian war's been going on. This acquisition will pay off quickly for GE, making it more likely that they can accelerate production. This is also good news, therefore, for Boeing, a huge customer of GE that needs to boost its production speed.
GE is relatively close to its highs, deservedly so. Boeing? Nowhere near its high. Yet the order book is full. Last week, there was this negative article about how Boeing is being hurt by the problem-filled Spirit AeroSystems acquisition. It made that one two years ago. But that actually had to be done because Boeing, like GE Aerospace, needs to get better control of its supply chain. Aha, you say, who needs that kind of problem? Boeing just reported its slowest deliveries in 4 months. I come back and say, wait a second. First, the problems from the Spirit deal are now behind them. You know what? The story is actually old news.
Plus, CEO Kelly Ortberg has made it clear that orders would be lumpy. I knew that. And look, I know the high price of oil, particularly jet fuel, is bad news for the airlines. But the higher price of fuel also makes these new engines and airplanes far more valuable than before. Why? They're way more energy efficient. It's a good situation that has nothing to do with the data center. It does require more, better tech that AI can help with.
GE Aerospace (NYSE:GE) and The Boeing Company (NYSE:BA) represent two distinct pillars of the aerospace manufacturing ecosystem, operating at massive commercial scale. GE Aerospace reported second-quarter revenue of $13.3 billion, up 21% year-over-year, driven by strong commercial engine services and record internal shop visit output. Its total order backlog extends past $210 billion, supported by sustained airline demand for propulsion systems and aftermarket maintenance.
#boeing #chain #consolidated
I still believe in the data center, but I also want to open your eyes to other opportunities. This morning, for example, GE Aerospace spent nearly $12 billion to buy a castings company called Consolidated Precision Products to integrate this key segment into its supply chain. It's vital for both commercial aircraft and particularly defense, both of which are booming. Now, on a day where oil's up, you might not want to focus on anything airline related, but travel's been booming the whole time, the whole time the Iranian war's been going on. This acquisition will pay off quickly for GE, making it more likely that they can accelerate production. This is also good news, therefore, for Boeing, a huge customer of GE that needs to boost its production speed.
GE is relatively close to its highs, deservedly so. Boeing? Nowhere near its high. Yet the order book is full. Last week, there was this negative article about how Boeing is being hurt by the problem-filled Spirit AeroSystems acquisition. It made that one two years ago. But that actually had to be done because Boeing, like GE Aerospace, needs to get better control of its supply chain. Aha, you say, who needs that kind of problem? Boeing just reported its slowest deliveries in 4 months. I come back and say, wait a second. First, the problems from the Spirit deal are now behind them. You know what? The story is actually old news.
Plus, CEO Kelly Ortberg has made it clear that orders would be lumpy. I knew that. And look, I know the high price of oil, particularly jet fuel, is bad news for the airlines. But the higher price of fuel also makes these new engines and airplanes far more valuable than before. Why? They're way more energy efficient. It's a good situation that has nothing to do with the data center. It does require more, better tech that AI can help with.
GE Aerospace (NYSE:GE) and The Boeing Company (NYSE:BA) represent two distinct pillars of the aerospace manufacturing ecosystem, operating at massive commercial scale. GE Aerospace reported second-quarter revenue of $13.3 billion, up 21% year-over-year, driven by strong commercial engine services and record internal shop visit output. Its total order backlog extends past $210 billion, supported by sustained airline demand for propulsion systems and aftermarket maintenance.
#boeing #chain #consolidated


2 months ago
GE Aerospace (GE) is acquiring castings supplier Consolidated Precision Products for nearly $12 billion, with Cramer calling it a defense-driven win for the stock.
GE's Defense & Propulsion Technologies segment grew revenue 16% to $3.4 billion in Q2 2026, backed by a $210 billion backlog.
GE's 433% five-year run tempers urgency, but the recent 9.5% monthly pullback gives new investors a better entry point.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and GE Aerospace didn't make the cut. Enter your email to see the names that beat GE. The report is free. Enter your email and see if any of your stocks made the cut.
Jim Cramer used his Mad Dash on September 8, 2026, to press the case for GE Aerospace (NYSE:GE), calling its purchase of Consolidated Precision Products the kind of consolidation the market has been asking for.
#enter #defense #calling
GE's Defense & Propulsion Technologies segment grew revenue 16% to $3.4 billion in Q2 2026, backed by a $210 billion backlog.
GE's 433% five-year run tempers urgency, but the recent 9.5% monthly pullback gives new investors a better entry point.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and GE Aerospace didn't make the cut. Enter your email to see the names that beat GE. The report is free. Enter your email and see if any of your stocks made the cut.
Jim Cramer used his Mad Dash on September 8, 2026, to press the case for GE Aerospace (NYSE:GE), calling its purchase of Consolidated Precision Products the kind of consolidation the market has been asking for.
#enter #defense #calling



2 months ago
American Century Investments, an investment management company, released its first-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ******* ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Broadcom Inc. (NASDAQ:AVGO) as a newly added position. Broadcom Inc. (NASDAQ:AVGO) is a leading American company that designs and develops various semiconductor devices and infrastructure software solutions. On September 08, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $368.56 per share, reflecting a market capitalization of $1.75 trillion. Over the past month, Broadcom Inc. (NASDAQ:AVGO) declined 13.20%, while its shares lost 2.29% over the past 52 weeks.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO). We initiated a position in this technology conglomerate because of its leading market position in its custom ASIC and networking chips businesses. While its software businesses are mature, we believe rapid artificial intelligence-driven growth in semiconductors has been very appealing."
Broadcom Inc. (NASDAQ:AVGO) ranks 8 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 170 hedge fund portfolios held Broadcom Inc. (NASDAQ:AVGO) at the end of the second quarter, compared to 173 in the previous quarter. While we acknowledge the potential of Broadcom Inc. (NASDAQ:AVGO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#american #Investments #fund
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Broadcom Inc. (NASDAQ:AVGO) as a newly added position. Broadcom Inc. (NASDAQ:AVGO) is a leading American company that designs and develops various semiconductor devices and infrastructure software solutions. On September 08, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $368.56 per share, reflecting a market capitalization of $1.75 trillion. Over the past month, Broadcom Inc. (NASDAQ:AVGO) declined 13.20%, while its shares lost 2.29% over the past 52 weeks.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO). We initiated a position in this technology conglomerate because of its leading market position in its custom ASIC and networking chips businesses. While its software businesses are mature, we believe rapid artificial intelligence-driven growth in semiconductors has been very appealing."
Broadcom Inc. (NASDAQ:AVGO) ranks 8 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 170 hedge fund portfolios held Broadcom Inc. (NASDAQ:AVGO) at the end of the second quarter, compared to 173 in the previous quarter. While we acknowledge the potential of Broadcom Inc. (NASDAQ:AVGO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#american #Investments #fund

2 months ago
As global travel continues its post-pandemic ascent, investors are weighing the recovery of an aviation ******* an against a leaner engine specialist. Choosing between Boeing (NYSE:BA) and GE Aerospace (NYSE:GE) requires careful scrutiny.
Boeing remains a global leader in commercial aircraft manufacturing and defense systems, while GE Aerospace has transformed into a focused aerospace power. Both companies benefit from rising demand for efficient travel, yet they offer vastly different financial health and risk profiles.
Boeing develops and services commercial airplanes, defense products, and ******* e systems for customers in over 150 countries. The company derives a significant portion of its revenue from the U.S. government, including the Department of Defense and NASA. Customer concentration like this adds a layer of risk to the business, particularly when specialized contracts are subject to shifting federal budget priorities.
In FY 2025, revenue reached nearly $89.5 billion, representing a significant 34.5% increase over the prior year. This growth helped the company report a net income of approximately $2.2 billion, which is a notable improvement from the net loss of roughly $11.8 billion in 2024. The turnaround suggests that production rates for major programs are beginning to stabilize after several years of operational disruptions.
As of its December 2025 balance sheet, the debt-to-equity ratio was 10.0x. This high figure indicates that total liabilities are ten times the value of shareholder equity. The current ratio, which indicates a company's ability to pay short-term obligations with short-term ******* ets, was nearly 1.2x. Free cash flow was negative $1.9 billion, and stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#cash #global #commercial
Boeing remains a global leader in commercial aircraft manufacturing and defense systems, while GE Aerospace has transformed into a focused aerospace power. Both companies benefit from rising demand for efficient travel, yet they offer vastly different financial health and risk profiles.
Boeing develops and services commercial airplanes, defense products, and ******* e systems for customers in over 150 countries. The company derives a significant portion of its revenue from the U.S. government, including the Department of Defense and NASA. Customer concentration like this adds a layer of risk to the business, particularly when specialized contracts are subject to shifting federal budget priorities.
In FY 2025, revenue reached nearly $89.5 billion, representing a significant 34.5% increase over the prior year. This growth helped the company report a net income of approximately $2.2 billion, which is a notable improvement from the net loss of roughly $11.8 billion in 2024. The turnaround suggests that production rates for major programs are beginning to stabilize after several years of operational disruptions.
As of its December 2025 balance sheet, the debt-to-equity ratio was 10.0x. This high figure indicates that total liabilities are ten times the value of shareholder equity. The current ratio, which indicates a company's ability to pay short-term obligations with short-term ******* ets, was nearly 1.2x. Free cash flow was negative $1.9 billion, and stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#cash #global #commercial
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

