44 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
It doesn't look like a market crash is in our future.
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
#market #crash #despite #offers
It doesn't look like a market crash is in our future.
A housing market crash happens when home values plummet due to a lack of demand for or an oversupply of homes. The factors leading to a housing market crash are varied, ranging from economic recessions to high mortgage rates that make it less affordable to buy a home. A housing crash can have upsides (low home prices) and downsides (losing built-up equity and tighter finances).
So, what's ahead for the housing market in 2026?
Read more: Want to buy a house in 2026? Here's what you need to know.
Despite 58% of Gen Z wanting a housing market crash, according to Clever, experts don't foresee one in 2026. If anything, they see a greater sense of normalcy following multiple years of twists and turns.
#market #crash #despite #offers


2 hours ago
Fed Chair Kevin Warsh used his Aug. 28 keynote speech at Jackson Hole to drive home the point that inflation is broader than the headline rate suggests, speaking directly to the everyday experiences of a rising price level that most people have been having for a while now. Specifically, Warsh said 54% of the 199 items in the personal consumption expenditures (PCE) price index, which is the Fed's preferred inflation gauge, had risen by more than 3% in the 12 months through summer 2026, versus 32% of those items in the two decades before the pandemic.
That's a bit of an awkward situation for the companies that make up the S&P 500 (SNPINDEX: ^GSPC), whose stellar growth in 2026 has been built on profits that are much higher than average. In short, the next thing the market will need to deal with is, in all probability, a Federal Reserve that's keen on making businesses pay more for each dollar of borrowing, which could in turn end up leading to investors paying less for each dollar of profit ***** ociated with the ***** ets they buy.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's how that could unfold, and soon.
After the Sept. 11 inflation report showed that consumer prices are still rising at a faster-than-desired pace, the odds of a rate hike by the Fed at its meeting on Sept. 16 were 90%, per the CME FedWatch. Warsh also said in his speech that he'd struggle to call the current set of financial conditions restrictive. That obviously means that investors need to brace for higher rates.
#inflation
That's a bit of an awkward situation for the companies that make up the S&P 500 (SNPINDEX: ^GSPC), whose stellar growth in 2026 has been built on profits that are much higher than average. In short, the next thing the market will need to deal with is, in all probability, a Federal Reserve that's keen on making businesses pay more for each dollar of borrowing, which could in turn end up leading to investors paying less for each dollar of profit ***** ociated with the ***** ets they buy.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's how that could unfold, and soon.
After the Sept. 11 inflation report showed that consumer prices are still rising at a faster-than-desired pace, the odds of a rate hike by the Fed at its meeting on Sept. 16 were 90%, per the CME FedWatch. Warsh also said in his speech that he'd struggle to call the current set of financial conditions restrictive. That obviously means that investors need to brace for higher rates.
#inflation

3 hours ago
Last month, Strategy (NASDAQ: MSTR) founder and Executive Chairman Michael Saylor predicted that Bitcoin's token price would grow at a 30% compound annual rate over a 10-year period. At the time, the market-leading cryptocurrency was trading at roughly $64,500.
As of this writing, Bitcoin is already up roughly 20% since Saylor made his prediction. Could Saylor's prediction for average annualized returns over the next 30 years really hold up?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Bitcoin hit an all-time high of roughly $126,200 per token in October 2025. It then began an extended downtrend that took it to a cyclical low of below $58,600 this summer. Even though the cryptocurrency has recently seen some strong bullish momentum, it's still down roughly 39% from its peak. It's possible that current macroeconomic dynamics will help the token continue regaining ground.
With concerns about rising bond yields, oil prices, and inflation recently shaping action across the stock market and weighing heavily on the broader macroeconomic outlook, the stage could be set for Bitcoin to continue coming back into favor with investors in the near term. Crypto bulls have long touted the token's ability to function as a store of value or "digital gold," and an inflationary environment that coincides with record national debt continuing to reach new highs seemingly reflects the kind of dynamics that Bitcoin has been championed as a bulwark against.
#saylor
As of this writing, Bitcoin is already up roughly 20% since Saylor made his prediction. Could Saylor's prediction for average annualized returns over the next 30 years really hold up?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Bitcoin hit an all-time high of roughly $126,200 per token in October 2025. It then began an extended downtrend that took it to a cyclical low of below $58,600 this summer. Even though the cryptocurrency has recently seen some strong bullish momentum, it's still down roughly 39% from its peak. It's possible that current macroeconomic dynamics will help the token continue regaining ground.
With concerns about rising bond yields, oil prices, and inflation recently shaping action across the stock market and weighing heavily on the broader macroeconomic outlook, the stage could be set for Bitcoin to continue coming back into favor with investors in the near term. Crypto bulls have long touted the token's ability to function as a store of value or "digital gold," and an inflationary environment that coincides with record national debt continuing to reach new highs seemingly reflects the kind of dynamics that Bitcoin has been championed as a bulwark against.
#saylor

3 hours ago
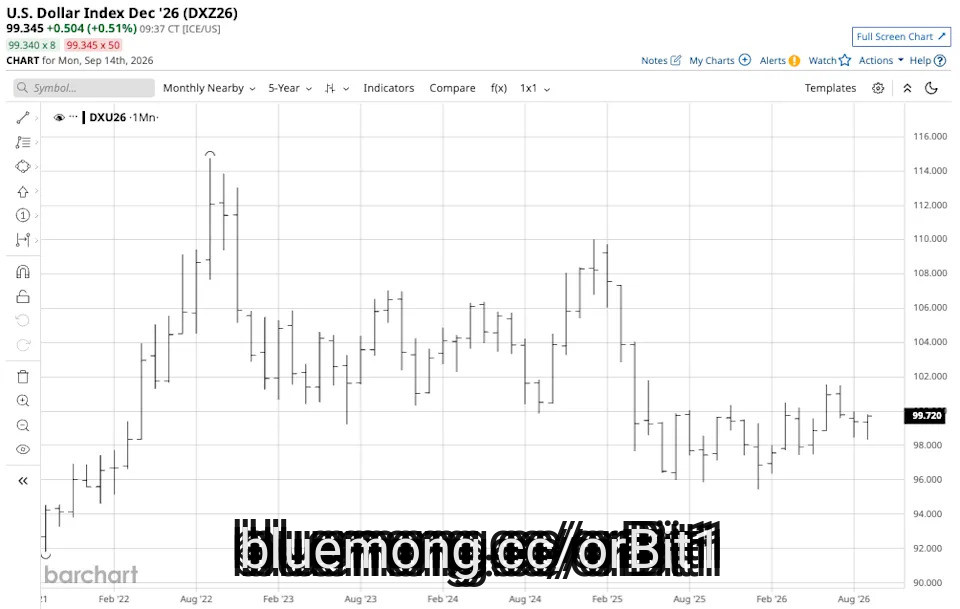
I last wrote about the dollar index on Barchart on July 23, 2026, when I asked if the index that measures the U.S. currency against the world's other leading convertible reserve currencies. I concluded the article with the following:
A weaker dollar, even if the dollar index moves higher, could fuel inflation, pushing prices of all ***** ets higher, including commodities, stocks, cryptocurrencies, and even bonds if central banks turn on liquidity faucets during a crisis as they did in 2020. Higher ***** et prices may only reflect the declining purchasing power of the world's reserve currency.
Dollar Rises on Surging Crude Prices and T-Note Yields
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Supported by Higher Crude Prices and T-Note Yields
#index #yields
A weaker dollar, even if the dollar index moves higher, could fuel inflation, pushing prices of all ***** ets higher, including commodities, stocks, cryptocurrencies, and even bonds if central banks turn on liquidity faucets during a crisis as they did in 2020. Higher ***** et prices may only reflect the declining purchasing power of the world's reserve currency.
Dollar Rises on Surging Crude Prices and T-Note Yields
Dollar Edges Higher as Stocks Fall and Crude Oil Rallies
Dollar Supported by Higher Crude Prices and T-Note Yields
#index #yields

3 hours ago
NuScale Power Corporation (SMR) stands out as America's leading developer of small modular reactors (SMRs), building light-water nuclear systems designed to deliver reliable, carbon-free baseload power. Its core product, the NuScale Power Module, targets a wide range of applications, from traditional electricity generation to industrial decarbonization, AI data center power supply, and hydrogen production. Notably, NuScale remains the only SMR developer to secure Standard Design Approval from the U.S. Nuclear Regulatory Commission, a regulatory milestone that continues to anchor its competitive positioning in the emerging advanced nuclear industry.
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude


4 hours ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft


5 hours ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects


5 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset


6 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
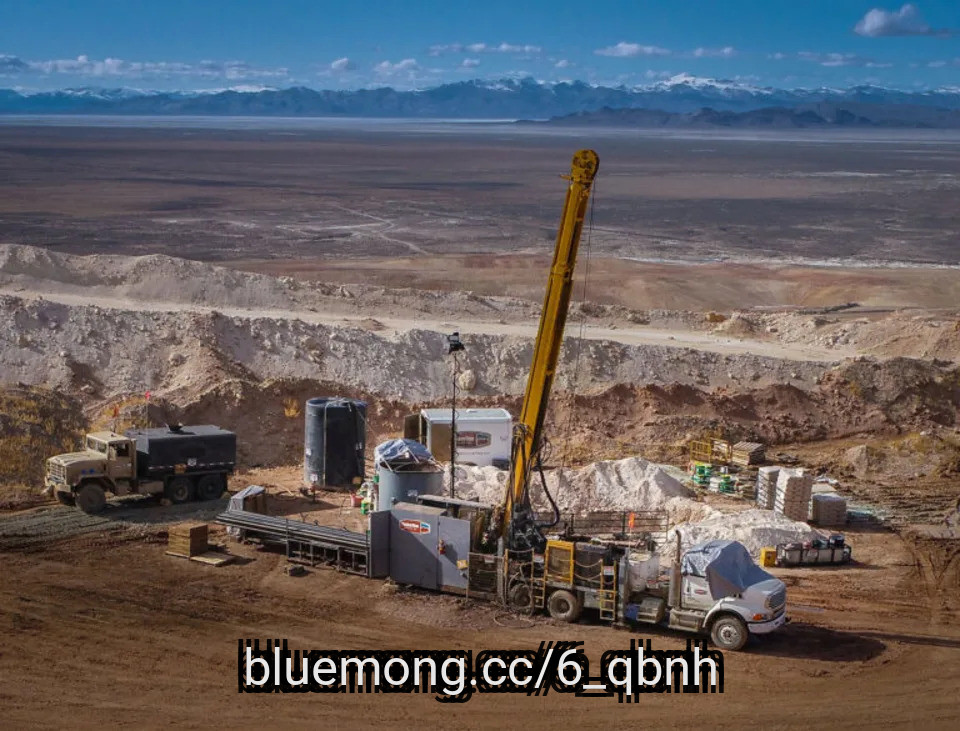
Photo from Hycroft Mining website
#letter
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ******* et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#letter

6 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


6 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval

6 hours ago
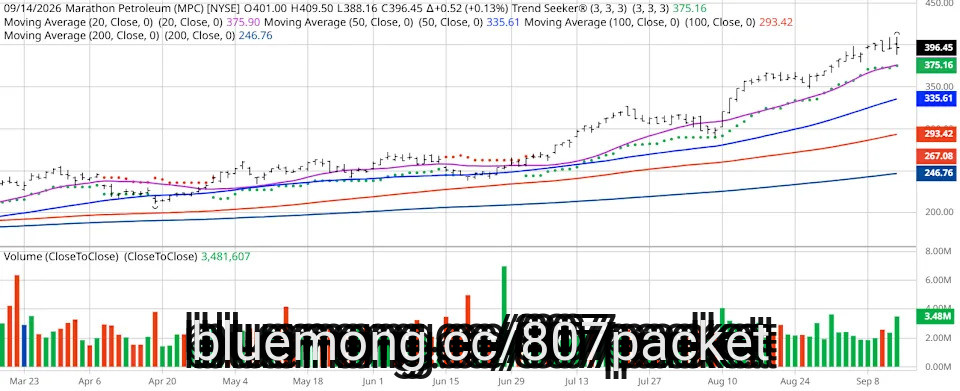
Marathon Petroleum (MPC) exhibits strong technical momentum, recently hitting a new all-time high.
Shares are up more than 120% over the past year.
MPC maintains a 100% "Buy" technical opinion from Barchart.
Future performance is highly sensitive to refining margins and oil prices, with downside risk if oil drops to $75 per barrel.
Valued at $116 billion, Marathon Petroleum (MPC) is a leading independent refiner, transporter, and marketer of petroleum products. The company came into existence following the spinoff from Marathon Oil Corporation's refining and sales business into a separate, independent and publicly traded entity. Marathon Oil completed the acquisition of its rival Andeavor. Marathon Petroleum operates in two segments: refining and marketing and pipeline transportation.
#independent #shares
Shares are up more than 120% over the past year.
MPC maintains a 100% "Buy" technical opinion from Barchart.
Future performance is highly sensitive to refining margins and oil prices, with downside risk if oil drops to $75 per barrel.
Valued at $116 billion, Marathon Petroleum (MPC) is a leading independent refiner, transporter, and marketer of petroleum products. The company came into existence following the spinoff from Marathon Oil Corporation's refining and sales business into a separate, independent and publicly traded entity. Marathon Oil completed the acquisition of its rival Andeavor. Marathon Petroleum operates in two segments: refining and marketing and pipeline transportation.
#independent #shares

6 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend


6 hours ago
KeyBanc targets $400 for MRVL, implying 83% upside, as the stock sits 34% below its 52-week high despite record Q2 revenue up 37% year-over-year.
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits
7 hours ago
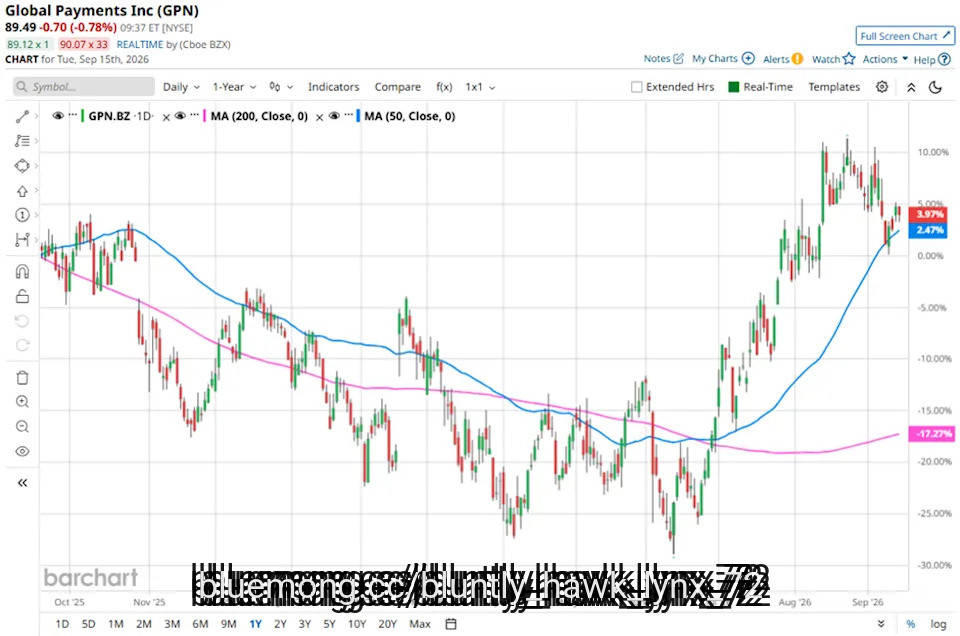
With a market cap of $23.9 billion, Global Payments Inc. (GPN) is a leading provider of payment technology and software solutions worldwide. The company operates primarily through its Merchant Solutions and Issuer Solutions segments, offering businesses and financial institutions secure, seamless, and innovative payment processing and software services.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant


7 hours ago
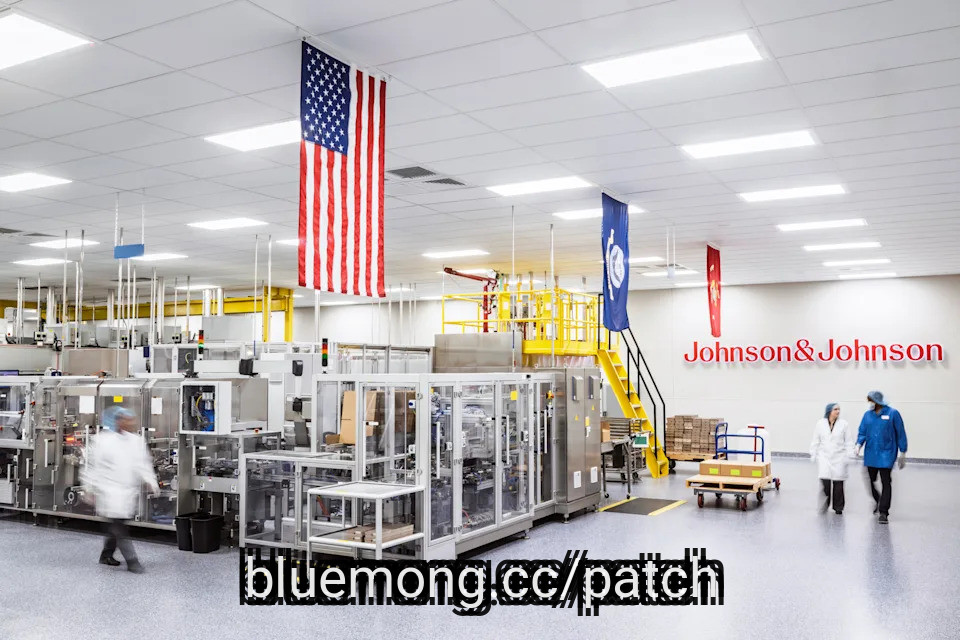
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

8 hours ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor

8 hours ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#middleby #corporation #broyhill #quarter
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted The Middleby Corporation (NASDAQ:MIDD). The Middleby Corporation (NASDAQ:MIDD), a leading player in the foodservice industry, contributed positively to performance during the quarter. On September 14, 2026, The Middleby Corporation (NASDAQ:MIDD) closed at $109.72 per share. Over the past month, The Middleby Corporation (NASDAQ:MIDD) declined 3.75%, but its shares are up 1.27% over the past year. The Middleby Corporation (NASDAQ:MIDD) has a market capitalization of $78.51 billion, and its stock has traded within a 52-week range of $89.14 to $148.55.
Broyhill ***** et Management stated the following regarding The Middleby Corporation (NASDAQ:MIDD) in its Q2 2026 investor letter:
"The Middleby Corporation (NASDAQ:MIDD) gained 31%. Commercial Foodservice grew organic revenue 8% as chains returned to growth and management raised full-year guidance by roughly 4%. More important was the structural progress: the Food Processing separation was confirmed at the May investor day (which our investment team attended) and completed on July 6th, creating Midera. Following the majority sale of the residential business earlier this year, what remains is a cleaner business with leverage approaching 2.5x."
The Middleby Corporation (NASDAQ:MIDD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held The Middleby Corporation (NASDAQ:MIDD) at the end of the second quarter which was 35 in the previous quarter. While we acknowledge the potential of The Middleby Corporation (NASDAQ:MIDD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#middleby #corporation #broyhill #quarter

8 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
8 hours ago
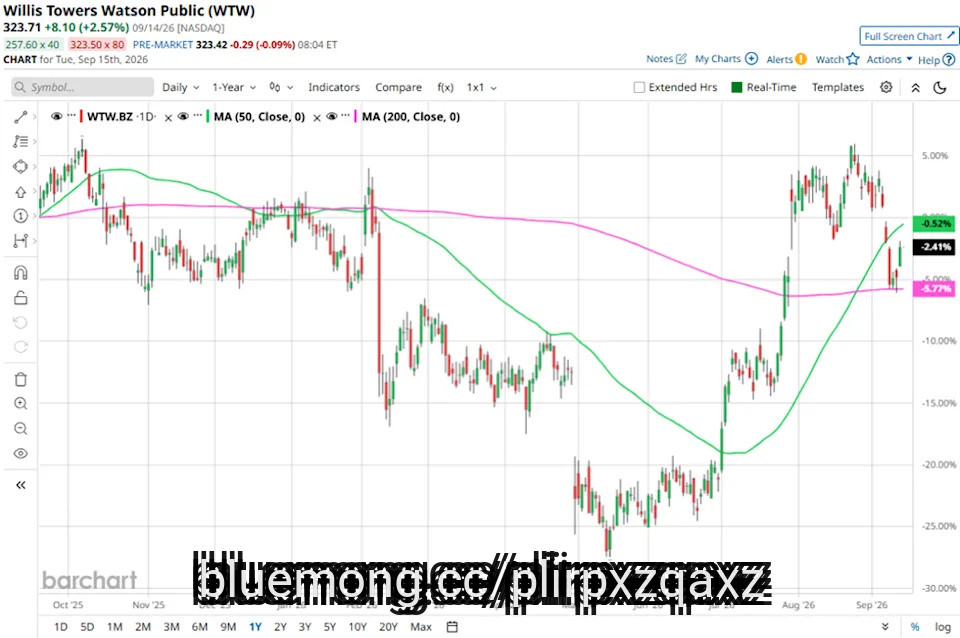
With a market cap of $30.1 billion, Willis Towers Watson Public Limited Company (WTW) is a leading global advisory, broking, and solutions company, serving clients worldwide. Through its two segments: Health, Wealth & Career and Risk & Broking, the firm delivers services that help organizations manage risk, optimize benefits, and enhance performance.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Willis Towers Watson fits right into that category. Headquartered in London, the United Kingdom, the company combines deep expertise, data-driven insights, and innovative solutions to support businesses of all sizes.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#towers #public
Companies valued over $10 billion are generally described as "large-cap" stocks, and Willis Towers Watson fits right into that category. Headquartered in London, the United Kingdom, the company combines deep expertise, data-driven insights, and innovative solutions to support businesses of all sizes.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#towers #public


8 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na

8 hours ago
With a market cap of $39.1 billion, California-based NetApp, Inc. (NTAP) is a leading provider of enterprise data storage and intelligent data infrastructure, helping businesses manage, protect, and activate data across on-premises systems, hybrid environments, and major public clouds. Its portfolio combines all-flash storage, cloud services, and data-management software, with its ONTAP platform at the core.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NetApp fits this criterion perfectly. Its leadership lies in its enterprise storage, strong hybrid-cloud capabilities, and deeply embedded customer relationships. Its ONTAP platform offers unified data management across on-premises and cloud environments, while partnerships with major cloud providers strengthen its position as enterprises shift toward hybrid infrastructure. NetApp also benefits from its growing all-flash storage portfolio, recurring software and services revenue, and expanding AI-focused data infrastructure offerings.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#netapp #storage #Stock #offerings
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NetApp fits this criterion perfectly. Its leadership lies in its enterprise storage, strong hybrid-cloud capabilities, and deeply embedded customer relationships. Its ONTAP platform offers unified data management across on-premises and cloud environments, while partnerships with major cloud providers strengthen its position as enterprises shift toward hybrid infrastructure. NetApp also benefits from its growing all-flash storage portfolio, recurring software and services revenue, and expanding AI-focused data infrastructure offerings.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#netapp #storage #Stock #offerings


9 hours ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st


9 hours ago
Baltimore, Maryland-based T. Rowe Price Group, Inc. (TROW) is a publicly owned investment manager that provides its services to individuals, institutional investors, retirement plans, financial intermediaries, and institutions. Valued at $22.7 billion by market cap, the company provides investment advisory services and manages a broad range of U.S. and international stock, blended ***** et, bond, and money market mutual funds and other investment portfolios.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TROW perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the ***** et management industry. TROW derives its core competitive strengths from its robust brand equity, extensive proprietary research capabilities, and industry-leading position in target-date retirement products.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#trow #market #Retirement
Companies worth $10 billion or more are generally described as "large-cap stocks," and TROW perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the ***** et management industry. TROW derives its core competitive strengths from its robust brand equity, extensive proprietary research capabilities, and industry-leading position in target-date retirement products.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#trow #market #Retirement

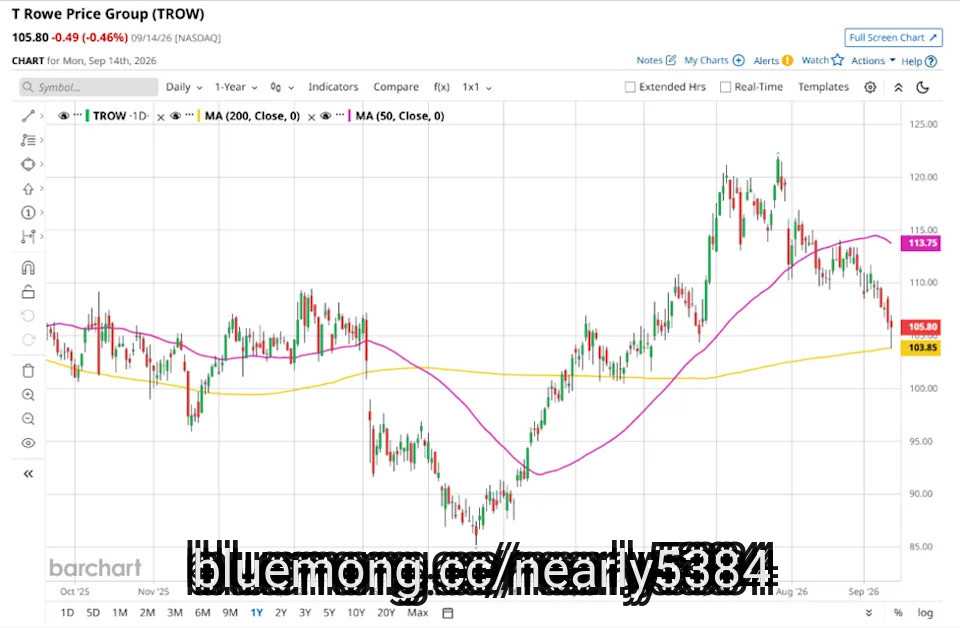

9 hours ago
With a market cap of $22.4 billion, Church & Dwight Co., Inc. (CHD) is a leading developer, manufacturer, and marketer of household, personal care, and specialty products. Best known as the U.S. leader in sodium bicarbonate production, the company's portfolio includes iconic power brands such as ARM & HAMMER, Trojan, OxiClean, Waterpik, and Vitafusion.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Church & Dwight fits this criterion perfectly. Operating across domestic, international, and specialty product segments, Church & Dwight serves consumers worldwide through retail, e-commerce, and industrial distribution channels.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#hammer #oxiclean
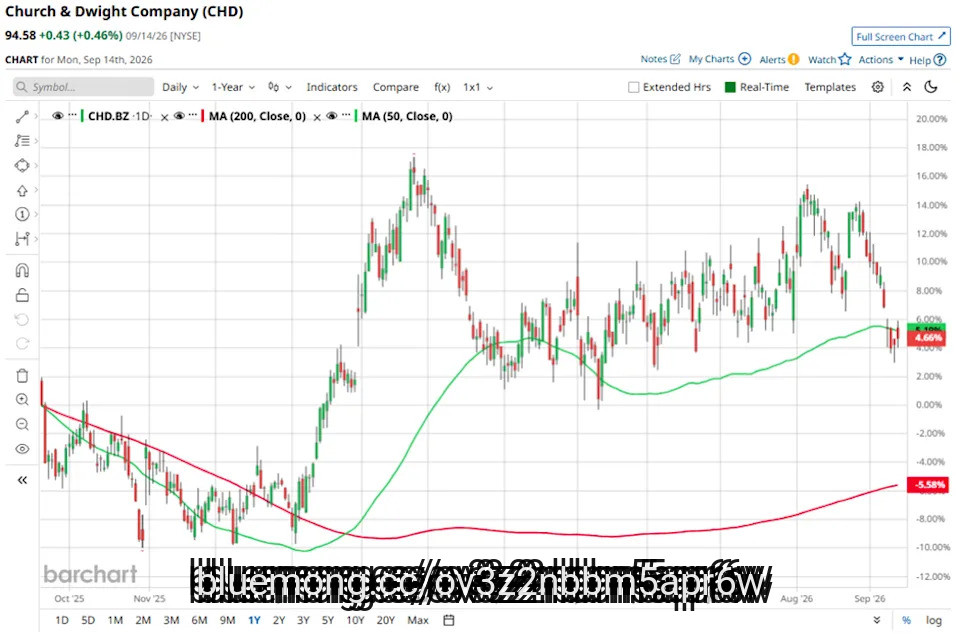

9 hours ago
Auxier ***** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
9 hours ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#quarter #asset #management #focus
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted Caterpillar Inc. (NYSE:CAT). Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On September 14, 2026, Caterpillar Inc. (NYSE:CAT) closed at $784.00 per share. Over the past month, Caterpillar Inc. (NYSE:CAT) declined 7.12%, but its shares are up 77.23% over the past year. Caterpillar Inc. (NYSE:CAT) has a market capitalization of $360.39 billion, and its stock has traded within a 52-week range of $423.32 to $1,073.46.
Auxier ****** et Management stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar Inc. (NYSE:CAT) and Gates also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Photo from Hycroft Mining website
#quarter #asset #management #focus
10 hours ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted Gates Industrial Corporation Ltd. (NYSE:GTES). Gates Industrial Corporation Ltd. (NYSE:GTES) is a leading manufacturer of engineered power transmission and fluid power solutions. On September 14, 2026, Gates Industrial Corporation Ltd. (NYSE:GTES) closed at $25.42 per share. Over the past month, Gates Industrial Corporation Ltd. (NYSE:GTES) declined 6.17%, and its shares gained 0.77% over the past 52 weeks. Gates Industrial Corporation Ltd. (NYSE:GTES) has a market capitalization of $6.44 billion, and its stock has traded within a 52-week range of $20.88 and $30.34.
Auxier ******* et Management stated the following regarding Gates Industrial Corporation Ltd. (NYSE:GTES) in its Q2 2026 investor letter:
"Industrials were the strongest performing sector during the quarter. Tech-facing industrial players benefited from a shift in investor focus toward AI buildout rather than the development of AI models. Caterpillar and Gates Industrial Corporation Ltd. (NYSE:GTES) Ltd. (NYSE:GTES) also benefited indirectly from the expansion of AI infrastructure, particularly through increased demand for energy generation and cooling capacity in data centers."
Gates Industrial Corporation Ltd. (NYSE:GTES) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Gates Industrial Corporation Ltd. (NYSE:GTES) at the end of the second quarter which was 37 in the previous quarter. While we acknowledge the potential of Gates Industrial Corporation Ltd. (NYSE:GTES) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from


10 hours ago
Marathon Petroleum (MPC) exhibits strong technical momentum, recently hitting a new all-time high.
Shares are up more than 120% over the past year.
MPC maintains a 100% "Buy" technical opinion from Barchart.
Future performance is highly sensitive to refining margins and oil prices, with downside risk if oil drops to $75 per barrel.
Valued at $116 billion, Marathon Petroleum (MPC) is a leading independent refiner, transporter, and marketer of petroleum products. The company came into existence following the spinoff from Marathon Oil Corporation's refining and sales business into a separate, independent and publicly traded entity. Marathon Oil completed the acquisition of its rival Andeavor. Marathon Petroleum operates in two segments: refining and marketing and pipeline transportation.
#marathon #future
Shares are up more than 120% over the past year.
MPC maintains a 100% "Buy" technical opinion from Barchart.
Future performance is highly sensitive to refining margins and oil prices, with downside risk if oil drops to $75 per barrel.
Valued at $116 billion, Marathon Petroleum (MPC) is a leading independent refiner, transporter, and marketer of petroleum products. The company came into existence following the spinoff from Marathon Oil Corporation's refining and sales business into a separate, independent and publicly traded entity. Marathon Oil completed the acquisition of its rival Andeavor. Marathon Petroleum operates in two segments: refining and marketing and pipeline transportation.
#marathon #future
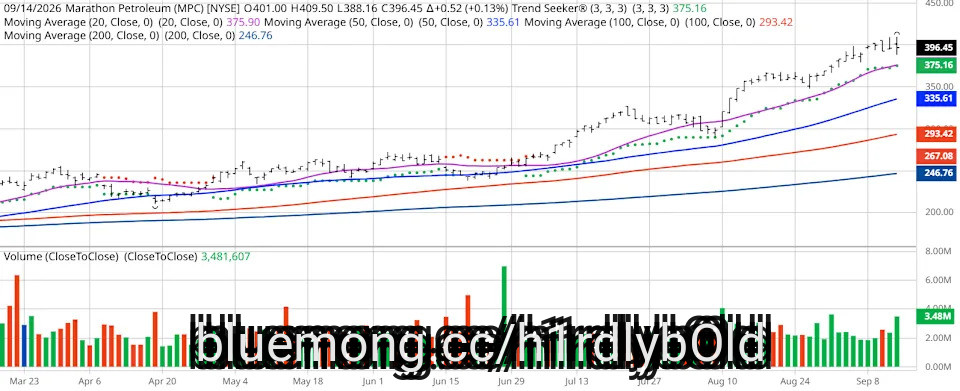

10 hours ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter