
1 day ago
Dafne Keen revealed she was offered cocaine at Hollywood wrap parties when she was just 11.
On the Nov. 3 episode of the "Inside of You" podcast, the "Logan" star, now 21, shared that she has never been "drunk enough" to have a hangover because of what she witnessed from the Los Angeles party scene as a child actress.
"I'm such a control freak with that because also I think as a child actor I witnessed so much of that as a child that I just had no interest," she said. "I was getting offered ******* e at wrap parties. Like, tiny. Like 11, 12, 13. So I saw what that was, so I was like, 'I don't really have any interest in that.'"
She emphasized that she was "saying no, fortunately."
As a teenager, the "His Dark Materials" actress said she would lie and tell people she wasn't sober so she wouldn't get peer pressured. "I'd be like, 'Nah, I'm good. I don't wanna drink. I already took something.' Dead sober. Like, the goodest goody-two-shoes ever."
#like
On the Nov. 3 episode of the "Inside of You" podcast, the "Logan" star, now 21, shared that she has never been "drunk enough" to have a hangover because of what she witnessed from the Los Angeles party scene as a child actress.
"I'm such a control freak with that because also I think as a child actor I witnessed so much of that as a child that I just had no interest," she said. "I was getting offered ******* e at wrap parties. Like, tiny. Like 11, 12, 13. So I saw what that was, so I was like, 'I don't really have any interest in that.'"
She emphasized that she was "saying no, fortunately."
As a teenager, the "His Dark Materials" actress said she would lie and tell people she wasn't sober so she wouldn't get peer pressured. "I'd be like, 'Nah, I'm good. I don't wanna drink. I already took something.' Dead sober. Like, the goodest goody-two-shoes ever."
#like

29 days ago
Amcor plc (NYSE:AMCR) isn't a flashy business. Most people probably don't know much about the company, even though they come across its products every day. The company makes the packaging used for food, drinks, healthcare products, beauty products, and plenty of other everyday items.
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE

29 days ago
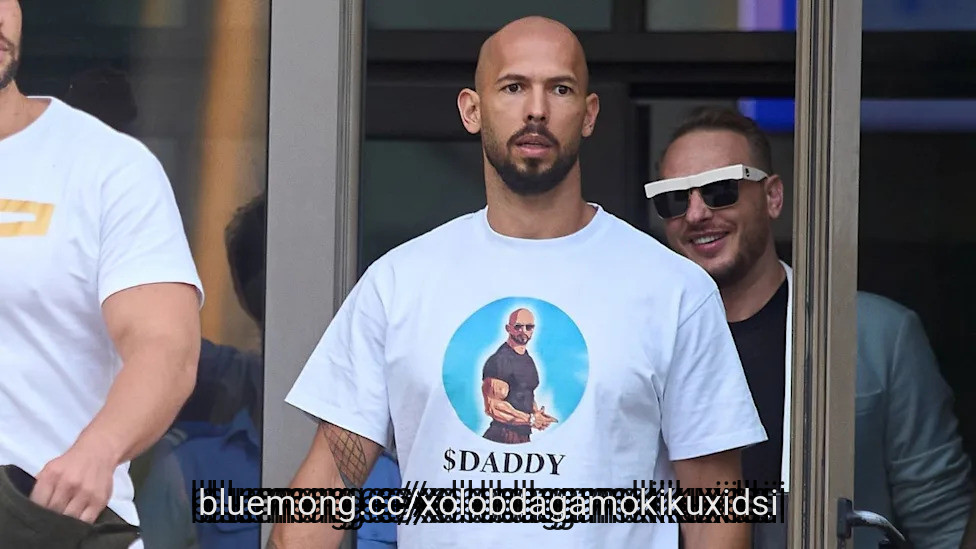
One of Andrew Tate's accusers says he convinced her to move to Romania by telling her she would be able to decide whether she participated in webcam work. According to newly public extradition materials, she says that choice disappeared after she arrived.
The woman alleges that she began working 12-hour shifts while Tate, his brother Tristan Tate and others controlled conversations with paying customers and accepted money for ***** ual acts she says she had never agreed to perform. TMZ reported the specific allegations from court documents filed as Britain seeks to extradite the brothers from the United States.
She says she had set explicit boundaries around what she would and would not do but was pressured into acts outside those limits, including one degrading act involving a bed fixture that allegedly continued for about an hour. The woman described her overall experience as feeling like "sexual slavery." The allegations have not been proven in court.
U.K. investigators allege the brothers used romantic relationships to draw women to Romania before using financial control, intimidation and violence to exploit them through online ***** ual content. The brothers deny wrongdoing and are fighting extradition from federal custody in Miami.
According to the documents described by TMZ, the woman says Tate persuaded her to relocate to Romania in 2017. The woman says she that Tate, Tristan and other people involved in the operation controlled communications with customers.
#sexual #tristan #controlled
The woman alleges that she began working 12-hour shifts while Tate, his brother Tristan Tate and others controlled conversations with paying customers and accepted money for ***** ual acts she says she had never agreed to perform. TMZ reported the specific allegations from court documents filed as Britain seeks to extradite the brothers from the United States.
She says she had set explicit boundaries around what she would and would not do but was pressured into acts outside those limits, including one degrading act involving a bed fixture that allegedly continued for about an hour. The woman described her overall experience as feeling like "sexual slavery." The allegations have not been proven in court.
U.K. investigators allege the brothers used romantic relationships to draw women to Romania before using financial control, intimidation and violence to exploit them through online ***** ual content. The brothers deny wrongdoing and are fighting extradition from federal custody in Miami.
According to the documents described by TMZ, the woman says Tate persuaded her to relocate to Romania in 2017. The woman says she that Tate, Tristan and other people involved in the operation controlled communications with customers.
#sexual #tristan #controlled

30 days ago
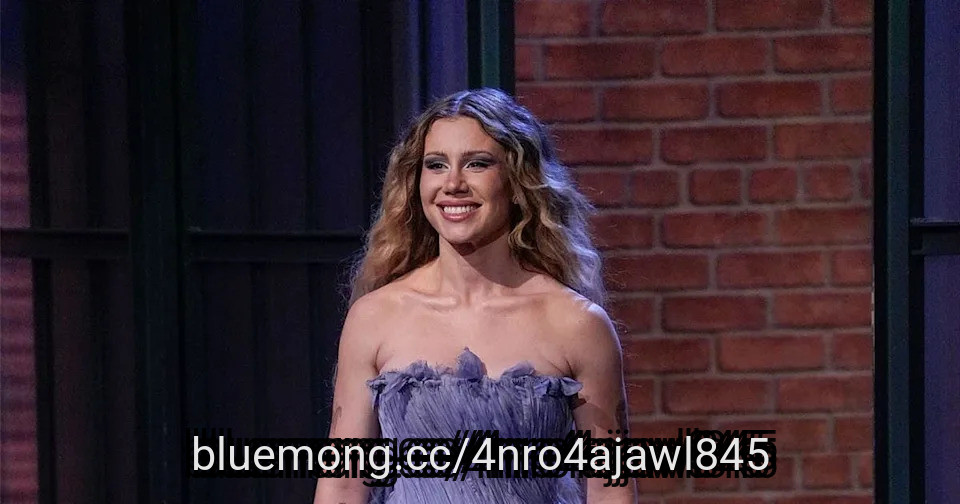
Slayyyter appeared on Late Night with Seth Meyers to discuss her newly announced album wor$t man in america, but her love of vintage showgirl costumes also became part of the conversation. She shared that an old French cabaret costume she had worn for a music video apparently contained hazardous materials and gave her a rash.
Lloyd Bishop/NBC
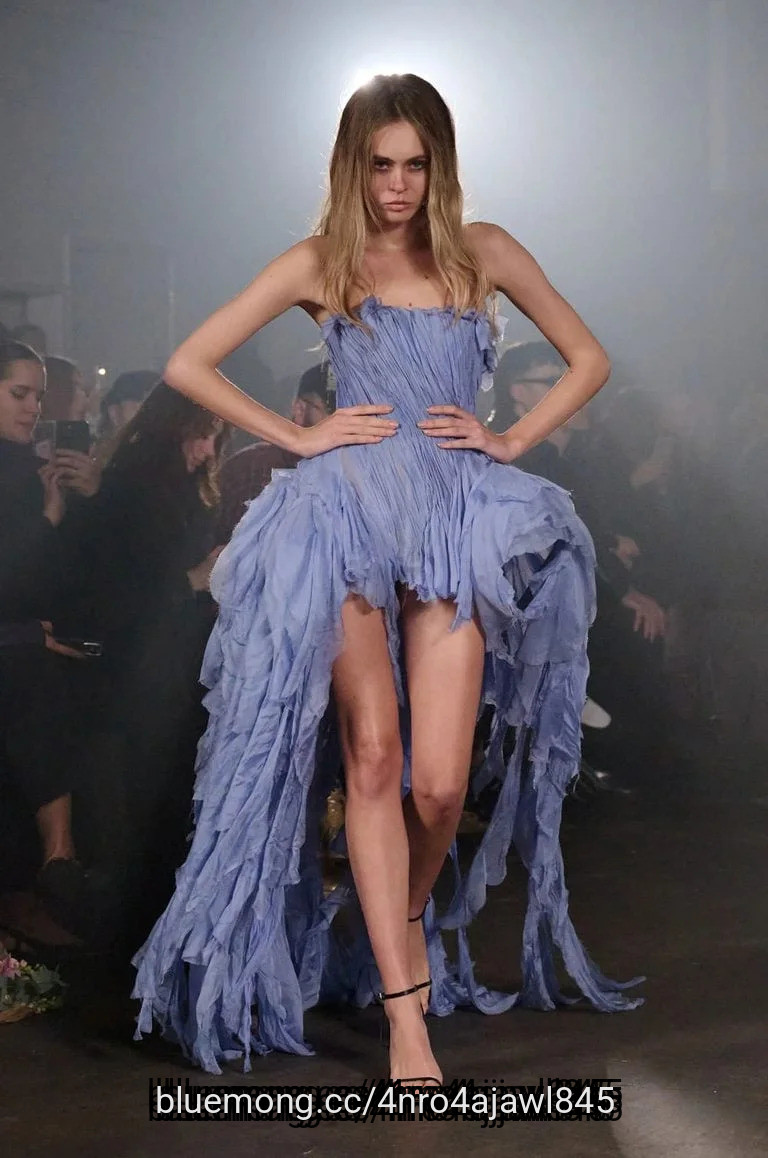
The showgirl context is really key to understanding why this MYAT Fall 2026 dress was chosen.
The distressed pleated silk is formed to create a showgirl silhouette through the fitted strapless bodice, high-low hemline and dramatic trailing volume. I don't feel that it looks like a literal costume, but I'm sure many will strongly disagree.
It's fun and playful, and it leans into what she loves, with MIRAKI jewels and decorative Jimmy Choo Sacora sandals adding even more personality without competing with the dress.
#dress
Lloyd Bishop/NBC
The showgirl context is really key to understanding why this MYAT Fall 2026 dress was chosen.
The distressed pleated silk is formed to create a showgirl silhouette through the fitted strapless bodice, high-low hemline and dramatic trailing volume. I don't feel that it looks like a literal costume, but I'm sure many will strongly disagree.
It's fun and playful, and it leans into what she loves, with MIRAKI jewels and decorative Jimmy Choo Sacora sandals adding even more personality without competing with the dress.
#dress
1 month ago
Dividend-paying stocks are taking a beating as surging Treasury yields make bonds a more competitive income source, creating a difficult environment for baby boomers who lean on dividend funds and individual stocks to cover living expenses in retirement.
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury

1 month ago
Oct 6 (Reuters) - Governments, courts and companies are considering restrictions and examining existing rules on smart glasses amid worries that the technology, brought to mainstream by Meta's Ray-Bans, could be used to photograph, film or audio-record confidential materials or people without their knowledge.
Here is a summary of what countries and regions are doing to protect people's privacy, in alphabetical order.
AUSTRALIA
The federal government said in September it was considering barring the use of camera-equipped smart glasses in government workplaces due to privacy and security concerns.
Public Service Minister Katy Gallagher asked the country's Public Service Commission for advice on whether their use should be prohibited and what exemptions might be required.
#governments
Here is a summary of what countries and regions are doing to protect people's privacy, in alphabetical order.
AUSTRALIA
The federal government said in September it was considering barring the use of camera-equipped smart glasses in government workplaces due to privacy and security concerns.
Public Service Minister Katy Gallagher asked the country's Public Service Commission for advice on whether their use should be prohibited and what exemptions might be required.
#governments

1 month ago
Sources identified the suspected attacker as 29-year-old Hamam Al Hammami.
The co-pilot of the FlyDubai plane who allegedly attacked the plane's captain and attempted to crash a flight bound for Israel on Wednesday is an Omani national who was previously suspended from flying by Oman Air after being identified as a security risk, according to senior intelligence and law enforcement officials.
Multiple sources familiar with the investigation identified the suspected attacker as 29-year-old Hamam Al Hammami.
The officials told ABC News that Al Hammami, while working as a co-pilot trainee for Oman Air in 2024, was found to be in possession of extremist materials. The suspect was allowed to continue working for the airline in an administrative role, the sources said.
United Arab Emirates Attorney General Hamad Saif Al Shamsi on Saturday said the aircraft's co-pilot had attempted to carry out a terrorist act and that he began executing his plan during the flight by ***** aulting the pilot inside the ***** pit using a crash axe and attempted to seize control of the aircraft's controls, according to WAM state news agency.
#attacker #year
The co-pilot of the FlyDubai plane who allegedly attacked the plane's captain and attempted to crash a flight bound for Israel on Wednesday is an Omani national who was previously suspended from flying by Oman Air after being identified as a security risk, according to senior intelligence and law enforcement officials.
Multiple sources familiar with the investigation identified the suspected attacker as 29-year-old Hamam Al Hammami.
The officials told ABC News that Al Hammami, while working as a co-pilot trainee for Oman Air in 2024, was found to be in possession of extremist materials. The suspect was allowed to continue working for the airline in an administrative role, the sources said.
United Arab Emirates Attorney General Hamad Saif Al Shamsi on Saturday said the aircraft's co-pilot had attempted to carry out a terrorist act and that he began executing his plan during the flight by ***** aulting the pilot inside the ***** pit using a crash axe and attempted to seize control of the aircraft's controls, according to WAM state news agency.
#attacker #year



2 months ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


2 months ago
On August 6, James Hardie Industries (NYSE:JHX) reported results for the quarter ended June 30 and beat its own numbers by enough to raise guidance just three months into the fiscal year. Net sales jumped 64% year over year to $1.475 billion, adjusted EBITDA climbed 79% to $422.1 million, and both figures came in ahead of what management had originally guided investors to expect. For a company that closed a transformative acquisition less than a year earlier, that kind of overshoot forces a reassessment of the growth story ahead.
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management


2 months ago
On September 4, the U.S. Department of War (DoW) announced a $336,112,000 Navy contract for Huntington Ingalls Industries, Inc. (NYSE:HII) to advance procurement of long-lead materials for the construction of the future USS William J. Clinton (CVN 82).
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries


2 months ago
Data center developer Crusoe said Thursday it raised $3.9 billion in a Series F round that pushes its valuation to $30.9 billion. The massive round was co-led by Atreides Management, Mubadala Capital, and Valor Equity Partners. Founders Fund, GIC, Nvidia, Qatar Investment Authority (QIA), Radical Ventures, and TPG also participated, according to Crusoe.
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round

2 months ago
Every time Silicon Valley's biggest names line up behind a single message, someone eventually asks who benefits from such universal agreement. This time, that someone was the investor best known for calling the housing crash before almost anyone else saw it coming.
Michael Burry has spent the past year building a reputation as one of the AI industry's loudest skeptics. His latest target is not a stock but a story. When three of the sector's most powerful executives suddenly agreed the technology needed to slow down, Burry saw the timing as less about caution and more like a self-serving pitch.
Burry has spent much of 2026 building short positions against companies tied to the AI trade, disclosing bets against Nvidia, Tesla, Micron, Applied Materials, Caterpillar and a leading semiconductor ETF, according to TheStreet.
On September 14, Burry published a post on X and on his Substack, Cassandra Unchained, arguing that people should take a moment to understand how self-serving it is for OpenAI, Anthropic and other big hyperscaler executives to talk about slowing things down. The post circulated quickly across financial media, Yahoo Finance reported.
Related: Michael Burry doubles down on his surprising AI bet
#michael #time #someone
Michael Burry has spent the past year building a reputation as one of the AI industry's loudest skeptics. His latest target is not a stock but a story. When three of the sector's most powerful executives suddenly agreed the technology needed to slow down, Burry saw the timing as less about caution and more like a self-serving pitch.
Burry has spent much of 2026 building short positions against companies tied to the AI trade, disclosing bets against Nvidia, Tesla, Micron, Applied Materials, Caterpillar and a leading semiconductor ETF, according to TheStreet.
On September 14, Burry published a post on X and on his Substack, Cassandra Unchained, arguing that people should take a moment to understand how self-serving it is for OpenAI, Anthropic and other big hyperscaler executives to talk about slowing things down. The post circulated quickly across financial media, Yahoo Finance reported.
Related: Michael Burry doubles down on his surprising AI bet
#michael #time #someone


2 months ago
Listen
(4 min)
The latest Market Talks covering Basic Materials. Published exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
1444 ET – Precious metals are giving back gains after the Federal Reserve raised interest rates as expected. Equities have taken the news “relatively well,” but “evidence of the Fed’s hawkishness is in the slightly firmer U.S. dollar and lower gold price,” Capital.com senior financial market ***** yst Kyle Rodda says in a note. “A special focus will be on the shape of the yield curve too as markets ***** s what impact policy is having on long-term inflation expectations.” Gold for December delivery is off 0.1% at $4,327.10 a troy ounce and silver up 0.7% at $64.33 a troy ounce. (anthony.harrupwsj.com)
#ounce #listen #jones
(4 min)
The latest Market Talks covering Basic Materials. Published exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
1444 ET – Precious metals are giving back gains after the Federal Reserve raised interest rates as expected. Equities have taken the news “relatively well,” but “evidence of the Fed’s hawkishness is in the slightly firmer U.S. dollar and lower gold price,” Capital.com senior financial market ***** yst Kyle Rodda says in a note. “A special focus will be on the shape of the yield curve too as markets ***** s what impact policy is having on long-term inflation expectations.” Gold for December delivery is off 0.1% at $4,327.10 a troy ounce and silver up 0.7% at $64.33 a troy ounce. (anthony.harrupwsj.com)
#ounce #listen #jones

2 months ago
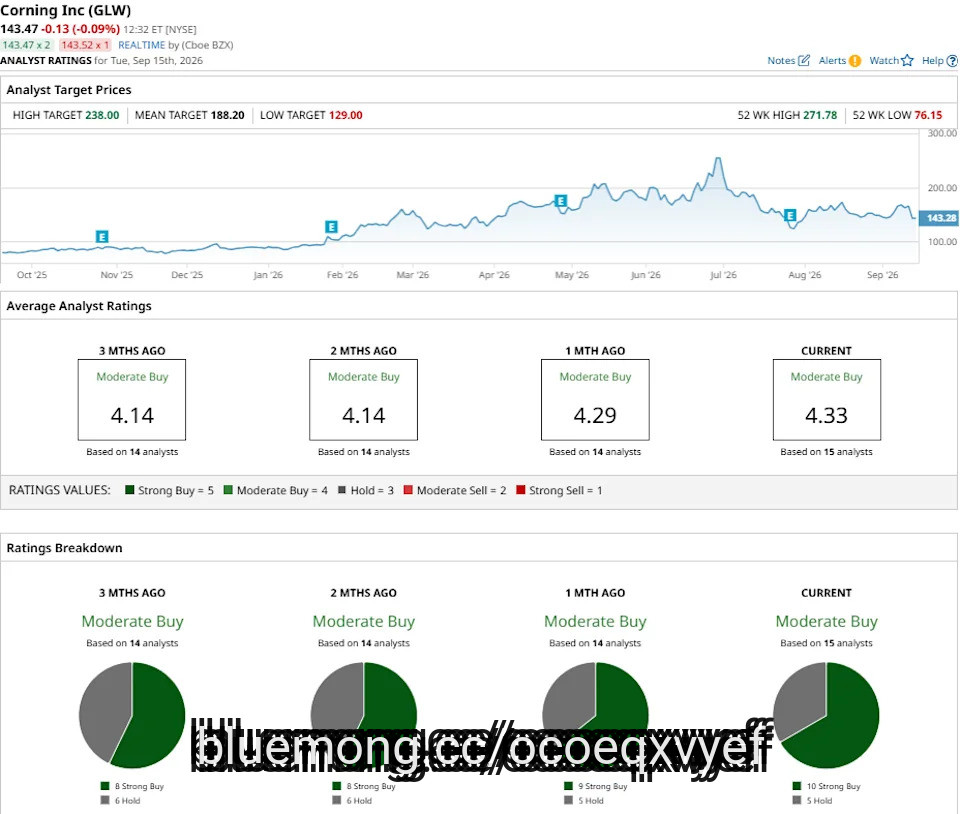
Corning Incorporated (GLW), the 175-year-old materials science giant based in Corning, New York, has become one of the more surprising beneficiaries of the artificial intelligence infrastructure buildout. Best known for its glass, ceramics, and optical technology innovations, Corning now plays a critical behind-the-scenes role as the dominant supplier of optical fiber powering hyperscale data centers and AI networks. The company has locked in major long-term supply agreements with tech heavyweights including Apple (AAPL), Meta (META), Nvidia (NVDA), Amazon (AMZN), and Verizon (VZ).
Corning stock has swung wildly of late, recently trading near $144 after plunging more than 13% in a single session following news of a $2 billion at-the-market equity offering arranged with Goldman Sachs, a move that reignited investor concerns over shareholder dilution. Shares now sit roughly in the middle of a wide 52-week range spanning $75.77 to $271.78, capturing a dramatic round trip. Corning suffered its worst monthly drop in 24 years this past July, only to rebound 8% in early September after unveiling a multibillion-dollar, 80-million-mile fiber supply deal with Verizon.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#meta #fiber
Corning stock has swung wildly of late, recently trading near $144 after plunging more than 13% in a single session following news of a $2 billion at-the-market equity offering arranged with Goldman Sachs, a move that reignited investor concerns over shareholder dilution. Shares now sit roughly in the middle of a wide 52-week range spanning $75.77 to $271.78, capturing a dramatic round trip. Corning suffered its worst monthly drop in 24 years this past July, only to rebound 8% in early September after unveiling a multibillion-dollar, 80-million-mile fiber supply deal with Verizon.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#meta #fiber


2 months ago
Avantor (AVTR) exhibits strong technical momentum, recently setting a new year-to-date high.
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits


2 months ago
On August 4, Westlake Corporation (NYSE:WLK) reported second-quarter results that erased two consecutive quarterly losses in a single swing. Net income landed at $260 million, or $2.01 per share, compared with a $169 million loss just three months earlier and a $142 million loss a year ago. EBITDA nearly tripled from the second quarter of 2025. The numbers mark a sharp reversal for a company whose chemicals business had been bleeding red ink.
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss


2 months ago
Steel and materials markets fluctuated between rallies and pullbacks as the US-Canada trade relationship shifted from near agreement to open dispute. Nucor Corporation (NYSE:NUE) and Cleveland-Cliffs Inc. (NYSE:CLF) rose on August 25, after discussions between the two countries broke down, a turnaround from the week before, when several of the same stocks fell on hopes that a new deal would decrease steel and aluminum tariffs. The VanEck Steel ETF gained 1.6% on the day, while the State Street Materials Select Sector SPDR reached an intraday high. The rise didn't last: by the end of the week, the materials ETF had slipped to negative territory, while the steel ETF was about flat, though, both remain substantially up for 2026.
The volatility traces a rapid escalation. On August 19, Bloomberg reported that the US and Canada had tentatively agreed to reduce tariffs on Canadian steel and aluminum to 25% and vehicle charges to 15%. That optimism was dashed within days: on August 22, the US imposed 50% tariffs on a wide variety of Canadian exports, and Canadian Prime Minister Mark Carney responded by declaring Canada officially "at war" with the United States, saying "You're at war when you're attacked, and we got attacked."
On August 25, Ottawa announced counter-tariffs of C$27.6 billion on American goods, which took effect on September 8 at rates ranging from 15% to 50%. The dispute has continued to escalate since then, with Washington announcing additional restrictions and tariffs on Canadian goods in September, reinforcing the view that a quick resolution remains unlikely.
Atsi Sheth, Moody's chief credit officer, put it bluntly: "Expect much more of this uncertainty for some time to come." Investors initially welcomed tariffs as good news for US steelmakers facing less Canadian competition, but the back-and-forth negotiations, as well as Canada's reaction, have made predicting a steady outcome difficult.
The more intriguing story is how differently the aforementioned companies are positioned. Nucor Corporation (NYSE:NUE) relies primarily on scrap-based electric arc furnace steelmaking, while Cleveland-Cliffs Inc. (NYSE:CLF) operates a vertically integrated model with internally sourced iron ore, scrap and other raw materials. Both have meaningful domestic raw-material exposure, although their production models differ substantially. Nucor Corporation (NYSE:NUE) is up more than 50% year-to-date, while Cleveland-Cliffs Inc. (NYSE:CLF), despite similar structural insulation, remains negative for 2026, which **** ysts attribute to balance sheet stress rather than tariffs.
#august #nucor #corporation #cleveland
The volatility traces a rapid escalation. On August 19, Bloomberg reported that the US and Canada had tentatively agreed to reduce tariffs on Canadian steel and aluminum to 25% and vehicle charges to 15%. That optimism was dashed within days: on August 22, the US imposed 50% tariffs on a wide variety of Canadian exports, and Canadian Prime Minister Mark Carney responded by declaring Canada officially "at war" with the United States, saying "You're at war when you're attacked, and we got attacked."
On August 25, Ottawa announced counter-tariffs of C$27.6 billion on American goods, which took effect on September 8 at rates ranging from 15% to 50%. The dispute has continued to escalate since then, with Washington announcing additional restrictions and tariffs on Canadian goods in September, reinforcing the view that a quick resolution remains unlikely.
Atsi Sheth, Moody's chief credit officer, put it bluntly: "Expect much more of this uncertainty for some time to come." Investors initially welcomed tariffs as good news for US steelmakers facing less Canadian competition, but the back-and-forth negotiations, as well as Canada's reaction, have made predicting a steady outcome difficult.
The more intriguing story is how differently the aforementioned companies are positioned. Nucor Corporation (NYSE:NUE) relies primarily on scrap-based electric arc furnace steelmaking, while Cleveland-Cliffs Inc. (NYSE:CLF) operates a vertically integrated model with internally sourced iron ore, scrap and other raw materials. Both have meaningful domestic raw-material exposure, although their production models differ substantially. Nucor Corporation (NYSE:NUE) is up more than 50% year-to-date, while Cleveland-Cliffs Inc. (NYSE:CLF), despite similar structural insulation, remains negative for 2026, which **** ysts attribute to balance sheet stress rather than tariffs.
#august #nucor #corporation #cleveland

2 months ago
Nvidia's (NVDA) Vera Rubin GPUs claim 70% of the $4M VR200 rack bill of materials, while Micron (MU) benefits from the 22% memory slice.
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
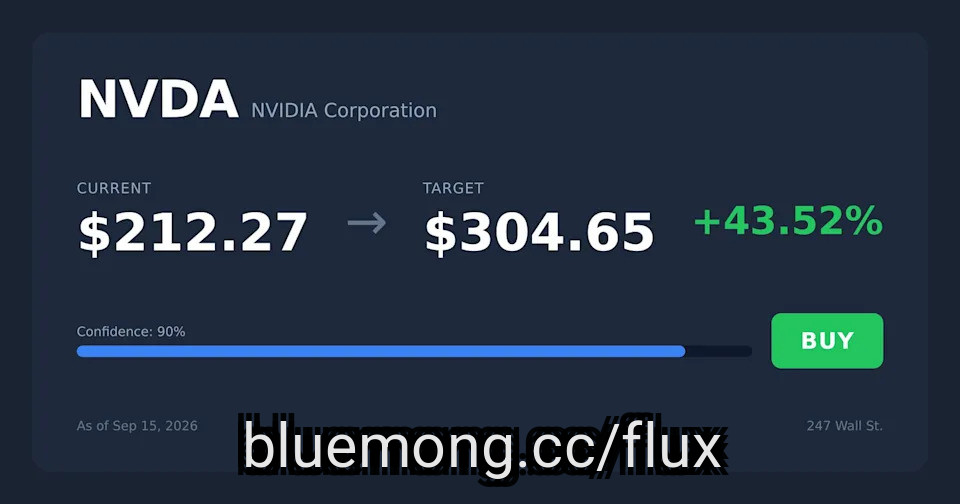
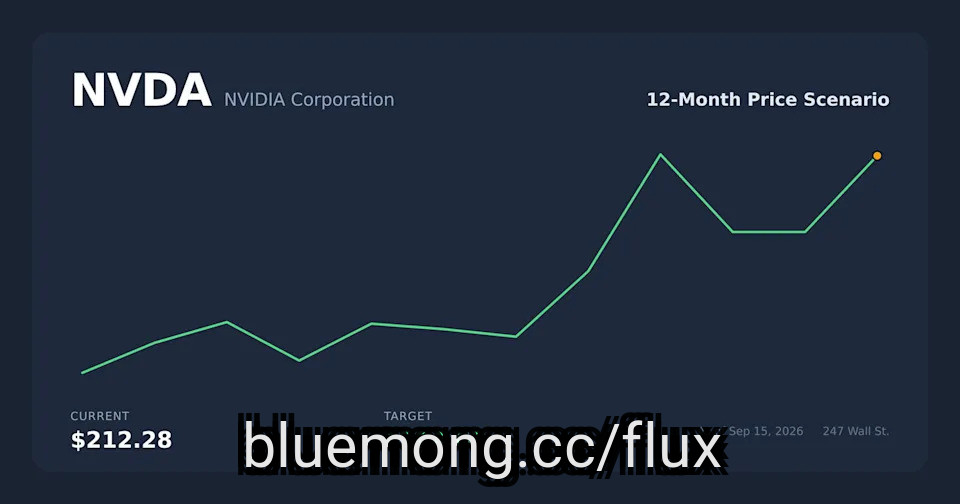
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera
Jensen Huang expects 70% revenue growth in fiscal 2028, supply-constrained despite purchase orders already secured from every major hyperscaler for Vera Rubin.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
Inside an NVIDIA (NASDAQ:NVDA) VR200 NVL72 rack-scale AI supercomputer, 70% of the roughly $4 million bill of materials goes to one line item: the Rubin GPUs themselves, excluding their high-bandwidth memory. That figure comes from an HSBC estimated bill of materials for the VR200 NVL72 platform, and it is the cleanest single data point yet on where the AI infrastructure dollar actually lands. DRAM adds another 13%, HBM 9%, NAND 2%, NVLink 2%, cooling 2%, power supply 1%, and the CPU 1%.
In an era where every hyperscaler is trying to bend the AI capex curve, the VR200 breakdown says the GPU is still where the value concentrates. Nvidia is selling the rack, and the silicon it designs takes seven of every ten dollars a customer spends to fill it. That maps to what CEO Jensen Huang told investors on the fiscal Q2 2027 call: "Today, we're not just selling the best chips. We're selling a full-stack AI factory platform."
#rack #materials #vera


2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend


2 months ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
2 months ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
2 months ago
On August 4, Westlake Corporation (NYSE:WLK) reported second-quarter results that erased two consecutive quarterly losses in a single swing. Net income landed at $260 million, or $2.01 per share, compared with a $169 million loss just three months earlier and a $142 million loss a year ago. EBITDA nearly tripled from the second quarter of 2025. The numbers mark a sharp reversal for a company whose chemicals business had been bleeding red ink.
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #quarter #westlake #earlier
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #quarter #westlake #earlier

2 months ago
Billionaire Ray Dalio's Bridgewater **** ociates has disclosed several new picks in its Q2 filings. In this article, we are going to focus on two non-AI stocks in which the fund opened new stakes in the June quarter.
Vulcan Materials Company (NYSE:VMC) is the larger of the two. Bridgewater bought about 108,700 shares worth roughly $32.1 million, a 0.13% portfolio weight. Toy company Hasbro, Inc. (NASDAQ:HAS) was another notable new pick as the fund bought a stake worth about $20.8 million in the company.
Let's focus on VMC in this article and see whether the stock is a decent buy-the-dip opportunity. It's down about 14% so far this year.
Vulcan Materials is a major producer of construction aggregates in the US. Aggregates are crushed stone, sand and gravel, the base material under roads, bridges, foundations and parking lots. Demand for these materials comes from public infrastructure, private non-residential and residential projects.
The bull case
#bridgewater #vulcan
Vulcan Materials Company (NYSE:VMC) is the larger of the two. Bridgewater bought about 108,700 shares worth roughly $32.1 million, a 0.13% portfolio weight. Toy company Hasbro, Inc. (NASDAQ:HAS) was another notable new pick as the fund bought a stake worth about $20.8 million in the company.
Let's focus on VMC in this article and see whether the stock is a decent buy-the-dip opportunity. It's down about 14% so far this year.
Vulcan Materials is a major producer of construction aggregates in the US. Aggregates are crushed stone, sand and gravel, the base material under roads, bridges, foundations and parking lots. Demand for these materials comes from public infrastructure, private non-residential and residential projects.
The bull case
#bridgewater #vulcan


2 months ago
The Justice Department's push to pursue a sweeping conspiracy probe into former officials behind investigations targeting President Donald Trump has descended into turmoil and possibly new delays following the abrupt resignation of the top prosecutor overseeing the probe.
Joe diGenova, the Washington lawyer and former top prosecutor leading the South Florida-based investigation, resigned a day after a tense phone call Wednesday with Attorney General Todd Blanche, according to two people familiar with the matter. The final clash centered on diGenova's effort to block lawyers dispatched by Justice Department headquarters from ***** isting the probe, following broader disagreements with top Justice officials over its pace.
Among the disputes that added to tensions between diGenova and his bosses in Washington was diGenova's request for a high-security room known as a SCIF to be built at the Fort Pierce office, to make it easier for the prosecution team to store highly classified materials, two people familiar with the investigation told CNN. The team worked in an office with a special room where sensitive, but not the highest-classified, evidence could be handled. Justice Department officials told diGenova he and his team should use a SCIF at an FBI office miles away, two people familiar with the investigation told CNN.
DiGenova also pressed for more lawyers for his team. Justice officials pushed back on any claims that he was denied resources, according to two people familiar with the investigation.
For more than a year, Justice Department officials have pushed to bring criminal charges against former CIA director John Brennan, who is accused of making false statements to Congress and has been the subject of the president's ire for years. Since diGenova joined the probe in April, he's chosen to pursue a broader set of charges against several of Trump's political critics — including Brennan — who were involved in investigations of him over the past decade.
#officials #familiar #department
Joe diGenova, the Washington lawyer and former top prosecutor leading the South Florida-based investigation, resigned a day after a tense phone call Wednesday with Attorney General Todd Blanche, according to two people familiar with the matter. The final clash centered on diGenova's effort to block lawyers dispatched by Justice Department headquarters from ***** isting the probe, following broader disagreements with top Justice officials over its pace.
Among the disputes that added to tensions between diGenova and his bosses in Washington was diGenova's request for a high-security room known as a SCIF to be built at the Fort Pierce office, to make it easier for the prosecution team to store highly classified materials, two people familiar with the investigation told CNN. The team worked in an office with a special room where sensitive, but not the highest-classified, evidence could be handled. Justice Department officials told diGenova he and his team should use a SCIF at an FBI office miles away, two people familiar with the investigation told CNN.
DiGenova also pressed for more lawyers for his team. Justice officials pushed back on any claims that he was denied resources, according to two people familiar with the investigation.
For more than a year, Justice Department officials have pushed to bring criminal charges against former CIA director John Brennan, who is accused of making false statements to Congress and has been the subject of the president's ire for years. Since diGenova joined the probe in April, he's chosen to pursue a broader set of charges against several of Trump's political critics — including Brennan — who were involved in investigations of him over the past decade.
#officials #familiar #department


2 months ago
As of 11:38 AM ET, the S&P 500 (SNPINDEX:^GSPC) is down 0.44% to 7,623, the Nasdaq Composite (NASDAQINDEX:^IXIC) has fallen 0.44% to 26,217 as cooling artificial intelligence sentiment weighs on growth stocks, and the Dow Jones Industrial Average (DJINDICES:^DJI) is trading 0.36% lower to 52,422.
Gold is down 1.88% to $4,325.10, and the 10-Year Treasury yield has slipped 0.02% to 4.96%, after reaching 5% for the first time since 2023. Communication stocks and healthcare are leading sector gains, while basic materials and industrials are underperforming.
Meta Platforms is climbing today after Goldman Sachs maintained a Buy rating, stressing the potential upside from its Muse AI agent. Micron Technology tumbled over 5% following warnings about the risks of rapid AI development. Those same concerns drove gains in cybersecurity stocks -- CrowdStrike Holdings soared 15%.
Tech leaders have issued dire warnings about the risks of rapid artificial intelligence (AI) development in recent days, prompting an industrywide pullback. Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman both highlighted the dangers that advanced systems could quickly move beyond human control and called for a slower pace of development.
Investors fear any slowdown could impact demand for AI infrastructure, pressuring some of this year's outperformers, such as Marvell Technology, CoreWeave, and Intel. Those worries are understandable, but it is important think about how any controls on AI development might impact long-term growth. Near-term sentiment may slip, but AI isn't going to disappear, and there is a chance that a slower build-out could actually strengthen the industry in the long term.
#down
Gold is down 1.88% to $4,325.10, and the 10-Year Treasury yield has slipped 0.02% to 4.96%, after reaching 5% for the first time since 2023. Communication stocks and healthcare are leading sector gains, while basic materials and industrials are underperforming.
Meta Platforms is climbing today after Goldman Sachs maintained a Buy rating, stressing the potential upside from its Muse AI agent. Micron Technology tumbled over 5% following warnings about the risks of rapid AI development. Those same concerns drove gains in cybersecurity stocks -- CrowdStrike Holdings soared 15%.
Tech leaders have issued dire warnings about the risks of rapid artificial intelligence (AI) development in recent days, prompting an industrywide pullback. Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman both highlighted the dangers that advanced systems could quickly move beyond human control and called for a slower pace of development.
Investors fear any slowdown could impact demand for AI infrastructure, pressuring some of this year's outperformers, such as Marvell Technology, CoreWeave, and Intel. Those worries are understandable, but it is important think about how any controls on AI development might impact long-term growth. Near-term sentiment may slip, but AI isn't going to disappear, and there is a chance that a slower build-out could actually strengthen the industry in the long term.
#down

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Europe's AI winners spent Monday discovering how quickly momentum can work in reverse, as investors dumped the semiconductor companies most exposed to the infrastructure boom behind increasingly powerful models.
ASML lost more than 5% while French semiconductor-materials specialist Soitec fell roughly 13%, showing that the same AI exposure that had recently justified higher forecasts and valuations can become painful when investors start questioning the pace of future spending.
The sell-off followed calls from some of the most prominent figures in artificial intelligence for a more cautious pace of frontier-model development, with concerns focused on the risks created as systems become more autonomous and capable.
That was enough to trigger a global unwind in the companies most closely ****** ociated with AI infrastructure. In Europe, ASML fell about 5.2%, ASM International dropped 8.7%, Infineon lost 7.6% and Soitec was the worst performer in the Stoxx 600 with a decline of roughly 12.6%.
#asml #investors #semiconductor #fell
Europe's AI winners spent Monday discovering how quickly momentum can work in reverse, as investors dumped the semiconductor companies most exposed to the infrastructure boom behind increasingly powerful models.
ASML lost more than 5% while French semiconductor-materials specialist Soitec fell roughly 13%, showing that the same AI exposure that had recently justified higher forecasts and valuations can become painful when investors start questioning the pace of future spending.
The sell-off followed calls from some of the most prominent figures in artificial intelligence for a more cautious pace of frontier-model development, with concerns focused on the risks created as systems become more autonomous and capable.
That was enough to trigger a global unwind in the companies most closely ****** ociated with AI infrastructure. In Europe, ASML fell about 5.2%, ASM International dropped 8.7%, Infineon lost 7.6% and Soitec was the worst performer in the Stoxx 600 with a decline of roughly 12.6%.
#asml #investors #semiconductor #fell


2 months ago
General Motors is developing a domestic battery supply chain it expects to complete within two to three years, even as the company currently relies on some Chinese-sourced materials for its existing battery production.
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're


2 months ago
Jim Cramer sees Enterprise Products Partners L.P. (NYSE:EPD) as a major beneficiary of the disruption surrounding the Strait of Hormuz, as he said during the September 8 episode of Mad Money:
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
2 months ago
Extreme weather is creating a more demanding environment for property owners, insurers, and communities. According to the National Centers for Environmental Information (NCEI), the United States recorded 27 confirmed billion-dollar weather and climate disasters in 2024, resulting in a total cost of $182.7 billion. These events spanned a wide range of extremes, including severe storm events, tropical cyclones, wildfires, drought/heat waves, and winter storm/cold wave events. Over the last decade, ***** ulative losses from these disasters have exceeded $1.4 trillion, driven significantly by population growth, material wealth, and increased development in hazard-prone areas. These figures suggest that the financial consequences of extreme events may increasingly depend on how accurately the value of exposed property is understood before a loss occurs.
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information


