7 mins. ago
As the artificial intelligence revolution shifts from experimentation to industrial scale, choosing between Cerebras Systems (NASDAQ:CBRS) and CoreWeave (NASDAQ:CRWV) presents a unique choice for investors seeking infrastructure growth in 2026.
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer

1 hr. ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion


2 hours ago
An AI approval in minutes means nothing if you retire before closing. Lenders must re-verify employment within 10 business days of the note date.
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval


3 hours ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year

3 hours ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


3 hours ago
On September 8, United Natural Foods Inc. (NYSE:UNFI) announced its fourth quarter and full FY26 results. For the final quarter, the company posted an adjusted EBITDA of $172 million, which grew 48.3% compared to Q4 FY25. United's fourth quarter adjusted EPS of $0.69 took a sharp turn relative to a $0.11 adjusted loss per share for the same period last year. Cash flow from operating activities for the quarter stood at $197 million, along with free cash flow of $80 million.
Nejron Photo/Shutterstock.com
Amid a favorable customer mix and network optimizations, United delivered Q4 gross profit of $1,050 million, increasing marginally by 1.9% from the same period last year. This led to a gross margin of 13.7%, compared to 13.4% recorded in Q4 FY25. Cost-saving initiatives, which included efficient productivity through distribution centers and network optimizations, translated into lower operating expenses on a year-over-year basis. It helped United jump from an $87 million net loss for Q4 FY25 to a net income of $35 million during the recently concluded quarter.
For the complete fiscal year, the company delivered an adjusted EBITDA of $701 million, showcasing a 27% growth compared to FY25. Full-year adjusted EPS also climbed from $0.71 last year to $2.65. United generated FY26 operating cash flow of $540 million and free cash flow of $323 million.
Several encouraging operational developments took place during the fourth quarter. United initiated onboarding additional business from its existing customer base, as well as the new ones. Topline impact of such additions will be seen during FY27, once the broader optimization initiatives have cycled through. For its Lean Daily Management (LDM) program, the company concluded a preliminary rollout covering 44 distribution centers. This resulted in year-over-year enhancement in fill rates, throughput, and on-time deliveries, for four consecutive quarters.
#cash #flow #fourth #company
Nejron Photo/Shutterstock.com
Amid a favorable customer mix and network optimizations, United delivered Q4 gross profit of $1,050 million, increasing marginally by 1.9% from the same period last year. This led to a gross margin of 13.7%, compared to 13.4% recorded in Q4 FY25. Cost-saving initiatives, which included efficient productivity through distribution centers and network optimizations, translated into lower operating expenses on a year-over-year basis. It helped United jump from an $87 million net loss for Q4 FY25 to a net income of $35 million during the recently concluded quarter.
For the complete fiscal year, the company delivered an adjusted EBITDA of $701 million, showcasing a 27% growth compared to FY25. Full-year adjusted EPS also climbed from $0.71 last year to $2.65. United generated FY26 operating cash flow of $540 million and free cash flow of $323 million.
Several encouraging operational developments took place during the fourth quarter. United initiated onboarding additional business from its existing customer base, as well as the new ones. Topline impact of such additions will be seen during FY27, once the broader optimization initiatives have cycled through. For its Lean Daily Management (LDM) program, the company concluded a preliminary rollout covering 44 distribution centers. This resulted in year-over-year enhancement in fill rates, throughput, and on-time deliveries, for four consecutive quarters.
#cash #flow #fourth #company
3 hours ago
A European independent power producer is expanding its ******* et base on the continent. Israel-headquartered Econergy on September 15 said it is entering the French market with a €134-million ($155 million) acquisition of Escofi, a private wind energy platform of about 740 MW.Econergy, which has offices across Europe, said the deal significantly expands the company's European wind ******* et base, bringing its total renewable portfolio to 13 GW. Escofi, founded in 1988, originates, finances, builds, and operates onshore wind projects, with its wind energy portfolio across four development stages: 128 MW in commercial operation, 34 MW under construction, 147 MW in advanced development stage (with building permits and grid connection approvals in place and construction due to commence between 2028 and 2030), and 432 MW in early and mid-stage development.Escofi's portfolio is concentrated in the Hauts-de-France and Grand Est regions of northern France, which officials said have the strongest onshore wind conditions and regulatory environments in the country.
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy


3 hours ago
When it comes to long-term success with dividend investing, you need to focus on criteria beyond just yield. While some high yield dividend stocks can be worth the risk, there are plenty that are trading at a high yield for a good reason.
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing


4 hours ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects


5 hours ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

5 hours ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly

6 hours ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o


6 hours ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

6 hours ago
GSK plc (NYSE:GSK) plans to close its vaccine manufacturing facility in Dresden, Germany, by summer 2027, putting 641 jobs at risk. The decision reflects declining demand for traditional egg-based flu vaccines, which has left GSK with more manufacturing capacity than it needs. GSK reviewed its Dresden and Ste-Foy, Canada, flu vaccine sites and chose to consolidate production in Canada, which it says can meet anticipated demand more sustainably and competitively.
The closure comes as GSK plc (NYSE:GSK) is shifting its influenza strategy toward newer technology: the company is advancing an mRNA-based seasonal flu vaccine into Phase III after Phase II results showed stronger immune responses than standard-dose vaccines in younger adults and high-dose vaccines in older adults. The broader vaccine environment has also weakened, with Reuters reporting declining sales across flu, RSV, and other vaccines amid lower demand and policy-related pressures, increasing the importance of manufacturing discipline and portfolio selection.
Copyright: kadmy / 123RF Stock Photo
The closure could ultimately strengthen GSK plc (NYSE:GSK)'s margins and cash generation by removing excess capacity from a declining part of the influenza market rather than continuing to carry the fixed costs of an underutilized facility. GSK explicitly said demand for traditional egg-based flu vaccines is falling and that it has more capacity than required, while the Canadian facility can meet anticipated future demand competitively.
This is particularly important because GSK's vaccine business remains a significant earnings contributor but is increasingly being driven by products with better growth prospects: second-quarter 2026 vaccine sales rose 8% to £2.3 billion, with meningitis vaccines up 21% and Arexvy sales increasing by more than 100%, while Shingrix generated £0.9 billion. The Dresden decision therefore looks less like a retreat from vaccines overall and more like a reallocation of manufacturing capacity away from mature egg-based products toward higher-value technologies.
#demand #Manufacturing
The closure comes as GSK plc (NYSE:GSK) is shifting its influenza strategy toward newer technology: the company is advancing an mRNA-based seasonal flu vaccine into Phase III after Phase II results showed stronger immune responses than standard-dose vaccines in younger adults and high-dose vaccines in older adults. The broader vaccine environment has also weakened, with Reuters reporting declining sales across flu, RSV, and other vaccines amid lower demand and policy-related pressures, increasing the importance of manufacturing discipline and portfolio selection.
Copyright: kadmy / 123RF Stock Photo
The closure could ultimately strengthen GSK plc (NYSE:GSK)'s margins and cash generation by removing excess capacity from a declining part of the influenza market rather than continuing to carry the fixed costs of an underutilized facility. GSK explicitly said demand for traditional egg-based flu vaccines is falling and that it has more capacity than required, while the Canadian facility can meet anticipated future demand competitively.
This is particularly important because GSK's vaccine business remains a significant earnings contributor but is increasingly being driven by products with better growth prospects: second-quarter 2026 vaccine sales rose 8% to £2.3 billion, with meningitis vaccines up 21% and Arexvy sales increasing by more than 100%, while Shingrix generated £0.9 billion. The Dresden decision therefore looks less like a retreat from vaccines overall and more like a reallocation of manufacturing capacity away from mature egg-based products toward higher-value technologies.
#demand #Manufacturing

6 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
6 hours ago
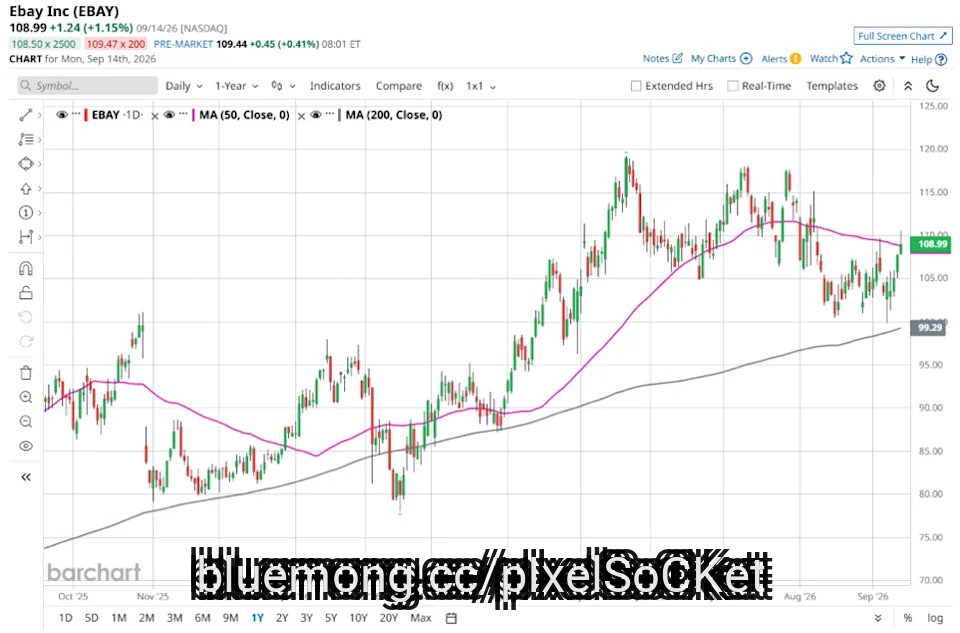
eBay Inc. (EBAY), headquartered in San Jose, California, operates marketplace platforms that connect buyers and sellers. With a market cap of $48.5 billion, the company's marketplace platform includes its online marketplace at ebay.com, off-platform businesses, and the eBay suite of mobile apps, focused on buying and selling electronics, cars, clothes, and collectibles.
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#eBay #marketplace #california #goldman
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#eBay #marketplace #california #goldman

8 hours ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket


8 hours ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current


9 hours ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management

9 hours ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ***** ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ***** ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#cultural #company #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ***** ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ***** ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#cultural #company #lilly

9 hours ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of

9 hours ago
GSK plc (NYSE:GSK) plans to close its vaccine manufacturing facility in Dresden, Germany, by summer 2027, putting 641 jobs at risk. The decision reflects declining demand for traditional egg-based flu vaccines, which has left GSK with more manufacturing capacity than it needs. GSK reviewed its Dresden and Ste-Foy, Canada, flu vaccine sites and chose to consolidate production in Canada, which it says can meet anticipated demand more sustainably and competitively.
The closure comes as GSK plc (NYSE:GSK) is shifting its influenza strategy toward newer technology: the company is advancing an mRNA-based seasonal flu vaccine into Phase III after Phase II results showed stronger immune responses than standard-dose vaccines in younger adults and high-dose vaccines in older adults. The broader vaccine environment has also weakened, with Reuters reporting declining sales across flu, RSV, and other vaccines amid lower demand and policy-related pressures, increasing the importance of manufacturing discipline and portfolio selection.
Copyright: kadmy / 123RF Stock Photo
The closure could ultimately strengthen GSK plc (NYSE:GSK)'s margins and cash generation by removing excess capacity from a declining part of the influenza market rather than continuing to carry the fixed costs of an underutilized facility. GSK explicitly said demand for traditional egg-based flu vaccines is falling and that it has more capacity than required, while the Canadian facility can meet anticipated future demand competitively.
This is particularly important because GSK's vaccine business remains a significant earnings contributor but is increasingly being driven by products with better growth prospects: second-quarter 2026 vaccine sales rose 8% to £2.3 billion, with meningitis vaccines up 21% and Arexvy sales increasing by more than 100%, while Shingrix generated £0.9 billion. The Dresden decision therefore looks less like a retreat from vaccines overall and more like a reallocation of manufacturing capacity away from mature egg-based products toward higher-value technologies.
#vaccine
The closure comes as GSK plc (NYSE:GSK) is shifting its influenza strategy toward newer technology: the company is advancing an mRNA-based seasonal flu vaccine into Phase III after Phase II results showed stronger immune responses than standard-dose vaccines in younger adults and high-dose vaccines in older adults. The broader vaccine environment has also weakened, with Reuters reporting declining sales across flu, RSV, and other vaccines amid lower demand and policy-related pressures, increasing the importance of manufacturing discipline and portfolio selection.
Copyright: kadmy / 123RF Stock Photo
The closure could ultimately strengthen GSK plc (NYSE:GSK)'s margins and cash generation by removing excess capacity from a declining part of the influenza market rather than continuing to carry the fixed costs of an underutilized facility. GSK explicitly said demand for traditional egg-based flu vaccines is falling and that it has more capacity than required, while the Canadian facility can meet anticipated future demand competitively.
This is particularly important because GSK's vaccine business remains a significant earnings contributor but is increasingly being driven by products with better growth prospects: second-quarter 2026 vaccine sales rose 8% to £2.3 billion, with meningitis vaccines up 21% and Arexvy sales increasing by more than 100%, while Shingrix generated £0.9 billion. The Dresden decision therefore looks less like a retreat from vaccines overall and more like a reallocation of manufacturing capacity away from mature egg-based products toward higher-value technologies.
#vaccine


9 hours ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson

9 hours ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care

10 hours ago
eBay Inc. (EBAY), headquartered in San Jose, California, operates marketplace platforms that connect buyers and sellers. With a market cap of $48.5 billion, the company's marketplace platform includes its online marketplace at ebay.com, off-platform businesses, and the eBay suite of mobile apps, focused on buying and selling electronics, cars, clothes, and collectibles.
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#marketplace #Stock #billion #goldman
Companies worth $10 billion or more are generally described as "large-cap stocks," and EBAY perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the internet retail industry. EBAY maintains a strong competitive advantage through its global two-sided network effect and **** et-light marketplace model, which generates robust cash flow without inventory risk. It dominates specialized, non-standardized categories where tailored trust tools create high entry barriers for competitors.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#marketplace #Stock #billion #goldman



10 hours ago
Cronos rebrands its trading app as Ult, expanding beyond crypto into prediction markets, perpetuals and tokenized **** ets.
Ult targets 100+ countries with 24/7/365 trading, 10 sports prediction categories and around 40 leveraged markets at launch.
Cronos Network could see more trading flow as Ult brings users, **** ets and liquidity into the ecosystem, with plans to move more markets onchain as volume grows.
Cronos, the blockchain ecosystem **** ociated with Crypto.com, is reshaping its product strategy around a new trading application called Ult. It has introduced a revenue-linked mechanism designed to support its native CRO token.
Cronos CEO Ryan Wyatt announced the changes on X, saying the new strategy is intended to provide greater clarity for users and developers. It aims to put a stronger focus on products that generate value for CRO.
#markets
Ult targets 100+ countries with 24/7/365 trading, 10 sports prediction categories and around 40 leveraged markets at launch.
Cronos Network could see more trading flow as Ult brings users, **** ets and liquidity into the ecosystem, with plans to move more markets onchain as volume grows.
Cronos, the blockchain ecosystem **** ociated with Crypto.com, is reshaping its product strategy around a new trading application called Ult. It has introduced a revenue-linked mechanism designed to support its native CRO token.
Cronos CEO Ryan Wyatt announced the changes on X, saying the new strategy is intended to provide greater clarity for users and developers. It aims to put a stronger focus on products that generate value for CRO.
#markets


11 hours ago
Piper Sandler believes Broadcom Inc. (NASDAQ:AVGO) is the leader in ASIC chips, holding 75% share of the ASIC market for AI inference. On September 9, firm ******* yst David O'Connor initiated coverage on the stock with an Overweight rating and a $460 price target.
O'Connor estimates demand running twice the available supply for Broadcom, which makes the ability to deliver chips central to his thesis. Even though the chipmaker boasts demand, component availability and deployment timing will determine its conversion into earnings.
The biggest advantage that Broadcom holds is that it doesn't need to win new customers, but to keep expanding what it ships to the ones it already has. The company is already ramping Meta's MTIA program and OpenAI's Jalapeno chips, along with two other customers.
Google's TPU program remains Broadcom's major volume ASIC program, while Anthropic is also scaling deployments using AVGO-enabled TPU compute. Broadcom also boasts a rising networking attach rate, which is currently around 30%. This would likely generate an estimated $20-30 billion of total content per gigawatt of deployed capacity.
The firm has a line of sight to 12 gigawatts of demand in fiscal 2027, rising toward an estimated 38 gigawatts by fiscal 2030. This underpins a roughly 51% EPS compound growth rate through the decade.
#asic
O'Connor estimates demand running twice the available supply for Broadcom, which makes the ability to deliver chips central to his thesis. Even though the chipmaker boasts demand, component availability and deployment timing will determine its conversion into earnings.
The biggest advantage that Broadcom holds is that it doesn't need to win new customers, but to keep expanding what it ships to the ones it already has. The company is already ramping Meta's MTIA program and OpenAI's Jalapeno chips, along with two other customers.
Google's TPU program remains Broadcom's major volume ASIC program, while Anthropic is also scaling deployments using AVGO-enabled TPU compute. Broadcom also boasts a rising networking attach rate, which is currently around 30%. This would likely generate an estimated $20-30 billion of total content per gigawatt of deployed capacity.
The firm has a line of sight to 12 gigawatts of demand in fiscal 2027, rising toward an estimated 38 gigawatts by fiscal 2030. This underpins a roughly 51% EPS compound growth rate through the decade.
#asic


14 hours ago
WASHINGTON (AP) — Republican Sen. Mitch McConnell of Kentucky returned to the Senate to vote on Monday for the first time in three months, looking noticeably more frail after he was hospitalized for a June fall in his home.
McConnell's lengthy absence from the Senate generated a flood of criticism and online speculation, as he initially remained quiet for weeks about his condition. The 84-year-old senator eventually disclosed a month later that he had been "briefly unconscious" due to the fall and had also been treated for mild pneumonia in the hospital.
He briefly addressed reporters Monday from a wheelchair outside the Senate chamber, smiling but speaking slowly and with some difficulty. McConnell joked that he wasn't sure how many reporters would be there after dodging so many questions during his almost two decades as leader.
He said he was back in the Senate to work on a pending farm bill and because he has an ongoing interest in NATO and "backing up our good friends who are totally in the fight against the Russians."
Reporters and photographers were told by Senate staff not to take video of his remarks in the second-floor hallway, even though video is often permitted in that area. Still images were allowed.
#mcconnell
McConnell's lengthy absence from the Senate generated a flood of criticism and online speculation, as he initially remained quiet for weeks about his condition. The 84-year-old senator eventually disclosed a month later that he had been "briefly unconscious" due to the fall and had also been treated for mild pneumonia in the hospital.
He briefly addressed reporters Monday from a wheelchair outside the Senate chamber, smiling but speaking slowly and with some difficulty. McConnell joked that he wasn't sure how many reporters would be there after dodging so many questions during his almost two decades as leader.
He said he was back in the Senate to work on a pending farm bill and because he has an ongoing interest in NATO and "backing up our good friends who are totally in the fight against the Russians."
Reporters and photographers were told by Senate staff not to take video of his remarks in the second-floor hallway, even though video is often permitted in that area. Still images were allowed.
#mcconnell



15 hours ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed

16 hours ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating