18 hours ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

19 hours ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

19 hours ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

19 hours ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

1 day ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services

1 day ago
Gold is the ******* et people buy when they have stopped believing in promises. Then most of them hand it to a bank in another country for safekeeping, which is itself a promise.
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters


1 day ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

1 day ago
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#less #retail
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#less #retail


1 day ago
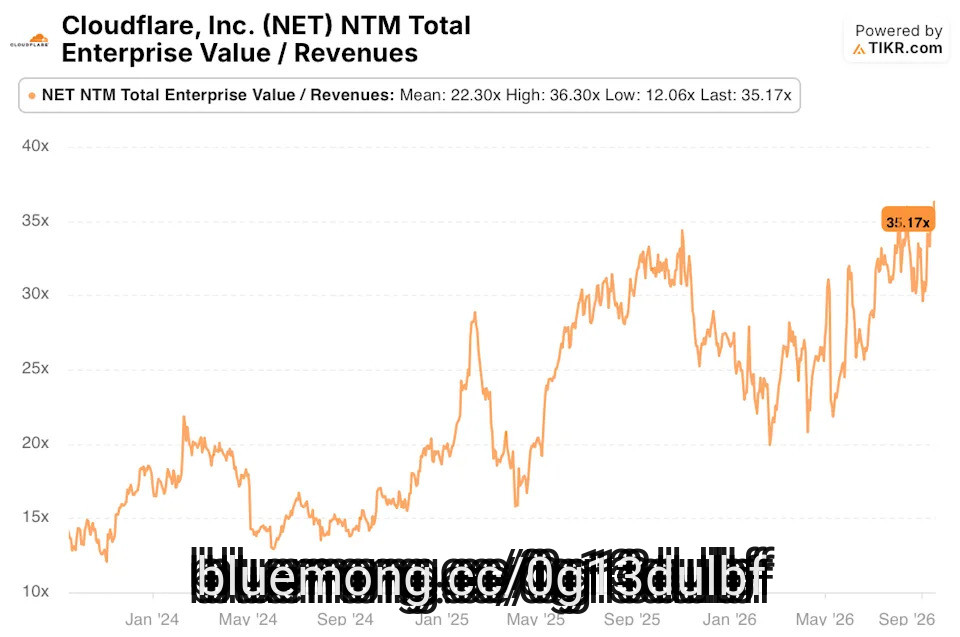
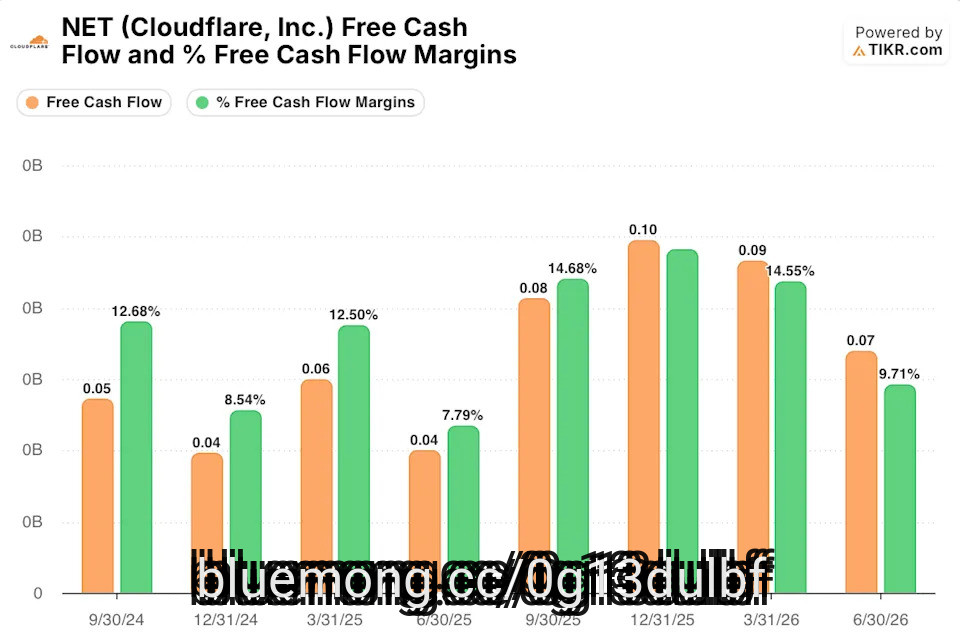
Cloudflare's Q2 beat and reaccelerating growth (36% revenue growth, 120% net dollar retention, record large customer adds) pushed NET stock to new highs, but the market has already paid up: NTM EV/Revenue sits at 35.17x, just below its all-time high of 36.30x and well above its roughly two-year average of 22.30x.
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar
1 day ago
On September 15, Digital Realty (NYSE:DLR) made ServiceFabric MCP available, a software layer that lets AI agents design, monitor and troubleshoot network connections across more than 800 data centers, including third-party sites. That nudges a real estate company toward becoming a control panel for enterprise AI. It arrives after second quarter results reported on July 23, when Core FFO per share, the company's preferred earnings yardstick, excluding net promote rose to $2.13 from $1.87 a year earlier. Here is what the launch does, and what it has yet to prove.
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18

1 day ago
Robinhood Markets (NASDAQ:HOOD) ended August with $384 billion in Total Platform **** ets, its term for everything customers hold on the platform -- up 8% from July and 26% from a year earlier, according to operating data published Sept. 10.
The next big round number, $500 billion, sits about 30% away. I think Robinhood gets there at some point during 2027.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The reason isn't a bold **** umption about markets or a bet on a new product taking off. Customers' own deposits carry the platform most of the way, and the market only has to cover a modest gap.
Image source: Getty Images.
#billion #think #NASDAQ
The next big round number, $500 billion, sits about 30% away. I think Robinhood gets there at some point during 2027.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The reason isn't a bold **** umption about markets or a bet on a new product taking off. Customers' own deposits carry the platform most of the way, and the market only has to cover a modest gap.
Image source: Getty Images.
#billion #think #NASDAQ

2 days ago
Eli Lilly (LLY) trades near $1,150, up about 52% over the past year, and is now worth more than a trillion dollars. At that size the easy read is that the big money has been made. But Lilly has barely started selling Foundayo, its oral obesity medicine, outside the United States. So how much is left? The scenario below starts from Lilly's own trailing numbers, but the growth, margin, and multiple it ***** umes are ours. It is not a forecast and not a price target.
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue
2 days ago
Accenture (ACN) stock has gone down for a year while the market has gone up. At around $190, it sits toward the cheap end of its own ten-year history on earnings. The risk sits in what those earnings are made of.
Accenture Stock Is Already Priced For Bad News
Accenture stock is down about 17% over the past year, while the S&P 500 gained about 17%. The stock has recovered some of that ground over the past three months. It trades at about 15 times earnings.
The question is whether the market has marked down the right thing.
But Accenture's Operating Margin Is At The High End Of Its Range
#accenture #down #market
Accenture Stock Is Already Priced For Bad News
Accenture stock is down about 17% over the past year, while the S&P 500 gained about 17%. The stock has recovered some of that ground over the past three months. It trades at about 15 times earnings.
The question is whether the market has marked down the right thing.
But Accenture's Operating Margin Is At The High End Of Its Range
#accenture #down #market


2 days ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
2 days ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

2 days ago
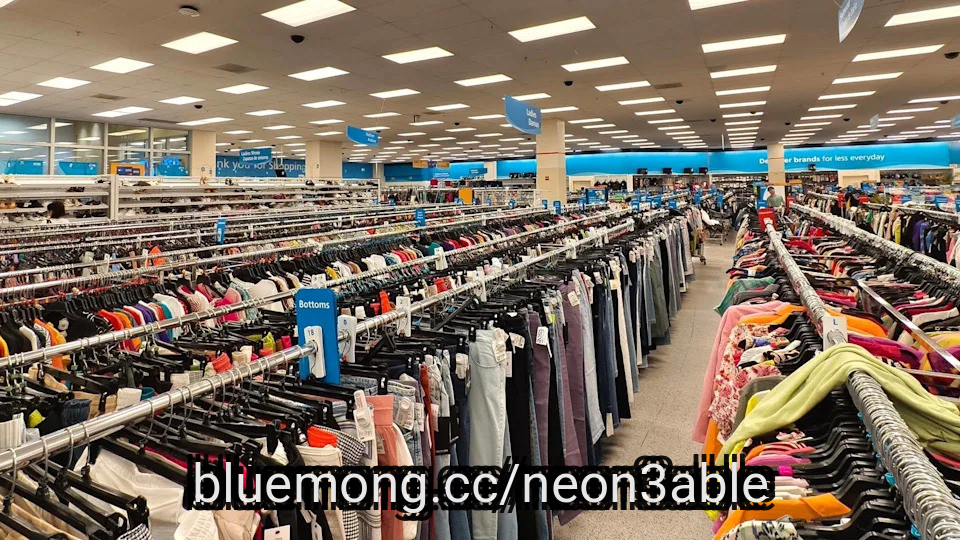
Pricing alone does not decide where people buy their clothes.
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price
With a number of retail chains competing for the off-price, on-trend fashion crown, it's easy for one brand to fall out of favor. Consumers seem to have an enduring love for Marshalls and TJ Maxx, while the popularity of Ross Dress for Less has grown steadily in recent years.
These brands drive sales by foot traffic, and that's a battle the aforementioned chains have been winning.
"Off-price apparel remained on solid footing in Q2 2026, with Ross leading the segment. Visits to Ross Dress for Less rose 16.4% year over year (YoY), while dd's DISCOUNTS grew 8.4%. TJX's TJ Maxx and Marshalls, meanwhile, saw visits hover around last year's levels — significantly outperforming traditional apparel, which declined 3.5% YoY," according to data from Placer.ai.
In the battle for customers looking for deals on trendy, fashionable clothes, Cato has been struggling, and now plans to close about 15% of its retail stores.
#price

2 days ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable

2 days ago
Recent initial public offering NB Bancorp (NBBK) is the IPO Stock Of The Week as it attempts to find support at a key level and with the stock within striking distance of a new buy point. This regional banking name also sits on Investor's Business Daily's IPO Leaders screen.
Massachusetts-based NB Bancorp is the holding company for Needham Bank, which was founded in 1892.
On July 22, NB Bancorp said its earnings growth accelerated to 33% in the second quarter, up from 9% in the first quarter. That was fueled by net interest margin expansion to 4% along with solid loan and deposit growth. Revenue jumped 46% from the year-ago period, to $74.7 million.
For the third quarter, ***** ysts expect NB Bancorp to earn 59 cents per share on revenue of $77.3 million. Those are respective year-over-year increases of 30% and 49%. Also, third-quarter earnings come due in late October.
And for the full year, Wall Street expects the banking leader to earn $2.14 per share, a 25% year-over-year increase. ***** ysts see further growth of 22% in 2027, according to IBD MarketSurge.
#revenue
Massachusetts-based NB Bancorp is the holding company for Needham Bank, which was founded in 1892.
On July 22, NB Bancorp said its earnings growth accelerated to 33% in the second quarter, up from 9% in the first quarter. That was fueled by net interest margin expansion to 4% along with solid loan and deposit growth. Revenue jumped 46% from the year-ago period, to $74.7 million.
For the third quarter, ***** ysts expect NB Bancorp to earn 59 cents per share on revenue of $77.3 million. Those are respective year-over-year increases of 30% and 49%. Also, third-quarter earnings come due in late October.
And for the full year, Wall Street expects the banking leader to earn $2.14 per share, a 25% year-over-year increase. ***** ysts see further growth of 22% in 2027, according to IBD MarketSurge.
#revenue
2 days ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management

2 days ago
Nvidia (NASDAQ: NVDA) and Micron Technology (NASDAQ: MU) are two of the biggest companies in the world. Nvidia holds the top spot, sitting at a $5.3 trillion valuation. Micron currently sits at 13th place worldwide, with a $1.1 trillion valuation. These companies are also two of the biggest beneficiaries of the artificial intelligence (AI) build-out, and with that expected to ramp up again in 2027, these two are in a prime position to benefit.
But which stock stands to benefit more? Let's take a look at these two and see which stock makes the most sense for your investment dollars.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Nvidia and Micron are partners in the AI arms race. Micron makes memory chips, including DRAM memory that's utilized inside Nvidia GPUs. Micron's DRAM chips are also utilized in several other competitors' products, and demand for these products continues to rise.
Nvidia forecasts that the big five AI hyperscalers will spend nearly $800 billion on data center capital expenditures during 2026. Next year, that figure is projected to rise to $1.3 trillion. That's a lot of GPUs from Nvidia, filled with memory chips from Micron. There is huge demand for each company's product, but there is a stark difference in the long-term demand curve for each.
#memory #demand #gpus
But which stock stands to benefit more? Let's take a look at these two and see which stock makes the most sense for your investment dollars.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Nvidia and Micron are partners in the AI arms race. Micron makes memory chips, including DRAM memory that's utilized inside Nvidia GPUs. Micron's DRAM chips are also utilized in several other competitors' products, and demand for these products continues to rise.
Nvidia forecasts that the big five AI hyperscalers will spend nearly $800 billion on data center capital expenditures during 2026. Next year, that figure is projected to rise to $1.3 trillion. That's a lot of GPUs from Nvidia, filled with memory chips from Micron. There is huge demand for each company's product, but there is a stark difference in the long-term demand curve for each.
#memory #demand #gpus

2 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
2 days ago
One of the challenges for nontraditional fintech lenders has been the expense **** ociated with lending.
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest

2 days ago
Zcash (ZEC) has climbed 177.8% in a month, and the traders betting against it are paying for that move.
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
#million #open
One short was closed at a $10.68 million loss this week, and the largest position still open sits $33.87 million underwater on Hyperliquid.
Lookonchain flagged the closed trade before the exit, citing 26 consecutive wins and an 89% rate across 47 trades. That record had produced more than $9 million in profit.
The short covered 12,285 ZEC and was worth $18.31 million earlier, with liquidation set at $1,550.66. Hyperliquid data shows the account now holds no positions at all.
Garrett Jin holds the largest short still open, covering 37,999 ZEC worth $59.37 million. He built the position at an average price of $671.05, so it now shows an unrealized loss of $33.87 million.
#million #open



2 days ago
It's no secret that Arm Holdings (NASDAQ: ARM) is a crucial piece of the artificial intelligence (AI) puzzle. But how often do you think of Arm as a top-shelf AI investment? It's easy to forget this impressive compounder amid the glitzy hypergrowth of Nvidia's and AMD's expensive AI accelerators.
Arm doesn't build the chips that train large language models. The company doesn't actually build chips at all. Instead, Arm designs fundamental instruction sets and CPU cores. It licenses those designs to anyone with a fab contract and an ambition and collects a royalty on every unit shipped. It's basically a toll booth on a road that keeps getting wider.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Arm's toll road used to run almost entirely through smartphones. Now it runs through the data center too. Nvidia's Vera CPU pairs Arm cores with its accelerators. Amazon's Graviton, Microsoft's Cobalt, and Alphabet's Google Axion are all Arm-based, built in-house by companies that spend like nation-states on server capacity.
Every AI cluster on the planet needs general-purpose compute to feed the high-speed AI accelerators, handle networking, and run the orchestration layer. A growing share of that work sits on Arm designs.
#signal #flashing #build #chips
Arm doesn't build the chips that train large language models. The company doesn't actually build chips at all. Instead, Arm designs fundamental instruction sets and CPU cores. It licenses those designs to anyone with a fab contract and an ambition and collects a royalty on every unit shipped. It's basically a toll booth on a road that keeps getting wider.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Arm's toll road used to run almost entirely through smartphones. Now it runs through the data center too. Nvidia's Vera CPU pairs Arm cores with its accelerators. Amazon's Graviton, Microsoft's Cobalt, and Alphabet's Google Axion are all Arm-based, built in-house by companies that spend like nation-states on server capacity.
Every AI cluster on the planet needs general-purpose compute to feed the high-speed AI accelerators, handle networking, and run the orchestration layer. A growing share of that work sits on Arm designs.
#signal #flashing #build #chips

2 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson


2 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
2 days ago
On September 16, Evolution Petroleum Corporation (NYSEAMERICAN:EPM) held its fiscal fourth-quarter and full-year 2026 earnings call, and the numbers told a story of a company climbing out of a rough patch. Revenue jumped 20% sequentially to $24.2 million as oil prices realized before hedge settlements shot up 49% year over year to $90.74 a barrel. Adjusted EBITDA more than doubled to $6.5 million. After a bruising third quarter, the fourth quarter finally looked like the recovery management had promised investors back in May.
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel

2 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

3 days ago
Data center developer Crusoe said Thursday it raised $3.9 billion in a Series F round that pushes its valuation to $30.9 billion. The massive round was co-led by Atreides Management, Mubadala Capital, and Valor Equity Partners. Founders Fund, GIC, Nvidia, Qatar Investment Authority (QIA), Radical Ventures, and TPG also participated, according to Crusoe.
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round


3 days ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion