

18 hours ago
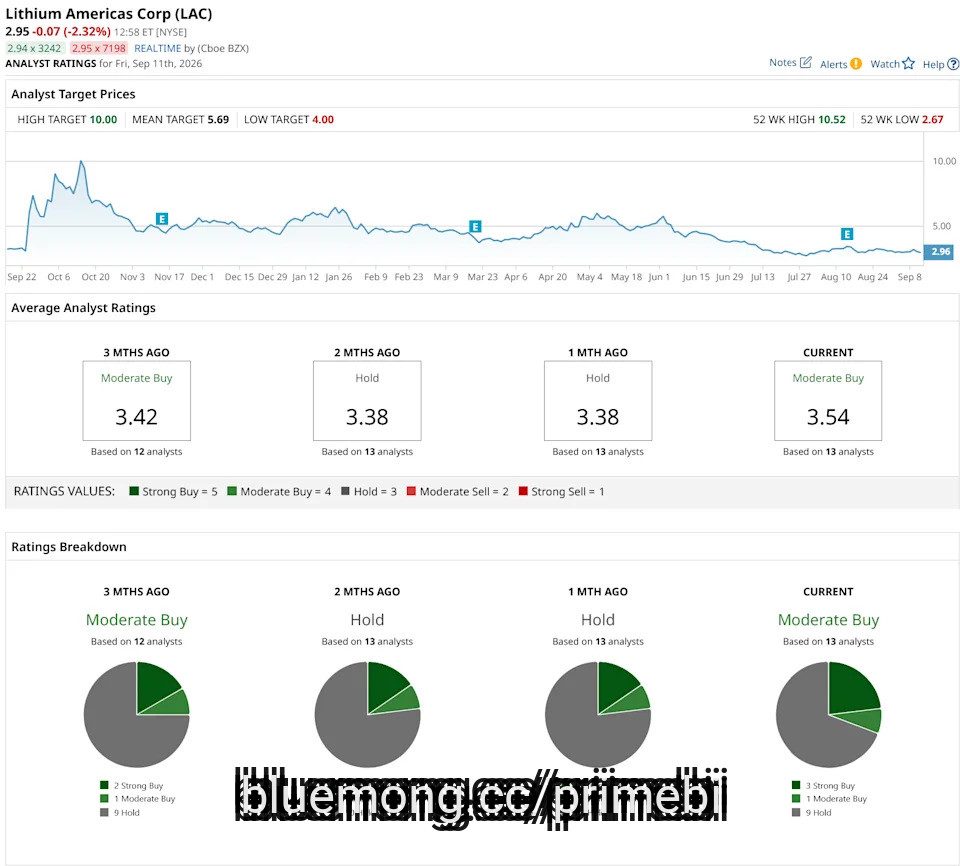
Lithium Americas Corp. (LAC) is back on Wall Street's radar after JPMorgan turned bullish on the lithium developer, upgrading the stock to an "Overweight" rating from "Neutral" and setting a $6 price target. The target implies close to 100% upside from the stock's previous close, giving investors a potentially significant re-rating opportunity if the bank's bullish **** umptions play out.
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play


18 hours ago
After spending years trading like a premium-priced AI leader, Nvidia may now be among the cheapest names in Piper Sandler's AI universe. NVIDIA Corporation (NASDAQ:NVDA) is trading at an attractive valuation according to Piper Sandler's forecast, with rapid AI growth backing its trajectory.
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company
On September 9, Piper Sandler ***** yst David O'Connor initiated coverage on NVIDIA Corporation (NASDAQ:NVDA) with an Overweight rating and a price target of $300, implying roughly 34% upside.
The firm believes that the chipmaker is an outright AI compute leader controlling 80% of the market by value and an estimated 50% by units. Owing to its annual cadence of next-generation products, it has been able to continue to drive the industry forward.
Everyone knows and agrees that Nvidia has grown at an exponential pace. Its recent results offer evidence of operational strength as well. The company reported second-quarter fiscal 2027 revenue of $96.2 billion, up 106% year-over-year.
The chipmaker's data center revenue also surged 117% to $89 billion. GAAP gross margin was75%, while adjusted diluted earnings reached $2.22 per share. The figures highlight how Nvidia's robust demand is translating into profitability for the company.
#NVIDIA #corporation #trading #company


23 hours ago
Taxes paid by pubs, hotels and cinemas in Wales will fall after the Welsh government announced a 30% cut in some business rates.
First Minister Rhun ap Iorwerth said hospitality, accommodation and leisure venues would receive the permanent cut in rates from April 2027.
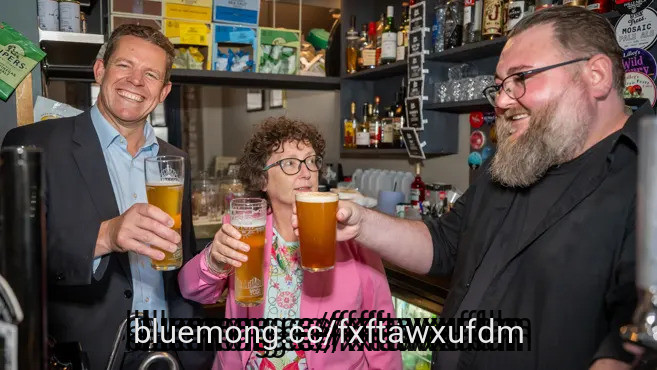
"It is about helping businesses like this to thrive, so our communities can thrive," ap Iorwerth said on a visit to a pub in Cardiff.
The cut, which will be funded by an increase in the rates paid by businesses with the highest-value properties, was welcomed by UK Hospitality Cymru. But the trade body warned businesses still faced "massive amounts of taxation coming from all areas".
Pubs will be among the hospitality businesses in Wales to receive a permanent tax cut from April [Getty Images]
#april
First Minister Rhun ap Iorwerth said hospitality, accommodation and leisure venues would receive the permanent cut in rates from April 2027.
"It is about helping businesses like this to thrive, so our communities can thrive," ap Iorwerth said on a visit to a pub in Cardiff.
The cut, which will be funded by an increase in the rates paid by businesses with the highest-value properties, was welcomed by UK Hospitality Cymru. But the trade body warned businesses still faced "massive amounts of taxation coming from all areas".
Pubs will be among the hospitality businesses in Wales to receive a permanent tax cut from April [Getty Images]
#april


1 day ago
In an early offseason move, the Kansas City Chiefs shocked the football world when they traded away former All-Pro cornerback Trent McDuffie to the Los Angeles Rams. After all, how could a Chiefs team, ostensibly in the middle of a Super Bowl window, trade away a 26-year-old cornerback entering his prime like McDuffie? Couldn't they have used him during monster matchups like their home date with the Denver Broncos on Monday night?
At face value, the move is honestly still kind of baffling from a Kansas City perspective, considering that older Chiefs veterans like Travis Kelce and Chris Jones aren't getting any younger. But as you watch the Chiefs' defense try to adjust without McDuffie, know that they did have a good reason for dealing one of their better young players.
As explained by ESPN's Nate Taylor, the Chiefs entered the 2026 offseason knowing they wanted a big draft haul so they could try to open a new Super Bowl window while their current core begins to age out of the NFL. After reviewing their best options, they eventually came to the conclusion that trading away McDuffie, a player they weren't too keen on giving a lucrative contract extension to, was their optimal path toward that goal.
I would say acquiring a first-round draft pick in 2026 (which became defensive tackle Peter Woods) and a host of other solid draft ****** ets for McDuffie was a pretty good deal for the team, with all things considered.
More from ESPN:
#away #super
At face value, the move is honestly still kind of baffling from a Kansas City perspective, considering that older Chiefs veterans like Travis Kelce and Chris Jones aren't getting any younger. But as you watch the Chiefs' defense try to adjust without McDuffie, know that they did have a good reason for dealing one of their better young players.
As explained by ESPN's Nate Taylor, the Chiefs entered the 2026 offseason knowing they wanted a big draft haul so they could try to open a new Super Bowl window while their current core begins to age out of the NFL. After reviewing their best options, they eventually came to the conclusion that trading away McDuffie, a player they weren't too keen on giving a lucrative contract extension to, was their optimal path toward that goal.
I would say acquiring a first-round draft pick in 2026 (which became defensive tackle Peter Woods) and a host of other solid draft ****** ets for McDuffie was a pretty good deal for the team, with all things considered.
More from ESPN:
#away #super


1 day ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen

1 day ago
September's debate over Chinese and American AI spending puts Alibaba Group Holding Limited (NYSE:BABA) and Amazon.com, Inc. (NASDAQ:AMZN) on opposite sides of the same investment question. Both report strong demand for computing services. Shareholders still need that demand to justify the infrastructure bill.
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services


1 day ago
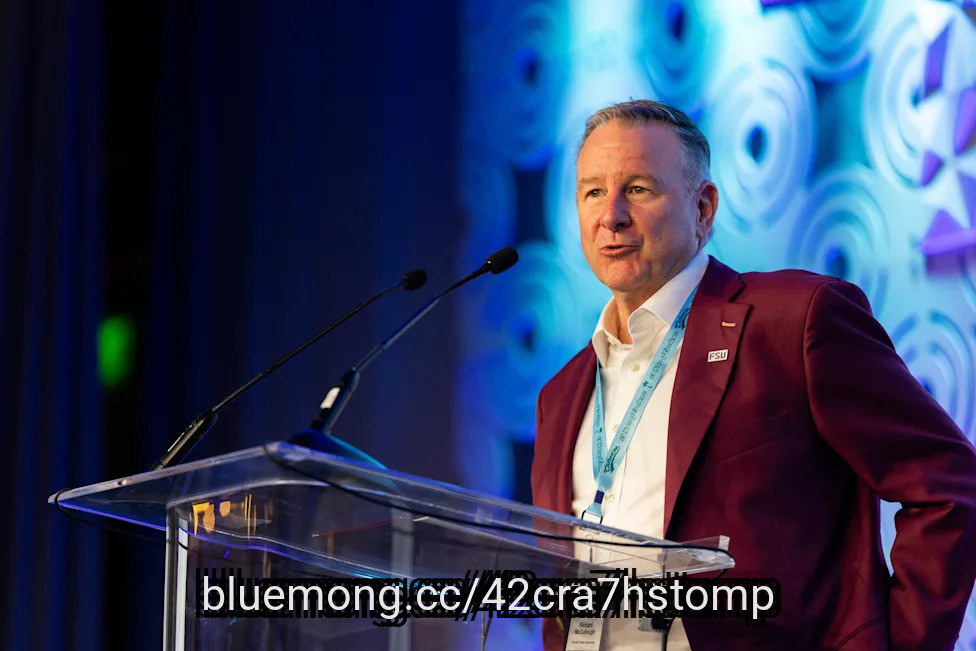
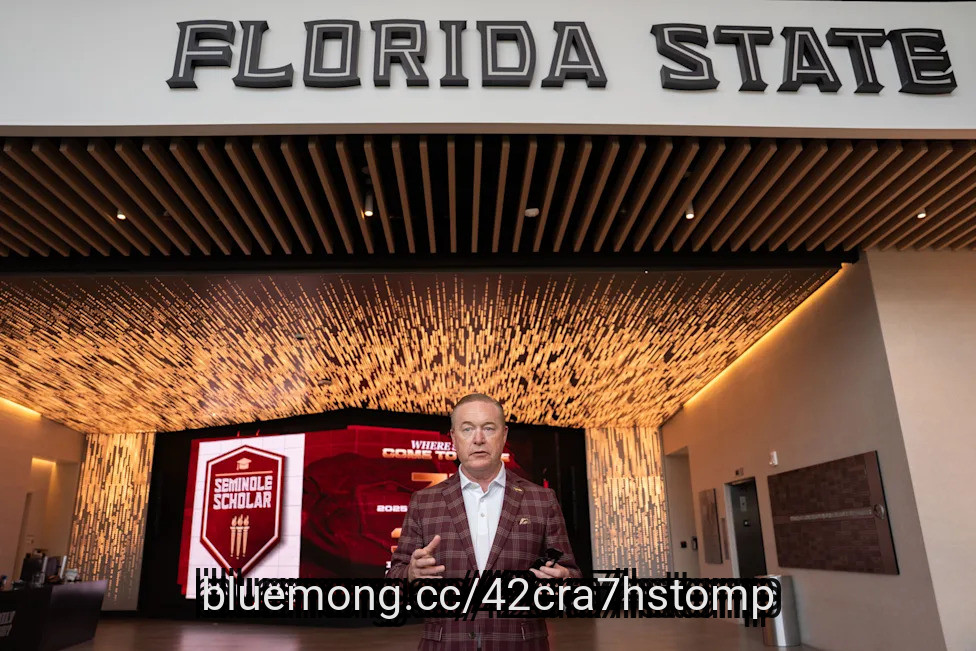
Florida State is in search of a new athletic director after the university fired Michael Alford on Monday, Sep. 14, four years after he was hired.
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate
The move was made by FSU president Richard McCullough, who said the Seminoles' athletic program needs to better position itself for the future of collegiate athletics. When he spoke with the media Monday morning, McCullough gave insight into what FSU is looking for in its next athletic director.
He placed a value on business acumen and cited the need for success in revenue generation, while also being savvy enough to navigate the complexities of modern collegiate sports, particularly football.
While no move is imminent, here are a few names that make our initial FSU AD hot board.
Dickey has led the Broncos since 2021, and during his time as the program's athletic director, ***** ey has had a huge impact on revenue generation for the program. That's an area that McCullough highlighted as being important to the Seminoles next AD when speaking to the media after Alford's firing. ***** ey, named the 2025 National ***** ociation of Collegiate Directors of Athletics AD of the year, has overseen Boise State's transition from the Mountain West into the reimagined Pac-12, which would suit FSU and the university's potential interest in departing the ACC.
#Athletic #collegiate


1 day ago
Oil futures have been rising, but recently hit a peak. ConocoPhillips (COP) reported strong Q2 earnings on Aug. 6, and COP stock may be fairly valued. However, shorting COP puts and vertical put credit spreads are attractive alternatives for value investors.
COP closed at $137.35 on Friday, Sept. 11, a recent three-, six-, and 12-month peak. That followed WTI Oct. futures contract (CLV26) spiking above $104 late Thursday, Sept. 10.
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The market clearly believes that Conoco's Q3 earnings and cash flow will be strong, given how high oil and gas prices have been this quarter. Barchart's CLV26 chart below shows the recent peak in oil futures.
Oil has been rising due to ongoing tensions and kinetic action between the U.S. and Iran, as well as in other areas in the Middle East where oil is transported.
#sept
COP closed at $137.35 on Friday, Sept. 11, a recent three-, six-, and 12-month peak. That followed WTI Oct. futures contract (CLV26) spiking above $104 late Thursday, Sept. 10.
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The market clearly believes that Conoco's Q3 earnings and cash flow will be strong, given how high oil and gas prices have been this quarter. Barchart's CLV26 chart below shows the recent peak in oil futures.
Oil has been rising due to ongoing tensions and kinetic action between the U.S. and Iran, as well as in other areas in the Middle East where oil is transported.
#sept



1 day ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
1 day ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted


1 day ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter

1 day ago
In fantasy football, you have to look back to move forward. Fantasy points are the goal, but how a player gets there is the key. Yahoo ******* yst Joel Smyth breaks down 11 usage notes from Week 1 in order to win your matchup in Week 2 and beyond.
Join or create a Yahoo Fantasy Football league for the 2026 NFL season
Of routes run in Week 1 for Dalton Kincaid, higher than any mark in 2025. This is good for most TEs, but incredible and notable for Kincaid. As a first-round TE talent, Kincaid has been limited throughout his career due to run blocking and injuries. Last season before his knee injury, he was right at 60% of the routes, good enough to be a mid-level TE1, although not ideal. After the injury, it dropped to 44%. If a ~70% route share holds, Kincaid can be the TE value of the year. His yards per route were top-three in the NFL (not just TE) and he is a part of one of the best offenses in the league. He had a nice start to the season with 130 receiving yards against the Texans defense.
The RB target split for Bucky Irving compared to Kenny Gainwell in Week 1 (and would've been eight without penalties). Gainwell was a backup RB that wasn't a focus of the offense, with only 18% of snaps resulting in a touch (Irving: 47%). Not to mention, Irving got both red-zone carries, one resulting in a touchdown. Sean Tucker is still out for now, but Irving looks to be a workhorse RB with elite receiving potential.
Gold opportunities for Chuba Hubbard: two red-zone targets and a goal-line attempt. They're the best opportunities for a touchdown for a RB, and it resulted in two here. Chicago's defense may need some help, but the workload should keep him as a weekly play as long as he holds off Jonathon Brooks. With 71% of the RB touches, anybody can have value. Before his injury last season, Hubbard began the 2025 season with nearly 20 touches per game over the first few weeks. I trust the stability of his volume going into Week 2 as a central role of the red-zone offense.
#season #fantasy #gainwell #hubbard
Join or create a Yahoo Fantasy Football league for the 2026 NFL season
Of routes run in Week 1 for Dalton Kincaid, higher than any mark in 2025. This is good for most TEs, but incredible and notable for Kincaid. As a first-round TE talent, Kincaid has been limited throughout his career due to run blocking and injuries. Last season before his knee injury, he was right at 60% of the routes, good enough to be a mid-level TE1, although not ideal. After the injury, it dropped to 44%. If a ~70% route share holds, Kincaid can be the TE value of the year. His yards per route were top-three in the NFL (not just TE) and he is a part of one of the best offenses in the league. He had a nice start to the season with 130 receiving yards against the Texans defense.
The RB target split for Bucky Irving compared to Kenny Gainwell in Week 1 (and would've been eight without penalties). Gainwell was a backup RB that wasn't a focus of the offense, with only 18% of snaps resulting in a touch (Irving: 47%). Not to mention, Irving got both red-zone carries, one resulting in a touchdown. Sean Tucker is still out for now, but Irving looks to be a workhorse RB with elite receiving potential.
Gold opportunities for Chuba Hubbard: two red-zone targets and a goal-line attempt. They're the best opportunities for a touchdown for a RB, and it resulted in two here. Chicago's defense may need some help, but the workload should keep him as a weekly play as long as he holds off Jonathon Brooks. With 71% of the RB touches, anybody can have value. Before his injury last season, Hubbard began the 2025 season with nearly 20 touches per game over the first few weeks. I trust the stability of his volume going into Week 2 as a central role of the red-zone offense.
#season #fantasy #gainwell #hubbard



1 day ago
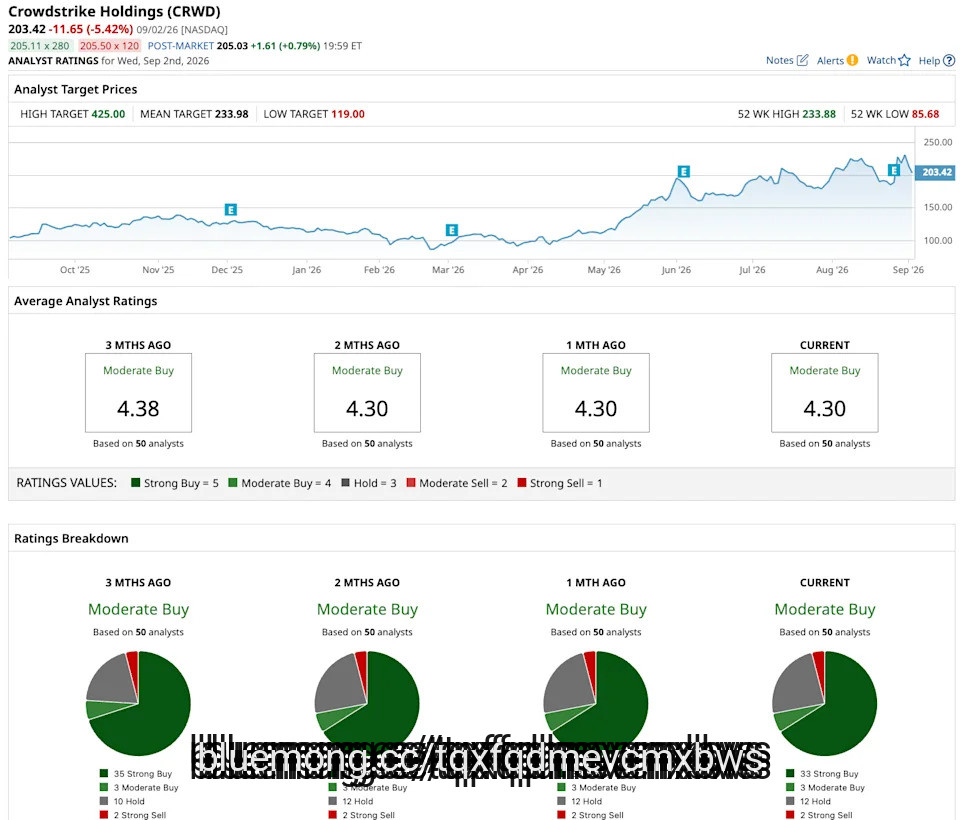
CrowdStrike (CRWD) is among the largest cybersecurity companies globally. Valued at a market capitalization of more than $218 billion, CrowdStrike stock has returned more than 500% since its initial public offering (IPO) in 2019.
At its Fal.Con conference this week, the cybersecurity giant rolled out two major artificial intelligence (AI) products built to protect the growing army of AI agents running inside businesses. These announcements have arrived as CRWD stock draws fresh attention from Wall Street. CrowdStrike is betting that securing AI will soon be the key driver of its future growth engine.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#Stock #fans
At its Fal.Con conference this week, the cybersecurity giant rolled out two major artificial intelligence (AI) products built to protect the growing army of AI agents running inside businesses. These announcements have arrived as CRWD stock draws fresh attention from Wall Street. CrowdStrike is betting that securing AI will soon be the key driver of its future growth engine.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#Stock #fans


1 day ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue


1 day ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal


1 day ago
On September 10, Tsakos Energy Navigation (NYSE:TEN) reported a first half of 2026 that reads like a fantasy year for a decades-old tanker operator. Net income hit $228 million, more than triple what the company earned over the same six months a year earlier, while diluted EPS climbed to $7.12 from $1.70. Behind those numbers sits a rare combination: a fleet locked into billions in forward earnings, war-driven cargo detours pushing rates higher, and a newbuilding bet that has already paid off before half the ships have even hit the water.
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion

1 day ago
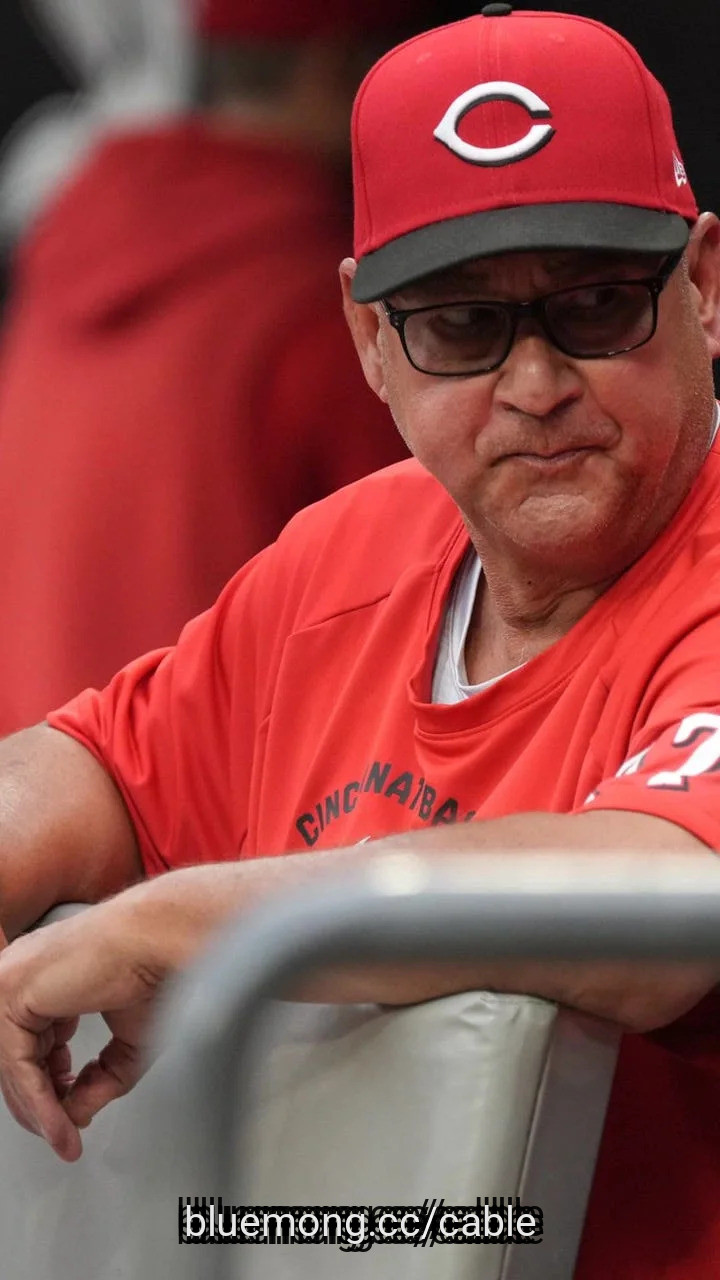
Cincinnati Reds manager Terry Francona's future is drawing attention as the front office looks ahead to next season. Francona has one guaranteed year left on his original three-year contract, plus a club option for 2028. Team president Nick Krall said he doesn't think it is a lame-duck status for someone like Francona. Francona said he values the people around him and feels stronger about them after being there for a while. He said the Reds would be hard pressed to find a better fit for what they are trying to do. Francona earned his 2,103rd managerial win when the Reds beat the Brewers 4-3 on Sunday, Sept. 13.
#year #cincinnati #nick #sunday
#year #cincinnati #nick #sunday

1 day ago
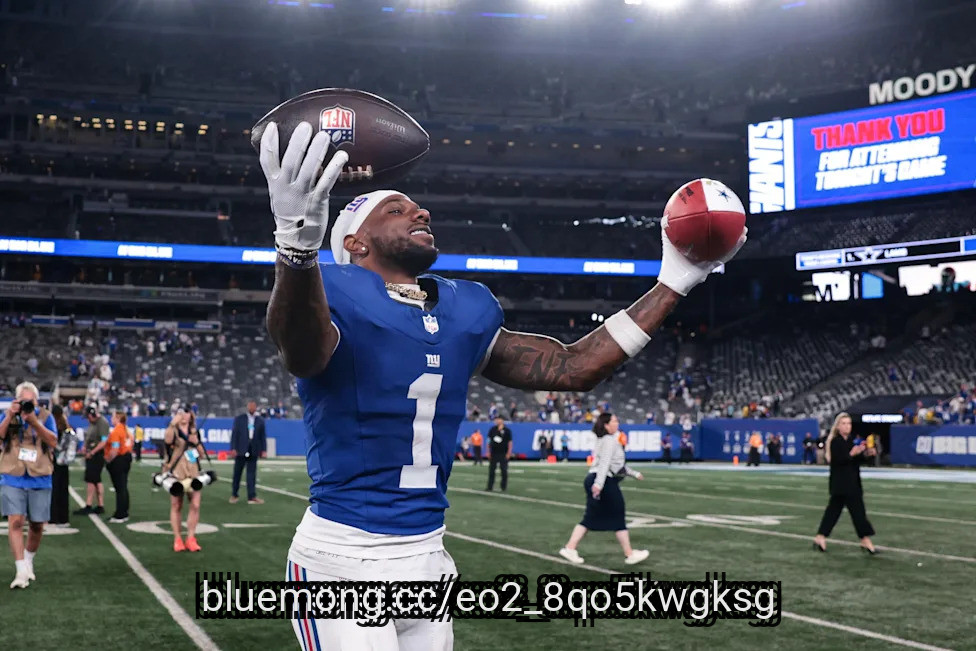
The John Harbaugh era got off to a rousing start last night with the New York Giants defeating the division rival Dallas Cowboys 28-20 at a raucous MetLife Stadium. (When was the last time "raucous" and "MetLife" appeared in the same sentence about a Giants game?) Let's see what the **** ysts at Pro Football Focus thought of the individual player performances.
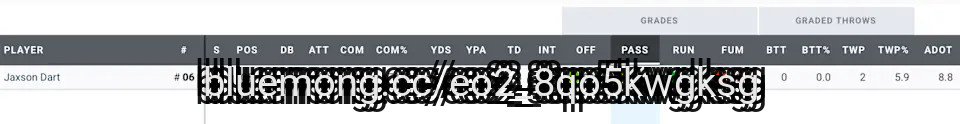
Focusing first on the passing, Jaxson Dart's 23 of 29, 230-yard, 3 TD, 0 INT performance was given a grade of…65.8, smack in the middle of their "average" range. I'm sure fans will take Dart's highly efficient game, as evidenced by his excellent 134.2 NFL passer rating last night, every week. PFF, though, grades on degree of difficulty and taking care of the ball. Dart didn't have any interceptions, but in PFF's eyes he had two turnover-worthy plays, which they see as being just as bad. He also did not have any "big-time," throws, i.e., **** placed accurately into tight windows and especially those that go deep downfield for explosive plays. Dart only threw three **** beyond 20 yards and only completed one. To quote Seinfeld, "Not that there's anything wrong with that," but that's what PFF values. Dart did what he had to do to win the game. In the long run, he'll have to show that he can hurt opposing defenses deep on a consistent basis, but for one game the short-range passing game was just fine.
Let's look at the effect of pressure:
Dart was an amazing 19 of 22 when kept clean, including all three of his TD passes. When pressured he was 4 of 7 for 57 yards, but both of his TWPs came under pressure.
Moving on to the pass blocking:
#night
Focusing first on the passing, Jaxson Dart's 23 of 29, 230-yard, 3 TD, 0 INT performance was given a grade of…65.8, smack in the middle of their "average" range. I'm sure fans will take Dart's highly efficient game, as evidenced by his excellent 134.2 NFL passer rating last night, every week. PFF, though, grades on degree of difficulty and taking care of the ball. Dart didn't have any interceptions, but in PFF's eyes he had two turnover-worthy plays, which they see as being just as bad. He also did not have any "big-time," throws, i.e., **** placed accurately into tight windows and especially those that go deep downfield for explosive plays. Dart only threw three **** beyond 20 yards and only completed one. To quote Seinfeld, "Not that there's anything wrong with that," but that's what PFF values. Dart did what he had to do to win the game. In the long run, he'll have to show that he can hurt opposing defenses deep on a consistent basis, but for one game the short-range passing game was just fine.
Let's look at the effect of pressure:
Dart was an amazing 19 of 22 when kept clean, including all three of his TD passes. When pressured he was 4 of 7 for 57 yards, but both of his TWPs came under pressure.
Moving on to the pass blocking:
#night


1 day ago
ARAPAHOE, Wyo. (AP) — Every Sunday morning on the Wind River Reservation, congregants gather at Foundations for Nations Church to pray while protesters outside do the same.
The two rituals have unfolded in parallel since the Christian church's pastor, Sarah Lucas, preached a sermon condemning Arapaho ceremonial ways.
The Northern Arapaho and Eastern Shoshone Tribes that share the reservation have made clear that Lucas is no longer welcome. Lucas, who is not Native American but owns the land under her church, says she isn't going anywhere. The standoff tests the boundaries of religious freedom and the right of a tribal nation to govern according to its own values and protocols.
The conflict stems from a video that circulated in July as Arapaho people surfaced from their weeklong sundance ceremony. In it, Lucas called that cornerstone of Arapaho spiritual life "idol worship."
"Jesus is the chain breaker. He is the only God that we should be praying to," Lucas said.
#arapaho #church
The two rituals have unfolded in parallel since the Christian church's pastor, Sarah Lucas, preached a sermon condemning Arapaho ceremonial ways.
The Northern Arapaho and Eastern Shoshone Tribes that share the reservation have made clear that Lucas is no longer welcome. Lucas, who is not Native American but owns the land under her church, says she isn't going anywhere. The standoff tests the boundaries of religious freedom and the right of a tribal nation to govern according to its own values and protocols.
The conflict stems from a video that circulated in July as Arapaho people surfaced from their weeklong sundance ceremony. In it, Lucas called that cornerstone of Arapaho spiritual life "idol worship."
"Jesus is the chain breaker. He is the only God that we should be praying to," Lucas said.
#arapaho #church

1 day ago
Nasdaq-listed DeFi Development Corp (NASDAQ: $DFDV) has increased its Solana (CRYPTO: $SOL) treasury by 55,491 SOL, bringing its total holdings to about 2.39 million SOL and SOL equivalents.
The company said Monday that its treasury has grown roughly 2% since August 27 as it resumed regular Solana purchases and continued generating yield from its holdings. DeFi Development Corp is now the second-largest public-company holder of Solana after Forward Industries.
Alongside the treasury increase, the company established a $300 million at-the-market offering for its CHAD perpetual preferred stock. The Variable Rate Series C Perpetual Preferred Stock carries an initial annual dividend rate of 13%. DeFi Development said it plans to issue the shares at or above their $10 par value, with most of the proceeds expected to fund additional SOL purchases.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#NASDAQ #offering
The company said Monday that its treasury has grown roughly 2% since August 27 as it resumed regular Solana purchases and continued generating yield from its holdings. DeFi Development Corp is now the second-largest public-company holder of Solana after Forward Industries.
Alongside the treasury increase, the company established a $300 million at-the-market offering for its CHAD perpetual preferred stock. The Variable Rate Series C Perpetual Preferred Stock carries an initial annual dividend rate of 13%. DeFi Development said it plans to issue the shares at or above their $10 par value, with most of the proceeds expected to fund additional SOL purchases.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#NASDAQ #offering
1 day ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product
1 day ago
Broadcom's AI revenue surged 221% year over year with a forward P/E of 19, making it cheaper than Nvidia despite a similar growth trajectory.
TSMC revenue rose 53% year over year at a forward P/E of 20, and Dell booked a record $61B in AI orders last quarter.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom's custom accelerator business the centerpiece of the case. Bilal countered that "you have to go with the people who are on the leaderboard," naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
#NVIDIA #billion #enter
TSMC revenue rose 53% year over year at a forward P/E of 20, and Dell booked a record $61B in AI orders last quarter.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA didn't make the cut. Enter your email to see the names that beat NVDA. The report is free. Enter your email and see if any of your stocks made the cut.
On a recent Earn Your Leisure episode, hosts Troy Millings and Rashaad Bilal split openly on where the next dollar of AI value accrues. Millings argued for names outside the Magnificent 7 and made Broadcom's custom accelerator business the centerpiece of the case. Bilal countered that "you have to go with the people who are on the leaderboard," naming Taiwan Semiconductor (NYSE:TSM), Nvidia (NASDAQ:NVDA), Micron (NASDAQ:MU), Apple (NASDAQ:AAPL), Alphabet (NASDAQ:GOOG, NASDAQ:GOOGL), Microsoft (NASDAQ:MSFT), and the Nasdaq 100.
I find Millings the more persuasive of the two. Broadcom (NASDAQ:AVGO) posted AI semiconductor revenue of $16.7 billion in the third quarter of fiscal 2026, up 221% year over year, and guided the fourth quarter to $21.7 billion, up 236%. On the earnings call, Hock Tan sketched a trajectory to roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
#NVIDIA #billion #enter



1 day ago
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing

1 day ago
CHATTANOOGA, Tenn. — Kenco opened a 30,000-square-foot Innovation Lab on Sept. 10, tripling a testing footprint the third-party logistics provider first built in 2015.
The larger facility allows Kenco to run warehouse automation testing on larger and more complex systems. It also allows more of those systems to run side by side. Testing takes place inside a building designed to mirror real-world warehouse conditions so results carry over to a live distribution center.
Ainsley Williams, vice president of automation and innovation at Kenco, described the expansion as benefiting both manufacturers and customers.
"The Innovation Lab has long stood as the convergence point for leading technologies and real-world applications, helping both manufacturers and customers identify and realize what's possible," Williams said. "By tripling our innovation footprint, we can further provide a ***** e for OEMs to continue experimenting with their products in a real environment and for customers to explore product and value without having to invest in them."
The original lab was created to help the company understand how emerging technologies such as automation would affect its operations.
#real #customers #larger
The larger facility allows Kenco to run warehouse automation testing on larger and more complex systems. It also allows more of those systems to run side by side. Testing takes place inside a building designed to mirror real-world warehouse conditions so results carry over to a live distribution center.
Ainsley Williams, vice president of automation and innovation at Kenco, described the expansion as benefiting both manufacturers and customers.
"The Innovation Lab has long stood as the convergence point for leading technologies and real-world applications, helping both manufacturers and customers identify and realize what's possible," Williams said. "By tripling our innovation footprint, we can further provide a ***** e for OEMs to continue experimenting with their products in a real environment and for customers to explore product and value without having to invest in them."
The original lab was created to help the company understand how emerging technologies such as automation would affect its operations.
#real #customers #larger


1 day ago
Micron Technology (NASDAQ:MU) has been one of the hottest stocks to own this year, with its value rising by more than 240% heading into trading this week. At over $1 trillion in market cap, it has joined the illustrious trillion-dollar club this year and become one of the most valuable companies in the world.
And yet, investors remain bullish that it can continue to soar higher due to the impressive growth it's been generating, as tech giants continue to invest heavily in artificial intelligence (AI).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron recently announced plans to increase production of high-bandwidth memory (HBM), which could result in even better financial results. Here's why.
Image source: Getty Images.
#micron #technology #NASDAQ #missed
And yet, investors remain bullish that it can continue to soar higher due to the impressive growth it's been generating, as tech giants continue to invest heavily in artificial intelligence (AI).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron recently announced plans to increase production of high-bandwidth memory (HBM), which could result in even better financial results. Here's why.
Image source: Getty Images.
#micron #technology #NASDAQ #missed
1 day ago
Dennis W. Liu, Chief Accounting Officer of Clear Secure, Inc. (NYSE:YOU), disposed of 6,059 shares of Class A Common Stock between September 1, 2026, and September 3, 2026, as disclosed in a recent SEC Form 4 filing.
Metric
Value
Transaction value
~$263,500
#september #dennis #secure
Metric
Value
Transaction value
~$263,500
#september #dennis #secure



1 day ago
New Balance has announced it has added Golden Globe Award-winning actor Ayo Edebiri to its roster of brand ambassadors.
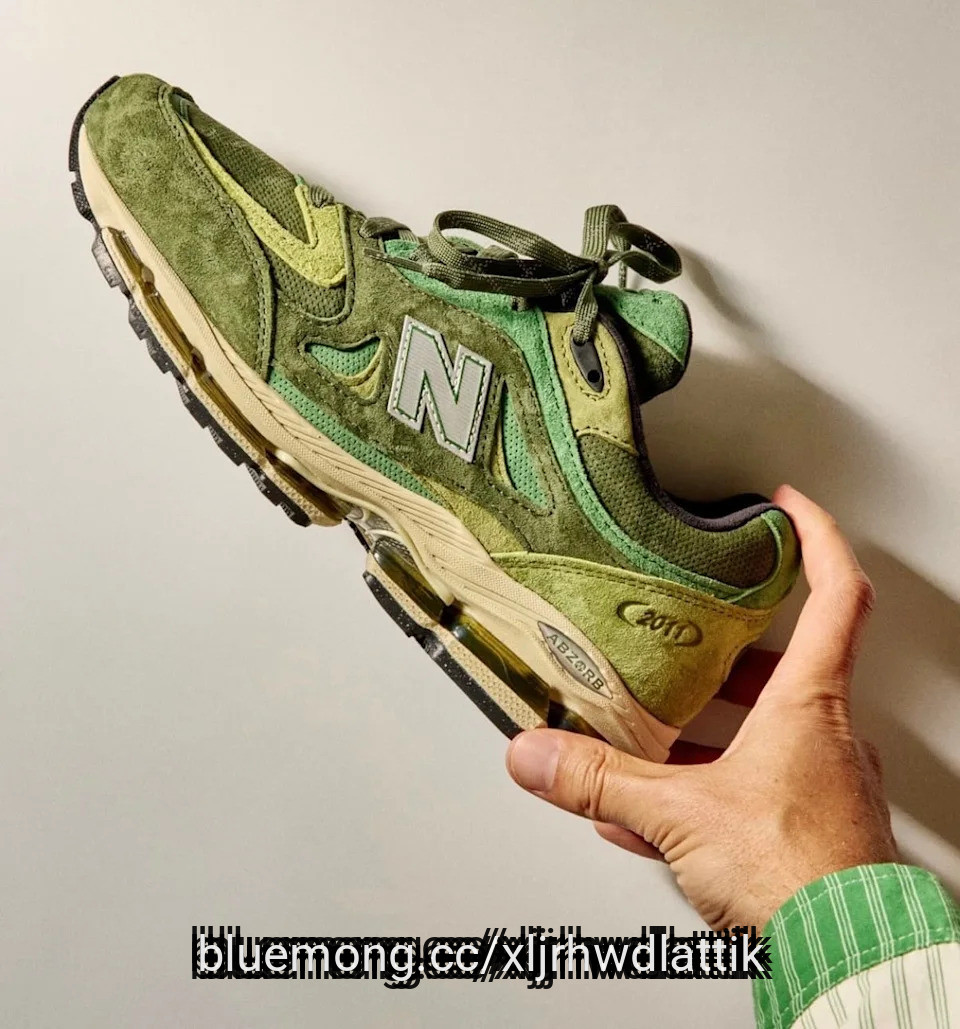
New Balance says its latest partnership with Edebiri makes for a natural fit given her upbringing in Boston, which is also where the brand's global headquarters is located. Edebiri's launch campaign captures her in her hometown of Dorchester while wearing the iconic New Balance 574.
"New Balance has always been part of the backdrop of my life growing up in Boston, so there was already a familiarity there. But as I learned more about the brand through conversations with the amazing team, the fit became about more than just the Boston connection," Edebiri said about joining New Balance. "I love how New Balance has such a clear sense of who they are, while still leaving room for self-expression and creativity, allowing people to make the brand their own. That balance of identity and individuality is something I value in both my personal style and my work, and is what makes this relationship feel like such a natural fit."
New Balance confirmed that Edebiri will appear in future campaigns and storytelling opportunities.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#brand #golden
New Balance says its latest partnership with Edebiri makes for a natural fit given her upbringing in Boston, which is also where the brand's global headquarters is located. Edebiri's launch campaign captures her in her hometown of Dorchester while wearing the iconic New Balance 574.
"New Balance has always been part of the backdrop of my life growing up in Boston, so there was already a familiarity there. But as I learned more about the brand through conversations with the amazing team, the fit became about more than just the Boston connection," Edebiri said about joining New Balance. "I love how New Balance has such a clear sense of who they are, while still leaving room for self-expression and creativity, allowing people to make the brand their own. That balance of identity and individuality is something I value in both my personal style and my work, and is what makes this relationship feel like such a natural fit."
New Balance confirmed that Edebiri will appear in future campaigns and storytelling opportunities.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#brand #golden

3 days ago
College football is unpredictable and delightful, which is why we live for what happens on Saturdays. And Week 2 absolutely delivered, from a stunner in Stillwater to an instant classic in Austin.
Each Sunday, I'll publish my biggest takeaways from the college football weekend. I'll highlight the most interesting storylines, track College Football Playoff contenders and specifically shout out individual and team performances that deserve the spotlight.
He beat one of college football's bluest bluebloods. I know he took the Longhorns to the semifinals of the College Football Playoff in back-to-back seasons, but we live in a what-have-you-done-for-me-lately world. And lately, Texas had been overhyped and under-delivering — with three losses to Georgia since joining the SEC, and two losses to Ohio State (in the CFP and last year's season-opener). After starting last year as the preseason No. 1 team, Texas didn't even make the CFP.
But Saturday was different, even after a first half that felt all too familiar. Arch Manning delivered with the game on the line. Hollywood Smothers showed the value of adding the transfer portal's best available running back. And Sarkisian got the kind of win that helps a head coach sleep at night. The kind of win that gives a team a nice cushion heading into conference play, knowing that its CFP resume has a pretty shiny centerpiece.
One note: Sark might want to work on his postgame interview etiquette.
#Football #playoff #texas #lately
Each Sunday, I'll publish my biggest takeaways from the college football weekend. I'll highlight the most interesting storylines, track College Football Playoff contenders and specifically shout out individual and team performances that deserve the spotlight.
He beat one of college football's bluest bluebloods. I know he took the Longhorns to the semifinals of the College Football Playoff in back-to-back seasons, but we live in a what-have-you-done-for-me-lately world. And lately, Texas had been overhyped and under-delivering — with three losses to Georgia since joining the SEC, and two losses to Ohio State (in the CFP and last year's season-opener). After starting last year as the preseason No. 1 team, Texas didn't even make the CFP.
But Saturday was different, even after a first half that felt all too familiar. Arch Manning delivered with the game on the line. Hollywood Smothers showed the value of adding the transfer portal's best available running back. And Sarkisian got the kind of win that helps a head coach sleep at night. The kind of win that gives a team a nice cushion heading into conference play, knowing that its CFP resume has a pretty shiny centerpiece.
One note: Sark might want to work on his postgame interview etiquette.
#Football #playoff #texas #lately


3 days ago
Rachel Barthelemy Marcon, President, Doors at Owens Corning (NYSE:OC), sold 900 shares of common stock on Aug. 28, 2026, according to a recent SEC Form 4 filing.
Metric
Value
Transaction value
$130,000
#president #doors #owens #form
Metric
Value
Transaction value
$130,000
#president #doors #owens #form



