

7 days ago
With a market cap of $19.5 billion, Best Buy Co., Inc. (BBY) is a leading technology retailer focused on enriching lives through technology by combining tech expertise with personalized customer service. The company serves customers through its online platform, stores, and in-home services, addressing a wide range of everyday technology needs.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known


10 days ago
Over the past few months, **** eX (SPCX) has hogged so much of the limelight that Elon Musk's "other" company, Tesla (TSLA), has slipped completely under the radar. Yet, the EV leader is looking to go back to the past to grow in the future.
An event scheduled for Oct. 1 is expected to provide a major glimpse into the second-generation Roadster—a car that the company sold between 2008 and 2012 and was the one that put it on the automobile map of the world. Described as the company's first production vehicle and built with a Lotus Elise Chassis, the Roadster offered things that no other electric vehicle did at that time. 0-60 mph in 39 seconds, had a top speed of 120 mph, and an initial range of 200+ miles, which eventually rose to 245.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #SpaceX #spcx #Tsla
An event scheduled for Oct. 1 is expected to provide a major glimpse into the second-generation Roadster—a car that the company sold between 2008 and 2012 and was the one that put it on the automobile map of the world. Described as the company's first production vehicle and built with a Lotus Elise Chassis, the Roadster offered things that no other electric vehicle did at that time. 0-60 mph in 39 seconds, had a top speed of 120 mph, and an initial range of 200+ miles, which eventually rose to 245.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #SpaceX #spcx #Tsla

13 days ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
17 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm

17 days ago
Newark, New Jersey-based Prudential Financial, Inc. (PRU) is a diversified global financial services company that helps individuals and institutions protect wealth, prepare for retirement and pursue long-term financial goals. Valued at a market cap of $41.2 billion, its businesses span life insurance, annuities, retirement solutions, group insurance and investment management through PGIM, its global ****** et-management arm.
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
23 days ago
Microsoft announced a new financial reporting structure on Wednesday, collapsing its three operating segments into two as artificial intelligence reshapes how the company organizes its business. The change takes effect in fiscal year 2027.
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents
The two new segments are Agents and Infra, and Devices and Consumer. Those three categories — Productivity and Business Processes, Intelligent Cloud, and More Personal Computing — dated to 2015, according to CNBC.
Agents and Infra will include Azure cloud infrastructure, Microsoft 365, GitHub, productivity and server licensing, industry solutions, and frontier and support services. Devices and Consumer will cover search and advertising, Xbox, Windows operating system licenses, and device sales. The restructuring brings Microsoft's advertising businesses together under one segment, the company said.
"There's no question AI represents a profound shift in both technology and business," Chairman and Chief Executive Officer Satya Nadella wrote in the presentation. "It is changing what we build and how we operate, and it is blurring the boundaries between our products and reshaping our business models."
As part of the changes, Microsoft will begin reporting quarterly Azure revenue figures — a disclosure it has not previously made. Under the new, narrower definition of Azure, which excludes GitHub cloud services, developer cloud services, the Security Copilot **** istant, and healthcare and life sciences cloud products, Azure revenue grew 42% to $29.42 billion in the June quarter. That compares with 43% growth under the old Azure and other cloud services metric. Azure represented roughly 33% of Microsoft's total revenue in that period.
#Services #agents

24 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Fund highlighted L3Harris Technologies, Inc. (NYSE:LHX). L3Harris Technologies, Inc. (NYSE:LHX) provides mission-critical solutions for government and commercial customers worldwide. On September 01, 2026, L3Harris Technologies, Inc. (NYSE:LHX) closed at $263.56 per share. Over the past month, L3Harris Technologies, Inc. (NYSE:LHX) declined 8.44%, and its shares lost 4.08% over the past 52 weeks. L3Harris Technologies, Inc. (NYSE:LHX) has a market capitalization of $48.76 billion.
Artisan Global Opportunities Fund stated the following regarding L3Harris Technologies, Inc. (NYSE:LHX) in its Q2 2026 investor letter:
"L3Harris Technologies, Inc. (NYSE:LHX) is a global aerospace and defense company that we believe remains well positioned to benefit from growing investment in next-generation missile defense, ****** e sensing and national security programs. Recent results exceeded expectations, with 15% organic growth driven by continued strength in its ****** e and mission systems and missile solutions segments. Order activity remained healthy, with backlog reaching $41 billion and international demand accelerating. Despite the solid operating performance, shares declined amid concerns over future competition and the potential implications for long-term market share. While strong bookings and accelerating revenue continue to support our long-term investment thesis, we began harvesting the position as we reallocated capital within the industrials sector."
#global #artisan #opportunities
In its second-quarter 2026 investor letter, Artisan Global Opportunities Fund highlighted L3Harris Technologies, Inc. (NYSE:LHX). L3Harris Technologies, Inc. (NYSE:LHX) provides mission-critical solutions for government and commercial customers worldwide. On September 01, 2026, L3Harris Technologies, Inc. (NYSE:LHX) closed at $263.56 per share. Over the past month, L3Harris Technologies, Inc. (NYSE:LHX) declined 8.44%, and its shares lost 4.08% over the past 52 weeks. L3Harris Technologies, Inc. (NYSE:LHX) has a market capitalization of $48.76 billion.
Artisan Global Opportunities Fund stated the following regarding L3Harris Technologies, Inc. (NYSE:LHX) in its Q2 2026 investor letter:
"L3Harris Technologies, Inc. (NYSE:LHX) is a global aerospace and defense company that we believe remains well positioned to benefit from growing investment in next-generation missile defense, ****** e sensing and national security programs. Recent results exceeded expectations, with 15% organic growth driven by continued strength in its ****** e and mission systems and missile solutions segments. Order activity remained healthy, with backlog reaching $41 billion and international demand accelerating. Despite the solid operating performance, shares declined amid concerns over future competition and the potential implications for long-term market share. While strong bookings and accelerating revenue continue to support our long-term investment thesis, we began harvesting the position as we reallocated capital within the industrials sector."
#global #artisan #opportunities


26 days ago
The Marzetti Company (NASDAQ:MZTI) is an interesting dividend story precisely because it is easy to overlook. Investors who knew it as Lancaster Colony may not immediately connect the new Marzetti name with a business that has increased its regular dividend for 63 consecutive years. The 2025 rebrand also means the company is now operating under a consumer-facing name that is much more closely **** ociated with its food brands. The latest fiscal-year results give both sides of the dividend argument something to work with.
Photo by Dan Dennis on Unsplash
The strongest argument is the track record. The Marzetti Company (NASDAQ:MZTI) increased its regular cash dividend for the 63rd consecutive year in fiscal 2026. The latest quarterly dividend was $1.00 per share, compared with $0.95 in the year-ago quarter, while the fiscal-year dividend was $3.95 per share, up from $3.75. That puts Marzetti among an unusually small group of companies with such a long record of consecutive dividend increases.
That history matters because the company has maintained the streak through very different economic environments. The dividend is not simply the result of a recent management commitment; it is part of a capital-allocation culture that has been maintained for decades. Fiscal 2026 operating cash flow reached a record $283.8 million, up $22.3 million from the prior year. The company paid $108.8 million in dividends during the year. On those figures, the dividend consumed roughly 38% of operating cash flow, leaving substantial cash generation after the dividend.
That is one of the more encouraging aspects of the latest results. The dividend is not being funded by accounting earnings alone. The Marzetti Company (NASDAQ:MZTI) is generating considerably more operating cash than it is distributing to shareholders. The company's earnings performance also improved. Fiscal 2026 net income was $191.6 million, or $6.98 per diluted share, compared with $167.3 million, or $6.07 per diluted share, in fiscal 2025. Adjusted diluted EPS was $6.83, compared with $6.72 a year earlier.
#year #million #operating
Photo by Dan Dennis on Unsplash
The strongest argument is the track record. The Marzetti Company (NASDAQ:MZTI) increased its regular cash dividend for the 63rd consecutive year in fiscal 2026. The latest quarterly dividend was $1.00 per share, compared with $0.95 in the year-ago quarter, while the fiscal-year dividend was $3.95 per share, up from $3.75. That puts Marzetti among an unusually small group of companies with such a long record of consecutive dividend increases.
That history matters because the company has maintained the streak through very different economic environments. The dividend is not simply the result of a recent management commitment; it is part of a capital-allocation culture that has been maintained for decades. Fiscal 2026 operating cash flow reached a record $283.8 million, up $22.3 million from the prior year. The company paid $108.8 million in dividends during the year. On those figures, the dividend consumed roughly 38% of operating cash flow, leaving substantial cash generation after the dividend.
That is one of the more encouraging aspects of the latest results. The dividend is not being funded by accounting earnings alone. The Marzetti Company (NASDAQ:MZTI) is generating considerably more operating cash than it is distributing to shareholders. The company's earnings performance also improved. Fiscal 2026 net income was $191.6 million, or $6.98 per diluted share, compared with $167.3 million, or $6.07 per diluted share, in fiscal 2025. Adjusted diluted EPS was $6.83, compared with $6.72 a year earlier.
#year #million #operating

1 month ago
By
Updated Aug. 26, 2026 5:23 pm ET
Listen
(1 min)
Salesforce CRM 22.58%
increase; up pointing triangle
posted higher second-quarter profit and revenue on rising demand for its artificial-intelligence and data offerings, and also expanded its partnership with the AI company Anthropic.
#listen #salesforce #increase #higher
Updated Aug. 26, 2026 5:23 pm ET
Listen
(1 min)
Salesforce CRM 22.58%
increase; up pointing triangle
posted higher second-quarter profit and revenue on rising demand for its artificial-intelligence and data offerings, and also expanded its partnership with the AI company Anthropic.
#listen #salesforce #increase #higher

1 month ago
Merck & Co., Inc. (NYSE:MRK) jumped 12.6% to a record $152.20 on August 19 after a pivotal melanoma trial validated intismeran autogene, the individualized mRNA cancer therapy developed with Moderna. In the 1,137-patient Phase 3 INTerpath-001 study, intismeran plus Keytruda produced statistically significant and clinically meaningful improvements in recurrence-free survival and distant-metastasis-free survival compared with Keytruda alone. No new safety concerns emerged. Investors are now asking whether intismeran can turn Keytruda from a drug approaching a patent cliff into the foundation of a personalized-cancer platform.
That distinction matters because Merck & Co., Inc. (NYSE:MRK) generated $31.68 billion from Keytruda and Keytruda Qlex in 2025, nearly half of the company's sales. In the U.S., biosimilar competition could begin after Keytruda's primary compound patent expires in December 2028, although biosimilars have already entered some smaller international markets. A successful combination could support continued use of the franchise without removing the need for other growth engines.
The bullish case for Merck & Co., Inc. (NYSE:MRK) is that intismeran adds a personalized immune response to a checkpoint inhibitor already embedded across oncology. The treatment is designed from the unique mutations in each patient's tumor and encodes as many as 34 neoantigens, training the immune system to recognize tumor cells while Keytruda removes a brake on the immune response.
Earlier Phase 2b data showed a 49% reduction in the risk of recurrence or death and a 59% reduction in distant metastasis or death at five years. Phase 3 confirmation makes the approach more credible for Merck & Co., Inc. (NYSE:MRK) beyond melanoma. The company is also studying intismeran combinations in non-small cell lung, bladder and renal-cell cancers. Success across several tumor types could create a portfolio of Keytruda combinations rather than a single indication.
That would give Merck & Co., Inc. (NYSE:MRK) another lifecycle-management tool alongside Keytruda Qlex and newer oncology ***** ets. It also strengthens the argument that Keytruda can remain commercially relevant after standalone pembrolizumab faces lower-priced competition.
#NYSE #tumor #cancer
That distinction matters because Merck & Co., Inc. (NYSE:MRK) generated $31.68 billion from Keytruda and Keytruda Qlex in 2025, nearly half of the company's sales. In the U.S., biosimilar competition could begin after Keytruda's primary compound patent expires in December 2028, although biosimilars have already entered some smaller international markets. A successful combination could support continued use of the franchise without removing the need for other growth engines.
The bullish case for Merck & Co., Inc. (NYSE:MRK) is that intismeran adds a personalized immune response to a checkpoint inhibitor already embedded across oncology. The treatment is designed from the unique mutations in each patient's tumor and encodes as many as 34 neoantigens, training the immune system to recognize tumor cells while Keytruda removes a brake on the immune response.
Earlier Phase 2b data showed a 49% reduction in the risk of recurrence or death and a 59% reduction in distant metastasis or death at five years. Phase 3 confirmation makes the approach more credible for Merck & Co., Inc. (NYSE:MRK) beyond melanoma. The company is also studying intismeran combinations in non-small cell lung, bladder and renal-cell cancers. Success across several tumor types could create a portfolio of Keytruda combinations rather than a single indication.
That would give Merck & Co., Inc. (NYSE:MRK) another lifecycle-management tool alongside Keytruda Qlex and newer oncology ***** ets. It also strengthens the argument that Keytruda can remain commercially relevant after standalone pembrolizumab faces lower-priced competition.
#NYSE #tumor #cancer
1 month ago
Last year was a busy one for Mark Walter. Not only did he buy a majority ownership in the Los Angeles Lakers, he also became the subject of a federal investigation into whether his companies, including several insurance firms, properly characterized billions of dollars in ****** ets.
A year later, he announced plans to sell his stake in the Lakers, but the investigation continues — and is raising questions about the investment strategies of the insurance industry as a whole.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#last #mark #jeff #bezos
A year later, he announced plans to sell his stake in the Lakers, but the investigation continues — and is raising questions about the investment strategies of the insurance industry as a whole.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#last #mark #jeff #bezos

1 month ago
It's a quiet but important week on the earnings front this week, with some key technology names set to report. This week we have Nvidia (NVDA), Marvell Technology (MRVL), Crowdstrike Holdings (CRWD) and Salesforce (CRM) all set to report.
Before a company reports earnings, implied volatility is usually high because the market is unsure about the outcome of the report. Speculators and hedgers create huge demand for the company's options which increases the implied volatility, and therefore, the price of options.
Nvidia Stock Is Treading Water Ahead of Earnings This Week - What's the Best NVDA Play?
Why the China-Led Weakness in NXP Semiconductors Stock Could Open Doors for Speculators
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market **** ysis you won't find anywhere else.
#earnings #report #NVIDIA #technology
Before a company reports earnings, implied volatility is usually high because the market is unsure about the outcome of the report. Speculators and hedgers create huge demand for the company's options which increases the implied volatility, and therefore, the price of options.
Nvidia Stock Is Treading Water Ahead of Earnings This Week - What's the Best NVDA Play?
Why the China-Led Weakness in NXP Semiconductors Stock Could Open Doors for Speculators
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market **** ysis you won't find anywhere else.
#earnings #report #NVIDIA #technology

1 month ago
Milestones are usually meant to be celebrated, but this achievement isn't necessarily a positive development. The U.S. government's debt balance has officially exceeded $40 trillion. This massive sum is equal to 124% of the country's gross domestic product (GDP), up from a 62% share in 2006.
What's more, the federal debt burden has more than doubled in a decade. Compared to 20 years ago, it has exploded 376% higher. Within the U.S. budget, more money goes to interest payments now than it does to anything else, except Social Security and Medicare.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's what history says all of this borrowing means for the stock market. Investors will want to pay attention.
When President Donald Trump began his second term, he immediately set up the Department of Government Efficiency. This agency, headed by Elon Musk, was tasked with cutting spending and reducing the deficit. But by any measure, it was a complete failure. Even the world's most prominent tech visionary couldn't make a tiny dent in fixing the country's finances.
#signal #debt #years #milestones
What's more, the federal debt burden has more than doubled in a decade. Compared to 20 years ago, it has exploded 376% higher. Within the U.S. budget, more money goes to interest payments now than it does to anything else, except Social Security and Medicare.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's what history says all of this borrowing means for the stock market. Investors will want to pay attention.
When President Donald Trump began his second term, he immediately set up the Department of Government Efficiency. This agency, headed by Elon Musk, was tasked with cutting spending and reducing the deficit. But by any measure, it was a complete failure. Even the world's most prominent tech visionary couldn't make a tiny dent in fixing the country's finances.
#signal #debt #years #milestones

1 month ago
On August 17, Nvidia (NASDAQ:NVDA) agreed to guarantee up to $105 billion to help OpenAI lease a massive data center in Pike County, Ohio, being developed by SoftBank-owned SB Energy. The site could reach 8 gigawatts of capacity, with the first 800 megawatts due online in 2028, and OpenAI has signed on for 20 years. Nvidia will also put $1.5 billion directly into SB Energy and will be the facility's exclusive chip supplier. It's the latest example of the company financing the very infrastructure that runs its own chips, a habit that keeps expanding even as it keeps drawing scrutiny.
The idea behind the guarantee is that Nvidia is using its balance sheet to lock up long-lived sites where its chips can run across multiple hardware generations, and the numbers behind that bet keep climbing. Revenue growth is expected to accelerate toward 97% this quarter, up from 85% the quarter before, as the company rolls out its new Rubin platform. Jensen Huang has floated $1 trillion in combined revenue across 2026 and 2027, which implies roughly $600 billion in fiscal 2028 alone. Demand isn't limited to hyperscalers, either.
SpaceX has said it will build its AI infrastructure exclusively on Nvidia chips, targeting 10 gigawatts of compute by the end of 2027, a build-out estimated to cost $150 billion to $250 billion. Add in the four largest hyperscalers, expected to spend roughly $700 billion on AI chips this year, plus a possible OpenAI or Anthropic IPO that could free up even more capital, and the picture is a company still early in monetizing an entire computing shift. The Ohio guarantee, paired with the $500 billion financing consortium Nvidia formed with six major financial institutions the week before, fits that same playbook: widen the pool of customers locked into its hardware so no single client's slowdown can shake the business.
The obvious pushback is circularity. Nvidia is effectively helping fund a customer's ability to buy Nvidia chips, first through the $500 billion consortium with BlackRock, Blackstone, KKR, Apollo, Brookfield and Goldman Sachs, and now through a direct guarantee tied to OpenAI's Ohio lease. Huang insists this isn't circular financing, but the plan to securitize AI infrastructure into a tradable ******* et class invites comparisons to how mortgage pools were packaged before 2008. Nvidia's exposure here isn't unlimited. It covers a portion of lease and power payments and a minimum-value commitment on the site, not the full $105 billion or all of OpenAI's obligations. But if OpenAI defaults, Nvidia still absorbs the difference between that floor value and whatever the site fetches if it's re-leased or sold.
#openai
The idea behind the guarantee is that Nvidia is using its balance sheet to lock up long-lived sites where its chips can run across multiple hardware generations, and the numbers behind that bet keep climbing. Revenue growth is expected to accelerate toward 97% this quarter, up from 85% the quarter before, as the company rolls out its new Rubin platform. Jensen Huang has floated $1 trillion in combined revenue across 2026 and 2027, which implies roughly $600 billion in fiscal 2028 alone. Demand isn't limited to hyperscalers, either.
SpaceX has said it will build its AI infrastructure exclusively on Nvidia chips, targeting 10 gigawatts of compute by the end of 2027, a build-out estimated to cost $150 billion to $250 billion. Add in the four largest hyperscalers, expected to spend roughly $700 billion on AI chips this year, plus a possible OpenAI or Anthropic IPO that could free up even more capital, and the picture is a company still early in monetizing an entire computing shift. The Ohio guarantee, paired with the $500 billion financing consortium Nvidia formed with six major financial institutions the week before, fits that same playbook: widen the pool of customers locked into its hardware so no single client's slowdown can shake the business.
The obvious pushback is circularity. Nvidia is effectively helping fund a customer's ability to buy Nvidia chips, first through the $500 billion consortium with BlackRock, Blackstone, KKR, Apollo, Brookfield and Goldman Sachs, and now through a direct guarantee tied to OpenAI's Ohio lease. Huang insists this isn't circular financing, but the plan to securitize AI infrastructure into a tradable ******* et class invites comparisons to how mortgage pools were packaged before 2008. Nvidia's exposure here isn't unlimited. It covers a portion of lease and power payments and a minimum-value commitment on the site, not the full $105 billion or all of OpenAI's obligations. But if OpenAI defaults, Nvidia still absorbs the difference between that floor value and whatever the site fetches if it's re-leased or sold.
#openai

1 month ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by a successful transition to a four-season brand, with closed-toe penetration increasing 500 basis points as management expands usage occasions beyond traditional sandals.
Direct-to-Consumer (DTC) growth of 16% outpaced wholesale for the first time in two years, fueled by a 50% increase in own retail revenue and high single-digit same-store sales.
Management attributed the 23% constant currency growth in APAC to high-quality, premium positioning, specifically noting that China grew over 50% and now represents the company's highest Average Selling Price (ASP) market.
Strategic scarcity and disciplined distribution maintained a 93% full-price realization in EMEA despite a broader market environment characterized by heavy promotional activity.
#high
Performance was driven by a successful transition to a four-season brand, with closed-toe penetration increasing 500 basis points as management expands usage occasions beyond traditional sandals.
Direct-to-Consumer (DTC) growth of 16% outpaced wholesale for the first time in two years, fueled by a 50% increase in own retail revenue and high single-digit same-store sales.
Management attributed the 23% constant currency growth in APAC to high-quality, premium positioning, specifically noting that China grew over 50% and now represents the company's highest Average Selling Price (ASP) market.
Strategic scarcity and disciplined distribution maintained a 93% full-price realization in EMEA despite a broader market environment characterized by heavy promotional activity.
#high
1 month ago
Timothy J. McGrath, President & CEO of PC Connection(NASDAQ:CNXN), sold 50,000 shares of common stock at $85.88 per share in transactions completed on Aug. 3 and Aug. 4, 2026. SEC Form 4 filing
Metric
Value
Shares sold (directly held)
50,000
#connection #cnxn
Metric
Value
Shares sold (directly held)
50,000
#connection #cnxn

2 months ago
Nebius Group (NBIS) stock has witnessed a strong rally of 175% in the last 12 months. This rally has been backed by stellar top-line growth, a swelling contracted backlog, industry tailwinds, and EBITDA-level profitability in the most recent quarter.
Amidst the bullish momentum, there are two points worth noting. First, NBIS stock had touched all-time highs of $299.9 in June 2026. From those levels, there has been a correction of 37%.
Don't **** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#nbis #rally #nebius
Amidst the bullish momentum, there are two points worth noting. First, NBIS stock had touched all-time highs of $299.9 in June 2026. From those levels, there has been a correction of 37%.
Don't **** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#nbis #rally #nebius


2 months ago
D.R. Horton, Inc. (DHI) operates as a homebuilding company. Valued at $42.3 billion by market cap, the company constructs and sells single-family homes designed primarily for the entry-level and move-up markets. DHI also provides mortgage financing and ***** le agency services to homebuyers.
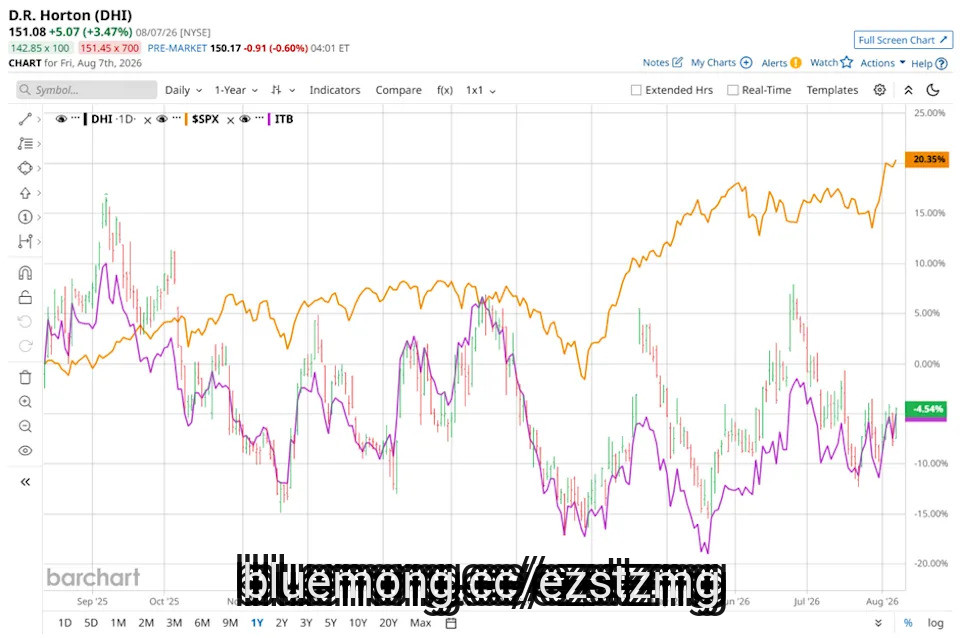
Shares of this leading homebuilder have underperformed the broader market over the past year. DHI has declined 1.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 22.4%. In 2026, DHI stock is up 4.9%, compared to the SPX's 13.3% rise on a YTD basis.
Don't ***** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#market #broader #micron
Shares of this leading homebuilder have underperformed the broader market over the past year. DHI has declined 1.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 22.4%. In 2026, DHI stock is up 4.9%, compared to the SPX's 13.3% rise on a YTD basis.
Don't ***** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#market #broader #micron


2 months ago
By Heard on the Street Staff
Aug. 7, 2026 4:33 pm ET
Listen
(2 min)
This is an edition of the Markets P.M. newsletter, a recap of the day’s most important markets moves, delivered after the closing bell. If you’re not subscribed, sign up here.
#edition #recap #important
Aug. 7, 2026 4:33 pm ET
Listen
(2 min)
This is an edition of the Markets P.M. newsletter, a recap of the day’s most important markets moves, delivered after the closing bell. If you’re not subscribed, sign up here.
#edition #recap #important


2 months ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
From the Great Resignation to quiet quitting, there's been no shortage of trends over the past few years that reflect growing dissatisfaction and disengagement in the workplace.
The newest trend, "quiet cracking," coined by TalentLMS, describes ongoing burnout and stagnation that leads to worker disengagement and poor performance. Their research shows 20% of employees experience it frequently, and 34% occasionally (1).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan still sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Learn more with a free guide from Priority Gold
#jeff
From the Great Resignation to quiet quitting, there's been no shortage of trends over the past few years that reflect growing dissatisfaction and disengagement in the workplace.
The newest trend, "quiet cracking," coined by TalentLMS, describes ongoing burnout and stagnation that leads to worker disengagement and poor performance. Their research shows 20% of employees experience it frequently, and 34% occasionally (1).
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan still sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Learn more with a free guide from Priority Gold
#jeff

2 months ago
Agilent Technologies Inc. (NYSE:A) just extended its diagnostics franchise into one of oncology's toughest corners. On July 23, the company said European regulators had certified its PD-L1 IHC 22C3 pharmDx test, Code SK006, as a companion diagnostic for epithelial ovarian, fallopian tube, and primary peritoneal carcinoma. That lets pathologists flag patients who might benefit from Merck's Keytruda. It is a narrow, technical-sounding approval, but it adds up to something bigger: Agilent's diagnostics business keeps racking up new indications while competitors scramble to keep pace.
Bull Case: A Diagnostics Machine That Keeps Adding Indications
This is now the eighth CE-marked indication for the 22C3 pharmDx ****** ay in the EU, following FDA approval of a related PD-L1 test (28-8 pharmDx) for esophageal and gastric cancers just nine days earlier. Each new label doesn't require Agilent to build a new product; it just extends the reach of an ****** ay already running in labs worldwide, which is a high-margin way to grow. Agilent has also been adding inorganically, closing its acquisition of Biocare Medical in June to deepen its clinical pathology reach, the same market where this new ovarian cancer approval lives. Together, the pipeline of regulatory wins and the acquisition strategy point to a company compounding its diagnostics footprint one label at a time rather than swinging for one blockbuster product.
Bear Case: A Crowded Diagnostics Field With A Scarier Neighbor
Companion diagnostics is not Agilent's alone to win. Danaher Corporation (NYSE:DHR), through its Leica Biosystems unit, competes directly for the same pathology lab budgets and just agreed on July 14 to acquire StatLab Medical Products to strengthen its own histology and AI-pathology pipeline. Danaher's own stock cratered 14% on July 21 after it trimmed its core revenue growth outlook, even though it beat on earnings and raised its profit forecast.
#pharmdx #pathology
Bull Case: A Diagnostics Machine That Keeps Adding Indications
This is now the eighth CE-marked indication for the 22C3 pharmDx ****** ay in the EU, following FDA approval of a related PD-L1 test (28-8 pharmDx) for esophageal and gastric cancers just nine days earlier. Each new label doesn't require Agilent to build a new product; it just extends the reach of an ****** ay already running in labs worldwide, which is a high-margin way to grow. Agilent has also been adding inorganically, closing its acquisition of Biocare Medical in June to deepen its clinical pathology reach, the same market where this new ovarian cancer approval lives. Together, the pipeline of regulatory wins and the acquisition strategy point to a company compounding its diagnostics footprint one label at a time rather than swinging for one blockbuster product.
Bear Case: A Crowded Diagnostics Field With A Scarier Neighbor
Companion diagnostics is not Agilent's alone to win. Danaher Corporation (NYSE:DHR), through its Leica Biosystems unit, competes directly for the same pathology lab budgets and just agreed on July 14 to acquire StatLab Medical Products to strengthen its own histology and AI-pathology pipeline. Danaher's own stock cratered 14% on July 21 after it trimmed its core revenue growth outlook, even though it beat on earnings and raised its profit forecast.
#pharmdx #pathology

2 months ago
Harris Oakmark recently released its second-quarter 2026 investor letter for the "Oakmark U.S. Concentrated Strategy". A copy of the letter can be downloaded here. The strategy returned 9.21% (net) in the second quarter, lagging the Russell 1000 Value Index's 13.87%. U.S. equities finished higher during the quarter, with nine of eleven GICS sectors posting gains, led by technology and industrials, while energy and utilities detracted. The market showed concentrated leadership, with investors favoring companies that benefit from AI spending. However, the firm continues to focus on value discipline, avoiding AI-driven market fads, prioritizing companies trading below intrinsic value. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Oakmark U.S. Concentrated Strategy highlighted Keurig Dr Pepper Inc. (NASDAQ:KDP) as a notable performance contributor. Keurig Dr Pepper Inc. (NASDAQ:KDP) owns and distributes beverages and single serve brewing systems. On July 28, 2026, Keurig Dr Pepper Inc. (NASDAQ:KDP) closed at $31.08 per share, reflecting a market capitalization of $42.29 billion. Keurig Dr Pepper Inc. (NASDAQ:KDP) posted a one-month return of -6.86%, while its shares lost 8.10% over the past 52 weeks.
Oakmark U.S. Concentrated Strategy stated the following regarding Keurig Dr Pepper Inc. (NASDAQ:KDP) in its Q2 2026 investor update:
"Keurig Dr Pepper Inc. (NASDAQ:KDP) was a contributor during the quarter. The U.S.-headquartered beverage company's stock rose after better-than-expected first-quarter results, a reaffirmed outlook, and a Barclays rating upgrade. Sales were strong, led by the cold beverage portfolio and the U.S. Refreshment Beverages segment, while U.S. Coffee remained pressured but met expectations. Management continues to make pro gress on its JDE Peet's integration. We met with management to discuss the departure of Rafa Oliveira, head of its coffee unit, who is leaving for the CEO role at Heineken; the company has begun searching for his replacement. We continue to believe strong execution and integra tion will help close the valuation gap relative to peers."
Keurig Dr Pepper Inc. (NASDAQ:KDP) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 43 hedge fund portfolios held Keurig Dr Pepper Inc. (NASDAQ:KDP) at the end of the first quarter, up from 41 in the previous quarter. While we acknowledge the risk and potential of Keurig Dr Pepper Inc. (NASDAQ:KDP) as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than Keurig Dr Pepper Inc. (NASDAQ:KDP) and that has 10,000% upside potential, check out our report about this cheapest AI stock.
#pepper #strategy
In its Q2 2026 investor letter, Oakmark U.S. Concentrated Strategy highlighted Keurig Dr Pepper Inc. (NASDAQ:KDP) as a notable performance contributor. Keurig Dr Pepper Inc. (NASDAQ:KDP) owns and distributes beverages and single serve brewing systems. On July 28, 2026, Keurig Dr Pepper Inc. (NASDAQ:KDP) closed at $31.08 per share, reflecting a market capitalization of $42.29 billion. Keurig Dr Pepper Inc. (NASDAQ:KDP) posted a one-month return of -6.86%, while its shares lost 8.10% over the past 52 weeks.
Oakmark U.S. Concentrated Strategy stated the following regarding Keurig Dr Pepper Inc. (NASDAQ:KDP) in its Q2 2026 investor update:
"Keurig Dr Pepper Inc. (NASDAQ:KDP) was a contributor during the quarter. The U.S.-headquartered beverage company's stock rose after better-than-expected first-quarter results, a reaffirmed outlook, and a Barclays rating upgrade. Sales were strong, led by the cold beverage portfolio and the U.S. Refreshment Beverages segment, while U.S. Coffee remained pressured but met expectations. Management continues to make pro gress on its JDE Peet's integration. We met with management to discuss the departure of Rafa Oliveira, head of its coffee unit, who is leaving for the CEO role at Heineken; the company has begun searching for his replacement. We continue to believe strong execution and integra tion will help close the valuation gap relative to peers."
Keurig Dr Pepper Inc. (NASDAQ:KDP) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 43 hedge fund portfolios held Keurig Dr Pepper Inc. (NASDAQ:KDP) at the end of the first quarter, up from 41 in the previous quarter. While we acknowledge the risk and potential of Keurig Dr Pepper Inc. (NASDAQ:KDP) as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than Keurig Dr Pepper Inc. (NASDAQ:KDP) and that has 10,000% upside potential, check out our report about this cheapest AI stock.
#pepper #strategy

2 months ago
Billionaire David Tepper made the bulk of his fortune investing on Wall Street, so it's understandable that people would peek into his hedge fund's holdings to get a look at where he's placing his bets. As of the first quarter (Q1), Tepper's hedge fund, Appaloosa Management, had $5.93 billion in ******* ets under management, with a surprising amount of that coming from a little-known energy company.
Vistra (NYSE: VST) was 5.12% of Appaloosa's portfolio, its seventh-largest holding. The six above it are Amazon, Micron, Alphabet, Uber, Taiwan Semiconductor Manufacturing, and Alibaba, all of which fall into the tech bucket.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So, why are Tepper and Appaloosa so high on Vistra? Let's take a look.
Vistra is an energy company that makes money in two main ways. The first is through retail, supplying power to around 5 million residential, commercial, and industrial customers.
#vistra #tepper
Vistra (NYSE: VST) was 5.12% of Appaloosa's portfolio, its seventh-largest holding. The six above it are Amazon, Micron, Alphabet, Uber, Taiwan Semiconductor Manufacturing, and Alibaba, all of which fall into the tech bucket.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So, why are Tepper and Appaloosa so high on Vistra? Let's take a look.
Vistra is an energy company that makes money in two main ways. The first is through retail, supplying power to around 5 million residential, commercial, and industrial customers.
#vistra #tepper

2 months ago
Starbucks CEO Brian Niccol built his reputation at Chipotle Mexican Grill by following one formula: fix operations, rebuild customer traffic, and wait for margins to follow.
That playbook produced a stock return of more than 770% during a six-year tenure that more than doubled annual revenue and saw restaurant-level margins climb from about 19% to nearly 29%, Chipotle's quarterly results showed.
Less than two years into his role at Starbucks (SBUX), the early data suggest the same recovery pattern is emerging across the chain's U.S. locations.
Customer visits are rising, same-store sales have accelerated for three consecutive quarters, and the company recently raised its full-year earnings outlook.
The stock sits near a 52-week high, however, and the market has priced in a completed turnaround that hasn't reached the income statement yet.
#brian #chipotle
That playbook produced a stock return of more than 770% during a six-year tenure that more than doubled annual revenue and saw restaurant-level margins climb from about 19% to nearly 29%, Chipotle's quarterly results showed.
Less than two years into his role at Starbucks (SBUX), the early data suggest the same recovery pattern is emerging across the chain's U.S. locations.
Customer visits are rising, same-store sales have accelerated for three consecutive quarters, and the company recently raised its full-year earnings outlook.
The stock sits near a 52-week high, however, and the market has priced in a completed turnaround that hasn't reached the income statement yet.
#brian #chipotle

2 months ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Jefferies upgraded Verisk ****** ytics (VRSK) to Buy from Hold with a price target of $235, up from $192. Verisk's Q1 report "likely marks a trough," with its organic growth improving to 5% year-over-year in Q2, and accelerating further in the second half of 2026, the firm tells investors in a research note.
Morgan Stanley upgraded PayPay (PAYP) to Overweight from Equal Weight with a price target of $23, down from $24. The firm says that while the company's near-term catalysts remain limited, the stock's risk/reward suggests the upside potential outweighs downside risk.
Wolfe Research upgraded AT&T (T) to Outperform from Peer Perform with a $29 price target. The company's Q2 brought "stable and better than expected" unit economics, the firm tells investors in a research note.
KeyBanc upgraded Ameren (AEE) to Overweight from Sector Weight with a $122 price target. The firm believes increasing visibility around incremental load growth could position Ameren for a "meaningful earnings growth revision as early as this fall."
#Research #price #investors #Growth
Top 5 Upgrades:
Jefferies upgraded Verisk ****** ytics (VRSK) to Buy from Hold with a price target of $235, up from $192. Verisk's Q1 report "likely marks a trough," with its organic growth improving to 5% year-over-year in Q2, and accelerating further in the second half of 2026, the firm tells investors in a research note.
Morgan Stanley upgraded PayPay (PAYP) to Overweight from Equal Weight with a price target of $23, down from $24. The firm says that while the company's near-term catalysts remain limited, the stock's risk/reward suggests the upside potential outweighs downside risk.
Wolfe Research upgraded AT&T (T) to Outperform from Peer Perform with a $29 price target. The company's Q2 brought "stable and better than expected" unit economics, the firm tells investors in a research note.
KeyBanc upgraded Ameren (AEE) to Overweight from Sector Weight with a $122 price target. The firm believes increasing visibility around incremental load growth could position Ameren for a "meaningful earnings growth revision as early as this fall."
#Research #price #investors #Growth

2 months ago
Tesla (TSLA) is due to report earnings after the market close today and the market is pricing in a 5.9% move in either direction.
Implied volatility is 48.74% which gives TSLA an IV Percentile of 73% and an IV Rank of 37.53%.
Walmart Stock's Extended Downturn Could Trigger a Possible Comeback
Bloom Energy Stock Is Very Risky, But This Speculative Trade on BE Is Tantalizing Here
CRWD Short Strangle Could Net $1,045 in a Few Weeks
#rank #walmart #extended #trigger
Implied volatility is 48.74% which gives TSLA an IV Percentile of 73% and an IV Rank of 37.53%.
Walmart Stock's Extended Downturn Could Trigger a Possible Comeback
Bloom Energy Stock Is Very Risky, But This Speculative Trade on BE Is Tantalizing Here
CRWD Short Strangle Could Net $1,045 in a Few Weeks
#rank #walmart #extended #trigger


2 months ago
You can find original article here Nrn. Subscribe to our free daily Nrn newsletters.
Nearly 12 months after backlash to a new logo tanked its sales, Cracker Barrel is on a roll.
In an update Monday, the family-dining chain said same-store restaurant sales were down 2.5% year over year through the first 11 weeks of the current quarter, while same-store retail sales were up 0.5%.
That continues the chain's momentum from the previous quarter, when same-store restaurant and retail sales were down 2.6% and 1.8%, respectively.
The company said it now expects to either meet or exceed the high end of its revenue and earnings guidance for the fiscal year, which runs through this month. That indicates it will generate at least $3.3 billion in revenue and $125 million in earnings before interest, taxes, depreciation, and amortization (EBITDA) for the fiscal year.
#year
Nearly 12 months after backlash to a new logo tanked its sales, Cracker Barrel is on a roll.
In an update Monday, the family-dining chain said same-store restaurant sales were down 2.5% year over year through the first 11 weeks of the current quarter, while same-store retail sales were up 0.5%.
That continues the chain's momentum from the previous quarter, when same-store restaurant and retail sales were down 2.6% and 1.8%, respectively.
The company said it now expects to either meet or exceed the high end of its revenue and earnings guidance for the fiscal year, which runs through this month. That indicates it will generate at least $3.3 billion in revenue and $125 million in earnings before interest, taxes, depreciation, and amortization (EBITDA) for the fiscal year.
#year

2 months ago
Deep Sail Capital Partners, an investment management company, released its first-quarter 2026 investor letter. A copy of the letter can be downloaded here. In the second quarter, the fund significantly outperformed both of its benchmarks, the Russell 2000 Mid Cap Growth Index and the Russell 2000 Index, returning 41.6% net of fees while averaging 88% net long exposure. YTD, the fund returned 16.5% net of fees. long portfolio significantly outperformed both benchmarks, while the short portfolio was mixed in the quarter. The letter states that there was a notable performance push in Q1, which was reflected in Q2, driven by both the Iran War and idiosyncratic impacts on positions in the fund. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Deep Sail Capital Partners highlighted AmpliTech Group, Inc. (NASDAQ:AMPG). AmpliTech Group, Inc. (NASDAQ:AMPG) is a technology company that focuses on the design, engineering, and ****** embly of microwave component-based amplifiers and systems. On July 21, 2026, AmpliTech Group, Inc. (NASDAQ:AMPG) closed at $6.09 per share. One-month return of AmpliTech Group, Inc. (NASDAQ:AMPG) was -13.86%, and its shares gained 126.39% over the past 52 weeks. AmpliTech Group, Inc. (NASDAQ:AMPG) has a market capitalization of $154.31 million.
Deep Sail Capital Partners stated the following regarding AmpliTech Group, Inc. (NASDAQ:AMPG) in its Q2 2026 investor update:
"There were a few large detractors at the end of the Q1 that have reversed in Q2 including our two biggest contributors in Q2 Credo Technology and AmpliTech Group, Inc. (NASDAQ:AMPG). Amplitech (which I shared my long thesis in the fund's Q1 investment letter) returned even more in Q2 at 266% driven on a narrative pushed by retail investors that Amazon has become a client and that their devices will be used in future satellite launches. The fund exited the position in May with a return of 166% because we believe this narrative is incorrect and the stock had reached our valuation target of $6. I had no idea Amplitech would get caught up in this retail bubble, but I'll take the win and move on."
AmpliTech Group, Inc. (NASDAQ:AMPG) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 5 hedge fund portfolios held AmpliTech Group, Inc. (NASDAQ:AMPG) at the end of the first quarter, compared to 7 in the previous quarter. While we acknowledge the potential of AmpliTech Group, Inc. (NASDAQ:AMPG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #deep #sail #capital
In its Q2 2026 investor letter, Deep Sail Capital Partners highlighted AmpliTech Group, Inc. (NASDAQ:AMPG). AmpliTech Group, Inc. (NASDAQ:AMPG) is a technology company that focuses on the design, engineering, and ****** embly of microwave component-based amplifiers and systems. On July 21, 2026, AmpliTech Group, Inc. (NASDAQ:AMPG) closed at $6.09 per share. One-month return of AmpliTech Group, Inc. (NASDAQ:AMPG) was -13.86%, and its shares gained 126.39% over the past 52 weeks. AmpliTech Group, Inc. (NASDAQ:AMPG) has a market capitalization of $154.31 million.
Deep Sail Capital Partners stated the following regarding AmpliTech Group, Inc. (NASDAQ:AMPG) in its Q2 2026 investor update:
"There were a few large detractors at the end of the Q1 that have reversed in Q2 including our two biggest contributors in Q2 Credo Technology and AmpliTech Group, Inc. (NASDAQ:AMPG). Amplitech (which I shared my long thesis in the fund's Q1 investment letter) returned even more in Q2 at 266% driven on a narrative pushed by retail investors that Amazon has become a client and that their devices will be used in future satellite launches. The fund exited the position in May with a return of 166% because we believe this narrative is incorrect and the stock had reached our valuation target of $6. I had no idea Amplitech would get caught up in this retail bubble, but I'll take the win and move on."
AmpliTech Group, Inc. (NASDAQ:AMPG) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 5 hedge fund portfolios held AmpliTech Group, Inc. (NASDAQ:AMPG) at the end of the first quarter, compared to 7 in the previous quarter. While we acknowledge the potential of AmpliTech Group, Inc. (NASDAQ:AMPG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #deep #sail #capital





