2 days ago
IonQ (IONQ) is a quantum computing company whose stock has been a favorite among speculative buyers and high-volatility traders, thanks to its high beta (3.30 over the last 60 months) and news-driven price action. It's not uncommon to see the stock swinging by double-digit percentages around news, earnings, partnership announcements, or sector sentiment shifts.
But today, we have a rare event.
Domino's Pizza Stock Is Dirt Cheap, With 30% Potential Upside - What's the Best Play?
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
IonQ, the volatile quantum stock, is now sitting at 0% IV rank. That means options on IONQ are priced much cheaper than they have been historically, creating an opportunity to go long.
#quantum #high #pizza #best
But today, we have a rare event.
Domino's Pizza Stock Is Dirt Cheap, With 30% Potential Upside - What's the Best Play?
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
IonQ, the volatile quantum stock, is now sitting at 0% IV rank. That means options on IONQ are priced much cheaper than they have been historically, creating an opportunity to go long.
#quantum #high #pizza #best



2 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

2 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

3 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

3 days ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet


3 days ago
Volkswagen cut its 2026 operating-margin forecast to no more than 1 per cent, down from a previous range of 4 to 5.5 per cent.
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion

3 days ago
On August 19, Ferrovial (NASDAQ:FER) announced it had been selected to deliver the I-24 Southeast Choice Lanes, a 26-mile project running between Nashville and Murfreesboro. It is the largest single capital investment in Tennessee's history and the state's first public-private partnership. The price tag is $9.2 billion, though Ferrovial isn't carrying it alone, since its DriveTN consortium also counts Transurban and Tikehau Star Infra as partners.
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice
Choice lanes are familiar ground for Ferrovial, which has replicated the model in Washington, D.C., Charlotte and Dallas-Fort Worth. On Virginia's 66 Express corridor, similar lanes shaved up to 50% off peak-hour travel times. That is the pitch for I-24, a stretch of highway that already ranks among the region's most jammed: drivers who opt in get steadier speeds, and those in the free lanes should see less traffic too.
The business behind the bid looks healthy, too. Ferrovial's July 28 results showed adjusted EBITDA up 21.6% on a like-for-like basis to €746 million over the first six months of the year, with U.S. highways doing most of the lifting. Those roads are sending cash home as well, since Ferrovial received €357 million in dividends from North America. And the construction order book reached an all-time high of €18 billion, so plenty of work is already in hand. The pipeline keeps filling: Ferrovial bid on I-285 East in Georgia in July, and its D35 Highway bid in the Czech Republic was the most cost-effective submitted, with technical evaluation still underway.
Beyond the roads, the balance sheet looks sturdy. Ferrovial ended the first half with €1.3 billion in net cash, excluding infrastructure projects, meaning cash outweighs debt outside those projects. The airport arm is progressing too: Ferrovial has finished funding the $1.1 billion in equity it pledged for New Terminal One at JFK, and construction there is 92% complete.
Start with the line that looks worst on the page. Net profit for the first half of 2026 came in at €258 million, versus €540 million for the same period of 2025. That earlier figure included capital gains from ******* et rotation, which makes the comparison harsh, but the mismatch is still there: EBITDA climbed while reported profit fell.
#first #million #choice


3 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax

3 days ago
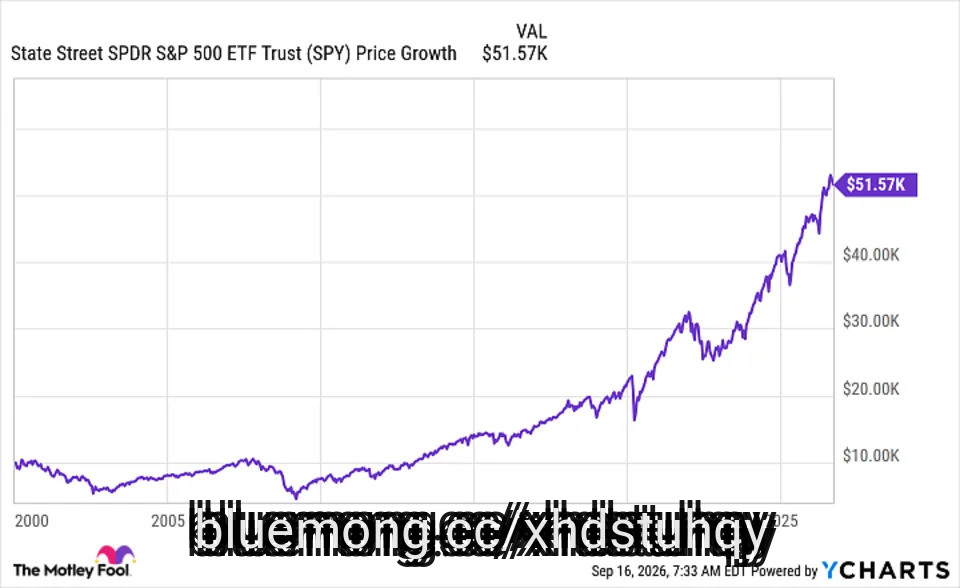
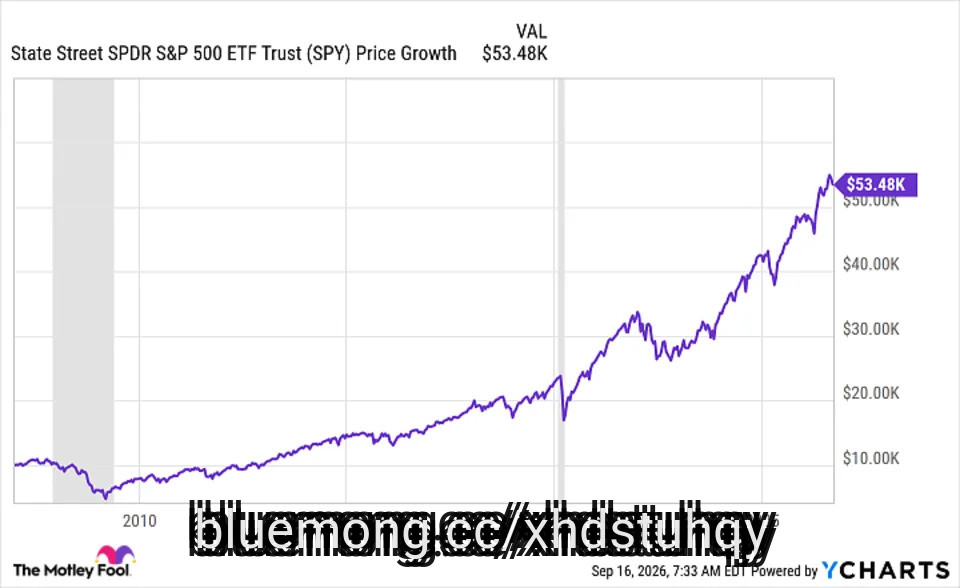
Wall Street pays a huge amount of attention to the price movements of the S&P 500 index (SNPINDEX: ^GSPC). If stocks are in a bull market, everyone wants to know when the next bear market will arrive. If there's a bear market, everyone keeps an eye out for the sign that the next bull market has come along. History shows you should ignore Wall Street and focus on a long-term plan of saving and investing, no matter what the market is doing.
World-famous investor and Wall Street icon Warren Buffett has often said that most investors would be better off buying an S&P 500 index fund, such as SPDR S&P 500 Trust (NYSEMKT: SPY) or Vanguard S&P 500 ETF (NYSEMKT: VOO), than trying to buy individual stocks. The real purpose of this is to create a simple, diversified portfolio that allows the investor to focus their attention on saving money and, frankly, living a happy life.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That said, a key part of Buffett's investment advice is that you should keep buying the S&P 500 no matter what is happening with the market. That's called dollar-cost averaging. You should also reinvest your dividends, which allows the dividends to compound over time. Both are simple, but powerful wealth-building tools.
SPY data by YCharts
#stocks
World-famous investor and Wall Street icon Warren Buffett has often said that most investors would be better off buying an S&P 500 index fund, such as SPDR S&P 500 Trust (NYSEMKT: SPY) or Vanguard S&P 500 ETF (NYSEMKT: VOO), than trying to buy individual stocks. The real purpose of this is to create a simple, diversified portfolio that allows the investor to focus their attention on saving money and, frankly, living a happy life.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That said, a key part of Buffett's investment advice is that you should keep buying the S&P 500 no matter what is happening with the market. That's called dollar-cost averaging. You should also reinvest your dividends, which allows the dividends to compound over time. Both are simple, but powerful wealth-building tools.
SPY data by YCharts
#stocks


4 days ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium


4 days ago
Most crypto wallets have functioned as a home for buying and selling speculative tokens. Caroline D. Pham, CEO of MoonPay Institutional and former acting chairman of the Commodity Futures Trading Commission (CFTC), thinks they are about to do something far more important for most investors.
"I do think that wallets are going to become the future, where you're going to have almost everything in your wallet," Pham said. "It's going to be your checking account, your savings account, your stablecoin wallet, your tokenized fund wallet. It's going to be your brokerage account."
Related: Duolingo beats Netflix by 80 spots in new power ranking
The first step came Sept. 17, when WisdomTree and MoonPay announced a collaboration to expand U.S. access to WTGXX, the WisdomTree Treasury Money Market Digital Fund, which holds short-term Treasuries.
WisdomTree said it is building an access point for its tokenized funds on MoonPay's technology, which reaches more than 35 million users. MoonPay also plans to use the fund in its stablecoin reserves.
#wisdomtree
"I do think that wallets are going to become the future, where you're going to have almost everything in your wallet," Pham said. "It's going to be your checking account, your savings account, your stablecoin wallet, your tokenized fund wallet. It's going to be your brokerage account."
Related: Duolingo beats Netflix by 80 spots in new power ranking
The first step came Sept. 17, when WisdomTree and MoonPay announced a collaboration to expand U.S. access to WTGXX, the WisdomTree Treasury Money Market Digital Fund, which holds short-term Treasuries.
WisdomTree said it is building an access point for its tokenized funds on MoonPay's technology, which reaches more than 35 million users. MoonPay also plans to use the fund in its stablecoin reserves.
#wisdomtree


4 days ago
XRP ranks last for Q4 after the CLARITY Act's Senate failure removed every legislative catalyst and invalidated year-end targets built around the bill.
Ethereum leads the Q4 outlook as the only coin carrying a dated technical upgrade still on the calendar, edging out Bitcoin and crushing XRP.
Bitcoin reclaiming $80,000 before the November midterms is the single falsifiable trigger that tightens the base scenario for all three coins.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The U.S. Senate voted 49-50 against advancing the CLARITY Act on September 15, falling eleven votes short of the 60 needed to end debate. The defeat leaves crypto's market-structure rules in the hands of the SEC and CFTC rather than Congress, at least for the remainder of 2026.
#senate #learn #september
Ethereum leads the Q4 outlook as the only coin carrying a dated technical upgrade still on the calendar, edging out Bitcoin and crushing XRP.
Bitcoin reclaiming $80,000 before the November midterms is the single falsifiable trigger that tightens the base scenario for all three coins.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The U.S. Senate voted 49-50 against advancing the CLARITY Act on September 15, falling eleven votes short of the 60 needed to end debate. The defeat leaves crypto's market-structure rules in the hands of the SEC and CFTC rather than Congress, at least for the remainder of 2026.
#senate #learn #september

4 days ago
On September 15, Needham ***** yst James Ricchiuti lifted the firm's price target on Teledyne Technologies Incorporated (NYSE:TDY) to $760 from $750, and reiterated a Buy rating. The revised price target reflected an upside of 27% from the close of the note.
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september


4 days ago
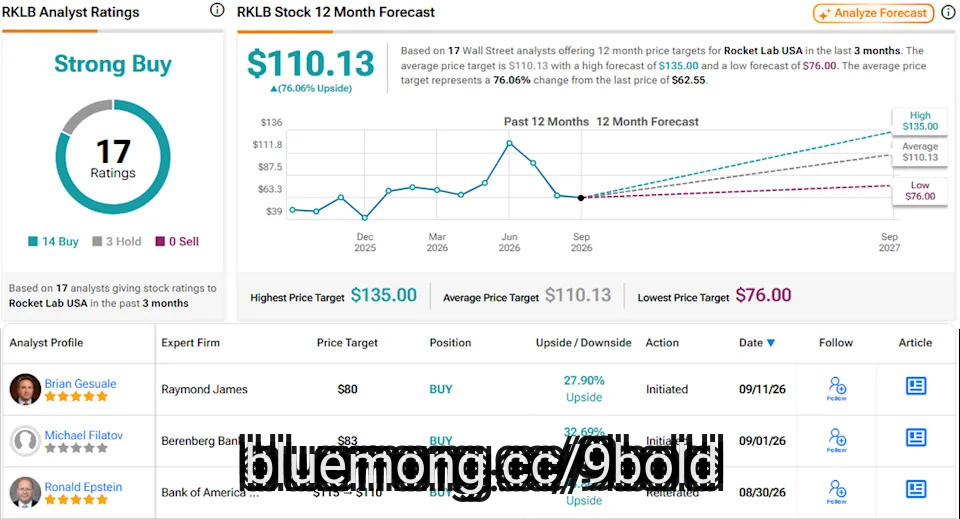
Palantir Technologies (Nasdaq: PLTR) and Rocket Lab Corporation (Nasdaq: RKLB) are among the biggest climbers in the Roundtable 100 this week.
While Palantir climbed 30 places to No. 33, Rocket Lab rose 34 places to No. 45.
Published with TheStreet, the Roundtable 100 ranks 100 publicly traded technology growth ****** ets. The Blue Ribbon Committee ****** ysts score each ****** et on team, safety, value, innovation and market dominance, with the average forming its power ranking.
Committee member Sam Badawi said the ****** ysts moved Palantir from No. 67 to No. 33 after the AI giant's revenue growth accelerated from 85% to 93% year over year and adjusted operating margin widened to 62%.
"This continues to strengthen through AIP, Foundry, and the Ontology, which are becoming deeply embedded into mission-critical government and enterprise workflows," he remarked.
#NASDAQ #rocket #places #technologies
While Palantir climbed 30 places to No. 33, Rocket Lab rose 34 places to No. 45.
Published with TheStreet, the Roundtable 100 ranks 100 publicly traded technology growth ****** ets. The Blue Ribbon Committee ****** ysts score each ****** et on team, safety, value, innovation and market dominance, with the average forming its power ranking.
Committee member Sam Badawi said the ****** ysts moved Palantir from No. 67 to No. 33 after the AI giant's revenue growth accelerated from 85% to 93% year over year and adjusted operating margin widened to 62%.
"This continues to strengthen through AIP, Foundry, and the Ontology, which are becoming deeply embedded into mission-critical government and enterprise workflows," he remarked.
#NASDAQ #rocket #places #technologies

4 days ago
Generac (GNRC) trades at the highest earnings multiple in its five-company peer group on a trailing basis. Yet it ranks last of the five on revenue growth over the past year, and fourth on operating margin. The case for paying up rests on something the trailing numbers do not show yet: a data center order book that ships mostly in 2027.
How Does The Past Year's Slowest Grower Carry The Highest Multiple?
AZZ trades at 20.0 times earnings, about half of Generac's 39.9. It grew revenue 5.7% over the last twelve months, against 0.6% for Generac. It also runs an operating margin of 16.2%, against Generac's 9.5%.
GNRC
RRX
#highest #past
How Does The Past Year's Slowest Grower Carry The Highest Multiple?
AZZ trades at 20.0 times earnings, about half of Generac's 39.9. It grew revenue 5.7% over the last twelve months, against 0.6% for Generac. It also runs an operating margin of 16.2%, against Generac's 9.5%.
GNRC
RRX
#highest #past




4 days ago
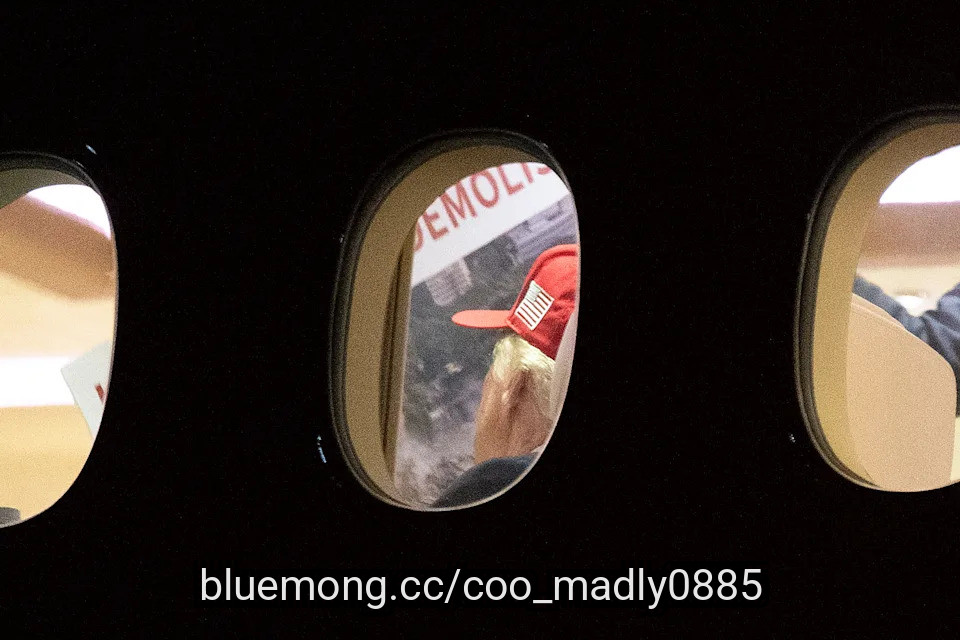
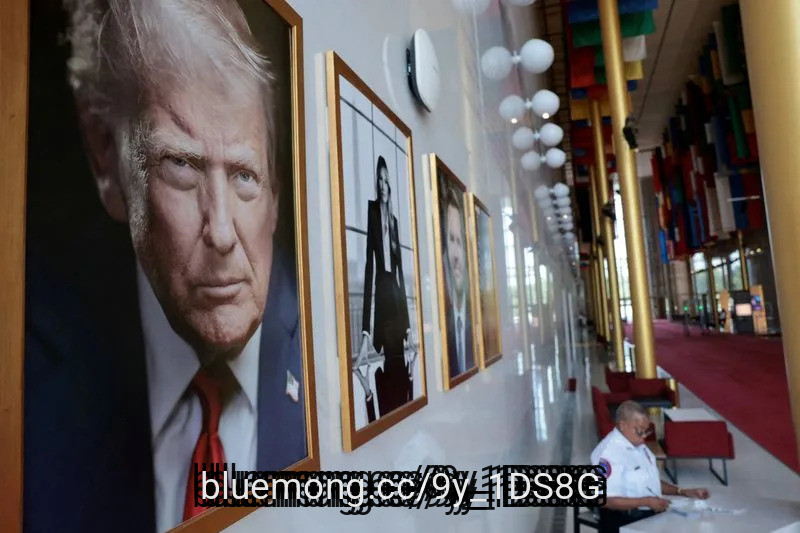
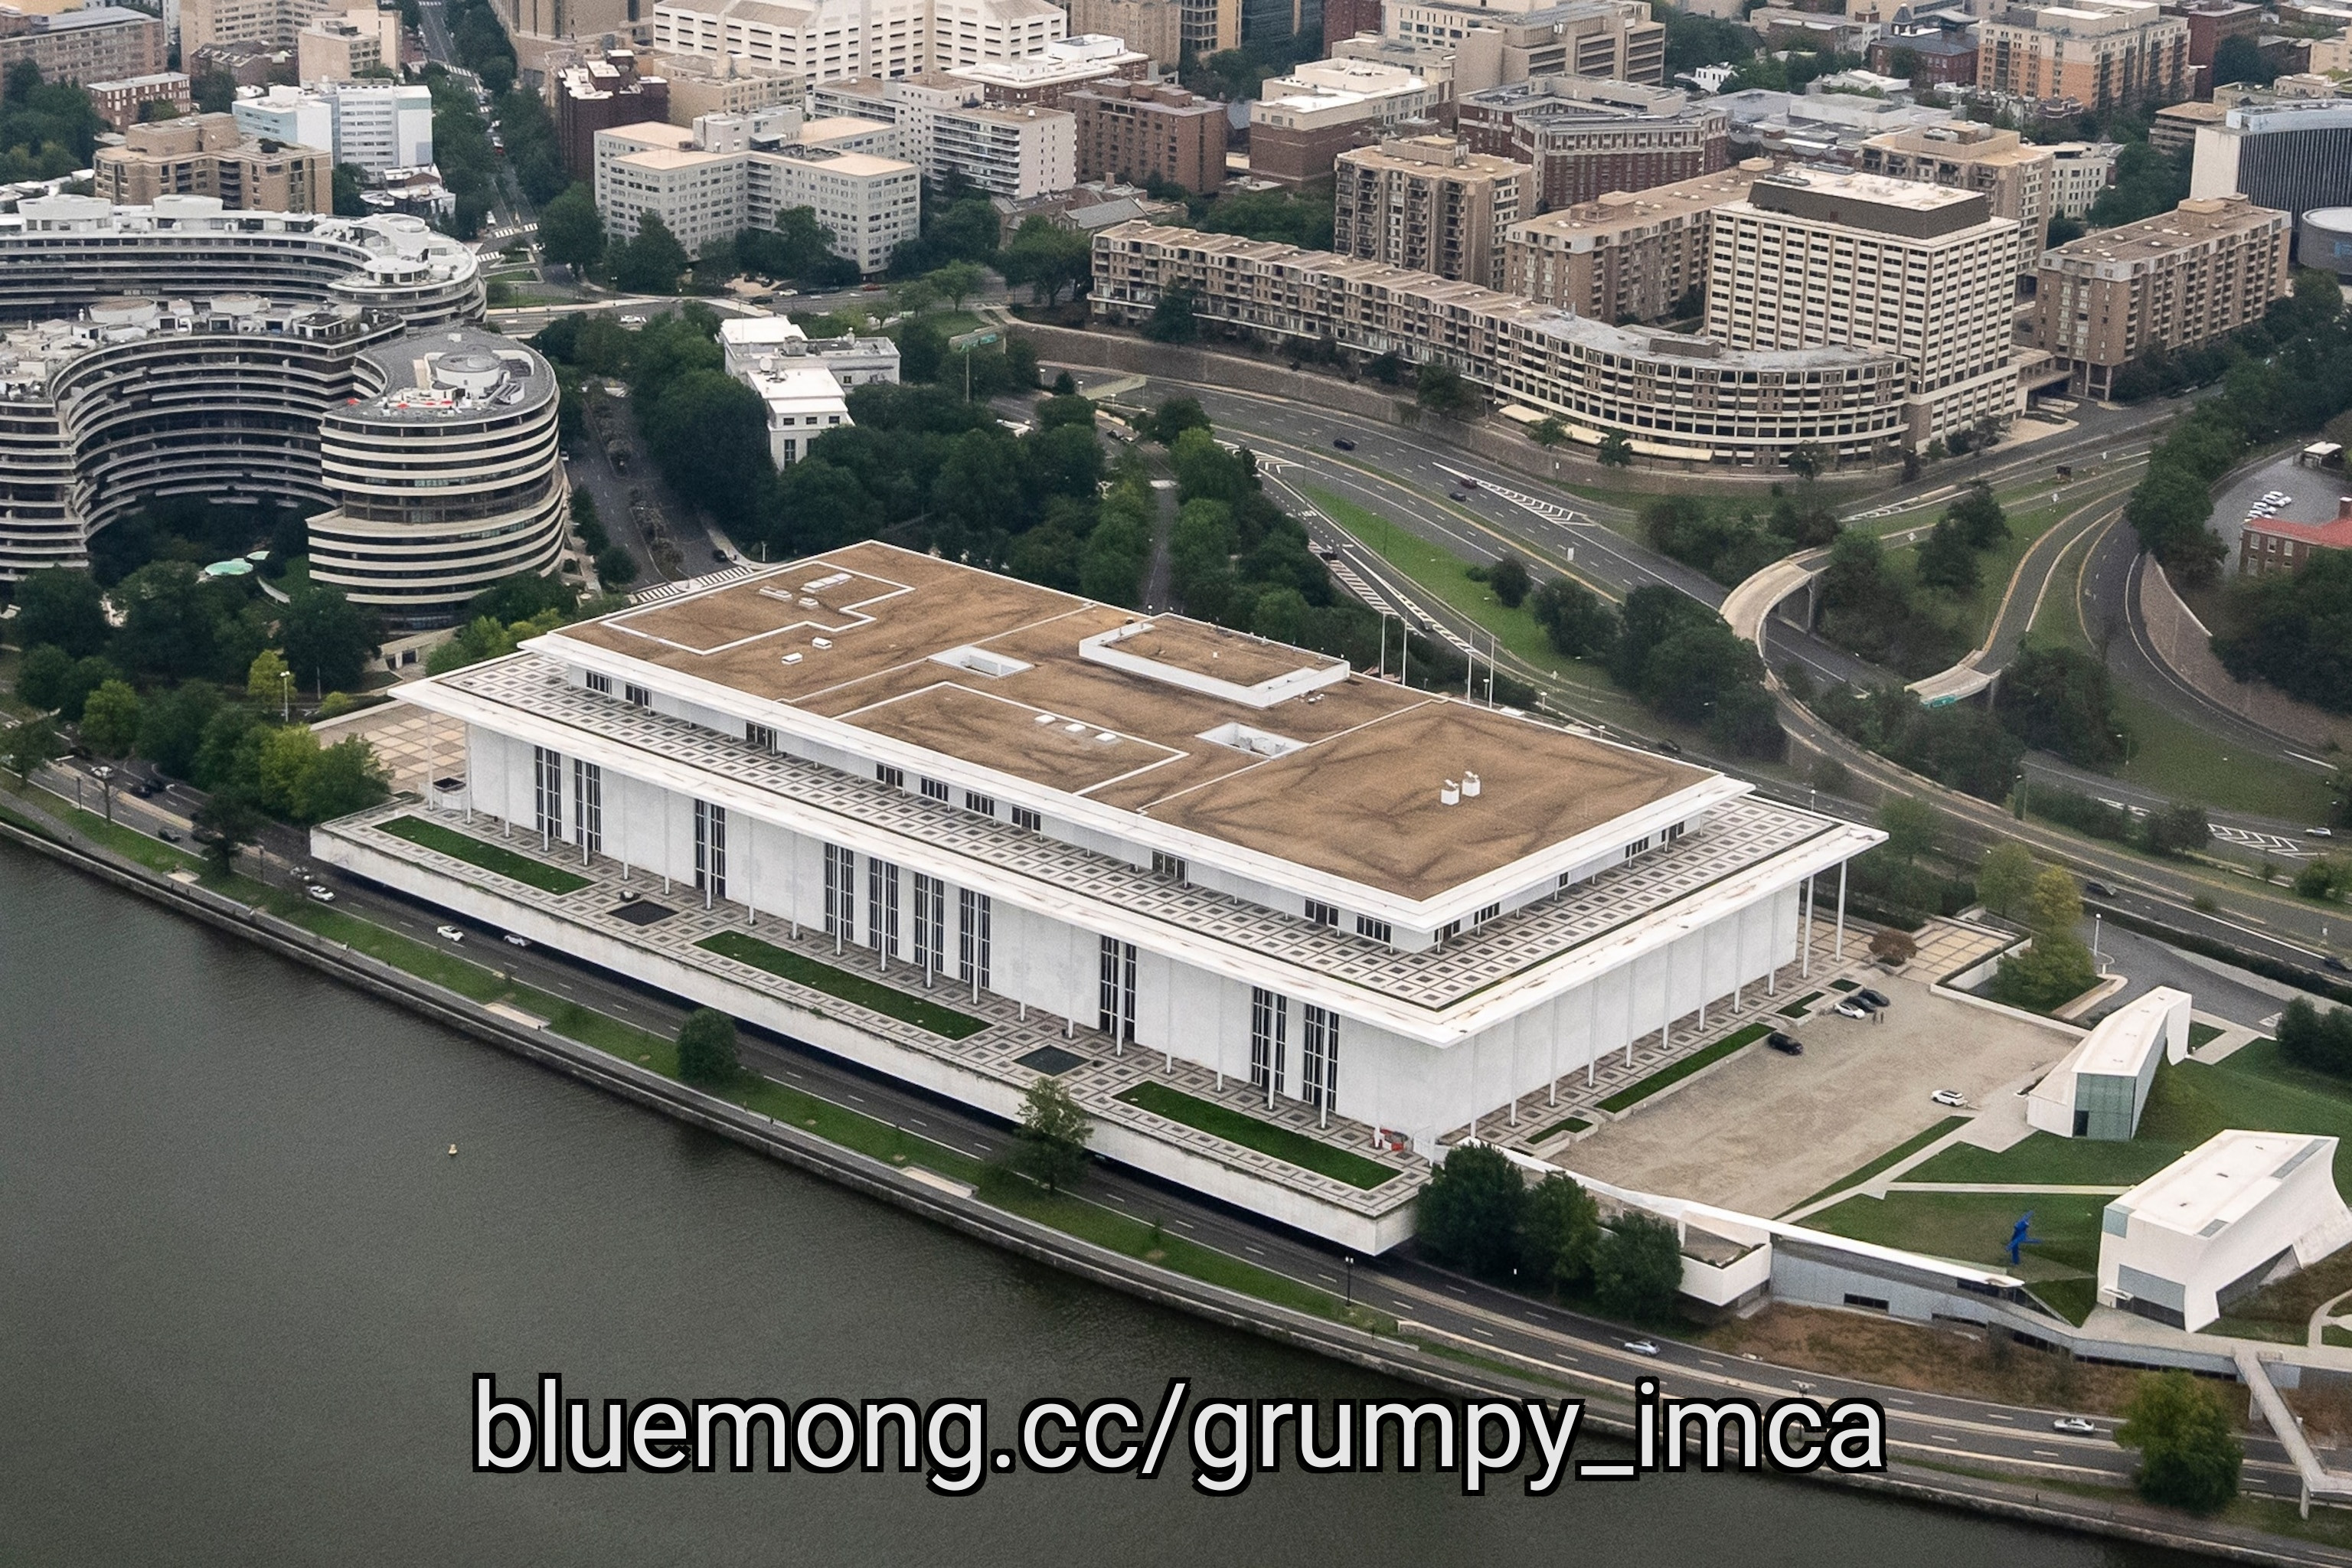
President Trump was photographed this week on board Air Force One examining a large poster with the words "Kennedy Center DEMOLISHED" printed above a rendering of a construction site, heightening concerns that his administration wants to raze Washington, D.C.'s iconic performing arts venue if his name is not added to its facade.
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
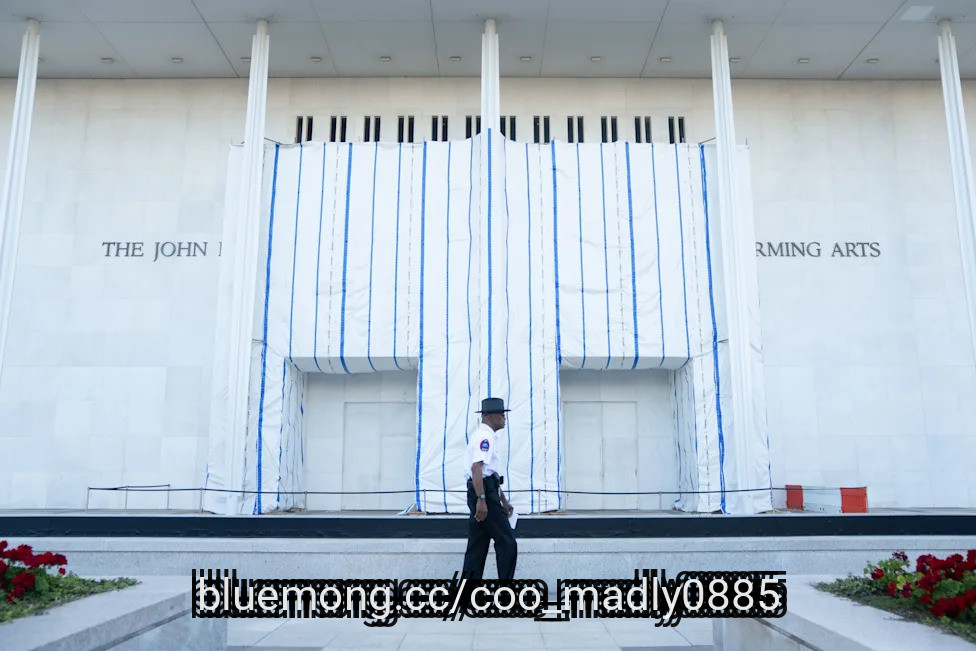
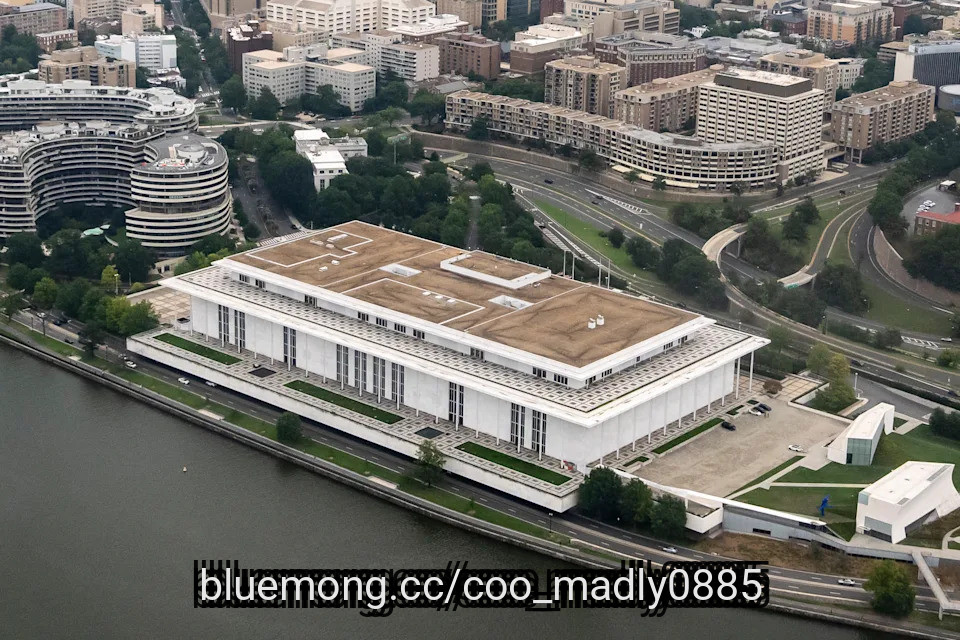
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing
"I think that the Trump administration should certainly have recognition," the president told reporters before he boarded the plane Wednesday in North Carolina. "Because frankly, if we don't do that, it's going to close. It'll end up being ripped down."
Trump's comments and the photographs that followed are the latest developments in a convoluted saga that started when he dismissed the center's trustees in February 2025 — just days after returning to office — and replaced them with loyalists who elected him chairman.
Despite several legal setbacks, Trump's handpicked board has been pushing ever since to rename the John F. Kennedy Center for the Performing Arts, which was built as a "living memorial" to the slain 35th president, after the White House's current occupant.
The day before Trump was photographed with the "Kennedy Center DEMOLISHED" poster, his appointees voted to close the center's main building for renovations. Does this mean Trump will bulldoze the Kennedy Center if he doesn't get the "recognition" he wants? Here's what we know — and what we don't.
#performing

5 days ago
In this episode of Motley Fool Hidden Gems Investing, Motley Fool contributors Jon Quast, Matt Frankel, and Rachel Warren discuss:
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt
Nvidia's potential acquisition of Hugging Face.
Hugging Face's new robot: Microduck.
What is an investment thesis?
Things that break an investment thesis.
#thesis #matt


5 days ago
Lululemon fell 18% after Meghan Frank delivered a second guidance cut, dropping the full-year EPS outlook to roughly $9.60 from last year's $13.26.
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook



5 days ago
Wall Street spent years debating whether crypto deserved a place inside the financial system.
Franklin Templeton increasingly thinks that debate has it backwards. The more important question may be how much of the existing financial system eventually starts behaving like crypto.
For Chris Perkins, head of Franklin Crypto, the shift is already underway.
"Every institution is integrating blockchain technology in one way, shape or form," Perkins told Coinage. "Market structure is changing overnight. We will be in an era of 24-seven markets. If you're not 24-seven capable, you'll be left behind and someone else is going to eat your lunch."
That is a notably aggressive prediction coming from Franklin Templeton, one of the world's largest traditional ***** et managers. But Franklin has increasingly been putting money behind that conviction, too.
#franklin #Crypto #seven #behind
Franklin Templeton increasingly thinks that debate has it backwards. The more important question may be how much of the existing financial system eventually starts behaving like crypto.
For Chris Perkins, head of Franklin Crypto, the shift is already underway.
"Every institution is integrating blockchain technology in one way, shape or form," Perkins told Coinage. "Market structure is changing overnight. We will be in an era of 24-seven markets. If you're not 24-seven capable, you'll be left behind and someone else is going to eat your lunch."
That is a notably aggressive prediction coming from Franklin Templeton, one of the world's largest traditional ***** et managers. But Franklin has increasingly been putting money behind that conviction, too.
#franklin #Crypto #seven #behind

5 days ago
GE Vernova Inc (NYSE:GEV) rebounded with Bernstein's backing after an earlier sell-off that followed broader concerns about technology infrastructure spending.
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing


5 days ago
By Katharine Jackson and Mike Scarcella
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue

5 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company

5 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second

5 days ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum

5 days ago
Is there anything prettier than a consistently uptrending stock price chart? I'm drawn to these types of charts. I've always thought a consistent uptrend is an indication of strong buying power for a stock. However, while I can tell you if a chart looks like a consistent, methodical trend, it's hard to define it using data, which is necessary to create an indicator. That's why, until now, I've never put numbers behind my theory.
I won't go into the details, but using moving averages over various time frames, I've created a ranking system for stocks with the most consistent uptrends and downtrends over the past three months. Using this ranking system, Docusign (DOCU) is one of the top uptrending stocks. That's a pretty chart, if I do say so myself. When I see a chart like this, I think, why would it stop now?
In this week's article, I'll test my theory with actual numbers and see if DOCU and other stocks like it are good bets, like my instincts have always led me to believe.
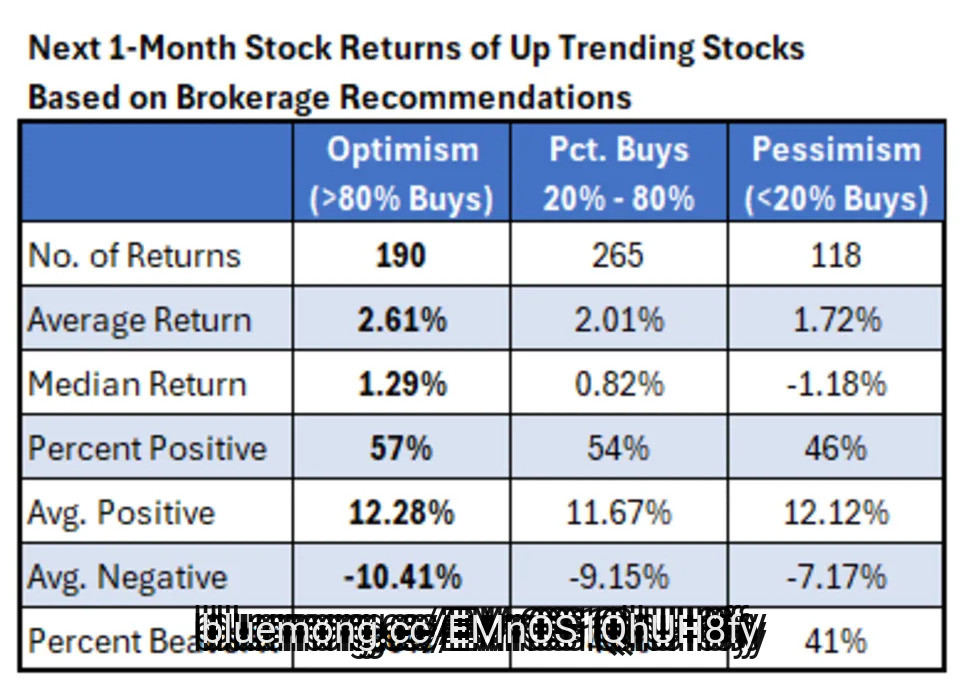
For this study, I went back to 2024 and picked the 18th of each month, which corresponds to the end of this week. I used my trend ranking system to find the 30 stocks in the strongest uptrends and the 30 in the most consistent downtrends. Then, I tracked how each group performed over the next month of trading. The table below summarizes the results.
My instincts look correct based on the average returns of the stocks. The top uptrending stocks averaged a return of 2.15% over the next month, while the most consistently downtrending stocks averaged a return of 1.57%. The other stocks averaged 1.84%, falling between the two groups.
#like #using
I won't go into the details, but using moving averages over various time frames, I've created a ranking system for stocks with the most consistent uptrends and downtrends over the past three months. Using this ranking system, Docusign (DOCU) is one of the top uptrending stocks. That's a pretty chart, if I do say so myself. When I see a chart like this, I think, why would it stop now?
In this week's article, I'll test my theory with actual numbers and see if DOCU and other stocks like it are good bets, like my instincts have always led me to believe.
For this study, I went back to 2024 and picked the 18th of each month, which corresponds to the end of this week. I used my trend ranking system to find the 30 stocks in the strongest uptrends and the 30 in the most consistent downtrends. Then, I tracked how each group performed over the next month of trading. The table below summarizes the results.
My instincts look correct based on the average returns of the stocks. The top uptrending stocks averaged a return of 2.15% over the next month, while the most consistently downtrending stocks averaged a return of 1.57%. The other stocks averaged 1.84%, falling between the two groups.
#like #using

6 days ago
A federal judge blocked Trump's name from being added to the building.
President Donald Trump said on Wednesday the Kennedy Center could "close" or be "ripped down" if his administration doesn't receive recognition on the performing arts center as tensions over his name being removed mount.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," the president told reporters on the tarmac in North Carolina.
Trump claimed that the Kennedy Center was a "mess" without his intervention and "has lost 10s of millions of dollars, even hundreds of millions of dollars," comparing it to New York's Carnegie Hall.
The president's comments come after a federal judge on Tuesday blocked the performing arts center's board from adding a tribute to Trump on the building or site. He responded by saying he wouldn't spend congressionally approved funding for the center's renovation unless the building also bears his name.
#blocked
President Donald Trump said on Wednesday the Kennedy Center could "close" or be "ripped down" if his administration doesn't receive recognition on the performing arts center as tensions over his name being removed mount.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," the president told reporters on the tarmac in North Carolina.
Trump claimed that the Kennedy Center was a "mess" without his intervention and "has lost 10s of millions of dollars, even hundreds of millions of dollars," comparing it to New York's Carnegie Hall.
The president's comments come after a federal judge on Tuesday blocked the performing arts center's board from adding a tribute to Trump on the building or site. He responded by saying he wouldn't spend congressionally approved funding for the center's renovation unless the building also bears his name.
#blocked


6 days ago
Once upon a time, the 'space race' meant the grand strategic competition between the USA and the USSR to gain control of the heavens. The superpowers designed and built satellites, manned capsules, orbital **** ecraft and long-endurance **** e stations, and NASA even sent the Apollo landers to put men on the Moon.
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once

6 days ago


6 days ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alibaba Group Holding Limited (NYSE:BABA). Alibaba Group Holding Limited (NYSE:BABA) is a Chinese multinational company that focuses on cloud computing, e-commerce, and artificial intelligence. On September 14, 2026, Alibaba Group Holding Limited (NYSE:BABA) closed at $109.23 per share. Over the past month, Alibaba Group Holding Limited (NYSE:BABA) declined 14.03%, and its shares lost 32.08% over the past 52 weeks. Alibaba Group Holding Limited (NYSE:BABA) has a market capitalization of $268.48 billion, and its stock has traded within a 52-week range of $91.99 and $192.67.
Conventum – Alluvium Global Fund stated the following regarding Alibaba Group Holding Limited (NYSE:BABA) in its Q2 2026 investor letter:
"Alibaba Group Holding Limited (NYSE:BABA) was down 21.3%. Its results were all about AI, and how its investments are paying off, and management's confidence to make further investments. So the only disappointing news (if you can call it that), was that free cash is being chewed up by capital expenses to the point where it has become negative. The results were generally well received. Share price fluctuations are par for the course, especially for Alibaba. We are not fussed. As a consequence of the falling share price, its maintainable earnings yield (on our numbers) has increased to 7.7% and it is trading at a circa 30% discount to our valuation. The Fund's current position is 2.6%."
Alibaba Group Holding Limited (NYSE:BABA) ranks 30 on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 97 hedge fund portfolios held Alibaba Group Holding Limited (NYSE:BABA) at the end of the second quarter which was 102 in the previous quarter. While we acknowledge the potential of Alibaba Group Holding Limited (NYSE:BABA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alibaba #baba #alluvium #quarter