1 day ago
John Leguizamo, the veteran stage and screen actor and leading activist for Latino representation in Hollywood, who is currently garnering career-best notices and Oscar buzz for his portrayal of Eumaeus in Christopher Nolan's The Odyssey, is our guest on this episode of The Hollywood Reporter's Awards Chatter podcast, which was recorded in front of an audience of students at Chapman University.
Over the course of 42 years in the business, Leguizamo has worked with everyone. He has been directed by Brian De Palma, Spike Lee, Baz Luhrmann and Jon Favreau multiple times, as well as by Mike Nichols, George A. Romero, Ridley Scott, Todd Haynes, M. Night Shyamalan, Ava DuVernay and Christopher Nolan. And he has shared the screen with the likes of Sean Penn, Harrison Ford, Al Pacino, Leonardo DiCaprio, Wesley Snipes, Arnold Schwarzenegger, Robert De Niro, Keanu Reeves, Nicole Kidman, Kevin Hart, Tina Fey, Amy Poehler and Matt Damon.
In the movies, he has starred in blockbuster studio franchises (Ice Age and John Wick), revered indies (Poison and Chef) and cult classics (Super Mario Bros. and To Wong Foo, Thanks for Everything! Julie Newmar). On TV, he has been on hit network shows (ER) and acclaimed limited series (Waco and When They See Us). And on the stage, he has written and starred in six acclaimed one-man shows. Between them all, he has accumulated an Emmy Award and a special Tony Award, as well as Golden Globe and Critics Choice award nominations.
More from The Hollywood Reporter
Universal Becomes First Studio to Cross $5B at 2026 Global Box Office
Charlize Theron Says 'The Odyssey' Just Gave Hollywood a Much-Needed Reminder
#hollywood


1 day ago
The woman who alleges she was drugged and raped by multiple members of a Cornell University fraternity in October 2024 told one of the accused men in a recorded phone call weeks later that she was "10 shots deep" when she arrived at the Chi Phi house and was now struggling to remember what had caused "so much damage on my body and brain."
"The only way for me to heal is to know what happened," the woman, identified as "Jane Doe" in a civil lawsuit, said during a Nov. 7, 2024, call, according to audio obtained by ABC News. "That's why I'm trying to just piece it together, you know, like I'm just like confused."
During the call, the Chi Phi fraternity member told her that she consented to having a threesome with him and another fraternity brother.
He also insisted that Jane Doe had told him she had not been drinking when she showed up.
"You did tell me you were sober, by the way," he said. "You said you hadn't been anywhere."
#call #woman #cornell #october

2 days ago
Kylie Jenner showed her playful mom trick to wake her kids in the "Day in the Life" vlog. She shared a video on her YouTube page, giving a glimpse of how she spends a day from morning to night. It started with waking her two kids — Stormi (8) and Aire (4) — using a clever parenting hack. This definitely seemed to work, as the two children were stirring in no time.
Kylie Jenner's "Day in the Life" vlog showed her using a clever mom trick to wake her kids as part of their morning routine. On her YouTube page, the socialite shared a video of her day with her fans. In it, she recorded herself from morning to night, sharing a glimpse of her daily routine and fun activities.
The 10-minute and 19-second clip started with Jenner holding a black megaphone. She was still under the blanket on her huge bed. Her slightly puffed face showed that she had just woken up as well. While the mother of two was on one end of the bed, her daughter Stormi was on the other side. Initially, Jenner's voice cracked while saying "Good Morning" using the megaphone. It made her burst into laughter.
Then, she composed herself and tried again— louder and clearer. "Good morning, Stormi! Rise and Shine! It's a beautiful day. You are healthy, you are beautiful, you're smart. And we're going to conquer the day. Get up," Jenner woke her daughter up in a ****** se voice. Meanwhile, Stormi stirred in her sleep and tried not to wake up, but failed.
Furthermore, Jenner used the same trick with her son, Aire. She playfully sang, "Rise and Shine. Good morning, stinky ****** ." Then, she snuggled into her kid and showered him with kisses to wake him up with more love and care. Later, Jenner set her daughter's hair before the 8-year-old left for school.
#kylie


5 days ago
Prince William has paid homage to the "incomparable" Dame Deborah James in a moving video message.
The Prince of Wales, 44, made a surprise appearance in a pre-recorded message at the inaugural Bowelbabe Fund Rebel Ball in London on what would have been the campaigner's 45th birthday.
He recalled: "What struck me was Deborah's positivity and humour in the face of adversity – what she liked to call 'rebellious hope'".
He described Dame Deborah, who died in 2022, as "an amazing woman" and said her Bowelbabe Fund for Cancer Research UK had achieved so much in the last four-and-a-half years, investing in pioneering research that was "giving more people more time with the ones they love".
Prince William addressed the room with a pre-recorded message (@ Simon Way)
#dame #james


5 days ago
Prince Harry is back in the spotlight after his eco-travel initiative, Travalyst, reported a five-figure loss. The Duke of Sussex launched the non-profit venture in 2019 with the goal of making travel more sustainable. Travalyst has maintained that the loss was planned and formed part of an investment in the organization's future.
According to RadarOnline.com, citing Travalyst's latest annual accounts, the organization recorded a loss of around $17,000 (£13,542) in 2025. The result represented a reversal from the previous year's stronger financial position.
A Travalyst spokesperson characterized the deficit as planned and relatively small, saying, "It was a planned and small loss of £13,000, very typical of a lean, not-for-profit organisation, making a critical investment for the future." The spokesperson continued, "Travalyst remains confident in its financial oversight and strength of its partnerships."
Questions surrounding Harry's role in the venture have persisted since 2023. The Duke of Sussex was reportedly absent during the organization's "pilot phase," which saw five new board members join with "world-class expertise." He has also become less visible as the venture's public face, with his most recent appearance in a promotional video dating back to May 2022.
Harry and his wife Meghan Markle's documentary, "Cookie Queens", also reportedly failed at the box office. In an interview with Page Six, royal commentator Kinsey Schofield advised the couple to "disappear professionally."
#planned #sussex

5 days ago
Elijah Randolf, a popular content creator, has been reported missing after sharing an eerie video saying farewell to his followers
The content creator said in a Sept. 30 video he was "done" with social media, but didn't specify why
A spokesperson for the San Francisco Police Department told PEOPLE that it had received a report in the evening of Sept. 30 that Randolph was missing and had opened a missing persons case
Elijah Randolf, a popular content creator, was been reported missing the same day he shared an eerie video saying farewell to his followers.
On Sept. 30, Randolph — whose legal name is Ellis Randolph — shared a video to his TikTok and Instagram accounts, telling his followers that he was "done" with social media. In the clip, which he said he initially recorded on Feb. 16, he admitted his followers "probably won't ever see me again" but didn't share a further reason for his departure.
#missing #elijah #randolf
6 days ago
Pennsylvania has reported its fifth measles-associated death of 2026 as the state's ongoing outbreak climbs to 943 confirmed cases across 39 counties.
The Pennsylvania department of health said on Wednesday that an unvaccinated Lancaster county resident who tested positive for measles had died. Health officials did not release further information about the individual, citing privacy protections.
The death marks the fifth Pennsylvania resident to meet the state's definition of a measles-associated death this year after a fourth death two weeks ago. Due to how the Trump administration has changed its method for reporting measles deaths, the Centers for Disease Control and Prevention (CDC) has not counted the Pennsylvania measles deaths in its national tally.
As of Monday 28 September, Pennsylvania had recorded 40 new positive cases. The outbreak has now reached 39 counties, with 943 ******* ulative confirmed cases, 176 hospitalizations and five confirmed measles-associated deaths.
Only four of those confirmed cases have involved vaccinated individuals, representing less than 1% of the state's total cases.
#associated

16 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
16 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

17 days ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

18 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

18 days ago
Sept 18 (Reuters) - US equity funds recorded outflows for a fourth consecutive week in the week to September 18, as rising crude oil prices heightened inflation concerns and expectations of a Federal Reserve rate hike added to investor caution ahead of its policy decision.
US equity funds recorded net redemptions of $31.44 billion during the week, largely matching the $32 billion withdrawn a week earlier, LSEG Lipper data showed.
Crude oil prices rose to four-month highs during the week, fueling inflation concerns and lifting Treasury yields, which weighed on growth-oriented funds.
The Fed raised interest rates by 25 basis points on Wednesday and signaled that further tightening may be needed to curb inflation fueled by higher energy costs linked to the war in Iran.
Investors withdrew $28.71 billion, $1.73 billion and $3.16 billion from US large-cap, mid-cap and multi-cap funds, respectively. In contrast, small-cap funds attracted $568 million in weekly inflows.
#funds #recorded #concerns

18 days ago
Tesla's (NASDAQ: TSLA) business is in an interesting spot. The company saw a significant sales rebound in the second quarter, with revenue rising 26% year over year to reach $22.5 billion. Recent reports also suggest that the company's share of the U.S. electric vehicle (EV) market has risen sharply amid a substantial sales contraction for the overall industry. And while the company's net income fell 5% annually in the second quarter, the business still recorded net income of $1.11 billion in the period.
On the other hand, positive net income doesn't tell the whole story because the metric doesn't include capital expenditures (capex) that are recorded as ****** ets on the balance sheet. With Tesla betting big on its robotaxi project, Optimus humanoid robots, and other potential growth drivers, the company recorded $5.79 billion in capex in Q2. As a result, the business posted -$1.1 billion in free cash flow (FCF) in the period. With FCF coming up negative lately, the company's $43.5 billion cash position provides a valuable cushion.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Tesla posted substantial sales growth in the second quarter as some of the pressures facing the brand eased, higher gas prices encouraged EV purchases, and price cuts helped spur demand. On the other hand, it remains to be seen whether this sales growth momentum is sustainable -- and banking on the core EV business to be an earnings driver that can support the company's highly growth-dependent valuation seems unwise.
While Tesla has seen competitors based in the U.S., ****** an, and South Korea reduce their focus on the EV market, BYD and other China-based rivals are making inroads in the market and continue to bet heavily on long-term growth in the category. CEO Elon Musk appears to have a good grasp on the challenging competitive landscape and has been positioning robotaxis, humanoid robots, and semiconductor projects as the core elements of his company's growth strategy.
#NVIDIA
19 days ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
19 days ago
On September 11, a caller praised The Boeing Company's (NYSE:BA) CEO and asked when the company would overcome the ongoing labor uncertainty and finally move beyond years of sideways stock performance. Mad Money host Jim Cramer replied:
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial
19 days ago
Argentina's controversial right-wing president, Javier Milei, slashed inflation with a brutal dose of economic austerity, but this came at a steep social cost. The cost of living is spiraling higher, fueling household debt, loan delinquencies, and economic hardship. Industrial output, since Milei took office, has declined sharply, with local companies closing at an alarming rate. While parts of the economy are falling into chaos, Argentina's oil and gas sector is experiencing a generational boom driven by the Vaca Muerta shale.
Argentina's vital hydrocarbon sector continues to surge, with oil production hitting yet another record in July 2026. Output reached 902,920 barrels per day, almost 1% above June and 12% higher than a year earlier, marking the country's highest oil production on record. Natural gas production has also expanded strongly, although output slipped 0.5% month over month and 1.6% year over year in July to average 5.6 billion cubic feet per day. That modest setback barely dents the bigger picture: economically crucial gas production has surged 21% over the past five years.
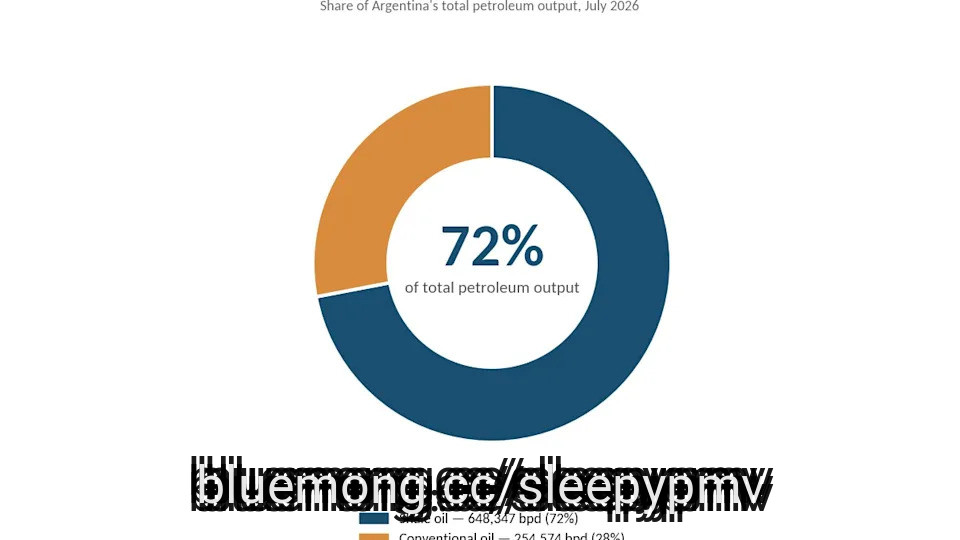
It is the ongoing and growing exploitation of the Vaca Muerta shale, situated in northern Patagonia in Neuquén Province which is responsible for Argentina's booming oil and natural gas complex. For July 2026, shale oil production rose by 1.2% month over month and a whopping 26% year over year to an all-time high of 648,347 barrels per day. As a result, shale oil now comprises a record 72% of Argentina's total petroleum output. This is also responsible for bolstering energy security in the Americas.
Shale gas production is also expanding at a healthy clip. For July 2026, Argentina lifted an average of 3.9 billion cubic feet per day of the fossil, which, despite being nearly 1% less than a month prior, was almost 4% higher year over year. That is the second-highest monthly shale gas production ever recorded. It was only eclipsed by June 2026 output, which hit 3.94 billion cubic feet per day. Shale gas now makes up 70% of Argentina's natural gas output, which is the highest level ever recorded.
Shale oil and gas production will keep growing at a solid pace, with Argentina on track to become a pure unconventional producer. You see, conventional oil output is in decline and has been for over a decade. Argentina's conventional fields are well past their prime, in many cases having hit peak production a decade ago with output now truly in decline. Government data shows July 2026 conventional oil production of 254,574 barrels per day, which is 2% lower than a month prior and 13% less year over year, indicating conventional oil output is 50% lower than a decade ago.
#shale #july #higher #record
19 days ago
Monthly car payments continue to hit record levels for both new and used cars.
The overall cost of car ownership remains elevated due to steep insurance and car maintenance prices in addition to the cost of a loan.
Good credit scores are key to qualifying for the best auto loan rates and driving away with a competitive monthly payment.
New car prices remain steep, with monthly payments for new cars soaring to the highest levels ever recorded. Amid this environment, buyers are taking on increasingly larger loans to make vehicle purchases, and some are also stretching repayment over a longer timeline — in some cases, up to seven years.
Whether you have poor credit or are looking to refinance your current loan, it's important to understand typical monthly payments and rates so you can feel confident that you are getting the best deal. While auto loan rates in 2026 are projected to lower slightly, it won't be enough to put a serious dent in the many factors that are driving up the cost of car ownership, including continued high cost of auto insurance and maintenance expenses.
#payments #rates #levels #ownership
19 days ago
VICTORIA, SEYCHELLES, September 16th, 2026, Chainwire
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's **** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked **** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#proof
20 days ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
Dallas, Tarrant, and Collin county records show 1,197 commercial and multifamily loans totaling $13.3 billion maturing over the next 12 months, with another $12.5 billion in loans already past their maturity date.
Only 3 of the 1,197 forward-maturing loans carry a recorded distress filing, underscoring how little of the real risk shows up in public records before a loan actually fails.
The wall stems from two colliding loan vintages: roughly $4.3 billion in 2016-2017 peak-era loans and $2.6 billion in short-term bridge debt originated since 2025.
DFW loan maturities over the next 12 months total $13.3 billion, according to a county-by-county read of deed of trust records by Circlemark. That's on top of $12.5 billion in loans that have already passed their stated maturity date and remain open. Circlemark, which reads scanned county clerk instruments rather than relying on servicer-reported data, calls its own $13.3 billion figure a floor, not a ceiling.
#records

20 days ago
On September 8, United Natural Foods Inc. (NYSE:UNFI) announced its fourth quarter and full FY26 results. For the final quarter, the company posted an adjusted EBITDA of $172 million, which grew 48.3% compared to Q4 FY25. United's fourth quarter adjusted EPS of $0.69 took a sharp turn relative to a $0.11 adjusted loss per share for the same period last year. Cash flow from operating activities for the quarter stood at $197 million, along with free cash flow of $80 million.
Nejron Photo/Shutterstock.com
Amid a favorable customer mix and network optimizations, United delivered Q4 gross profit of $1,050 million, increasing marginally by 1.9% from the same period last year. This led to a gross margin of 13.7%, compared to 13.4% recorded in Q4 FY25. Cost-saving initiatives, which included efficient productivity through distribution centers and network optimizations, translated into lower operating expenses on a year-over-year basis. It helped United jump from an $87 million net loss for Q4 FY25 to a net income of $35 million during the recently concluded quarter.
For the complete fiscal year, the company delivered an adjusted EBITDA of $701 million, showcasing a 27% growth compared to FY25. Full-year adjusted EPS also climbed from $0.71 last year to $2.65. United generated FY26 operating cash flow of $540 million and free cash flow of $323 million.
Several encouraging operational developments took place during the fourth quarter. United initiated onboarding additional business from its existing customer base, as well as the new ones. Topline impact of such additions will be seen during FY27, once the broader optimization initiatives have cycled through. For its Lean Daily Management (LDM) program, the company concluded a preliminary rollout covering 44 distribution centers. This resulted in year-over-year enhancement in fill rates, throughput, and on-time deliveries, for four consecutive quarters.
#cash #flow #fourth #company
20 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Open Market Committee (FOMC) is meeting this week. During these meetings, the committee ****** ses the health of the economy and potentially adjusts the federal funds rate. Read on to learn more about the timeline for this meeting, what it involves, and expected outcomes.
The latest FOMC meeting takes place on September 15-16, 2026. This is its sixth scheduled meeting of the year.
Once the meeting concludes, the FOMC will release its policy decisions on Wednesday at 2 p.m. Eastern time. Then the Fed chairman will hold a news conference at 2:30 p.m.
The live news conferences, held by the Federal Reserve chairman, are livestreamed and recorded. Additionally, the minutes of regularly scheduled meetings are released three weeks after the date of the policy decision.
#federal #chairman
20 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
20 days ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current

20 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
20 days ago
Forgent Power Solutions (NYSE:FPS) shares rose 10.9% in premarket trading on Tuesday after the company released its fiscal fourth-quarter and full-year 2026 financial results.
The results cover the period ended June 30, 2026. Forgent scheduled a conference call for 11:00 a.m. ET to discuss its financial performance and outlook.
The supplied information did not include the company's reported fourth-quarter or full-year revenue, earnings or other financial figures from Tuesday's release.
Ahead of the latest results, Forgent had reported fiscal third-quarter revenue of $379 million, more than double the level recorded a year earlier.
Third-quarter bookings reached $867 million, an increase of 308% year over year and a company record, according to the supplied information. The result increased Forgent's backlog to nearly $2 billion.
#year #quarter #Third #fourth
20 days ago
Six Anthropic cofounders made their debut on the Forbes 400 list of America's wealthiest people on Tuesday, with a combined net worth of $93 billion. Daniela Amodei, Dario Amodei, Tom Brown, Jack Clark, Jared Kaplan, and Sam McCandlish are each worth an estimated $15.5 billion, according to Forbes.
The six cofounders left OpenAI in 2021 to found Anthropic and have built the company into a significant competitor in the artificial intelligence industry, partly through the popularity of its Claude chatbot. Their fortunes rose in May, when Anthropic closed a funding round that more than doubled the estimated value of their individual stakes of roughly 1.6% each, according to Forbes. A seventh cofounder holds Canadian citizenship and does not appear on the list.
The Anthropic group ranked among the most prominent of 34 first-time entrants to this year's Forbes 400, which set a record minimum net worth of $4.4 billion, up from $3.8 billion in 2025. America's 400 wealthiest people are collectively worth $8 trillion, up from $6.6 trillion a year ago. The 34 newcomers account for $321 billion of that total.
The AI sector drove the largest share of new entrants, with 15 of the 34 newcomers drawing their wealth from the industry. OpenAI cofounder Greg Brockman topped the new members, debuting at No. 45 overall with an estimated $25.5 billion fortune. Robotics entrepreneur Brett Adcock ranked second among newcomers with an estimated $23.4 billion net worth, while investor Antonio Gracias, an early backer of multiple Elon Musk companies, placed third at $17.1 billion.
The Anthropic cofounders' arrival on the list follows a period of rapid growth at the company. Anthropic posted $11.6 billion in revenue in the second quarter, surpassing OpenAI's $6.7 billion for the same period — the first time Anthropic had led its rival on that measure. Anthropic also recorded a small adjusted operating profit of $559 million in the quarter, according to Forbes.
#estimated
21 days ago
VICTORIA, SEYCHELLES, September 16th, 2026, Chainwire
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's ***** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked ***** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#valuation


22 days ago
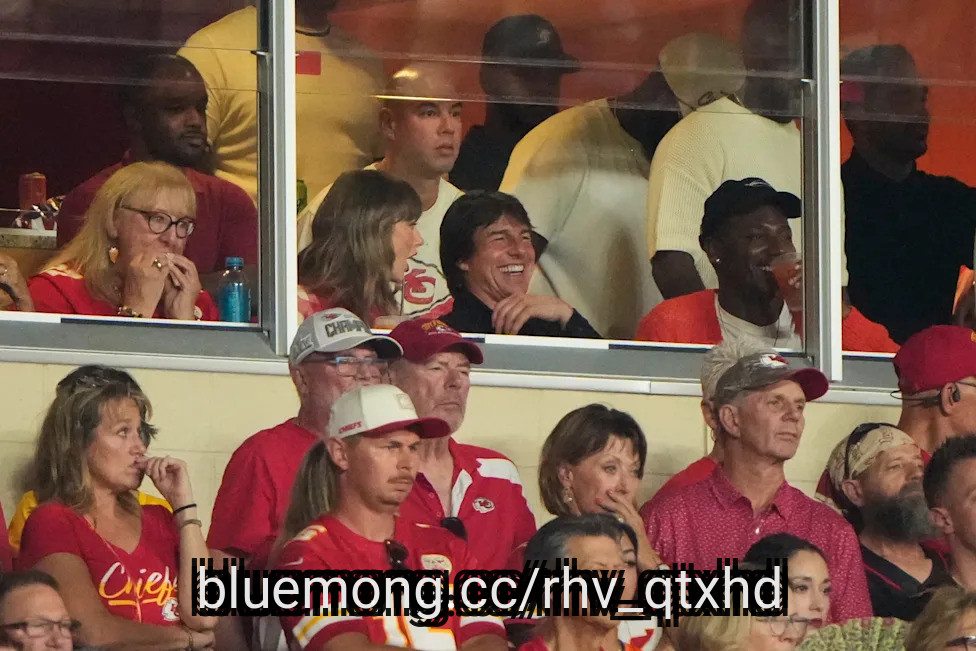
KANSAS CITY, Mo. (AP) — Pop superstar Taylor Swift was back at Arrowhead Stadium on Monday night, and sitting alongside Tom Cruise, to watch new husband Travis Kelce and his Kansas City Chiefs open the NFL season against the Denver Broncos.
It was the first time Swift has seen Kelce play since they were married over the summer.
The 14-time Grammy Award winner decided to skip the Emmy Awards in Los Angeles, though it wasn't necessarily a big surprise. Even though "The Eras Tour: The Final Show" was nominated for outstanding variety special (pre-recorded), the category winner already was announced at the Creative Arts Emmys earlier this month, with "The Muppet Show" taking top honors.
The Emmys had fun with the possibility of Swift's attendance, airing a recorded bit where the "Law & Order: Special Victims Unit" cast, led by host Mariska Hargitay, is trying to figure out whether she will be there. Swift herself appears at the end, though not as herself.
"Maybe she'll do one those cool, pre-taped sketch things to support the host," Swift's character says.
#emmys #time

22 days ago
Rookie defensive back Mansoor Delane is questionable to return to the Kansas City Chiefs' Week 1 matchup against the Denver Broncos on 'Monday Night Football' after sustaining a shoulder injury in the first quarter of the primetime tilt.
Delane joined Kansas City as the No. 6 overall pick in the first round of the 2026 NFL Draft and recorded his first career interception in front of a national audience on the game's first drive, which gave the Chiefs an early advantage over Denver.
The Chiefs shared an official update on Delane's status in a post to their official Twitter account:
While it remains unclear if Delane will be able to return to the field in Week 1, Chiefs defensive coordinator Steve Spagnuolo is already adjusting his scheme to account for the former LSU Tiger's absence.
Stay tuned to find out if Delane's absence will prove to be temporary, or if the rookie defender will need to miss games due to his shoulder injury.
#kansas #city #rookie #defensive

22 days ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda