6 mins. ago
Intel sold control of Altera last year. Now the programmable-chip company is heading back toward the public market just as AI gives investors a new reason to care about FPGAs.
Altera said on September 15 that it confidentially filed for a U.S. IPO. Reuters previously reported that the offering could raise more than $2 billion. Silver Lake owns 51% after investing $4.46 billion for control, while Intel Corporation (NASDAQ:INTC) retains 49%.
Intel Corp.'s headquarters, the Robert Noyce Building in Santa Clara, California. Photo from Intel Corp website
The most useful strategic comparison is Advanced Micro Devices, Inc. (NASDAQ:AMD), which bought FPGA leader Xilinx in 2022 and integrated programmable silicon into a much broader data-center portfolio.
Intel bought Altera for $16.7 billion in 2015 before separating the business and selling control to Silver Lake. An IPO would create a new market valuation for Intel Corporation's (NASDAQ:INTC) remaining interest.
#corp
7 mins. ago
When AI stocks rebounded last week, optical networking companies did not rebound equally.
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
8 mins. ago
Former Intel CEO Pat Gelsinger is backing a startup that thinks AI's next bottleneck is not the accelerator. It is everything waiting for data to arrive.
Delos Data announced on September 15 that it raised more than $100 million to develop networking chips and software for increasingly heterogeneous AI data centers. Playground Global, where Gelsinger is a general partner, joined the round. Reuters reported that Delos is designing the network to work across different types of compute hardware rather than **** uming every accelerator comes from NVIDIA Corporation (NASDAQ:NVDA).
That makes Advanced Micro Devices, Inc. (NASDAQ:AMD) an important read-through even though AMD is not an investor in Delos.
For illustration purposes only. Photo by Brett Sayles on Pexels
Nvidia does not dominate AI simply because its GPUs are fast. NVIDIA Corporation (NASDAQ:NVDA) sells a tightly integrated system of accelerators, networking, interconnects and software. That makes large clusters easier to deploy and gives customers fewer reasons to mix architectures.
#delos #data #Networking #software

12 mins. ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ

13 mins. ago
Vista Gold Corp. (NYSEAMERICAN:VGZ) announced on September 21 that it had agreed to be acquired by Artemis Gold Inc. (TSXV:ARTG). Under the agreement signed September 20, shareholders would receive 0.0966 buyer common shares for each existing common share and own approximately 5% of the combined company. That ownership calculation excludes the buyer's existing 4.95% stake in Vista Gold Corp. (NYSEAMERICAN:VGZ), which it intends to cancel at completion.
For shareholders, the trade-off is a smaller interest in a larger mining business with an operating ***** et and development expertise. The central question is whether that combination can supply the capital and execution needed to bring Australia's Mt Todd gold project into production.
Artemis Gold Inc. (TSXV:ARTG) operates the Blackwater mine in British Columbia and expects its future cash generation to support Mt Todd. That offers Vista Gold a potential funding source alongside a team experienced in building and operating mines.
The financial starting point explains the appeal. Vista Gold Corp. (NYSEAMERICAN:VGZ) ended June 2026 with $49.5 million in cash and no debt. Management described that cash as sufficient for interim development objectives. Joining an operating producer could broaden the resources available for the much larger task of construction.
The acquisition requires no cash consideration or new acquisition debt. Preserving the buyer's financial capacity could leave more room for investment, although the share exchange itself does not raise construction funding.
#cash

15 mins. ago
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) announced on September 21 a services agreement worth more than $700 million with La Compagnie du TransGuinéen. Combined with locomotive orders placed in 2024, announced agreements for the Simandou project now exceed $1.2 billion.
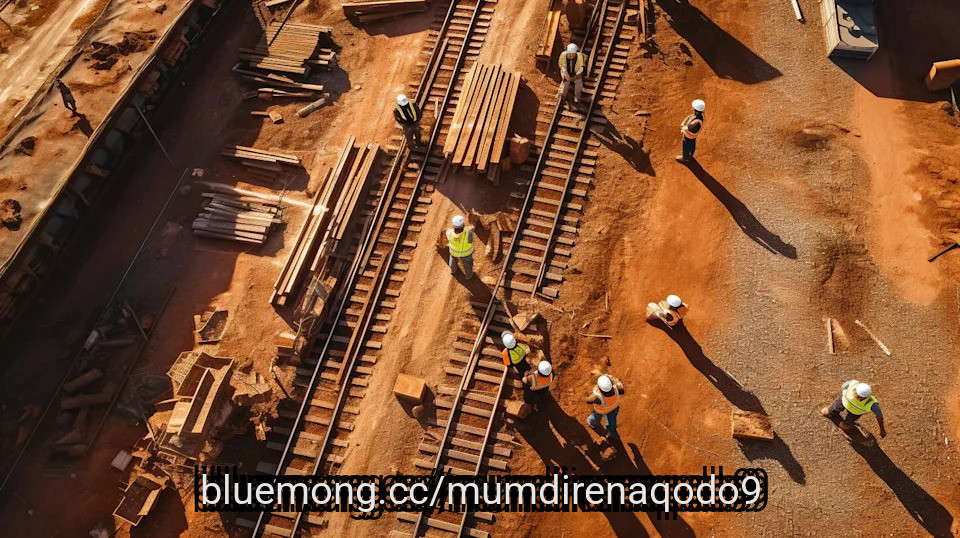
The railway stretches more than 600 kilometers between the Simandou mine and Guinea's Port of Morebaya. The new agreement extends the relationship beyond locomotive delivery into ongoing fleet support. For investors, the opportunity is to earn revenue throughout the equipment's operating life.
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) will provide scheduled and unscheduled maintenance, parts, component overhauls, logistics support, remote diagnostics, and training. These activities create multiple opportunities to serve the same fleet after the initial equipment sale.
That is an attractive business model when maintenance needs translate into repeat orders and efficient service delivery. Familiarity with the locomotives should help technicians diagnose problems and plan repairs. Remote monitoring could also help identify faults before they cause prolonged downtime, strengthening the customer's incentive to maintain the relationship.
Local workforce development and partnerships with Guinean businesses could improve responsiveness as the operation matures. Over time, an experienced local team could reduce dependence on specialists traveling to the site and make parts planning more efficient.
#westinghouse #brake #agreement

16 mins. ago
CBS Photo Archive / CBS via Getty Images
Evening Standard / Getty Images
Even wilder, Beatles insider Chris O'Dell says she was actually sitting at Ringo's kitchen table when George finally told him, "I'm in love with your wife." According to O'Dell, Ringo responded, "Better you than someone we don't know." O'Dell said Ringo was nevertheless heartbroken by what happened. (Ringo got remarried in 1981 to Bond girl Barbara Bach, so he's doing alright!)
Somehow, George and Ringo's friendship survived and they worked together many more times (notably on the Beatles' reunion tracks "Free as a Bird," "Real Love," and "Now and Then.") When George died in 2001, Ringo called him "a best friend of mine," adding, "I loved him very much."
Vinnie Zuffante / Getty Images
#images #archive


7 days ago
IonQ (IONQ) is a quantum computing company whose stock has been a favorite among speculative buyers and high-volatility traders, thanks to its high beta (3.30 over the last 60 months) and news-driven price action. It's not uncommon to see the stock swinging by double-digit percentages around news, earnings, partnership announcements, or sector sentiment shifts.
But today, we have a rare event.
Domino's Pizza Stock Is Dirt Cheap, With 30% Potential Upside - What's the Best Play?
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
IonQ, the volatile quantum stock, is now sitting at 0% IV rank. That means options on IONQ are priced much cheaper than they have been historically, creating an opportunity to go long.
#quantum #high #pizza #best


7 days ago
On September 17, shares of Marvell Technology, Inc. (NASDAQ:MRVL) and GLOBALFOUNDRIES Inc. (NASDAQ:GFS) moved sharply higher, with Marvell Technology, Inc. (NASDAQ:MRVL) gaining more than 4% and GLOBALFOUNDRIES Inc. (NASDAQ:GFS) rising more than 6% by the end of the trading session.
Reuters reported that the two companies have expanded their agreement to increase production capacity for silicon germanium (SiGe), a semiconductor technology used in high-speed optical connections for data centers. The multi-year agreement will expand capacity for GLOBALFOUNDRIES Inc.'s (NASDAQ:GFS) SiGe technology at its facility in Burlington, Vermont. SiGe allows semiconductor devices to operate at higher speeds while using less energy, making it increasingly important as data centers handle larger volumes of data.
Robb Johnson, Vice President, Foundry Technology at Marvell Technology, Inc. (NASDAQ:MRVL) said the expanded collaboration will help ensure that the company has the "SiGe technology and manufacturing capacity to support the significant growth" it expects ahead.
According to the report, the increased manufacturing capacity will help Marvell Technology, Inc. (NASDAQ:MRVL) meet growing demand for optical networking products, including pluggable optical transceivers, near-packaged optics, and co-packaged optics.
GlobalFoundries Is Seeing Strong SiGe Demand
#sige #globalfoundries #optical #data

7 days ago
By Jana Choukeir and Doina Chiacu
DUBAI/WASHINGTON, Sept 20 (Reuters) - Iran and the United States exchanged new threats on Sunday, with President Donald Trump warning Iran would fail economically or face its leadership being wiped out if it didn't make a deal, and the Iranian military saying it would retaliate harshly to any fresh attack.
The conflict has looked stalemated for months, with no sign either side was ready for concessions even as it has deepened a global energy crisis, cratered swathes of Iran's economy and spilled over into new regional escalations.
In a phone call with a Fox News reporter, Trump said Iran's leaders should make a deal, rot economically or be wiped out, the reporter said.
However, with Iran's President Masoud Pezeshkian expected in New York this week for the United Nations General ***** embly, Trump said he would be open to meeting him, the Fox reporter added.
#reporter #Iran #make
7 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
7 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high
7 days ago
For the past couple of decades, the so-called "American Dream" has followed a pretty linear pathway. You finish high school, go to a four-year university, and then graduate straight into a corporate office that comes with a slick 401(k).
That bachelor's degree was the golden ticket that made everything possible, and your parents probably told you that earning a diploma was critical to your success, right? Well, new labor market data has turned that decades-old playbook upside down.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#firm #jensen

7 days ago
Just over a year ago, investors largely viewed IREN (IREN) as a bitcoin mining company. Today, the company supplies AI infrastructure to Microsoft (MSFT) and signs billion-dollar contracts with some of the biggest names in the AI market, including Nvidia (NVDA) and Dell Technologies (DELL). These developments provide evidence that IREN's shift toward AI infrastructure is translating into actual business activity, and the market has responded strongly to that progress. IREN shares have been rewarded with two strong moves over the last two months.
IREN's AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
JPMorgan Changed Its Mind on Meta Stock After This Major AI Breakthrough
#NVIDIA

8 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
8 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

8 days ago
With a market cap of $19.5 billion, Best Buy Co., Inc. (BBY) is a leading technology retailer focused on enriching lives through technology by combining tech expertise with personalized customer service. The company serves customers through its online platform, stores, and in-home services, addressing a wide range of everyday technology needs.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Best Buy fits this criterion perfectly. Best Buy operates more than 1,000 stores across the United States and Canada and employs more than 85,000 people.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#stores #known



8 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
8 days ago
When Christmas rolls around, my wife puts out a very small tree and some stuffed ornaments we bought a few years ago at Target. That's a pretty modest approach to decorating for the holidays compared to many of our neighbors.
At the house we just moved out of, some homes added tasteful lights, others opted for religious displays, and a few opted for a whole lot of inflatables. In some cases, the spending was significant, although many of the items were reused year after year.
Decorations are a small but meaningful part of holiday spending.
Americans planned to spend an average of $1,172 on travel, $632 on gifts, $351 on entertaining, and $227 on decorations, according to a BMO survey conducted before the 2024 holiday season.
Getting those items may be more of a challenge this year, as Gordon Companies, which runs a number of Christmas-themed websites and lists Target, Kohl's, Home Depot, Walmart, Amazon, Lowe's, and Michaels as retail partners, has filed for Chapter 11 bankruptcy.
#christmas #decorations #opted #items
8 days ago
On the Sept. 3, 2026 episode of The Ramsey Show, a Houston caller named Nathan asked whether he should use his savings to clear a mortgage he described as a "whatever, 2% mortgage or something." He had about $280,000 left on it and roughly $346,000 in liquid ******* ets, most of it cash and the rest in a taxable brokerage account. Dave Ramsey told him to do it, and to do it that night.
Five months earlier, Ramsey had told a caller in almost the same position the opposite. On April 1, 2026, a web engineer earning around $600,000 a year called in about three weeks after being laid off, sitting on enough cash to clear a San Francisco, California mortgage. "When you're in the middle of a storm, you do temporary things," Ramsey said. "Hold on to the cash. We're not gonna pay off the house because we may not be staying in the house."
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#mortgage #told

8 days ago
Today, I'm kicking off a new risk management series here at Barchart called "Look Both Ways Before You Cross Wall Street."
Instead of hitting you with my topical trade ideas, I'll get a little more nitty-gritty and into the weeds – explaining the what, why, how, and the real risk/reward math you need to know as a DIY manager of your own wealth.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#look


8 days ago
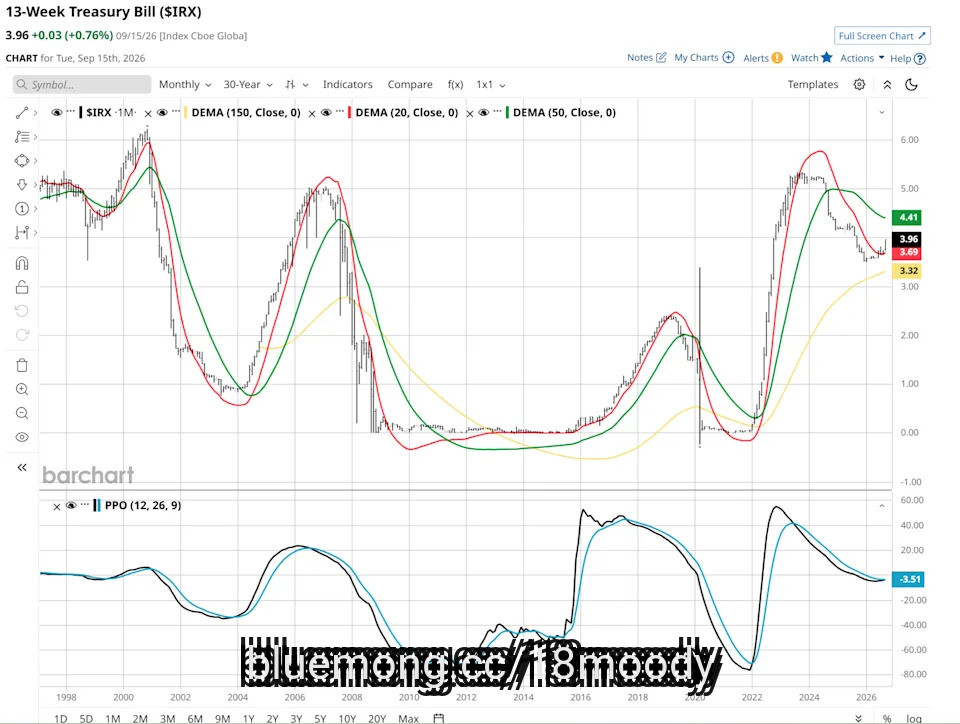
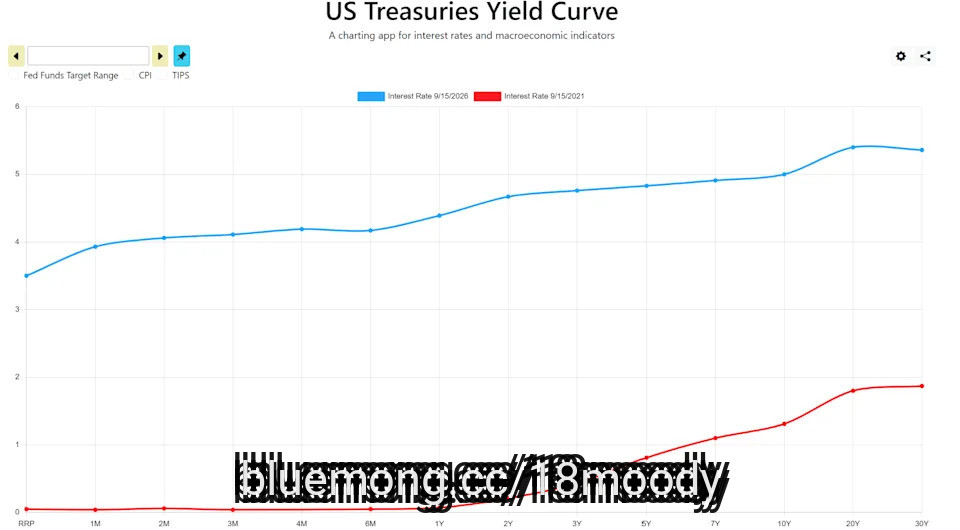
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
8 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
8 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited

8 days ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
8 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
8 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

8 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

8 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
8 days ago
On September 9, 2026, Reuters reported that Stellantis N.V. (NYSE:STLA) is recalling 201,976 Jeep vehicles in the U.S., including certain Grand Cherokee, Wagoneer and Grand Wagoneer models. It happened after the National Highway Traffic Safety Administration found a software error that can prevent the tire-pressure monitoring system from detecting low tire pressure or alerting the driver, raising crash risk.
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software