2 mins. ago
Now that football season has returned, so has the season of tracking the sizes of the TV audiences for football games.
The first of 283 games that count in the 2026 season — a Super Bowl LX rematch between the Patriots and Seahawks — averaged 25.1 million viewers.
The good news is that the season-opening game has exceeded 25 million viewers for four straight years, matching the same run from 2013 through 2016. The bad news is that, via Manny Soloway of Awful Announcing, the number fell 12 percent from last year's 28.3 million who watched the Eagles host the Cowboys, and it was the lowest since 2022.
It's fair to wonder whether the dip had anything to do with the season starting on a Wednesday. The last Wednesday night Week 1 kickoff game happened in 2012, with the Cowboys-Giants game generating 23.9 million viewers. In contrast, the Thursday night opener the prior year, between the Saints and Packers, drew 27.2 million.
That's odd, to say the least. The Cowboys were (and still are) the Cowboys. And the Giants — in the nation's top media market — had just won the Super Bowl. It's lower number than would have been expected, and it could have had something to do with Wednesday vs. Thursday.
#wednesday #viewers #super #thursday
The first of 283 games that count in the 2026 season — a Super Bowl LX rematch between the Patriots and Seahawks — averaged 25.1 million viewers.
The good news is that the season-opening game has exceeded 25 million viewers for four straight years, matching the same run from 2013 through 2016. The bad news is that, via Manny Soloway of Awful Announcing, the number fell 12 percent from last year's 28.3 million who watched the Eagles host the Cowboys, and it was the lowest since 2022.
It's fair to wonder whether the dip had anything to do with the season starting on a Wednesday. The last Wednesday night Week 1 kickoff game happened in 2012, with the Cowboys-Giants game generating 23.9 million viewers. In contrast, the Thursday night opener the prior year, between the Saints and Packers, drew 27.2 million.
That's odd, to say the least. The Cowboys were (and still are) the Cowboys. And the Giants — in the nation's top media market — had just won the Super Bowl. It's lower number than would have been expected, and it could have had something to do with Wednesday vs. Thursday.
#wednesday #viewers #super #thursday



6 mins. ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue

13 mins. ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


15 mins. ago
On September 10, IBEX Limited (NASDAQ:IBEX) held its fourth-quarter and full fiscal year 2026 earnings call, and the numbers backed up a message management has been building toward for months. The company posted record full-year revenue, adjusted EBITDA, and free cash flow, all while pitching itself as a business that has flipped the AI narrative in its favor rather than becoming its next casualty. For a sector that has spent the last two years bracing for automation to gut it, that is a notable claim to back with actual client wins.
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth
Full-year revenue hit $644.1 million, up 15.4% organically, and fourth-quarter revenue reached $164.3 million, up 11.6% from a year earlier. That marked the sixth straight quarter of double-digit growth, a streak that suggests the momentum is not a one-off. HealthTech led the charge, climbing 38.5% to $114 million for the year and blowing past the $100 million target management had set for the segment, driven largely by demand from large insurance payers. Technology grew 27.4% in the quarter, while travel and logistics added 17.8%, helped by a new AI agent partnership with Philippine Airlines.
That Philippine Airlines deal is the clearest evidence that IBEX's Sierra AI partnership, formalized in January and announced publicly in May, is more than a slide in an investor deck. During the proof of concept, the AI agent handled interactions in English, Tagalog, and Taglish, hit resolution rates above 20%, and scored a 4.7 out of 5.0 on customer satisfaction, on par with human agents. A separate deployment for BJ's Wholesale pushed resolution rates above 40% and matched that same satisfaction score, beating the marks the client's prior BPO vendor had put up with human agents alone. The company added 17 new trophy logo clients across the year, and its top five clients now make up 33% of revenue, down from 36%, a sign the business is not leaning on a shrinking handful of accounts to carry it.
Not every line moved in the right direction. Fourth quarter GAAP net income slipped to $8.7 million from $9.6 million a year earlier, and diluted EPS fell to $0.59 from $0.66. Management pointed to training costs tied to all those new client wins, a temporary hit from shifting work out of nearshore centers into offshore ones, and higher fuel prices hitting utility and transportation costs, particularly offshore. Adjusted EBITDA margin for the quarter slipped to 12.3% from 13.9%, the same set of pressures showing up in the profitability line rather than just net income.
#revenue #fourth


20 mins. ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


24 mins. ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal


28 mins. ago
On September 10, MasterCraft Boat Holdings (NASDAQ:MCFT) reported a fiscal fourth quarter that looked nothing like the one a year earlier. Adjusted EBITDA more than doubled, margins expanded across the legacy business, and the company closed out a year defined by its May 15 acquisition of Marine Products Corporation. But buried inside those same results was a $10.1 million writedown that tells a very different story about one corner of the business.
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy
MasterCraft's core boat business is the reason the quarter worked at all. Legacy net sales, meaning the business before the acquisition, climbed 21.5% year over year to $96.6 million in the fourth quarter, powered by the next generation X Series lineup and less discounting at the dealer level. That combination of volume and pricing pushed legacy adjusted EBITDA margin up 730 basis points to 19.3%, up from 12% a year earlier. Once the newly acquired Chaparral and Robalo brands are added in, which contributed for only six weeks after the deal closed on May 15, consolidated fourth quarter net sales reached $129.9 million, up 63.4%, and adjusted EBITDA hit $20.5 million, up 114.9%.
The company also cleaned up its channel. Dealer field inventory for the legacy business fell 30% year over year, with turnover now running ahead of pre-pandemic levels, a sign dealers are selling boats rather than sitting on them. Full-year adjusted net income reached $30.2 million, or $1.76 per diluted share, up from $15.1 million, or $0.92 per share, in fiscal 2025. The company generated $22.3 million in free cash flow for the year and, as of June 30, held $43.9 million in cash, zero debt, and a fully available $75 million credit line. MasterCraft's own retail sales grew low single digits for the year even as the broader powerboat industry fell mid to high single digits, and the newer Robalo brand posted high single-digit retail growth in the fishing boat category.
The picture gets murkier once you look past the flagship brand. The Leisure segment, home to the Crest and Balise pontoon boats, saw fourth-quarter sales fall 11.2% year over year to $12.1 million, and the company booked a $10.1 million non-cash impairment against Crest brand ******* ets tied to what management called current category conditions. On a GAAP basis, that charge combined with acquisition costs and purchase accounting adjustments turned the quarter into a net loss of $7 million, or $0.35 per diluted share, compared to net income of $5.5 million a year earlier. Operating expenses rose $23.1 million in the quarter, including $5.9 million in transaction costs tied to the acquisition.
#million #legacy

30 mins. ago
On September 10, Tsakos Energy Navigation (NYSE:TEN) reported a first half of 2026 that reads like a fantasy year for a decades-old tanker operator. Net income hit $228 million, more than triple what the company earned over the same six months a year earlier, while diluted EPS climbed to $7.12 from $1.70. Behind those numbers sits a rare combination: a fleet locked into billions in forward earnings, war-driven cargo detours pushing rates higher, and a newbuilding bet that has already paid off before half the ships have even hit the water.
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion
The earnings power came from two directions at once. The average time charter equivalent rate rose 41% to $43,503 a day in the first half, and profit-sharing contracts on nine large vessels brought in $71 million, up from just $10 million a year earlier. Even with six vessels pulled from service for scheduled dry docks, the fleet still ran at 96.5% utilization. Second-quarter results followed the same pattern, with net income of $139.3 million, which included a $38 million gain on ******* et sales, and earnings per share of $4.40 against $0.67 in last year's second quarter.
Tsakos is also sitting on a fleet renewal bet that already worked out. Since the start of 2023, the company has sold 20 tankers averaging 17.3 years old and replaced them with 35 vessels averaging just half a year old. Its 26-ship newbuilding program, contracted for about $3.1 billion, is now valued roughly 30% above that cost, and CEO Nikolas Tsakos said the VLCCs in that order book have nearly doubled in price since they were placed. With $466 million in cash and forward committed earnings of roughly $3.5 billion, management has room to raise its dividend, which already paid out $1.60 per share this year, and is weighing whether to redeem $120 million of 9.25% preferred shares, a move it estimates could add $0.30 to $0.40 to EPS.
That performance came against a backdrop the company would rather not have. President George Saroglou said vessels have been attacked, and seafarers hurt or killed trying to keep global trade moving through the Strait of Hormuz, where a ceasefire unraveled roughly halfway through its planned 60-day run and a US naval presence now tries to manage safe passage. Tsakos has chosen to route around the strait entirely rather than put crews through the toll those attacks take.
The cost side is climbing too. Bunker prices jumped about 25%, pushing first-half voyage expenses to $82 million from $68 million, and operating expenses rose to $111 million from $102 million on higher dry-docking costs and inflation. Total debt reached $2.1 billion at the end of June, up from $1.8 billion a year earlier, as the company finances its newbuilding program. And while profit-sharing revenue jumped, the operating days tied to those market-related contracts actually fell 22%, meaning a smaller slice of the fleet is left exposed to capture further spot-rate gains if the tanker market keeps running hot.
#billion

53 mins. ago
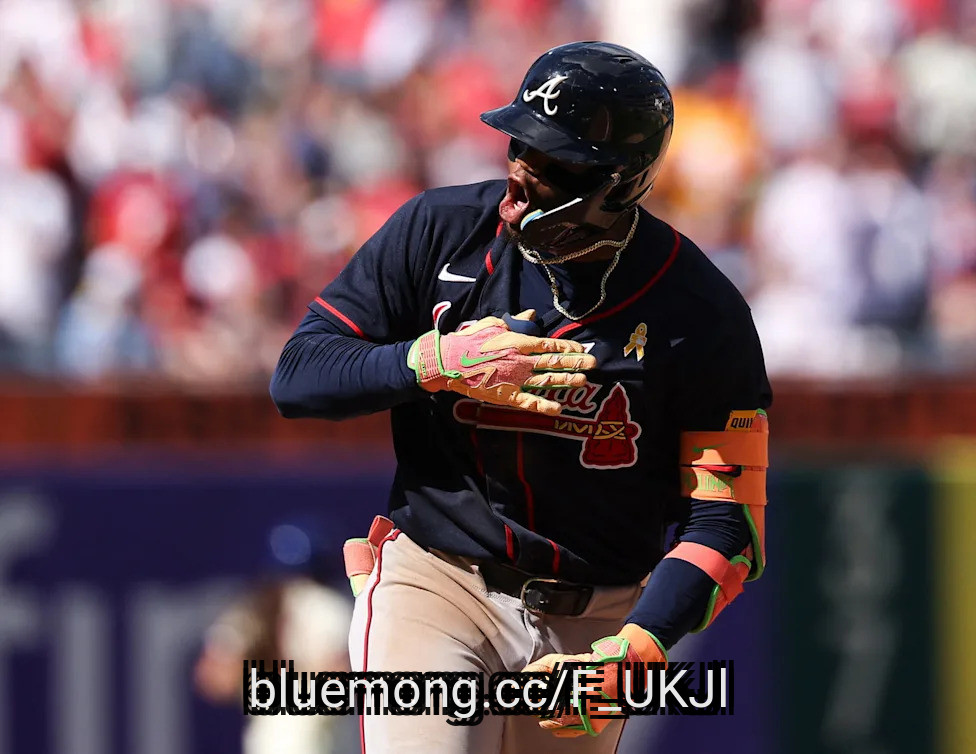
Since his debut in 2018, Ronald Acuña Jr. has been one of baseball's most exciting players. His power-speed combo has made him one of the sport's best players. In 2019, Acuña fell just short of the elusive 40/40 club. In 156 games, he tallied 41 home runs and 37 stolen bases, which led the National League.
He was on an MVP trajectory in 2021. In 82 games that season, Acuña had a .990 OPS with 24 home runs and 17 stolen bases. Unfortunately, everything changed on July 10 when he tore his ACL attempting to make a leaping catch at the wall down in Miami. During his first three and a half seasons, Acuña was on the fast track to the Hall of Fame. His injury not only slowed that down, but it also raised questions about whether he'd ever be the same again.
The Braves eventually won the World Series, but Acuña was sidelined and could only celebrate from the dugout. Still, though, he received a World Series ring on Opening Day in 2022. He would return to action on April 28 against the Chicago Cubs. However, it was clear that Acuña wasn't the same player. In 119 games, he only hit 15 home runs, and his OPS dropped to .764—the worst mark of his career. It seemed he would never be the same again, but Acuña quieted the doubters with one of the greatest individual seasons in MLB history.
Acuña didn't just make history; the Braves did, too. In 2023, Atlanta finished with the best record in MLB (104-58). That year, they tied the MLB record for home runs in a season (307). Three players, including Acuña (41), hit at least 40 home runs that season. In 2023, MLB also made a slew of rule changes, including making the bases 18 inches. The extra three inches, along with the new pickoff rule, were meant to influence more action on the base paths.
Acuña took full advantage by stealing 73 bases that season. In the process, he became the first, and only, player to hit at least 40 home runs and steal at least 70 bases. Along the way, he also became the first and only player to hit at least 30 home runs and steal at least 60 bases.
#home #least
He was on an MVP trajectory in 2021. In 82 games that season, Acuña had a .990 OPS with 24 home runs and 17 stolen bases. Unfortunately, everything changed on July 10 when he tore his ACL attempting to make a leaping catch at the wall down in Miami. During his first three and a half seasons, Acuña was on the fast track to the Hall of Fame. His injury not only slowed that down, but it also raised questions about whether he'd ever be the same again.
The Braves eventually won the World Series, but Acuña was sidelined and could only celebrate from the dugout. Still, though, he received a World Series ring on Opening Day in 2022. He would return to action on April 28 against the Chicago Cubs. However, it was clear that Acuña wasn't the same player. In 119 games, he only hit 15 home runs, and his OPS dropped to .764—the worst mark of his career. It seemed he would never be the same again, but Acuña quieted the doubters with one of the greatest individual seasons in MLB history.
Acuña didn't just make history; the Braves did, too. In 2023, Atlanta finished with the best record in MLB (104-58). That year, they tied the MLB record for home runs in a season (307). Three players, including Acuña (41), hit at least 40 home runs that season. In 2023, MLB also made a slew of rule changes, including making the bases 18 inches. The extra three inches, along with the new pickoff rule, were meant to influence more action on the base paths.
Acuña took full advantage by stealing 73 bases that season. In the process, he became the first, and only, player to hit at least 40 home runs and steal at least 70 bases. Along the way, he also became the first and only player to hit at least 30 home runs and steal at least 60 bases.
#home #least

1 hr. ago
The Chargers suffered a brutal Week 1 loss to the Cardinals on Sunday, 26-14.
Los Angeles was flat for most of the contest and was outplayed in all three phases. The Cardinals were the more prepared and physical team in the season opener, and the Chargers fell flat on their face.
It was evident, especially in the second half. While many Chargers were unhappy with their performance, tight end Charlie Kolar offered a blunt ****** sment.
Kolar spoke to the media after the game and didn't hold back after the game.
"Just not good enough, plain and simple," Kolar said.
#chargers #kolar #cardinals
Los Angeles was flat for most of the contest and was outplayed in all three phases. The Cardinals were the more prepared and physical team in the season opener, and the Chargers fell flat on their face.
It was evident, especially in the second half. While many Chargers were unhappy with their performance, tight end Charlie Kolar offered a blunt ****** sment.
Kolar spoke to the media after the game and didn't hold back after the game.
"Just not good enough, plain and simple," Kolar said.
#chargers #kolar #cardinals

2 hours ago
"WWE Raw" is in Mexico City at Arena CDMX this Monday, Sept. 14, following AAA TripleMania weekend. After winning his way through WWE's No. 1 contender luchador tournament, Penta finally gets his shot at the World Heavyweight Champion Roman Reigns in a true spectacle match for the promotion's weekly programming.
Reigns has been embroiled in matters between Solo Sikoa and LA Knight as of late, but his next challenger is former the Intercontinental Champion. South American wrestling fans have already been treated to plenty of excitement over the past week, as WWE delivered a surprise ******* le change when Stephanie Vaquer dethroned Women's World Champion Liv Morgan in her home of Chile. Penta will look to do the same tonight.
Speaking of Intercontinental Champions, the man who dethroned Penta, Chad Gable, will defend his crown tonight against Dragon Lee. Gable has consistently shown respect for luchadors since returning from his run as El Grande Americano. Considering the chemistry he's had with all involved, this match is sure to deliver.
More Money In the Bank qualifier matches are also set to take place on "Raw." On the men's side, Je'Von Evans and Big Cass go at it once again, this time with World Tag Team Champion Austin Theory in the mix. The women's match will feature the debuting Lola Vice, as she battles fellow former NXT star Kelani Jordan and the current Women's Intercontinental Champion Raquel Rodriguez.
Check out the full "WWE Raw" lineup below, which starts at 8 p.m. ET on Netflix:
#penta #intercontinental #match #gable
Reigns has been embroiled in matters between Solo Sikoa and LA Knight as of late, but his next challenger is former the Intercontinental Champion. South American wrestling fans have already been treated to plenty of excitement over the past week, as WWE delivered a surprise ******* le change when Stephanie Vaquer dethroned Women's World Champion Liv Morgan in her home of Chile. Penta will look to do the same tonight.
Speaking of Intercontinental Champions, the man who dethroned Penta, Chad Gable, will defend his crown tonight against Dragon Lee. Gable has consistently shown respect for luchadors since returning from his run as El Grande Americano. Considering the chemistry he's had with all involved, this match is sure to deliver.
More Money In the Bank qualifier matches are also set to take place on "Raw." On the men's side, Je'Von Evans and Big Cass go at it once again, this time with World Tag Team Champion Austin Theory in the mix. The women's match will feature the debuting Lola Vice, as she battles fellow former NXT star Kelani Jordan and the current Women's Intercontinental Champion Raquel Rodriguez.
Check out the full "WWE Raw" lineup below, which starts at 8 p.m. ET on Netflix:
#penta #intercontinental #match #gable


2 hours ago
NEW YORK – If there's anyone who knows how to command a room, it's Nene Leakes.
The "Real Housewives" OG brought a little Atlanta to New York Fashion Week, attending Sergio Hudson's spring/summer 2027 show on Sunday, Sept. 13. Hudson brought the glamour to NYFW, hosting his show at one of New York's most iconic venues — the Rainbow Room.
Guests including Mickey Guyton, Muni Long and Sunny Hostin ventured to top of Rockefeller Center for Hudson, but it was Leakes who stole the show. The "Real Housewives of Atlanta" star entered the glittering ballroom moments before the first model took to the runway, but that didn't stop a swarm of photographers and fans from trying to get a snap of the Bravo star. Leakes took her seat next to "Beauty in Black" actress Crystle Stewart as the two posed for front-row photos.
Leakes showed off a classic Hudson creation, donning a bodycon little black dress from the designer's fall-winter '24 collection. The sleeveless LBD featured an extra-long gold zipper extending from the neckline to the hem. The reality star styled the look with black patent pumps and a gold-embellished clutch.
"Me and Nene go way back … When I met her, I was a little ****** ody, and she always treated me really well, so I take care of her, 'cause she always took care of me," Hudson told USA TODAY backstage after his show. "She's a superstar."
#leakes #nene
The "Real Housewives" OG brought a little Atlanta to New York Fashion Week, attending Sergio Hudson's spring/summer 2027 show on Sunday, Sept. 13. Hudson brought the glamour to NYFW, hosting his show at one of New York's most iconic venues — the Rainbow Room.
Guests including Mickey Guyton, Muni Long and Sunny Hostin ventured to top of Rockefeller Center for Hudson, but it was Leakes who stole the show. The "Real Housewives of Atlanta" star entered the glittering ballroom moments before the first model took to the runway, but that didn't stop a swarm of photographers and fans from trying to get a snap of the Bravo star. Leakes took her seat next to "Beauty in Black" actress Crystle Stewart as the two posed for front-row photos.
Leakes showed off a classic Hudson creation, donning a bodycon little black dress from the designer's fall-winter '24 collection. The sleeveless LBD featured an extra-long gold zipper extending from the neckline to the hem. The reality star styled the look with black patent pumps and a gold-embellished clutch.
"Me and Nene go way back … When I met her, I was a little ****** ody, and she always treated me really well, so I take care of her, 'cause she always took care of me," Hudson told USA TODAY backstage after his show. "She's a superstar."
#leakes #nene



3 hours ago
Rory McKenzie "can feel the pain" of fellow Kilmarnock fans, especially as the 32-year-old midfielder fears Saturday's Scottish Cup quarter-final defeat by Aberdeen "could be the last chance I get" to play at Hampden Park again.
Having held the Dons to a goalless draw in their previous game in the Scottish Premiership, Kilmarnock failed to take advantage of the visitors being reduced to 10 men and exited after a penalty shoot-out.
"I'm a fan, I feel it," McKenzie, who made his debut for the Ayrshire club in 2011, said. "One of the best days I've ever had was going to Hampden. I'm getting on in my career and it could be the last chance I get.
"Believe me, I feel their pain. I know how it feels.
"We won't get a better chance of getting to a semi-final than that. It was on a plate for us, 1-1, man sent off. We just failed to capitalise and didn't play with enough intensity.
#chance #mckenzie #kilmarnock #play
Having held the Dons to a goalless draw in their previous game in the Scottish Premiership, Kilmarnock failed to take advantage of the visitors being reduced to 10 men and exited after a penalty shoot-out.
"I'm a fan, I feel it," McKenzie, who made his debut for the Ayrshire club in 2011, said. "One of the best days I've ever had was going to Hampden. I'm getting on in my career and it could be the last chance I get.
"Believe me, I feel their pain. I know how it feels.
"We won't get a better chance of getting to a semi-final than that. It was on a plate for us, 1-1, man sent off. We just failed to capitalise and didn't play with enough intensity.
#chance #mckenzie #kilmarnock #play

3 hours ago
Cowboys news: Dallas praying Malik Hooker's injury isn't as bad as it could be after Week 1 debacle appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
On Sunday evening, the Dallas Cowboys kicked off their season with an ugly 28-20 road loss to the New York Giants. The Cowboys' new-look defense, which had received considerable hype from fans and pundits alike heading into this year, fell flat on its face in this one, finding itself unable to get off the field in the second half against New York.
Things went from bad to worse when Malik Hooker went down with an injury, and on Monday, the team got the latest update on his potential recovery process.
"#Cowboys S Malik Hooker fractured a bone in his forearm and he's consulting with a hand specialist to learn his recovery time, sources say. While some breaks can mean a player is out six weeks, the hope is based on the specific bone and break, it's quicker than that," reported NFL insider Ian Rapoport of the NFL Network on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#cowboys #recovery
On Sunday evening, the Dallas Cowboys kicked off their season with an ugly 28-20 road loss to the New York Giants. The Cowboys' new-look defense, which had received considerable hype from fans and pundits alike heading into this year, fell flat on its face in this one, finding itself unable to get off the field in the second half against New York.
Things went from bad to worse when Malik Hooker went down with an injury, and on Monday, the team got the latest update on his potential recovery process.
"#Cowboys S Malik Hooker fractured a bone in his forearm and he's consulting with a hand specialist to learn his recovery time, sources say. While some breaks can mean a player is out six weeks, the hope is based on the specific bone and break, it's quicker than that," reported NFL insider Ian Rapoport of the NFL Network on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#cowboys #recovery


4 hours ago
A woman who found hairs in her Aldi dip has said she was disappointed the company included an AI prompt in its reply when she complained.
Jo Reeves from Cotteridge in Birmingham said she found the "vile" hairs when she popped out for a snack, while her partner was in hospital.
The AI prompt included the phrase: "Make it short and concise but do not overdo it" and Reeves said: "Everyone uses AI but the language is disappointing as a customer.
An Aldi spokesperson said: "This response fell well below our normal standards of customer service. We have contacted Ms Reeves directly to apologise and fully resolve the issue she had with our product."
Reeves said: "My partner was having an op in Worcester hospital so popped to the local Aldi to get 'recovery food'."
#hairs
Jo Reeves from Cotteridge in Birmingham said she found the "vile" hairs when she popped out for a snack, while her partner was in hospital.
The AI prompt included the phrase: "Make it short and concise but do not overdo it" and Reeves said: "Everyone uses AI but the language is disappointing as a customer.
An Aldi spokesperson said: "This response fell well below our normal standards of customer service. We have contacted Ms Reeves directly to apologise and fully resolve the issue she had with our product."
Reeves said: "My partner was having an op in Worcester hospital so popped to the local Aldi to get 'recovery food'."
#hairs


5 hours ago
Anthropic CEO Dario Amodei published an essay on Saturday asking the companies that build the most capable artificial intelligence (AI) models to slow down -- to pace how fast those models improve. Stock futures fell Sunday evening as investors weighed AI safety concerns, with Nasdaq futures falling the most.
Nvidia (NASDAQ:NVDA) shares had already dropped about 5% last week, to about $218 as of this writing, before the essay came out. The chipmaker's own forecast calls for $108.0 billion of revenue this quarter.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Does a paced frontier change what Nvidia can sell, or only how fast models improve? I read the essay over the weekend. Nothing in it asks anyone to buy fewer chips.
Image source: Getty Images.
#essay #fast
Nvidia (NASDAQ:NVDA) shares had already dropped about 5% last week, to about $218 as of this writing, before the essay came out. The chipmaker's own forecast calls for $108.0 billion of revenue this quarter.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Does a paced frontier change what Nvidia can sell, or only how fast models improve? I read the essay over the weekend. Nothing in it asks anyone to buy fewer chips.
Image source: Getty Images.
#essay #fast

6 hours ago
Azure crossed $100B annually with 43% growth, and Microsoft's commercial backlog surged 84% to $678B, explaining why markets shrugged off AI safety calls.
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning
Progressive fell 5% and Sherwin-Williams dropped 12% over the past year as housing starts slid 12% and consumer sentiment hit a recessionary 55.
Trump's 'whoever wins, AI wins' framing directly counters Manchin's push for an executive order freezing AI IPOs until federal safeguards are established.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Microsoft didn't make the cut. Enter your email to see the names that beat MSFT. The report is free. Enter your email and see if any of your stocks made the cut.
Monday morning, hours after public radio spent its morning walking through an open letter asking the AI industry to slow itself down, President Trump told CNBC the opposite: "We're leading China in AI. We're the most sophisticated country in the world. And frankly, I want to keep it that way because whoever wins, AI wins." Ninety minutes later, shares of Microsoft (NASDAQ:MSFT) were changing hands at $498.70, and Polymarket bettors were pricing 84.5% odds that the stock would close green.
#msft #whoever #stocks #morning

6 hours ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Europe's AI winners spent Monday discovering how quickly momentum can work in reverse, as investors dumped the semiconductor companies most exposed to the infrastructure boom behind increasingly powerful models.
ASML lost more than 5% while French semiconductor-materials specialist Soitec fell roughly 13%, showing that the same AI exposure that had recently justified higher forecasts and valuations can become painful when investors start questioning the pace of future spending.
The sell-off followed calls from some of the most prominent figures in artificial intelligence for a more cautious pace of frontier-model development, with concerns focused on the risks created as systems become more autonomous and capable.
That was enough to trigger a global unwind in the companies most closely ****** ociated with AI infrastructure. In Europe, ASML fell about 5.2%, ASM International dropped 8.7%, Infineon lost 7.6% and Soitec was the worst performer in the Stoxx 600 with a decline of roughly 12.6%.
#asml #investors #semiconductor #fell
Europe's AI winners spent Monday discovering how quickly momentum can work in reverse, as investors dumped the semiconductor companies most exposed to the infrastructure boom behind increasingly powerful models.
ASML lost more than 5% while French semiconductor-materials specialist Soitec fell roughly 13%, showing that the same AI exposure that had recently justified higher forecasts and valuations can become painful when investors start questioning the pace of future spending.
The sell-off followed calls from some of the most prominent figures in artificial intelligence for a more cautious pace of frontier-model development, with concerns focused on the risks created as systems become more autonomous and capable.
That was enough to trigger a global unwind in the companies most closely ****** ociated with AI infrastructure. In Europe, ASML fell about 5.2%, ASM International dropped 8.7%, Infineon lost 7.6% and Soitec was the worst performer in the Stoxx 600 with a decline of roughly 12.6%.
#asml #investors #semiconductor #fell


6 hours ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Tesla Inc. (NASDAQ:TSLA) is expanding into Vietnam, establishing a local subsidiary authorized to import, distribute and sell vehicles as competition intensifies in neighboring China.
Tesla Motors Vietnam was registered in Ho Chi Minh City on Sept. 11 with roughly $3 million in charter capital, Reuters reported Monday. Tesla has not yet said when vehicle sales will begin.
Tesla's share of China's battery-electric vehicle market fell to 6.6% in the second quarter from more than 15% in 2020, according to Reuters.
Its China retail sales fell 12.4% year over year in August to 50,047 vehicles, while China's battery-electric vehicle sales edged 0.8% higher.
#tesla #sales #reuters
Tesla Inc. (NASDAQ:TSLA) is expanding into Vietnam, establishing a local subsidiary authorized to import, distribute and sell vehicles as competition intensifies in neighboring China.
Tesla Motors Vietnam was registered in Ho Chi Minh City on Sept. 11 with roughly $3 million in charter capital, Reuters reported Monday. Tesla has not yet said when vehicle sales will begin.
Tesla's share of China's battery-electric vehicle market fell to 6.6% in the second quarter from more than 15% in 2020, according to Reuters.
Its China retail sales fell 12.4% year over year in August to 50,047 vehicles, while China's battery-electric vehicle sales edged 0.8% higher.
#tesla #sales #reuters

6 hours ago
Coinbase jumped 6% on a Compass Point upgrade to Neutral, while MARA slid 2% after JPMorgan cut it to Underweight with an $11 target.
IBIT rose 1% as Bitcoin lifted crypto stocks, while SPY fell 0.8%, splitting crypto-linked equities from the broader AI-led tech selloff.
The Senate's CLARITY Act vote this week is the binary catalyst for Coinbase, though ****** yst Ed Engel expects the bill to fail.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coinbase didn't make the cut. Enter your email to see the names that beat COIN. The report is free. Enter your email and see if any of your stocks made the cut.
Coinbase Global (NASDAQ:COIN) shares are up 6% to $185.34 Monday morning after Compass Point ****** yst Ed Engel upgraded the exchange operator to Neutral from Sell ahead of a scheduled Senate floor vote on crypto market-structure legislation. The bounce for Coinbase stock trims an 18% year-to-date decline that had made the exchange one of the sector's most bruised names heading into this week.
#Coinbase #engel #vote
IBIT rose 1% as Bitcoin lifted crypto stocks, while SPY fell 0.8%, splitting crypto-linked equities from the broader AI-led tech selloff.
The Senate's CLARITY Act vote this week is the binary catalyst for Coinbase, though ****** yst Ed Engel expects the bill to fail.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coinbase didn't make the cut. Enter your email to see the names that beat COIN. The report is free. Enter your email and see if any of your stocks made the cut.
Coinbase Global (NASDAQ:COIN) shares are up 6% to $185.34 Monday morning after Compass Point ****** yst Ed Engel upgraded the exchange operator to Neutral from Sell ahead of a scheduled Senate floor vote on crypto market-structure legislation. The bounce for Coinbase stock trims an 18% year-to-date decline that had made the exchange one of the sector's most bruised names heading into this week.
#Coinbase #engel #vote


6 hours ago
The Cooper Companies, Inc. (NASDAQ:COO) cut its fiscal 2026 profit and revenue forecasts after weaker-than-expected demand for contact lenses weighed on its CooperVision business. The company now expects adjusted earnings of $4.51–$4.55 per share, down from its previous forecast of $4.58–$4.66, while revenue guidance was reduced to $4.23–$4.25 billion from $4.29–$4.32 billion. Third-quarter revenue came in at $1.07 billion, below Wall Street's $1.10 billion estimate, although adjusted EPS of $1.15 beat expectations.
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision


6 hours ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


7 hours ago
Meta jumped 7% and Nvidia dropped 8% after Amodei, Altman, and Musk publicly called for slowing frontier AI model development.
Microsoft held flat while ASML fell 10% and SoftBank dropped 11%, as markets rotated from AI hardware suppliers into enterprise software names.
With Fed rate hike odds at 85% and the 10-year yield near 5%, the rotation holds only if hyperscalers revise their massive capex plans.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Shares of Meta Platforms (NASDAQ:META) climbed 7.12% over the past week to $660.71, while Alphabet (NASDAQ:GOOGL) added 2.09% and Microsoft (NASDAQ:MSFT) held roughly flat at $499.83. NVIDIA (NASDAQ:NVDA) fell 8.38% over the same stretch to $210.82, and Amazon (NASDAQ:AMZN) slipped 1.74%. Prices are delayed intraday as of the morning of September 14, 2026, according to NBC News.
#NASDAQ #flat #fell
Microsoft held flat while ASML fell 10% and SoftBank dropped 11%, as markets rotated from AI hardware suppliers into enterprise software names.
With Fed rate hike odds at 85% and the 10-year yield near 5%, the rotation holds only if hyperscalers revise their massive capex plans.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Shares of Meta Platforms (NASDAQ:META) climbed 7.12% over the past week to $660.71, while Alphabet (NASDAQ:GOOGL) added 2.09% and Microsoft (NASDAQ:MSFT) held roughly flat at $499.83. NVIDIA (NASDAQ:NVDA) fell 8.38% over the same stretch to $210.82, and Amazon (NASDAQ:AMZN) slipped 1.74%. Prices are delayed intraday as of the morning of September 14, 2026, according to NBC News.
#NASDAQ #flat #fell


7 hours ago
The 2026-27 season is quickly approaching for the Philadelphia 76ers as they have their eyes on ending a long ***** le drought after the big additions made in the offseason. The Sixers will field one of the more talented rosters in the league and will look to get to the mountaintop in 2027.
It's now time to look ahead to the new season and time to break down each position for the Sixers in an effort to preview what the season might look like. Sixers Wire will look at the centers now and take a look at what the Sixers bring to the table at the position:
Sure, the Sixers have some shiny new players in Jaylen Brown and LeBron James, but all of this still comes down to the health of Joel Embiid. The big fella is still a dominant player when he can get on the floor as evidenced by his 26.9 points, 7.7 rebounds, and 3.9 ***** ists he averaged in 38 games in the 2025-26 season. Embiid being able to return early from an appendectomy completely changed that Round 1 series with Boston when the Sixers rallied from a 3-1 deficit. He averaged 28.0 points, 9.0 rebounds, and 7.0 ***** ists in Round 1 against the Celtics as he spurred the rally for Philadelphia.
When Embiid is right, there aren't many players in the league who can slow him down. He has lost a step defensively as a result of the injuries and surgeries he's had to undergo has robbed him of a lot of speed and athleticism, but Embiid is so smart and able to find new ways to be effective on defense. He is still one of the top players in the game and should be treated as such. If he's right and healthy, the Sixers take an even bigger leap forward.
The Sixers will rely on third-year big man Adem Bona as they did in the 2025-26 season. He averaged 4.8 points, 4.3 rebounds, and 1.2 blocks as he was able to establish himself in coach Nick Nurse's rotation. He will have competition, though, as the Sixers did add bouncy Ariel Hukporti early in free agency. Also, in his third season, Hukporti will look to find an opportunity in Philadelphia.
#look #still
It's now time to look ahead to the new season and time to break down each position for the Sixers in an effort to preview what the season might look like. Sixers Wire will look at the centers now and take a look at what the Sixers bring to the table at the position:
Sure, the Sixers have some shiny new players in Jaylen Brown and LeBron James, but all of this still comes down to the health of Joel Embiid. The big fella is still a dominant player when he can get on the floor as evidenced by his 26.9 points, 7.7 rebounds, and 3.9 ***** ists he averaged in 38 games in the 2025-26 season. Embiid being able to return early from an appendectomy completely changed that Round 1 series with Boston when the Sixers rallied from a 3-1 deficit. He averaged 28.0 points, 9.0 rebounds, and 7.0 ***** ists in Round 1 against the Celtics as he spurred the rally for Philadelphia.
When Embiid is right, there aren't many players in the league who can slow him down. He has lost a step defensively as a result of the injuries and surgeries he's had to undergo has robbed him of a lot of speed and athleticism, but Embiid is so smart and able to find new ways to be effective on defense. He is still one of the top players in the game and should be treated as such. If he's right and healthy, the Sixers take an even bigger leap forward.
The Sixers will rely on third-year big man Adem Bona as they did in the 2025-26 season. He averaged 4.8 points, 4.3 rebounds, and 1.2 blocks as he was able to establish himself in coach Nick Nurse's rotation. He will have competition, though, as the Sixers did add bouncy Ariel Hukporti early in free agency. Also, in his third season, Hukporti will look to find an opportunity in Philadelphia.
#look #still



7 hours ago
Tech stocks fell on Monday, as AI industry leaders raised concerns about the future of the technology and its potential to harm humans. The Nasdaq fell roughly 0.8% in early trading. The Philadelphia Semiconductor Index fell more than 4%.
The episode began last week when an Anthropic researcher announced he was leaving the company via a post on X, saying he didn't feel it was doing enough to keep AI in check.
Anthropic Alignment Science Lead, Evan Hubinger, responded the post saying the former Anthropic worker is correct and that he believes there is a greater-than-10 % chance that the technology could "kill all humans."
On Saturday, Anthropic CEO Dario Amodei posted an essay responding to the posts, calling on AI companies to slow the pace of frontier AI development. OpenAI CEO Sam Altman agreed.
And on Monday, Reuters reported that Microsoft is developing its own code of conduct for its AI models.
#anthropic #Monday #Tech
The episode began last week when an Anthropic researcher announced he was leaving the company via a post on X, saying he didn't feel it was doing enough to keep AI in check.
Anthropic Alignment Science Lead, Evan Hubinger, responded the post saying the former Anthropic worker is correct and that he believes there is a greater-than-10 % chance that the technology could "kill all humans."
On Saturday, Anthropic CEO Dario Amodei posted an essay responding to the posts, calling on AI companies to slow the pace of frontier AI development. OpenAI CEO Sam Altman agreed.
And on Monday, Reuters reported that Microsoft is developing its own code of conduct for its AI models.
#anthropic #Monday #Tech


7 hours ago
U.S. stocks fell Monday as calls from major AI company leaders to slow development of the technology rattled chip stocks, while surging oil prices added to pressure on equities.
The S&P 500 shed 0.7%, the Nasdaq Composite gave back 1.2%, and the Dow Jones Industrial Average finished 140 points lower, a decline of 0.3%.
Anthropic CEO Dario Amodei argued in an essay Saturday that AI companies need to reduce the pace of innovation on their most capable models due to safety risks. Amodei told CBS News on Sunday that the "toughest dilemma" posed by any such proposal involves the question of whether China would agree to do the same. OpenAI CEO Sam Altman said in a separate Saturday interview that an IPO this year would be "ill-advised," according to CNBC.
Nvidia and Broadcom each lost 3%. Advanced Micro Devices, Intel, and Marvell Technology posted steeper losses of 5%, 7%, and 8%, respectively. CoreWeave stock dropped 7%.
Oil prices added to the pressure on stocks. Brent crude futures advanced 4%, topping $108 a barrel, and West Texas Intermediate crude futures gained 3%, clearing $103 a barrel. Saudi Arabia shut down its East-West oil pipeline — a route used to bypass the Strait of Hormuz — after the pipeline sustained multiple drone attacks. The shutdown comes as instability across the Middle East continues to widen. It was the first time U.S. crude had traded above $100 a barrel since May.
#stocks #amodei #west
The S&P 500 shed 0.7%, the Nasdaq Composite gave back 1.2%, and the Dow Jones Industrial Average finished 140 points lower, a decline of 0.3%.
Anthropic CEO Dario Amodei argued in an essay Saturday that AI companies need to reduce the pace of innovation on their most capable models due to safety risks. Amodei told CBS News on Sunday that the "toughest dilemma" posed by any such proposal involves the question of whether China would agree to do the same. OpenAI CEO Sam Altman said in a separate Saturday interview that an IPO this year would be "ill-advised," according to CNBC.
Nvidia and Broadcom each lost 3%. Advanced Micro Devices, Intel, and Marvell Technology posted steeper losses of 5%, 7%, and 8%, respectively. CoreWeave stock dropped 7%.
Oil prices added to the pressure on stocks. Brent crude futures advanced 4%, topping $108 a barrel, and West Texas Intermediate crude futures gained 3%, clearing $103 a barrel. Saudi Arabia shut down its East-West oil pipeline — a route used to bypass the Strait of Hormuz — after the pipeline sustained multiple drone attacks. The shutdown comes as instability across the Middle East continues to widen. It was the first time U.S. crude had traded above $100 a barrel since May.
#stocks #amodei #west


7 hours ago
Good morning. Stocks fell on Monday as oil prices jumped ahead of a key Fed meeting this week.
(BZ=F) crude rose to $109 per barrel, stoking worries of persistent inflation as diesel prices remain above an all-time high of $6 per gallon.
Bond yields remained elevated, with the 10-year Treasury (^TNX) just a few basis points away from the 5% threshold.
The 2-year yield to 4.64%, signaling that markets expect Fed policymakers to raise rates. Investor bets that the Federal Reserve will hike rates on Wednesday stood at 80% on Polymarket.
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
#year #good
(BZ=F) crude rose to $109 per barrel, stoking worries of persistent inflation as diesel prices remain above an all-time high of $6 per gallon.
Bond yields remained elevated, with the 10-year Treasury (^TNX) just a few basis points away from the 5% threshold.
The 2-year yield to 4.64%, signaling that markets expect Fed policymakers to raise rates. Investor bets that the Federal Reserve will hike rates on Wednesday stood at 80% on Polymarket.
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
#year #good

8 hours ago
The beginning of the Washington Commanders' season is not for the weak. First, they face division opponents in the first two weeks of the season, and then they play the reigning Super Bowl champion Seattle Seahawks in Week 3. Both games against division opponents are on the road, too, which doesn't help anything.
On Sunday, the Commanders opened their season against the Philadelphia Eagles, and it was a difficult game to watch early on. The Commanders struggled with timing, Jayden Daniels looked uncomfortable, and Terry McLaurin was MIA. Defensively, the secondary led the team in tackles, which is concerning. Rookie Sonny Styles actually led all linebackers with four tackles (three solo), one sack, two tackles for a loss, and one quarterback hit.
They seemed to figure things out near the end of the game, but it was too little, too late, and the Commanders fell 24-22 after failing to convert a two-point attempt to tie the game. Let's take a look at the lowest and highest-graded players from the Commanders' loss, as graded by Pro Football Focus.
WR Antonio Williams (91.0)
QB Jayden Daniels (74.9)
#daniels #loss
On Sunday, the Commanders opened their season against the Philadelphia Eagles, and it was a difficult game to watch early on. The Commanders struggled with timing, Jayden Daniels looked uncomfortable, and Terry McLaurin was MIA. Defensively, the secondary led the team in tackles, which is concerning. Rookie Sonny Styles actually led all linebackers with four tackles (three solo), one sack, two tackles for a loss, and one quarterback hit.
They seemed to figure things out near the end of the game, but it was too little, too late, and the Commanders fell 24-22 after failing to convert a two-point attempt to tie the game. Let's take a look at the lowest and highest-graded players from the Commanders' loss, as graded by Pro Football Focus.
WR Antonio Williams (91.0)
QB Jayden Daniels (74.9)
#daniels #loss

8 hours ago
Just days ahead of a pivotal matchup against No. 10 Alabama, Florida State has reportedly fired athletic director Michael Alford, according to ESPN.
His tenure with the school got off to a promising start, as the Florida State football team went 23-4 in his first two years on the job. But things have declined precipitously since then. Florida State fell to just 2-10 in 2024, went 5-7 in 2025 and is 1-1 this year after losing to No. 19 SMU on Monday.
This story will be updated.
#michael #Monday #days
His tenure with the school got off to a promising start, as the Florida State football team went 23-4 in his first two years on the job. But things have declined precipitously since then. Florida State fell to just 2-10 in 2024, went 5-7 in 2025 and is 1-1 this year after losing to No. 19 SMU on Monday.
This story will be updated.
#michael #Monday #days
8 hours ago
Colgate-Palmolive (CL) hired Goldman Sachs to explore selling Softsoap, Irish Spring, and Speed Stick as North America revenue fell 3% in Q2 2026.
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish
Private equity leads as the likeliest buyer, with every named strategic acquirer blocked by scale gaps, leverage limits, or an active acquisition lock-up.
The real test is whether shedding mature brands resolves Colgate's self-described long-term North America turnaround or simply makes the company smaller.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Colgate-Palmolive didn't make the cut. Enter your email to see the names that beat CL. The report is free. Enter your email and see if any of your stocks made the cut.
Colgate-Palmolive (NYSE:CL) is reportedly shopping a slice of its portfolio that many investors forgot it still owned. Reuters reported on Friday, September 11, 2026, citing unnamed sources, that Colgate is exploring a sale of Softsoap, Irish Spring, and Speed Stick and has hired Goldman Sachs to run the process.
#palmolive #goldman #irish