

4 days ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson
10 days ago
A few weeks ago, I used Uber Eats to deliver me a case of bottled water, a dozen Starbucks iced coffee bottles, and a 12-pack of Gatorade Zero.
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero
14 days ago
Gold has long served as a portfolio diversifier, often drawing renewed attention during periods of inflation, geopolitical uncertainty, and shifts in monetary policy. In recent years, gold has rallied sharply, reinforcing its reputation as both a store of value and a hedge against macroeconomic risk.
But gold's path has never been a straight line. While the metal has delivered strong returns in certain environments, it has also gone through extended stretches of sideways performance, contributing little to portfolio growth or income. That leaves investors with a familiar tradeoff: maintain gold exposure for its diversification benefits, or reallocate to ***** ets that can generate income along the way.
The NEOS Gold High Income ETF (IAUI) aims to combine gold's traditional store-of-value role with an income-generating options strategy, seeking to deliver high monthly income while preserving upside potential.
The fund's approach rests on two components:
Gold exposure: Up to 25% of the portfolio is allocated to low-cost physical gold ETPs, with the remaining 75% gained through synthetic exposure via GLD options, aiming to track gold's price movements directly. Limiting direct physical gold exposure to 25% also allows the fund to report taxes via Form 1099-DIV rather than a K-1, simplifying year-end tax reporting for investors.
#store
But gold's path has never been a straight line. While the metal has delivered strong returns in certain environments, it has also gone through extended stretches of sideways performance, contributing little to portfolio growth or income. That leaves investors with a familiar tradeoff: maintain gold exposure for its diversification benefits, or reallocate to ***** ets that can generate income along the way.
The NEOS Gold High Income ETF (IAUI) aims to combine gold's traditional store-of-value role with an income-generating options strategy, seeking to deliver high monthly income while preserving upside potential.
The fund's approach rests on two components:
Gold exposure: Up to 25% of the portfolio is allocated to low-cost physical gold ETPs, with the remaining 75% gained through synthetic exposure via GLD options, aiming to track gold's price movements directly. Limiting direct physical gold exposure to 25% also allows the fund to report taxes via Form 1099-DIV rather than a K-1, simplifying year-end tax reporting for investors.
#store

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
17 days ago
On August 5, Protagonist Therapeutics (NASDAQ:PTGX) reported second-quarter 2026 results that flipped the company from red ink to a $162.8 million profit, or $2.29 per diluted share, compared with a $34.8 million loss a year earlier. The swing came as the company banked payments tied to two drugs moving from the lab bench to the pharmacy counter: ICOTYDE, an oral psoriasis treatment, and rusfertide, an injectable now awaiting an FDA decision. Cash and marketable securities climbed to $849.5 million. Here's what's fueling the optimism, and what could complicate it.
The quarter marked the first full three months of commercial sales for ICOTYDE, which won FDA approval on March 18 for moderate-to-severe plaque psoriasis in patients 12 and older weighing at least 40 kg. That approval triggered a $50 million milestone payment and made ICOTYDE, according to the company, the first and only FDA-approved targeted oral peptide for the condition. Protagonist can still collect up to $580 million more in milestones from partner Johnson & Johnson, plus royalties that average around 7.25 percent at $4 billion in annual sales.
Rusfertide carries even more weight. Its new drug application sits under Priority Review with a PDUFA goal date in August, backed by Breakthrough Therapy, Orphan Drug, and Fast Track designations for polycythemia vera. Partner Takeda already paid Protagonist $200 million on an opt-out election in April, with another $200 million and a $75 million approval milestone still due, on top of royalties that can reach 29 percent of sales above $1.5 billion. Behind both drugs, PN-881, an oral IL-17 antagonist, is heading into a Phase 2b psoriasis program in early 2027 after Phase 1 data showed drug levels beating their pharmacokinetic targets, and a Phase 1 study just began for PN-477sc, an injectable obesity peptide.
Look closer at that $213.5 million in license and collaboration revenue, and $192.4 million of it traces to the proportional recognition of Takeda's initial opt-out payment, not repeatable product sales. A year earlier, the same line item was just $5.5 million, so the growth reflects a single deal event more than an operating business scaling up. And that opt-out itself cuts both ways: Protagonist gave up its right to develop and commercialize rusfertide on its own, trading full ownership for royalties and milestones that depend on Takeda's execution rather than Protagonist's.
Spending is also set to climb. Management expects research and development costs to increase significantly in the second half of 2026 versus the first half, driven by the new PN-881 Phase 2b program, manufacturing investments, and added headcount. General and administrative costs are rising too, largely on stock-based compensation. And rusfertide's fate still hinges on an FDA decision that hasn't happened yet, priority review or not.
#protagonist
The quarter marked the first full three months of commercial sales for ICOTYDE, which won FDA approval on March 18 for moderate-to-severe plaque psoriasis in patients 12 and older weighing at least 40 kg. That approval triggered a $50 million milestone payment and made ICOTYDE, according to the company, the first and only FDA-approved targeted oral peptide for the condition. Protagonist can still collect up to $580 million more in milestones from partner Johnson & Johnson, plus royalties that average around 7.25 percent at $4 billion in annual sales.
Rusfertide carries even more weight. Its new drug application sits under Priority Review with a PDUFA goal date in August, backed by Breakthrough Therapy, Orphan Drug, and Fast Track designations for polycythemia vera. Partner Takeda already paid Protagonist $200 million on an opt-out election in April, with another $200 million and a $75 million approval milestone still due, on top of royalties that can reach 29 percent of sales above $1.5 billion. Behind both drugs, PN-881, an oral IL-17 antagonist, is heading into a Phase 2b psoriasis program in early 2027 after Phase 1 data showed drug levels beating their pharmacokinetic targets, and a Phase 1 study just began for PN-477sc, an injectable obesity peptide.
Look closer at that $213.5 million in license and collaboration revenue, and $192.4 million of it traces to the proportional recognition of Takeda's initial opt-out payment, not repeatable product sales. A year earlier, the same line item was just $5.5 million, so the growth reflects a single deal event more than an operating business scaling up. And that opt-out itself cuts both ways: Protagonist gave up its right to develop and commercialize rusfertide on its own, trading full ownership for royalties and milestones that depend on Takeda's execution rather than Protagonist's.
Spending is also set to climb. Management expects research and development costs to increase significantly in the second half of 2026 versus the first half, driven by the new PN-881 Phase 2b program, manufacturing investments, and added headcount. General and administrative costs are rising too, largely on stock-based compensation. And rusfertide's fate still hinges on an FDA decision that hasn't happened yet, priority review or not.
#protagonist
20 days ago
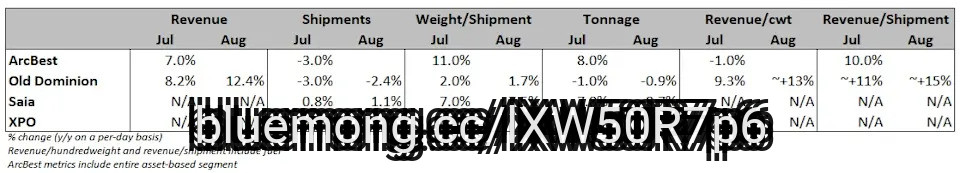
Less-than-truckload carrier Old Dominion Freight Line saw yield growth accelerate in August, but tonnage remained slightly negative, according to a Thursday update.
The Thomasville, North Carolina-based company's daily revenue increased 12.4% year over year in August, an improvement from the 8.2% y/y growth rate logged in July. However, diesel fuel prices increased 46% y/y in August compared with a 31% y/y increase in July. (Fuel was up 10% sequentially in August.)
Less-than-truckload fuel surcharge programs include a step function as diesel prices rise, typically resulting in better margins.
Old Dominion's (NASDAQ: ODFL) yield growth accelerated from July, both with and without fuel surcharges. August revenue per hundredweight (yield) was likely 13% higher y/y with fuel surcharges, and roughly 5.5% higher excluding fuel. The July growth rates were 9.3% and 4.2%, respectively. (Growth rates for the two months combined were 11.3% and 4.8%, respectively.) Higher shipment weights were a modest drag on the yield metrics in both months.
"Old Dominion produced solid revenue growth for July and August, with underlying demand trends remaining relatively consistent as the quarter has progressed," said Marty Freeman, president and CEO, in a news release. "In addition, the strength and consistency of our industry-leading service continue to support the ongoing improvement in our LTL revenue per hundredweight."
#revenue #higher
The Thomasville, North Carolina-based company's daily revenue increased 12.4% year over year in August, an improvement from the 8.2% y/y growth rate logged in July. However, diesel fuel prices increased 46% y/y in August compared with a 31% y/y increase in July. (Fuel was up 10% sequentially in August.)
Less-than-truckload fuel surcharge programs include a step function as diesel prices rise, typically resulting in better margins.
Old Dominion's (NASDAQ: ODFL) yield growth accelerated from July, both with and without fuel surcharges. August revenue per hundredweight (yield) was likely 13% higher y/y with fuel surcharges, and roughly 5.5% higher excluding fuel. The July growth rates were 9.3% and 4.2%, respectively. (Growth rates for the two months combined were 11.3% and 4.8%, respectively.) Higher shipment weights were a modest drag on the yield metrics in both months.
"Old Dominion produced solid revenue growth for July and August, with underlying demand trends remaining relatively consistent as the quarter has progressed," said Marty Freeman, president and CEO, in a news release. "In addition, the strength and consistency of our industry-leading service continue to support the ongoing improvement in our LTL revenue per hundredweight."
#revenue #higher

21 days ago
By Nupur Anand
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#reuters #democrat #anand #york
NEW YORK, Sept 2 (Reuters) - A Democratic U.S. senator has pressed Capital One Financial for details about an internal anti-money laundering review that the bank said last month led it to close accounts linked to President Donald Trump and his businesses.
In a letter sent to Capital One CEO Richard Fairbank on Tuesday evening and first reported by Reuters, Senator Maggie Hassan, a New Hampshire Democrat, asked for documents describing the transactions, alerts and other factors that prompted the review, as well as any communications with law enforcement or regulators related to the matter.
"The American people deserve to know," wrote Hassan, the top Democrat on the Joint Economic Committee.
Capital One declined to comment.
#reuters #democrat #anand #york

21 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved seven consecutive quarters of positive cash from operations, signaling a successful transition from business stabilization to a foundation for sustainable growth.
Performance was driven largely by Supercuts, which delivered 3% same-store sales growth for the full year, marking its fifth consecutive year of growth.
Management attributed the 7.3% decline in fourth-quarter total revenue to lower non-margin franchise rental income as franchisees transitioned to independent leases.
The decline in franchise salon count was mitigated by the fact that closures were predominantly lower-volume locations with an average unit volume of $136,000, significantly below the top-quartile average.
#year #NVIDIA
Achieved seven consecutive quarters of positive cash from operations, signaling a successful transition from business stabilization to a foundation for sustainable growth.
Performance was driven largely by Supercuts, which delivered 3% same-store sales growth for the full year, marking its fifth consecutive year of growth.
Management attributed the 7.3% decline in fourth-quarter total revenue to lower non-margin franchise rental income as franchisees transitioned to independent leases.
The decline in franchise salon count was mitigated by the fact that closures were predominantly lower-volume locations with an average unit volume of $136,000, significantly below the top-quartile average.
#year #NVIDIA
23 days ago
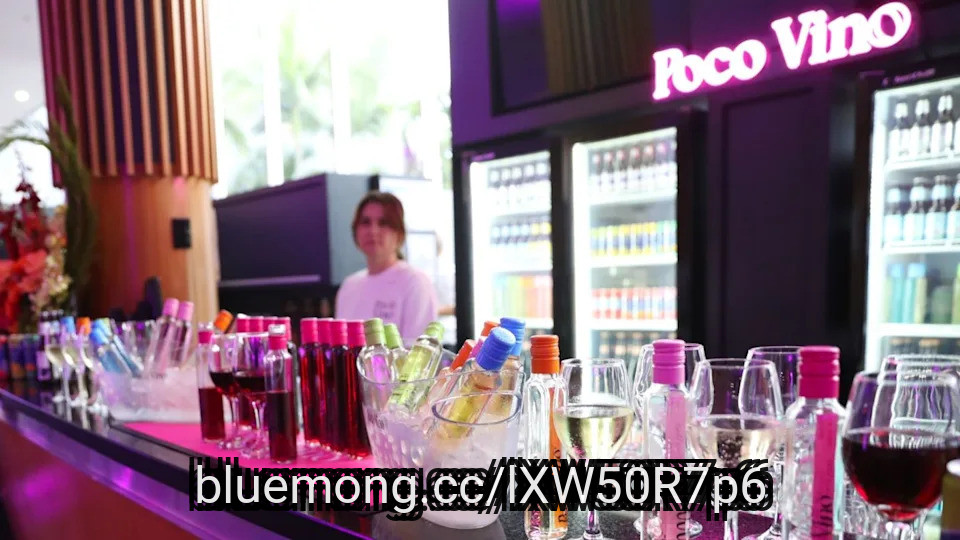
Australian Vintage is now a "stronger, more agile business", the wine group's management has said, after 12 months of work to boost cash, bolster the company's balance sheet and cut costs.
The group saw its annual losses grow in the year to the end of June amid an impairment charge on inventory, restructuring costs and a strengthening Australian dollar.
The McGuigan brand owner's revenue inched up 0.4% as growth in the second half offset lower sales in the first six months of the year.
Australian Vintage reported improvements in cash flow and said it had "focused on cash generation as a key measure of the underlying health and performance of the business".
In a stock-exchange filing, the company said the 2025/26 financial year had been "a year of significant transformation" for the business.
#australian #year #months #costs
The group saw its annual losses grow in the year to the end of June amid an impairment charge on inventory, restructuring costs and a strengthening Australian dollar.
The McGuigan brand owner's revenue inched up 0.4% as growth in the second half offset lower sales in the first six months of the year.
Australian Vintage reported improvements in cash flow and said it had "focused on cash generation as a key measure of the underlying health and performance of the business".
In a stock-exchange filing, the company said the 2025/26 financial year had been "a year of significant transformation" for the business.
#australian #year #months #costs
27 days ago
A popular sports bar and grill chain has abruptly closed four restaurants, cutting its footprint by 20%, less than two years after a new owner acquired the brand.
The closures come as restaurant chains across the country continue to deal with severe challenges stemming from rising food and labor costs, shifting consumer habits, and aggressive competition for diners.
Full-service restaurants are feeling more pressure as they rely heavily on front-of-house staffing, table service, and bar staff. Moreover, full-service restaurants earn 3%-5% net, versus 6%-9% for fast-casual concepts and quick-service restaurants, on a scale where net margin above 6% is considered strong, according to data from Bloom Intelligence.
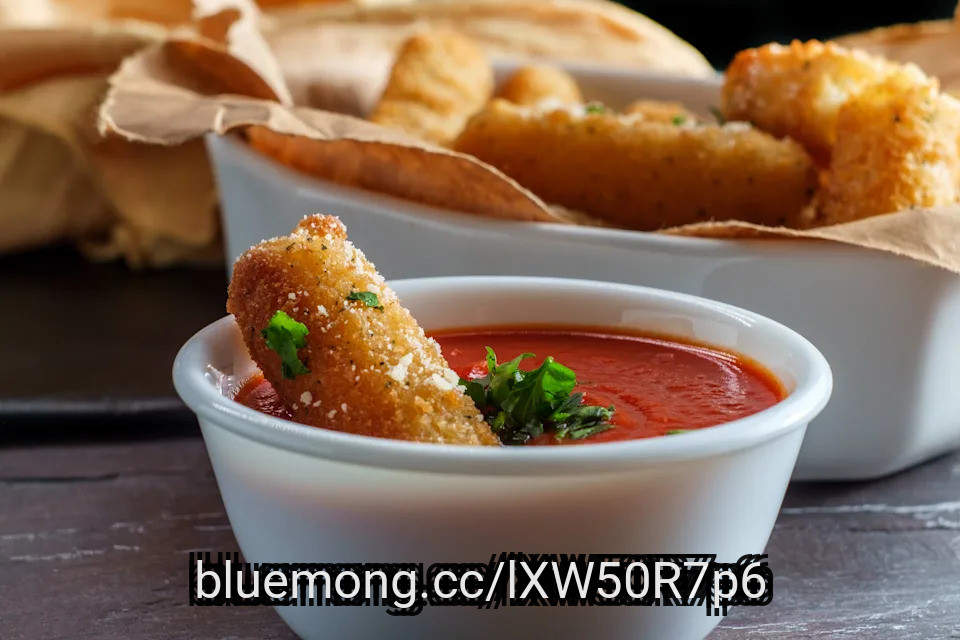
Founded in 1997 in Hickory, North Carolina, Hickory Tavern is a sports bar and grill family restaurant chain popular for its saucy wings, flatbreads, loaded nachos, and mozzarella sticks. Aside from food, the bar was often seen as a popular neighborhood gathering place.
Hickory Tavern abruptly closed four locations, leaving the chain with 16 remaining across the Carolinas, reported FSR Magazine.
#restaurants #hickory #chain #grill
The closures come as restaurant chains across the country continue to deal with severe challenges stemming from rising food and labor costs, shifting consumer habits, and aggressive competition for diners.
Full-service restaurants are feeling more pressure as they rely heavily on front-of-house staffing, table service, and bar staff. Moreover, full-service restaurants earn 3%-5% net, versus 6%-9% for fast-casual concepts and quick-service restaurants, on a scale where net margin above 6% is considered strong, according to data from Bloom Intelligence.
Founded in 1997 in Hickory, North Carolina, Hickory Tavern is a sports bar and grill family restaurant chain popular for its saucy wings, flatbreads, loaded nachos, and mozzarella sticks. Aside from food, the bar was often seen as a popular neighborhood gathering place.
Hickory Tavern abruptly closed four locations, leaving the chain with 16 remaining across the Carolinas, reported FSR Magazine.
#restaurants #hickory #chain #grill

29 days ago
Wall Street is focused on Nvidia's (NVDA) graphics processing units (GPUs). The faster-growing story is sitting beside them.
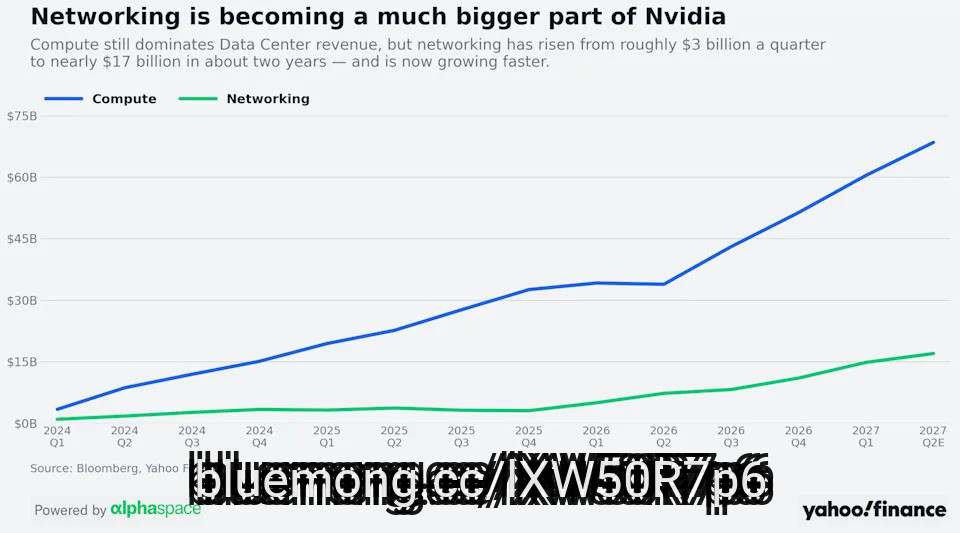
Nvidia has quietly built a networking operation that generated nearly $15 billion last quarter, up from roughly $3 billion per quarter two years ago. Wall Street expects that figure to approach $17 billion when the company reports earnings on Wednesday.
Compute still dwarfs networking inside Nvidia's Data Center business. But networking has been growing faster, up nearly 200% year over year in the last quarter compared with 77% for compute.
That pace is slowing. ******* ysts expect networking growth of roughly 134% in the quarter about to be reported, still ahead of compute at about 100%.
The change goes straight to one of the biggest questions hanging over Nvidia.
#quarter #growing #nearly
Nvidia has quietly built a networking operation that generated nearly $15 billion last quarter, up from roughly $3 billion per quarter two years ago. Wall Street expects that figure to approach $17 billion when the company reports earnings on Wednesday.
Compute still dwarfs networking inside Nvidia's Data Center business. But networking has been growing faster, up nearly 200% year over year in the last quarter compared with 77% for compute.
That pace is slowing. ******* ysts expect networking growth of roughly 134% in the quarter about to be reported, still ahead of compute at about 100%.
The change goes straight to one of the biggest questions hanging over Nvidia.
#quarter #growing #nearly



1 month ago
A survey of financial professionals at the nation's second-largest bank has revealed that the people handling your money may be overly confident in the stock market right now, even in the face of clear warning signs from the systems meant to alert them of imminent risk.
Each month, Bank of America polls its institutional investors to see where they're directing ****** ets and where they anticipate the market heading in the coming months, among other things.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#bank #market #America #dave
Each month, Bank of America polls its institutional investors to see where they're directing ****** ets and where they anticipate the market heading in the coming months, among other things.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#bank #market #America #dave

1 month ago
On August 17, Google, a unit of Alphabet Inc. (NASDAQ:GOOGL), agreed to buy internal business data from bankrupt Spirit Airlines for $10 million, outbidding a $7.5 million offer from AI data company Mercor. The haul includes employee emails, Microsoft Teams messages, spreadsheets, calendars, and marketing and operations records, all to be stripped of customer information before the sale closes at a bankruptcy court hearing. It is a tiny deal by Alphabet's standards. But it says something about how aggressively the company is hunting for raw material to train its AI models.
Google Cloud revenue grew 82% year over year to $24.8 billion in the second quarter, accelerating from 63% growth in the first. That pace dwarfs the 43% growth Microsoft reported for Azure and the 37% growth Amazon posted for AWS over the same period. Google Cloud is still the smallest of the three in dollar terms, but its operating income more than tripled, from $2.8 billion to $8.8 billion, pushing its margin from about 21% to 36%. Its backlog reached $514 billion, roughly five years of work at the current pace, and Alphabet expects to recognize just over half of it as revenue within 24 months. CEO Sundar Pichai said nearly 90% of the Fortune 100 now use its Gemini Enterprise model, with existing customers exceeding their original commitments by more than 50%.
AI is reshaping the advertising side of the business too. Gemini is helping Alphabet find relevant ads for longer, harder-to-monetize searches, while a tool called AI Max uses AI to expand keyword matches and rewrite ad copy automatically. Management has credited AI Overviews and AI Mode with lifting search revenue by making results more relevant, all built on top of a Chrome browser with 68% global market share and a Google Search engine that holds 91%.
Alphabet's headline numbers are less impressive up close. The company reported net income of $112.2 billion on revenue of $119.8 billion in the second quarter, but $98 billion of that came from "other income," driven mainly by a $94.1 billion unrealized gain tied to its early stake in **** eX. Alphabet invested $900 million in **** eX back in 2015 for roughly 7.5% of the company, a position that ballooned in value after **** eX's June IPO priced shares at $135 and closed the quarter at $170.86. Strip that gain out and Alphabet's net income falls closer to $18 billion, which works out to a 35% year-over-year decline in earnings per share. Because the gain is unrealized, it rises and falls with **** eX's stock price and could reverse just as fast as it appeared.
#year
Google Cloud revenue grew 82% year over year to $24.8 billion in the second quarter, accelerating from 63% growth in the first. That pace dwarfs the 43% growth Microsoft reported for Azure and the 37% growth Amazon posted for AWS over the same period. Google Cloud is still the smallest of the three in dollar terms, but its operating income more than tripled, from $2.8 billion to $8.8 billion, pushing its margin from about 21% to 36%. Its backlog reached $514 billion, roughly five years of work at the current pace, and Alphabet expects to recognize just over half of it as revenue within 24 months. CEO Sundar Pichai said nearly 90% of the Fortune 100 now use its Gemini Enterprise model, with existing customers exceeding their original commitments by more than 50%.
AI is reshaping the advertising side of the business too. Gemini is helping Alphabet find relevant ads for longer, harder-to-monetize searches, while a tool called AI Max uses AI to expand keyword matches and rewrite ad copy automatically. Management has credited AI Overviews and AI Mode with lifting search revenue by making results more relevant, all built on top of a Chrome browser with 68% global market share and a Google Search engine that holds 91%.
Alphabet's headline numbers are less impressive up close. The company reported net income of $112.2 billion on revenue of $119.8 billion in the second quarter, but $98 billion of that came from "other income," driven mainly by a $94.1 billion unrealized gain tied to its early stake in **** eX. Alphabet invested $900 million in **** eX back in 2015 for roughly 7.5% of the company, a position that ballooned in value after **** eX's June IPO priced shares at $135 and closed the quarter at $170.86. Strip that gain out and Alphabet's net income falls closer to $18 billion, which works out to a 35% year-over-year decline in earnings per share. Because the gain is unrealized, it rises and falls with **** eX's stock price and could reverse just as fast as it appeared.
#year

1 month ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed the revenue decline to significant headwinds in traditional advertising monetization, despite stable audience consumption levels.
The company is executing a 'remodeling the house while living in it' strategy, incurring higher operating expenses to build out digital infrastructure and sales leadership.
A strategic shift toward a 'blended digital strategy'—combining radio with search, SEO, and social—drove a 76.4% increase in blended digital revenue for the first half of the year.
Management emphasized a return to in-house search tools and specialized digital fulfillment teams to improve speed-to-market and campaign optimization.
#revenue #strategy
Management attributed the revenue decline to significant headwinds in traditional advertising monetization, despite stable audience consumption levels.
The company is executing a 'remodeling the house while living in it' strategy, incurring higher operating expenses to build out digital infrastructure and sales leadership.
A strategic shift toward a 'blended digital strategy'—combining radio with search, SEO, and social—drove a 76.4% increase in blended digital revenue for the first half of the year.
Management emphasized a return to in-house search tools and specialized digital fulfillment teams to improve speed-to-market and campaign optimization.
#revenue #strategy

1 month ago
Hertz Global Holdings (HTZ) is one of the world's largest car rental and mobility companies, operating roughly 11,000 locations across 160 countries with a fleet of more than 500,000 vehicles. But lately, the century-old rental giant has been giving investors something else to watch.
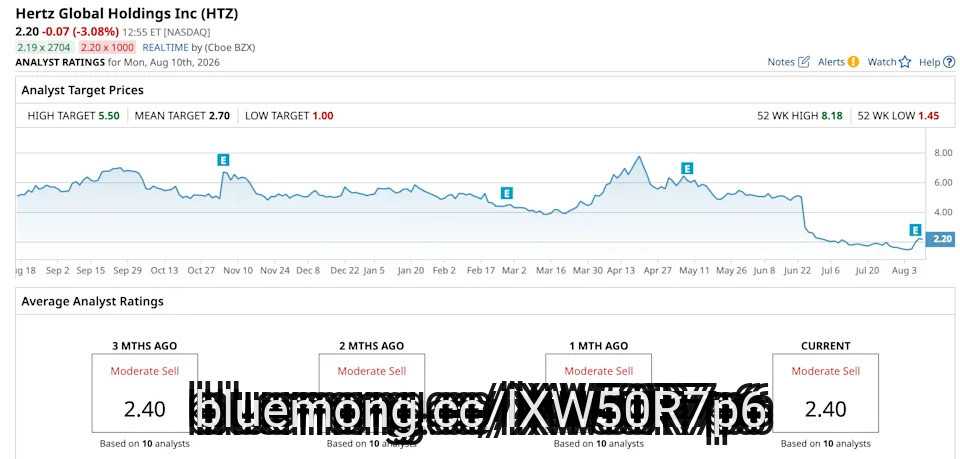
Hertz's second-quarter 2026 report, released on Aug. 6, was impressive, with the numbers coming in well above expectations. In fact, the quarter marked the strongest revenue per day (RPD) in recent history, excluding the COVID-era peak of 2022. Adjusted losses remain, but they are narrowing, and that was enough to put some wind back in HTZ's sails. Shares jumped 29.5% and another 12.4% the following day.
Don't ****** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#quarter #shares
Hertz's second-quarter 2026 report, released on Aug. 6, was impressive, with the numbers coming in well above expectations. In fact, the quarter marked the strongest revenue per day (RPD) in recent history, excluding the COVID-era peak of 2022. Adjusted losses remain, but they are narrowing, and that was enough to put some wind back in HTZ's sails. Shares jumped 29.5% and another 12.4% the following day.
Don't ****** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#quarter #shares


2 months ago
Apple (NASDAQ: AAPL) CEO Tim Cook just passed his successor an absolute mess. Cook steps down on Sept. 1 from his role as CEO but will remain on the board. In his place, John Ternus will ****** ume the role of CEO. However, the situation Ternus is taking over isn't a pretty one.
What's going on with Apple that caused this problem? Rising commodity prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
During Cook's last earnings call, he stated that rising memory chip prices are undergoing a "100-year flood." Essentially, ****** ody could have seen this coming, and the effects could be disastrous. He noted that Apple already had to raise prices on some products, but it may not be able to stop at just a few product lines. If prices continue to rise, it could force Apple to raise prices again, alienating some of its consumer base, which is already stretched thin.
However, Cook noted that it is decreasing costs on other components that help offset rising memory chip prices. We'll see how this pans out, but if prices continue to rise, it could get ugly for Apple and cause John Ternus to deal with a crisis just a few months into the job.
#continue
What's going on with Apple that caused this problem? Rising commodity prices.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
During Cook's last earnings call, he stated that rising memory chip prices are undergoing a "100-year flood." Essentially, ****** ody could have seen this coming, and the effects could be disastrous. He noted that Apple already had to raise prices on some products, but it may not be able to stop at just a few product lines. If prices continue to rise, it could force Apple to raise prices again, alienating some of its consumer base, which is already stretched thin.
However, Cook noted that it is decreasing costs on other components that help offset rising memory chip prices. We'll see how this pans out, but if prices continue to rise, it could get ugly for Apple and cause John Ternus to deal with a crisis just a few months into the job.
#continue


2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record quarterly sales of $528 million, a 16.4% increase driven by the Koch Filter acquisition and strong Power Solutions performance.
Successfully exited more than 95% of transition services agreements (TSAs) for Koch Filter, with full integration expected by the third quarter.
Observed a cyclical recovery in first-fit markets starting in late Q2, with Atmus seeing demand upticks 4 to 6 weeks ahead of vehicle OEM builds.
Maintained a flat outlook for the global aftermarket as stronger sentiment in the U.S. and Mexico is offset by subdued conditions in Europe, the Middle East, and Asia Pacific.
#filter #observed
Achieved record quarterly sales of $528 million, a 16.4% increase driven by the Koch Filter acquisition and strong Power Solutions performance.
Successfully exited more than 95% of transition services agreements (TSAs) for Koch Filter, with full integration expected by the third quarter.
Observed a cyclical recovery in first-fit markets starting in late Q2, with Atmus seeing demand upticks 4 to 6 weeks ahead of vehicle OEM builds.
Maintained a flat outlook for the global aftermarket as stronger sentiment in the U.S. and Mexico is offset by subdued conditions in Europe, the Middle East, and Asia Pacific.
#filter #observed


2 months ago
SKYRIZI supplies close to a third of guided company revenue, which puts an unusual amount of AbbVie's future behind one patent estate.
AbbVie (ABBV) has guided total 2026 revenue to roughly $67.6 billion. About $21.7 billion of that, close to one-third, is expected to come from a single medicine, SKYRIZI. That share is the number a holder should sit with before anything else in this story.
The quarterly picture has the same shape. SKYRIZI sold $5.5 billion in the second quarter of 2026, up 24% operationally, against total net revenues of nearly $17 billion, and the next largest product AbbVie broke out, RINVOQ, sold more than $2.5 billion. Immunology as a whole brought in nearly $8.8 billion, more than half the company, on 14.6% operational growth. What makes that concentration matter is what sits beside it: oncology revenue of more than $1.6 billion fell 2.4% operationally in the same three months, and aesthetics, at nearly $1.3 billion, slipped 0.9%. Neuroscience did grow, at more than $3.2 billion and roughly 20%. So the growth you are paying for sits in immunology and neuroscience, and inside the bigger of the two it leans mostly on one molecule.
AbbVie does not have to imagine what biosimilar entry does to a large immunology franchise, because it is happening on its own income statement right now. HUMIRA sold $756 million in the second quarter of 2026, down 36% operationally, which the company puts down to biosimilar competition. A franchise shedding better than a third of its sales year over year is the shape of the risk, not its timing, because the two products sit on very different clocks.
SKYRIZI's clock is public and much further out. The company says the US composition-of-matter patent expires in 2033, that later-expiring patents embodying the product are granted or in process and run into the mid twenty-thirties and later, that regulatory data protection does not lapse until 2031, and that it does not expect biosimilar applications before the end of the decade. That is a long runway by any standard. It is also why the question keeps coming back, because close to a third of today's guided revenue eventually sits behind that later intellectual property rather than behind the original patent.
#billion #skyrizi #abbvie #behind
AbbVie (ABBV) has guided total 2026 revenue to roughly $67.6 billion. About $21.7 billion of that, close to one-third, is expected to come from a single medicine, SKYRIZI. That share is the number a holder should sit with before anything else in this story.
The quarterly picture has the same shape. SKYRIZI sold $5.5 billion in the second quarter of 2026, up 24% operationally, against total net revenues of nearly $17 billion, and the next largest product AbbVie broke out, RINVOQ, sold more than $2.5 billion. Immunology as a whole brought in nearly $8.8 billion, more than half the company, on 14.6% operational growth. What makes that concentration matter is what sits beside it: oncology revenue of more than $1.6 billion fell 2.4% operationally in the same three months, and aesthetics, at nearly $1.3 billion, slipped 0.9%. Neuroscience did grow, at more than $3.2 billion and roughly 20%. So the growth you are paying for sits in immunology and neuroscience, and inside the bigger of the two it leans mostly on one molecule.
AbbVie does not have to imagine what biosimilar entry does to a large immunology franchise, because it is happening on its own income statement right now. HUMIRA sold $756 million in the second quarter of 2026, down 36% operationally, which the company puts down to biosimilar competition. A franchise shedding better than a third of its sales year over year is the shape of the risk, not its timing, because the two products sit on very different clocks.
SKYRIZI's clock is public and much further out. The company says the US composition-of-matter patent expires in 2033, that later-expiring patents embodying the product are granted or in process and run into the mid twenty-thirties and later, that regulatory data protection does not lapse until 2031, and that it does not expect biosimilar applications before the end of the decade. That is a long runway by any standard. It is also why the question keeps coming back, because close to a third of today's guided revenue eventually sits behind that later intellectual property rather than behind the original patent.
#billion #skyrizi #abbvie #behind

2 months ago
As energy demand from artificial intelligence surges, investors are weighing the merits of fuel cells versus next-generation nuclear. Choosing between Bloom Energy (NYSE:BE) and Oklo (NYSE:OKLO) requires balancing established revenue against futuristic potential.
Bloom Energy provides solid-oxide fuel cell technology for reliable on-site power, catering to data centers and industrial clients. Oklo is a pre-revenue developer of small modular reactors aiming to revolutionize carbon-free energy. Both companies target the massive power needs of the modern economy, yet they sit at very different stages of commercial maturity.
Bloom Energy sells solid-oxide energy servers providing onsite electricity and hydrogen to customers like SK ecoplant and American Electric Power (NASDAQ:AEP). Customer concentration like this adds a layer of risk to the business since revenue depends heavily on major partnerships. Recently, the company secured a $1.7 billion project with Nebius (NASDAQ:NBIS) and a financing framework with Brookfield ****** et Management (NYSE:BAM).
In FY 2025, revenue reached nearly $2.0 billion, representing growth of approximately 37.3%. This expansion was driven by increasing demand for onsite generation in the electric utility stocks ****** e. Despite the top-line growth, the company reported a net loss of roughly $88.4 million, representing a net margin of negative 4.4%.
As of its December 2025 balance sheet, the debt-to-equity ratio was approximately 3.9x. This ratio measures total debt relative to shareholder equity, suggesting the company uses a significant amount of borrowed money. The current ratio is a healthy 6.0x, while free cash flow, or cash left after capital expenditures, reached roughly $57.2 million.
#oklo
Bloom Energy provides solid-oxide fuel cell technology for reliable on-site power, catering to data centers and industrial clients. Oklo is a pre-revenue developer of small modular reactors aiming to revolutionize carbon-free energy. Both companies target the massive power needs of the modern economy, yet they sit at very different stages of commercial maturity.
Bloom Energy sells solid-oxide energy servers providing onsite electricity and hydrogen to customers like SK ecoplant and American Electric Power (NASDAQ:AEP). Customer concentration like this adds a layer of risk to the business since revenue depends heavily on major partnerships. Recently, the company secured a $1.7 billion project with Nebius (NASDAQ:NBIS) and a financing framework with Brookfield ****** et Management (NYSE:BAM).
In FY 2025, revenue reached nearly $2.0 billion, representing growth of approximately 37.3%. This expansion was driven by increasing demand for onsite generation in the electric utility stocks ****** e. Despite the top-line growth, the company reported a net loss of roughly $88.4 million, representing a net margin of negative 4.4%.
As of its December 2025 balance sheet, the debt-to-equity ratio was approximately 3.9x. This ratio measures total debt relative to shareholder equity, suggesting the company uses a significant amount of borrowed money. The current ratio is a healthy 6.0x, while free cash flow, or cash left after capital expenditures, reached roughly $57.2 million.
#oklo

2 months ago
Apple (NASDAQ: AAPL) has long been one of the most valuable companies in the world. But the iPhone maker saw its shares underperform many of the biggest artificial intelligence (AI) stocks over the last few years, ultimately leading it to lose its throne as the top company by market cap to Microsoft in May 2025, before Nvidia surpassed both companies in June 2025.
It's been over a year since Apple was the most valuable company in the world, the longest streak since it first climbed to that position in 2011.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But investors have been piling into its stock recently, pushing the market cap to about $4.9 trillion and making it, once again, the most valuable company in the world. Here's why the stock keeps climbing and why it can continue higher from here.
While some of the world's largest companies build out extensive AI infrastructure, Apple has remained a relatively ***** et-light business. Its capital expenditures (capex) for the past 12 months have totaled $11 billion. By comparison, Microsoft is spending about $200 billion this year, as are Alphabet and Amazon.
#company #Microsoft
It's been over a year since Apple was the most valuable company in the world, the longest streak since it first climbed to that position in 2011.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But investors have been piling into its stock recently, pushing the market cap to about $4.9 trillion and making it, once again, the most valuable company in the world. Here's why the stock keeps climbing and why it can continue higher from here.
While some of the world's largest companies build out extensive AI infrastructure, Apple has remained a relatively ***** et-light business. Its capital expenditures (capex) for the past 12 months have totaled $11 billion. By comparison, Microsoft is spending about $200 billion this year, as are Alphabet and Amazon.
#company #Microsoft

2 months ago
The number of wealthy non-dom taxpayers shrank by 1,200 last year amid warnings that Labour's tax rises could push even more rich people offshore.
New figures from HMRC reveal that 9,000 non-doms – foreign investors living in Britain – left the country or changed their tax status in the financial year ending April 2025.
Meanwhile, the number of non-doms arriving in the country dropped 14pc to 8,600. A further 800 "deemed-domicile" taxpayers – former non-doms who have since become British tax residents – also quit the UK, for an overall net reduction of 1,200.
Leslie MacLeod-Miller, the chief executive of Foreign Investors for Britain, a pressure group, warned that government inaction could push more investors and entrepreneurs to leave, reducing their £13.6bn annual tax contribution to the public finances.
"Britain is losing internationally mobile wealth at an accelerating pace," he said. "The exodus of wealth will only get worse if the Government does not introduce a competitive tax regime to restore Britain's place in the world."
#investors #government
New figures from HMRC reveal that 9,000 non-doms – foreign investors living in Britain – left the country or changed their tax status in the financial year ending April 2025.
Meanwhile, the number of non-doms arriving in the country dropped 14pc to 8,600. A further 800 "deemed-domicile" taxpayers – former non-doms who have since become British tax residents – also quit the UK, for an overall net reduction of 1,200.
Leslie MacLeod-Miller, the chief executive of Foreign Investors for Britain, a pressure group, warned that government inaction could push more investors and entrepreneurs to leave, reducing their £13.6bn annual tax contribution to the public finances.
"Britain is losing internationally mobile wealth at an accelerating pace," he said. "The exodus of wealth will only get worse if the Government does not introduce a competitive tax regime to restore Britain's place in the world."
#investors #government

2 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #c1b67d90 -8b46-11f1-a34e-bb829fa6d182
#page
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #c1b67d90 -8b46-11f1-a34e-bb829fa6d182
#page
2 months ago
It was reported Wednesday afternoon that a large call option spread, equating to 500 million bushels, was created in November corn.
This position is a bet on a US weather market through the rest of summer and into fall.
Brazil Coffee Harvest Pressures Weigh on Prices
Cocoa Prices Slump Amid Weak Demand and Abundant Supplies
Three Key Factors to Watch in Grains During Late Summer
#november #harvest #weigh
This position is a bet on a US weather market through the rest of summer and into fall.
Brazil Coffee Harvest Pressures Weigh on Prices
Cocoa Prices Slump Amid Weak Demand and Abundant Supplies
Three Key Factors to Watch in Grains During Late Summer
#november #harvest #weigh


2 months ago
With a market cap of $39.8 billion, Ares Management Corporation (ARES) is a leading global alternative investment manager that provides primary and secondary investment solutions across credit, real estate, private equity, and infrastructure ***** et classes. As of March 31, 2026, the firm managed approximately $644 billion in ***** ets under management (AUM) and employed around 4,400 professionals across North America, South America, Europe, Asia Pacific, and the Middle East.
The Los Angeles, California-based company is set to announce its fiscal Q2 2026 results before the market opens on Friday, Jul. 31. Ahead of this event, ***** ysts forecast ARES to report an EPS of $1.30, an increase of 26.2% from $1.03 in the year-ago quarter. It has exceeded Wall Street's earnings estimates in one of the last four quarters while missing on three other occasions.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#market #billion #America #investment
The Los Angeles, California-based company is set to announce its fiscal Q2 2026 results before the market opens on Friday, Jul. 31. Ahead of this event, ***** ysts forecast ARES to report an EPS of $1.30, an increase of 26.2% from $1.03 in the year-ago quarter. It has exceeded Wall Street's earnings estimates in one of the last four quarters while missing on three other occasions.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#market #billion #America #investment


2 months ago
This story was originally published on QSR. To receive daily news and insights, subscribe to our free daily QSR AM Jolt.
Qu, the intelligent commerce platform for enterprise QSR and fast-casual restaurant brands, announced Qu Pay, an embedded, end-to-end payments solution. A first-of-its-kind innovation, Qu Pay combines four systems: payment processing, guest identity, order intelligence, and capital access into a single layer of the unified platform.
Until now, payments lived outside the core restaurant operating system—treated as a cost center, not an intelligence hub. Qu Pay ends that separation. Every transaction becomes data brands can use to better understand and serve their guests. Qu Pay serves enterprise brands across point-of-sale, kiosks, drive-thru, web, and mobile channels. The platform is already live with multiple brands, including Roy Rogers.
"I've spent my career watching operators treat payments as a necessary evil instead of a value-added capability," said Rachid Hassan, Vice President of Payments at Qu. "We built Qu Pay because operators shouldn't have to choose between running their business and understanding it. Now every transaction feeds both."
Every Transaction Unlocks Guest Intelligence
#transaction #guest #daily
Qu, the intelligent commerce platform for enterprise QSR and fast-casual restaurant brands, announced Qu Pay, an embedded, end-to-end payments solution. A first-of-its-kind innovation, Qu Pay combines four systems: payment processing, guest identity, order intelligence, and capital access into a single layer of the unified platform.
Until now, payments lived outside the core restaurant operating system—treated as a cost center, not an intelligence hub. Qu Pay ends that separation. Every transaction becomes data brands can use to better understand and serve their guests. Qu Pay serves enterprise brands across point-of-sale, kiosks, drive-thru, web, and mobile channels. The platform is already live with multiple brands, including Roy Rogers.
"I've spent my career watching operators treat payments as a necessary evil instead of a value-added capability," said Rachid Hassan, Vice President of Payments at Qu. "We built Qu Pay because operators shouldn't have to choose between running their business and understanding it. Now every transaction feeds both."
Every Transaction Unlocks Guest Intelligence
#transaction #guest #daily

2 months ago
December soybean meal (ZMZ26) futures present a buying opportunity on more price strength.
See on the daily bar chart for December soybean meal futures that prices are in an uptrend. See, too, at the bottom of the chart that the moving average convergence divergence (MACD) indicator is in a bullish posture, as the blue MACD line is above the red trigger line and both lines are trending up.
The Cattle Conundrum
There's a Trainwreck Happening in Cattle Prices. Here's What You Need to Watch This Week.
Coffee Prices Supported by Delay of Brazil's Coffee Harvest
#macd #cattle #soybean
See on the daily bar chart for December soybean meal futures that prices are in an uptrend. See, too, at the bottom of the chart that the moving average convergence divergence (MACD) indicator is in a bullish posture, as the blue MACD line is above the red trigger line and both lines are trending up.
The Cattle Conundrum
There's a Trainwreck Happening in Cattle Prices. Here's What You Need to Watch This Week.
Coffee Prices Supported by Delay of Brazil's Coffee Harvest
#macd #cattle #soybean


2 months ago
Viridian Therapeutics Inc. (NASDAQ:VRDN) is one of the 10 affordable biotech stocks to buy right now.
On June 30, Goldman Sachs increased its target price for Viridian Therapeutics Inc. (NASDAQ:VRDN) from $35 to $39, implying an adjusted upside potential in excess of 105% at the prevailing level. The firm maintained its Buy rating on the stock.
Mila Supinskaya Glashchenko/Shutterstock.com
Goldman Sachs reflected on the FDA approval call regarding Viridian's Lumvoa, which carries a unique profile for the treatment of thyroid eye disease compared to Tepezza. The firm stated that Lumvoa is more efficient for the improvement of proptosis, and its safety profile is promising. Its dosing regimen is also more convenient, which backs a highly optimistic stance towards its planned commercial launch.
On June 30, Truist also increased its target price on the stock from $35 to $38, which yields more than 100% upside potential. The firm reiterated a Buy rating on the stock, also highlighting Lumvoa's differentiated profile relative to Tepezza.
On June 30, Goldman Sachs increased its target price for Viridian Therapeutics Inc. (NASDAQ:VRDN) from $35 to $39, implying an adjusted upside potential in excess of 105% at the prevailing level. The firm maintained its Buy rating on the stock.
Mila Supinskaya Glashchenko/Shutterstock.com
Goldman Sachs reflected on the FDA approval call regarding Viridian's Lumvoa, which carries a unique profile for the treatment of thyroid eye disease compared to Tepezza. The firm stated that Lumvoa is more efficient for the improvement of proptosis, and its safety profile is promising. Its dosing regimen is also more convenient, which backs a highly optimistic stance towards its planned commercial launch.
On June 30, Truist also increased its target price on the stock from $35 to $38, which yields more than 100% upside potential. The firm reiterated a Buy rating on the stock, also highlighting Lumvoa's differentiated profile relative to Tepezza.





