11 days ago
MLB playoff games on TV today: Schedule, times, TV channels, live streams to watch ALCS, NLCS games originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
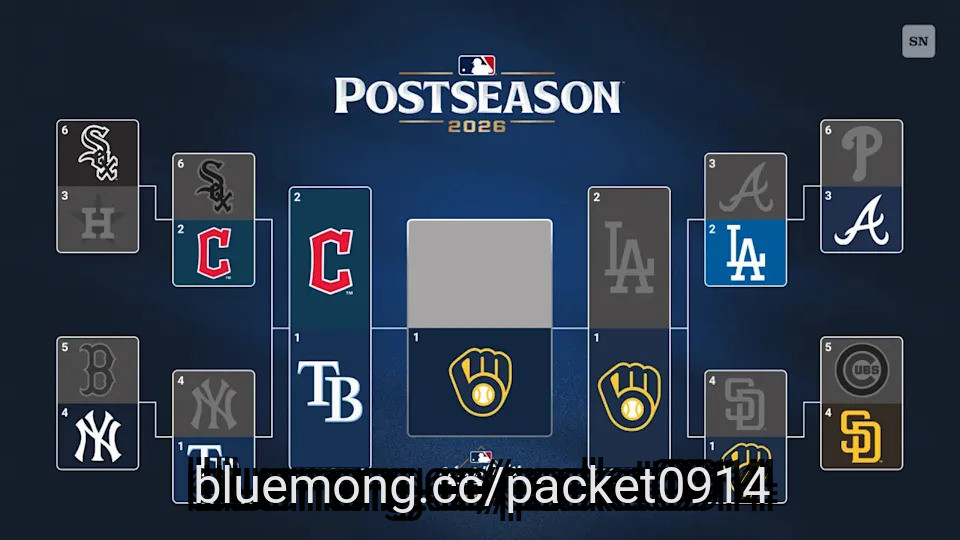
The 2026 World Series could be set Monday night, with the Rays on the brink of advancing as they host Game 6 against the Guardians.
Tampa Bay's 3-1 win Sunday put Cleveland on the brink, needing a pair of wins at Tropicana Field to return to the Fall Classic for the first time since 2016. The Rays are trying to reach the World Series for the third time, but their most recent trip came in the COVID-shortened 2020 season when all the games were played in Arlington, Texas, so their fans mostly missed out that time.
The Rays got a brilliant pitching performance from Drew Rasmussen in Game 5 and will look for more of the same Monday with veteran Freddy Peralta on the mound. The trade-deadline acquisition started Game 2 of this series and was dominant, holding the Guardians to four hits in six scoreless innings of a 3-1 Tampa Bay win. He also pitched 2/3 of an inning in relief Saturday in Game 4.
Cleveland's pitching situation is unclear but it will be all hands on deck for Stephen Vogt as the Guardians hope their offense can get going the way it did to turn around the Division Series against the White Sox. Can they stay alive, or will the top-seeded Rays move on?
#Guardians #sporting #World

11 days ago
I'm living proof of the saying that "kids keep you young." My wife and I don't need social media. We've got multiple social barometers living in our house. But my usual reaction to every new trend or slang that enters their lexicon ("cooked" and "tuff" have been the new favorites) is skepticism. Before I try to figure out how much attention I need to put into what has them hyped, I try to figure out how serious they are about their enthusiasm.
Sunday's fantasy football action left me in a similar spot. We didn't get many massive box score performances from our stars. Instead, Week 6 was about our mid- and late-round picks or waiver-wire acquisitions. And with some giving us repeat results, the storylines coming out of Sunday should have us adjusting how we approach fantasy free agency on Tuesday.
Both Trevor Lawrence and C.J. Stroud were hooping all morning. They were the perfect pivot from whatever we had to watch on TNF. But as I was watching the Texans offense, a couple of things stood out.
what a throw from Stroud, too. pic.twitter.com/fz4EbOAKvT https://t.co/2MaTqWpPgd
First, Stroud's command of the offense was at an all-time high. Jacksonville came into the game with the 12th-highest pressure rate. Houston had a twofold response. It used an extra lineman on 35.6% of its plays (a season-high), and Stroud was getting rid of the football in 2.31 seconds (a season-low). The result was not only his lowest pressure rate (8.6%) but also his highest EPA per dropback (0.35). More importantly, the Jaguars' defensive measures, which included blitzing Stroud on 31.4% of his dropbacks, didn't stop him from throwing the ball.
#fantasy


22 days ago
Investing.com -- Shares of Chipotle Mexican Grill (NYSE: CMG) and Starbucks (NASDAQ: SBUX) swung sharply Thursday following a Financial Times report that Starbucks has explored a potential acquisition of the burrito chain.
Before you buy NVIDIA: our AI model's stock picks are beating the market by 120%+. See the list now »
Chipotle shares initially jumped as much as 8% following the report, while Starbucks fell as much as 6%. Both stocks later pared those moves as investors weighed the potential implications of a deal.
Whispers of a potential tie-up had circulated previously, including a report from Semafor, but the speculation was largely dismissed by the market at the time. The Financial Times report carries greater weight, indicating that Starbucks has worked with advisers in recent months on a potential proposal for Chipotle, which currently has a market value of nearly $39 billion.
The sharp divergence in the stocks, however, could complicate the financial mechanics of a potential transaction. Starbucks' declining share price would reduce the value of any equity used as consideration, while Chipotle's rally increases the price Starbucks would need to pay for the company. The status of Starbucks' plans, including whether it has made a formal offer, remains unclear.
#starbucks #market #shares


22 days ago
Amcor plc (NYSE:AMCR) isn't a flashy business. Most people probably don't know much about the company, even though they come across its products every day. The company makes the packaging used for food, drinks, healthcare products, beauty products, and plenty of other everyday items.
That gives the company an interesting quality from an investment perspective. Consumers may cut back on certain purchases when the economy gets tougher, but they still need to buy food, medicine, and other basic products. About 60% of Amcor's markets are tied to nutrition, while health, beauty, and wellness make up another 25%. Billionaires are gravitating towards another packaging company, and that has also returned nearly 20% in the past year. Find here.
The company's size is another advantage. Amcor operates across a large global manufacturing network and has relationships with major customers that have been built over many years. It also offers a wide range of packaging formats and materials. For a large multinational customer, being able to deal with one supplier across multiple markets can be a meaningful advantage. The Berry Global acquisition has made Amcor even larger, although it also brought more debt onto the balance sheet.
Amcor plc (NYSE:AMCR) pays $0.65 per share every quarter, giving investors an annual dividend of $2.60. At the October 7 closing price of $41.26, that works out to a yield of about 6.3%. That's a big yield for a company selling products that are tied to everyday consumption. However, a high yield doesn't automatically make a dividend attractive. What matters is whether the business can actually afford to keep paying it. Amcor's latest numbers offer some comfort. Its steady dividend growth is one reason the stock remains popular with income-focused investors.
The company generated $1.303 billion in free cash flow during fiscal 2026, while adjusted diluted EPS came in at $4.02, up 13% from the previous year. Amcor also increased its annual dividend to $2.60. On an adjusted earnings basis, the payout ratio is around 65%. That's not unusual for a mature company and doesn't immediately raise a red flag.
#NYSE

22 days ago
Khaby Lame turned a simple comedy concept into a global creator business. The Senegalese-born Italian star built his following by silently mocking complicated life-hack videos. His signature facial expressions and palms-up gesture became instantly recognizable. Lame has more than 160 million TikTok followers and was ranked among the world's highest-earning creators in 2025. Forbes estimated his earnings at $20 million that year. But what is Khaby Lame's net worth?
Lame's rise started after he lost his factory job during Italy's COVID-19 lockdown in 2020. TikTok gave him an audience, but brand partnerships turned that attention into money. Forbes Africa further reports that Lame has worked with brands including Hugo Boss, Airbnb and Binance. His business now stretches beyond TikTok, making Khaby Lame's net worth a bigger creator-economy story.
Yes, but the $975 million headline needs context. In January 2026, Rich Sparkle Holdings announced its acquisition of Step Distinctive Limited, a company tied to Lame's brand. According to Forbes Africa, Lame owned 49% of Step Distinctive before the transaction.
The deal involved Rich Sparkle shares rather than a straightforward cash payment. Forbes Africa also reported that Lame's stake reached a paper value of $6.6 billion when Rich Sparkle's stock surged.
That figure did not mean Lame suddenly had $6.6 billion in cash. Forbes also raised concerns about Rich Sparkle's small public float and the difficulty of using its stock price to measure Lame's actual wealth.
#rich #million #distinctive

23 days ago
Realty Income (NYSE: O) buyers who entered at the 2013 acquisition milestone turned $1,000 into $2,444, a 144% total return through October 2026.
Buying when Realty Income joined the Dividend Aristocrats in 2020 at $54.21 left investors with just 0.07% total return after six years, as dividends failed to offset share price decline.
Prestige-driven entries consistently underperformed, while the best recent result came after shares already fell, with the 2024 Spirit Realty entry returning 13%.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Realty Income (NYSE:O) built its reputation on reliable monthly income. (Seven of our favorite monthly payers are rounded up in this free report.) Among the key milestones discussed here, its first two were excellent entry points; the three that followed were poor ones. Each return below runs from the milestone's adjusted price to the October 6, 2026, close of $54.25, adjusted for splits and dividends.
#income #october #dividends #price

23 days ago
XOM has raised its dividend for 43 straight years, while CVX yields 3.45% with Hess acquisition synergies running 50% above initial targets.
EPD's distributable cash flow covered its 6% distribution 1.9x last quarter, with a trailing payout ratio of just 56% on adjusted cash flow.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Energy has a reputation for boom and bust, yet the sector's largest companies have turned volatile commodities into some of the market's most reliable income. Exxon Mobil (NYSE:XOM) alone has grown its annual dividend per share for 43 consecutive years. The four large caps below split into two integrated oil majors and two midstream toll-road operators. Each pairs a well-covered payout with strong cash generation, making them natural candidates for a long-term income portfolio.
At a recent price of $163.83, Exxon's annualized forward dividend of $4.12 per share works out to a 2.51% yield. The quarterly payout is $1.03, up from $0.99 after a 4% raise late last year.
#income
24 days ago
Paramount completed its $111bn acquisition of Warner Bros Discovery on Tuesday, consolidating some of the world's most recognizable studios and news outlets after a bidding war with Netflix and months of legal turmoil.
The new company, now called Skydance, will have David Ellison, the son of a billionaire tech mogul, at its helm, with the former CEO of Mattel, Ynon Kreiz, as co-executive. They will oversee Paramount and Warner Bros' movie studios, HBO Max, CBS News and CNN.
"Today is a historic day, not just for Skydance but for our entire industry," Ellison said in a statement. "From the start, our ambition was to bring these two storied studios together and create a stronger competitor, with the talent, resources, and reach to tell great stories in every genre, on every platform, for audiences everywhere. Now that ambition is a reality."
The consolidation of Paramount and Warner Bros combines two of the last five legacy studios in Hollywood, which includes Disney, Universal Pictures and Sony Pictures.
Though the merger was approved in June, California, New York and 10 other states sued Paramount over concerns that the move would "extinguish" competition and lead to fewer movie theaters in theaters and at home.
#studios #ellison

1 month ago
Investors eager to buy into the futuristic vision of profitable driverless vehicles will get their chance soon. May Mobility is aiming to become the first U.S. publicly listed pure-play option for an autonomous ride-hailing technology company. It is poised to go public through a special purpose acquisition company (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the combined company at roughly $1.4 billion.
It's expected to operate as May Mobility. trading on the Nasdaq exchange under MAY. But before investors get too excited, let's pump the brakes and take a look at the details.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's easy for investors to get excited about the opportunity, but many might not be aware of the potential market size or growth prospects. The global robotaxi market is projected to reach about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. commercial autonomous vehicles (AVs) is projected to expand from only about 4,000 vehicles currently to around 35,000 by 2030 -- or about 8% of the ride-sharing market.
A year ago this month, Bank of America projected that the long-term U.S. total addressable market (TAM) for AV ride-hailing is a trillion-dollar opportunity as companies such as May Mobility aim to replace the drivers that take roughly 70% of every fare. It's also important for investors to realize how early in the game this is: Alphabet's Waymo, with an estimated $350 million in annualized revenue, would represent only about 0.5% of U.S. ride-hailing bookings.
#vehicles #company #roughly #billion

1 month ago
Titan International, Inc. (NYSE:TWI) announced a definitive agreement on September 21 to sell its Italtractor ITM undercarriage business to USCO S.p.A. The initial purchase price is approximately $207 million, while the stated total cash value reaches up to approximately $285 million. Understanding that difference is central to ******* sing the financial flexibility the disposal could create.
Titan International, Inc. (NYSE:TWI) expects approximately $23 million from closing adjustments and $11 million in dividends before closing. A further $6 million depends on ITM meeting specified 2026 performance criteria. The headline also includes $38 million in dividends received in earlier years.
Subtracting those historical dividends leaves approximately $247 million in potential future gross receipts, including the earnout, or $241 million without it. These calculations use the announced estimates and span different payment dates. Final adjustments, taxes, and transaction costs will determine how much cash becomes available for deployment.
The disclosed dollar amounts were translated at €1.00 to $1.148, the September 18, 2026 exchange rate. Currency movements could increase or reduce the eventual dollar receipts.
Titan International, Inc. (NYSE:TWI) intends to use part of the proceeds to reduce debt and pursue growth investments, including acquisitions and partnerships. The disposal would also concentrate resources on wheel and tire operations.
#september #announced

1 month ago
Vista Gold Corp. (NYSEAMERICAN:VGZ) announced on September 21 that it had agreed to be acquired by Artemis Gold Inc. (TSXV:ARTG). Under the agreement signed September 20, shareholders would receive 0.0966 buyer common shares for each existing common share and own approximately 5% of the combined company. That ownership calculation excludes the buyer's existing 4.95% stake in Vista Gold Corp. (NYSEAMERICAN:VGZ), which it intends to cancel at completion.
For shareholders, the trade-off is a smaller interest in a larger mining business with an operating ***** et and development expertise. The central question is whether that combination can supply the capital and execution needed to bring Australia's Mt Todd gold project into production.
Artemis Gold Inc. (TSXV:ARTG) operates the Blackwater mine in British Columbia and expects its future cash generation to support Mt Todd. That offers Vista Gold a potential funding source alongside a team experienced in building and operating mines.
The financial starting point explains the appeal. Vista Gold Corp. (NYSEAMERICAN:VGZ) ended June 2026 with $49.5 million in cash and no debt. Management described that cash as sufficient for interim development objectives. Joining an operating producer could broaden the resources available for the much larger task of construction.
The acquisition requires no cash consideration or new acquisition debt. Preserving the buyer's financial capacity could leave more room for investment, although the share exchange itself does not raise construction funding.
#cash

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

1 month ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


1 month ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount


1 month ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional

1 month ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE

1 month ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

1 month ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


1 month ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
1 month ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target

1 month ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year
1 month ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

1 month ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


1 month ago
NextEra Energy, Inc. (NYSE:NEE) has outlined its growth targets for 2026 and beyond. This comes as the company advances plans to acquire Dominion Energy Inc (NYSE:D). It's a $67 billion all-stock transaction expected to close before the end of next year. If the merger is completed as expected, it would result in the largest US electricity producer.
NextEra's business is already growing, and Dominion is expected to increase the growth rate. The deal's promise is exciting, but its value to investors ultimately depends on NextEra securing regulatory approvals and successfully integrating Dominion ***** ets.
NextEra Energy, Inc. (NYSE:NEE) has reaffirmed its 2026 adjusted EPS guidance of $3.92 to $4.02 and said it was targeting the high end of that range. NextEra also said it expects adjusted EPS to grow at a compound annual rate of at least 8% through 2032 and is targeting the same growth rate through 2035, off the 2025 base.
NextEra also plans to continue rewarding its shareholders with higher dividends. The company expects its dividend per share to grow at a roughly 10% annual rate through 2026, off the 2024 base. It expects the dividend to grow 6% a year through 2028 from the 2026 base.
The EPS and dividend growth projections give investors a financial foundation for evaluating the Dominion deal. NextEra does not need Dominion simply to prevent a growth slowdown. Instead, it's looking to add another growth engine through the acquisition.
#dominion #rate
1 month ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents

1 month ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic

1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Ripple-backed XRP treasury company Evernorth Holdings has lined up $30 million in new financing as it prepares to go public through a merger with Armada Acquisition Corp. II (NASDAQ:XRPN).
The deal would bring Evernorth onto Nasdaq under the XRPN ticker, giving public-market investors exposure to a company built around accumulating XRP (CRYPTO: XRP) and deploying it across the XRP ecosystem.
Evernorth said the new financing may be used to buy more XRP and fund other ecosystem investments. The $30 million arrives when the merger closes, which the company expects in the fourth quarter.
Evernorth and an affiliate held 473.1 million XRP at the end of 2025. At around $1.38 per token, $30 million would buy roughly another 21.7 million XRP, or less than 5% of that existing position.
#financing #merger