

4 days ago
Chinese independent refiners may be about to start reducing their processing rates as international oil prices rise and supply from major exporters such as Venezuela and Iran dries up as a result of U.S. foreign policy decisions.
"Teapots are unlikely to be able to afford a full shift to mainstream grades," an Energy Aspects ***** yst said this week, as quoted by Bloomberg. The so-called teapots are more sensitive to adverse oil market changes due to their refining margins being slimmer than those of state-owned majors. These margins have already fallen to breakeven, from around $10 per barrel in early July, Jianan Sun also said.
China imported 37.93 million tons, or 8.93 million barrels per day of crude oil in August, up by 6.2% compared to July, and further recovering from the decade-low seen in June, official Chinese customs data showed on Tuesday. The August import level was still 23.4% lower compared to the same month last year, but it's a marked improvement from the June lows of just 7.1 million bpd.
China slashed its total crude oil imports to a decade low in June, culminating three months of very low import levels amid high prices and constrained supply from the Middle East. This affected refinery output, which in turn contributed to the global fuel squeeze that is now set to deepen and extend in time as fighting in the Middle East continues and intensifies, pushing oil prices higher and sapping some refiners' appetite for the commodity.
With Venezuelan and Iranian crude all but gone, Chinese refiners will probably lean more heavily on Russian crude in the coming weeks. However, Russian crude prices are also on the rise on the futures market, in tune with all the other blends that trade internationally, which will likely put a lid on demand.
#june #july #China #middle
"Teapots are unlikely to be able to afford a full shift to mainstream grades," an Energy Aspects ***** yst said this week, as quoted by Bloomberg. The so-called teapots are more sensitive to adverse oil market changes due to their refining margins being slimmer than those of state-owned majors. These margins have already fallen to breakeven, from around $10 per barrel in early July, Jianan Sun also said.
China imported 37.93 million tons, or 8.93 million barrels per day of crude oil in August, up by 6.2% compared to July, and further recovering from the decade-low seen in June, official Chinese customs data showed on Tuesday. The August import level was still 23.4% lower compared to the same month last year, but it's a marked improvement from the June lows of just 7.1 million bpd.
China slashed its total crude oil imports to a decade low in June, culminating three months of very low import levels amid high prices and constrained supply from the Middle East. This affected refinery output, which in turn contributed to the global fuel squeeze that is now set to deepen and extend in time as fighting in the Middle East continues and intensifies, pushing oil prices higher and sapping some refiners' appetite for the commodity.
With Venezuelan and Iranian crude all but gone, Chinese refiners will probably lean more heavily on Russian crude in the coming weeks. However, Russian crude prices are also on the rise on the futures market, in tune with all the other blends that trade internationally, which will likely put a lid on demand.
#june #july #China #middle
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
9 days ago
Replenish Nutrients Holding Corp (CSE:ERTH, OTC:VVIVF, FRA:7KE) earlier this week outlined how its strategic relationship with Spanish River Carbonatite (SRC) could support a significant production scale-up, with CEO Neil Wiens saying the company has reached an operational "inflection point".
Wiens told Proactive that the relationship initially developed through Replenish Nutrients evaluating Spanish River Carbonatite as an ingredient in its products. He said the material demonstrated strong efficacy when incorporated into the company's blends, leading to discussions about securing greater and more consistent supply.
Following due diligence, SRC made a sizable strategic investment in Replenish Nutrients, while SRC CEO Tim Close has become chairman of the company.
Close described SRC's northern Ontario carbonatite resource as a naturally occurring blend containing calcium, potassium, phosphate and magnesium, together with trace and micronutrients and beneficial microbes.
He said Replenish Nutrients' production capabilities, distribution network and relationships throughout the agricultural supply chain had been important attractions for SRC. Close added that the respective products represented an "ideal fit", with benefits from combining SRC's material with Replenish Nutrients' products.
#nutrients #products #river #wiens
Wiens told Proactive that the relationship initially developed through Replenish Nutrients evaluating Spanish River Carbonatite as an ingredient in its products. He said the material demonstrated strong efficacy when incorporated into the company's blends, leading to discussions about securing greater and more consistent supply.
Following due diligence, SRC made a sizable strategic investment in Replenish Nutrients, while SRC CEO Tim Close has become chairman of the company.
Close described SRC's northern Ontario carbonatite resource as a naturally occurring blend containing calcium, potassium, phosphate and magnesium, together with trace and micronutrients and beneficial microbes.
He said Replenish Nutrients' production capabilities, distribution network and relationships throughout the agricultural supply chain had been important attractions for SRC. Close added that the respective products represented an "ideal fit", with benefits from combining SRC's material with Replenish Nutrients' products.
#nutrients #products #river #wiens

10 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Apple Inc is now being led by John Ternus as the new CEO. Ternus takes over for Tim Cook, who served in the CEO role for 15 years, formerly replacing co-founder Steve Jobs.
Cook stepped down on Aug. 31, 2026.
During Cook's time as CEO, Apple went through several changes and introduced multiple new product lines that exist today. Cook's tenure as head of Apple also saw the technology company explode in value, becoming one of the most valuable companies in the world.
Here's a look back at how much Apple stock is up since Cook took over as CEO.
#commission
Apple Inc is now being led by John Ternus as the new CEO. Ternus takes over for Tim Cook, who served in the CEO role for 15 years, formerly replacing co-founder Steve Jobs.
Cook stepped down on Aug. 31, 2026.
During Cook's time as CEO, Apple went through several changes and introduced multiple new product lines that exist today. Cook's tenure as head of Apple also saw the technology company explode in value, becoming one of the most valuable companies in the world.
Here's a look back at how much Apple stock is up since Cook took over as CEO.
#commission
11 days ago
For most of its life, Palantir Technologies (NASDAQ:PLTR) has been a government software company.
Even now, with shares near $186 as of this writing, the artificial intelligence (AI) software specialist's biggest business at home is still the one built on government contracts. U.S. government revenue was $809 million in the second quarter, against $764 million for U.S. commercial.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But the gap is down to $45 million, and the two lines are not growing at the same speed. Last quarter, the U.S. commercial side grew 149% year over year. The government side grew 90%.
Roll those curves forward and they cross almost immediately. My prediction: U.S. commercial revenue passes U.S. government revenue in the third quarter of 2026 (the quarter that ends this month), and well before 2027 even if the timing slips.
#quarter
Even now, with shares near $186 as of this writing, the artificial intelligence (AI) software specialist's biggest business at home is still the one built on government contracts. U.S. government revenue was $809 million in the second quarter, against $764 million for U.S. commercial.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But the gap is down to $45 million, and the two lines are not growing at the same speed. Last quarter, the U.S. commercial side grew 149% year over year. The government side grew 90%.
Roll those curves forward and they cross almost immediately. My prediction: U.S. commercial revenue passes U.S. government revenue in the third quarter of 2026 (the quarter that ends this month), and well before 2027 even if the timing slips.
#quarter

12 days ago
Brennan ***** et Management recently released its Q2 2026 investor letter. The letter can be downloaded here. Investors were optimistic about a potential truce with Iran, highlighted by a mid-June memorandum for negotiations on regional security and sanctions, causing oil prices to drop and the market to rally. Despite geopolitical uncertainties, investors remain focused on a surge in AI infrastructure spending, which is expected to heavily influence the global economy, although questions about the returns from this investment loom. Overall, the S&P 500 remains at high valuations, seemingly unfazed by these challenges, while there are few pockets of value left, mostly outside the U.S. market. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Brennan ***** et Management highlighted Garrett Motion Inc. (NASDAQ:GTX). Garrett Motion Inc. (NASDAQ:GTX) designs and manufactures engineered turbocharging and high-speed electric motor technologies for OEMs, distributors, and industrial fields. On August 28, 2026, Garrett Motion Inc. (NASDAQ:GTX) stock closed at $26.66 per share. The one-month return of Garrett Motion Inc. (NASDAQ:GTX) was -12.70%, and its shares gained 105.66% over the past 52 weeks. Garrett Motion Inc. (NASDAQ:GTX) has a market capitalization of $4.97 billion.
Brennan ***** et Management stated the following regarding Garrett Motion Inc. (NASDAQ:GTX) in its Q2 2026 investor letter:
"TIGO and Garrett Motion Inc. (NASDAQ:GTX) operate in vastly different businesses, but our investment journey with each shares some similarities. We believe that both are good businesses. TIGO is an oligopoly of an essential service (broadband and cell phone). Meanwhile, GTX is an oligopoly provider of turbochargers to the automotive industry with a potentially valuable new product portfolio focused on industrial and electric vehicle (EV) markets. At the time of purchase, both stocks were hated and exceptionally cheap. GTX was a post bankruptcy special situation name, and we initially bought preferred shares that ultimately were forcefully converted to common stock. As EV sales expanded across the world, there was understandable concern that GTX's core turbocharger business was at risk and huge uncertainty arose about whether the company could ever crack the EV market. At the time of purchase TIGO traded for ~17% forward free cash flow yield (post rights offering) while GTX sported valuations only slightly higher…." (Click here to read the full text)
#asset
In its second-quarter 2026 investor letter, Brennan ***** et Management highlighted Garrett Motion Inc. (NASDAQ:GTX). Garrett Motion Inc. (NASDAQ:GTX) designs and manufactures engineered turbocharging and high-speed electric motor technologies for OEMs, distributors, and industrial fields. On August 28, 2026, Garrett Motion Inc. (NASDAQ:GTX) stock closed at $26.66 per share. The one-month return of Garrett Motion Inc. (NASDAQ:GTX) was -12.70%, and its shares gained 105.66% over the past 52 weeks. Garrett Motion Inc. (NASDAQ:GTX) has a market capitalization of $4.97 billion.
Brennan ***** et Management stated the following regarding Garrett Motion Inc. (NASDAQ:GTX) in its Q2 2026 investor letter:
"TIGO and Garrett Motion Inc. (NASDAQ:GTX) operate in vastly different businesses, but our investment journey with each shares some similarities. We believe that both are good businesses. TIGO is an oligopoly of an essential service (broadband and cell phone). Meanwhile, GTX is an oligopoly provider of turbochargers to the automotive industry with a potentially valuable new product portfolio focused on industrial and electric vehicle (EV) markets. At the time of purchase, both stocks were hated and exceptionally cheap. GTX was a post bankruptcy special situation name, and we initially bought preferred shares that ultimately were forcefully converted to common stock. As EV sales expanded across the world, there was understandable concern that GTX's core turbocharger business was at risk and huge uncertainty arose about whether the company could ever crack the EV market. At the time of purchase TIGO traded for ~17% forward free cash flow yield (post rights offering) while GTX sported valuations only slightly higher…." (Click here to read the full text)
#asset

13 days ago
Hennessy Fund's Q2 2026 investor letter for the Hennessy Equity and Income Fund. The letter can be downloaded here. The letter discusses portfolio changes, emphasizing opportunities in equity and fixed income markets that can withstand economic uncertainty. The portfolio held businesses with a 23.0% pre-tax return on invested capital versus 16.1% for the S&P 500. The letter notes a reversal in U.S. equities, driven by AI spending and strong earnings, despite cautious sentiment among lower-income households. The focus on high-quality firms with durable advantages is expected to yield positive outcomes as valuation pressures mount, indicating that future market performance may hinge on fundamentals rather than speculative trends. The portfolio aims to capitalize on the overlooked valuations of quality companies, presenting significant investment opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
13 days ago
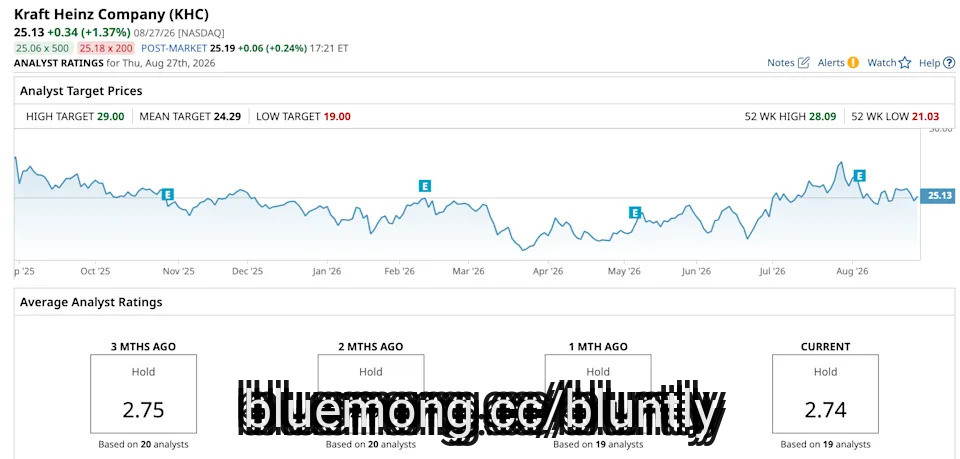
From ketchup and cheese to sauces and other household food staples, Kraft Heinz Company (KHC) has built a portfolio that has become a familiar name in kitchens worldwide. Now, the food giant is making a small but notable change on Wall Street, and KHC stock investors may want to mark their calendars. No, it is not about a new product hitting grocery shelves. This time, the change is happening on Wall Street.
Kraft Heinz is moving its stock listing from the Nasdaq ($NASX) to the New York Stock Exchange (NYSE) on Monday, Sept. 14. The company has traded on the Nasdaq since 2015, following the merger of Kraft Foods and H.J. Heinz. The food giant has called the NYSE its "natural home" as it moves into what CEO Steve Cahillane describes as its next chapter.
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Intel vs. AMD: Why the Market Share Number Is Misleading
A $100 Billion Buildout In Louisiana Is Planned for Starship. What This Means for SPCX Stock.
#Stock #company
Kraft Heinz is moving its stock listing from the Nasdaq ($NASX) to the New York Stock Exchange (NYSE) on Monday, Sept. 14. The company has traded on the Nasdaq since 2015, following the merger of Kraft Foods and H.J. Heinz. The food giant has called the NYSE its "natural home" as it moves into what CEO Steve Cahillane describes as its next chapter.
Jeff Bezos' Heartfelt Tribute to Dolly Parton Drew Brutal Backlash: 'Nobody Wanted to Hear This From You' — He Once Gave Her $100 Million for Charity
Intel vs. AMD: Why the Market Share Number Is Misleading
A $100 Billion Buildout In Louisiana Is Planned for Starship. What This Means for SPCX Stock.
#Stock #company

16 days ago
Nvidia (NVDA) just posted another banger earnings report on Aug. 26, blowing past Wall Street's expectations as sales more than doubled and adjusted profit handily cleared estimates.
Then Raymond James raised the temperature further when the firm's 5-star ****** yst Simon Leopold dropped an eye-popping new Nvidia price target, which is comfortably above other major Wall Street forecasts.
Investors responded with force post earnings, as, per Bloomberg, Nvidia stock jumped 8.7% the following session to $227.9. This added $442 billion in market value, while finishing just below its record close after another punishing choppy stretch.
Moreover, it's important to note that Leopold's call lands after Nvidia stock has gained nearly 21% year to date and around 8% over the past three months, according to Seeking Alpha, despite concerns that AI spending, competition, and elevated memory costs might slow the company's momentum.
Leopold believes Wall Street is still underestimating Nvidia's massive scale and sees supply, rather than customer demand, as arguably the biggest obstacle ahead.
#NVIDIA #wall #nvda
Then Raymond James raised the temperature further when the firm's 5-star ****** yst Simon Leopold dropped an eye-popping new Nvidia price target, which is comfortably above other major Wall Street forecasts.
Investors responded with force post earnings, as, per Bloomberg, Nvidia stock jumped 8.7% the following session to $227.9. This added $442 billion in market value, while finishing just below its record close after another punishing choppy stretch.
Moreover, it's important to note that Leopold's call lands after Nvidia stock has gained nearly 21% year to date and around 8% over the past three months, according to Seeking Alpha, despite concerns that AI spending, competition, and elevated memory costs might slow the company's momentum.
Leopold believes Wall Street is still underestimating Nvidia's massive scale and sees supply, rather than customer demand, as arguably the biggest obstacle ahead.
#NVIDIA #wall #nvda
17 days ago
On August 19, Lowe's Companies (NYSE:LOW) reported second-quarter sales of $26 billion, up 8.3% from a year earlier, even though comparable sales inched up just 0.2%. The headline number hides a split personality inside the business. Pro contractors, online shoppers and Do-It-For-Me customers kept spending, while everyday DIY homeowners pulled back hard enough that management trimmed its full-year guidance. That gap between who is still spending and who isn't is the real story in this quarter.
Pro sales grew again, and management credited small and medium-sized contractors responding to the company's digital planning tools and the MyLowe's Pro Rewards loyalty program, which lets Pros quote, plan, and manage jobs inside Lowe's own platform. Online sales jumped 15.7%, helped by expanded visualization tools and the Mylow AI agent, which has fielded more than 25 million customer and ******* ociate questions since launch.
Notably, CEO Marvin Ellison said the conversion rate for online shoppers who use Mylow runs triple that of shoppers who don't, a sign the tool is doing more than answering questions. Appliances delivered a seventh straight quarter of positive comparable sales, aided by next-day delivery in virtually every US ZIP code and a push into premium products like Traeger grills and a GE Profile refrigerator that scans groceries for an Instacart shopping list. Loyalty is compounding too: MyLowe's Rewards has crossed 30 million members who shop more often and spend more per visit than nonmembers, giving the company a growing base to sell that premium ******* ortment into even while the broader housing market stalls.
Comparable transactions fell 2.1% during the quarter, offset only by a 2.3% rise in average ticket, and management pinned the weakness on weather-sensitive and seasonal categories where DIY shoppers dominate. Executive Vice President Joe McFarland said Pro customers themselves are noticing it, describing homeowners who are "more cautious about their spending" and shifting toward smaller repair jobs instead of full remodels.
That caution pushed Lowe's to guide toward the bottom of its prior range, now targeting roughly $92 billion in sales and $12.25 in adjusted earnings per share for the full year. Margins felt it too. Adjusted operating margin slipped 62 basis points to 14%, and CFO Brandon Sink noted that an $80 million tariff refund benefit was largely wiped out by elevated fuel and transportation costs. The company's Foundation Building Materials and Artisan Design Group acquisitions add another layer of risk, since Sink flagged "softer-for-longer new home construction" pressuring demand in both segments. Inventory climbed to $17.7 billion, up $1.4 billion year over year, and adjusted debt to EBITDA sits at 3.0x against a 2.75x target management doesn't expect to hit until mid-2027. Third quarter earnings are guided to come in roughly 7% below last year's adjusted EPS.
#sales #billion #shoppers #online
Pro sales grew again, and management credited small and medium-sized contractors responding to the company's digital planning tools and the MyLowe's Pro Rewards loyalty program, which lets Pros quote, plan, and manage jobs inside Lowe's own platform. Online sales jumped 15.7%, helped by expanded visualization tools and the Mylow AI agent, which has fielded more than 25 million customer and ******* ociate questions since launch.
Notably, CEO Marvin Ellison said the conversion rate for online shoppers who use Mylow runs triple that of shoppers who don't, a sign the tool is doing more than answering questions. Appliances delivered a seventh straight quarter of positive comparable sales, aided by next-day delivery in virtually every US ZIP code and a push into premium products like Traeger grills and a GE Profile refrigerator that scans groceries for an Instacart shopping list. Loyalty is compounding too: MyLowe's Rewards has crossed 30 million members who shop more often and spend more per visit than nonmembers, giving the company a growing base to sell that premium ******* ortment into even while the broader housing market stalls.
Comparable transactions fell 2.1% during the quarter, offset only by a 2.3% rise in average ticket, and management pinned the weakness on weather-sensitive and seasonal categories where DIY shoppers dominate. Executive Vice President Joe McFarland said Pro customers themselves are noticing it, describing homeowners who are "more cautious about their spending" and shifting toward smaller repair jobs instead of full remodels.
That caution pushed Lowe's to guide toward the bottom of its prior range, now targeting roughly $92 billion in sales and $12.25 in adjusted earnings per share for the full year. Margins felt it too. Adjusted operating margin slipped 62 basis points to 14%, and CFO Brandon Sink noted that an $80 million tariff refund benefit was largely wiped out by elevated fuel and transportation costs. The company's Foundation Building Materials and Artisan Design Group acquisitions add another layer of risk, since Sink flagged "softer-for-longer new home construction" pressuring demand in both segments. Inventory climbed to $17.7 billion, up $1.4 billion year over year, and adjusted debt to EBITDA sits at 3.0x against a 2.75x target management doesn't expect to hit until mid-2027. Third quarter earnings are guided to come in roughly 7% below last year's adjusted EPS.
#sales #billion #shoppers #online

17 days ago
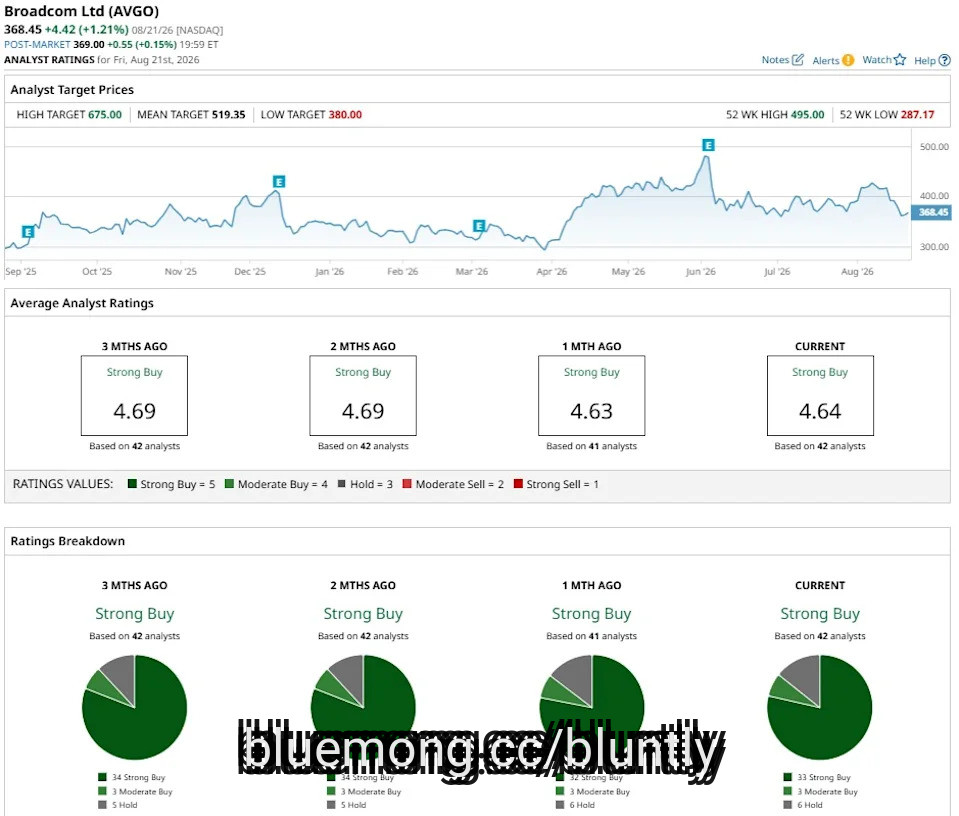
Broadcom (AVGO) is a premier global technology leader specializing in semiconductors and infrastructure software solutions that power mission-critical systems worldwide. Founded in 1961 and headquartered in Palo Alto, California, Broadcom designs advanced chips for networking connectivity, wireless devices, servers, storage, broadband, and industrial applications, alongside robust software for private cloud, mainframe, cybersecurity, and enterprise needs via VMware.
With more than 33,000 employees, thousands of patents, and more than $11 billion invested in research and development in fiscal 2025 alone, the company enables hyperscale data centers, artificial intelligence (AI) acceleration, and secure enterprise infrastructure.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ****** ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#enterprise #avgo
With more than 33,000 employees, thousands of patents, and more than $11 billion invested in research and development in fiscal 2025 alone, the company enables hyperscale data centers, artificial intelligence (AI) acceleration, and secure enterprise infrastructure.
Walmart Stock Is More Expensive Than Nvidia Amid Earnings Miss
SpaceX Stock Just Crashed Below Its IPO Price: Here's the Bull Case ****** ody Can Ignore
A Major Bitcoin Short Squeeze Is Taking MicroStrategy Stock Higher. What Comes Next.
#enterprise #avgo
18 days ago
Langdon Partners' Q2 2026 investor letter for the Langdon Global Smaller Companies Strategy revealed a 9.4% return, lagging behind the MSCI World Small Cap Net Index's 17.0% gain, with a year-to-date return of -10.7% versus the index's 35.3%. A copy of the letter can be downloaded here. Despite the improvement, the seven-percentage point lag behind the benchmark is considered disappointing, and year-to-date performance is still below long-term expectations. The market sends signals through share prices, where rising prices indicate improvement and falling prices suggest decline. However, blindly following these signals can be misleading. The portfolio's performance reflected this, with technology lagging and consumer discretionary stocks performing well. The quarter emphasized that market expectations can shift quickly, demanding careful ***** sment of a business's long-term earning potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Langdon Global Smaller Companies Strategy highlighted YETI Holdings, Inc. (NYSE:YETI). YETI Holdings, Inc. (NYSE:YETI) is a US-based outdoor products company known for coolers, drinkware, and gear. On August 26, 2026, YETI Holdings, Inc. (NYSE:YETI) closed at $41.78 per share, reflecting a market capitalization of $3.05 billion. YETI Holdings, Inc. (NYSE:YETI) posted a one‑month return of -15.18%, while its shares gained 20.78% over the past 52 weeks.
Langdon Global Smaller Companies Strategy stated the following regarding YETI Holdings, Inc. (NYSE:YETI) in its Q2 2026 investor letter:
"Elsewhere, portfolio performance was considerably stronger. Consumer discretionary holdings contributed 4.0%, outperforming the benchmark sector by approximately 2.7 percentage points, while financial holdings also added positively on both an absolute and relative basis. Watches of Switzerland was the largest individual contributor, followed by YETI Holdings, Inc. (NYSE:YETI) and DO & CO. Goosehead Insurance, L1 Group and several other holdings also made meaningful positive contributions.
Markets are forward-looking, but their horizon is elastic. When uncertainty rises, the market's gaze into the future shortens. Investors begin to demand immediate clarity, effectively penalizing long-duration ***** ets. By compressing its time horizon, the market discounts far-off cash flows at a much higher rate. This change in investor behaviour can produce a significant decline in a share price, even when the business's long-term earning power has changed relatively little. For long-term investors, these moments of shortened market duration deserve intense attention.
#long #smaller
In its Q2 2026 investor letter, Langdon Global Smaller Companies Strategy highlighted YETI Holdings, Inc. (NYSE:YETI). YETI Holdings, Inc. (NYSE:YETI) is a US-based outdoor products company known for coolers, drinkware, and gear. On August 26, 2026, YETI Holdings, Inc. (NYSE:YETI) closed at $41.78 per share, reflecting a market capitalization of $3.05 billion. YETI Holdings, Inc. (NYSE:YETI) posted a one‑month return of -15.18%, while its shares gained 20.78% over the past 52 weeks.
Langdon Global Smaller Companies Strategy stated the following regarding YETI Holdings, Inc. (NYSE:YETI) in its Q2 2026 investor letter:
"Elsewhere, portfolio performance was considerably stronger. Consumer discretionary holdings contributed 4.0%, outperforming the benchmark sector by approximately 2.7 percentage points, while financial holdings also added positively on both an absolute and relative basis. Watches of Switzerland was the largest individual contributor, followed by YETI Holdings, Inc. (NYSE:YETI) and DO & CO. Goosehead Insurance, L1 Group and several other holdings also made meaningful positive contributions.
Markets are forward-looking, but their horizon is elastic. When uncertainty rises, the market's gaze into the future shortens. Investors begin to demand immediate clarity, effectively penalizing long-duration ***** ets. By compressing its time horizon, the market discounts far-off cash flows at a much higher rate. This change in investor behaviour can produce a significant decline in a share price, even when the business's long-term earning power has changed relatively little. For long-term investors, these moments of shortened market duration deserve intense attention.
#long #smaller
19 days ago
By Mike Scarcella
WASHINGTON, Aug 25 (Reuters) - Alphabet's Google on Tuesday expanded its Gemini Enterprise artificial intelligence platform with new tools for lawyers and law firms, accelerating a race among technology companies to meet legal sector demand for AI.
The company said its Gemini Enterprise for Legal would help law firms use AI to manage routine and complex work to allow lawyers to focus on higher-value services, while keeping their data secure and confidential.
The new plug-in for Gemini Enterprise includes integration with legal software and data platforms and a stable of AI agents that Google said can handle specialized legal and administrative functions without significant human oversight.
Alphabet launched Gemini Enterprise for business customers in October, in a bid to attract more corporate clients with its AI offerings. Google Cloud has become one of Alphabet's fastest-growing businesses.
#Legal #lawyers #firms #mike
WASHINGTON, Aug 25 (Reuters) - Alphabet's Google on Tuesday expanded its Gemini Enterprise artificial intelligence platform with new tools for lawyers and law firms, accelerating a race among technology companies to meet legal sector demand for AI.
The company said its Gemini Enterprise for Legal would help law firms use AI to manage routine and complex work to allow lawyers to focus on higher-value services, while keeping their data secure and confidential.
The new plug-in for Gemini Enterprise includes integration with legal software and data platforms and a stable of AI agents that Google said can handle specialized legal and administrative functions without significant human oversight.
Alphabet launched Gemini Enterprise for business customers in October, in a bid to attract more corporate clients with its AI offerings. Google Cloud has become one of Alphabet's fastest-growing businesses.
#Legal #lawyers #firms #mike
20 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record full-year net sales and operating income, marking the fourth consecutive year of top-line growth despite a challenging operating environment.
Retail segment performance was driven by the successful acquisition of Bachan's and continued momentum in specialty bakery, specifically Texas Roadhouse dinner rolls which grew 28.1% in the quarter.
Gross margin expansion for the 12th consecutive quarter was attributed to a multi-year network restructuring, including the sale of the Milpitas facility and optimization of the Horse Cave and College Park plants.
Foodservice stability was maintained through strategic partnerships with high-growth national QSR chains like Chick-fil-A, Domino's, and Taco Bell, offsetting declines in smaller accounts.
#year #Growth #tell #retail
Achieved record full-year net sales and operating income, marking the fourth consecutive year of top-line growth despite a challenging operating environment.
Retail segment performance was driven by the successful acquisition of Bachan's and continued momentum in specialty bakery, specifically Texas Roadhouse dinner rolls which grew 28.1% in the quarter.
Gross margin expansion for the 12th consecutive quarter was attributed to a multi-year network restructuring, including the sale of the Milpitas facility and optimization of the Horse Cave and College Park plants.
Foodservice stability was maintained through strategic partnerships with high-growth national QSR chains like Chick-fil-A, Domino's, and Taco Bell, offsetting declines in smaller accounts.
#year #Growth #tell #retail

20 days ago
Oracle (NYSE: ORCL) stock has plummeted by 56% from last year's record high, but I'm not convinced this is a good buying opportunity. Although the company operates some of the world's best data centers for processing artificial intelligence (AI) workloads, investors are concerned about its substantial debts, especially because some of its top customers could struggle to fulfill their financial obligations over the next few years.
Oracle will have an opportunity to ease some of those jitters in early September when it releases its financial results for its fiscal 2027 first quarter (ending Aug. 31), but here's why the report -- expected on Sept. 8 -- probably won't turn sentiment around.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Oracle has a diverse business spanning enterprise software, database systems, AI infrastructure, and more. All eyes are on the cloud infrastructure segment right now, which is where the company logs the revenue it earns from renting data center computing capacity to AI customers.
Oracle's data centers are filled with thousands of advanced chips from suppliers like Nvidia and Advanced Micro Devices, connected by proprietary random direct memory access networking (RDMA) technology that moves information between components faster than traditional Ethernet networks. Moreover, Oracle's infrastructure is highly automated by software, so the company can bring new locations online faster than competitors that rely on human-led processes.
#signal #infrastructure #flashing #advanced
Oracle will have an opportunity to ease some of those jitters in early September when it releases its financial results for its fiscal 2027 first quarter (ending Aug. 31), but here's why the report -- expected on Sept. 8 -- probably won't turn sentiment around.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Oracle has a diverse business spanning enterprise software, database systems, AI infrastructure, and more. All eyes are on the cloud infrastructure segment right now, which is where the company logs the revenue it earns from renting data center computing capacity to AI customers.
Oracle's data centers are filled with thousands of advanced chips from suppliers like Nvidia and Advanced Micro Devices, connected by proprietary random direct memory access networking (RDMA) technology that moves information between components faster than traditional Ethernet networks. Moreover, Oracle's infrastructure is highly automated by software, so the company can bring new locations online faster than competitors that rely on human-led processes.
#signal #infrastructure #flashing #advanced


24 days ago
By Karen Brettell and Niket Nishant
Aug 21 (Reuters) - The dollar slipped on Friday, trading near a three-month low against the euro, as concerns mounted that the U.S. Treasury's plan to expand buybacks of longer-dated government debt could weigh further on the U.S. currency.
Treasury Secretary Scott Bessent said Thursday he may increase the government's repurchases of Treasuries even further, a day after the department surprised markets by pledging to at least double the size of its buybacks of longer-dated debt in an effort to rein in bond yields.
Long-dated yields jumped this week, with the 30-year yield reaching its highest level since 2007. Traders cited concerns over the deteriorating fiscal outlook, heavy issuance, geopolitical risk stemming from the war with Iran, and uncertainty over the Federal Reserve's policy path.
Analysts say that holding yields down will simply shift the burden of fiscal concerns onto the currency. And so far the strategy hasn't achieved its primary goal, as yields have crept back higher.
#longer #debt #karen
Aug 21 (Reuters) - The dollar slipped on Friday, trading near a three-month low against the euro, as concerns mounted that the U.S. Treasury's plan to expand buybacks of longer-dated government debt could weigh further on the U.S. currency.
Treasury Secretary Scott Bessent said Thursday he may increase the government's repurchases of Treasuries even further, a day after the department surprised markets by pledging to at least double the size of its buybacks of longer-dated debt in an effort to rein in bond yields.
Long-dated yields jumped this week, with the 30-year yield reaching its highest level since 2007. Traders cited concerns over the deteriorating fiscal outlook, heavy issuance, geopolitical risk stemming from the war with Iran, and uncertainty over the Federal Reserve's policy path.
Analysts say that holding yields down will simply shift the burden of fiscal concerns onto the currency. And so far the strategy hasn't achieved its primary goal, as yields have crept back higher.
#longer #debt #karen

24 days ago
On August 11, Aramark (NYSE:ARMK) reported fiscal third-quarter results that beat expectations on nearly every line, with organic revenue climbing 9% to $5 billion and adjusted earnings per share jumping almost 30% from a year earlier. The company also raised its full-year revenue growth outlook and pointed to a growing footprint inside AI data centers as its next act. A closer look at the numbers shows some of that strength leaning on adjustments and calendar quirks that are worth understanding before getting too excited.
Aramark's growth is broad and not dependent on one segment. Organic revenue in the Food and Support Services/FSS US segment rose 8% to $3.5 billion, and would have topped 10% if not for a calendar shift in the education business that pushed some revenue into the fourth quarter. FSS International organic revenue rose 11% to $1.5 billion, led by strong performance in Spain, Canada, the UK, and Germany, contributing to nearly 200 new client locations added globally during the quarter. Client retention sits near 98%, and the company has landed more than $1.6 billion in new client wins so far this fiscal year, 51% ahead of the same stretch a year ago.
The more interesting story sits inside Aramark Nexus, the unit built to serve hospitality needs at data centers and industrial sites. Aramark began operating its first site for a major hyperscaler in Texas just weeks before the earnings call, and management said the scope of work across that client's two locations has already grown roughly 40% beyond original estimates. A second site is being mobilized, and Aramark separately signed a multiyear deal with an AI data center colocation provider to run hospitality services for workforce communities in Wyoming and Texas, with the first site set to open early in the next fiscal year. If AI infrastructure spending keeps expanding the way it has, Aramark has positioned itself as a landlord of sorts for the workers building it.
Not every number tells as clean a story. Aramark's GAAP earnings per share came in at $0.36 for the quarter, well below the $0.52 adjusted figure the company highlighted, a reminder that a meaningful chunk of the improvement comes from items management chooses to exclude. The calendar shift created an estimated $18 million to $19 million drag on adjusted operating income this quarter, temporarily weighing down reported growth rates across the international and domestic food segments. That means the reported 13% AOI growth and 9% revenue growth both come with an asterisk, making quarter-over-quarter comparisons harder to trust at face value.
#fiscal
Aramark's growth is broad and not dependent on one segment. Organic revenue in the Food and Support Services/FSS US segment rose 8% to $3.5 billion, and would have topped 10% if not for a calendar shift in the education business that pushed some revenue into the fourth quarter. FSS International organic revenue rose 11% to $1.5 billion, led by strong performance in Spain, Canada, the UK, and Germany, contributing to nearly 200 new client locations added globally during the quarter. Client retention sits near 98%, and the company has landed more than $1.6 billion in new client wins so far this fiscal year, 51% ahead of the same stretch a year ago.
The more interesting story sits inside Aramark Nexus, the unit built to serve hospitality needs at data centers and industrial sites. Aramark began operating its first site for a major hyperscaler in Texas just weeks before the earnings call, and management said the scope of work across that client's two locations has already grown roughly 40% beyond original estimates. A second site is being mobilized, and Aramark separately signed a multiyear deal with an AI data center colocation provider to run hospitality services for workforce communities in Wyoming and Texas, with the first site set to open early in the next fiscal year. If AI infrastructure spending keeps expanding the way it has, Aramark has positioned itself as a landlord of sorts for the workers building it.
Not every number tells as clean a story. Aramark's GAAP earnings per share came in at $0.36 for the quarter, well below the $0.52 adjusted figure the company highlighted, a reminder that a meaningful chunk of the improvement comes from items management chooses to exclude. The calendar shift created an estimated $18 million to $19 million drag on adjusted operating income this quarter, temporarily weighing down reported growth rates across the international and domestic food segments. That means the reported 13% AOI growth and 9% revenue growth both come with an asterisk, making quarter-over-quarter comparisons harder to trust at face value.
#fiscal
27 days ago
On August 6, Petrobras (NYSE:PBR) held its second-quarter 2026 earnings webcast, reporting strong quarterly net profit and gross profit driven by record production volumes rather than peak Brent prices. Executives said the quarter delivered the highest recurring net profit and the highest gross profit in company history, even though oil prices in the period ranked outside the ten highest quarters Petrobras has ever posted. That distinction matters, because it points to something more durable than a commodity tailwind: production that keeps beating its own targets.
Petrobras pumped 2.7 million barrels of oil per day in the quarter, a 15% jump from a year earlier and 200,000 barrels per day above its own 2.5 million target. Several platforms are doing more than they were built for. The Almirante Tamandare FPSO at Buzios has a nameplate capacity of 225,000 barrels per day but hit a peak of 270,000, making it the highest-producing platform in Brazil. Six other platforms are running above their original capacity too, adding more than 100,000 barrels per day combined, output the company says required no new construction spending.
Refining kept pace. Utilization topped 100% for the quarter and hit 102% in April and May, while the company held its mix of diesel, jet fuel, and gasoline steady rather than shifting toward cheaper output. That let Petrobras cut oil product imports by 40% from the prior quarter and lift exports by 12%. Adjusted EBITDA, excluding one-off items, reached $20 billion, up 70% from the first quarter and nearly double a year earlier, while operating cash flow climbed almost 50% quarter-over-quarter to $12.3 billion.
Growth this fast isn't free. Petrobras spent $5.3 billion on capital projects in the quarter, up 4% from the first quarter's $5.1 billion, with 82% of that aimed at exploration and production. First-half operating expenses reached $11.7 billion, already more than half the full-year plan of $20.2 billion, pressured by freight and logistics costs tied to the added output plus exchange-rate swings. Management said expenses could exceed that plan if logistics costs and the exchange rate hold at current levels.
Debt tells a mixed story. Petrobras prepaid $2.9 billion in loans and bonds during the quarter and is targeting $65 billion in net debt over its plan horizon, versus the $60.4 billion net debt and $70.8 billion gross debt it reported. But renegotiating recharter and well-service contracts to save over $1 billion through 2030 required reorganizing lease liabilities right away, pushing them higher near-term even as future payments shrink. And despite record output, Petrobras still needs imports to fully cover diesel demand.
#debt #highest #barrels #first
Petrobras pumped 2.7 million barrels of oil per day in the quarter, a 15% jump from a year earlier and 200,000 barrels per day above its own 2.5 million target. Several platforms are doing more than they were built for. The Almirante Tamandare FPSO at Buzios has a nameplate capacity of 225,000 barrels per day but hit a peak of 270,000, making it the highest-producing platform in Brazil. Six other platforms are running above their original capacity too, adding more than 100,000 barrels per day combined, output the company says required no new construction spending.
Refining kept pace. Utilization topped 100% for the quarter and hit 102% in April and May, while the company held its mix of diesel, jet fuel, and gasoline steady rather than shifting toward cheaper output. That let Petrobras cut oil product imports by 40% from the prior quarter and lift exports by 12%. Adjusted EBITDA, excluding one-off items, reached $20 billion, up 70% from the first quarter and nearly double a year earlier, while operating cash flow climbed almost 50% quarter-over-quarter to $12.3 billion.
Growth this fast isn't free. Petrobras spent $5.3 billion on capital projects in the quarter, up 4% from the first quarter's $5.1 billion, with 82% of that aimed at exploration and production. First-half operating expenses reached $11.7 billion, already more than half the full-year plan of $20.2 billion, pressured by freight and logistics costs tied to the added output plus exchange-rate swings. Management said expenses could exceed that plan if logistics costs and the exchange rate hold at current levels.
Debt tells a mixed story. Petrobras prepaid $2.9 billion in loans and bonds during the quarter and is targeting $65 billion in net debt over its plan horizon, versus the $60.4 billion net debt and $70.8 billion gross debt it reported. But renegotiating recharter and well-service contracts to save over $1 billion through 2030 required reorganizing lease liabilities right away, pushing them higher near-term even as future payments shrink. And despite record output, Petrobras still needs imports to fully cover diesel demand.
#debt #highest #barrels #first

1 month ago
When Nvidia (NVDA) rival AMD (AMD) uncorks its earnings report later today, it's reasonable to expect a whole lot of bullishness.
That comes as no surprise. AMD has been knocking it out of the park for more than two years amid strong demand for its AI chips.
AMD has earned its rockstar status with investors, which a casual dive on Yahoo Finance AlphaSpace quickly uncovers.
Here are a couple of bullish call-outs on AMD's fundamentals:
Revenue growth accelerated from 8.9% in the quarter ended June 30, 2024, to 37.8% for the quarter ended March 31, 2026.
#NVIDIA #nvda
That comes as no surprise. AMD has been knocking it out of the park for more than two years amid strong demand for its AI chips.
AMD has earned its rockstar status with investors, which a casual dive on Yahoo Finance AlphaSpace quickly uncovers.
Here are a couple of bullish call-outs on AMD's fundamentals:
Revenue growth accelerated from 8.9% in the quarter ended June 30, 2024, to 37.8% for the quarter ended March 31, 2026.
#NVIDIA #nvda


1 month ago
Shares of chip company On Semiconductor rose Monday after it beat ******* ysts’ expectations for both earnings and revenue in its second fiscal quarter. It also raised guidance on revenue from sales to artificial intelligence data centers, which it now says will more than double this year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
The semiconductor materials supplier reported second-quarter earnings per share of $1.19 on sales of $1.4 billion. Wall Street was looking for EPS of $1.07 and sales of just under $1.4 billion.
#company #semiconductor #revenue #Monday
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
The semiconductor materials supplier reported second-quarter earnings per share of $1.19 on sales of $1.4 billion. Wall Street was looking for EPS of $1.07 and sales of just under $1.4 billion.
#company #semiconductor #revenue #Monday

1 month ago
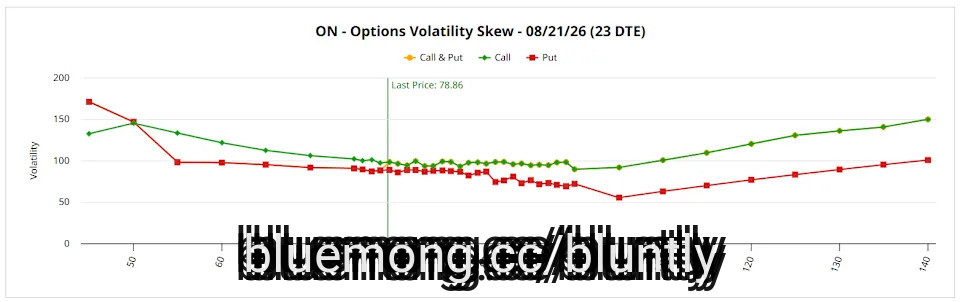
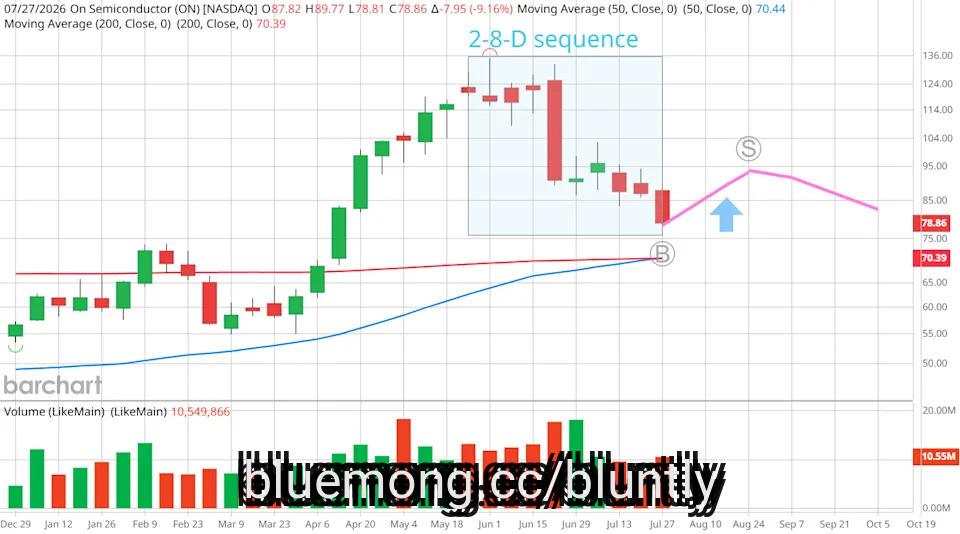
By no means is ON Semiconductor (ON) an easy trade to navigate. Investors are increasingly skeptical about execution risks, particularly tied to how the tech company can fully integrate its $7 billion all-stock deal to buy edge-AI and connectivity chipmaker Synaptics (SYNA). At the same time, the strategic decision should help the firm gain additional ground in the competitive AI ****** e, thus raising an interesting question for ON stock.
Basically, there's a compelling quantitative case that the ticker could be a discount, at least in the near term. It's not a matter of opinion but rather inductive logic. Previously, when ON stock suffered similar bearish cycles, the share price popped higher — perhaps due to dead-cat bounce mechanics — before settling into a consolidatory range.
Corning Delivers Strong FCF Results, But Investors Play GLW Stock's Drop With an Unusual Short-Put Play
How Volatility Clustering Could Trigger a Comeback in Baker Hughes (BKR) Stock
Long Call ****** erfly Trade Ideas for July 27th
#trade #synaptics #corning
Basically, there's a compelling quantitative case that the ticker could be a discount, at least in the near term. It's not a matter of opinion but rather inductive logic. Previously, when ON stock suffered similar bearish cycles, the share price popped higher — perhaps due to dead-cat bounce mechanics — before settling into a consolidatory range.
Corning Delivers Strong FCF Results, But Investors Play GLW Stock's Drop With an Unusual Short-Put Play
How Volatility Clustering Could Trigger a Comeback in Baker Hughes (BKR) Stock
Long Call ****** erfly Trade Ideas for July 27th
#trade #synaptics #corning
2 months ago
A post asking whether 20,000 XRP is enough for retirement savings drew heavy criticism on X, exposing how far optimistic price targets sit from current reality.
The debate cuts to a question every crypto holder eventually faces: how much is actually enough?
A savings threshold is the portfolio size needed to generate a reliable income without depleting the principal. Jake Claver, chairman of DAG Family Office, applied that idea to XRP holdings this week.
His scenario rested on a single ***** umption. If XRP reached $100 per token, a 20,000 XRP position would be worth $2 million. From there, the math looked simple enough.
A conservative 5% annual return on that sum would produce roughly $100,000 in pre-tax income each year.
#enough #office
The debate cuts to a question every crypto holder eventually faces: how much is actually enough?
A savings threshold is the portfolio size needed to generate a reliable income without depleting the principal. Jake Claver, chairman of DAG Family Office, applied that idea to XRP holdings this week.
His scenario rested on a single ***** umption. If XRP reached $100 per token, a 20,000 XRP position would be worth $2 million. From there, the math looked simple enough.
A conservative 5% annual return on that sum would produce roughly $100,000 in pre-tax income each year.
#enough #office


2 months ago
ZenaTech, Inc. (NASDAQ:ZENA), an AI drone company, announced Thursday that it completed its 26th Drone as a Service acquisition, buying Dayton, Ohio-based BA Land Professionals LLC.
The transaction gives ZenaTech its first Ohio location and expands its U.S. network to 12 states. BA Land Professionals is licensed in Ohio, Kentucky, Tennessee and North Carolina.
The surveying firm serves construction, energy, industrial and government customers. Its services include land surveying, construction layout, and topographic and boundary surveys.
It also provides ALTA/NSPS surveys, drone and LiDAR mapping, and GPS control services.
Read Also:ZenaTech's IQ Quad Moves Closer To US Government Drone Procurement Path
#drone
The transaction gives ZenaTech its first Ohio location and expands its U.S. network to 12 states. BA Land Professionals is licensed in Ohio, Kentucky, Tennessee and North Carolina.
The surveying firm serves construction, energy, industrial and government customers. Its services include land surveying, construction layout, and topographic and boundary surveys.
It also provides ALTA/NSPS surveys, drone and LiDAR mapping, and GPS control services.
Read Also:ZenaTech's IQ Quad Moves Closer To US Government Drone Procurement Path
#drone



2 months ago
With a market cap of $12.2 billion, GoDaddy Inc. (GDDY) is a trusted growth partner to more than 20 million entrepreneurs worldwide, helping them build, manage, and grow their businesses online. Beyond domain names, GoDaddy provides integrated solutions that connect digital identity, web presence, commerce, and payments to drive profitable growth.
The Tempe, Arizona-based company is slated to announce its fiscal Q2 2026 results after the market closes on Thursday, Jul. 30. Ahead of the release, ***** ysts predict GDDY to report EPS of $1.72, a growth of nearly 22% from $1.41 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in each of the past four quarters.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#godaddy
The Tempe, Arizona-based company is slated to announce its fiscal Q2 2026 results after the market closes on Thursday, Jul. 30. Ahead of the release, ***** ysts predict GDDY to report EPS of $1.72, a growth of nearly 22% from $1.41 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in each of the past four quarters.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#godaddy


2 months ago
New York-based Take-Two Interactive Software, Inc. (TTWO) is a leading video game publisher and developer that creates, markets, and distributes interactive entertainment for consoles, PCs, and mobile devices. Valued at a market cap of $44.4 billion, the company owns some of the gaming industry's most valuable franchises and generates revenue from full-game sales, digital downloads, in-game purchases, subscriptions, and mobile gaming.
TTWO is expected to announce its fiscal Q1 2027 earnings before the market opens on Friday, Aug. 7. Ahead of this event, ******* ysts expect this gaming company to report a profit of $0.08 per share, down 81.4% from $0.43 per share in the year-ago quarter. The company has topped Wall Street's bottom-line estimates in each of the last four quarters.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#game #company #interactive #billion
TTWO is expected to announce its fiscal Q1 2027 earnings before the market opens on Friday, Aug. 7. Ahead of this event, ******* ysts expect this gaming company to report a profit of $0.08 per share, down 81.4% from $0.43 per share in the year-ago quarter. The company has topped Wall Street's bottom-line estimates in each of the last four quarters.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#game #company #interactive #billion


2 months ago
Updated July 21, 2026 4:52 pm ET
Listen
(3 min)
The latest Market Talks covering Financial Services. Exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
1635 ET – Capital One Financial’s total credit-card delinquency rate fell both quarter-over-quarter and year-over-year, offering a sign that the bank’s cardholders are doing a better job of keeping up with their bills. The company says total credit-card delinquency rate edged down to 3.4% in the second quarter, compared to 3.7% in the first quarter and 3.6% in the year-ago quarter. The delinquency rate in its consumer banking division, meanwhile, was lower than a year ago but higher than the first quarter, coming in around 4.3%. (kelly.cloonanwsj.com)
#delinquency #financial #card #first
Listen
(3 min)
The latest Market Talks covering Financial Services. Exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
1635 ET – Capital One Financial’s total credit-card delinquency rate fell both quarter-over-quarter and year-over-year, offering a sign that the bank’s cardholders are doing a better job of keeping up with their bills. The company says total credit-card delinquency rate edged down to 3.4% in the second quarter, compared to 3.7% in the first quarter and 3.6% in the year-ago quarter. The delinquency rate in its consumer banking division, meanwhile, was lower than a year ago but higher than the first quarter, coming in around 4.3%. (kelly.cloonanwsj.com)
#delinquency #financial #card #first

2 months ago
It's been a tumultuous year for Meta Platforms (NASDAQ: META) investors. Despite the company's strong underlying ad revenue and user engagement metrics, the stock has been under meaningful pressure.
While the stock at one point cratered by as much as 20%, shares are now down just 2% year to date -- showing some degree of resilience as capital continues rotating toward companies that are viewed as clearer artificial intelligence (AI) infrastructure winners. With its next earnings reported scheduled for July 29, I predict Meta CEO Mark Zuckerberg will take that opportunity to announce a major strategic shift that could reframe Meta's role in the AI economy.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Meta's stock has been under pressure this year for one reason: the scale of its AI investments. The company is deploying unprecedented sums to build data centers, design custom silicon, and procure GPU clusters to support its AI initiatives.
Those capital expenditures have compressed its free cash flow in the near term. Investors are growing increasingly concerned about the potential timeline for Meta to deliver meaningful returns on this capital, especially amid questions about how AI will be monetized across the broader tech sector.
#year #Stock #flashing
While the stock at one point cratered by as much as 20%, shares are now down just 2% year to date -- showing some degree of resilience as capital continues rotating toward companies that are viewed as clearer artificial intelligence (AI) infrastructure winners. With its next earnings reported scheduled for July 29, I predict Meta CEO Mark Zuckerberg will take that opportunity to announce a major strategic shift that could reframe Meta's role in the AI economy.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Meta's stock has been under pressure this year for one reason: the scale of its AI investments. The company is deploying unprecedented sums to build data centers, design custom silicon, and procure GPU clusters to support its AI initiatives.
Those capital expenditures have compressed its free cash flow in the near term. Investors are growing increasingly concerned about the potential timeline for Meta to deliver meaningful returns on this capital, especially amid questions about how AI will be monetized across the broader tech sector.
#year #Stock #flashing


2 months ago
J.B. Hunt Transport Services reported second-quarter earnings of $1.91 per diluted share on revenue of $3.5 billion, topping Wall Street expectations and sending the company's stock higher in after-hours trading. The results compared to earnings of $1.31 per share and revenue of $2.93 billion in the same period a year earlier. ******* ysts had expected earnings of $1.74 per share and revenue of $3.25 billion, according to Bloomberg.
Shares of J.B. Hunt climbed as high as 9.5% in after-hours trading Wednesday following the results.
Operating income rose 32% to $259.5 million from $197.3 million a year earlier, the company said. The improvement was driven by higher revenue, productivity gains, and continued efforts to reduce costs, partially offset by higher purchased transportation expenses.
Intermodal was the clear highlight of the quarter, generating $1.75 billion in revenue — a 22% year-over-year increase — while operating income jumped 58% to $150.9 million. The segment's volume grew 10%, with the company attributing the gain to rising fuel costs and constrained trucking supply that pushed customers toward rail-connected freight options. Transcontinental network loads rose 5% while Eastern network loads grew 16%.
Dedicated Contract Services revenue increased 9% to $921 million, with operating income up 9% to $102.5 million. The Integrated Capacity Solutions segment posted revenue of $388 million, up 49%, swinging to an operating profit of $1.7 million from a loss of $3.6 million a year earlier. The Truckload segment posted a $1.3 million operating loss despite a 35% increase in revenue to $240 million, as higher purchased transportation costs outweighed gains. Final Mile Services revenue fell 6% to $198 million, with operating income declining 30% to $5.6 million, due to known business losses tied to efforts to improve revenue quality.
Shares of J.B. Hunt climbed as high as 9.5% in after-hours trading Wednesday following the results.
Operating income rose 32% to $259.5 million from $197.3 million a year earlier, the company said. The improvement was driven by higher revenue, productivity gains, and continued efforts to reduce costs, partially offset by higher purchased transportation expenses.
Intermodal was the clear highlight of the quarter, generating $1.75 billion in revenue — a 22% year-over-year increase — while operating income jumped 58% to $150.9 million. The segment's volume grew 10%, with the company attributing the gain to rising fuel costs and constrained trucking supply that pushed customers toward rail-connected freight options. Transcontinental network loads rose 5% while Eastern network loads grew 16%.
Dedicated Contract Services revenue increased 9% to $921 million, with operating income up 9% to $102.5 million. The Integrated Capacity Solutions segment posted revenue of $388 million, up 49%, swinging to an operating profit of $1.7 million from a loss of $3.6 million a year earlier. The Truckload segment posted a $1.3 million operating loss despite a 35% increase in revenue to $240 million, as higher purchased transportation costs outweighed gains. Final Mile Services revenue fell 6% to $198 million, with operating income declining 30% to $5.6 million, due to known business losses tied to efforts to improve revenue quality.

2 months ago
Walmart (NASDAQ: WMT) has quietly become one of the market's strongest large-cap performers over the past few years, rewarding investors who had long underestimated it. Lately, though, the run has cooled. Yet even after slipping from a 52-week high near $135 to about $114 as of this writing, the stock still fetches about 40 times earnings -- a growth stock multiple for a retailer that rings up most of its sales on low-margin groceries.
That gap is the whole question for anyone buying today. Can a company this enormous grow into a price like that over the next five years? The answer sits in a surprisingly small corner of the business.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
On the surface, Walmart's results read like a big, dependable retailer's. In its fiscal first quarter of 2027 (the period ended April 30, 2026), total revenue rose 7.3% to $177.8 billion. Comparable sales in the U.S., excluding fuel, grew 4.1% -- healthy, but a notch below the 4.5% it posted a year earlier. Growth like that doesn't explain such a premium.
The explanation sits beneath the top line. Walmart's fastest-growing businesses happen to be its highest-margin, and they are finally big enough to matter. In the U.S., its Walmart Connect ad platform grew 44%, part of a broad jump in higher-margin advertising across the company. Membership fee income climbed 17.4% globally. And e-commerce sales rose 26%, now about 23% of net sales.
That gap is the whole question for anyone buying today. Can a company this enormous grow into a price like that over the next five years? The answer sits in a surprisingly small corner of the business.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
On the surface, Walmart's results read like a big, dependable retailer's. In its fiscal first quarter of 2027 (the period ended April 30, 2026), total revenue rose 7.3% to $177.8 billion. Comparable sales in the U.S., excluding fuel, grew 4.1% -- healthy, but a notch below the 4.5% it posted a year earlier. Growth like that doesn't explain such a premium.
The explanation sits beneath the top line. Walmart's fastest-growing businesses happen to be its highest-margin, and they are finally big enough to matter. In the U.S., its Walmart Connect ad platform grew 44%, part of a broad jump in higher-margin advertising across the company. Membership fee income climbed 17.4% globally. And e-commerce sales rose 26%, now about 23% of net sales.

2 months ago
Access to this page has been denied because we believe you are using automation tools to browse the website.
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #10391c08 -7cc5-11f1-807d-830efb1b1e08
This may happen as a result of the following:
Please make sure that Javascript and cookies are enabled on your browser and that you are not blocking them from loading.
Reference ID: #10391c08 -7cc5-11f1-807d-830efb1b1e08




