1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

1 month ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

1 month ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley

1 month ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
1 month ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


1 month ago
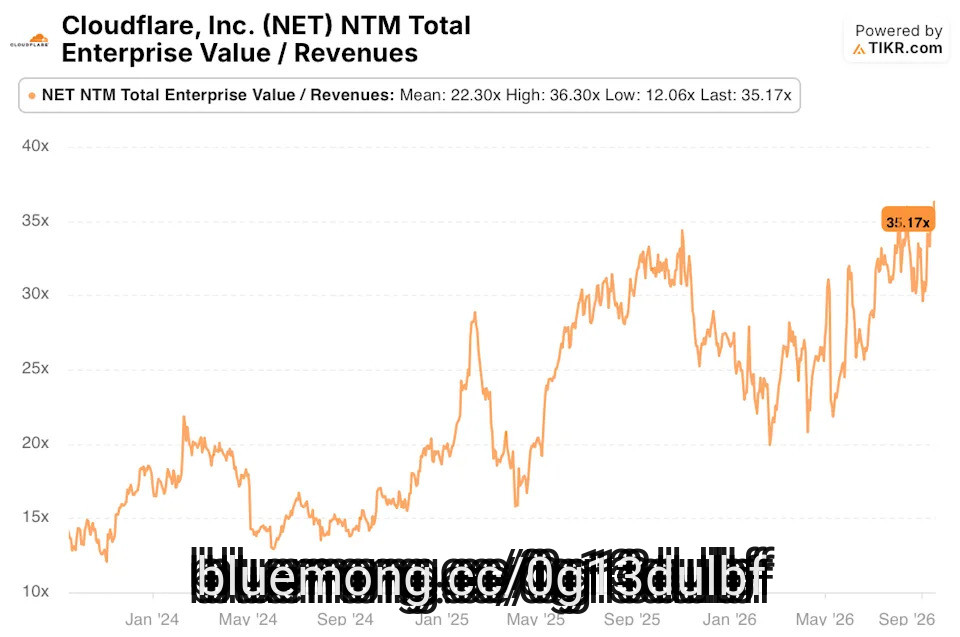
Cloudflare's Q2 beat and reaccelerating growth (36% revenue growth, 120% net dollar retention, record large customer adds) pushed NET stock to new highs, but the market has already paid up: NTM EV/Revenue sits at 35.17x, just below its all-time high of 36.30x and well above its roughly two-year average of 22.30x.
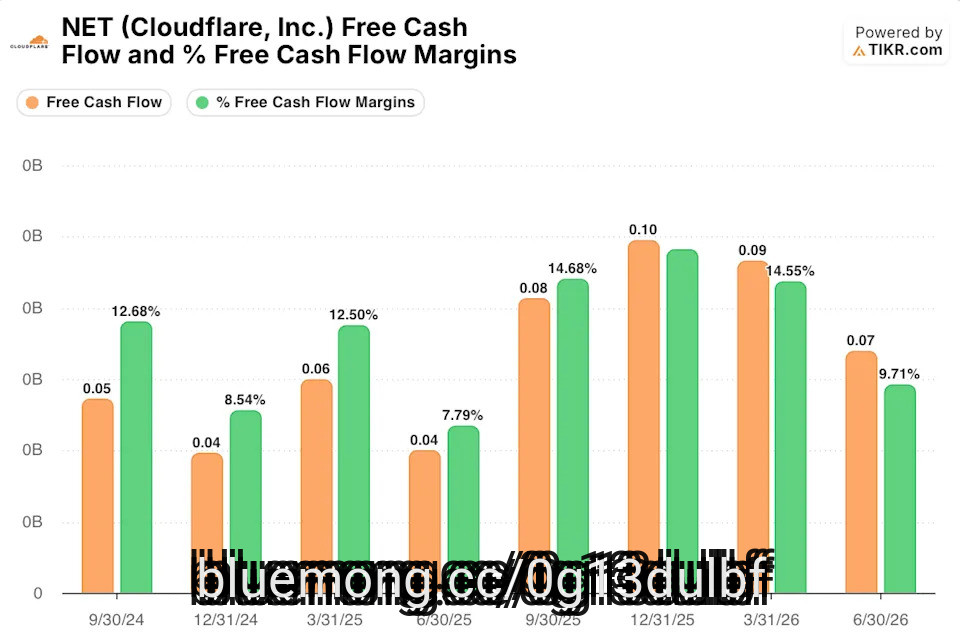
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar

1 month ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings

1 month ago
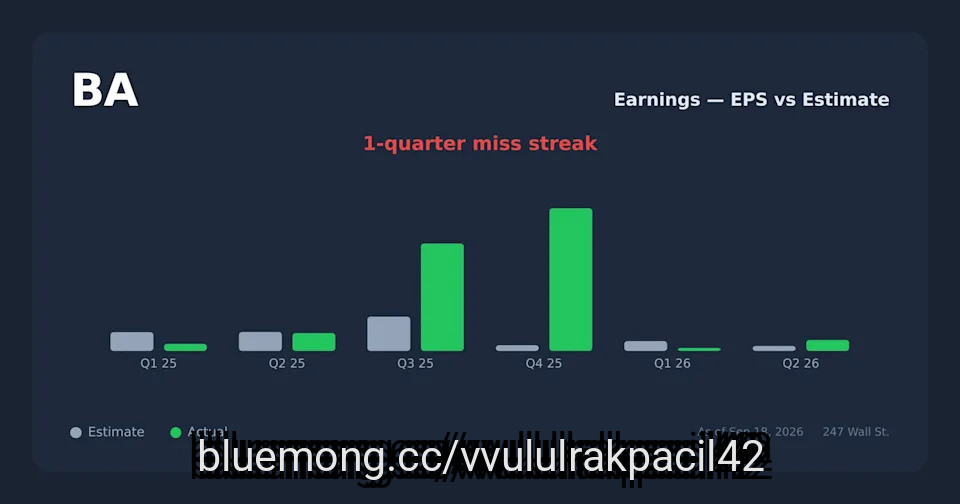
Boeing locked Korean Air into a $36.2 billion order spanning 737 MAX, 787-10, and 777X variants, but no deliveries arrive until the early 2030s.
Lockheed Martin posts steady profits while Boeing burns cash lifting production rates, carrying $600 million in quarterly interest expense that pressures GAAP results.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Boeing didn't make the cut. Enter your email to see the names that beat BA. The report is free. Enter your email and see if any of your stocks made the cut.
Boeing (NYSE:BA) confirmed a firm Korean Air order for the stretched 737 MAX, 787-10, and 777X in passenger and freighter variants, valued at $36.2 billion. Deliveries begin in the early 2030s.
These aircraft were previously logged as unidentified orders from a commitment announced last summer, so this is existing backlog getting a customer name rather than fresh demand.
#boeing #deliveries



1 month ago
Jim Cramer put Intel Corporation (NASDAQ:INTC) and Micron Technology, Inc. (NASDAQ:MU) at the top of his technology stock list during the September 17 episode of Mad Money, as he said:
Yesterday, I said that people would buy tech. We got that in spades today. I continue to recommend the cybersecurity stocks, and I'd add Okta to the list because rogue agents cannot be stopped unless we can identify them first. That's Okta's job. I still think that Intel, as I tell club members, is the best stock in show, and Micron, number two… Both their products are in short supply. I just bought some Micron, candidly.
Intel Corporation's (NASDAQ:INTC) second-quarter revenue rose 25% year over year to $16.1 billion, while Data Center and AI revenue increased 59% to $6.3 billion. Intel Products generated $4.8 billion of operating income in the second quarter, up from $2.7 billion a year earlier, while Data Center and AI operating income increased $1.8 billion to $2.5 billion.
The company said client supply constraints are expected to ease in the second half of 2026, while industry-wide constraints affecting Data Center and AI products are expected to persist into 2027.
Micron Technology, Inc.'s (NASDAQ:MU) fiscal third-quarter GAAP operating margin reached 80.4%, up from 67.6% in the prior quarter and 23.3% a year earlier. Its non-GAAP operating margin was 81.2%. Operating cash flow reached $25.4 billion. The company also said DRAM inventories were "very tight and below 120 days."
#NASDAQ #operating #year #data

1 month ago
Anthropic's initial public offering (IPO), expected no earlier than mid-October, will be a test of just how hungry the financial markets still are for exposure to artificial intelligence (AI). The S&P 500 (SNPINDEX: ^GSPC) is going to react depending on how that test goes. Its backers want a valuation of $2 trillion or more, which would top ******* e Exploration Technologies as the biggest IPO ever if it happens.
Don't expect S&P 500 funds to buy it immediately, though. The road for Anthropic entering the S&P 500 is going to be slow, and it could test some nerves along the way.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
By definition, index funds tracking the S&P 500 must buy whatever the S&P 500 adds to its list of stocks.
Anthropic probably won't get special treatment, given that on June 4, S&P Dow Jones Indices declined to loosen its rules for mega-cap listings. Those rules still require 12 months as a public company, at least 10% of shares being publicly held, and reported positive earnings under generally accepted accounting principles (GAAP).
#snpindex


1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson


1 month ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


1 month ago
Starting the lightning round on September 14, when a caller inquired about SentinelOne, Inc. (NYSE:S), Mad Money host Jim Cramer remarked:
No, look, I think you don't need, look, my Charitable Trust owns both Palo Alto and CrowdStrike. It's already too many. I think either one of those two is superior to letter S.
The latest results show a large difference in scale. SentinelOne's fiscal second-quarter 2027 revenue rose 21% year over year to $292 million, while annualized recurring revenue increased 22% to $1.218 billion. Palo Alto Networks, Inc.'s (NASDAQ:PANW) fiscal fourth-quarter 2026 revenue rose 34% to $3.41 billion, while Next-Generation Security ARR increased 63% to $9.10 billion. Additionally, we have discussed CRWD in our recent article, "Jim Cramer Highlights CrowdStrike (CRWD) as AI Security Concerns Lift Cybersecurity Stocks."
SentinelOne, Inc. (NYSE:S) non-GAAP operating margin reached 10% in fiscal Q2 2027, up from 2% a year earlier, while its GAAP operating margin improved to negative 31% from negative 33%. The company guided for fiscal third-quarter revenue of $309 million to $311 million and full-year revenue of $1.202 billion to $1.207 billion.
Palo Alto Networks, Inc. (NASDAQ:PANW) reported approximately $1 billion of non-GAAP operating income in its fiscal fourth quarter of 2026, compared with $768 million a year earlier. Adjusted free cash flow reached approximately $1.3 billion, while GAAP operating income was $172 million versus $497 million a year earlier. Palo Alto CEO Nikesh Arora said in the September 1 earnings release that the latest advances in AI are "elevating cybersecurity to the top of the CIO priority list."
#billion #year #gaap #operating

1 month ago
On September 14, during the episode of Mad Money, Jim Cramer said CrowdStrike Holdings, Inc. (NASDAQ:CRWD) is emerging as a beneficiary of growing concerns over the cybersecurity risks created by artificial intelligence, as he said:
Over the weekend, the co-founder and CEO of Anthropic published an essay where he pushed for a slowdown among the frontier AI labs in order to handle newfound security concerns. In response to that, the cybersecurity cohort just went crazy because there are the companies that can prevent AI agents from randomly hacking into networks all over the world, and it's the cybersecurity companies. Take CrowdStrike, which shot up nearly 14% today, leading the S&P 500, something I feel great about, of course, because we own it big for the Charitable Trust. These guys have been adamant that AI represented a great opportunity for their business, and now Wall Street's finally gotten the memo.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) second-quarter fiscal 2027 revenue increased 26% year over year to $1.47 billion, while ending annual recurring revenue rose 25% to $5.84 billion. Net new ARR reached a record $332.8 million, and free cash flow was $377.4 million. The company also raised its full-year fiscal 2027 net new ARR growth outlook to 34% at the midpoint, up 630 basis points. CEO George Kurtz said the company believes securing AI is its "largest market opportunity in our history."
Kurtz said on September 14 that AI-driven threats are already operating at machine speed, describing the emerging threat as autonomous campaigns rather than individual hackers. He identified endpoints, cloud workloads and SaaS as key battlegrounds and said "enforcement at machine speed" is needed to stop AI agents in motion. CrowdStrike has responded by expanding into AI-agent, model and infrastructure protection, including Continuous Identity for AI Agents and Falcon AI Detection and Response.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) valuation leaves little room for a meaningful slowdown in growth. Yahoo Finance currently shows a forward P/E of approximately 188.7 times and a price-to-sales ratio of roughly 44.6 times. Those multiples leave little room for a material slowdown in ARR growth, weaker adoption of newer products, or greater competitive pressure. The company also remains much less profitable on a GAAP basis than its adjusted results suggest. The company reported a $33.2 million GAAP operating loss in the latest quarter against $371.6 million of non-GAAP operating income, while stock-based compensation and related employer payroll taxes totaled $399 million.
#crwd

1 month ago
CoinShares PLC (NASDAQ:CSHR) reported approximately $27.6 million in net inflows for the first half of 2026, yet U.S. GAAP revenue fell 35.7% to $51.4 million from $80 million. The September 14 results show that attracting **** ets and restoring earnings are different challenges.
Asset Management revenue declined to $40 million from $59.6 million. CoinShares PLC (NASDAQ:CSHR) attributed that decline primarily to lower average **** ets under management (AUM) following weaker digital-asset prices. Product mix and a targeted fee reduction add another hurdle: the revenue generated by each dollar of **** ets.
Positive flows during a difficult market provide evidence of demand. The physically backed product platform generated approximately $155.9 million in net inflows during the half. That suggests CoinShares PLC (NASDAQ:CSHR) can attract capital even when market performance reduces the value of existing holdings.
CoinShares PLC (NASDAQ:CSHR) reported that AUM recovered to approximately $6.93 billion by August 31 from $5.52 billion at June 30. Whether that recovery restores fee revenue depends on average **** ets and product mix.
A broader product mix also has strategic value. Lower-fee products may reach customers who would otherwise invest elsewhere. For CoinShares PLC (NASDAQ:CSHR), accepting a lower fee can make economic sense if it secures durable **** ets at an attractive cost.
#revenue
1 month ago
Hub Group, Inc. (NASDAQ:HUBG) disclosed on September 14 that preliminary, unaudited first-half 2026 revenue was expected to reach $1.7 billion to $1.8 billion, near management's expectations. Yet management anticipated an operating loss before one-time charges. This non-GAAP presentation excludes those charges, but neither the loss nor the exclusions were quantified.
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better

1 month ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE


1 month ago
Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) reported a widening split between dining and entertainment in its September 14 second-quarter results. Food-and-beverage revenue increased to $211.5 million from $192.9 million, while entertainment revenue fell to $332.6 million from $364.5 million.
For the fiscal quarter ended August 4, 2026, total revenue declined 2.4% to $544.1 million. Operating income dropped to $19.4 million from $53 million. The GAAP net loss was $12.5 million, versus net income of $11.4 million a year earlier. Stronger restaurant sales are providing support, but the investment question is whether they can also bring customers back to the games.
Food-and-beverage revenue grew approximately 9.6%, giving Dave & Buster's Entertainment, Inc. (NASDAQ:PLAY) an identifiable source of momentum. A more appealing dining experience could encourage repeat visits, group occasions, and longer stays, creating additional opportunities to sell entertainment.
Management reported ongoing growth in food-and-beverage and special-events sales, alongside improving comparable-sales trends in July and the third quarter to date. That suggests the recovery effort has some traction beyond a single revenue category, although the later sales improvement was not quantified.
Management also said remodeled locations continued to outperform the system on comparable sales. That supports selective investment in existing venues, provided the additional revenue earns adequate returns on remodeling costs.
#entertainment #dave

1 month ago
The Children's Place, Inc. (NASDAQ:PLCE) reported on September 14 that fiscal second-quarter net sales declined 18.9% year over year to $241.8 million. Reported gross margin rose to 34.4% from 34.0% a year earlier for the quarter ended August 1, 2026.
The apparent margin improvement depended heavily on $39 million of tariff refunds recognized as a reduction of cost of sales. That benefit was equivalent to nearly 47% of reported gross profit of $83.3 million.
Management said gross margin excluding the refunds declined 1,550 basis points, or 15.5 percentage points, year over year. This non-GAAP comparison removes the cost-of-sales benefit. The central question is whether inventory cleanup can establish a healthier operating base.
The Children's Place, Inc. (NASDAQ:PLCE) reduced inventory to $340.2 million, down 23.2% from $442.7 million a year earlier. A smaller inventory position allows management to improve the merchandise mix and reduce future exposure to aging products.
Clearing excess stock can release working capital and create room for products better aligned with demand. The eventual benefit depends on rebuilding sales with less discounting, but reducing the stock burden is a useful starting point.
#reported #Margin
1 month ago
On September 11, a caller praised The Boeing Company's (NYSE:BA) CEO and asked when the company would overcome the ongoing labor uncertainty and finally move beyond years of sideways stock performance. Mad Money host Jim Cramer replied:
I think that Boeing is ready to go up. But here's the problem. Every time crude goes up a dollar, the stock goes down a dollar. And that, think about it, that was actually the ratio. I did some work on this. And because today crude was down, Boeing went up $5... No, it's so stupid because, in truth, the airlines need more planes because the planes are more fuel-efficient. So they actually do better in this environment, but ******* ody cares. They know that airlines have to borrow money to buy planes and rates are higher, and they think that oil somehow's bad. But what ends up happening is the stock does nothing. I think it's about to go up because I think oil might be peaking unless there's some catastrophe over there.
The Boeing Company's (NYSE:BA) second-quarter results showed improving cash generation, but profitability remained weak. Revenue rose 8% year over year to $24.6 billion, while operating cash flow reached $1.4 billion and free cash flow was $631 million. Its total backlog reached a record $715 billion, including more than 6,200 commercial airplanes. CEO Kelly Ortberg said, "We're ramping up production just as we planned. That's driving higher revenues and improved cash flow." He also said there's more work ahead to ramp production, complete commercial-aircraft certifications and uphold customer commitments. Boeing said the 737-7 and 737-10 had completed flight testing, with deliveries expected to begin in 2027.
The Boeing Company's (NYSE:BA) large backlog has yet to translate into consistent commercial-aircraft profitability, leaving execution and margins as important concerns for investors. Commercial Airplanes delivered 171 aircraft in the second quarter but still posted a $322 million operating loss and a negative 2.7% operating margin. It also reported a $428 million GAAP net loss.
The balance sheet leaves less room for further setbacks. The company ended June with $45.9 billion of consolidated debt against $20 billion of cash and investments in marketable securities. The FAA certified the 737-7 on August 3, while Boeing continues working toward certification of the 737-10. First deliveries of the variants are expected in 2027. The company also recorded $280 million of losses on the VC-25B program in the quarter.
#boeing #cash #commercial

1 month ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

1 month ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ


1 month ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects


1 month ago
Core & Main, Inc. (NYSE:CNM) reported quarterly sales of $2.145 billion on September 9, up 2.5%. Company-defined non-GAAP adjusted EBITDA reached $274 million. The measure adjusts consolidated net income for interest, taxes, depreciation and amortization, equity compensation, debt modification and extinguishment losses, offering expenses, and specified other income or expenses.
Consolidated net income rose 6.4% to $150 million, while GAAP diluted earnings per share increased 10% to $0.77. Diluted weighted-average shares declined approximately 2.5% to 193.4 million. Buybacks amplified an improvement that also had an operating foundation.
The company repurchased $169 million of equity during the quarter, against $62 million of operating cash flow. The investment question is whether cash generation can sustain capital returns alongside the spending needed to grow.
Core & Main, Inc. (NYSE:CNM) benefits from demand for essential infrastructure products. Management highlighted municipal demand, fire protection, treatment plants, and data centers as areas of strength. These end markets provide several sources of business even when construction demand is uneven.
Expense discipline also helped. Quarterly selling, general and administrative expenses declined to $301 million from $302 million. Controlling overhead allows modest sales growth to contribute more to earnings. Stronger volumes would make further earnings gains easier to sustain.
#income #main #quarterly

1 month ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity


1 month ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment


1 month ago
Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) reported on September 9 that fiscal first-quarter revenue increased 11.2% to $3.115 billion, including $2.927 billion of rental revenue, up 12.5%. The quarter ended July 31, 2026.
Management raised fiscal 2027 rental-revenue growth guidance to 7% through 10%, while increasing planned net rental-equipment capital expenditures to $2.4 billion through $2.8 billion. Demand supports expansion, but investors need to ****** s how much cash remains after funding the fleet.
North America Specialty rental revenue grew 25.3%, giving Sunbelt Rentals Holdings, Inc. (NYSE:SUNB) a strong source of growth beyond general equipment rentals. Specialized services can deepen customer relationships and create opportunities to supply several needs on the same project.
The company estimated that the FIFA World Cup contributed 2.5 percentage points to quarterly rental-revenue growth. Serving complex events demonstrates the commercial value of a broad equipment network. The investment opportunity is to turn that capability into recurring work across industrial, energy and construction customers.
Adjusted EBITDA increased 8.7% to $1.315 billion. This company-defined non-GAAP measure adds taxes, net interest, depreciation, amortization, stock-based compensation and specified restructuring costs to net income. Its margin is adjusted EBITDA divided by revenue.
#rentals

1 month ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company

1 month ago
On September 14, Dave & Buster's Entertainment (NASDAQ:PLAY) reported second-quarter fiscal 2026 results that read like two different companies at once. Revenue fell, and the company posted a net loss for the period ended August 4, yet comparable sales, which had been sliding for more than a year, kept getting less bad every month from June through the first five weeks of the third quarter. New CEO Darin Harper is betting that improvement compounds into something bigger.
The clearest evidence is the trend line itself. Comparable store sales fell 5.4% in the first quarter of fiscal 2026, then 2.9% in the second quarter, then just 1.6% in July after a 5% decline in June, and Harper said trends improved further over the first five weeks of the third quarter. Food and beverage sales are moving in the opposite direction entirely, up 7.6% in the quarter and positive for five straight quarters, helped by the Eat & Play Combo, a bundled meal and game credit offer sold through kiosks. Special event sales have now grown for seven consecutive quarters.
Behind that shift sits a rebuilt leadership bench. Dave & Buster's went more than a year without a chief marketing officer, and Harper has since added a CMO, a chief operations officer, a chief technology officer, and a chief legal officer since taking over. The company also leaned on new content, launching 10 games and attractions this year, including tie-ins with Mandalorian and Grogu, John Wick and Stranger Things, after research found more than 70% of guests said new games would bring them back more often. Changes to game pricing pushed play and dwell time up 16% to 20% or more. Six remodeled stores are already outperforming the rest of the chain, and management says the newest remodel template costs less to build than the last one. Net capital spending dropped to $127.6 million through the first half of the year from $155.4 million, and adjusted free cash flow swung to positive $19.5 million from negative $36.5 million, a $56 million improvement.
The headline figures were still rough. Total revenue slipped 2.4% to $544.1 million from $557.4 million a year earlier, and adjusted EBITDA dropped to $98.9 million, an 18.2% margin, from $129.8 million and a 23.3% margin. On a GAAP basis, the company posted a net loss of $12.5 million, or $0.36 per diluted share, versus net income of $11.4 million in the same quarter last year. About $15 million of the EBITDA decline came from items management calls non-normalized, including a $10 million noncash deferral adjustment that did not repeat this year, $3 million in extra preopening costs and $2 million in higher insurance expenses, but even stripped of those, the underlying decline was still roughly $16 million.
#year #first #harper #play

1 month ago
Welltower and Ventas posted SHOP NOI growth of 20.5% and 16.3%, respectively, as senior occupancy rates climb and new supply starts remain at record lows.
Roughly 2 million people turn 80 in 2026, and Ventas CEO Debra Cafaro says the senior population growth rate will more than double over the next decade.
OHI's 5.68% yield carries real tenant risk: Genesis Healthcare is in Chapter 11 with $148 million in loans outstanding and the CEO is retiring.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing and skilled nursing REITs are riding a demographic tide that shows up in the operating data. Roughly two million people will turn 80 in 2026 alone, and Ventas Chair and CEO Debra A. Cafaro told investors that "the leading edge of the nearly 70 million baby boomers has just begun turning 80 this year, ushering in a decade where the growth rate of the senior population more than doubles, yet new starts remain at record lows." Four US-listed equity REITs sit squarely in that trade. Dividend safety leads the **** ysis, so every payout is measured against FFO or AFFO, not GAAP earnings.
#ventas #welltower