

1 month ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
1 month ago
Interested in Motorola Solutions, Inc.? Here are five stocks we like better.
Motorola Solutions expects broad-based growth, projecting 2026 gains of 10%–11% in mission-critical networks, about 11% in video security and about 15% in command-center software, supported by modernization of public-safety and federal infrastructure.
Silvus Technologies is becoming a major defense growth driver, with approximately $850 million in expected 2026 sales at current capacity. Motorola is expanding production, sales and R&D as demand grows for secure communications in contested environments and unmanned-systems operations.
D-Fend Solutions expands Motorola's counter-drone opportunity in public safety, airports, critical infrastructure and venues. The business was selected for a $1.5 billion U.S. Department of Homeland Security grant program and uses cyber-based technology to take control of and safely land threatening drones.
Motorola's $1.5B Bet to Own the Skies
#Growth #safety #infrastructure

1 month ago
(Table below reflects daily flows on September 16, 2026 and ***** et totals as of that date.)
ETF Brand League Table
Welcome to the etf.com league table. On this page, you'll find the U.S. ETF market through different lenses: brand and issuer. What's the difference? The brand is what the ETF says on the tin. For example, "iShares" is the brand of issuer "BlackRock's" ETFs. Because many issuers license their ETF infrastructure to third parties, we present the data in both ways. The identification of the correct brand and legal issuer is done by our key data provider, FactSet.
Brand
AUM ($, mm)
#september #welcome #factset

1 month ago
Blink Charging jumped 6% and ChargePoint rose 4% Wednesday with no news, contracts, or ******* yst actions triggering the synchronized move.
DRIV and SPY each gained less than 1%, isolating the charging trio as speculative flow rather than a broad sector re-rating.
ChargePoint surged 49% over the past month while Blink and EVgo fell 7% and 13%, giving each name a meaningfully different risk profile.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Small-cap electric vehicle charging stocks are running together Wednesday morning with nothing from the companies to explain the bid. The three names climbing in sync while broader mobility exposure barely moves reads as speculative flow into beaten-down charging shares rather than any change in the businesses themselves.
#blink #wednesday #rather

1 month ago
Alluvium ****** et Management, an ****** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. (NASDAQ:CHTR) closed at $141.20 per share. Over the past month, Charter Communications, Inc. (NASDAQ:CHTR) declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. (NASDAQ:CHTR) has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Conventum – Alluvium Global Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) and its tracking stock Liberty Broadband fell 34.1% and 33.7% following the release of Charter's results in April. It seems the market is understandably concerned with the average revenue per user (ARPU) being flat, and the continual loss of internet customers. Competition is intense from both fixed wireless providers and low earth orbit satellite (Starlink). Compared to Charter's cables, these are higher cost and more capacity constrained. Charter's flat ARPU is the result of its decision to provide a demonstrably better offering at a low price - so why is it losing so many internet customers? We do not know the answer. We do know though that it is growing its mobile subscribers at a much faster rate than it is losing its internet customers, and more than half of its residential customers subscribe to more than one product. We also see positives stemming from the pending ****** acquisition, and indeed management increased expected synergies by 60%. It seems to us that the broader market has extrapolated current conditions to perpetuity..." (Click here to read the full text)
#fund
1 month ago
Forgent Power Solutions (NYSE:FPS) shares rose 10.9% in premarket trading on Tuesday after the company released its fiscal fourth-quarter and full-year 2026 financial results.
The results cover the period ended June 30, 2026. Forgent scheduled a conference call for 11:00 a.m. ET to discuss its financial performance and outlook.
The supplied information did not include the company's reported fourth-quarter or full-year revenue, earnings or other financial figures from Tuesday's release.
Ahead of the latest results, Forgent had reported fiscal third-quarter revenue of $379 million, more than double the level recorded a year earlier.
Third-quarter bookings reached $867 million, an increase of 308% year over year and a company record, according to the supplied information. The result increased Forgent's backlog to nearly $2 billion.
#year #quarter #Third #fourth
2 months ago
Saia, Inc. (NASDAQ:SAIA) reported that August less-than-truckload shipments per workday increased 1.1% year over year, while tonnage per workday rose 8.7% and weight per shipment increased 7.5%. For July and August combined, shipments per workday increased 1.0%, tonnage per workday rose 8.3%, and weight per shipment grew 7.2%.
The data show higher freight intensity, but most of the tonnage growth came from heavier shipments rather than strong shipment-count growth. The investment question is whether that mix can improve trailer utilization and spread terminal, driver, and line-haul costs across more freight without weakening yield or service.
Heavier shipments can support operating leverage when added weight fills available trailer capacity and moves through the network efficiently. The 218-terminal network of Saia, Inc. (NASDAQ:SAIA) may provide room to absorb incremental tonnage, although Saia, Inc. (NASDAQ:SAIA) did not disclose network utilization.
Second-quarter results offer evidence that higher volume can translate into improved economics. Saia, Inc. (NASDAQ:SAIA) increased tonnage per workday 8.4%, grew revenue 17.1%, and increased operating income 26%. The operating ratio improved to 86.9% from 87.8%, meaning operating expenses consumed a smaller share of revenue.
Pricing and shipment economics were mixed but constructive. Second-quarter revenue per shipment, excluding fuel surcharge revenue, increased 1.5%. If heavier freight continues to raise revenue per shipment while fixed network costs grow more slowly, Saia, Inc. (NASDAQ:SAIA) could produce additional operating leverage.
#operating #revenue #shipments
2 months ago
CNBC reported that Salesforce, Inc. (NYSE:CRM) reported fiscal second-quarter revenue of $11.35 billion, up 11% year over year and above the $11.32 billion ******* ysts expected. Net income rose to $3.53 billion from $1.89 billion a year earlier, boosted by a $2.6 billion gain on its Anthropic investment.
Shares surged more than 12% on the results and kept climbing the next day after Salesforce CEO Marc Benioff and Anthropic CEO Dario Amodei disclosed "Claudeforce," a plug-in bringing Salesforce data into Claude. "This SaaSpocalypse narrative has been such nonsense," Benioff told CNBC's Jim Cramer. "Frontier models depend on CRM. They don't replace it." Agentforce annualized revenue topped $1.5 billion, up 240% year over year. Salesforce announced a $1.6 billion VA contract and a planned $3.6 billion acquisition of Fin.
The quarter's strength was broad-based, not confined to one metric skeptics could dismiss. Net new annual order value growth was the strongest in four years. Seats grew across Agentforce, Sales, Service, and Slack rather than declining as bears predicted; attrition sat near its lowest level ever, and bookings more than doubled quarter over quarter, directly rebutting the claims the "SaaSpocalypse" narrative was built on.
Agentforce is now a large, fast-growing business on its own, not just a talking point. Annualized revenue from the AI agent platform topped $1.5 billion, up 240% year over year. It gives Salesforce a concrete, rapidly scaling product line that validates its AI strategy with real recurring revenue.
The Claude partnership strengthens Salesforce, Inc. (NYSE:CRM)'s AI offering by giving customers direct access to Anthropic's models within its CRM platform. Incorporating Claude with Salesforce's proprietary customer data could make Agentforce and other AI tools more useful to businesses while giving Salesforce another way to monetize the growing demand for enterprise AI. The partnership also shows Salesforce can work with leading AI model developers rather than relying entirely on its own models.
#billion #year

2 months ago
Florida resident Colleen German is looking for answers and compensation from Walmart after someone hacked her account and charged up $2,000 worth of groceries.
"We don't have $2,000 just to fork out, you know?" she told WFTV News. "This is a hardship for us."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#Florida #german #ramsey
2 months ago
With a market cap of $69.7 billion, Boston Scientific Corporation (BSX) is a global medical technology leader focused on developing innovative solutions that improve patient health and transform lives. The company offers a broad portfolio of high-performance devices and therapies designed to address unmet medical needs while helping reduce healthcare costs.
Companies valued at more than $10 billion are generally considered "large-cap" stocks, and Boston Scientific fits this criterion perfectly. Its technologies support physicians in diagnosing and treating complex cardiovascular, respiratory, digestive, oncological, neurological, and urological conditions.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#boston #scientific


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Capital One Venture Rewards makes sense if you want to earn travel rewards on your everyday purchases. It's easy to use and provides a flexible rewards rate that works with any eligible purchase. That's especially useful because Walmart stores aren't typically categorized as a "grocery store" or "supermarket" for credit card purchases.
Read our full Capital One Venture Rewards review
Why we like it: The Blue Cash Everyday is an excellent gas and grocery card, but those types of purchases don't typically apply to Walmart. However, this card also offers 3% cash back on US online retail purchases of up to $6,000 per year, then 1%*. This category includes purchases on Walmart.com. Some reports say that using Walmart Pay in-store could also trigger this spending category.
*Cash back is received in the form of Reward Dollars that can be redeemed as a statement credit or on Amazon.com at checkout
#walmart #like


2 months ago
(Table below reflects daily flows on August 28, 2026 and ******* et totals as of that date.)
ETF Brand League Table
Welcome to the etf.com league table. On this page, you'll find the U.S. ETF market through different lenses: brand and issuer. What's the difference? The brand is what the ETF says on the tin. For example, "iShares" is the brand of issuer "BlackRock's" ETFs. Because many issuers license their ETF infrastructure to third parties, we present the data in both ways. The identification of the correct brand and legal issuer is done by our key data provider, FactSet.
Brand
AUM ($, mm)
#brand #issuer
2 months ago
Prediction market Kalshi is partnering with brokerage and financial infrastructure start-up Alpaca as it looks to expand internationally.
Individuals and businesses who use Alpaca's brokerage infrastructure now have access to Kalshi's prediction market platform, said the companies in a joint news release.
Alpaca recently secured a U.S. brokerage license that allows it to facilitate orders to buy or sell derivatives contracts.
More From Cryptoprowl:
Goldman Sachs Reiterates Buy Ratings On Coinbase And Robinhood
#brokerage #infrastructure #goldman
2 months ago
Rep. Nancy Pelosi — Washington's most famous stock picker and the congresswoman representing California's 11th district — has now trained her eyes on chipmaker Intel (INTC). According to a recent disclosure, Pelosi's household reportedly bought 10,000 shares of INTC stock on July 24, with a total value ranging from $500,000 and $1 million. Notably, Pelosi also purchased 50 call options on the company with a strike price of $50, expiring on June 17, 2027. This was interesting, as long-term options like what Pelosi purchased suffer less from theta decay or a loss in value due to the passing of time.
Thus, it can be inferred that even if the stock loses value, Pelosi is of the belief that Intel can recover in about a year's time when she can get the stock at as cheap a rate as $50. Further, the $50 strike price gives Pelosi the scope for additional upside if the stock price appreciates.
Why Options Traders Are Betting That Marvell Technology Stock Could Soon Hit $300
1,000 Reasons to Buy AST **** eMobile Stock Now
Nvidia's Equity Portfolio Is Now Worth Over $63 Billion. 3 Top Stocks the Jensen Huang-Led Company Is Buying.
#value #Intel #company


2 months ago
Pharmaceutical giant Johnson & Johnson (NYSE:JNJ) is one of Jim Cramer's favorite stocks in the sector. Over the course of this year, the CNBC TV host has praised the firm on multiple occasions. Among the reasons that he has been optimistic about Johnson & Johnson (NYSE:JNJ) include the firm's cancer drug portfolio and its Triple A balance sheet. For instance, in his July 6th appearance on Mad Money, Cramer remarked that "P&Gs and the J&Js in your portfolio allow you to safely own the techs." With tech stocks struggling recent due to concerns about the data center buildout, it was unsurprising that Johnson & Johnson (NYSE:JNJ) popped up on his radar once again on August 24th:
"I've been using that one stock JNJ to be able to [example] becuase it has a better balance sheet at this point than the US government, it doesn't need money, it's got very good science. It's not hostage to the government right now. It's got more new drugs than any of the, 18 new compounds, could be a billion dollars. And I come back and say, all right, well that's the treasury, plus the upside."
Johnson & Johnson (NYSE:JNJ)'s shares are up by more than 50% over the past year. Cramer's optimism about the firm covers several, but not all, aspects of the debate surrounding the firm. While Johnson & Johnson (NYSE:JNJ) has raised its full-year revenue guidance to a midpoint of $101 billion, removed headwinds related to its longstanding talcum powder lawsuits and posted strong growth with its Darzalex and Tremfya drugs for myeloma and psoriasis, concerns about its MedTech growth, flat profits growth and a 55.7% sales hit to its immune system disorders drug Stelara continue to raise the potential for headwinds.
For instance, Johnson & Johnson (NYSE:JNJ)'s MedTech business grew by a mere 3.6% in the second quarter as it was impacted by a slowdown in sales of heart-recovery devices following a study in the United Kingdom. Additionally, for a firm that's struggling on the net income growth front, $5.5 billion in talc powder settlements will continue to be a headwind to the cash flow. Johnson & Johnson (NYSE:JNJ) is due to pay $3 billion out of the $5.5 billion in 2027. Yet, at the same time, the diversified business nature means that some segments are growing. One example is the Innovative Medicine Business, which grew by 6.8% to $16.4 billion revenue, due to Darzalex and Tremfya.
Looking at hedge fund sentiment, while 113 out of the 1,022 funds part of Insider Monkey's Q1 database had held a stake in Johnson & Johnson (NYSE:JNJ), the figure jumped to 117 out of 1,006 funds in Q2. Among the notable additions was Polar Capital's $199 million stake, while Fisher ****** et Management ****** ped its stake by 44% to $3.3 billion. On the valuation front, Johnson & Johnson (NYSE:JNJ) trades at a forward P/E ratio of 23.4,2 which is lower than MRK's 56.82 and higher than AbbVie's 18.83. Shares short as a percentage of float are negligible at roughly 1%.
#billion #tremfya

2 months ago
Unilever and McCormick & Co. have decided to look for a buyer for the UK group's Colman's mustard.
Ahead of the planned deal to combine the bulk of Unilever's food business with McCormick, the Colman's brand is going on the block.
"A decision has been taken to market the Colman's brand and **** ets to potential buyers in order to proactively seek to address potential competition concerns from the planned combination of Unilever Foods and McCormick," the FMCG giant said in a statement today (27 August).
The companies announced their transaction, which valued the Unilever food **** ets at around $44.8bn, in March.
The deal will house Unilever brands including Knorr and **** mann's with McCormick products such as Schwartz spices and French's mustard.
#planned #Food #Potential #ahead

2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved eighth consecutive quarter of comparable store sales growth, driven by a balanced increase in both transaction counts and basket size.
Refined 'good, better, best' pricing tiers to capture a broad demographic, noting that 25% of customers earn between $75,000 and $150,000 and generate 40% of revenue.
Leveraged AI-driven allocation systems and enterprise data tools to improve inventory productivity and merchandising efficiency.
Improved selling margins and reduced shrinkage through store-level technology investments, successfully offsetting increased transportation fuel surcharges.
#leveraged
2 months ago
NEA delivers a 7.14% federally tax-free yield, which is double MUB's 3.52%, and posted a 12% price return over the past year.
NEA slashed its distribution nearly in half during 2022-2023 rate hikes and now trades at a NAV premium, eliminating the traditional CEF discount cushion.
Don't wait: the **** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Investors who bought the iShares National Muni Bond ETF (NYSEARCA:MUB) did so for a good reason: it is the cheapest, most liquid way to own a diversified basket of federally tax-free municipal bonds. With a 0.05% expense ratio and $45.4 billion in **** ets, MUB has become the default core holding for taxable brokerage accounts. The problem is the payout. MUB's 30-day SEC yield of 3.52% as of August 13, 2026 looks thin against a 10-year Treasury at 4.63%, and even thinner for anyone trying to live on the income. A specific municipal fund pays more than double that rate, with the same AMT-free federal exemption, and Wall Street is only now re-rating it.
Roughly 5,900 investment-grade munis make up the portfolio at MUB, held with no leverage and no active security selection. That structure keeps the fee at a rounding error, though it also caps income near the underlying bond coupons. A retiree in the 32% federal bracket with $100,000 in MUB collects about $3,520 a year in tax-free interest. The taxable-equivalent yield is roughly 5.18%, which is respectable but leaves real purchasing power close to flat once inflation is deducted. For an investor whose entire reason for holding munis is tax-free monthly income, MUB is doing the job at half speed.
#federally
2 months ago
Fulcrum Therapeutics and Slate Medicines have signed a definitive agreement to merge in an all-stock transaction backed by a $245m private placement financing from a syndicate of healthcare investors.
The combined organisation, which will operate as Slate Medicines, is expected to be listed on Nasdaq under the "SLTE" ticker symbol.
Following completion of the merger, the new entity will focus on developing Slate's pipeline of migraine treatments, with SLTE-1009 as its lead candidate.
This clinical-stage subcutaneous anti- pituitary adenylate cyclase-activating peptide / vasoactive intestinal peptide (PACAP/VIP) monoclonal antibody is intended for the prevention of migraine and other headache disorders.
The financing is expected to support operations through 2029, enabling progress of SLTE-1009 through Phase I studies in healthy volunteers and a Phase II dose-range finding study in patients with migraine.
#phase #expected #peptide #therapeutics
3 months ago
By Samuel Shen and Eduardo Baptista
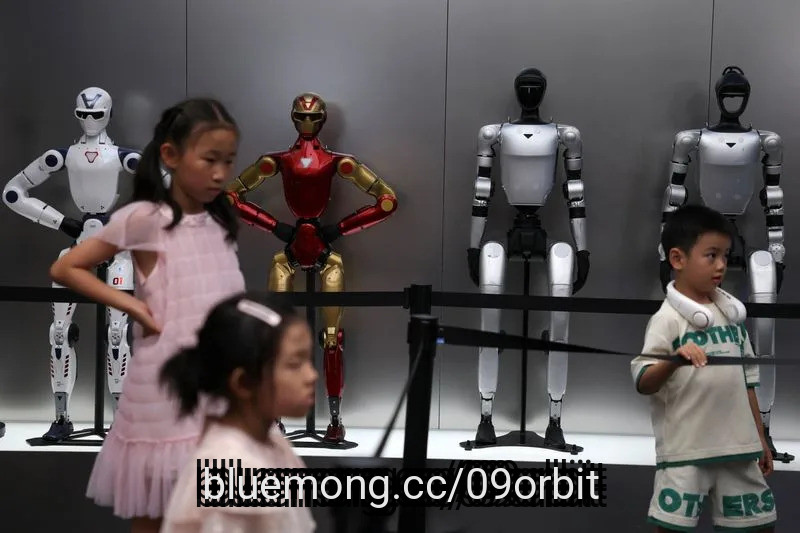
SHANGHAI/BEIJING, Aug 14 (Reuters) - China's Unitree, the country's most high-profile humanoid robot maker, is widely expected to have an explosive stock market debut in Shanghai next week. The only question is — how frenzied is it going to be?
Outside China, on private share platforms such as EquityZen, UpMarket and Hiive, Unitree shares are tipped to almost triple, while on crypto exchanges Hyperliquid and Gate, derivative trades point to a jump of almost four times.
Some others expect much more.
Such is the excitement around Unitree, whose humanoid robots have drawn global attention for their running, dancing and performing of martial arts, that its IPO was more than 8,000 times oversubscribed by retail investors, a record for Shanghai's STAR Market for tech startups.
#samuel



3 months ago
Alerian MLP ETF (NYSEMKT:AMLP) offers a much higher dividend yield and heavy concentration in energy MLPs, while First Trust North American Energy Infrastructure Fund (NYSEMKT:EMLP) provides broader diversification across utilities and lower total volatility.
Choosing between Alerian MLP ETF and First Trust North American Energy Infrastructure Fund involves weighing high income from concentrated MLPs against broader utility diversification. While both funds target North American energy infrastructure, their portfolio structures and yield profiles differ significantly. Alerian MLP ETF focuses strictly on master limited partnerships, while the First Trust fund includes corporations and utilities. This distinction affects not just the yield but also the sensitivity to commodity prices.
Metric
EMLP
AMLP
#energy #american



3 months ago
It did not take long on the C.H. Robinson second quarter earnings call with ***** ysts late Wednesday for the subject to switch away from a strong financial performance in the quarter to the fallout from its more than $600 million nuclear verdict handed down in a Texas courtroom last week.
While there might have been some speculation that CEO Dave Bozeman and other members of the management team might have cited "ongoing litigation" as a reason to not discuss the Dallas County case of Lipe vs. Lupus Superior, with C.H. Robinson also as a defendant, Bozeman addressed it in his opening remarks, and numerous questions from ***** ysts were all answered with the same reply: our behavior was proper and we're confident this verdict will not stand.
That message on Lipe vs. Lupus Superior ultimately became likely the most-discussed topic of the phone call, though Michael Castagnetto, the president of North American Surface Transportation, was able to make his core point at least twice about the company's core brokerage operations: it has now been 13 quarters where volume growth at C.H. Robinson outstripped the benchmark volume numbers published by Cass Information Systems.
Bozeman introduced his remarks on Lipe vs. Lupus Superior by referring to the "evolving legal environment regarding trucking accidents," which he described as "tragic, and every loss of life on our nation's highways is one too many."
It's a tragedy but we didn't cause it
#quarter #call #verdict

3 months ago
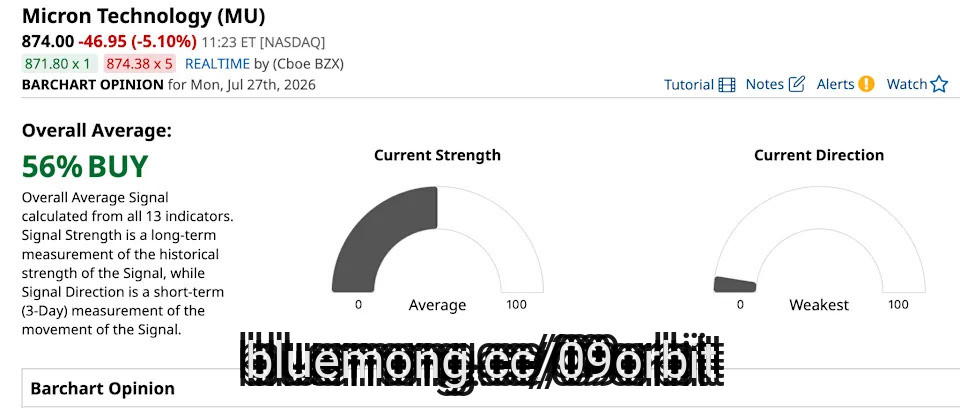
Micron (MU) stock has multiple strong positive and negative catalysts at this point, making its performance difficult to predict. On the positive side, the memory-chip maker should continue to benefit significantly in the near-to-medium term from the AI boom, and Bank of America recently ******* erted that MU should be boosted by the release of low-cost, open-source AI models made in China. Additionally, the valuation of MU stock remains low.
On the other hand, Alphabet's (GOOG) (GOOGL) technological breakthrough remains a long-term threat for MU, and investors have been unenthusiastic about Micron in recent weeks.
Dear ******* eX Stock Fans, Mark Your Calendars for August 6
Amazon Stock Just Hit a Major Hurdle Ahead of Earnings
Elon Musk Just Revealed a Quiet Win for Tesla's AI Ambitions
#micron #positive #America #China

3 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Has your savings balance finally hit $100,000? If so, congratulations on reaching this financial milestone! Chances are, you had to apply a combination of discipline and hard work to get here.
Once you've taken a beat to celebrate, you may notice a feeling of uncertainty set in, especially when it comes to deciding where to put the money. You may even feel overwhelmed when you think about spending time opening new accounts and moving the funds around.
It's natural to feel unsure about what to do with such a significant sum of money, considering it doesn't come with an owner's manual. But with that said, there are tried-and-true strategies for prioritizing where your money goes.
If you've got high-interest debt — loans or lines of credit with an annual percentage rate (APR) of 6% or higher — do yourself a big favor and pay it off ASAP. For most people, this will include credit cards, which currently have average interest rates above 21%, and personal loans, which average over 12%.
#money #advertiser #chances


3 months ago
NZS Capital, LLC, an investment management company, released its "NZS Growth Equity Strategy" second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Equity markets delivered a strong performance in the second quarter of 2026, driven by demand for AI infrastructure, geopolitical stabilization, and positive earnings reports. The portfolio achieved a gross return of +24.96% and a net return of +24.76%, significantly outperforming the +14.79% return for the Morningstar Global Target Market Exposure Index. Overweight in Semiconductors, stock selection in areas like Software and Industrials, and zero exposure to Energy contributed to the Strategy's outperformance in the quarter. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, NZS Growth Equity Strategy highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company that operates through Compute & Networking and Graphics segments. On July 20, 2026, NVIDIA Corporation (NASDAQ:NVDA) stock closed at $203.28 per share. One-month return of NVIDIA Corporation (NASDAQ:NVDA) was -2.80%, and its shares gained 18.34% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $4.95 trillion.
NZS Growth Equity Strategy stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor update:
"Elsewhere, NVIDIA Corporation (NASDAQ:NVDA) was added back to the portfolio as a resilient position late in the quarter. NVIDIA had been a long-time holding in the portfolio before we exited in the third quarter of 2025. The stock has since lagged the broad surge in the AI semiconductor ecosystem as the market began contemplating budding risks to the GPU's market share in AI compute. This scenario was our primary concern when we exited the position, but we now think the lowered valuation more than compensates for this type of risk. Further, NVIDIA's growth relative to competitors indicates the GPU is actually taking share at present."
NVIDIA Corporation (NASDAQ:NVDA) is in fourth position on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 275 hedge fund portfolios held NVIDIA Corporation (NASDAQ:NVDA) at the end of the fourth quarter, compared to 264 in the previous quarter. In the first quarter of fiscal year 2027, NVIDIA Corporation (NASDAQ: NVDA) reported revenues of $82 billion, achieving an impressive 85% year-over-year growth. While we acknowledge the potential of NVIDIA Corporation (NASDAQ:NVDA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NASDAQ #Growth
3 months ago
Walk into almost any bank today and look at its premium current account.
The benefits are remarkably familiar. Airport lounge access. Concierge services. Travel insurance. Cashback. A metal payment card.
There's nothing wrong with any of those features. Many customers value them. The problem is that they're no longer particularly distinctive.
Premium banking has spent years refining the same formula, to the point where many propositions now look and feel remarkably similar.
That raises an obvious question.
If every bank offers broadly the same premium experience, what differentiates one from another?
#many #same





