7 days ago
One of the top companies I'm keeping my eye on right now happens to be among the leading quantum computing companies in North America, and globally.
Shares of Infleqtion (INFQ) have been on a roller coaster ride lately, partly due to the volatility we've seen across this sector.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
'Even Though It's Bad for Berkshire' Billionaire Charlie Munger Said to Skip Insurance Because 'You're Paying for the Other Fellow's Frauds'
#shares #infleqtion #known #firm
Shares of Infleqtion (INFQ) have been on a roller coaster ride lately, partly due to the volatility we've seen across this sector.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
'Even Though It's Bad for Berkshire' Billionaire Charlie Munger Said to Skip Insurance Because 'You're Paying for the Other Fellow's Frauds'
#shares #infleqtion #known #firm


7 days ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


7 days ago
Gold is the ******* et people buy when they have stopped believing in promises. Then most of them hand it to a bank in another country for safekeeping, which is itself a promise.
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters


7 days ago
It's been a disappointing couple of years for shareholders of biotechnology outfit CRISPR Therapeutics (NASDAQ: CRSP). This stock's barely up since the end of 2022, lagging the broad market's gains. It's not the performance that investors keeping tabs on this company were expecting, given its potential.
Don't be discouraged, though. While still speculative like most young biotech names, CRISPR Therapeutics remains a compelling prospect for investors who can stomach the risk and its inevitable volatility. Here's why.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
On the off-chance you're reading this and aren't already familiar with the company, CRISPR Therapeutics is a drug developer that specializes in gene editing.
It's probably an area you've heard a great deal about. No gene-editing drugs were actually on the market in the United States until CRISPR Therapeutics' Casgevy was approved by the FDA as a treatment for sickle cell disease in late 2023. Any and all gene therapies currently on the market followed this pioneer's foray. Being first is a well-deserved accolade for the company, too, which was co-founded by Dr. Emmanuelle Charpentier, who was one of the co-discoverers of the CRISPR/Cas9 gene-editing mechanism that makes Casgevy work.
#crispr #gene #company
Don't be discouraged, though. While still speculative like most young biotech names, CRISPR Therapeutics remains a compelling prospect for investors who can stomach the risk and its inevitable volatility. Here's why.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
On the off-chance you're reading this and aren't already familiar with the company, CRISPR Therapeutics is a drug developer that specializes in gene editing.
It's probably an area you've heard a great deal about. No gene-editing drugs were actually on the market in the United States until CRISPR Therapeutics' Casgevy was approved by the FDA as a treatment for sickle cell disease in late 2023. Any and all gene therapies currently on the market followed this pioneer's foray. Being first is a well-deserved accolade for the company, too, which was co-founded by Dr. Emmanuelle Charpentier, who was one of the co-discoverers of the CRISPR/Cas9 gene-editing mechanism that makes Casgevy work.
#crispr #gene #company
7 days ago
The 'half-a-loaf' plan gifts roughly half of excess ***** ets to children, then uses a Medicaid-compliant annuity to bridge the penalty period.
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly

7 days ago
Valero Energy Corporation (NYSE:VLO) has been on a strong rally, posting gains of over 140% since the beginning of 2026. The strong performance is fuelled by an unusually sharp surge in global refining margins as the ongoing disruptions have significantly reduced the world's refining capacity and tightened supplies of gasoline, diesel, and jet fuel.
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong


8 days ago
Investors are largely in agreement that most of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) stock holdings are solid picks. Every now and then, though, one of its selections raises a few eyebrows.
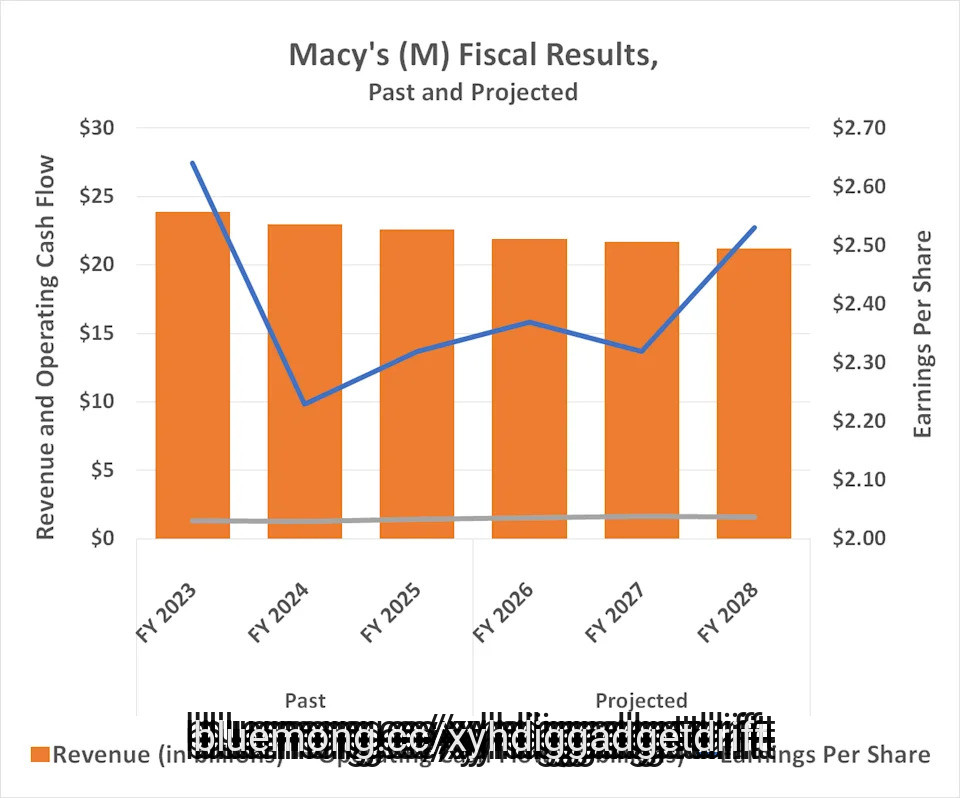
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (NYSE: M) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
#real
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (NYSE: M) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
#real



8 days ago
Amazon (AMZN) has spent the bulk of 2026 giving investors tons to debate, from its growing cloud business to the enormous bill for its AI ambitions. Now, it's putting another spending decision in the spotlight, one that goes directly into workers' household budgets.
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn

8 days ago
On September 10, 2026, Copart, Inc. (NASDAQ:CPRT) reported fourth-quarter results for the period ended July 31, 2026, and used the call to announce an all-cash acquisition of digital auto marketplace ACV Auctions. Revenue grew 2.4% to $1.2 billion, but gross profit fell 5.5% to $481.4 million and net income dropped 17.4% to $327.4 million. Diluted EPS came in at $0.35 against $0.41 a year earlier.
Wall Street spent the following days separating the deal from the quarter.
Barrington's Gary Prestopino saw enough in the transaction to move off the sidelines, upgrading Copart, Inc. (NASDAQ:CPRT) to Outperform from Market Perform with a $40 target. His argument is that combining Copart's physical network with ACV's digital marketplace, at an implied equity value of $1.9 billion or $10.50 per share in cash, creates an end-to-end remarketing platform and opens a new growth vector in dealer-to-dealer and commercial vehicle auctions.
JPMorgan's Jash Patwa had already upgraded Copart, Inc. (NASDAQ:CPRT) to Overweight from Neutral ahead of the print, raising his target to $40 from $32 on encouraging salvage industry channel checks, web scraping data showing Copart gaining share with a carrier across several states, and a collision cycle he sees turning more favorable as insurance penetration recovers.
Freedom Broker, which trimmed its target to $36 from $39 while keeping a Buy rating, called the report mixed but framed the ACV move as a strong pivot toward digital marketplace expansion.
#NASDAQ #cprt #auctions
Wall Street spent the following days separating the deal from the quarter.
Barrington's Gary Prestopino saw enough in the transaction to move off the sidelines, upgrading Copart, Inc. (NASDAQ:CPRT) to Outperform from Market Perform with a $40 target. His argument is that combining Copart's physical network with ACV's digital marketplace, at an implied equity value of $1.9 billion or $10.50 per share in cash, creates an end-to-end remarketing platform and opens a new growth vector in dealer-to-dealer and commercial vehicle auctions.
JPMorgan's Jash Patwa had already upgraded Copart, Inc. (NASDAQ:CPRT) to Overweight from Neutral ahead of the print, raising his target to $40 from $32 on encouraging salvage industry channel checks, web scraping data showing Copart gaining share with a carrier across several states, and a collision cycle he sees turning more favorable as insurance penetration recovers.
Freedom Broker, which trimmed its target to $36 from $39 while keeping a Buy rating, called the report mixed but framed the ACV move as a strong pivot toward digital marketplace expansion.
#NASDAQ #cprt #auctions


8 days ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter


8 days ago
On September 2, 2026, Snowflake Inc. (NYSE:SNOW) reported second-quarter fiscal 2027 results for the period ended July 31, 2026. Revenue rose 35% to $1.55 billion against a $1.48 billion consensus, product revenue grew 37% to $1.49 billion, and adjusted earnings came in at $0.62 per share versus the $0.45 ******* ysts expected. Management raised full-year product revenue guidance to $6.07 billion from $5.84 billion. Shares surged more than 20% in extended trading, and within 48 hours eight firms had rewritten their models.
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target

9 days ago
Reps. Mike Lawler (R-NY) and Josh Gottheimer (D-NJ) say they would not have raised interest rates and discuss the impact of higher rates and inflation on consumers. Rep. Lawler says the Fed's decision demonstrated its independence and discusses President Trump's proposed $5,000 dividend and questions over how it would be paid for. Rep. Gottheimer says higher rates will hurt consumers through credit-card bills, housing payments and other costs. They also discuss their bipartisan Stop Rogue AI Act and the need for federal standards to identify and control AI agents, while keeping the US competitive in artificial intelligence. They speak with Kailey Leinz and Joe Mathieu on Bloomberg's "Balance of Power."
#rates #lawler #president
#rates #lawler #president
9 days ago
Bunker fuel prices for ships remain at historically elevated levels, keeping pressure on vessel operating costs even as the marine-fuel supply squeeze that followed disruption around the Strait of Hormuz has eased at major fueling hubs.
In Singapore, the world's largest bunkering center, very-low-sulphur fuel oil, or VLSFO, was ******* sed at about $908 per metric ton this week, while marine gasoil (MGO) stood at $1,448 per ton and high-sulphur fuel oil at roughly $770 per ton, according to ******* yst Ship & Bunker.
At Rotterdam, Europe's busiest port, VLSFO was about $731 per ton, compared with $804 per ton in Houston and $1,005 per ton in Fujairah, United Arab Emirates.
The premium at Fujairah, the Middle East's principal bunker hub, shows the continuing impact of constrained traffic and supply-chain disruption in and around the Strait of Hormuz. Bunkering activity at Fujairah has recovered to about 40% of its prewar level, according to industry comments reported from the Asia Pacific Petroleum Conference, but remains well below normal.
Costs still far above January
#fuel #strait #hormuz #supply
In Singapore, the world's largest bunkering center, very-low-sulphur fuel oil, or VLSFO, was ******* sed at about $908 per metric ton this week, while marine gasoil (MGO) stood at $1,448 per ton and high-sulphur fuel oil at roughly $770 per ton, according to ******* yst Ship & Bunker.
At Rotterdam, Europe's busiest port, VLSFO was about $731 per ton, compared with $804 per ton in Houston and $1,005 per ton in Fujairah, United Arab Emirates.
The premium at Fujairah, the Middle East's principal bunker hub, shows the continuing impact of constrained traffic and supply-chain disruption in and around the Strait of Hormuz. Bunkering activity at Fujairah has recovered to about 40% of its prewar level, according to industry comments reported from the Asia Pacific Petroleum Conference, but remains well below normal.
Costs still far above January
#fuel #strait #hormuz #supply

9 days ago
GPC's unbroken dividend streak since 1999 yields 3%, while LKQ's 5% yield trades below book value with a Goldman-led strategic review pending.
Gentex runs a nearly debt-free balance sheet, with $1.89 trailing EPS covering its $0.48 annual dividend and aggressive buybacks shrinking the share count.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Repair demand is the quiet defensive layer inside a cyclical industry. Americans are keeping cars longer, and every mile driven eventually needs a filter, a mirror, a ***** per cover, or a brake caliper. That reality is why a small group of US-listed auto parts names have been able to send cash to shareholders through recessions, tariff scares, and new-vehicle slumps. The three names below all pay a verified dividend, span both aftermarket distribution and original-equipment supply, and range from a 2.13% yield backed by a debt-free balance sheet to a 5.05% yield trading below book value.
Genuine Parts (NYSE:GPC) is the NAPA owner and the closest thing this bundle has to an income staple. The stock yields 3.13% at a recent price of $131.45, with a quarterly payout of $1.0625 per share and an annualized run rate of $4.25.
#free
Gentex runs a nearly debt-free balance sheet, with $1.89 trailing EPS covering its $0.48 annual dividend and aggressive buybacks shrinking the share count.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Repair demand is the quiet defensive layer inside a cyclical industry. Americans are keeping cars longer, and every mile driven eventually needs a filter, a mirror, a ***** per cover, or a brake caliper. That reality is why a small group of US-listed auto parts names have been able to send cash to shareholders through recessions, tariff scares, and new-vehicle slumps. The three names below all pay a verified dividend, span both aftermarket distribution and original-equipment supply, and range from a 2.13% yield backed by a debt-free balance sheet to a 5.05% yield trading below book value.
Genuine Parts (NYSE:GPC) is the NAPA owner and the closest thing this bundle has to an income staple. The stock yields 3.13% at a recent price of $131.45, with a quarterly payout of $1.0625 per share and an annualized run rate of $4.25.
#free


9 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated

10 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company


10 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue


10 days ago
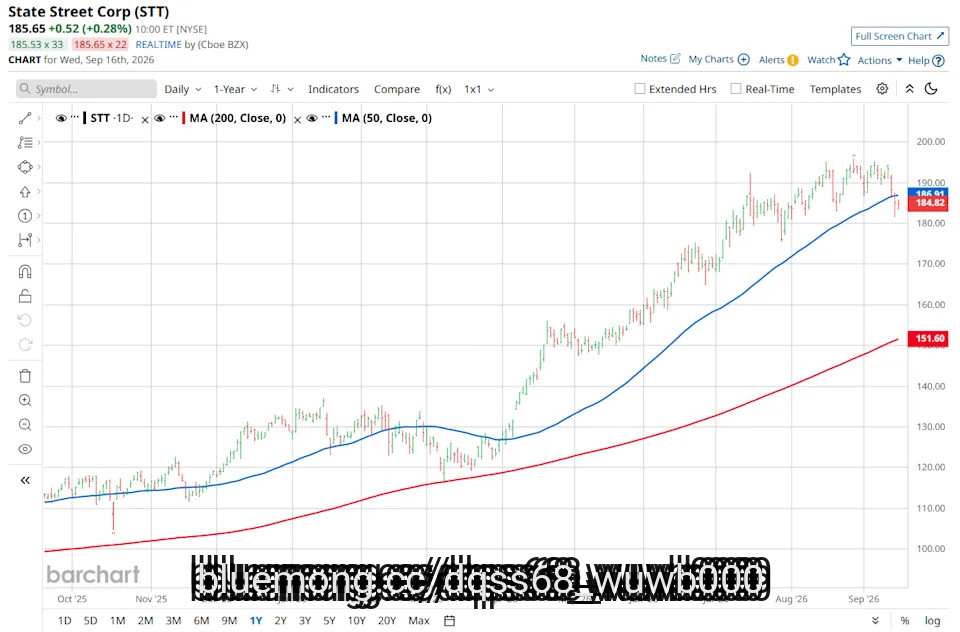
Boston, Massachusetts-based State Street Corporation (STT) provides a range of financial products and services to institutional investors. Valued at a market cap of $50.9 billion, it offers custody, accounting, and fund administration services for traditional and alternative ****** ets, as well as multi-asset-class investments, recordkeeping, client reporting, and more.
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." STT fits squarely in that category, with a market cap above this threshold that reflects its size and influence in the ****** et management industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#market #street
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." STT fits squarely in that category, with a market cap above this threshold that reflects its size and influence in the ****** et management industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#market #street

10 days ago
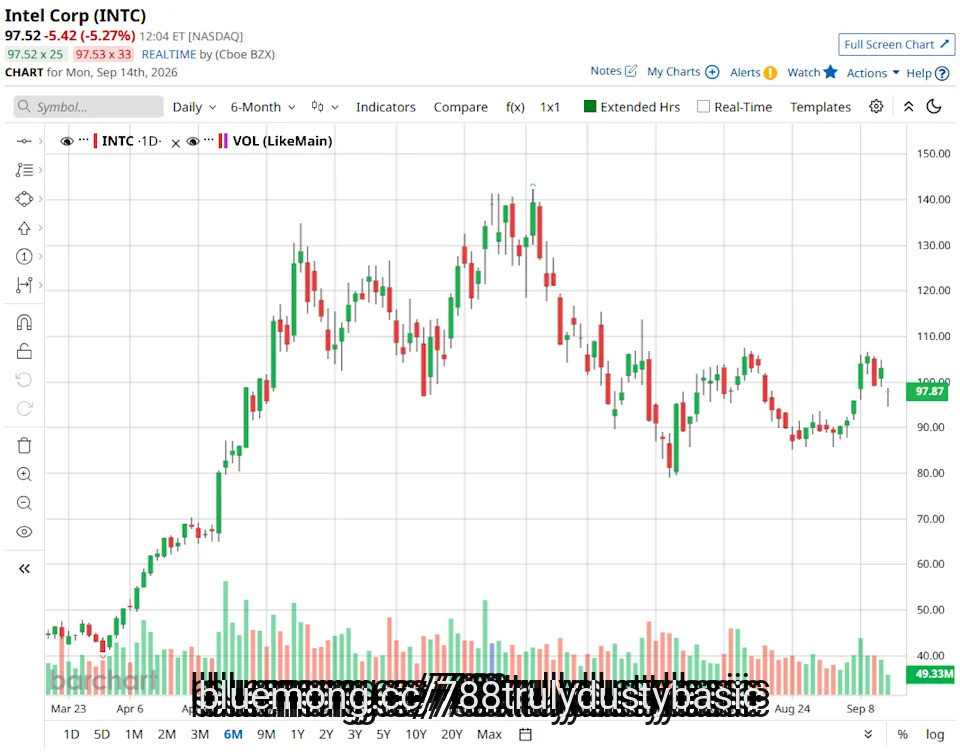
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four

10 days ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry **** ysis delivered straight to their inbox with the free CRE Daily newsletter.
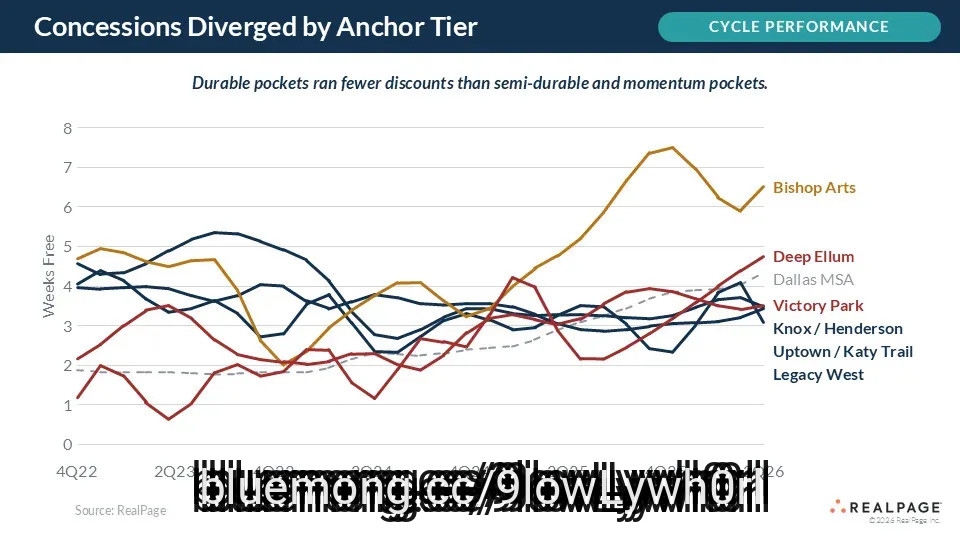
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand

11 days ago
Texas Democratic gubernatorial candidate Gina Hinojosa spent the summer keeping Republican Gov. Greg Abbott within arm's reach — never letting him lead by more than a few points.
However, two new polls disagree on whether that's still true, and the answer may decide how competitive the race really is.
A Sept. 15 poll from Mason-Dixon Polling & Research Inc. showed that Republican Gov. Greg Abbott is leading his Democratic challenger, Gina Hinojosa, by 7 points, 48% to 41%, with 8% of voters undecided.
The Mason-Dixon had a 4-point margin of error, with Libertarian Pat Dixon at 1% and Independent Jenn Mack Raphoon at 2%. It surveyed 625 registered Texas voters Sept. 8-10 who said they are likely to vote in the November 2026 election.
The poll follows a Sept. 13 poll from SoCal Strategies that showed Abbott still in a strong position in his bid for a fourth term, leading Hinojosa 52% to 44%.
#dixon #gina #republican
However, two new polls disagree on whether that's still true, and the answer may decide how competitive the race really is.
A Sept. 15 poll from Mason-Dixon Polling & Research Inc. showed that Republican Gov. Greg Abbott is leading his Democratic challenger, Gina Hinojosa, by 7 points, 48% to 41%, with 8% of voters undecided.
The Mason-Dixon had a 4-point margin of error, with Libertarian Pat Dixon at 1% and Independent Jenn Mack Raphoon at 2%. It surveyed 625 registered Texas voters Sept. 8-10 who said they are likely to vote in the November 2026 election.
The poll follows a Sept. 13 poll from SoCal Strategies that showed Abbott still in a strong position in his bid for a fourth term, leading Hinojosa 52% to 44%.
#dixon #gina #republican

11 days ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating

11 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal

11 days ago
XRP dropped 9% on the CLARITY Act's Senate failure, but Coinbase fell 9%, more exposed to the rulebook the bill would have set.
XRP retains its SEC-CFTC commodity classification and 5 live spot ETFs with $1.7 billion in net inflows, keeping its legal floor intact.
XRP has underperformed Bitcoin on every rate release this month, with $1.25 as the critical support heading into the Fed's afternoon decision.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
On Monday, XRP (CRYPTO:XRP) surged 9.8% to $1.49, while Ripple CEO Brad Garlinghouse told the Senate that "the world was watching." However, two days later, the Senate failed to open debate on the CLARITY Act, and XRP fell to $1.28.
#senate #fell #learn #Monday
XRP retains its SEC-CFTC commodity classification and 5 live spot ETFs with $1.7 billion in net inflows, keeping its legal floor intact.
XRP has underperformed Bitcoin on every rate release this month, with $1.25 as the critical support heading into the Fed's afternoon decision.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
On Monday, XRP (CRYPTO:XRP) surged 9.8% to $1.49, while Ripple CEO Brad Garlinghouse told the Senate that "the world was watching." However, two days later, the Senate failed to open debate on the CLARITY Act, and XRP fell to $1.28.
#senate #fell #learn #Monday


11 days ago
Nokia stock surged 6% to $10.39 after its AI-RAN platform advanced to live field trials with eight global operators, delivering 20%+ spectral efficiency gains.
Ericsson's near-flat 0.7% move signals markets aren't pricing AI-RAN as a category-wide event, keeping today's rally a Nokia-specific story.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Nokia (NYSE:NOK) stock is rising in early Wednesday trading, up 6% to $10.39 after the company said its artificial intelligence-powered radio access network (AI-RAN) platform is moving from evaluation to live field trials at eight global operators. The list spans North America, Europe, Asia-Pacific and the Middle East, and it reframes AI-RAN as a shared industry priority rather than a single-vendor pilot. That geographic reach is what today's move is paying up for.
The move is Nokia-specific. The iShares U.S. Technology ETF (NYSEARCA:IYW) is unchanged at $250.08, and the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.4% to $760.33. Nokia stock is climbing while U.S. technology sits still and the broad benchmark is only marginally higher, which frames today as a name-specific catalyst.
#trials
Ericsson's near-flat 0.7% move signals markets aren't pricing AI-RAN as a category-wide event, keeping today's rally a Nokia-specific story.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Nokia (NYSE:NOK) stock is rising in early Wednesday trading, up 6% to $10.39 after the company said its artificial intelligence-powered radio access network (AI-RAN) platform is moving from evaluation to live field trials at eight global operators. The list spans North America, Europe, Asia-Pacific and the Middle East, and it reframes AI-RAN as a shared industry priority rather than a single-vendor pilot. That geographic reach is what today's move is paying up for.
The move is Nokia-specific. The iShares U.S. Technology ETF (NYSEARCA:IYW) is unchanged at $250.08, and the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.4% to $760.33. Nokia stock is climbing while U.S. technology sits still and the broad benchmark is only marginally higher, which frames today as a name-specific catalyst.
#trials



13 days ago
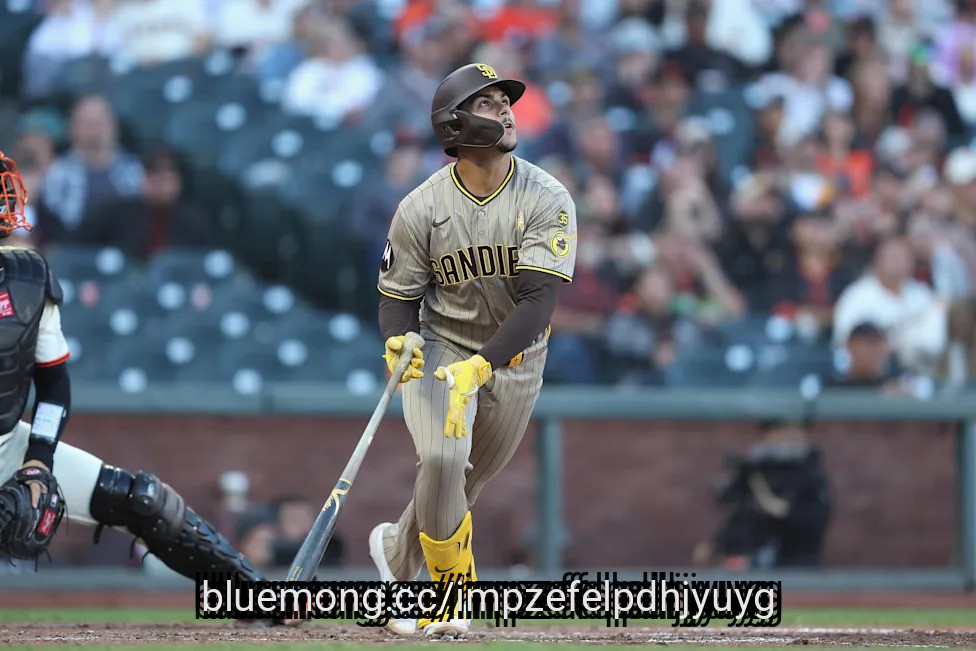
It was a nail biter, but the San Diego Padres came away from it with a seven-game win streak and back-to-back sweeps for the third time this season. It was a great game to cap off the sweep. Ethan Salas finally notched his first big-league hit with a triple in Oracle Park, Fernando Tatis Jr. went 3-for-4 with two RBI and Manny Machado launched his 27th home run of the season.
The Friars will now turn to the Colorado Rockies to round out their penultimate road trip of the 2026 season. It's a four-game set in the hitter-friendly environs of Coors Field. With the way the Padres have been swinging their bats lately (37 runs in their last six games; 6.2 runs per game), they should have no problem keeping the good vibes rolling.
Sugano has been surprisingly good in the hitter-friendly confines of Coors Field. That said, he's still pitched to a 5.30 ERA. But that number goes down to 4.96 at home compared to 5.64 away. It's an interesting split to have when Colorado is known for being a hitter's dream.
The righty has been particularly awful recently. In his last seven starts, Sugano has pitched to a 7.71 ERA across 35 innings pitched. In his last three starts, he's surrendered a whopping 14 runs (16.0 IP). If San Diego's recently potent lineup can take advantage of that, they would be well on their way to their eighth straight win.
Since joining the Padres, it's no secret that Mize has struggled. He's posted a dismal 6.34 ERA in his first seven games. Much of that is believed to be due to a groin injury that Mize has been pitching through. It was reported earlier this week that that injury was the reason many scouts decided against Mize, lowering his trade stock.
#game #runs #last #Colorado
The Friars will now turn to the Colorado Rockies to round out their penultimate road trip of the 2026 season. It's a four-game set in the hitter-friendly environs of Coors Field. With the way the Padres have been swinging their bats lately (37 runs in their last six games; 6.2 runs per game), they should have no problem keeping the good vibes rolling.
Sugano has been surprisingly good in the hitter-friendly confines of Coors Field. That said, he's still pitched to a 5.30 ERA. But that number goes down to 4.96 at home compared to 5.64 away. It's an interesting split to have when Colorado is known for being a hitter's dream.
The righty has been particularly awful recently. In his last seven starts, Sugano has pitched to a 7.71 ERA across 35 innings pitched. In his last three starts, he's surrendered a whopping 14 runs (16.0 IP). If San Diego's recently potent lineup can take advantage of that, they would be well on their way to their eighth straight win.
Since joining the Padres, it's no secret that Mize has struggled. He's posted a dismal 6.34 ERA in his first seven games. Much of that is believed to be due to a groin injury that Mize has been pitching through. It was reported earlier this week that that injury was the reason many scouts decided against Mize, lowering his trade stock.
#game #runs #last #Colorado
13 days ago
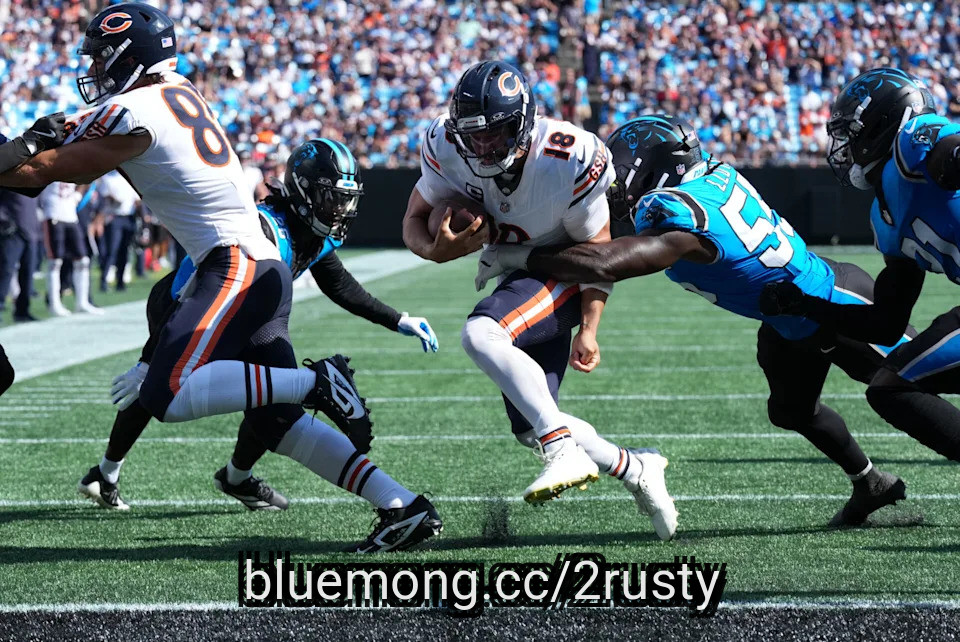
Caleb Williams and the Chicago Bears enjoyed an incredible offensive performance in their 59-37 win over the Carolina Panthers on Sunday afternoon. However, they are keeping their eye on the ball with some issues they must address as the 2026 campaign is underway.
Williams filled up the stat sheet as he enjoyed his activity in the offense. He completed 21 out of 29 passes for 269 yards and two touchdowns while racking up 10 rushes for 65 yards and two touchdowns.
Williams reflected on the performance after the game, per reporter Chris Emma. He surprisingly said this game will be the team's worst as he anticipates stronger displays throughout the coming weeks this year.
"That's who we want to be this week. We got to go clean up. We want to be truthers. Obviously, this is going to be our kind of worst game. I know points don't necessarily show that, but execution, the blocking, the penalties, all these different things," Williams said.
Sep 13, 2026; Charlotte, North Carolina, USA; Chicago Bears quarterback Caleb Williams (18) runs the ball while defended by Carolina Panthers linebacker Devin Lloyd (55) in the second half at Bank of America Stadium. Mandatory Credit: Jim Dedmon-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#williams #caleb #bears #images
Williams filled up the stat sheet as he enjoyed his activity in the offense. He completed 21 out of 29 passes for 269 yards and two touchdowns while racking up 10 rushes for 65 yards and two touchdowns.
Williams reflected on the performance after the game, per reporter Chris Emma. He surprisingly said this game will be the team's worst as he anticipates stronger displays throughout the coming weeks this year.
"That's who we want to be this week. We got to go clean up. We want to be truthers. Obviously, this is going to be our kind of worst game. I know points don't necessarily show that, but execution, the blocking, the penalties, all these different things," Williams said.
Sep 13, 2026; Charlotte, North Carolina, USA; Chicago Bears quarterback Caleb Williams (18) runs the ball while defended by Carolina Panthers linebacker Devin Lloyd (55) in the second half at Bank of America Stadium. Mandatory Credit: Jim Dedmon-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#williams #caleb #bears #images
13 days ago
TotalEnergies SE (NYSE:TTE) plans to invest $10 billion alongside its partners in Angola over the next five years, with the goal of maintaining and potentially increasing its oil production in the country. TotalEnergies currently produces around 450,000 barrels per day in Angola, making it the country's largest oil operator and accounting for more than 40% of its total output.
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore
The investment will go toward existing operations, new exploration, and projects aimed at replacing production from Angola's aging offshore fields. One of the biggest projects in the pipeline is the $6 billion Kaminho development, which is expected to start producing oil in 2028. TotalEnergies SE (NYSE:TTE) is also expanding its exploration efforts after signing agreements for two additional offshore blocks. On top of that, the company recently announced a new discovery in Block 17 that could add roughly 6,000 barrels per day to production.
The investment strengthens TotalEnergies SE (NYSE:TTE)'s position in one of Africa's key oil-producing markets and, perhaps more importantly, helps protect a major source of existing production. With around 450,000 barrels per day already coming from Angola, simply keeping output at current levels could continue to provide a meaningful contribution to the company's upstream cash flow. Any additional production from new discoveries and projects would offer further upside.
The current oil-price environment also works in TotalEnergies' favor. Brent crude recently climbed above $100 a barrel amid supply concerns and geopolitical tensions and is currently trading near this range. If prices remain elevated, projects designed to maintain or increase Angolan production could generate strong returns and make the company's investment more attractive.
There are also signs that TotalEnergies SE (NYSE:TTE) is doing more than just trying to slow production declines. Its recent Acacia-5 discovery in Block 17 could add around 6,000 barrels per day, while the company is expanding its exploration presence through new offshore blocks in the Lower Congo Basin. Angola's efforts to reform its oil sector and attract more exploration investment could also create a more favorable environment for TotalEnergies over the longer term.
#investment #offshore


13 days ago
Lyft, Inc. (NASDAQ:LYFT) has begun offering Waymo's fully autonomous robotaxi rides directly through its app in Nashville, marking the first market where Waymo vehicles can be booked through both the Waymo and Lyft apps. Lyft users requesting Standard, Priority Pickup, Wait & Save, or Extra Comfort rides within the designated Nashville service area can be matched with a Waymo vehicle at no additional cost.
The rollout also gives Lyft a larger role in the autonomous-vehicle ecosystem through its Flexdrive subsidiary, which will manage charging, cleaning and maintenance for Waymo's fleet. Reuters previously reported that the Nashville partnership was intended to become Waymo's first commercial deployment through Lyft's ride-hailing network.
paul-hanaoka-D-qq7W751vs-unsplash
The partnership could strengthen Lyft, Inc. (NASDAQ:LYFT)'s long-term position in a ride-hailing industry that is increasingly moving toward autonomous vehicles. Rather than spending heavily to develop its own robotaxi technology, Lyft can leverage Waymo's autonomous-driving capabilities while providing the customer base, app infrastructure, and fleet-management services needed to put those vehicles to work. This ****** et-light approach could allow Lyft to participate in the growth of robotaxis without bearing the enormous technological costs and risks ****** ociated with developing a self-driving system internally.
The bigger opportunity is Flexdrive. Lyft is not simply sending customers to Waymo; its subsidiary is taking responsibility for keeping Waymo vehicles operational in Nashville. Lyft says its new 80,000-square-foot facility will support more than 70 full-time positions and help optimize vehicle availability. If this operating model proves successful, Lyft could potentially become a valuable infrastructure and fleet-management partner as Waymo expands into additional markets. That would give Lyft another potential revenue opportunity beyond traditional ride commissions.
#vehicle #fleet #ride #NASDAQ
The rollout also gives Lyft a larger role in the autonomous-vehicle ecosystem through its Flexdrive subsidiary, which will manage charging, cleaning and maintenance for Waymo's fleet. Reuters previously reported that the Nashville partnership was intended to become Waymo's first commercial deployment through Lyft's ride-hailing network.
paul-hanaoka-D-qq7W751vs-unsplash
The partnership could strengthen Lyft, Inc. (NASDAQ:LYFT)'s long-term position in a ride-hailing industry that is increasingly moving toward autonomous vehicles. Rather than spending heavily to develop its own robotaxi technology, Lyft can leverage Waymo's autonomous-driving capabilities while providing the customer base, app infrastructure, and fleet-management services needed to put those vehicles to work. This ****** et-light approach could allow Lyft to participate in the growth of robotaxis without bearing the enormous technological costs and risks ****** ociated with developing a self-driving system internally.
The bigger opportunity is Flexdrive. Lyft is not simply sending customers to Waymo; its subsidiary is taking responsibility for keeping Waymo vehicles operational in Nashville. Lyft says its new 80,000-square-foot facility will support more than 70 full-time positions and help optimize vehicle availability. If this operating model proves successful, Lyft could potentially become a valuable infrastructure and fleet-management partner as Waymo expands into additional markets. That would give Lyft another potential revenue opportunity beyond traditional ride commissions.
#vehicle #fleet #ride #NASDAQ


13 days ago
Trends come and go each year, and keeping up with them can be quite a task. In case you weren't aware, tartan is the print to be seen wearing this autumn.
The trusty check print has returned for AW26, nodding to the heritage trend that we often see our favourite royal ladies embrace. From flannel shirts to sleek coats, tartan is here to stay.
The tartan print is often embraced by the royal family (@ Getty Images)
Someone who has embraced this trend for many years is the Princess of Wales. The mother-of-three has a huge collection of tartan pieces - in fact, it's her most-worn print aside from polka dots, of course.
Tartan print is the go-to fashion statement this autumn
#trend #often #trends #getty
The trusty check print has returned for AW26, nodding to the heritage trend that we often see our favourite royal ladies embrace. From flannel shirts to sleek coats, tartan is here to stay.
The tartan print is often embraced by the royal family (@ Getty Images)
Someone who has embraced this trend for many years is the Princess of Wales. The mother-of-three has a huge collection of tartan pieces - in fact, it's her most-worn print aside from polka dots, of course.
Tartan print is the go-to fashion statement this autumn
#trend #often #trends #getty