

5 hours ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Columbia Threadneedle Investments and alternative ******* et manager Hamilton Lane announced a strategic collaboration to deliver new investment products for the wealth channel. An interval fund combining public and private equity exposure, currently awaiting SEC approval, will likely be the first product launched through the two firms' partnership.
Columbia Threadneedle brings its public markets expertise, multi-asset investment capabilities and strategic distribution relationships to the collaboration. Hamilton Lane specializes in alternatives, with an established private markets platform, investment sourcing capabilities and data ******* ytics expertise.
Columbia Threadneedle filed a preliminary registration statement with the SEC for the Columbia Hamilton Lane Growth Innovation Fund, a public-private growth equity interval fund. If the fund is approved by the SEC, it will be offered to the wealth channel through financial advisors.
According to the filing, the fund will focus on capital appreciation, allocating at least 80% of its net ******* ets to investments in growth innovation companies. The fund will be roughly evenly split in exposure to publicly traded securities and private ******* ets. At least 40% of the fund's ******* ets will be invested in underlying funds managed by Hamilton Lane.
#lane
Columbia Threadneedle Investments and alternative ******* et manager Hamilton Lane announced a strategic collaboration to deliver new investment products for the wealth channel. An interval fund combining public and private equity exposure, currently awaiting SEC approval, will likely be the first product launched through the two firms' partnership.
Columbia Threadneedle brings its public markets expertise, multi-asset investment capabilities and strategic distribution relationships to the collaboration. Hamilton Lane specializes in alternatives, with an established private markets platform, investment sourcing capabilities and data ******* ytics expertise.
Columbia Threadneedle filed a preliminary registration statement with the SEC for the Columbia Hamilton Lane Growth Innovation Fund, a public-private growth equity interval fund. If the fund is approved by the SEC, it will be offered to the wealth channel through financial advisors.
According to the filing, the fund will focus on capital appreciation, allocating at least 80% of its net ******* ets to investments in growth innovation companies. The fund will be roughly evenly split in exposure to publicly traded securities and private ******* ets. At least 40% of the fund's ******* ets will be invested in underlying funds managed by Hamilton Lane.
#lane
7 hours ago
Palantir Technologies (PLTR) and Nebius Group (NBIS) have joined forces in a partnership that directly supports both companies' growth stories. Palantir gets a compute partner that can support its push into sovereign AI, while Nebius gains access to a prominent enterprise distribution channel through Palantir. That makes the deal appear straightforward and mutually beneficial on paper. Still, both stocks face growing investor skepticism. Palantir's valuation remains a major point of debate among investors, and Nebius still needs to show that its capital-heavy build-out will eventually lead to durable profitability.
Palantir has designated Nebius as its preferred sovereign AI infrastructure partner. The company plans to integrate Nebius' compute and inference endpoints into the Palantir enterprise perimeter following an integration period. The partnership will allow eligible Palantir customers to use Nebius' infrastructure while maintaining control over their own compute, models, and data. The companies will also collaborate to expand compute capacity more quickly, including through modular data center builds at sites with available power.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#palantir #compute #still
Palantir has designated Nebius as its preferred sovereign AI infrastructure partner. The company plans to integrate Nebius' compute and inference endpoints into the Palantir enterprise perimeter following an integration period. The partnership will allow eligible Palantir customers to use Nebius' infrastructure while maintaining control over their own compute, models, and data. The companies will also collaborate to expand compute capacity more quickly, including through modular data center builds at sites with available power.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#palantir #compute #still



7 hours ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ******* ysis, subscribe to Bisnow's free suite of newsletters.
A pair of national real estate investment managers closed their U.S. office credit fund with $1.1B in investor commitments.
Hines and Rialto Capital secured 126 investors for their Hines Rialto Credit Partners, a co-general partnership focused on U.S. office credit investments. The fund required a minimum investment of $100K, according to a filing with the U.S. Securities and Exchange Commission.
With the rapid growth of private credit, Hines said it believes investors are searching for real estate credit strategies grounded in specialized underwriting and deep market knowledge.
"Yield alone does not tell you the quality of the risk," Alfonso Munk, Hines' global co-head of investment management, said in a statement. "In real estate credit, understanding the underlying ******* et — what it is worth, how it performs and how it may hold up under pressure — is becoming increasingly important as the market works through a significant refinancing cycle."
#real #rialto
A pair of national real estate investment managers closed their U.S. office credit fund with $1.1B in investor commitments.
Hines and Rialto Capital secured 126 investors for their Hines Rialto Credit Partners, a co-general partnership focused on U.S. office credit investments. The fund required a minimum investment of $100K, according to a filing with the U.S. Securities and Exchange Commission.
With the rapid growth of private credit, Hines said it believes investors are searching for real estate credit strategies grounded in specialized underwriting and deep market knowledge.
"Yield alone does not tell you the quality of the risk," Alfonso Munk, Hines' global co-head of investment management, said in a statement. "In real estate credit, understanding the underlying ******* et — what it is worth, how it performs and how it may hold up under pressure — is becoming increasingly important as the market works through a significant refinancing cycle."
#real #rialto

8 hours ago
MiKargo247 is expanding its spot cargo insurance coverage to include strategic cargo theft under a new partnership with Verified Carrier.
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies


8 hours ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
9 hours ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Mexico #chemical #Logistics


10 hours ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


10 hours ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o


11 hours ago
The artificial intelligence (AI) boom is entering a new phase, and this time, the battle is moving deeper into the data center. It is no longer simply about who can build the fastest AI accelerator. Hyperscalers are scrambling for more compute, faster connectivity, and better power efficiency as AI workloads continue to grow at a breakneck pace. That is opening the door for chipmakers that can deliver customized, energy-efficient solutions at scale.
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #hyperscalers #amzn
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #hyperscalers #amzn


11 hours ago
Carter's unveiled a new brand identity and marketing campaign on Tuesday, as the children's clothing company works to attract a younger generation of parents and build on a recent business turnaround.
The rebrand centers on a new brand promise — "Let every child's light shine" — and a refreshed logo in which a shooting star replaces the apostrophe in the Carter's wordmark, the company said. A new 60-second film called "Watch Them Glow" will debut across connected television as the first major marketing expression of the new direction.
Chief Marketing Officer Sarah Crockett told CNBC that the company sees a significant shift in its core customer base. Gen Z is expected to account for a large share of new parents over the next several years, according to Carter's, and those parents tend to let children make their own clothing choices and turn to social media for guidance.
"We had an opportunity to really tap into the values that parents are bringing into the household," Crockett told CNBC.
The new identity will begin rolling out across Carter's channels in 2026, with additional retail, product, and packaging elements to follow in 2027, the company said. Carter's is also launching a creator program called Light Makers, featuring voices across North America, and expanding partnerships with organizations including Outward Bound and Boys & Girls Clubs of America.
#parents #Marketing #cnbc #America
The rebrand centers on a new brand promise — "Let every child's light shine" — and a refreshed logo in which a shooting star replaces the apostrophe in the Carter's wordmark, the company said. A new 60-second film called "Watch Them Glow" will debut across connected television as the first major marketing expression of the new direction.
Chief Marketing Officer Sarah Crockett told CNBC that the company sees a significant shift in its core customer base. Gen Z is expected to account for a large share of new parents over the next several years, according to Carter's, and those parents tend to let children make their own clothing choices and turn to social media for guidance.
"We had an opportunity to really tap into the values that parents are bringing into the household," Crockett told CNBC.
The new identity will begin rolling out across Carter's channels in 2026, with additional retail, product, and packaging elements to follow in 2027, the company said. Carter's is also launching a creator program called Light Makers, featuring voices across North America, and expanding partnerships with organizations including Outward Bound and Boys & Girls Clubs of America.
#parents #Marketing #cnbc #America


12 hours ago
With a market cap of $39.1 billion, California-based NetApp, Inc. (NTAP) is a leading provider of enterprise data storage and intelligent data infrastructure, helping businesses manage, protect, and activate data across on-premises systems, hybrid environments, and major public clouds. Its portfolio combines all-flash storage, cloud services, and data-management software, with its ONTAP platform at the core.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NetApp fits this criterion perfectly. Its leadership lies in its enterprise storage, strong hybrid-cloud capabilities, and deeply embedded customer relationships. Its ONTAP platform offers unified data management across on-premises and cloud environments, while partnerships with major cloud providers strengthen its position as enterprises shift toward hybrid infrastructure. NetApp also benefits from its growing all-flash storage portfolio, recurring software and services revenue, and expanding AI-focused data infrastructure offerings.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#netapp #storage #Stock #offerings
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and NetApp fits this criterion perfectly. Its leadership lies in its enterprise storage, strong hybrid-cloud capabilities, and deeply embedded customer relationships. Its ONTAP platform offers unified data management across on-premises and cloud environments, while partnerships with major cloud providers strengthen its position as enterprises shift toward hybrid infrastructure. NetApp also benefits from its growing all-flash storage portfolio, recurring software and services revenue, and expanding AI-focused data infrastructure offerings.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#netapp #storage #Stock #offerings



12 hours ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june

12 hours ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease


12 hours ago
Chemical manufacturer OXEA has selected Uber Freight as its strategic logistics provider across the U.S., Canada, Mexico and Europe as the company moves to consolidate regional transportation operations into a more unified global network.
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Transportation #Logistics
Houston-based OXEA said Uber Freight will manage day-to-day transportation execution across truckload, rail and ocean freight, using technology, data and logistics services to provide greater visibility across the chemical manufacturer's supply chain.
The agreement represents Uber Freight's (NYSE: UBER) first managed transportation engagement designed from the outset to span the U.S., Canada, Mexico and Europe, according to the companies.
OXEA manufactures oxo intermediates and oxo performance chemicals used in products including coatings, lubricants, cosmetics, pharmaceuticals, flavors and fragrances, printing inks and plastics. The company employs more than 1,200 people and sells chemicals in more than 60 countries.
The partnership is intended to replace a more regionally segmented approach to transportation management with an integrated operation connecting OXEA's plants, carriers and customers.
#Transportation #Logistics

14 hours ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of **** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable of

14 hours ago
The artificial intelligence (AI) boom is entering a new phase, and this time, the battle is moving deeper into the data center. It is no longer simply about who can build the fastest AI accelerator. Hyperscalers are scrambling for more compute, faster connectivity, and better power efficiency as AI workloads continue to grow at a breakneck pace. That is opening the door for chipmakers that can deliver customized, energy-efficient solutions at scale.
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #amzn
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #amzn


15 hours ago
This story was originally published on Construction Dive. To receive daily news and insights, subscribe to our free daily Construction Dive newsletter.
Two recent road projects have been turning heads in the construction industry, and they have something interesting in common.
Both the $9.2 billion Interstate 24 Southeast Choice Lanes project in Tennessee and the $4.6 billion state Route 400 Express Lanes in Georgia use concessions, which allow a consortium in a public-private partnership to benefit from future use fees, such as revenue from tolls.
In exchange, the consortium puts forward a significant amount of cash to design, build, operate and maintain the roadways. For contractors, being a part of a consortium can potentially give them stable work and revenue for decades.
For example, in the case of the Georgia state Route 400 project, the consortium is Peach Partners, comprising Acciona Concessions, ACS Infrastructure and Meridiam, which will deliver and maintain the project under a 56-year public-private partnership. The consortium is providing a $3.8 billion concession fee to the state's DOT to help fund other roadway projects as part of the P3 to design, build, operate and maintain the express lanes, per the U.S. DOT.
#consortium #lanes #route
Two recent road projects have been turning heads in the construction industry, and they have something interesting in common.
Both the $9.2 billion Interstate 24 Southeast Choice Lanes project in Tennessee and the $4.6 billion state Route 400 Express Lanes in Georgia use concessions, which allow a consortium in a public-private partnership to benefit from future use fees, such as revenue from tolls.
In exchange, the consortium puts forward a significant amount of cash to design, build, operate and maintain the roadways. For contractors, being a part of a consortium can potentially give them stable work and revenue for decades.
For example, in the case of the Georgia state Route 400 project, the consortium is Peach Partners, comprising Acciona Concessions, ACS Infrastructure and Meridiam, which will deliver and maintain the project under a 56-year public-private partnership. The consortium is providing a $3.8 billion concession fee to the state's DOT to help fund other roadway projects as part of the P3 to design, build, operate and maintain the express lanes, per the U.S. DOT.
#consortium #lanes #route


15 hours ago
Realty Income (NYSE:O) aims to be the real estate partner to the world's leading companies. It has really leaned into forming new capital partnerships with leading institutional investors over the past year. It just formed a new joint venture (JV) with KKR, adding to prior strategic partnership deals with Apollo and GIC.
These partnerships might have income investors wondering if they're a sign of financial strength or weakness. Here's how they align with Realty Income's strategic plan to continue growing its high-yielding monthly dividend (currently 5.5%).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Realty Income is a real estate investment trust (REIT) with a globally diversified portfolio of net lease real estate. It launched an investment management platform (Realty Income Investment Management or RIM) last year to allow institutional investors to invest alongside it through funds, JVs, and separately managed mandates. This strategy has four key advantages: accelerating its adjusted funds from operations (AFFO) per share growth through capital-light revenue, expanding its addressable market, reducing its reliance on public equity, and providing its partners with distinct, non-overlapping vehicles.
#income #estate #continue
These partnerships might have income investors wondering if they're a sign of financial strength or weakness. Here's how they align with Realty Income's strategic plan to continue growing its high-yielding monthly dividend (currently 5.5%).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Realty Income is a real estate investment trust (REIT) with a globally diversified portfolio of net lease real estate. It launched an investment management platform (Realty Income Investment Management or RIM) last year to allow institutional investors to invest alongside it through funds, JVs, and separately managed mandates. This strategy has four key advantages: accelerating its adjusted funds from operations (AFFO) per share growth through capital-light revenue, expanding its addressable market, reducing its reliance on public equity, and providing its partners with distinct, non-overlapping vehicles.
#income #estate #continue

15 hours ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq


20 hours ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real


21 hours ago
US-based accounting, tax and advisory practice PKF O'Connor Davies has appointed Mark Goldschmitt as a partner within its commercial tax practice, based at its office in Hauppauge, New York.
Goldschmitt brings close to 30 years of public accounting experience.
His work focuses on tax planning, regulatory compliance and business advisory services for corporate entities, partnerships, privately held enterprises and high-net-worth individuals.
His sector experience spans architecture, legal services, digital media, staffing and recruitment.
The appointment forms part of the company's plans to develop its commercial tax service capabilities across the New York metropolitan region.
#experience #o 'connor
Goldschmitt brings close to 30 years of public accounting experience.
His work focuses on tax planning, regulatory compliance and business advisory services for corporate entities, partnerships, privately held enterprises and high-net-worth individuals.
His sector experience spans architecture, legal services, digital media, staffing and recruitment.
The appointment forms part of the company's plans to develop its commercial tax service capabilities across the New York metropolitan region.
#experience #o 'connor


23 hours ago
Walmart and SCAN Health Plan announced a partnership on Wednesday to offer co-branded Medicare Advantage plans in two states, targeting a pool of more than two million Medicare enrollees.
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#plan #Wellness #members #advantage
The plans, pending regulatory approval, may include pharmacy, vision, food, and over-the-counter benefits, the companies said. Open enrollment for Medicare Advantage begins Oct. 15, according to MarketWatch.
A central feature of the partnership is Walmart's Everyday Health Signals platform, an AI tool designed to provide personalized nutrition and wellness guidance based on members' shopping preferences and self-reported wellness goals. The companies said they plan to make that capability available to participating plan members as part of broader coaching and wellness support.
"By combining Walmart's technology capabilities and consumer retail expertise with SCAN's Medicare product experience, we have an opportunity to develop products that translate those insights into meaningful support that helps members make more informed choices about their health and well-being," said Zack Myers, national general manager of SCAN Health Plan, in a statement.
Walmart Group Director for Consumer Health and Data Solutions Pravene Nath said the collaboration is distinct because of Walmart's role in customers' everyday lives. "Because customers regularly turn to Walmart for groceries and other everyday essentials, we have an opportunity for those who choose to participate, to use insights from their shopping experiences to make nutrition guidance more relevant and actionable," Nath said in a statement.
#plan #Wellness #members #advantage

2 days ago
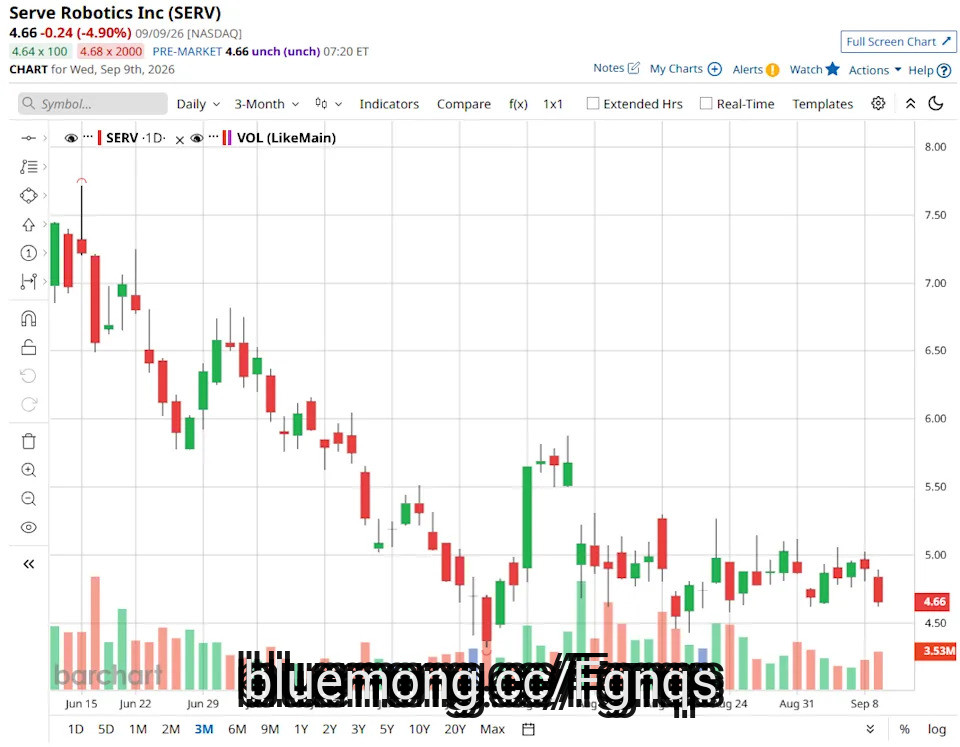
Serve Robotics (SERV) shares have tumbled roughly 20% since the autonomous delivery company lowered its 2026 revenue guidance on Aug. 6. The cut came despite quarterly revenue surging 404% year-over-year (YOY). Serve Robotics also said it may not renew its foundational partnership with Uber (UBER) after it expires in early 2027. The development follows Serve's first decline in Uber Eats delivery volume in 17 consecutive quarters. However, Serve has $240 million in cash and is intentionally expanding into DoorDash (DASH), healthcare robotics, and advertising. The debate now is whether the reset reflects deeper trouble or a strategic effort to diversify beyond a weakening partnership.
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#company


3 days ago
ESPN's decision to air an interview with U.S. Sen. Ted Cruz on College GameDay this week was bound to get attention.
That's why they did it.
The backlash the network is facing has a lot more to do with its refusal to balance Cruz's perspective with anyone on the GameDay panel or from another guest — and what Bomani Jones, in an episode of his podcast The Right Time on Sunday, called "pretty dire consequences" that could come from "shilling" for the Senate's Protect College Sports Act.
Jones called out ESPN for not bringing on an opponent of the PCSA on the show, and for compounding its partnership with the powers that be with another unusual decision during its broadcast from the University of Texas on Saturday.
"There are serious consequences to what ESPN chose to do," he said. "What they did was flatly wrong, and it is possible that it will contribute to limiting the ability of players to cash in, their chance to cash in in this life. I think those are pretty dire consequences, and I think that there should be a pretty loud uproar about that."
#jones #decision
That's why they did it.
The backlash the network is facing has a lot more to do with its refusal to balance Cruz's perspective with anyone on the GameDay panel or from another guest — and what Bomani Jones, in an episode of his podcast The Right Time on Sunday, called "pretty dire consequences" that could come from "shilling" for the Senate's Protect College Sports Act.
Jones called out ESPN for not bringing on an opponent of the PCSA on the show, and for compounding its partnership with the powers that be with another unusual decision during its broadcast from the University of Texas on Saturday.
"There are serious consequences to what ESPN chose to do," he said. "What they did was flatly wrong, and it is possible that it will contribute to limiting the ability of players to cash in, their chance to cash in in this life. I think those are pretty dire consequences, and I think that there should be a pretty loud uproar about that."
#jones #decision

3 days ago
DETROIT (AP) — The Detroit Lions know they are asking a lot of star running back Jahmyr Gibbs.
His next major test will come Thursday against the Buffalo Bills.
For the first three years of his career, Gibbs was paired with David Montgomery in Detroit's "Sonic and Knuckles" partnership. Montgomery wasn't a little-used backup, either. He averaged 853.3 yards and 11 touchdowns over the past three seasons.
Montgomery picked up where he left off Sunday, scoring three touchdowns, but that was for the Houston Texans in a 36-31 loss to the Bills.
At the same time, Gibbs was dealing with his new workload as Detroit's only experienced rusher. He averaged a career-high 18.8 touches per game last season, but got 34 in Sunday's 31-30 overtime win over the New Orleans Saints — three more than his previous high.
#bills #Career #averaged #lions
His next major test will come Thursday against the Buffalo Bills.
For the first three years of his career, Gibbs was paired with David Montgomery in Detroit's "Sonic and Knuckles" partnership. Montgomery wasn't a little-used backup, either. He averaged 853.3 yards and 11 touchdowns over the past three seasons.
Montgomery picked up where he left off Sunday, scoring three touchdowns, but that was for the Houston Texans in a 36-31 loss to the Bills.
At the same time, Gibbs was dealing with his new workload as Detroit's only experienced rusher. He averaged a career-high 18.8 touches per game last season, but got 34 in Sunday's 31-30 overtime win over the New Orleans Saints — three more than his previous high.
#bills #Career #averaged #lions



3 days ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months

3 days ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
3 days ago
On August 6, PureCycle Technologies (NASDAQ:PCT) reported second-quarter results for the period ended June 30, and buried in the numbers was something the plastics recycler has chased for years: an actual branded product on store shelves. Select Downy detergent caps made with PureCycle's PureFive resin entered commercial production for Procter & Gamble during the quarter, the first tangible sign the company's purification technology can clear a major consumer brand's supply chain. Revenue came in at $4.5 million, up roughly 173% from a year earlier and the sixth straight quarter of sequential growth.
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss

3 days ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue

3 days ago
International Business Machines (IBM) is building a rather interesting corner of the enterprise artificial intelligence (AI) market. The company has combined its hybrid-cloud expertise with foundation models and deep government and scientific partnerships, while its Prithvi family of open models now spans weather, geospatial, and lunar data.
That gives IBM a credible position in domain-specific AI, particularly where the stakes are too high for generic models to wing it. The latest example is the NASA IBM Lunar Foundation Model, open-sourced on Thursday, Sept. 10, which brings decades of multi-instrument lunar observations into a unified, machine-learning-ready dataset and model.
Dear ******* eX Stock Fans, Mark Your Calendars for September 21
Google Just Dropped a Bombshell on AI Spending — Alphabet's $200 Billion AI Bet Is Starting to Pay Off Big
Dear Nike Stock Fans, Mark Your Calendars for September 21
#lunar
That gives IBM a credible position in domain-specific AI, particularly where the stakes are too high for generic models to wing it. The latest example is the NASA IBM Lunar Foundation Model, open-sourced on Thursday, Sept. 10, which brings decades of multi-instrument lunar observations into a unified, machine-learning-ready dataset and model.
Dear ******* eX Stock Fans, Mark Your Calendars for September 21
Google Just Dropped a Bombshell on AI Spending — Alphabet's $200 Billion AI Bet Is Starting to Pay Off Big
Dear Nike Stock Fans, Mark Your Calendars for September 21
#lunar



